
 Global SDHI Fungicide Market | 2026-2036
Global SDHI Fungicide Market Size, Share, and Industry Trends Forecast 2026-2036
Global SDHI Fungicide Market Foresight
ISO 17025 accreditation for residue analytical laboratories is rotating the competitive threshold for SDHI manufacturers seeking EU and North American market access. BASF SE leverages its captive synthesis of fluxapyroxad intermediates to sustain cost positions across Latin American export channels. Syngenta Group anchors its portfolio breadth through integrated seed-treatment-to-foliar fungicide protocols in European cereal systems. Bayer AG competes on the strength of its fluopyram registrations in vineyard and specialty crop segments where residue limits are most stringent.
Succinate dehydrogenase inhibitors constitute a class of carboxamide fungicides that block mitochondrial respiration in fungal pathogens by binding the ubiquinone reduction site of the SDH enzyme complex, with typical application rates ranging from 125 to 250 grams active ingredient per hectare depending on crop-pathogen combination. These chemistries serve primarily as resistance-breaking partners in azole-strobilurin programs across broadacre and specialty agriculture. Fluxapyroxad formulations command premium positioning in cereals and oilseeds where protective efficacy against rust complexes justifies higher input costs. Suspension concentrate delivery systems are displacing wettable powders in vineyard and vegetable applications where drift reduction and operator exposure limits drive formulation selection. The turf and ornamentals channel occupies a discrete margin pool served by specialized distributors with dedicated technical support infrastructure.
The EPA's Endangered Species Act consultation requirements and the EU's REACH substance evaluation protocols are extending registration timelines and elevating ecotoxicology data costs for new SDHI entrants. India's Central Insecticides Board maintains distinct residue tolerance schedules that condition import acceptance and local manufacturing investment decisions. Brazil's national agricultural regulator ANVISA coordinates with the Ministry of Agriculture on re-evaluation cycles that increasingly incorporate pollinator risk assessments into fungicide renewal criteria. Stakeholders must track the divergence between precautionary regulatory frameworks in Europe and productivity-oriented approval pathways in major Southern Hemisphere grain exporters.
Market Dynamics
Resistance management protocols across Brazil, Germany, and India are tightening co-application requirements with azole and strobilurin partners, forcing reformulation investments and shortening product lifecycles for SDHI manufacturers.
Growth Catalysts
- EU Green Deal Farm to Fork:The strategy accelerates regulatory reviews that favor reduced-application-rate chemistries, creating preference pull for high-efficacy SDHI molecules in European cereal programs.
- Brazil soybean-corn rotation belts:Asian soybean rust pressure sustains premium fungicide deployment volumes where protective efficacy justifies repeat applications across growing seasons.
- Suspension concentrate delivery systems:Drift reduction properties and operator exposure limits in vineyard and vegetable applications are displacing wettable powder formulations and expanding addressable crop segments.
Market Restraints
- EPA Endangered Species Act consultations:Extended registration timelines and elevated ecotoxicology data costs create capital barriers for new SDHI entrants seeking US market access.
- Fluxapyroxad intermediate supply:Captive synthesis concentration among established manufacturers limits cost-competitive sourcing options for second-tier formulators in Latin American export channels.
- Azole-strobilurin resistance rotation requirements:Mandatory partner chemistry obligations compress standalone SDHI revenue potential and complicate portfolio architecture decisions.
Strategic Opportunities
- India Central Insecticides Board residue schedules:Distinct tolerance protocols condition import acceptance pathways and local manufacturing investment decisions for early-mover registrants.
- Turf and ornamentals channel infrastructure:Specialized distributor networks with dedicated technical support capabilities offer margin pool separation from commoditized broadacre segments.
- ISO 17025 residue analytical accreditation:Laboratory certification requirements for EU and North American market access create service-revenue adjacencies for manufacturers with captive analytical capabilities.
Industry Challenges
- Pollinator risk assessment integration:Brazil ANVISA re-evaluation cycles now incorporate bee toxicity protocols that extend renewal timelines and require additional field study investments.
- REACH substance evaluation data packages:EU ecotoxicology dossier requirements demand specialized regulatory affairs talent that concentrates among incumbent registrants with established submission track records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global SDHI Fungicide Market |
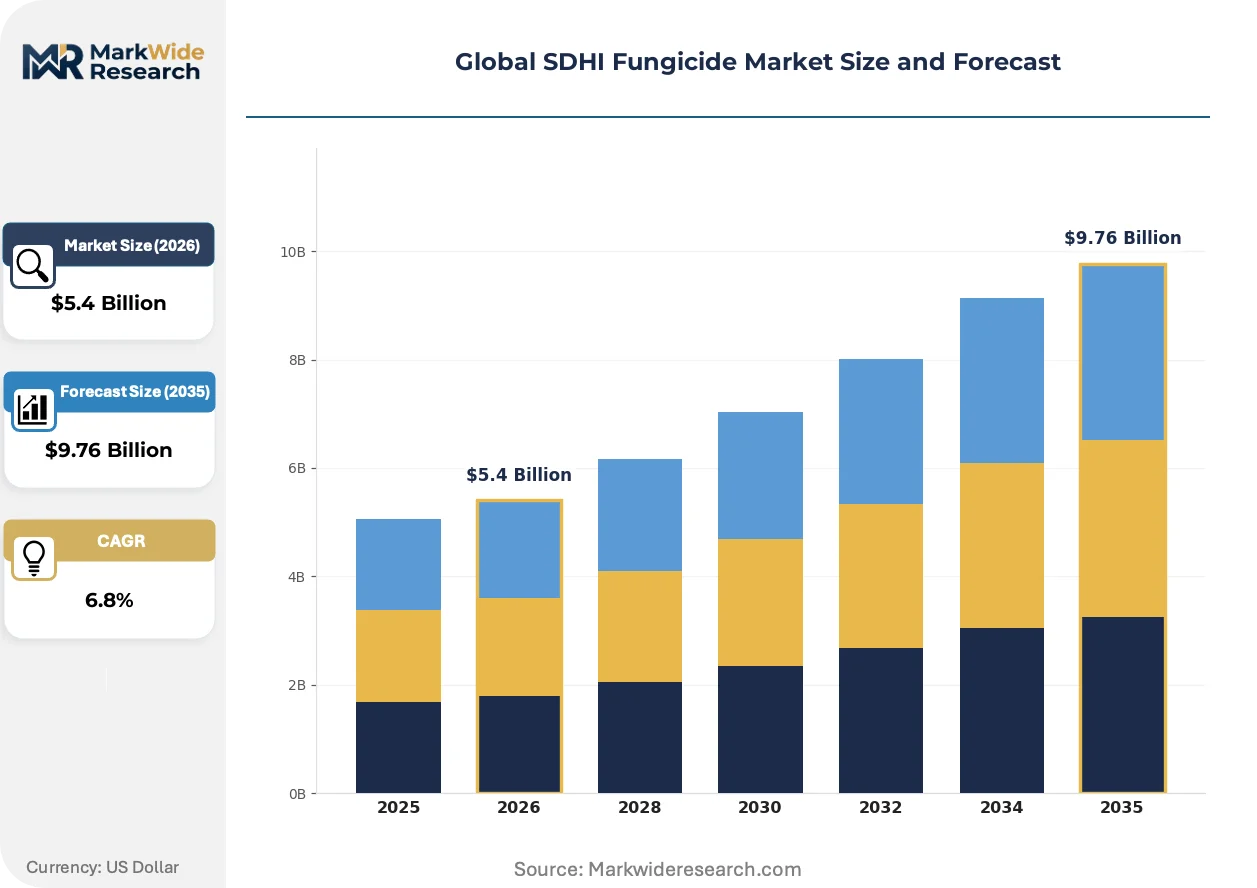
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boscalid, Fluxapyroxad, Fluopyram, Penthiopyrad, Isopyrazam, Others Application: Cereals, Fruits, Vegetables, Oilseeds, Turf & Ornamentals, Vineyards End User: Agricultural Cooperatives, Crop Consultants, Independent Farmers, Agrochemical Distributors Formulation Type: Wettable Powder, Suspension Concentrate, Granules, Emulsifiable Concentrate |
| Companies Covered | Corteva Agriscience, Nufarm Limited, Syngenta Group, Adama Ltd, UPL Limited, BASF SE, FMC Corporation, Valent U.S.A. Corporation, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global SDHI Fungicide Market Shifts & Advancements
Formulation chemistry and application precision technologies are compressing dose rates while expanding crop-pest combinations, reshaping competitive differentiation around delivery system performance rather than molecule novelty alone.
Micro-encapsulation technology for controlled-release SDHI delivery is miniaturizing effective application windows and reducing environmental load. European vineyard operators are adopting these systems to meet drift reduction mandates. The technology is compressing seasonal labor requirements while maintaining protective coverage through rainfall events.
REACH substance evaluation protocols are extending data requirements for succinate dehydrogenase inhibitor chemistries entering EU renewal cycles. Manufacturers must generate additional aquatic toxicity and metabolite fate studies. Specialty crop segments with stringent residue limits face the greatest compliance cost concentration.
Seed-treatment-to-foliar protocol integration is consolidating purchasing decisions around single-supplier crop protection programs. European cereal growers increasingly specify bundled fungicide packages from germination through flag leaf stage. Germany and France demonstrate the strongest concentration of this procurement pattern shift.
Global SDHI Fungicide Market Segmentation
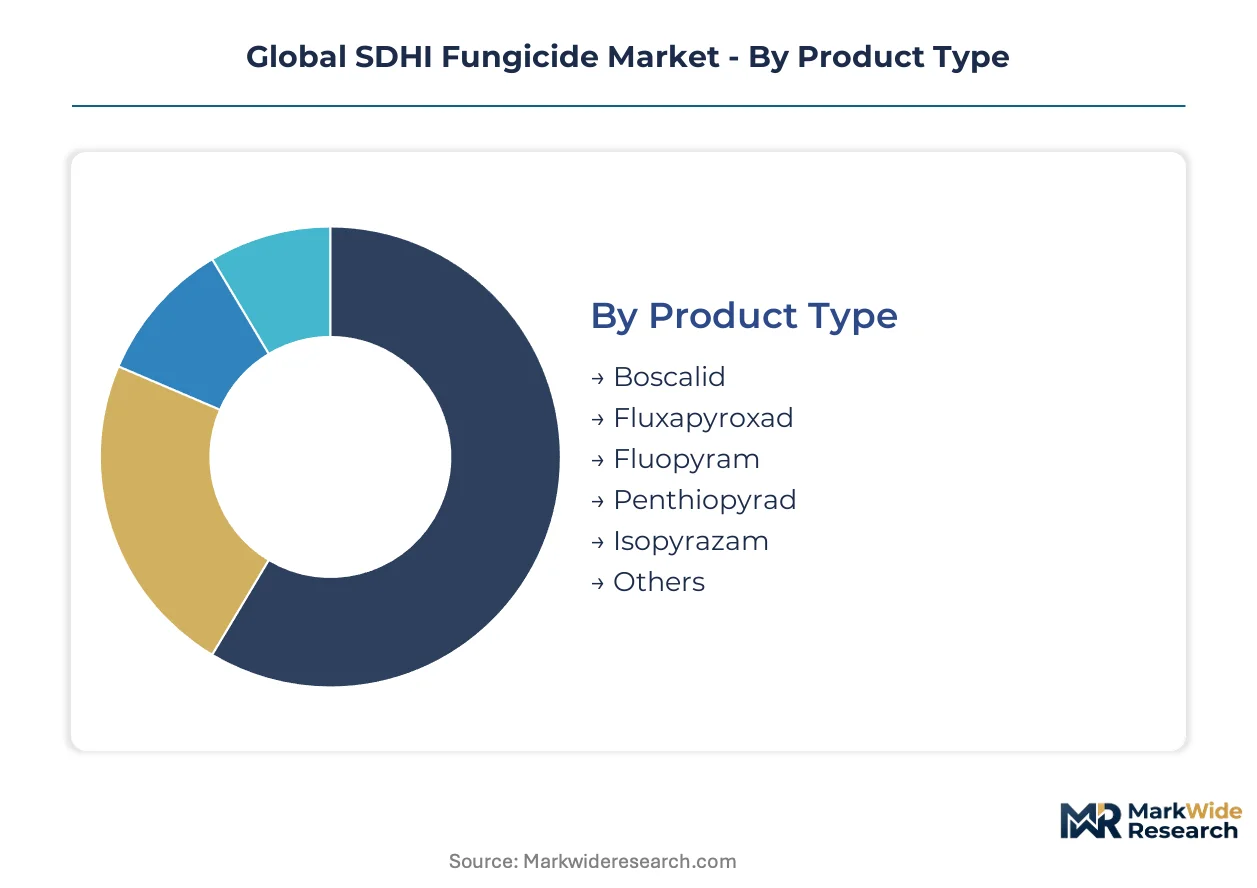
SDHI fungicide segmentation reveals distinct procurement patterns across molecule chemistry, crop specificity, and formulation delivery. Manufacturers align R&D investment with resistance management protocols and residue tolerance schedules that vary sharply by end-use channel.
Product Type:
Fluxapyroxad and boscalid dominate export-oriented volume, while fluopyram concentrates in domestic specialty crop channels with stringent residue limits.
- Fluxapyroxad:Captive synthesis of intermediates by major manufacturers secures cost positions in Latin American cereal and oilseed programs. Brazilian soybean-corn rotation belts sustain repeat application volumes where protective efficacy against rust complexes justifies premium positioning.
- Boscalid:Broad-spectrum activity against Botrytis and Alternaria species supports vineyard and vegetable registrations across EU member states. Germany and France demonstrate concentrated uptake in integrated pest management protocols where reduced-application-rate chemistries align with Farm to Fork targets.
- Fluopyram:Vineyard and specialty crop segments with stringent residue limits drive registration investments.
- Penthiopyrad:Turf and ornamentals applications benefit from specialized distributor technical support infrastructure.
- Isopyrazam:European cereal systems anchor demand through seed-treatment-to-foliar protocol bundles.
- Others:Emerging SDHI molecules target niche pathogen resistance profiles in regional markets.
Fluxapyroxad holds the largest share; momentum sits with fluopyram in high-value specialty segments.
Application:
Cost tier stratification separates broadacre commodity programs from precision vineyard and vegetable systems requiring drift-reduction formulations.
- Cereals:Seed-treatment-to-foliar protocol integration consolidates purchasing decisions around single-supplier programs in Germany and France. Bundled fungicide packages from germination through flag leaf stage compress standalone product selection.
- Vineyards:Micro-encapsulation technology for controlled-release delivery meets EU drift reduction mandates while compressing seasonal labor requirements. European operators adopt these systems to maintain protective coverage through rainfall events.
- Fruits:Residue limit stringency conditions import acceptance pathways into regulated markets.
- Vegetables:Suspension concentrate formulations displace wettable powders where operator exposure limits drive selection.
- Oilseeds:Asian soybean rust pressure in Brazil sustains premium deployment across growing seasons.
- Turf & Ornamentals:Discrete margin pool served by specialized distributors with dedicated technical support infrastructure.
Cereals command the deepest volume; vineyards are climbing the fastest on precision formulation premiums.
End User:
Customer type determines technical service intensity and procurement scale, with cooperatives and distributors anchoring volume while consultants drive specification decisions.
- Agricultural Cooperatives:Centralized purchasing across member farms generates scale economies in Brazilian and Indian broadacre programs. Negotiating leverage concentrates procurement around established manufacturer relationships with proven registration track records.
- Agrochemical Distributors:Inventory carrying capacity and local regulatory compliance expertise condition market access in fragmented farmer networks. Brazilian ANVISA re-evaluation coordination requirements favor distributors with dedicated regulatory affairs capabilities.
- Crop Consultants:Specification influence in resistance management protocol design creates pull-through demand for partner chemistry combinations.
- Independent Farmers:Price sensitivity and smaller application scale favor generic or second-tier formulator sourcing where available.
Agricultural cooperatives hold the largest share; momentum sits with agrochemical distributors expanding technical service capabilities.
Formulation Type:
Application precision and environmental load regulations are displacing legacy delivery systems in regulated markets.
- Suspension Concentrate:Drift reduction properties and operator exposure limits in vineyard and vegetable applications displace wettable powder alternatives. European regulatory frameworks accelerate adoption where aquatic toxicity concerns elevate environmental fate requirements.
- Wettable Powder:Cost-sensitive broadacre segments in India and Brazil retain volume despite handling and drift limitations.
- Granules:Seed treatment applications benefit from controlled-release properties in soil-incorporated delivery.
- Emulsifiable Concentrate:Solvent-based systems face regulatory pressure from VOC restrictions in EU and North American markets.
Suspension concentrate holds the largest share; momentum sits with granules in precision seed treatment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural cooperatives in Brazil, Germany, and India anchor procurement scale for SDHI fungicides, with distributor networks in each country conditioning technical service intensity and registration compliance capabilities.
Brazil
Asian soybean rust pressure across Mato Grosso and Paraná sustains repeat application volumes of fluxapyroxad-based formulations. ANVISA coordinates with the Ministry of Agriculture on re-evaluation cycles that now incorporate pollinator risk assessments into fungicide renewal criteria. The soybean-corn rotation belts of the Cerrado region concentrate premium fungicide deployment where protective efficacy justifies higher input costs.
Germany
Seed-treatment-to-foliar protocol integration consolidates purchasing decisions around single-supplier crop protection programs in Bavaria and North Rhine-Westphalia. The EU Green Deal's Farm to Fork strategy accelerates regulatory reviews that favor reduced-application-rate chemistries in cereal systems. BASF SE leverages captive synthesis capabilities from its Ludwigshafen complex to serve export channels across Latin America.
United States
Vineyard operators in California's Central Valley adopt micro-encapsulation technologies to meet EPA drift reduction mandates while compressing seasonal labor requirements. The EPA's Endangered Species Act consultation requirements extend registration timelines and elevate ecotoxicology data costs for new SDHI entrants. Fluopyram registrations concentrate in specialty crop segments where residue limits are most stringent.
India
Centralized purchasing across member farms in Maharashtra and Gujarat generates scale economies in broadacre cereal and oilseed programs. The Central Insecticides Board maintains distinct residue tolerance schedules that condition import acceptance and local manufacturing investment decisions. Punjab's wheat belt demonstrates concentrated uptake of resistance management protocols requiring azole-strobilurin co-applications.
France
Integrated pest management protocols in the Champagne and Bordeaux wine regions drive suspension concentrate adoption where operator exposure limits govern formulation selection. REACH substance evaluation protocols demand additional aquatic toxicity and metabolite fate studies for SDHI renewal cycles. Syngenta Group anchors portfolio breadth through bundled fungicide packages from germination through flag leaf stage in the Paris Basin cereal zone.
Global SDHI Fungicide Market Competitive Landscape
Player mix skews toward integrated agrochemical conglomerates with captive synthesis infrastructure and established registration track records across multiple jurisdictions. The competitive terrain rewards backward integration into active ingredient production and regulatory affairs capabilities that compress approval timelines. Three archetypes dominate: multinational conglomerates with seed-to-spray portfolios, mid-tier formulators serving regional export channels, and specialized distributors with technical support infrastructure. Dominant competitive moves include captive supply of fluxapyroxad intermediates and strategic seed-treatment-to-foliar protocol bundling.
Among the integrated conglomerates, BASF SE, Syngenta Group, and Bayer AG occupy positions that exemplify divergent strategic emphases. BASF SE represents the synthesis-integrated archetype with cost positions anchored in captive intermediate production. Syngenta Group exemplifies protocol-bundling competitive logic through integrated seed-treatment-to-foliar fungicide systems. Bayer AG sits within the specialty-crop registration tier where fluopyram vineyard registrations command premium positioning. These three entities collectively illustrate how R&D concentration, regulatory dossier depth, and geographic footprint interact to structure competitive access in this chemistry class.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Nufarm Limited |
| Syngenta Group |
| Adama Ltd |
| UPL Limited |
| BASF SE |
| FMC Corporation |
| Valent U.S.A. Corporation |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Suspension concentrate formulations displacing wettable powders in vineyard and vegetable applications are simultaneously shifting production geography toward EU formulation hubs and compressing pricing premiums for legacy powder products. This substitution dynamic concentrates margin capture with manufacturers possessing captive micro-encapsulation capabilities while eroding cost-competitive positioning for second-tier powder formulators in Latin American export channels.
Pricing Analysis
Cost-plus contracts with active ingredient indexation dominate procurement between Brazilian agricultural cooperatives and established manufacturers, insulating suppliers from raw material volatility while transferring formulation efficiency gains to buyers. Three-tier pricing structure across premium, standard, and economy levels separates fluxapyroxad-based proprietary formulations from licensed generics and unbranded wettable powders. Pricing pressure stems from ANVISA's pollinator risk assessment requirements extending registration renewal timelines and elevating compliance costs. Agricultural cooperatives in Mato Grosso demonstrate highest price sensitivity, while vineyard operators in Champagne accept premium positioning for drift-certified suspension concentrates.
Supply Chain Analysis
Inventory lead times for fluxapyroxad intermediates stretch 16-24 weeks for non-integrated formulators sourcing from China and India, compressing to 6-8 weeks for manufacturers with captive Ludwigshafen or Basel synthesis capabilities. Active ingredient production concentrates in Germany, China, and India, with formulation finishing distributed across Brazil, France, and the United States. Raw material dependencies include chloro-nicotinic acid derivatives, pyrazole carboxylic acid building blocks, and specialized surfactant packages. Single-source vulnerability in pyrazole intermediate supply from Zhejiang province creates concentration risk. Distribution runs through agrochemical distributor networks with ANVISA compliance capabilities in Brazil, and through cooperative procurement consortia in Germany and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SDHI fungicide market is entering a cyclical recovery phase as resistance management protocol tightening across Brazil, Germany, and India forces replacement demand for co-formulated products. Asian soybean rust pressure cycles and EU Farm to Fork regulatory acceleration provide the cyclical impetus.
For Market Incumbents: Fortify captive synthesis positions in fluxapyroxad intermediates through backward integration into pyrazole carboxylic acid production, defending against Chinese intermediate cost erosion. Deepen seed-treatment-to-foliar protocol bundling in European cereal systems to lock out competitor molecule substitution. ANVISA's pollinator risk integration threatens standalone SDHI renewal timelines; invest in combination study dossiers preemptively. For New Entrants and Emerging Players: Technical support infrastructure gaps in India's Central Insecticides Board residue compliance consulting create service-layer entry points where incumbents under-serve fragmented farmer networks. Target Maharashtra and Gujarat agricultural cooperatives with ISO 17025 analytical service bundling. Penetrate through distributor regulatory affairs partnerships rather than direct manufacturer competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier formulators in Latin America lacking captive synthesis but holding ANVISA registration track records. Five-to-ten year viability hinges on regulatory dossier depth rather than molecule novelty alone. Watch for REACH substance evaluation outcome clustering as inflection signal separating compliant from stranded asset portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Intermediate Synthesis Expansion | Backward integration into pyrazole carboxylic acids secures cost positions against Chinese supply volatility. |
| Seed-to-Spray Protocol Bundling | Integrated treatment packages from germination through flag leaf stage compress competitor access in German cereal zones. |
| Micro-Encapsulation Technology Licensing | Controlled-release delivery systems meet EU drift mandates while opening vineyard premium segments. |
| Regulatory Affairs Capability Acquisition | ANVISA and REACH submission expertise accelerates renewal timelines and defends registration portfolios. |
| Residue Analytical Laboratory Accreditation | ISO 17025 certification creates service-revenue adjacencies and conditions EU market access. |
Research Methodology
Cross-validation between manufacturer shipment data and import customs records anchors the qualitative findings on channel inventory dynamics. Primary interviews with regulatory affairs directors at agrochemical conglomerates, procurement managers at Brazilian agricultural cooperatives, and technical directors at formulation laboratories combined with secondary validation from ANVISA registration databases, REACH dossier submissions, and Central Insecticides Board tolerance schedules. Bottom-up volume builds from crop-specific application rate assumptions triangulate against top-down manufacturer revenue disclosures.
Sensitivity analysis across resistance management protocol adoption scenarios and regulatory timeline variations stress-tests projection robustness. The analytical framework models molecule chemistry, crop specificity, formulation delivery, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derive from segmented volume builds incorporating application rate compression from micro-encapsulation adoption and resistance rotation requirement intensity. Forecast inputs include Asian soybean rust pressure indices and EU Farm to Fork implementation pace assumptions.
Material uncertainties — abrupt regulatory reclassification, supply chain disruption in Chinese intermediate production, and pollinator risk assessment outcome reversals — sit outside the modeled envelope. Forecasts reflect documented assumptions on protocol adoption rates and registration timeline continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Grape Fungicides Market
Crop Protection
Global Seed Treatment Chemicals Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
Sweet Potato Fly Market
Crop Protection
Thailand Crop Protection Chemicals Market
Crop Protection
North America Acaricides Market
Crop Protection
Low-Odor, Enclosed-Greenhouse Foliar Protection Market
Crop Protection
Europe Nematicide Market
Crop Protection
Grain Fumigants Market
Crop Protection
Italy Crop Protection Chemicals (Pesticides) Market
Crop Protection
Fosthiazate Market
Crop Protection
Tebuconazole Epoxide Market
Crop Protection
Synthetic Pesticide Market
Crop Protection
Europe Insecticides Market
Crop Protection
Corn Preemergence Herbicide Market
Crop Protection
France Crop Protection Chemicals Market