
 Agricultural Pumps Market | 2026-2036
Agricultural Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Pumps Market Analytics
Preventive maintenance contracts and remote monitoring subscriptions is decoupling equipment sales from long-term vendor relationships in the agricultural pumps sector. Grundfos leverages its digital service platform to anchor recurring revenue streams across European dairy and horticulture operations. Xylem Inc competes through vertical integration into pump control software, while KSB SE & Co sustains manufacturing scale advantages in cast-iron centrifugal systems for emerging-market irrigation districts.
Agricultural pumps are electromechanical devices designed to lift, pressurize, or transfer water and nutrient solutions for crop production, typically rated by flow rate, total dynamic head, and hydraulic efficiency. Submersible pumps dominate deep-well extraction where suction lift limits surface-mounted alternatives, while centrifugal pumps occupy surface-water and canal-fed distribution networks. Smart irrigation technology is capturing margin pools through sensor-integrated variable frequency drives that modulate motor speed against real-time soil moisture, though diesel-powered units still lead in off-grid regions with unreliable electric infrastructure.
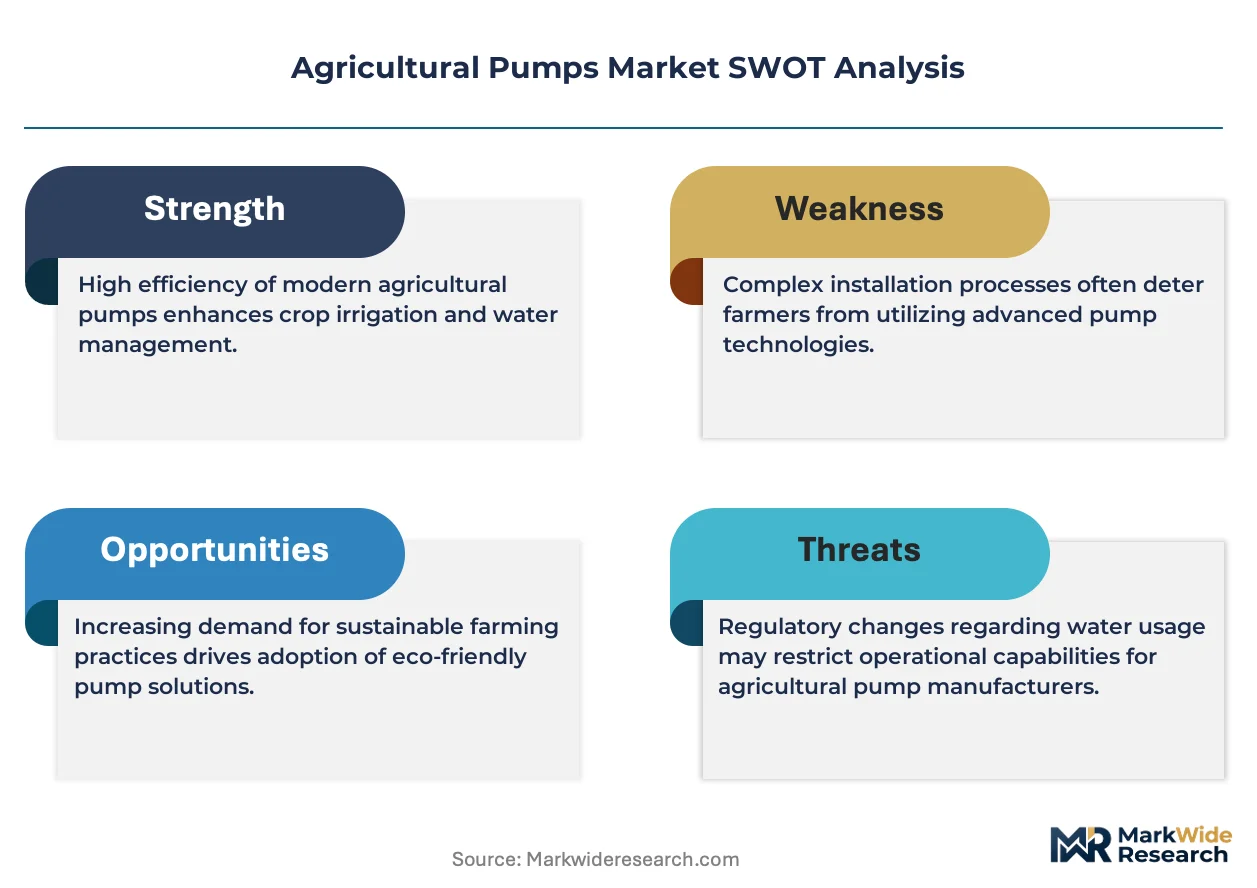
The US EPA Energy Star program and India's Bureau of Energy Efficiency (BEE) star-rating mandates are tightening minimum efficiency standards for electric motor-driven pumps, forcing redesigns toward permanent magnet synchronous motors. REACH compliance in Europe restricts certain elastomer compounds in diaphragm pump seals, redirecting material sourcing toward fluoropolymer alternatives. Stakeholders must weigh capital commitments to solar-diesel hybrid architectures against the regulatory trajectory of fossil-fuel pump phase-outs in key procurement markets.
Market Dynamics
The transition from diesel to solar-electric pumping architectures is compressing replacement cycles and rewiring vendor-customer relationships across commercial farming corridors. India's PM-KUSUM subsidy regime and tightening EPA efficiency mandates are accelerating capital redeployment toward renewable-powered systems.
Growth Catalysts
- Drip Irrigation Scale-Up:Large horticulture operations in Israel and Spain are deploying pressure-compensated networks that demand variable-frequency drive pumps. Equipment refresh timelines have shortened from twelve to seven years.
- PM-KUSUM Scheme:India's solar pump subsidy program targets 3.5 million grid-connected and standalone units. Capital flows are redirecting from diesel infrastructure toward photovoltaic-powered submersible systems.
- Groundwater Depletion Mandates:China's Ministry of Water Resources enforces deeper borewell extraction limits across the North China Plain. Higher-head submersible units are displacing surface-mounted centrifugal alternatives.
Market Restraints
- Permanent Magnet Motor Cost Concentration:Neodymium supply chains concentrate in Chinese rare-earth processing facilities. Price volatility in magnet materials compresses margins for efficiency-tier pump manufacturers.
- REACH Elastomer Restrictions:ECHA limitations on nitrile rubber compounds in diaphragm seals force fluoropolymer sourcing. European pump assemblers face eighteen-month qualification timelines for alternative materials.
- Off-Grid Diesel Entrenchment:Unreliable rural electrification in sub-Saharan Africa sustains fossil-fuel pump dominance. Solar-battery hybrid architectures remain uneconomical below fifty-meter head requirements.
Strategic Opportunities
- Sensor-Integrated VFD Convergence:Soil moisture telemetry and variable frequency drives are merging into unified control platforms. OEMs capturing this integration capture recurring software revenue streams.
- Preventive Maintenance Subscriptions:Remote vibration monitoring and predictive bearing replacement are unbundling service from equipment sales. Dairy cooperatives in Denmark and the Netherlands are piloting per-hectare pumping-as-a-service contracts.
- Cast-Iron Centrifugal Scale:India's Bureau of Energy Efficiency star-rating mandates create tiered efficiency markets. Domestic foundries with captive iron supply are positioned for volume irrigation district procurement.
Industry Challenges
- Electromechanical Skill Scarcity:Permanent magnet synchronous motor repair requires specialized winding expertise unavailable in rural service networks. Training pipelines lag solar pump deployment rates.
- Legacy Control Integration:Analog float-switch irrigation systems resist digital retrofit. Compatibility layers add cost and failure points in mixed-technology installations.
- Dual Certification Burden:Separate BEE and CE efficiency testing protocols duplicate validation expense. Mid-tier manufacturers face six-month market entry delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Pumps Market |
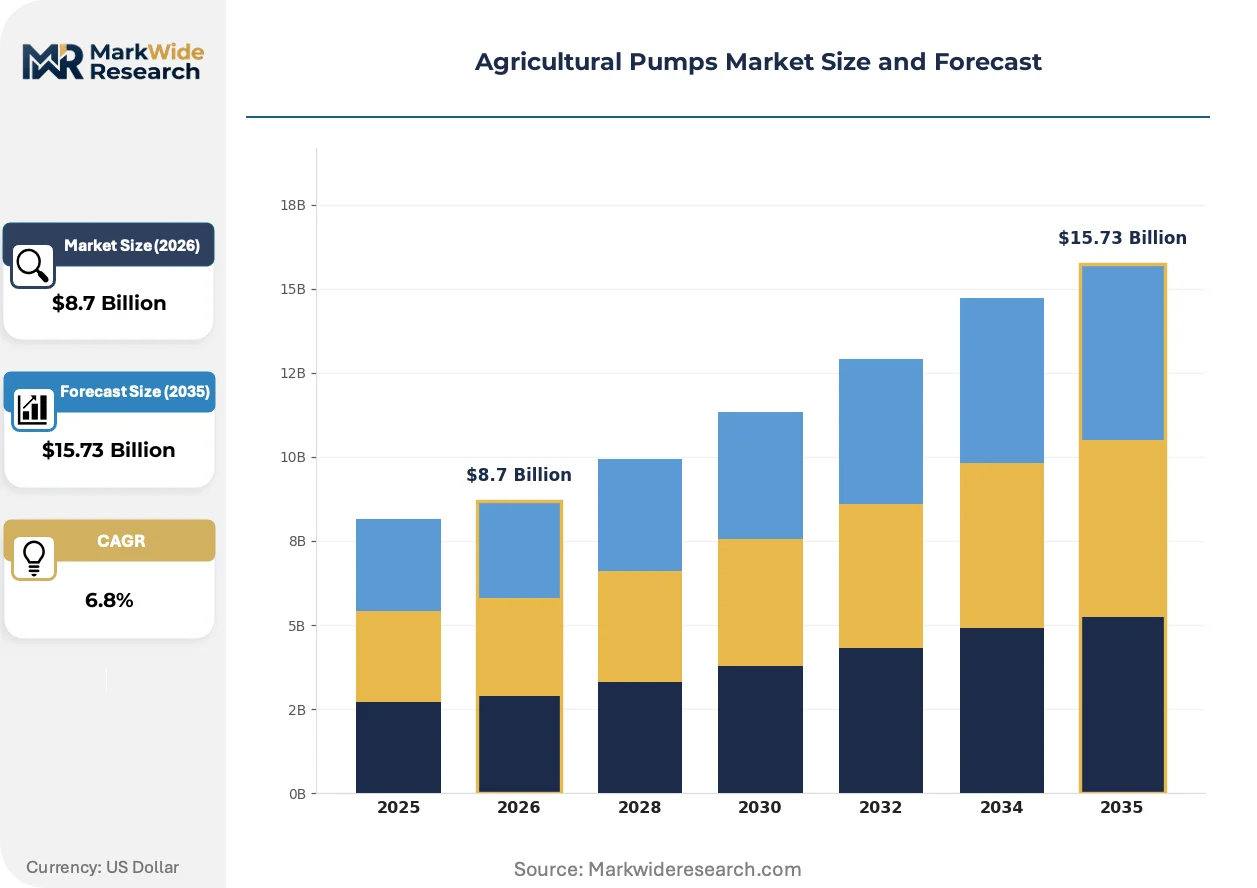
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Centrifugal Pumps, Diaphragm Pumps, Gear Pumps End Use: Irrigation, Drainage, Water Transfer, Fertilizer Application Power Source: Electric, Diesel, Solar, Wind Technology: Smart Irrigation, Variable Frequency Drives, Automation, Sensor Integration |
| Companies Covered | Grundfos, Xylem Inc, KSB SE & Co, Flowserve Corporation, Lindsay Corporation, Valmont Industries, Jain Irrigation Systems, Sulzer Ltd, Pentair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Pumps Market Evolving Landscape
Digital service platforms and renewable power architectures are fragmenting traditional equipment-only business models. Vendors now compete on telemetry integration and energy optimization rather than hydraulic performance alone.
Variable frequency drive technology is modularizing pump system architecture. Sensor-integrated VFD units enable real-time head and flow adjustment against soil moisture telemetry. Large-scale almond and pistachio growers in California's Central Valley are retrofitting existing submersible motors with aftermarket drive controllers. This modularity is compressing the addressable market for fixed-speed pump OEMs while expanding margins for control software specialists.
REACH compliance deadlines are forcing material transitions across European pump manufacturing. ECHA restrictions on phthalate plasticizers in cable insulation and nitrile seals require fluoropolymer and thermoplastic elastomer substitutions. Diaphragm pump assemblers serving Dutch greenhouse irrigation face twelve-month requalification cycles. German centrifugal manufacturers are consolidating supplier bases to reduce compliance audit burden.
Service unbundling is displacing bundled equipment-and-maintenance contracts. Dairy operations in Denmark now procure pumping capacity through outcome-based subscriptions tied to liters-per-kilowatt-hour performance. Grundfos and Xylem are restructuring field service organizations around remote diagnostics rather than scheduled preventive visits. This shift is most visible in high-value horticulture clusters where downtime costs exceed equipment depreciation.
Agricultural Pumps Market Segmentation
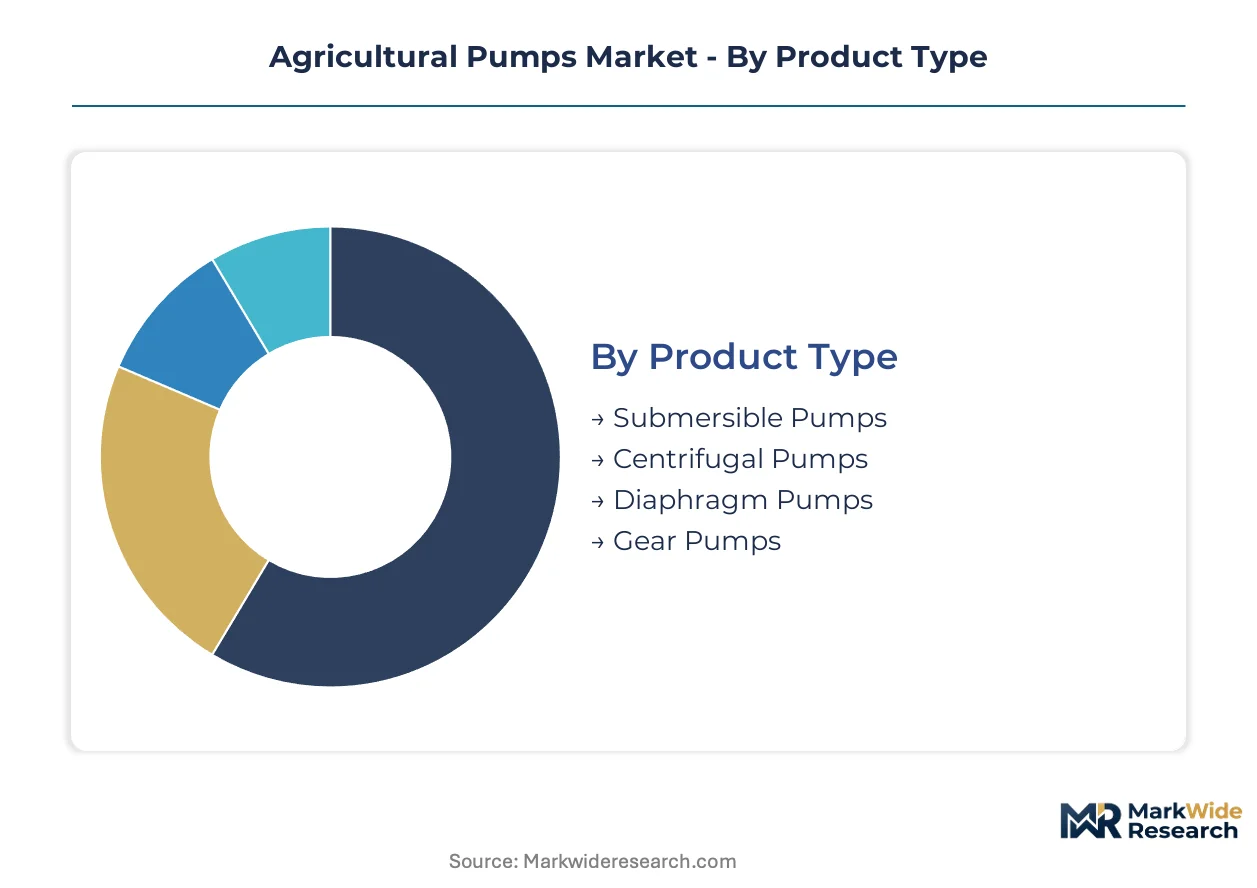
Pump specification choices directly determine replacement timing and energy economics across commercial farming operations. Segmentation reveals where upgrade cycles compress and where legacy equipment persists despite efficiency penalties.
Product Type:
Replacement cycles diverge sharply between deep-well extraction systems and surface-mounted distribution equipment.
- Submersible Pumps:Multi-stage centrifugal units designed for vertical immersion in borewells, rated by total dynamic head and motor diameter. Demand concentrates in India's Indo-Gangetic Plain and China's North China Plain, where groundwater depletion mandates deeper extraction and higher-head configurations.
- Centrifugal Pumps:Surface-mounted volute or turbine designs for canal-fed irrigation and low-lift water transfer. Spanish horticulture clusters and California's Central Valley almond growers favor these for pressure-compensated drip networks, though suction lift limits constrain deployment depth.
- Diaphragm Pumps:Positive-displacement units with reciprocating elastomer membranes for precise chemical metering. REACH compliance in Europe forces fluoropolymer seal transitions, extending qualification timelines for Dutch greenhouse suppliers.
- Gear Pumps:Intermeshing rotor designs for viscous fertilizer suspensions and slurry transfer. Brazilian sugarcane cooperatives deploy these for fertigation systems where abrasive particulate resistance outweighs efficiency concerns.
Volume placements concentrate in Submersible Pumps; the faster expansion belongs to Centrifugal Pumps.
End Use:
Application-specific duty cycles reshape procurement priorities between continuous-operation irrigation and intermittent drainage workloads.
- Irrigation:Continuous-duty pumping for sprinkler, drip, and flood systems across field crops and orchards. Israeli kibbutzim and Spanish Almería greenhouse complexes drive specification toward variable-frequency compatibility.
- Drainage:Intermittent dewatering of saturated soils in rice paddies and flood-prone lowlands. Bangladesh's coastal belt and Vietnam's Mekong Delta sustain demand for portable diesel units where electrification remains unreliable.
- Water Transfer:Bulk movement between storage reservoirs, canals, and distribution headers. Australian Murray-Darling Basin water authorities specify large-diameter mixed-flow designs for inter-basin transfer infrastructure.
- Fertilizer Application:Precision injection of nutrient solutions into pressurized irrigation lines. Brazilian citrus groves and Florida vegetable operations favor diaphragm and peristaltic architectures for chemical compatibility.
Revenue concentration sits with Irrigation; Drainage claims the steepest expansion trajectory as climate volatility intensifies.
Power Source:
Capital redeployment patterns separate subsidy-driven renewable adoption from entrenched fossil-fuel infrastructure in off-grid corridors.
- Electric:Grid-connected or generator-fed AC induction and permanent magnet synchronous motors. India's BEE star-rating mandates and US EPA Energy Star standards force redesigns toward higher efficiency tiers.
- Diesel:Compression-ignition engines for standalone operation beyond grid reach. Sub-Saharan Africa's Sahel region and Afghanistan's Helmand Valley sustain this segment despite fuel price volatility.
- Solar:Photovoltaic-powered DC or AC submersible systems with battery or direct-drive architectures. India's PM-KUSUM subsidy regime redirects capital flows toward this category across Rajasthan and Gujarat.
- Wind:Mechanical windmill pumps and small turbine-electric hybrids for coastal and plains applications. Argentine Patagonia and South African Karoo retain niche deployments where wind resource consistency exceeds solar yield.
Installed base dominance remains with Electric; Solar gains share fastest where subsidy mechanisms align with rural electrification gaps.
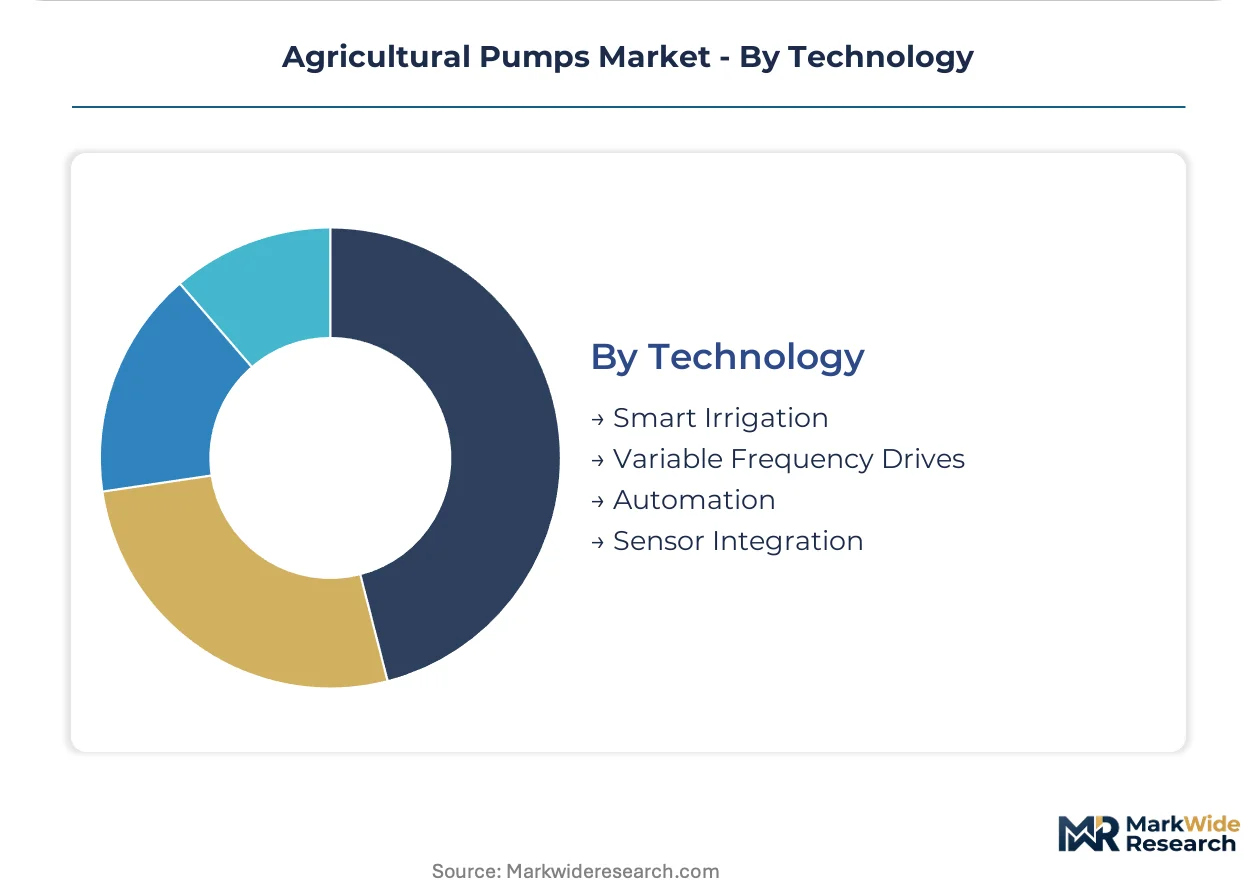
Technology:
Control-layer integration determines margin capture between hardware-only vendors and software-anchored service providers.
- Smart Irrigation:Networked control platforms coordinating pumps, valves, and soil sensors through centralized telemetry. California's Central Valley pistachio growers and Dutch greenhouse clusters pilot subscription-based optimization services.
- Variable Frequency Drives:Solid-state motor controllers modulating speed against real-time head and flow requirements. Aftermarket retrofit kits compress replacement timelines for fixed-speed submersible motors in mature irrigation districts.
- Automation:Programmable logic controllers and remote terminal units for unmanned operation sequences. Australian broadacre wheat operations deploy these for scheduling around time-of-use electricity tariffs.
- Sensor Integration:Soil moisture, pressure transducer, and flowmeter inputs feeding closed-loop control algorithms. Israeli drip irrigation OEMs bundle these as proprietary ecosystems, raising switching costs for growers.
Hardware shipments concentrate in Variable Frequency Drives; Sensor Integration climbs the fastest as telemetry unbundles from pump equipment sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Indo-Gangetic Plain anchors global agricultural pump deployment, with groundwater depletion across Uttar Pradesh and Punjab mandating deeper borewell extraction and higher-head submersible configurations.
India
PM-KUSUM subsidies redirect capital toward solar-powered submersible systems across Rajasthan and Gujarat. The Bureau of Energy Efficiency's star-rating mandates force redesigns toward permanent magnet synchronous motors. Punjab's rice-wheat belt concentrates replacement demand as diesel pumps face phase-out timelines.
China
The North China Plain's extraction depth limits drive demand for multi-stage submersible units. The Ministry of Water Resources enforces stricter groundwater withdrawal permits across Hebei and Shandong provinces. Shandong's foundry corridor supplies cast-iron centrifugal housings for domestic irrigation districts.
United States
California's Central Valley almond and pistachio growers retrofit fixed-speed motors with aftermarket variable frequency drives. EPA Energy Star efficiency standards tighten minimum motor performance tiers. Fresno County's irrigation cooperatives pilot subscription-based pumping-as-a-service contracts.
Spain
Almería's greenhouse complexes deploy pressure-compensated drip networks requiring variable-frequency compatibility. REACH compliance deadlines force fluoropolymer seal transitions in diaphragm pump assemblies. Murcia's citrus belt sustains demand for surface-mounted centrifugal distribution systems.
Brazil
São Paulo state's sugarcane cooperatives deploy gear pumps for abrasive fertigation suspensions. ANVISA regulations govern chemical compatibility in precision injection systems. The Cerrado agricultural frontier expands center-pivot irrigation requiring high-flow electric centrifugal units.
Agricultural Pumps Market Competitive Landscape
Capital-heavy foundry operators compete with asset-light control software specialists for margin capture in agricultural pumping systems. Market structure tilts toward consolidation among integrated motor-pump assemblers, while sensor-telemetry providers fragment the control layer. Three archetypes dominate: European digital service platforms, Asian scale manufacturers with captive iron supply, and North American irrigation system integrators. Competitive moves concentrate on backward integration into permanent magnet motor production and strategic partnerships for solar-diesel hybrid architectures.
Among European digital service platforms, Grundfos anchors recurring revenue models through remote monitoring subscriptions, while Xylem Inc exemplifies control software specialization. KSB SE & Co occupies a position within the scale-driven tier of cast-iron centrifugal manufacturing. These three represent contrasting strategic postures: telemetry-anchored services, vertical integration into pump control systems, and foundry-scale cost positioning for emerging-market procurement.
| Leading Market Players |
|---|
| Grundfos |
| Xylem Inc |
| KSB SE & Co |
| Flowserve Corporation |
| Lindsay Corporation |
| Valmont Industries |
| Jain Irrigation Systems |
| Sulzer Ltd |
| Pentair |
| Others |
Value Network & Pricing Analysis
Star-rating certification divergence between BEE-compliant premium tiers and unlabeled commodity units manifests in both pricing premiums and foundry sourcing patterns across Indian irrigation districts. Permanent magnet motor mandates concentrate procurement power among Tier-1 assemblers with captive neodymium supply agreements, while smaller fabricators absorb margin compression through gray-market magnet channels.
Pricing Analysis
Margin tightening in standard-efficiency electric tiers reflects BEE star-rating compliance costs and permanent magnet motor redesigns. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated VFD bundles from fixed-speed cast-iron units. Pricing pressure stems from neodymium price volatility and REACH fluoropolymer qualification delays. Smallholder cooperatives in sub-Saharan Africa exhibit highest price sensitivity; European dairy operations show lowest sensitivity due to energy-cost recovery timelines.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Mumbai anchor hub-and-spoke patterns for spare parts and aftermarket controllers. Manufacturing concentrates in China, India, and Germany. Neodymium magnet supply draws from Chinese rare-earth processing; cast-iron housings source from Shandong and Punjab foundries. Single-source vulnerability in magnet supply chains threatens margin stability. Distribution runs through irrigation equipment dealers and OEM-direct channels for large horticulture contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards players capturing upstream motor production and downstream telemetry subscriptions. Permanent magnet synchronous motor supply and sensor-integrated control platforms represent the decisive integration levers.
For Market Incumbents: Extend preventive maintenance subscription coverage to anchor recurring revenue against Chinese scale manufacturers entering European horticulture markets. Consolidate supplier bases to reduce REACH compliance audit burden. Deepen backward integration into permanent magnet motor winding to secure magnet allocation priority.
For New Entrants and Emerging Players: The premium-to-economy price gap in Indian solar pump retrofit markets creates entry space for DC submersible specialists. Target Rajasthan and Gujarat PM-KUSUM subsidy corridors with direct-to-farmer financing partnerships. Lead with modular VFD retrofit kits that bypass incumbent dealer networks.
For Investors and Strategic Acquirers: Re-rating potential sits with sensor-telemetry specialists given convergence of soil moisture data and pump control algorithms. Long-term viability favors platforms with recurring software revenue over hardware-only foundry operators. Watch BEE star-rating enforcement intensity as inflection signal for premium tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Motors | Captive neodymium supply hedges against Chinese export quota volatility for Tier-1 assemblers. |
| Sensor-Telemetry Platform Launch | Soil moisture integration with VFD control captures recurring SaaS revenue from California almond growers. |
| REACH Fluoropolymer Qualification | Twelve-month seal requalification timelines create compliance moats for early-mover Dutch greenhouse suppliers. |
| Solar-Diesel Hybrid Architecture Partnership | PM-KUSUM subsidy alignment accelerates deployment across Rajasthan's off-grid irrigation corridors. |
| Preventive Maintenance Subscription Rollout | Per-hectare pumping-as-a-service contracts unbundle equipment sales in Danish dairy cooperatives. |
Research Methodology
Trade databases, BEE star-rating registries, and PM-KUSUM disbursement records formed the secondary backbone for market sizing. Primary interviews with irrigation cooperative managers, OEM procurement directors, foundry operations heads, and aftermarket service technicians supplied ground-level deployment data. Bottom-up unit shipment estimates triangulated against top-down energy consumption models across the analysis window.
Historical trendline analysis tracked replacement cycle compression from twelve to seven years in drip irrigation corridors. Segmentation dimensions modeled include pump type, power source architecture, control technology tier, and regional subsidy eligibility. CAGRs derived from fitted growth curves against policy milestone timelines. Groundwater depth trajectories in the Indo-Gangetic Plain and North China Plain informed submersible pump demand projections.
Inputs from Indian Ministry of New and Renewable Energy officials were available through the study window; gaps in real-time PM-KUSUM installation data introduce uncertainty bands around solar pump penetration rates. Forecasts reflect documented assumptions regarding subsidy continuity and neodymium price stabilization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Crop Spraying Drone Market
Agricultural Equipment
Solar Fruit Dryer Market
Agricultural Equipment
Forestry Equipment Market
Agricultural Equipment
Agricultural Rake Market
Agricultural Equipment
North America Electric Zero Turn Mower Market
Agricultural Equipment
Billhook Market
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Food Bucket Elevators Market
Agricultural Equipment
Manure Separator Market
Agricultural Equipment
Planter Market
Agricultural Equipment
Aquatic Weed Harvester Market
Agricultural Equipment
Pond Aeration System Market
Agricultural Equipment
Soil Aerators Market
Agricultural Equipment
India Color Sorter Market
Agricultural Equipment
Fishing Net Market
Agricultural Equipment
Battery Powered Cultivators Market