
 North America Agricultural Disinfectants Market | 2026-2036
North America Agricultural Disinfectants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Agricultural Disinfectants Market Analytics
Veterinary pharmacology expertise scarcity is redrawing competitive boundaries across the North America agricultural disinfectants landscape. Zoetis Services LLC leverages its animal health heritage to sustain channel dominance in livestock biosecurity applications. Neogen Corporation anchors its position through specialized diagnostics-integrated sanitation protocols. DuPont competes on manufacturing scale for quaternary ammonium compound production.
Agricultural disinfectants comprise formulated biocidal agents designed to eliminate pathogenic microorganisms from farming environments, typically containing active concentrations of quaternary ammonium salts, chlorine releasers, or peroxygen compounds effective against bacteria, viruses, and fungi in agricultural settings. These formulations serve the primary commercial purpose of preventing disease transmission across intensive farming operations where animal density and crop monoculture amplify contagion risk. Quaternary ammonium compounds occupy the largest product share due to broad-spectrum efficacy and surface compatibility, while hydrogen peroxide formulations represent the fastest-growing category driven by residue-free profiles and organic farming eligibility. Equipment sanitation applications command premium pricing relative to soil treatment, reflecting the criticality of pathogen break chains in milking parlors and processing machinery.
EPA registration under FIFRA governs active ingredient approval and label claims for all agricultural disinfectants sold in the United States, while Health Canada's PMRA maintains parallel regulatory authority for Canadian market access. The USDA National Organic Program further constrains formulation choices for certified operations, directly shaping R&D investment toward peroxygen and botanical alternatives. Stakeholders must monitor evolving state-level antibiotic resistance mandates that increasingly extend to biocidal stewardship in animal agriculture.
Market Dynamics
Livestock biosecurity mandates from USDA and EPA registration tightening are compressing formulation choices while concentrating procurement among large integrated operations across the Midwest Corn Belt and Canadian prairie provinces.
Growth Catalysts
- USDA National Organic Program expansion:Certified organic acreage growth across Wisconsin and Quebec is accelerating peroxygen compound demand for residue-free sanitation protocols.
- Concentrated animal feeding operation density:Iowa, Minnesota, and Nebraska dairy clusters are mandating pathogen break chains through equipment disinfection schedules.
- Antibiotic resistance stewardship extension:State-level biocidal usage tracking in California and New York is institutionalizing veterinary disinfectant protocols.
Market Restraints
- Active ingredient supply concentration:Quaternary ammonium compound feedstock production clusters in Gulf Coast petrochemical corridors create input vulnerability.
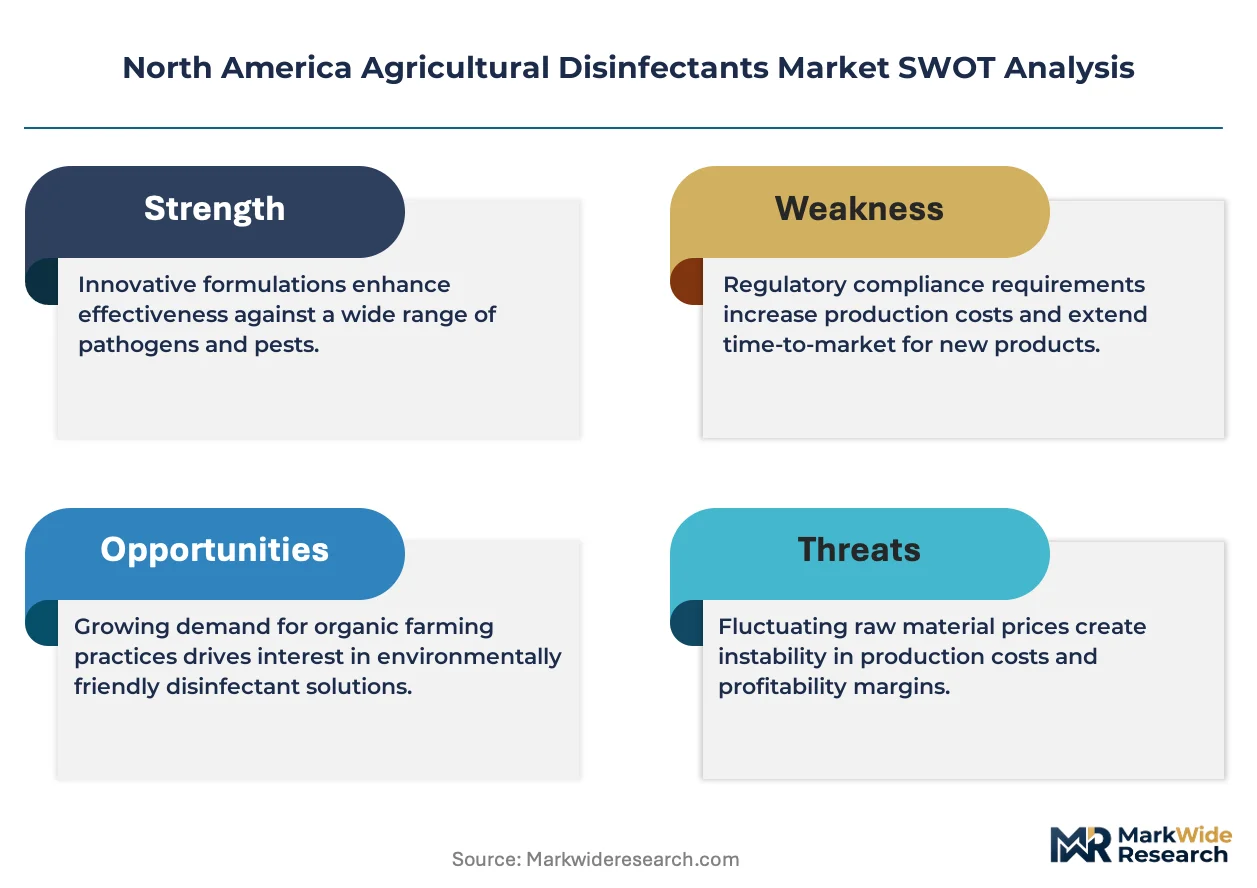
- EPA FIFRA registration timelines:New active ingredient approval cycles extending 24-36 months delay novel formulation commercialization.
- Chlorine releaser substitution pressure:Peroxygen and botanical alternatives are displacing hypochlorite-based products in organic-certified operations.
Strategic Opportunities
- Canadian prairie province expansion:Saskatchewan and Manitoba hog operation consolidation is creating underserved biosecurity procurement nodes.
- Diagnostics-integrated sanitation protocols:Pathogen detection technology convergence with automated dispensing systems enables precision application.
- Direct-to-producer digital channels:E-commerce platforms are disintermediating traditional agricultural supply cooperatives in equipment sanitation segments.
Industry Challenges
- Veterinary pharmacology expertise scarcity:Qualified formulation chemists with livestock pathogen knowledge are concentrated among legacy animal health companies.
- Legacy milking parlor retrofit complexity:Automated disinfection system integration with existing infrastructure requires specialized engineering capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Agricultural Disinfectants Market |
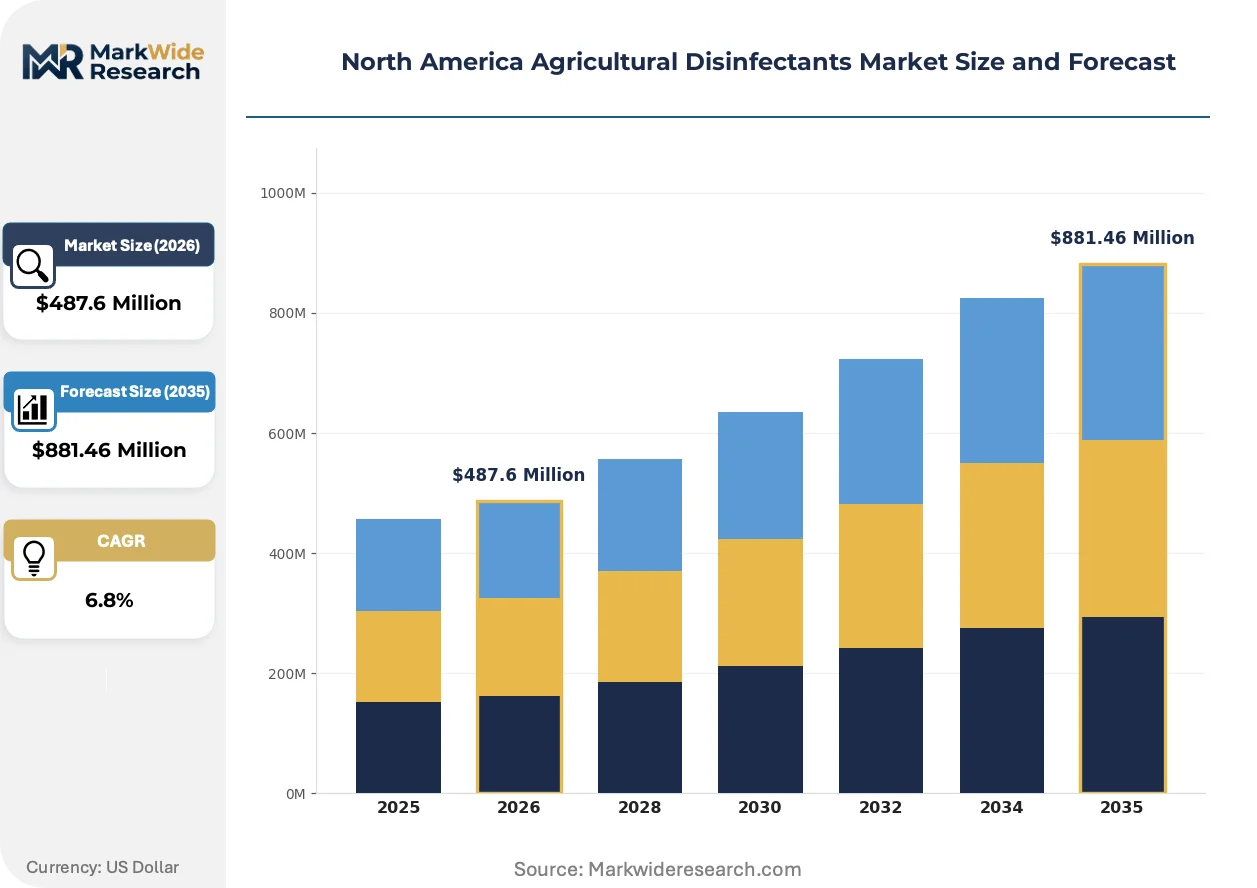
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quaternary Ammonium Compounds, Chlorinated Compounds, Hydrogen Peroxide, Phenolic Compounds Application: Crop Protection, Equipment Sanitation, Soil Treatment, Water Treatment End User: Farms, Greenhouses, Nurseries, Agricultural Cooperatives Distribution Channel: Online Retail, Direct Sales, Distributors, Farm Supply Stores |
| Companies Covered | DuPont, Neogen Corporation, Zoetis Services LLC, Stepan Company, Lanxess AG, Nufarm Limited, The Chemours Company, Ecolab, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Agricultural Disinfectants Market Evolving Landscape
Electrolyzed water generation systems and precision application hardware are compressing chemical usage rates while elevating efficacy verification standards across North American livestock operations.
Peroxygen-based formulations containing accelerated hydrogen peroxide are gaining traction in organic dairy operations. Wisconsin and Vermont producers are adopting these systems at twice the rate of conventional quaternary ammonium protocols. The technology is bifurcating the market between residue-conscious organic certifiers and cost-optimized conventional operators.
EPA's revised data requirements for antimicrobial pesticide registration under FIFRA Section 3 are elevating toxicology study burdens. Formulators are consolidating active ingredient portfolios to focus on established chemistries with complete dossiers. Small and mid-sized manufacturers are exiting novel active development, concentrating innovation among entities with dedicated regulatory affairs infrastructure.
Consolidated procurement through integrated protein company supply agreements is displacing independent distributor relationships. Tyson Foods and JBS USA are mandating approved vendor lists for biosecurity inputs across their contract grower networks. This concentration is most visible in the Texas Panhandle and North Carolina poultry belts where grower density supports direct manufacturer contracting.
North America Agricultural Disinfectants Market Segmentation
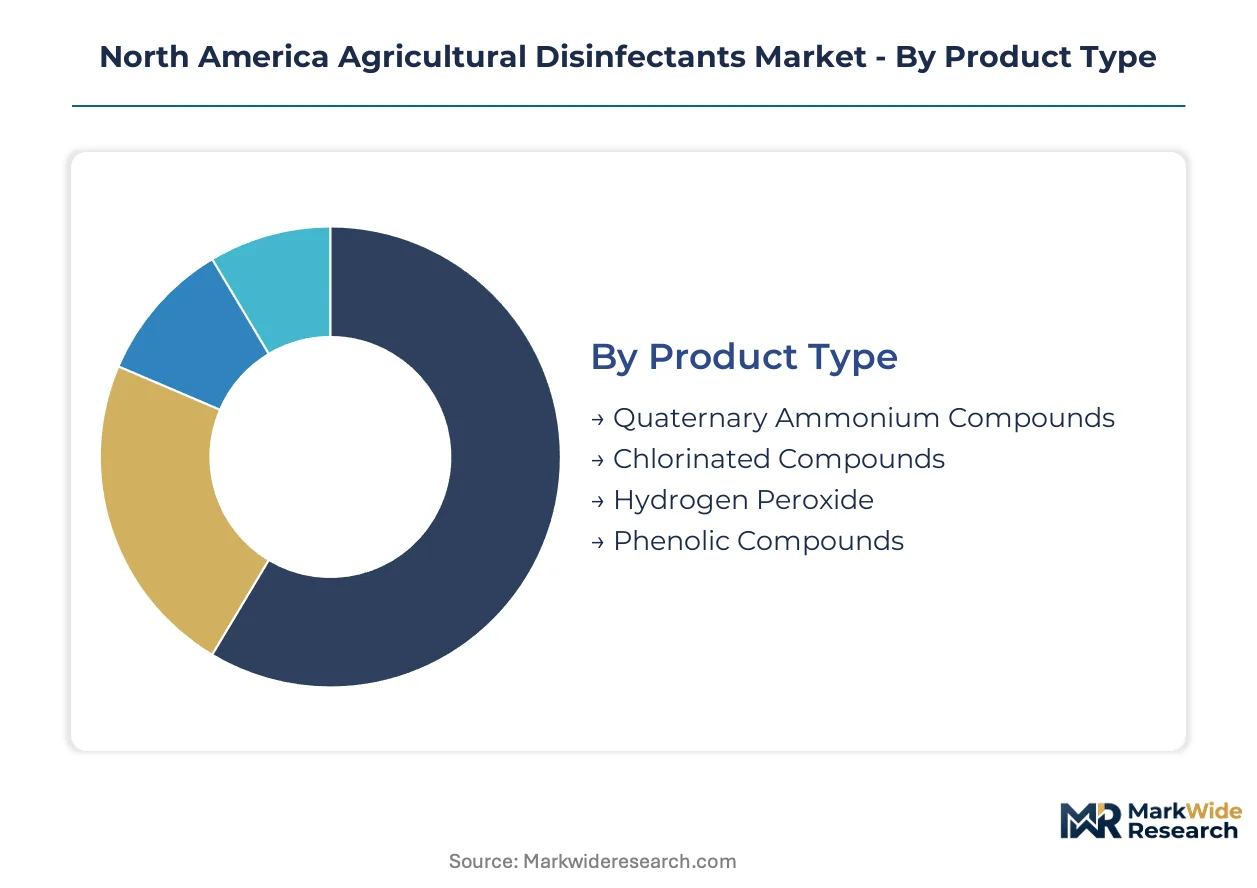
Segmentation in agricultural disinfectants reveals where formulation chemistry intersects with operational scale. Procurement patterns diverge sharply between concentrated animal feeding operations and diversified crop producers, while regulatory constraints on residue profiles reshape product mix priorities across end-use categories.
Product Type:
Margin pools concentrate in quaternary ammonium compounds due to established manufacturing scale and broad-spectrum registration portfolios, while peroxygen alternatives command premium positioning in certified organic channels.
- Quaternary Ammonium Compounds:Formulated biocides containing dialkyl dimethyl ammonium chloride and related cationic surfactants deliver persistent surface activity against gram-positive and gram-negative bacteria. Iowa and Minnesota dairy clusters drive procurement volume through equipment sanitation protocols in milking parlors, though Gulf Coast petrochemical feedstock concentration creates input cost vulnerability.
- Hydrogen Peroxide:Accelerated hydrogen peroxide formulations with silver ion stabilizers achieve rapid pathogen kill without chlorinated residue. Wisconsin and Vermont organic dairy operations are adopting these systems at twice the rate of conventional protocols, propelled by USDA National Organic Program compliance requirements and consumer-facing residue transparency demands.
- Chlorinated Compounds:Hypochlorite-based sanitizers remain cost-competitive for bulk water treatment in Nebraska feedlot operations.
- Phenolic Compounds:Tar acid derivatives persist in veterinary facility applications requiring tuberculocidal claims under EPA FIFRA registration.
Quaternary ammonium compounds hold installed capacity. Hydrogen peroxide is rotating up the share rankings.
Application:
Application segmentation tracks where pathogen break chains command premium pricing versus commodity volume plays.
- Equipment Sanitation:Automated dispensing systems for milking parlors, processing machinery, and veterinary equipment require formulation compatibility with stainless steel, rubber, and electronic components. Texas Panhandle and North Carolina poultry belts concentrate demand through Tyson Foods and JBS USA approved vendor mandates, with precision application hardware compressing chemical usage rates while elevating efficacy verification standards.
- Crop Protection:Foliar and post-harvest biocidal treatments target fungal and bacterial pathogens in high-value fruit and vegetable production. California Central Valley strawberry and lettuce operations drive procurement through state-level antibiotic resistance stewardship extension programs that institutionalize disinfectant protocols.
- Soil Treatment:Pre-plant fumigation alternatives in Florida tomato and pepper production face EPA registration tightening for legacy chemistries.
- Water Treatment:Drinking water and process water disinfection in Saskatchewan and Manitoba hog operations is creating underserved procurement nodes.
Equipment sanitation commands pricing premiums. Crop protection maintains volume leadership.
End User:
End user structure reflects operational scale concentration and biosecurity mandate intensity.
- Farms:Concentrated animal feeding operations across the Midwest Corn Belt dominate procurement through integrated protein company supply agreements. Iowa, Minnesota, and Nebraska dairy clusters mandate pathogen break chains through scheduled equipment disinfection, with direct manufacturer contracting displacing traditional agricultural supply cooperatives.
- Greenhouses:Controlled environment agriculture in Quebec and British Columbia drives peroxygen compound demand for residue-free sanitation protocols aligned with certified organic acreage expansion.
- Nurseries:Ornamental and propagation operations in Oregon and Washington state prioritize surface compatibility with young plant tissue.
- Agricultural Cooperatives:Member-owned purchasing entities in the Canadian prairie provinces face consolidation pressure from e-commerce platform disintermediation.
Farms concentrate procurement volume. Greenhouses are gaining share fastest.
Distribution Channel:
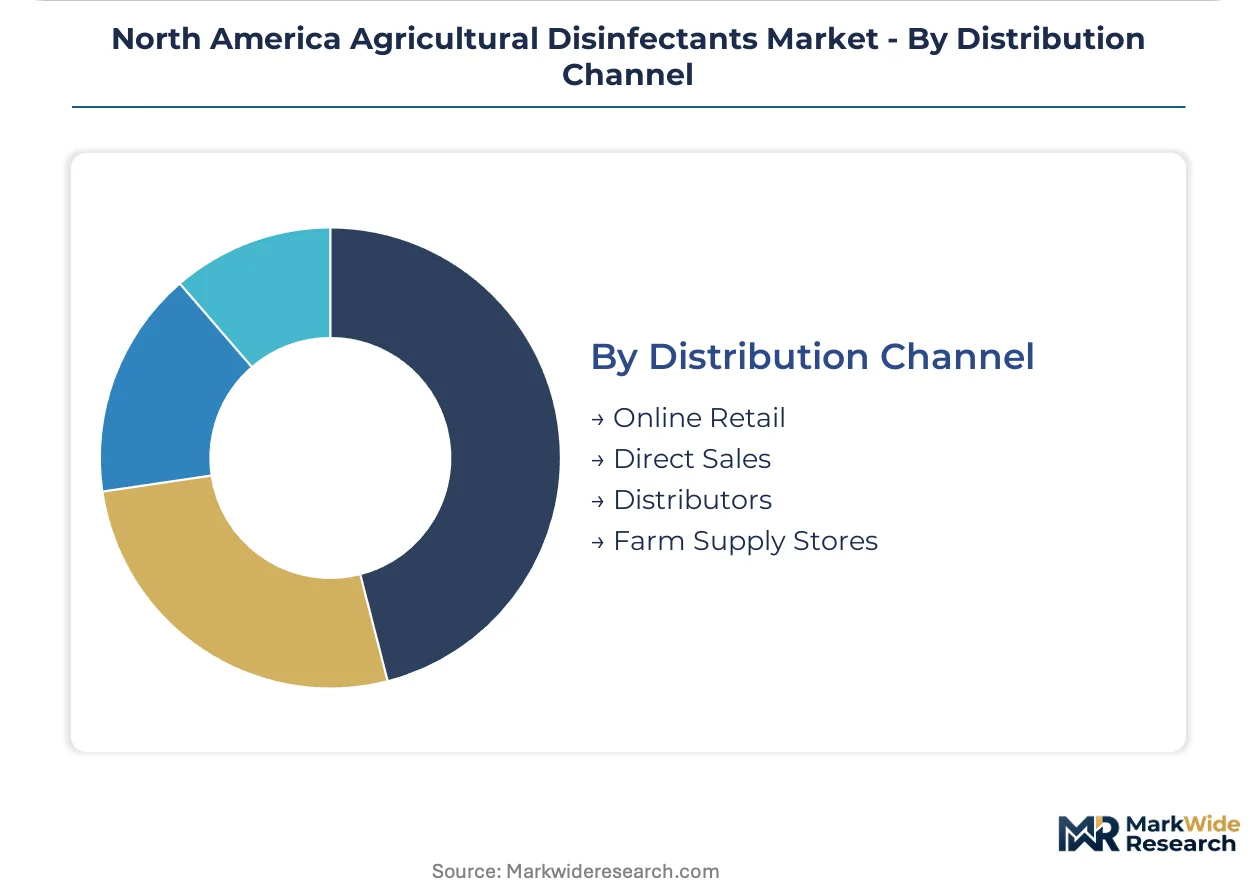
Channel structure is bifurcating between legacy cooperative relationships and direct digital access.
- Direct Sales:Manufacturer-to-producer relationships through integrated protein company approved vendor lists capture biosecurity input procurement across contract grower networks. Tyson Foods and JBS USA mandates in the Texas Panhandle and North Carolina poultry belts exemplify this concentration, with specialized diagnostics-integrated sanitation protocols requiring technical service support.
- Distributors:Regional agricultural supply cooperatives maintain position in equipment sanitation segments requiring application engineering expertise for legacy milking parlor retrofit complexity.
- Online Retail:E-commerce platforms are disintermediating traditional channels for standardized quaternary ammonium formulations in smaller operations.
- Farm Supply Stores:Local retail presence persists in diversified crop regions with fragmented land ownership patterns.
Direct sales holds contract value. Online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States dairy clusters favor quaternary ammonium compounds for equipment sanitation, while Canadian prairie operations rotate toward peroxygen alternatives under organic certification pressure. Mexico's poultry belt maintains chlorine releaser dominance for cost-sensitive bulk water treatment.
United States
Iowa, Minnesota, and Nebraska concentrated animal feeding operations mandate pathogen break chains through scheduled equipment disinfection protocols. EPA FIFRA registration requirements under Section 3 continue tightening active ingredient standards for veterinary disinfectants. The Midwest Corn Belt dominates procurement volumes where direct manufacturer contracting displaces traditional agricultural supply cooperatives.
Canada
Saskatchewan and Manitoba hog operation consolidation creates underserved biosecurity procurement nodes across the prairie provinces. Health Canada PMRA maintains parallel regulatory authority to EPA for disinfectant market access, constraining formulation choices for cross-border suppliers. Quebec's controlled environment agriculture sector drives peroxygen compound demand for residue-free sanitation aligned with certified organic acreage expansion.
Mexico
Poultry belt operations in Guanajuato and Querétaro prioritize cost-competitive chlorine releasers for bulk drinking water disinfection in contract grower networks. The country's national agricultural regulator enforces biocidal registration timelines that lag EPA approval cycles by 12-18 months. Northern border states concentrate disinfectant distribution infrastructure serving integrated protein company supply agreements.
North America Agricultural Disinfectants Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with manufacturing scale separating volume players from formulation innovators. The market structure concentrates procurement leverage among entities with dedicated regulatory affairs infrastructure capable of navigating EPA FIFRA registration timelines. Two strategic archetypes dominate: legacy animal health companies leveraging veterinary pharmacology expertise, and chemical manufacturers competing on quaternary ammonium compound production scale. Competitive moves center on diagnostics-integrated sanitation protocol development and direct-to-producer digital channel expansion.
Within the animal health heritage tier, Zoetis Services LLC and Neogen Corporation exemplify positioning built on livestock biosecurity specialization and diagnostics-integrated protocols respectively. DuPont anchors the chemical manufacturing archetype through quaternary ammonium compound production scale. These three entities occupy positions that reflect divergent capability accumulation: veterinary pharmacology expertise, pathogen detection technology convergence, and petrochemical feedstock integration.
| Leading Market Players |
|---|
| DuPont |
| Neogen Corporation |
| Zoetis Services LLC |
| Stepan Company |
| Lanxess AG |
| Nufarm Limited |
| The Chemours Company |
| Ecolab |
| Bayer AG |
| Others |
Value Network & Pricing Analysis
Quaternary ammonium compound manufacturing scale in Gulf Coast petrochemical corridors anchors both supply concentration and price floors across North American agricultural disinfectant procurement. Iowa and Minnesota dairy clusters absorb premium pricing for equipment sanitation protocols while Canadian prairie hog operations face cost compression from feedstock volatility.
Pricing Analysis
Long-term offtake agreements between integrated protein companies and formulators dominate procurement, with Tyson Foods and JBS USA mandating approved vendor lists that compress spot market liquidity. Three-tier pricing structure across premium peroxygen formulations, standard quaternary ammonium protocols, and economy chlorine releasers reflects certification grade and volume scale differentiation. Pricing pressure stems from EPA FIFRA registration cost escalation that squeezes mid-tier manufacturers. Smaller diversified crop producers exhibit highest price sensitivity, while concentrated animal feeding operations trade cost for biosecurity compliance assurance.
Supply Chain Analysis
Texas and Louisiana anchor quaternary ammonium compound feedstock production through Gulf Coast petrochemical integration, while Ohio and Pennsylvania concentrate peroxygen formulation finishing capacity. Active ingredient production draws from ethylene oxide derivatives, fatty alcohols, and silver ion stabilizers. Single-source vulnerability in dialkyl dimethyl ammonium chloride precursors creates disruption exposure from hurricane corridor weather events. Distribution runs through integrated protein company supply agreements and direct manufacturer contracting, displacing traditional agricultural supply cooperative intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American agricultural disinfectants sit in early-cycle expansion as USDA National Organic Program acreage growth accelerates peroxygen compound penetration beyond legacy quaternary ammonium dominance.
For Market Incumbents: Secure veterinary pharmacology talent pools through targeted recruitment from university extension programs and competitor technical service teams. Deepen backward integration into Gulf Coast petrochemical feedstocks to buffer input cost volatility from hurricane season disruption. Fortify EPA FIFRA registration dossiers against tightening toxicology study requirements that threaten smaller competitor portfolios.
For New Entrants and Emerging Players: Differentiate on diagnostics-integrated sanitation protocols that converge pathogen detection with automated dispensing hardware. Target Saskatchewan and Manitoba hog operation consolidation nodes where biosecurity procurement remains underserved by legacy animal health company coverage. Pursue direct-to-producer digital channel establishment to bypass entrenched agricultural supply cooperative relationships.
For Investors and Strategic Acquirers: Specialized formulation chemists with livestock pathogen expertise represent the highest-conviction acquisition archetype for capability accumulation in a talent-scarce environment. Long-term viability hinges on regulatory affairs infrastructure depth capable of navigating EPA registration timelines without novel active ingredient development exposure. Watch California and New York state-level biocidal usage tracking mandates as signal for stewardship-driven procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | Gulf Coast ethylene oxide derivative captive supply buffers quaternary ammonium compound input volatility. |
| Diagnostics-Integrated Sanitation Protocol Development | Pathogen detection convergence with automated dispensing enables precision application in Iowa dairy clusters. |
| EPA FIFRA Registration Dossier Consolidation | Established active ingredient focus reduces toxicology study burden under revised Section 3 data requirements. |
| Direct-to-Producer Digital Channel Expansion | E-commerce platform establishment disintermediates traditional agricultural supply cooperatives for equipment sanitation segments. |
| Canadian Prairie Province Market Entry | Saskatchewan and Manitoba hog operation consolidation creates underserved biosecurity procurement nodes. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dairy operation managers, hog facility biosecurity officers, agricultural supply cooperative procurement leads, EPA regulatory affairs consultants, and veterinary extension specialists. Secondary validation incorporated EPA FIFRA registration databases, Health Canada PMRA submission records, USDA National Organic Program certification data, and integrated protein company supply agreement disclosures. Bottom-up volume triangulation from state-level CAFO density data intersected with top-down value estimates from petrochemical feedstock pricing indices.
Across the analysis window, the forecasting framework modeled product type chemistry tiers, application segmentation across equipment sanitation and crop protection, end-user operational scale categories, and distribution channel structure evolution. CAGRs derived from regression analysis against organic acreage expansion trajectories and antibiotic resistance stewardship mandate adoption curves. Industry-specific inputs included EPA registration pipeline status for novel active ingredients and integrated protein company approved vendor list expansion rates.
Decision-makers should treat outputs as directional under assumptions of continued USDA National Organic Program growth and stable EPA FIFRA regulatory timelines; material deviation from these base conditions would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Glyphosate Herbicide Market
Agricultural Chemicals
Global Dinotefuran Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
Europe Feed Enzymes Market
Agricultural Chemicals
South America Feed Acidifiers Market
Agricultural Chemicals
ASEAN Livestock Disinfectant Market
Agricultural Chemicals
Europe Feed Premix Market
Agricultural Chemicals
Pesticide Adjuvant Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
Neem Pesticides Market
Agricultural Chemicals
Vietnam Feed Additives Market
Agricultural Chemicals
Bird Repellent Market
Agricultural Chemicals
US Fungicide Market
Agricultural Chemicals
Europe Swine Feed Premix Market
Agricultural Chemicals
Asia-Pacific Soil Treatment Market