
 Marine Powder Market | 2026-2036
Marine Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Powder Market Analytics
Marine biochemistry expertise is rotating toward specialized hydrolysis and extraction capabilities that constrain output scalability. Rousselot leverages its integrated gelatin and collagen peptide infrastructure to secure raw marine material streams across multiple coastlines. Nitta Gelatin Inc. anchors its competitive position through precision enzymatic processing technologies that yield consistent molecular weight profiles. Vital Proteins dominates direct-to-consumer marine collagen positioning, while Great Lakes Gelatin sustains bulk ingredient supply relationships with North American nutraceutical formulators.
Marine powder comprises dried, pulverized biomass from fish, shellfish, seaweed, or algae, typically processed through spray-drying or freeze-drying to preserve protein integrity and bioactive compound stability; its primary commercial purpose spans human nutrition fortification, animal feed protein supplementation, and cosmetic active delivery. Fish powder occupies the largest volume share within product type segmentation due to established supply chains from whitefish and tuna processing bycatch. Nutraceutical applications generate the fastest value growth as hydrolyzed marine collagen peptides penetrate functional food and beauty-from-within formulations. Online retail channels are gaining share within distribution channel segmentation, though specialty stores retain margin concentration for premium-certified grades targeting cosmetic manufacturers and health supplement companies.
REACH registration through ECHA governs heavy-metal and contaminant thresholds for marine powders entering European cosmetic and food additive supply chains. FDA GRAS self-affirmation pathways shape US market access timelines for novel marine-derived protein ingredients. MFDS marine-sourced health functional food codes in South Korea create compliance benchmarks that influence export-oriented producers across Asia-Pacific. Stakeholders must monitor evolving microplastic detection protocols and traceability mandates that will reshape supplier qualification criteria and capital allocation toward certified sustainable fisheries partnerships.
Market Dynamics
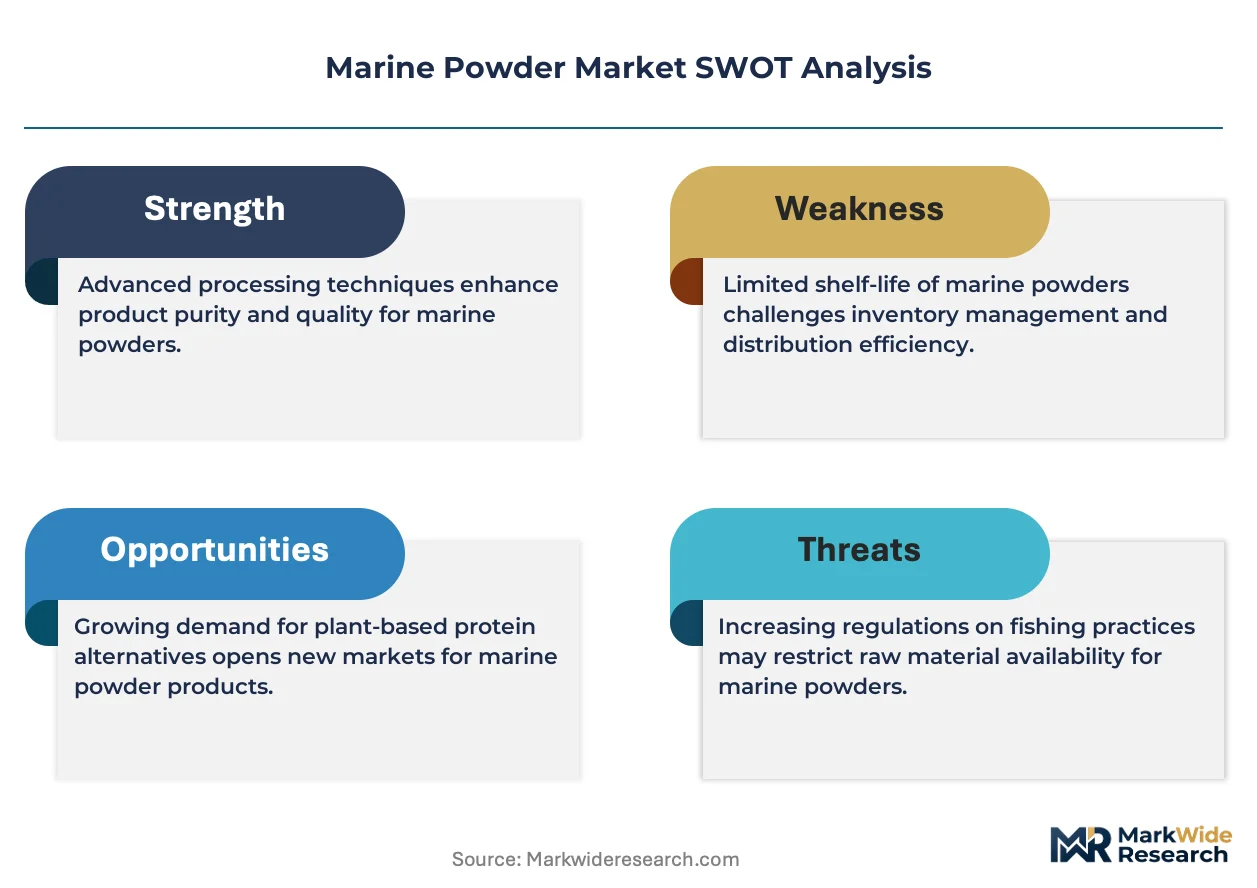
Marine powder supply chains face intensifying pressure from REACH and ECHA heavy-metal threshold tightening, which forces producers to redirect capital toward certified sustainable fisheries partnerships and advanced contaminant filtration infrastructure.
Growth Catalysts
- Clean-label functional food demand:Health supplement companies are expanding marine collagen procurement as MFDS-certified grades command premium positioning in South Korean beauty-from-within formulations.
- Enzymatic hydrolysis advancement:Precision processing technologies now yield consistent molecular weight profiles, unlocking broader nutraceutical application scopes.
- Bycatch utilization mandates:Whitefish and tuna processing waste streams are redirecting into marine powder production, tightening circular economy compliance in North Atlantic fisheries.
Market Restraints
- Heavy-metal compliance costs:ECHA threshold reductions for arsenic and mercury in marine-derived inputs inflate qualification expenses for European market entry.
- Raw material geographic concentration:Premium-grade fish powder supply clusters around North Atlantic and North Pacific coastal processing infrastructure.
- Plant protein substitution:Pea and fava bean protein isolates are capturing share in mid-tier animal feed applications where bioactive specificity matters less.
Strategic Opportunities
- Seaweed biomass expansion:Algae-derived marine powders remain underpenetrated in cosmetic active delivery, offering white space beyond established fish collagen segments.
- Direct-to-consumer channel development:Online retail platforms are gaining distribution share for premium-certified grades targeting individual health supplement buyers.
- EU Green Deal alignment:CSRD reporting requirements and sustainable sourcing incentives favor producers with certified fisheries partnerships and blockchain traceability systems.
Industry Challenges
- Specialized biochemistry talent scarcity:Marine hydrolysis and extraction expertise constrains output scalability as demand outpaces technical workforce development.
- Microplastic detection protocol evolution:Emerging analytical standards for marine biomass certification create compliance timeline uncertainty for export-oriented producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Powder Market |
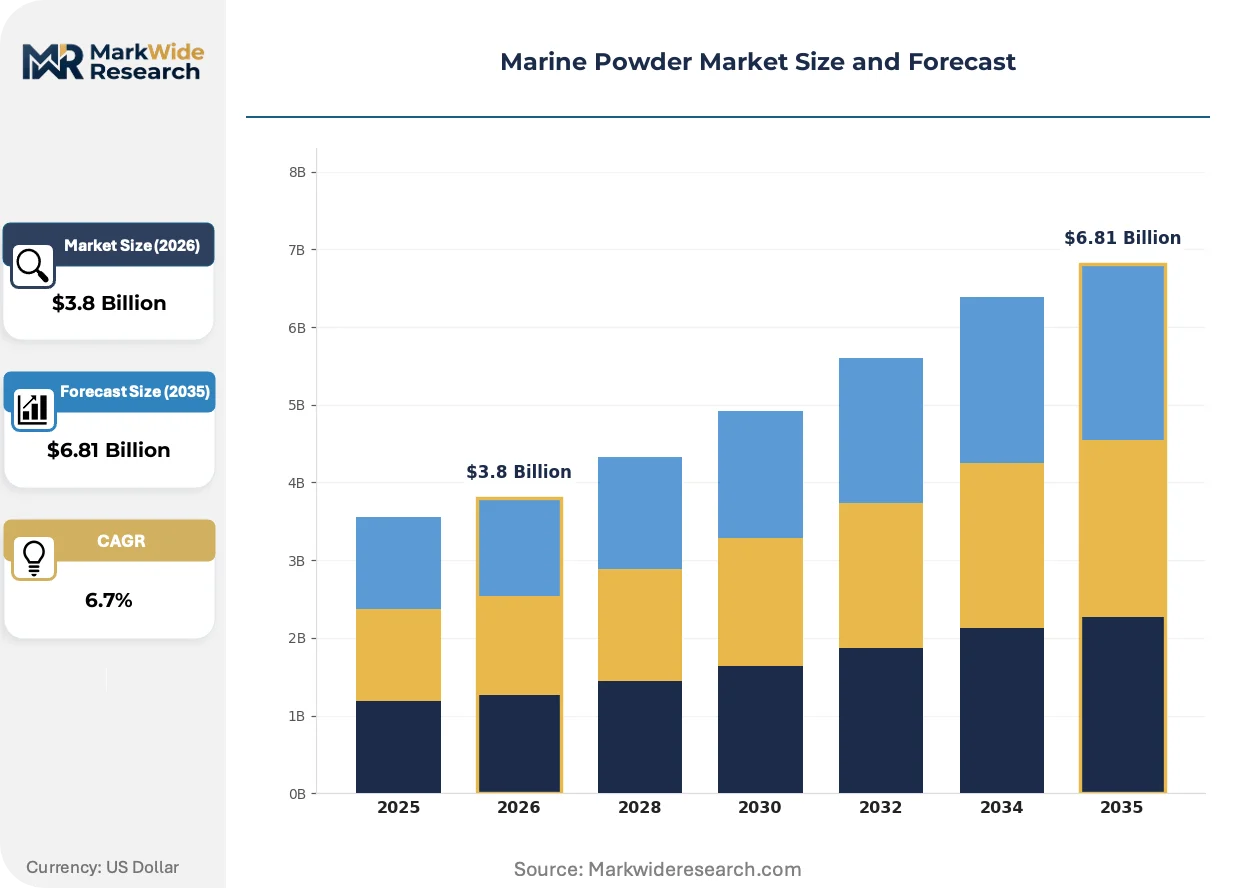
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Powder, Shellfish Powder, Seaweed Powder, Algal Powder Application: Food Additive, Nutraceutical, Animal Feed, Cosmetics Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale End User: Food Manufacturers, Pet Food Producers, Health Supplement Companies, Cosmetic Manufacturers |
| Companies Covered | Vital Proteins, Rousselot, Nitta Gelatin Inc., Ashland Inc., Neocell, Great Lakes Gelatin, Collagen Solutions, Nutraceutical International Corporation, Further Food, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Powder Market Evolving Landscape
Clean-label certification requirements and precision extraction technologies are actively restructuring competitive advantage in marine powder value chains. Producers now differentiate through molecular specificity rather than commodity volume positioning.
Low-temperature enzymatic hydrolysis is displacing traditional thermal processing in premium collagen peptide production. Cosmetic manufacturers and functional food formulators are adopting these methods to preserve bioactive integrity. This shift is compressing margins for conventional spray-drying operations while rewarding precision processing capabilities.
REACH registration amendments through ECHA are tightening contaminant thresholds for marine powders entering European cosmetic supply chains. Heavy-metal testing protocols now require third-party verification at multiple processing stages. Nutraceutical exporters to Germany and France are restructuring supplier qualification criteria to maintain market access.
Beauty-from-within consumption patterns are rotating procurement priorities toward MFDS-certified marine collagen in South Korea. Specialty stores and clinic channels are consolidating premium-grade demand as direct-to-consumer brands fragment mid-market supply relationships. This behavioral shift concentrates margin capture in certification-holding producers across Asia-Pacific functional food markets.
Marine Powder Market Segmentation
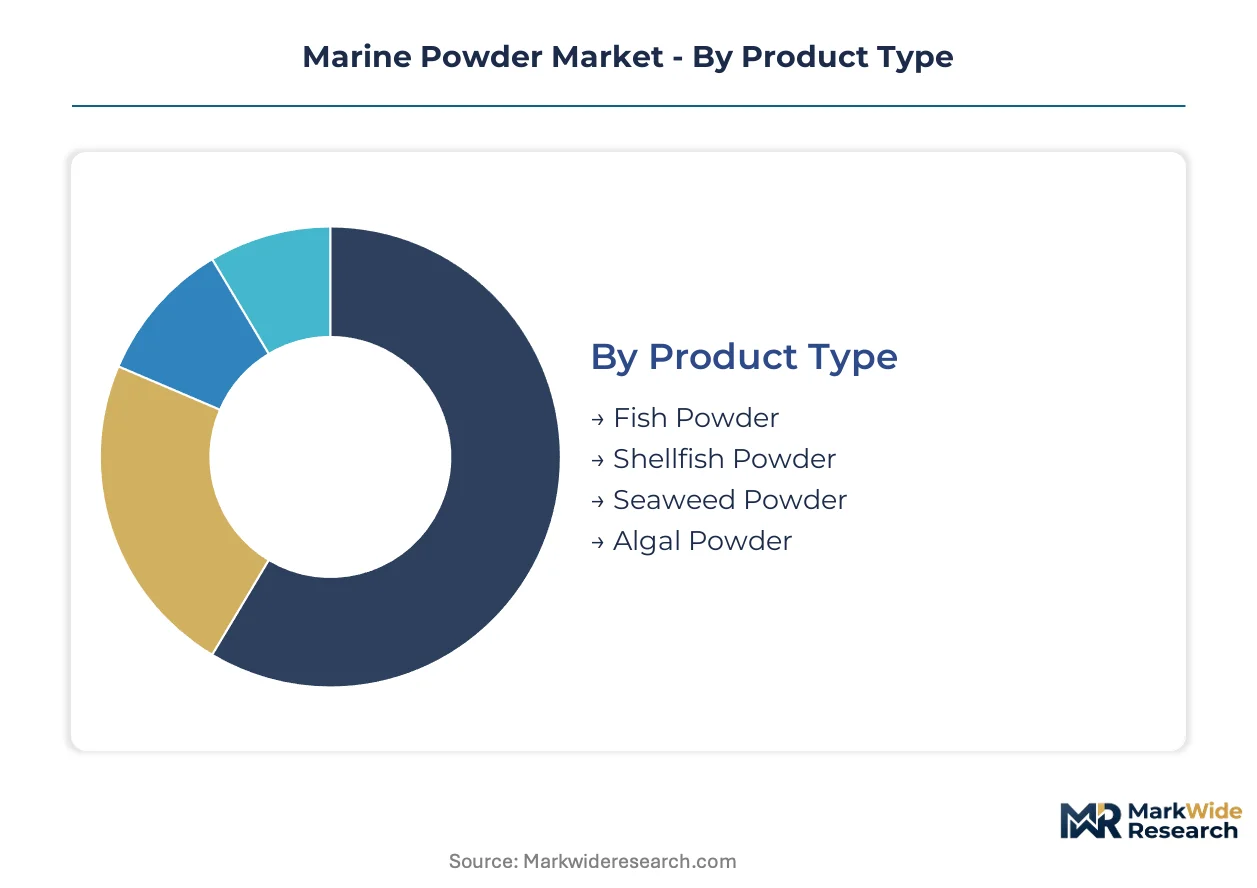
Marine powder market segmentation reveals distinct procurement pathways where product chemistry dictates channel selection and margin capture. Certification requirements and end-use specificity fragment supply relationships across nutraceutical, cosmetic, and feed applications.
Product Type:
Channel-mix patterns diverge sharply across marine powder categories, with spray-dried fish products flowing predominantly through wholesale bulk contracts while freeze-dried algal grades concentrate in specialty direct-to-consumer channels.
- Fish Powder:Derived from whitefish and tuna processing bycatch through thermal drying or enzymatic hydrolysis, yielding protein concentrates at 65-80% purity. Demand clusters in North Atlantic coastal processing zones where circular economy mandates redirect waste streams. Pet food producers and animal feed compounders anchor volume procurement through long-term supply agreements.
- Seaweed Powder:Harvested from brown and red macroalgae species, processed through low-temperature dehydration to preserve sulfated polysaccharides and mineral bioavailability. Cosmetic manufacturers in South Korea drive premium positioning through MFDS-certified grades for beauty-from-within formulations.
- Shellfish Powder:Chitin-rich biomass from crustacean processing waste, functional in agricultural biostimulant and specialty feed applications.
- Algal Powder:Microalgae-derived protein and omega-3 concentrates, supplying high-value nutraceutical encapsulation and infant formula fortification.
Fish powder dominates installed base. Seaweed powder is where expansion concentrates.
Application:
Cost tier differentiation separates commodity feed applications from pharmaceutical-grade nutraceutical and cosmetic segments, with enzymatic processing intensity determining margin structure.
- Nutraceutical:Hydrolyzed marine collagen peptides and bioactive protein fractions command premium pricing through functional food and dietary supplement channels. South Korean beauty-from-within consumption patterns and MFDS certification requirements reshape procurement priorities for export-oriented producers.
- Cosmetics:Molecular-weight-specific collagen peptides and algae-derived bioactives serve active ingredient delivery in topical and ingestible beauty formulations. REACH and ECHA heavy-metal thresholds constrain European market access, forcing qualification investment in third-party verification infrastructure.
- Food Additive:Protein fortification and texture modification in processed seafood and savory applications, competing with plant protein alternatives on cost.
- Animal Feed:High-volume protein supplementation for aquaculture and companion animal nutrition, vulnerable to pea and fava bean isolate substitution in mid-tier segments.
Animal feed anchors volume throughput. Nutraceutical applications are climbing the fastest.
Distribution Channel:
Customer type fragmentation—bulk compounders versus individual health-conscious consumers—drives channel bifurcation between relationship-based wholesale and algorithm-driven e-commerce.
- Wholesale:Long-term supply contracts with feed mills, food manufacturers, and cosmetic formulators concentrate volume in North Atlantic and North Pacific coastal logistics hubs. Blockchain traceability systems increasingly qualify supplier participation.
- Specialty Stores:Premium-certified grades for cosmetic manufacturers and health supplement companies consolidate margin in clinic and professional channels, particularly in South Korea's functional food retail landscape.
- Online Retail:Direct-to-consumer marine collagen positioning gains share through subscription models and influencer-mediated discovery, fragmenting mid-market supply relationships.
- Supermarkets:Mass-market protein fortification and private-label supplement placement, constrained by shelf-life requirements and clean-label certification costs.
Wholesale channels dominate installed base. Online retail is where expansion concentrates.
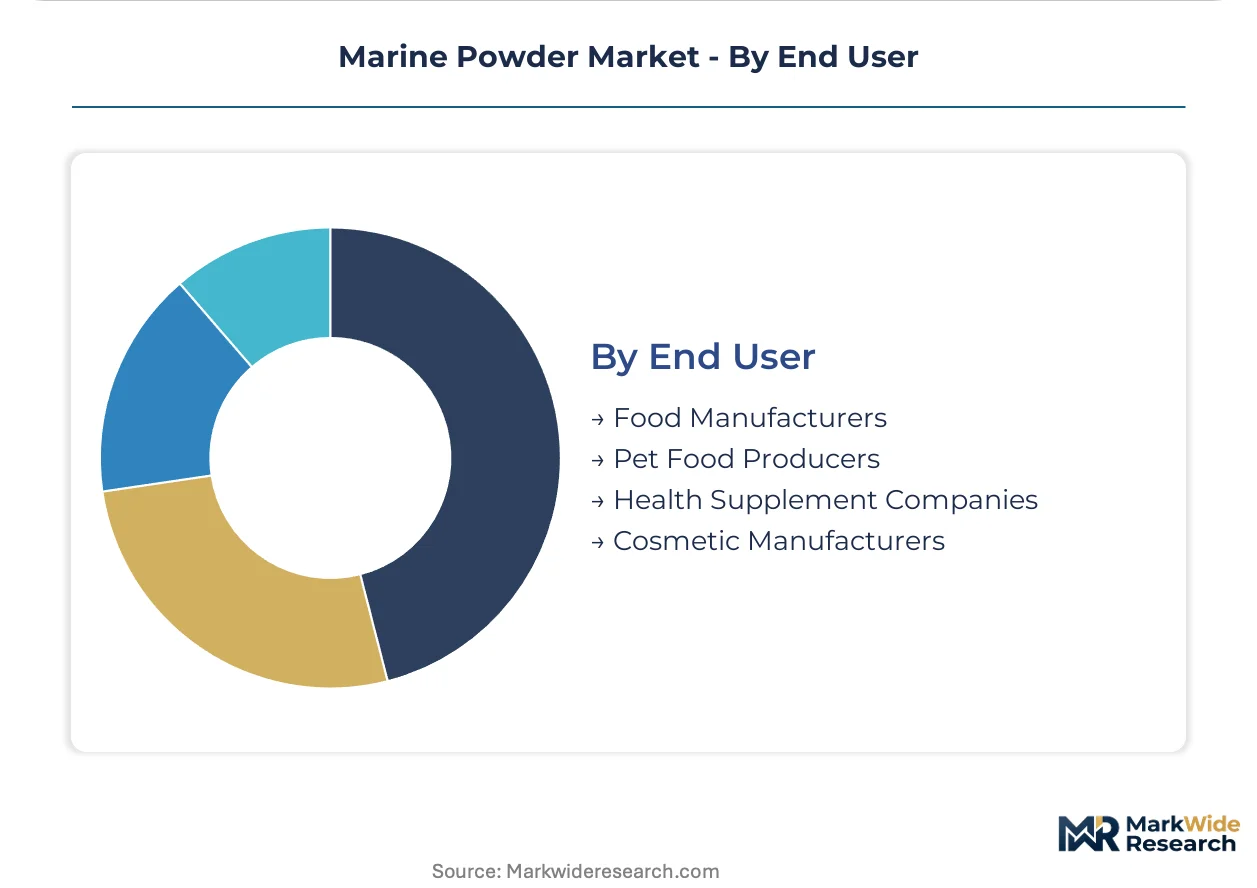
End User:
Supply concentration in certified sustainable fisheries partnerships favors scaled processors capable of meeting divergent regulatory requirements across FDA GRAS, REACH, and MFDS jurisdictions.
- Health Supplement Companies:Clean-label demand intensifies marine collagen procurement with full-chain traceability from vessel to capsule. Precision enzymatic processing capabilities constrain supplier qualification.
- Cosmetic Manufacturers:Bioactive specificity requirements for molecular weight profiles and heavy-metal compliance reshape RFP criteria, rewarding producers with in-house hydrolysis expertise.
- Food Manufacturers:Protein enrichment and umami enhancement in processed seafood, savory, and functional food applications.
- Pet Food Producers:Palatability-driven fish powder demand for premium companion animal nutrition, competing with poultry and plant protein meals on formulation cost.
Pet food producers dominate installed base. Health supplement companies are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFDS marine-sourced health functional food codes in South Korea create compliance benchmarks that reshape procurement patterns across Asia-Pacific export corridors. REACH and ECHA frameworks in Europe tighten heavy-metal thresholds for marine-derived inputs. Demand concentrates in coastal processing clusters where circular economy mandates redirect fishery waste streams.
South Korea
Beauty-from-within consumption patterns drive MFDS-certified marine collagen procurement for functional food and cosmetic applications. Seoul Capital Area clinics and specialty stores consolidate premium-grade demand as direct-to-consumer brands fragment mid-market channels. Busan-Ulsan coastal processing infrastructure anchors raw material qualification for export-oriented producers.
United States
FDA GRAS self-affirmation pathways shape market access timelines for novel marine-derived protein ingredients targeting nutraceutical formulators. Health supplement companies expand clean-label marine collagen sourcing with full-chain traceability requirements. Pacific Northwest and Alaska coastal zones concentrate whitefish and tuna processing bycatch utilization for powder production.
Germany
ECHA threshold reductions for arsenic and mercury in marine-derived inputs inflate qualification expenses for cosmetic and food additive market entry. REACH registration amendments mandate third-party verification at multiple processing stages for biomass certification. Hamburg and Bremerhaven logistics hubs concentrate wholesale distribution for European nutraceutical compounders.
Japan
METI industrial policy supports enzymatic hydrolysis technology development for consistent molecular weight profile production in premium collagen peptides. Cosmetic manufacturers prioritize bioactive specificity for molecular-weight-specific formulations in topical and ingestible beauty segments. Chubu-Nagoya and Kansai-Osaka regions anchor precision processing capabilities for domestic and export supply.
China
SAMR food safety supervision and GB standards govern marine protein ingredient registration for functional food and infant formula fortification applications. Dual carbon goals redirect capital toward certified sustainable fisheries partnerships and blockchain traceability systems. Shandong Peninsula and Yangtze River Delta coastal zones dominate algal and fish powder processing infrastructure scale.
Marine Powder Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where precision enzymatic processors capture premium nutraceutical margins while bulk commodity suppliers anchor animal feed volume. The vendor base spans integrated gelatin conglomerates, specialized collagen peptide processors, and direct-to-consumer wellness brands. Three archetypes dominate: coastal-integrated raw material controllers, precision biochemistry specialists, and algorithm-driven consumer marketers. Competitive moves concentrate on certified fisheries partnership formation and low-temperature hydrolysis capacity expansion.
Among integrated material processors, Rousselot and Nitta Gelatin Inc. exemplify the coastal-integrated archetype through multi-coastline raw material stream security. Vital Proteins occupies the direct-to-consumer positioning tier, representing wellness-brand penetration of marine collagen subscription models. These three anchors illustrate how molecular specificity capabilities separate premium-tier capture from commodity volume positioning.
| Leading Market Players |
|---|
| Vital Proteins |
| Rousselot |
| Nitta Gelatin Inc. |
| Ashland Inc. |
| Neocell |
| Great Lakes Gelatin |
| Collagen Solutions |
| Nutraceutical International Corporation |
| Further Food |
| Others |
Value Network & Pricing Analysis
Ninety-day raw material qualification timelines for MFDS-certified marine collagen concentrate pricing power with Busan-Ulsan processors capable of integrated vessel-to-capsule traceability. Inventory carrying costs for heavy-metal-compliant biomass inflate working capital requirements, compressing margins for European exporters facing ECHA threshold tightening while rewarding coastal-integrated operators with captive cold-chain infrastructure.
Pricing Analysis
Price spreads between South Korean MFDS-certified grades and commodity fish powder widen as enzymatic hydrolysis intensity differentiates molecular weight specificity. Three-tier pricing structure across premium enzymatic peptides, standard spray-dried concentrates, and economy thermal-processed grades anchors the market. Cost compression in mid-tier segments intensifies as plant protein isolates capture animal feed applications. Pet food producers exhibit highest price sensitivity; cosmetic manufacturers demonstrate lowest.
Supply Chain Analysis
Norway, South Korea, and China anchor marine powder processing through contrasting specializations—North Atlantic whitefish bycatch utilization, precision enzymatic peptide production, and algal biomass scale respectively. Supply chains draw from certified sustainable fisheries partnerships, low-temperature dehydration infrastructure, and blockchain traceability systems. Single-source vulnerability concentrates in North Atlantic coastal processing zones where circular economy mandates redirect limited waste streams. Distribution runs through wholesale bulk contracts with feed mills and cosmetic formulators, supplemented by direct-to-consumer subscription platforms fragmenting mid-market relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label certification requirements fragment procurement relationships, creating specialized service gaps between commodity volume suppliers and precision biochemistry specialists. Beauty-from-within consumption patterns in South Korea and enzymatic processing capability scarcity generate defendable niche positions.
For Market Incumbents: Compound defensive positioning through backward integration into certified sustainable fisheries partnerships and precision enzymatic capacity expansion in Busan-Ulsan coastal zones. Plant protein substitution in mid-tier animal feed segments threatens volume anchors; MFDS certification maintenance represents the priority retention lever against emerging Asian-Pacific competitors. For New Entrants and Emerging Players: Direct-to-consumer subscription fulfillment infrastructure presents a service-layer gap where incumbents under-serve individual health supplement buyers with algorithm-driven personalization. White space concentrates in seaweed-derived cosmetic actives for European REACH-compliant supply chains and blockchain-verified traceability platforms for North American clean-label procurement. Go-to-market execution should prioritize influencer-mediated discovery channels with MFDS-certified storytelling. For Investors and Strategic Acquirers: Long-term, this sits as a capability-scarcity play because enzymatic hydrolysis expertise constrains output scalability faster than demand expansion across nutraceutical applications. Acquisition targets should emphasize coastal-integrated processors with in-house molecular weight profiling and existing ECHA registration infrastructure. The signal to watch is microplastic detection protocol finalization timelines that will reshape supplier qualification criteria and capital allocation priorities.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Fisheries Partnership Formation | Secures raw material streams compliant with ECHA heavy-metal thresholds and EU Green Deal traceability mandates. |
| Low-Temperature Enzymatic Hydrolysis Capacity Expansion | Unlocks premium nutraceutical margins through consistent molecular weight profiles for cosmetic manufacturers. |
| Blockchain Traceability System Deployment | Qualifies supplier participation in CSRD-reporting European cosmetic and food additive supply chains. |
| Direct-to-Consumer Channel Development | Captures individual health supplement buyers through subscription models and influencer-mediated discovery platforms. |
| MFDS Certification Investment | Commands premium positioning in South Korean beauty-from-within functional food and clinic retail channels. |
Research Methodology
A spread of perspectives from marine biochemistry R&D directors, cosmetic formulator procurement leads, health supplement company supply chain managers, and certified fisheries compliance officers converged on the working assumptions shaping this analysis. Primary interview intelligence combined with secondary validation from ECHA registration databases, MFDS health functional food code filings, FAO fishery statistics, and customs trade records. Bottom-up volume modeling across product type and application segments triangulated against top-down macroeconomic drivers.
Segmentation dimensions modeled span product chemistry, processing technology intensity, end-use application specificity, distribution channel structure, and geographic regulatory cluster across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for enzymatic hydrolysis adoption curves and clean-label certification penetration rates. Industry-specific forecast inputs incorporated circular economy mandate implementation timelines and microplastic detection protocol development status.
Forecasts assume regulatory continuity in REACH-ECHA, MFDS, and FDA GRAS regimes; material policy shifts would require re-modeling. Specific risks include heavy-metal threshold unilateral tightening, sustainable fisheries certification scheme fragmentation, and enzymatic processing talent pipeline constraints. Recalibration cycles align with material shifts in regulatory enforcement intensity and beauty-from-within consumption pattern evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Blood Meal Market
Agricultural Commodities
North America Feed Lutein and Zeaxanthin Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Premix Market
Agricultural Commodities
Africa Feed Amino Acids Market
Agricultural Commodities
India Feed Amino Acids Market
Agricultural Commodities
Global Seed Cotton Market
Agricultural Commodities
Aloe Vera Market
Agricultural Commodities
Soybean Derivatives Market
Agricultural Commodities
UK Bird Feeder Market
Agricultural Commodities
Growing Peat Market
Agricultural Commodities
South America Feed Premix Market
Agricultural Commodities
Europe Feed Amino Acids Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Market
Agricultural Commodities
Global Ruminant Feed Premix Market
Agricultural Commodities
Alfalfa Powder Market