
 US Durable Medical Equipment Market | 2026-2036
US Durable Medical Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
US Durable Medical Equipment Market Intelligence
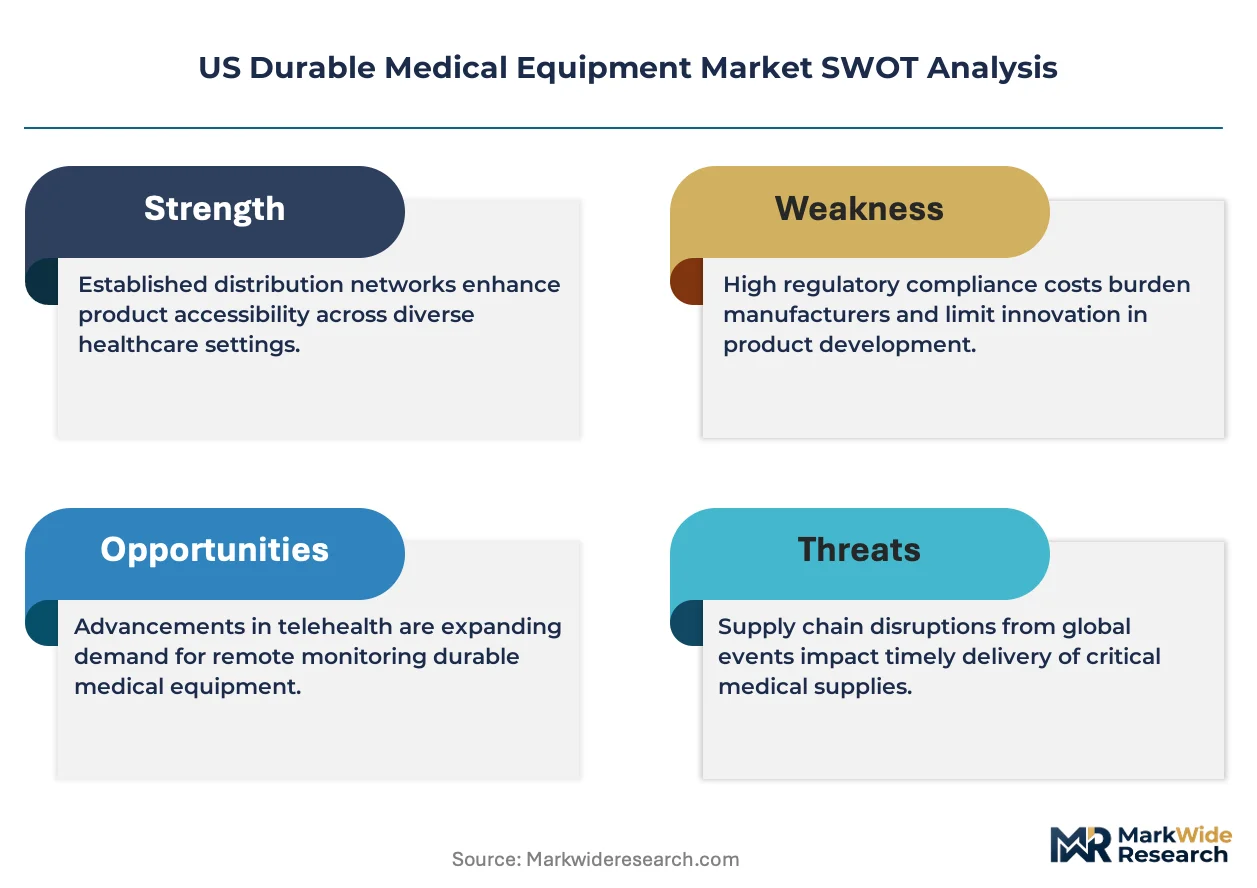
The price-performance gap between premium and commodity durable medical equipment is hardening. Invacare Corporation leverages its vertical manufacturing footprint to dominate standard wheelchair and hospital bed segments. Medline Industries anchors its position through private-label scale and direct-to-facility distribution networks that bypass traditional distributor markups.
Durable medical equipment encompasses reusable devices prescribed for medical purposes, including wheelchairs with aluminum or titanium frames rated to specific load capacities, oxygen concentrators delivering continuous flow rates, and hospital beds with integrated scale and positioning systems. Wheelchairs and oxygen equipment command mature volume bases, while AI-enabled devices and smart sensors capture disproportionate R&D investment as reimbursement codes expand for remote patient monitoring. Home care end users now represent the fastest-growing demand pool, shifting procurement power away from centralized healthcare facilities toward individual caregivers and patients.
FDA 510(k) clearances and CMS National Coverage Determinations govern market access, with the former dictating product safety benchmarks and the latter controlling reimbursement eligibility that directly shapes manufacturer revenue. The FTC monitors anti-competitive contracting practices between group purchasing organizations and equipment suppliers. Stakeholders must track how CMS revalues remote therapeutic monitoring codes, as these reimbursement decisions will determine which technology segments attract sustained capital deployment.
Market Dynamics
Medicare's site-neutral payment reforms are compressing reimbursement differentials between hospital outpatient departments and home-based settings, forcing manufacturers to redesign equipment for unsupervised residential use rather than clinical environments.
Growth Catalysts
- Remote Therapeutic Monitoring (RTM) Codes:CMS reimbursement expansion for RTM services under Medicare Part B incentivizes manufacturers to integrate cellular connectivity and automated data transmission into respiratory and musculoskeletal devices.
- Sun Belt Demographics:Retiree migration to Florida, Arizona, and Texas concentrates demand for aging-in-place infrastructure, with home care equipment procurement accelerating in metropolitan statistical areas with median age above 45.
- AI-Enabled Diagnostics:FDA 510(k) clearance pathways for machine learning-based monitoring algorithms compress development cycles for predictive fall detection and sleep apnea screening accessories.
Market Restraints
- Aluminum and Titanium Input Volatility:Wheelchair frame manufacturers face margin pressure from aerospace sector competition for lightweight alloys, with spot prices for Grade 5 titanium fluctuating based on defense procurement cycles.
- Concentrated Oxygen Concentrator Supply:Compressor motor and molecular sieve production concentrates in East Asian contract manufacturers, creating single-source vulnerability for US-based device assemblers.
- Competitive Bidding Program Compression:CMS mandatory competitive bidding for durable medical equipment in designated metropolitan areas caps reimbursement rates below production cost for commodity wheelchair and hospital bed categories.
Strategic Opportunities
- Medicaid Expansion States:States that expanded Medicaid eligibility under the ACA present underpenetrated demand for bariatric equipment and pressure injury prevention surfaces among newly insured populations.
- Voice-First Interface Convergence:Integration of natural language processing with environmental control units creates white space for hands-free wheelchair navigation and bed positioning systems targeting high-level spinal cord injury users.
- Direct-to-Consumer Channel Development:E-commerce platforms with virtual fitting tools and insurance pre-authorization APIs bypass durable medical equipment suppliers, capturing margin previously allocated to distributor networks.
Industry Challenges
- Biomedical Technician Shortage:Home care agencies struggle to recruit technicians certified for ventilator and infusion pump maintenance, extending equipment downtime and elevating replacement rates.
- Interoperability Certification Delays:ONC 21st Century Cures Act compliance timelines for electronic health record integration stall product launches for connected glucose monitors and pulse oximeters.
- Legacy Facility Contract Lock-In:Multi-year sole-source agreements between hospital systems and incumbent suppliers create switching friction for innovative entrants with superior pressure redistribution mattress technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Durable Medical Equipment Market |
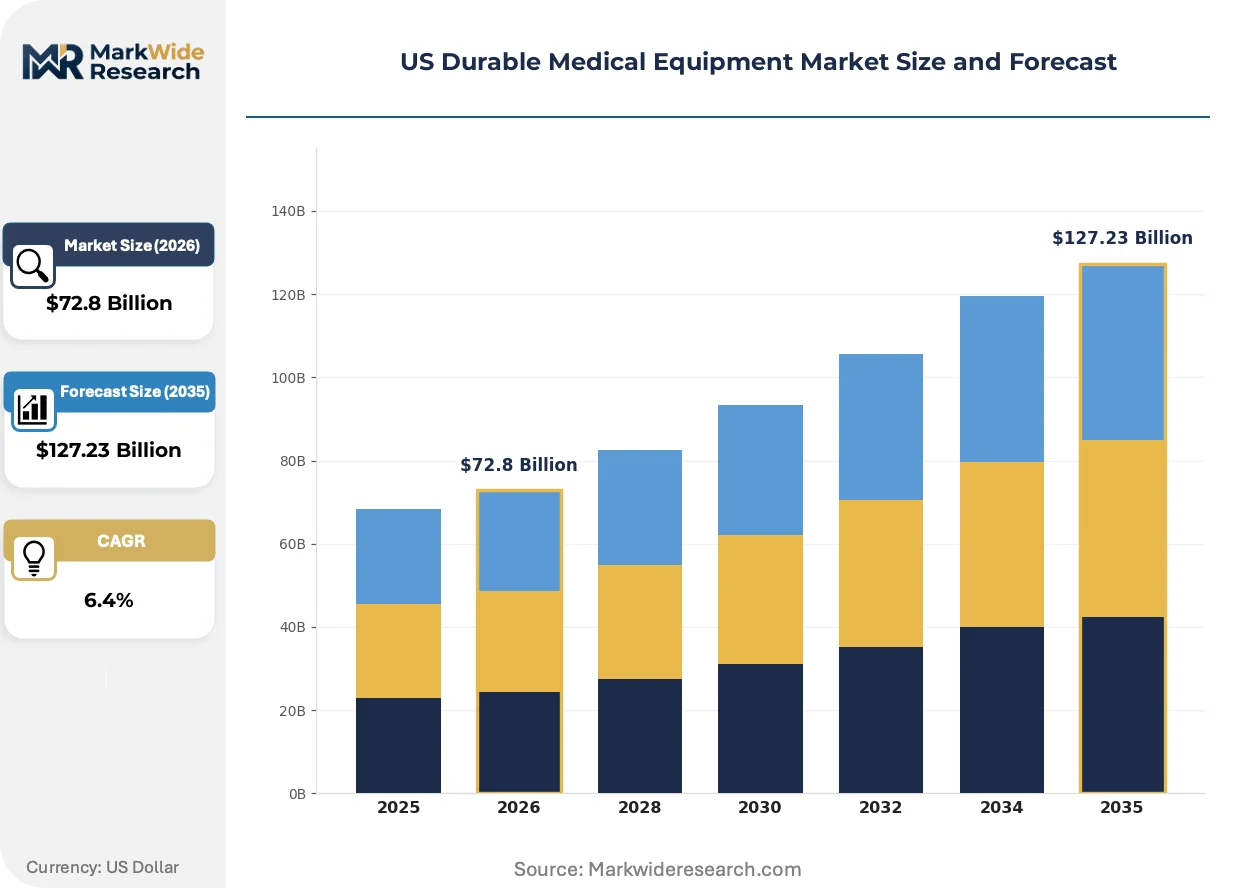
| Market Size in 2026 | $72.8 Billion |
| Market Size in 2035 | $127.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheelchairs, Hospital Beds, Oxygen Equipment, Mobility Scooters End User: Healthcare Facilities, Home Care, Rehabilitation Centers, Nursing Homes Technology: Telehealth, AI-Enabled Devices, Wearable Monitors, Smart Sensors Distribution Channel: Online Retailers, Medical Supply Stores, Pharmacies, Direct Sales |
| Companies Covered | Invacare Corporation, Medline Industries, Cardinal Health, Stryker, Sunrise Medical, GE HealthCare, Arjo, ResMed, Drive Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Durable Medical Equipment Market Strategic Shifts & Innovations
Device connectivity and predictive analytics are redefining how equipment performance is monitored, reimbursed, and serviced across home and institutional settings.
Continuous glucose monitoring systems with factory-calibrated sensors are consolidating real-time metabolic tracking into standard diabetes management protocols. Endocrinology practices and Medicare Advantage plans are adopting these devices at accelerating rates, replacing fingerstick glucometer workflows. This consolidation is compressing the traditional blood glucose monitoring supply chain and elevating subscription-based data platform revenue over hardware margins.
FDA breakthrough device designation pathways for AI-enabled diagnostic accessories are accelerating clearance timelines for algorithm-based arrhythmia detection and respiratory event classification. The industrial consequence is a bifurcation between established manufacturers with regulatory affairs infrastructure and software-native entrants lacking quality management system maturity. Cardiovascular monitoring segments are responding by acquiring FDA pre-submission expertise through consulting partnerships and former agency staff hires.
Consolidated billing arrangements between Medicare Advantage plans and national home health networks are displacing fee-for-service equipment rental models. Durable medical equipment suppliers face disintermediation as payers contract directly with manufacturers for multi-year managed service agreements. This restructuring is most visible in Florida and Texas markets where vertically integrated home health platforms command sufficient census volume to justify direct procurement relationships.
US Durable Medical Equipment Market Segmentation
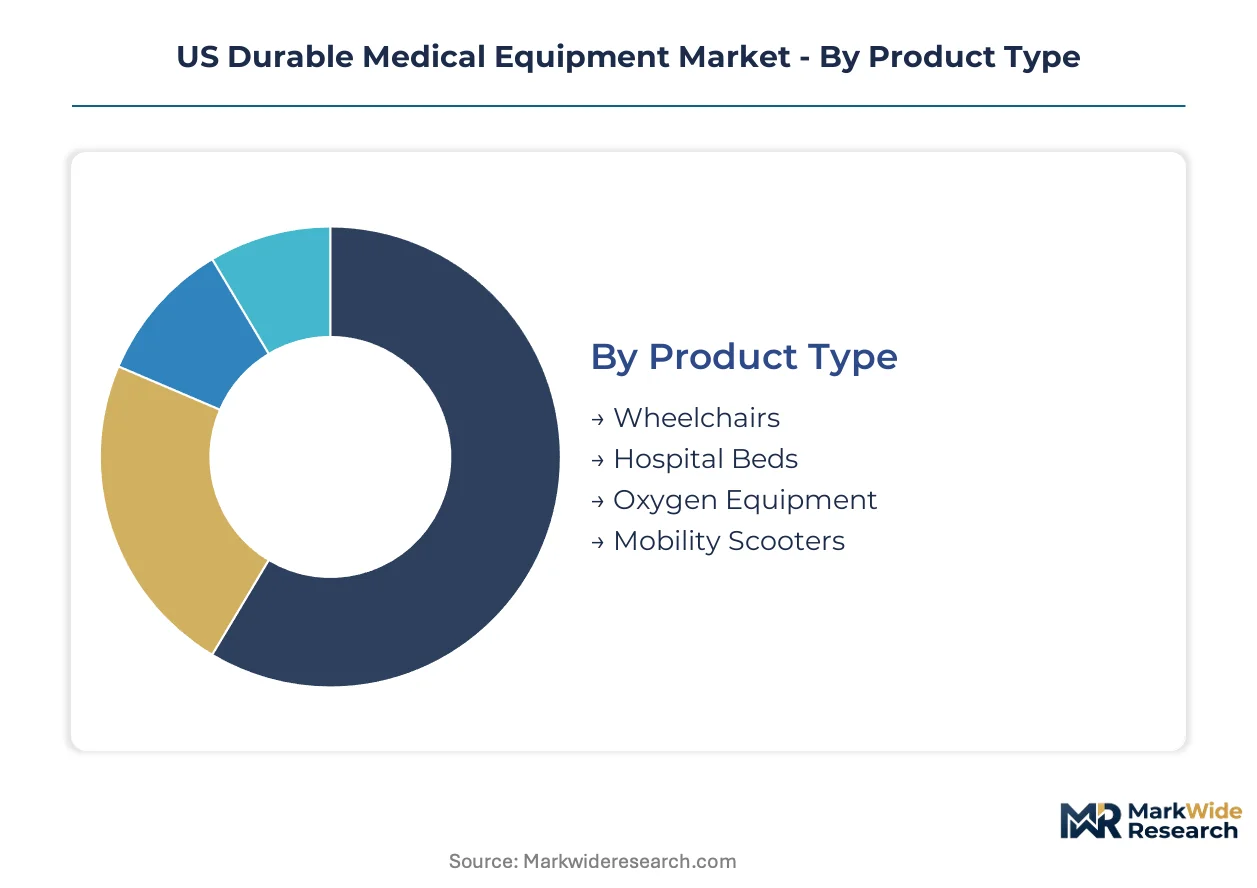
Equipment procurement decisions in the US durable medical equipment market diverge sharply across care settings, with reimbursement codes and patient acuity dictating technology specifications and channel selection. Segmentation reveals how CMS payment reforms are fragmenting demand pools and compressing margin structures differently by product category.
Product Type:
Load capacity ratings and frame material specifications drive hospital procurement committees, while home care purchasers prioritize Medicare reimbursement eligibility and residential footprint constraints.
- Wheelchairs:Aluminum and titanium frame variants rated to specific load capacities dominate institutional procurement, with bariatric specifications gaining traction in Texas and Florida home care markets as obesity prevalence climbs among Medicare populations.
- Hospital Beds:Integrated scale and positioning systems with Trendelenburg capability anchor acute care contracts, though CMS site-neutral payment reforms are forcing manufacturers to strip clinical features for cost-competitive home care configurations.
- Oxygen Equipment:Continuous flow concentrators and portable pulse-dose systems face compressor motor supply constraints from East Asian contract manufacturers.
- Mobility Scooters:Three-wheel and four-wheel configurations with disassembly capability for vehicle transport target Sun Belt retiree demographics.
Hospital beds lead on scale; AI-enabled accessories lead on momentum.
End User:
Care setting determines regulatory burden and service intensity, with home care agencies now absorbing equipment maintenance responsibilities previously borne by hospital biomedical departments.
- Healthcare Facilities:Acute care hospitals and outpatient clinics demand ISO 13485-certified equipment with preventive maintenance contracts, though legacy sole-source agreements with incumbent suppliers create switching friction for innovative mattress and positioning technologies.
- Home Care:Medicare-certified home health agencies and private-duty caregivers represent the steepest expansion trajectory, with CMS reimbursement for remote therapeutic monitoring codes accelerating connected device deployment in Florida and Arizona metropolitan statistical areas.
- Rehabilitation Centers:Inpatient and outpatient therapy facilities require equipment with adjustable resistance and positioning for functional recovery protocols.
- Nursing Homes:Long-term care facilities face Medicaid reimbursement compression that limits capital equipment refresh cycles.
Healthcare facilities lead on scale; home care leads on momentum.
Technology:
FDA clearance pathway complexity and CMS code valuation determine which connected technologies attract sustained R&D investment versus pilot deployment without reimbursement anchoring.
- Telehealth:Video-enabled consultation platforms with integrated device data streaming are consolidating into Medicare Advantage chronic care management workflows, displacing standalone remote monitoring vendors.
- AI-Enabled Devices:Machine learning algorithms for predictive fall detection and sleep apnea screening compress development cycles through FDA 510(k) clearance pathways, though quality management system maturity gaps separate established manufacturers from software-native entrants.
- Wearable Monitors:Factory-calibrated continuous glucose sensors and pulse oximeters face ONC 21st Century Cures Act interoperability certification delays.
- Smart Sensors:Environmental and biometric data capture devices with cellular connectivity enable automated transmission to electronic health records.
Telehealth leads on scale; AI-enabled devices leads on momentum.
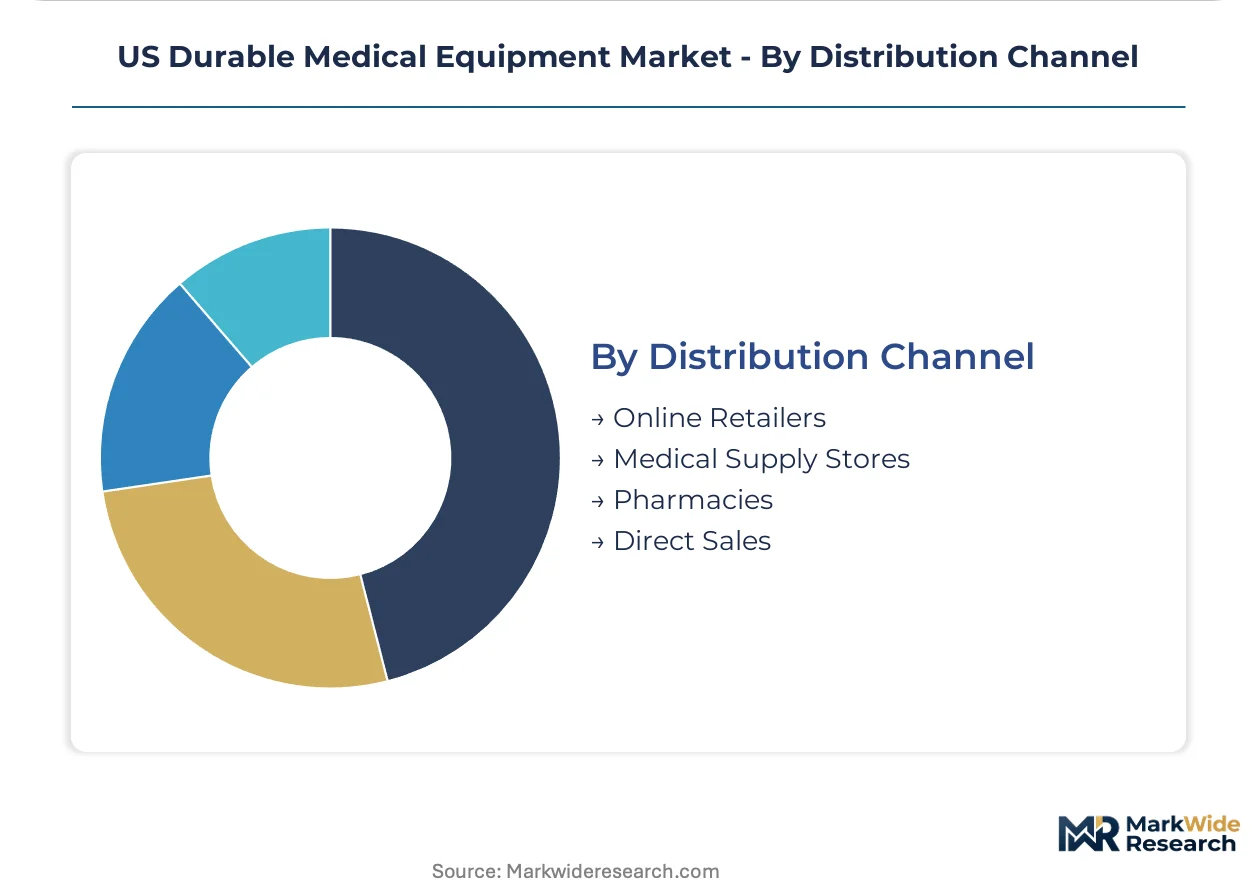
Distribution Channel:
Channel selection determines margin capture and patient onboarding friction, with direct relationships threatening traditional distributor networks.
- Online Retailers:E-commerce platforms with virtual fitting tools and insurance pre-authorization APIs are capturing margin previously allocated to durable medical equipment suppliers, particularly for standard wheelchairs and mobility scooters in cash-pay segments.
- Medical Supply Stores:Local brick-and-mortar networks with technician staffing for fitting and maintenance retain preference for complex rehabilitation equipment and bariatric specifications.
- Pharmacies:Retail pharmacy chains with Medicare billing infrastructure leverage foot traffic for diabetes and respiratory device dispensing.
- Direct Sales:Manufacturer-to-payer contracting through national home health networks displaces fee-for-service rental models in Florida and Texas markets.
Medical supply stores lead on scale; online retailers leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in metropolitan statistical areas with aging-in-place infrastructure anchor regional demand distribution across the United States.
Florida
Retiree migration concentrates Medicare Advantage enrollment in Tampa-St. Petersburg and Miami-Dade metropolitan areas, with CMS site-neutral payment reforms accelerating home care equipment procurement. Florida's Agency for Health Care Administration oversees Medicaid managed care contracts that capitate durable medical equipment benefits. Jacksonville anchors distribution networks serving the Interstate 10 corridor into Alabama and Georgia.
Texas
Houston and Dallas-Fort Worth medical centers drive bariatric equipment specifications as obesity prevalence climbs among insured populations. Texas Health and Human Services Commission administers Medicaid waiver programs for home and community-based services that expand wheelchair and hospital bed eligibility. Austin's health technology corridor attracts FDA pre-submission consulting firms serving AI-enabled device developers.
Arizona
Phoenix-Mesa-Scottsdale metropolitan statistical area leads per-capita mobility scooter deployment among Sun Belt retirement destinations. Arizona Health Care Cost Containment System reimbursement rates for remote therapeutic monitoring codes match Medicare Part B valuations. Tucson's University of Arizona Health Sciences campus trains rehabilitation technicians for ventilator and infusion pump maintenance roles.
California
Los Angeles County's dense home health agency network absorbs equipment maintenance responsibilities previously centralized in hospital biomedical departments. California Department of Health Care Services Medi-Cal expansion covers pressure injury prevention surfaces for newly eligible populations. San Diego's proximity to Tijuana maquiladoras creates cross-border sourcing relationships for aluminum wheelchair frame components.
US Durable Medical Equipment Market Key Industry Players
Capital-heavy producers compete with asset-light designers across durable medical equipment segments, with integrated manufacturers maintaining captive production of wheelchair frames and hospital bed platforms while specialty developers outsource compressor motors and molecular sieves to East Asian contract manufacturers. The vendor base stratifies across three tiers: national distributors with direct-to-facility networks, regional suppliers with technician staffing for complex rehabilitation fitting, and direct-to-consumer platforms with insurance pre-authorization APIs. Dominant competitive moves include vertical consolidation of distribution channels and acquisition of FDA regulatory affairs expertise through consulting partnerships.
Among publicly traded equipment specialists, Invacare Corporation and Sunrise Medical occupy positions exemplifying the rehabilitation-focused archetype, while Medline Industries anchors the private-label scale tier through direct procurement relationships with national home health networks. These three entities represent divergent strategic postures: one emphasizing aluminum and titanium frame manufacturing integration, another prioritizing pediatric and complex rehabilitation customization, and the third leveraging distributor bypass to capture margin compression from group purchasing organization contracting.
| Leading Market Players |
|---|
| Invacare Corporation |
| Medline Industries |
| Cardinal Health |
| Stryker |
| Sunrise Medical |
| GE HealthCare |
| Arjo |
| ResMed |
| Drive Medical |
| Others |
Cost & Logistics Intelligence
Cellular connectivity integration into respiratory and musculoskeletal devices compresses development economics while concentrating component sourcing among FDA-registered contract manufacturers. CMS reimbursement for remote therapeutic monitoring codes simultaneously expands addressable volume and intensifies cost scrutiny across connected equipment tiers.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes institutional procurement from home care channels, with acute care contracts wrapping preventive maintenance and clinical training into multi-year agreements while direct-to-consumer platforms strip services to hit cash-pay price points. Price differentiation rests on ISO 13485 certification status and after-sales service bundling, with hospital systems least sensitive to unit cost and Medicaid expansion states exhibiting acute price elasticity. Pricing pressure stems from CMS competitive bidding compression in designated metropolitan areas, forcing commodity wheelchair and hospital bed margins below sustainable thresholds for distributors lacking direct-to-facility scale.
Supply Chain Analysis
ISO 13485 certification gating restricts viable contract manufacturers for compressor motors and molecular sieves to East Asian facilities with FDA establishment registration. Component sourcing draws from China, Taiwan, and South Korea for electronic subassemblies, while Grade 5 titanium for wheelchair frames faces aerospace sector competition. Single-source vulnerability concentrates in molecular sieve production for oxygen concentrators. Distribution runs through national home health networks in Florida and Texas, bypassing traditional durable medical equipment supplier markups through direct manufacturer-to-payer contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with CMS National Coverage Determinations for remote therapeutic monitoring codes accelerating capital deployment into connected device segments.
For Market Incumbents: Extend FDA regulatory affairs infrastructure through consulting partnerships and former agency staff hires to compress 510(k) clearance timelines for AI-enabled accessories. Deepen backward integration into aluminum and titanium frame production to defend margin position against aerospace sector alloy competition. Prioritize captive supply of compressor motor assemblies to mitigate East Asian single-source vulnerability. For New Entrants and Emerging Players: Medicare-certified home health agencies in Medicaid expansion states represent the most penetrable channel archetype, with underpenetrated demand for bariatric equipment and pressure injury prevention surfaces among newly insured populations. Voice-first interface convergence for hands-free wheelchair navigation creates white space targeting high-level spinal cord injury users. Pursue e-commerce platforms with virtual fitting tools and insurance pre-authorization APIs to bypass distributor networks. For Investors and Strategic Acquirers: Valuations sit cheapest among regional suppliers with technician staffing for complex rehabilitation fitting but lacking direct-to-facility scale. Long-term viability favors entities with FDA quality management system maturity and CMS reimbursement code expertise. Watch CMS revaluation of remote therapeutic monitoring codes as the inflection signal determining which technology segments attract sustained capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance timelines compress development cycles for AI-enabled fall detection algorithms. |
| Hospital System Partnership | Sole-source agreements with integrated delivery networks lock out innovative mattress entrants. |
| Reimbursement Strategy | CMS National Coverage Determinations directly shape manufacturer revenue eligibility. |
| Software Companion Development | Cellular connectivity integration enables automated data transmission for RTM billing codes. |
| Backward Integration | Captive production of wheelchair frames defends margin against aerospace titanium competition. |
Research Approach
Direct dialogue with hospital purchasing committees, biomedical engineers, GPO contracts managers, and durable medical equipment supplier executives grounded qualitative findings in operational reality. Secondary validation drew from CMS Medicare data, FDA 510(k) clearance databases, hospital procurement records, and SEC filings of publicly traded equipment specialists. Bottom-up and top-down triangulation cross-checked volume estimates against reimbursement code utilization and manufacturing capacity disclosures.
Bottom-up modeling aggregated product-level demand across wheelchairs, hospital beds, oxygen equipment, and AI-enabled accessories, while top-down analysis calibrated aggregate market expansion against Medicare enrollment and site-neutral payment reform impacts. Segmentation dimensions spanned product type, end user setting, technology tier, and distribution channel, with CAGRs derived from reimbursement trajectory modeling and demographic migration patterns. Forecast inputs incorporated Sun Belt retiree concentration indices and FDA breakthrough device designation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS competitive bidding expansion and aluminum spot price volatility. Projections reflect assumptions regarding Medicare Advantage plan consolidation and remote monitoring code valuation stability. A model refresh is warranted upon material change in CMS National Coverage Determination schedules or East Asian contract manufacturer capacity disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Hospital Equipment and Supplies Market
Medical Equipment
Floor-Standing Platelet Agitator Market
Medical Equipment
Hospital-at-Home Equipment Rental Market
Medical Equipment
Diathermy Equipment Market
Medical Equipment
Global Microtome Market
Medical Equipment
Medical Equipment Reimbursement Market
Medical Equipment
Global Examination Lights Market
Medical Equipment
Tanning Units Market
Medical Equipment
ECG Equipment and Management Systems Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Durable Medical Equipment Rental Market
Medical Equipment
Asia-Pacific Medical Device Cleaning Market
Medical Equipment
Southern Europe and Middle East Medical Robotics Market
Medical Equipment
Mercury Thermometer Market
Medical Equipment
Europe Nuclear Medicine Equipment Market