
 Hospital-at-Home Equipment Rental Market | 2026-2036
Hospital-at-Home Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital-at-Home Equipment Rental Market Insights
Modular equipment bundling is shifting how health systems procure hospital-at-home fleets, replacing standalone device rentals with integrated respiratory-monitoring-mobility packages that reduce procurement friction. AdaptHealth leverages its national distribution footprint to anchor bundled respiratory programs across multiple states. US Med-Equip competes through rapid-turn logistics infrastructure that sustains same-day equipment deployment to hospital discharge planners. Agiliti differentiates by maintaining specialized biomedical technician networks that extend device uptime guarantees to health system clients.
Hospital-at-Home Equipment Rental encompasses the temporary provision of FDA-classified therapeutic and monitoring devices intended for acute-level care delivered in residential settings, typically including ventilators with integrated oxygen blending, multi-parameter patient monitors with cloud telemetry modules, and infusion pumps with dose-error reduction systems. These rentals enable health systems to avoid capital expenditure while maintaining clinical equivalence to inpatient wards. Ventilators and patient monitors command the dominant rental revenue share due to their higher per-day rates and mandatory biomedical oversight requirements. Subscription-based rental models are expanding fastest among telehealth-integrated providers seeking predictable cash flows and reduced administrative burden across chronic disease management programs.
FDA device classification requirements and CMS Conditions of Participation for hospital-at-home programs shape product eligibility and reimbursement pathways, directly determining which equipment manufacturers can access rental channels. HIPAA security rules and state-level home health licensure standards further constrain data transmission protocols and technician credentialing across multi-state rental operations. Stakeholders must monitor evolving FDA guidance on software-as-a-medical-device classifications that could reclassify cloud-connected monitoring platforms and alter compliance obligations for rental fleet operators.
Market Dynamics
CMS reimbursement waivers have dismantled payment barriers that previously confined acute care to hospital walls, triggering fleet expansion by US health systems seeking lower-cost discharge settings without sacrificing clinical intensity.
Growth Catalysts
- CMS Hospital-at-Home Waivers:Medicare reimbursement parity for home-based acute care eliminates financial disincentives that previously blocked residential ventilator and infusion pump deployment.
- Value-Based Care Contracts:Bundled payment models from commercial payers reward health systems for reducing inpatient length of stay through equipment-enabled home recovery protocols.
- Aging Demographics:The 65-plus population concentration in Florida, Arizona, and Texas generates concentrated demand for respiratory support rentals in post-acute discharge corridors.
Market Restraints
- Biomedical Technician Scarcity:FDA-mandated device servicing requirements outstrip certified technician supply, constraining fleet expansion velocity for rental operators.
- Supply Concentration in Semiconductor Components:Patient monitor telemetry modules depend on concentrated Asian chip foundry output, exposing rental fleets to input volatility.
- State Licensure Fragmentation:Home health agency licensing standards vary across 50 state jurisdictions, multiplying compliance overhead for multi-state rental operations.
Strategic Opportunities
- Rural Hospital Partnerships:Critical access hospitals in Montana, Wyoming, and North Dakota lack capital budgets for owned fleets, creating white-space demand for rental-based acute home care.
- Telehealth Platform Convergence:Integration of cloud-connected patient monitors with synchronous video triage enables remote physician oversight that satisfies CMS Conditions of Participation.
- Chronic Disease Management Subscriptions:Monthly bundled respiratory rentals for COPD and heart failure patients extend addressable demand beyond episodic acute episodes.
Industry Challenges
- HIPAA-Compliant Data Architecture:Cloud telemetry from multi-parameter monitors requires end-to-end encryption redesigns that delay product launches and inflate development costs.
- Legacy EHR Integration:Home device data streams must map to Epic and Cerner inpatient records, forcing custom API development that fragments vendor resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital-at-Home Equipment Rental Market |
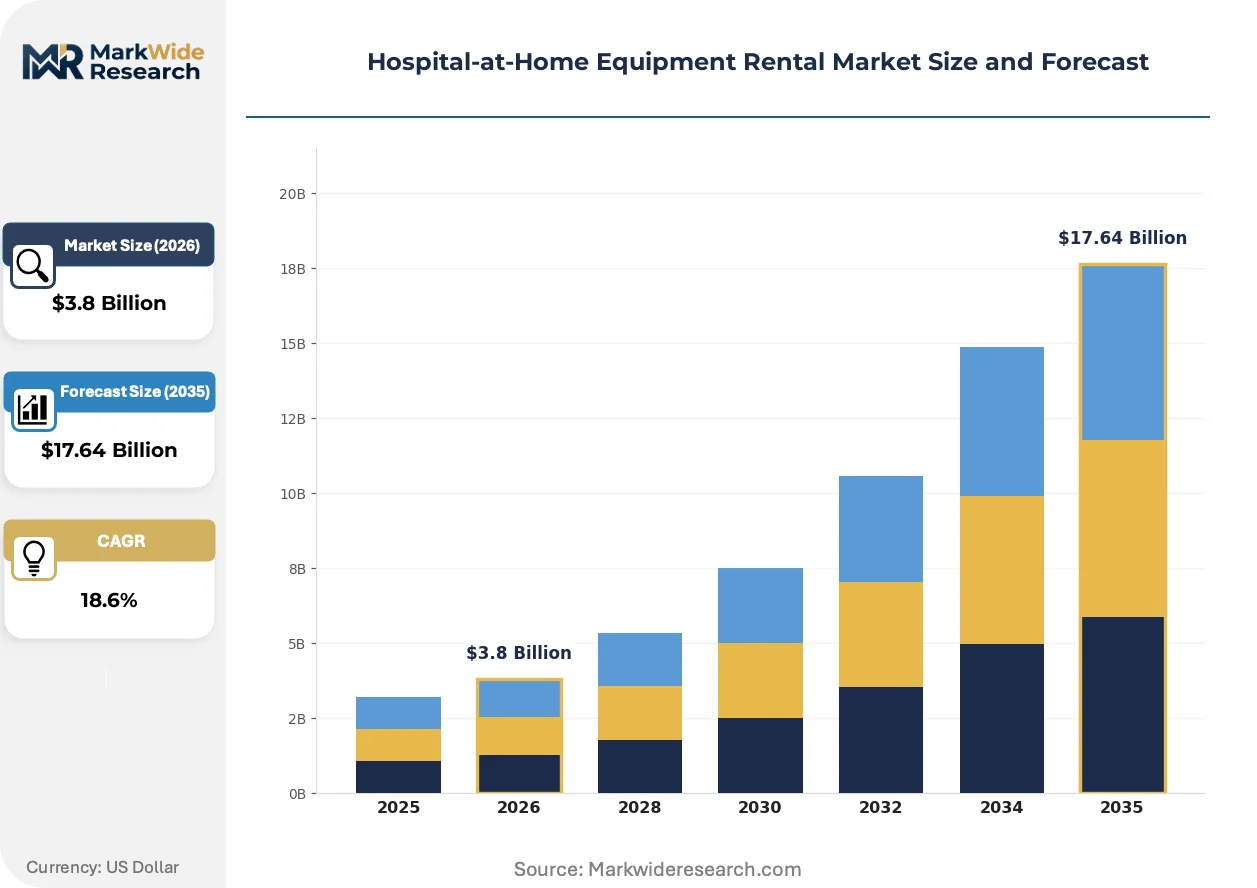
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilators, Infusion Pumps, Patient Monitors, Mobility Aids, Oxygen Concentrators Application: Postoperative Care, Chronic Disease Management, Remote Patient Monitoring, Palliative Care, Acute Illness Recovery End User: Home Healthcare Providers, Rehabilitation Centers, Nursing Agencies, Telehealth Services, Medical Equipment Suppliers Rental Model: Short-Term Lease, Long-Term Lease, Pay-Per-Use, Subscription-Based, Equipment Exchange |
| Companies Covered | AdaptHealth, Accendra Health, Quipt Home Medical, InfuSystem Holdings, Med One Group, US Med-Equip, Agiliti, Apria Healthcare, Hillrom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital-at-Home Equipment Rental Market Trends and Innovations
Equipment rental models are pivoting from transactional device provision toward integrated clinical service bundles that embed monitoring, logistics, and compliance oversight within single contracts.
Remote patient monitoring platforms with embedded artificial intelligence scoring are expanding into predictive deterioration alerts that trigger nurse intervention before emergency transport becomes necessary. Health systems in Texas and California are deploying these systems for post-surgical orthopedic patients within 72 hours of discharge. The technology is compressing readmission rates and extending rental contract durations from days to weeks.
FDA draft guidance on software-as-a-medical-device classifications is redefining which cloud-connected monitoring platforms require 510(k) clearance before rental fleet deployment. Rental operators must now validate algorithm updates through quality management systems that mirror pharmaceutical manufacturing protocols. Ventilator-integrated oxygen blenders with automated titration software face the steepest compliance burden under this evolving framework.
Health system procurement departments are consolidating vendor relationships around single-source equipment-service bundles that replace fragmented device-by-device sourcing. Discharge planners in Michigan and Ohio now contract with rental providers for guaranteed same-day deployment across ventilator, infusion, and mobility categories. This consolidation favors rental operators with national logistics infrastructure over regional equipment specialists.
Hospital-at-Home Equipment Rental Market Segmentation
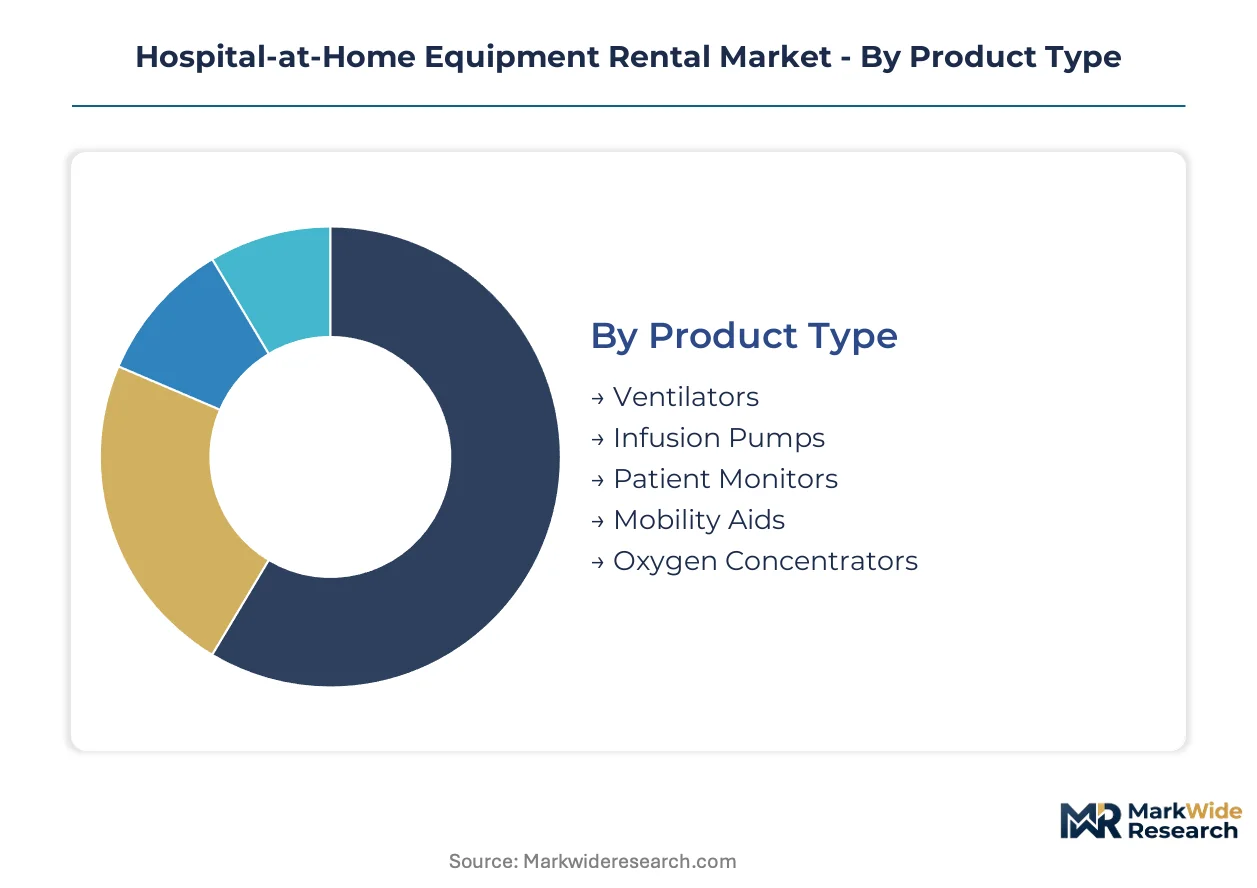
Equipment rental decisions in hospital-at-home programs hinge on clinical acuity levels, reimbursement pathways, and fleet utilization economics. Segmentation reveals how ventilator-heavy acute deployments diverge from chronic disease subscription models in procurement patterns and margin structures.
Product Type:
Clinical intensity and FDA servicing mandates drive procurement prioritization, with per-day rental rates scaling directly with biomedical oversight requirements.
- Ventilators:Devices with integrated oxygen blending and automated titration software command premium daily rates due to mandatory 24/7 respiratory therapist availability and complex disinfection protocols between patients. Demand concentrates in Florida and Arizona discharge corridors where post-acute COPD exacerbations dominate hospital-at-home admissions, constrained by biomedical technician scarcity that limits fleet expansion velocity.
- Patient Monitors:Multi-parameter units with cloud telemetry modules enable remote physician oversight that satisfies CMS Conditions of Participation for acute-level home care. Health systems in Texas and California deploy these for post-surgical orthopedic patients within 72 hours of discharge, with AI-embedded deterioration alerts compressing readmission rates and extending contract durations.
- Infusion Pumps:Dose-error reduction systems with smart drug libraries support complex antibiotic and chemotherapy administration in residential settings.
- Mobility Aids:Hospital beds, patient lifts, and wheelchairs complete bundled discharge packages but carry lower per-day margins.
- Oxygen Concentrators:Stationary and portable units serve chronic hypoxemia patients with simpler logistics requirements than ventilator deployments.
Ventilators lead on scale due to acute-care reimbursement parity; patient monitors lead on momentum as telehealth platform convergence accelerates.
Application:
Reimbursement pathway maturity determines addressable market depth, with episodic acute episodes offering higher per-case revenue than chronic management subscriptions.
- Postoperative Care:Orthopedic and cardiac surgery discharge protocols increasingly mandate home-based monitoring to reduce inpatient length of stay under bundled payment models. Michigan and Ohio health systems now contract for guaranteed same-day equipment deployment across ventilator, infusion, and mobility categories.
- Chronic Disease Management:Monthly bundled respiratory rentals for COPD and heart failure patients extend demand beyond acute episodes into predictable recurring revenue streams.
- Remote Patient Monitoring:Cloud-connected platforms with synchronous video triage satisfy regulatory oversight requirements while enabling geographic expansion.
- Palliative Care:End-of-life symptom management in residential settings prioritizes comfort-focused equipment configurations over acute-intensity monitoring.
- Acute Illness Recovery:Pneumonia and sepsis recovery protocols represent emerging applications with evolving clinical guidelines.
Postoperative care dominates current revenue concentration; chronic disease management offers the steepest expansion trajectory as subscription models mature.
End User:
Procurement sophistication varies sharply across customer types, with integrated health systems demanding single-source bundles that regional specialists cannot fulfill.
- Home Healthcare Providers:Licensed agencies with multi-state operations require HIPAA-compliant data architecture and standardized technician credentialing across jurisdictions.
- Rehabilitation Centers:Post-acute facilities transitioning patients to home settings prioritize equipment continuity during care handoffs.
- Nursing Agencies:Staffing-focused operators rely on rental partners for device logistics while managing clinical labor directly.
- Telehealth Services:Virtual-first providers integrating cloud-connected monitors with synchronous video platforms represent the fastest-climbing customer segment.
- Medical Equipment Suppliers:Traditional durable medical equipment dealers expanding into acute-care rentals face steeper compliance burdens than specialized hospital-at-home operators.
Home healthcare providers anchor volume through established CMS relationships; telehealth services gain share fastest as platform convergence redefines care delivery infrastructure.
Rental Model:
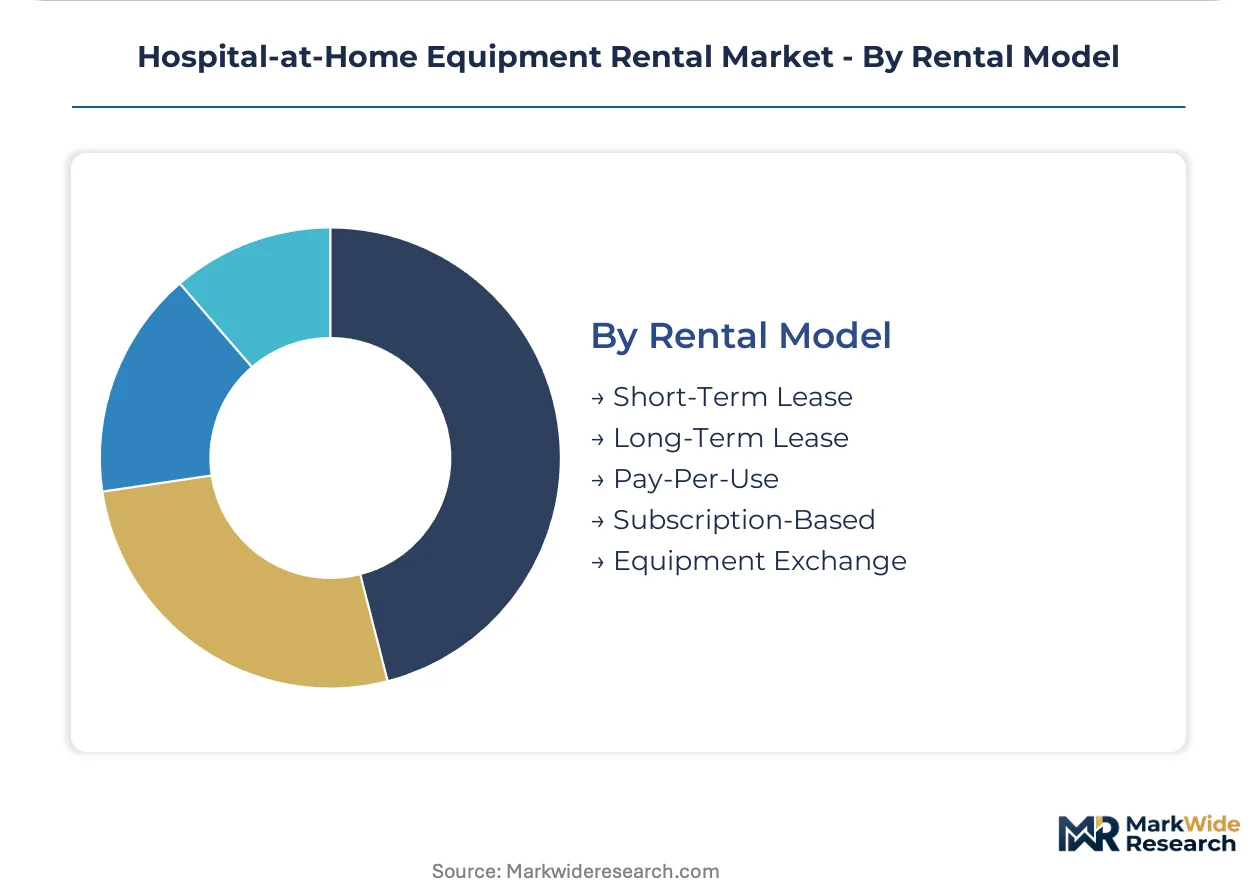
Cash flow predictability and administrative burden tradeoffs shape health system preferences, with subscription structures reducing procurement friction for chronic programs.
- Short-Term Lease:Daily or weekly arrangements serve episodic acute episodes with variable duration, requiring flexible logistics infrastructure for rapid deployment and retrieval.
- Long-Term Lease:Multi-month contracts support extended recovery protocols but demand accurate utilization forecasting to avoid stranded equipment.
- Pay-Per-Use:Metered billing based on actual device runtime appeals to cost-conscious critical access hospitals in Montana, Wyoming, and North Dakota with constrained capital budgets.
- Subscription-Based:Monthly bundled fees covering equipment, monitoring, and compliance oversight reduce administrative burden for chronic disease management programs.
- Equipment Exchange:Pool-based models allowing device swaps as patient acuity changes optimize fleet utilization for high-variability patient populations.
Short-term leases dominate acute-care revenue; subscription-based contracts expand most quickly as value-based care contracts reward predictable cost structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital-at-home equipment rental originated in the United States during the 1990s with Medicare-certified home health agencies deploying ventilators for post-acute respiratory patients. CMS reimbursement waivers in 2020 accelerated fleet scaling across multiple states, establishing the US as the primary demand center for acute-level home care rentals.
United States
Florida, Arizona, and Texas discharge corridors concentrate demand for ventilator rentals among aging COPD populations. CMS Hospital-at-Home Waivers eliminate payment barriers that previously blocked residential acute care deployment. Health systems in Michigan and Ohio now contract for guaranteed same-day equipment deployment across bundled respiratory-monitoring-mobility packages.
Germany
Germany's statutory health insurance system funds home ventilation through Diagnosis-Related Group carve-outs for chronic respiratory failure. The EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements on cloud-connected monitoring platforms than FDA 510(k) pathways. Rental operators in Bavaria and North Rhine-Westphalia maintain specialized biomedical technician networks to satisfy MDR post-market surveillance obligations.
United Kingdom
NHS England's virtual ward programs expanded from 7,000 to over 25,000 acute-level home care beds between 2021 and 2023. NICE guidelines now recommend pulse oximetry with automated deterioration alerts for post-COVID respiratory monitoring. London and Greater Manchester health systems pilot subscription-based rental models that bundle equipment with remote nursing oversight.
Japan
Japan's Ministry of Health, Labour and Welfare revised home medical care fee schedules in 2022 to cover ventilator rentals for amyotrophic lateral sclerosis patients. METI promotes telehealth-integrated monitoring platforms through regulatory sandboxes in Kansai and Chubu regions. Osaka-based rental providers face PMDA software-as-a-medical-device classification uncertainty for AI-embedded deterioration alert algorithms.
Australia
Australia's National Disability Insurance Scheme funds complex home respiratory equipment for neuromuscular disease patients. TGA conformity assessment procedures for cloud-connected patient monitors align with EU MDR mutual recognition agreements. New South Wales and Victoria health districts concentrate rental fleet deployment for post-surgical orthopedic patients within 72 hours of discharge.
Hospital-at-Home Equipment Rental Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service integration depth, with bundled clinical oversight commanding 40-60% rental rate premiums over standalone device provision. The market structures around three tiers: national logistics operators with same-day deployment guarantees, regional specialists with deep biomedical technician networks, and telehealth-integrated platforms with AI-embedded monitoring. Dominant competitive moves include fleet expansion through hospital system sole-source contracts and technology licensing for cloud telemetry integration.
Within the national logistics tier, AdaptHealth leverages its distribution footprint across multiple states, while US Med-Equip anchors rapid-turn deployment capabilities for discharge planners. Agiliti occupies a position among specialized service providers through biomedical technician networks that extend device uptime guarantees. These three represent distinct archetypes: AdaptHealth exemplifies scale-driven bundling, US Med-Equip anchors speed-to-bedside logistics, and Agiliti sits within the technical service specialization tier.
| Leading Market Players |
|---|
| AdaptHealth |
| Accendra Health |
| Quipt Home Medical |
| InfuSystem Holdings |
| Med One Group |
| US Med-Equip |
| Agiliti |
| Apria Healthcare |
| Hillrom |
| Others |
Pricing and Supply Chain Analysis
Integrated health systems with multi-state discharge programs command subscription-based bundled contracts that compress per-day rates while extending contract durations. Their procurement consolidation forces rental operators to absorb biomedical technician costs within flat-fee structures rather than pass through variable service charges.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by clinical intensity and service bundling. Premium tiers attach 24/7 respiratory therapist coverage and guaranteed uptime SLAs; standard tiers cover equipment-only deployment with business-hour support; economy tiers serve chronic oxygen patients with minimal logistics overhead. Price differentiation hinges on FDA device classification tier and geographic delivery density—rural deployments carry 15-25% surcharges due to technician travel costs. Cost compression in the economy tier is intensifying because critical access hospitals in Montana and Wyoming negotiate metered billing arrangements that shift utilization risk to rental operators. Telehealth-integrated platforms exhibit the lowest price sensitivity, accepting premium rates for AI-embedded monitoring that satisfies CMS Conditions of Participation.
Supply Chain Analysis
Direct-to-hospital discharge planner channels handle same-day deployment demand across ventilator, infusion, and mobility categories. Manufacturing concentrates in the United States, Germany, and China—FDA-cleared device production clusters in Minnesota and Massachusetts, precision sensor fabrication in Bavaria, and semiconductor components in Shenzhen and Shanghai. Patient monitor telemetry modules draw from concentrated Asian chip foundry output, creating single-source vulnerability for cloud-connected platforms. Distribution runs through regional biomedical technician hubs that maintain disinfection and calibration capabilities within four-hour response radii of major discharge corridors in Florida, Arizona, and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where health system procurement committees now mandate ISO 13485-certified service operations and FDA-compliant data architectures as table stakes, filtering out commodity rental operators.
For Market Incumbents: To counter biomedical technician scarcity constraining fleet expansion velocity, anchor defensive positioning through backward integration into in-house technician training academies partnered with community colleges in high-demand states. Lock in sole-source contracts with integrated delivery networks by embedding predictive maintenance algorithms that extend device uptime guarantees beyond regional competitors. For New Entrants and Emerging Players: CMS Hospital-at-Home Waivers in the United States open a window for specialized respiratory subscription services targeting COPD exacerbation corridors in Florida and Arizona discharge markets. Pursue white-space partnerships with critical access hospitals in Montana, Wyoming, and North Dakota through pay-per-use models that eliminate capital commitment barriers. Lead go-to-market with telehealth platform integration that bundles synchronous video triage with cloud-connected patient monitors. For Investors and Strategic Acquirers: National home health agencies with multi-state licensing infrastructure are the most active acquirer in this space, seeking rental fleet capabilities that extend service footprints beyond traditional durable medical equipment. Long-term viability hinges on regulatory compliance automation that reduces state-by-state licensure overhead. Watch for FDA draft guidance finalization on software-as-a-medical-device classifications as the inflection signal that separates AI-embedded monitoring platforms from commodity hardware rental.| Strategic Initiative | Industry Significance |
|---|---|
| Biomedical Technician Training Academy | Addresses FDA-mandated servicing requirements that outstrip certified technician supply in high-demand states. |
| AI-Embedded Deterioration Alert Development | Satisfies evolving FDA guidance on software-as-a-medical-device classifications for cloud-connected monitoring platforms. |
| Hospital System Sole-Source Contracting | Secures guaranteed same-day deployment relationships with Michigan and Ohio discharge planners seeking bundled packages. |
| Critical Access Hospital Partnership | Captures white-space demand in Montana, Wyoming, and North Dakota through pay-per-use rental models. |
| HIPAA-Compliant Data Architecture | Enables multi-state operations by satisfying encryption requirements for cloud telemetry from patient monitors. |
Research Methodology
Bottom-up health system procurement modeling reconciled against top-down rental fleet capacity tracking forms the analytical core of this study. Primary interviews with hospital discharge planners, biomedical engineering directors, GPO contracts managers, and home health agency executives combined with secondary validation against FDA 510(k) filings, CMS Medicare cost report data, state home health licensure databases, and hospital procurement system records. Triangulation across stakeholder inputs and regulatory filings ensures segmentation integrity across product type, application, end user, and rental model dimensions.
Input-output matrices map equipment deployment volumes against reimbursement pathway maturity and fleet utilization economics across the projection horizon. Segmentation dimensions modeled include clinical acuity tier, CMS waiver eligibility status, geographic discharge corridor density, and telehealth integration depth. CAGRs derive from equipment rental day trajectories weighted by per-day rate stratification and contract duration shifts toward subscription structures. Forecast inputs incorporate biomedical technician supply constraints and semiconductor component lead time volatility.
Revisions become necessary when FDA guidance finalization on software-as-a-medical-device classifications, CMS reimbursement waiver extensions or contractions, or state licensure reciprocity agreements materialize differently than baseline assumptions. Forecasts reflect documented assumptions about technician training pipeline throughput and cloud telemetry platform validation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Single-Coated Medical Tape Market
Medical Equipment
Global Gynecological Examination Chairs Market
Medical Equipment
Urodynamics Equipment and Disposables Market
Medical Equipment
North America Medical Automation Market
Medical Equipment
Tissue Culture Incubator Market
Medical Equipment
Birthing Beds Market
Medical Equipment
Centrifuge Market
Medical Equipment
Global Medical Copper Tubing Market
Medical Equipment
Global Vacuum Mixing Devices Market
Medical Equipment
Surgical Lighting System Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Photorejuvenation Equipment Market
Medical Equipment
Global Hospital Equipment and Supplies Market
Medical Equipment
Asia-Pacific Medical Device Reprocessing Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Europe Medical Device Reprocessing Market