
 Floor-Standing Platelet Agitator Market | 2026-2036
Floor-Standing Platelet Agitator Market Size, Share, and Industry Trends Forecast 2026-2036
Floor-Standing Platelet Agitator Market Insights
CE-marked and FDA-cleared specification tiers is redrawing competitive boundaries in platelet agitation equipment. Helmer Scientific leverages its vertically integrated manufacturing campus in Indiana to dominate North American hospital procurement. Sarstedt AG & Co. KG anchors European demand through specialized cold-chain logistics integration. Terumo Corporation competes across Asia-Pacific with electromechanical platforms calibrated to local voltage and frequency standards.
A floor-standing platelet agitator is a temperature-controlled mechanical device that maintains platelet concentrates in continuous gentle motion at 20–24°C to preserve viability and prevent aggregation during storage. The unit integrates electromechanical or magnetic levitation drive systems with calibrated oscillation frequencies, typically 60–70 cycles per minute, within a monitored thermal envelope. Automated agitators command premium positioning as blood banks replace manual units to reduce human error and extend platelet shelf life toward seven days. Dual-platform configurations capture expanding share in high-volume transfusion centers where throughput and redundancy determine capital allocation. Hospitals remain the dominant end-user channel, though research laboratories represent the fastest-growing demand node as cell therapy workflows proliferate.
FDA 21 CFR Part 606, EU MDR Class IIa requirements, and ISO 13485 quality management standards collectively shape product design, validation protocols, and market access timelines for platelet agitation equipment. The FDA's platelet storage guidance document directly influences oscillation parameter specifications and alarm system mandates for US-labeled devices. Stakeholders must monitor evolving CE marking transition deadlines under EU MDR and assess magnetic levitation technology maturation as a potential displacement vector for traditional electromechanical platforms.
Market Dynamics
Electromechanical platform upgrades are compressing replacement cycles for legacy manual agitators as blood banks face FDA-mandated shelf-life extensions and alarm system compliance deadlines.
Growth Catalysts
- FDA 21 CFR Part 606:Storage protocol mandates for continuous agitation and temperature monitoring are forcing manual unit retirements across US hospital networks.
- Magnetic levitation drive systems:Reduced mechanical wear and energy consumption are accelerating platform transitions in high-throughput transfusion centers.
- Cell therapy laboratories:Ex vivo platelet production workflows are creating parallel demand channels beyond traditional blood banking infrastructure.
Market Restraints
- Stainless steel and precision motor costs:Input price volatility for medical-grade alloys and brushless DC motors compresses margin structures for mid-tier manufacturers.
- EU MDR Class IIa transition:Extended validation timelines and notified body bottlenecks are delaying CE-marked product launches by 12-18 months.
- Benchtop agitator substitution:Compact units for low-volume settings are capturing share in rural hospitals and satellite collection centers.
Strategic Opportunities
- India's CDSCO pathway harmonization:Streamlined medical device registration is opening procurement channels for European and North American OEMs.
- Research laboratory channel:Gene therapy and regenerative medicine workflows are diversifying revenue beyond transfusion-dependent buyers.
- Dual-platform redundancy configurations:Capital allocation toward backup-capable systems is expanding average contract values in academic medical centers.
Industry Challenges
- ISO 13485 quality management implementation:Smaller manufacturers face resource constraints documenting design controls and risk management files for FDA submissions.
- Legacy electromechanical integration:Blood banks with 15-20 year-old infrastructure struggle to retrofit alarm interfaces and data logging protocols required by current guidance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor-Standing Platelet Agitator Market |
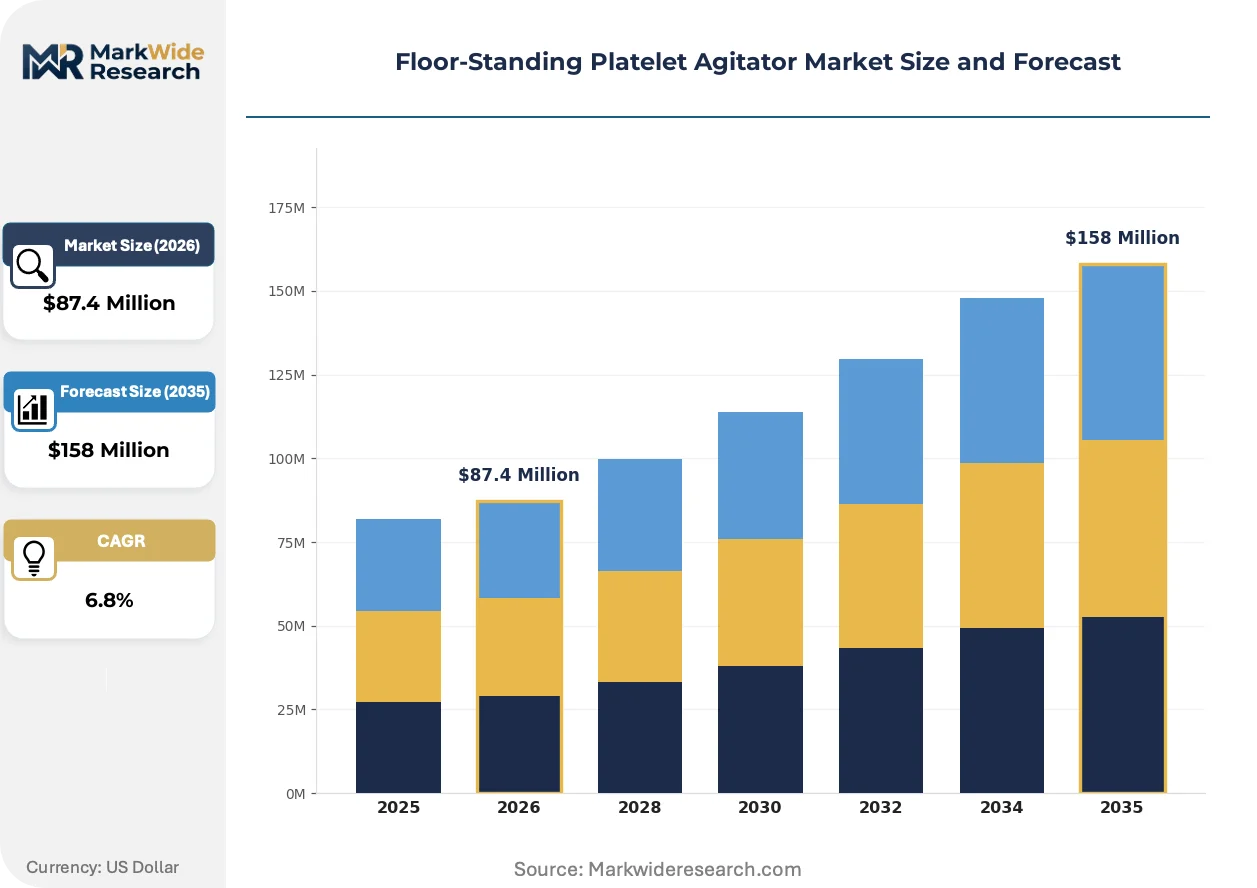
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Platform Agitators, Dual-Platform Agitators, Automated Agitators, Manual Agitators End User: Hospitals, Blood Banks, Research Laboratories, Diagnostic Centers Technology: Electromechanical, Magnetic Levitation, Pneumatic, Hybrid Systems Application: Platelet Storage, Blood Component Processing, Sample Preparation, Bioprocessing |
| Companies Covered | BIOBASE BIODUSTY(SHANDONG), Co., Ltd., NÜVE SANAYİ MALZEMELERİ İMALAT VE TİCARET A.Ş., Helmer Scientific, Sarstedt AG & Co. KG, Biolab Scientific, Terumo Corporation, Meditech Technologies India Private Limited, Lmb Technologie GmbH, Boekel Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor-Standing Platelet Agitator Market Trends and Innovations
Platform architecture is bifurcating between premium automated systems and cost-optimized electromechanical units as buyer sophistication diverges across hospital tiers and research settings.
Magnetic levitation agitation technology is fragmenting the traditional electromechanical supplier base by eliminating drive belt maintenance and enabling sealed chamber designs. Academic medical centers in Germany and Japan are piloting these platforms for seven-day platelet storage validation studies. The technology is fragmenting procurement committees into performance-specification and total-cost-of-ownership factions.
EU MDR technical documentation requirements are extending product development cycles for CE-marked devices. Manufacturers must now submit clinical evaluation reports and post-market surveillance protocols that exceed previous Medical Device Directive thresholds. Blood banks in France and Italy are delaying replacement purchases until supplier recertification status clarifies.
Service contract unbundling is separating hardware acquisition from calibration and preventive maintenance agreements. Hospital procurement departments in the United States are negotiating multi-vendor service portfolios rather than single-source captive arrangements. This shift is most visible in integrated delivery networks consolidating transfusion services across multiple sites.
Floor-Standing Platelet Agitator Market Segmentation
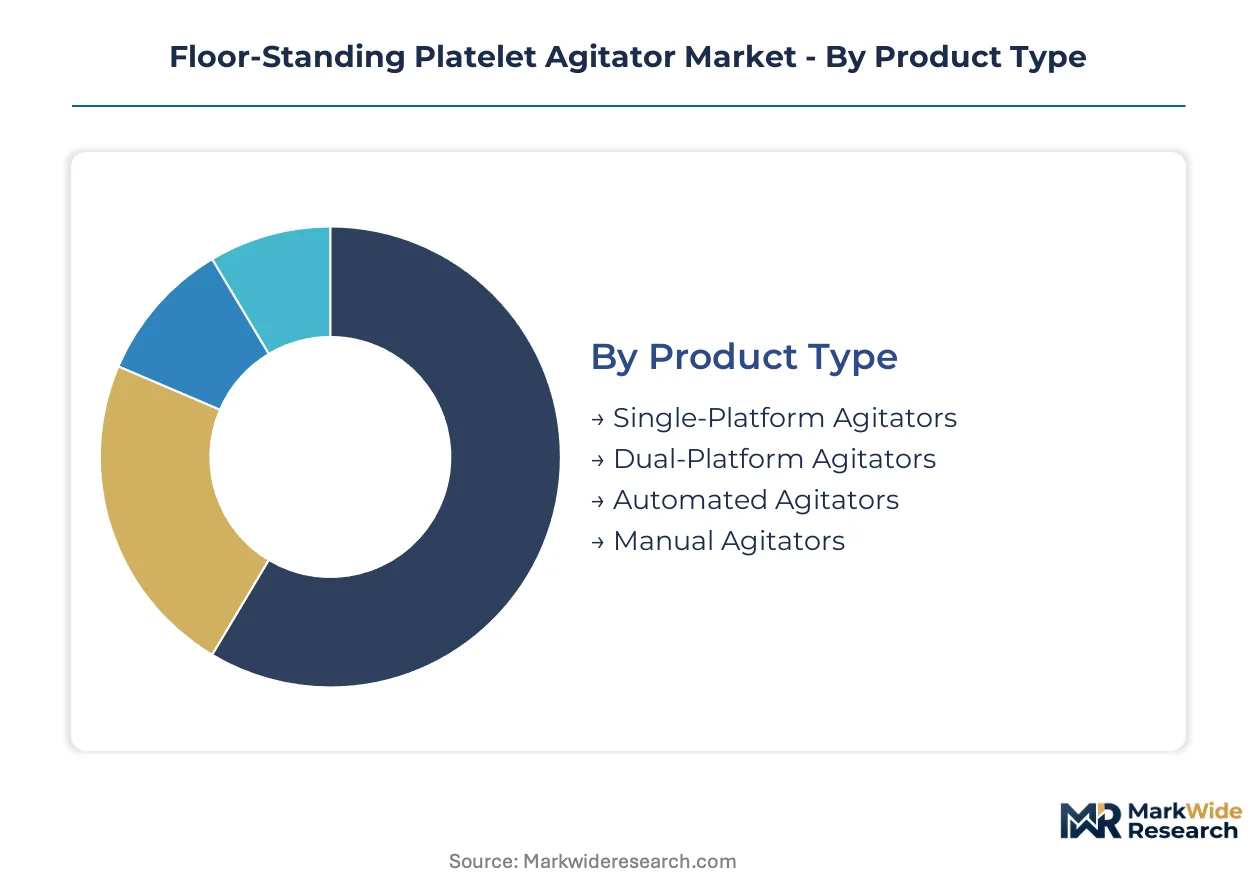
Segmentation in the floor-standing platelet agitator market reveals how procurement committees balance throughput requirements against total cost of ownership. Blood banks and hospital networks prioritize different performance tiers based on transfusion volume, regulatory compliance deadlines, and integration with existing cold-chain infrastructure.
Product Type:
Benchtop units and compact alternatives are exerting substitution pressure on floor-standing configurations in low-throughput settings, forcing manufacturers to defend the value proposition of full-size platforms through extended shelf-life capabilities and redundant alarm systems.
- Dual-Platform Agitators:These units integrate two independent oscillation chambers within a single thermal envelope, enabling simultaneous processing of platelet concentrates at different storage stages. Academic medical centers in the United States and Germany are standardizing on these configurations to consolidate footprint while maintaining backup capacity during maintenance windows.
- Automated Agitators:Microprocessor-controlled platforms with integrated data logging, remote monitoring capability, and programmable alarm thresholds. Blood banks facing FDA 21 CFR Part 606 compliance deadlines are retiring manual units for these systems to eliminate human error in continuous agitation protocols.
- Single-Platform Agitators:Compact floor-standing units designed for satellite collection centers and rural hospital networks with moderate transfusion volumes.
- Manual Agitators:Basic electromechanical platforms without automated monitoring, now restricted to research settings and legacy infrastructure in regions with delayed regulatory enforcement.
Dual-platform configurations anchor the volume base while automated agitators gain share at the steepest rate as compliance deadlines compress replacement cycles.
End User:
Customer procurement sophistication diverges sharply across this dimension, with integrated delivery networks negotiating enterprise-wide service contracts while independent blood banks prioritize capital efficiency and extended warranty terms.
- Hospitals:Transfusion services departments within tertiary care facilities represent the core installed base, with procurement decisions increasingly centralized at the IDN level. These buyers demand ISO 13485-compliant documentation and validated integration with laboratory information systems.
- Blood Banks:Centralized transfusion services in the United States, Germany, and Japan drive replacement demand as seven-day platelet storage protocols expand. These facilities specify continuous temperature monitoring and redundant drive systems to prevent inventory loss.
- Research Laboratories:Cell therapy and gene therapy workflows are creating parallel demand channels with distinct specifications for ex vivo platelet production and bioprocessing applications.
- Diagnostic Centers:Smaller-volume settings where benchtop units often substitute for floor-standing platforms, limiting addressable market penetration.
Hospitals and blood banks together dominate current procurement volumes, though research laboratories are climbing the fastest as regenerative medicine infrastructure expands.
Technology:
Platform architecture choices directly determine maintenance burden, energy consumption, and compliance with sealed-chamber requirements for extended platelet storage validation.
- Electromechanical:Brushless DC motor systems with belt-driven oscillation mechanisms represent the established installed base. These platforms face margin pressure from stainless steel and precision motor input costs while requiring periodic maintenance for drive component replacement.
- Magnetic Levitation:Contactless drive systems eliminating mechanical wear and enabling fully sealed chamber designs. High-throughput transfusion centers in Germany and Japan are piloting these platforms for seven-day storage studies, though upfront capital requirements limit adoption to premium-tier buyers.
- Pneumatic:Compressed air-driven oscillation systems with simpler mechanical construction but higher operational noise profiles and facility infrastructure requirements.
- Hybrid Systems:Configurations combining electromechanical reliability with magnetic levitation precision in multi-chamber units, targeting academic medical centers with diverse processing needs.
Electromechanical platforms retain the largest installed base while magnetic levitation systems are expanding most quickly among early-adopter facilities.
Application:
Use-case specificity determines oscillation parameter requirements, chamber configuration, and integration with upstream collection and downstream distribution workflows.
- Platelet Storage:The core application requiring continuous gentle agitation at 60-70 cycles per minute within a 20-24°C thermal envelope. FDA guidance on shelf-life extension is driving specification upgrades across US hospital networks.
- Blood Component Processing:Agitation during leukoreduction, pooling, and irradiation procedures, with demand concentrated in centralized transfusion facilities with integrated component manufacturing capabilities.
- Sample Preparation:Pre-analytical processing workflows in clinical laboratories with lower throughput requirements and greater price sensitivity.
- Bioprocessing:Cell therapy manufacturing applications including ex vivo platelet production, with specifications diverging from transfusion-medicine standards.
Platelet storage anchors procurement volumes while bioprocessing applications are gaining share fastest as cell therapy manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from German and US manufacturers dominate cross-border equipment supply, while import dependency shapes procurement patterns in emerging transfusion markets. Japan and India represent net import zones where domestic production capacity lags clinical demand growth. Regulatory harmonization initiatives are compressing market access timelines for OEMs seeking multi-territory certification.
United States
FDA 21 CFR Part 606 compliance deadlines are accelerating replacement cycles across hospital networks as seven-day platelet storage protocols expand. Blood centers in the American Red Cross network specify automated agitation systems with integrated data logging to meet shelf-life extension requirements. Indiana hosts vertically integrated manufacturing campuses serving North American procurement channels.
Germany
EU MDR Class IIa transition timelines are delaying CE-marked product launches while academic medical centers pilot magnetic levitation platforms for extended storage validation. The country's national pharmaceutical regulator enforces stringent post-market surveillance protocols that exceed previous Medical Device Directive thresholds. Bavarian transfusion centers are consolidating procurement across integrated delivery networks.
Japan
PMDA calibration requirements for electromechanical platforms are shaping product specifications for voltage and frequency standards unique to the domestic grid. METI initiatives on regenerative medicine infrastructure are channeling capital toward cell therapy laboratory buildouts. Tokyo and Osaka metropolitan clusters anchor demand for dual-platform configurations in high-throughput academic hospitals.
India
CDSCO pathway harmonization is streamlining medical device registration for European and North American OEMs seeking market entry. Maharashtra and Karnataka state health departments are centralizing transfusion services previously fragmented across district hospitals. Mumbai and Bangalore host emerging procurement clusters where blood banks replace manual units with automated systems.
Floor-Standing Platelet Agitator Market Competitive Landscape
Concentration sits with vertically integrated specialists and regional cold-chain integrators who control manufacturing depth and distribution proximity. The supplier base stratifies across three tiers: premium automated platforms, mid-range electromechanical units, and cost-optimized manual systems. Dominant competitive moves include geographic expansion through regulatory harmonization and technology licensing partnerships for magnetic levitation drive systems.
Among US and European equipment fabricators, Helmer Scientific, Sarstedt AG & Co. KG, and Terumo Corporation occupy distinct positioning archetypes. Helmer Scientific exemplifies the vertically integrated North American manufacturer with captive production capacity. Sarstedt AG & Co. KG represents the European cold-chain logistics specialist with integrated distribution control. Terumo Corporation anchors the Asia-Pacific regional supplier segment with platforms calibrated to local electrical standards.
| Leading Market Players |
|---|
| BIOBASE BIODUSTY(SHANDONG), Co., Ltd. |
| NÜVE SANAYİ MALZEMELERİ İMALAT VE TİCARET A.Ş. |
| Helmer Scientific |
| Sarstedt AG & Co. KG |
| Biolab Scientific |
| Terumo Corporation |
| Meditech Technologies India Private Limited |
| Lmb Technologie GmbH |
| Boekel Scientific |
| Others |
Pricing and Supply Chain Analysis
Multi-year service contracts with embedded calibration and preventive maintenance clauses lock in both supply access and price visibility for blood banks navigating FDA compliance deadlines. These arrangements insulate buyers from stainless steel and precision motor cost volatility while tying vendors to performance guarantees on uptime and alarm system reliability.
Pricing Analysis
Hospital procurement committees and integrated delivery network buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on FDA 510(k) clearance tier and ISO 13485 documentation completeness, with academic medical centers least sensitive and rural satellite collection centers most price-responsive. Cost compression in mid-range electromechanical units is intensifying because brushless DC motor suppliers face medical-grade alloy input volatility. Automated agitation platforms with integrated data logging command premium positioning against manual units facing regulatory obsolescence.
Supply Chain Analysis
Indiana and Bavaria anchor captive production of electromechanical drive systems and thermal envelope assemblies for North American and European demand. Manufacturing draws from Japanese brushless DC motor suppliers, German precision bearing fabricators, and domestic stainless steel processors. Single-source vulnerability concentrates in medical-grade alloy supply from specialized foundries. Distribution runs through cold-chain logistics integrators with GMP-certified warehousing and direct-to-hospital installation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery driven by FDA-mandated shelf-life extension protocols forcing replacement of legacy manual agitators across American hospital networks.
For Market Incumbents: Fortify installed base retention through backward integration into precision motor supply and predictive maintenance software layers. Magnetic levitation technology threatens electromechanical margins; counter by accelerating ISO 13485 certification investments for dual-platform configurations that academic medical centers specify for redundancy. Channel control through exclusive GPO contracts remains essential. For New Entrants and Emerging Players: Remote monitoring and calibration service gaps in rural blood bank networks offer white-space entry points. India's CDSCO harmonization creates the most penetrable geography for European and North American OEMs seeking regulatory arbitrage. Target research laboratories with ex vivo platelet production specifications diverging from transfusion-medicine standards, using cell therapy workflow integration as the go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated manufacturers with captive Indiana or Bavarian production campuses and established FDA 510(k) portfolios. Long-term viability over a five-to-ten year horizon rests on magnetic levitation technology maturation and seven-day storage validation completion. Watch for PMDA calibration requirement shifts in Japan as the inflection signal for Asia-Pacific platform standardization.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Recertification | CE marking transition timelines determine European market access for automated agitation platforms. |
| Magnetic Levitation Technology Licensing | Contactless drive partnerships enable sealed chamber designs for seven-day storage validation. |
| Hospital System Partnership | Integrated delivery network contracts consolidate procurement across multi-site transfusion services. |
| Software Companion Development | Remote monitoring applications differentiate automated platforms from legacy electromechanical units. |
| CDSCO Registration Pathway | Streamlined Indian medical device approval opens procurement channels for Western OEMs. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases preceded structured interviews with biomedical engineers, blood bank operations directors, GPO contracts managers, and cold-chain logistics specialists. Primary fieldwork with transfusion service administrators and regulatory affairs leads at device manufacturers was cross-validated against secondary sources including ISO 13485 audit records and customs trade data. Bottom-up unit demand estimates were triangulated with top-down market sizing across product type, end user, and technology segments.
Variance decomposition across electromechanical and magnetic levitation technology adoption curves, regional regulatory compliance deadlines, and research laboratory channel expansion shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include platform configuration, end-user procurement sophistication, drive system architecture, and application specificity from platelet storage through bioprocessing. CAGRs were derived from replacement cycle compression analysis and installed base turnover rates, with inputs from stainless steel price indices and notified body capacity constraints.
Underlying assumptions cover FDA guidance stability, EU MDR transition timelines, and magnetic levitation reliability maturation, with deviation risk concentrated in input cost volatility for medical-grade alloys and brushless DC motors. Recalibration cycles align with material shifts in regulatory enforcement patterns and seven-day storage protocol adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Power Supply Market
Medical Equipment
Medical Linear Accelerators (MLA) Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Benchtop Platelet Agitator Market
Medical Equipment
Faecal Extraction System Market
Medical Equipment
Global Surgical Lights Market
Medical Equipment
Global Surgical Table Market
Medical Equipment
Medical Carts and Workstations Market
Medical Equipment
Global Carbon Dioxide Incubators Market
Medical Equipment
Global Radiation Therapy Equipment Market
Medical Equipment
Centrifuge Market
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
Asia-Pacific Nuclear Medicine Equipment Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
Medical Thawing Systems Market
Medical Equipment
Cryogenic Freezers Market