
 Mercury Thermometer Market | 2026-2036
Mercury Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Mercury Thermometer Market Analytics
Digital temperature sensing is tilting the product architecture away from glass-encased mercury columns toward semiconductor-based probes and infrared modules. Geratherm Medical AG leverages its European manufacturing base to sustain specialized mercury instrument production for legacy clinical environments. Terumo Corporation anchors its position through diversified temperature management portfolios that span both conventional and electronic platforms. Welch Allyn competes primarily in North American hospital procurement channels where institutional buying preferences still accommodate mercury devices for specific calibration protocols.
A mercury thermometer is a sealed glass instrument containing elemental mercury that expands through a calibrated capillary bore to indicate temperature readings, typically manufactured with precision-bored soda-lime or borosilicate glass and graduated in Celsius or Fahrenheit scales for clinical, laboratory, or industrial measurement. The device serves fundamentally as a passive, non-powered thermal measurement tool requiring no electrical infrastructure, which preserves its utility in resource-constrained settings. Clinical thermometers retain the dominant share of residual value as healthcare facilities balance replacement costs against infection control requirements, while laboratory thermometers command tighter margin pools due to stringent calibration traceability demands. Industrial thermometers face accelerated displacement from thermocouple and RTD alternatives, though ambient temperature sensors maintain niche applications in meteorological stations where mercury's thermal linearity remains valued.
The Minamata Convention on Mercury governs international phase-down commitments, while the EPA administers domestic mercury waste disposal rules in the United States and the EMA's Medical Device Regulation imposes conformity assessment burdens on clinical instruments sold in Europe. FDA enforcement discretion for existing mercury thermometer inventories shapes liquidation timelines and secondary market dynamics. Stakeholders must monitor regulatory enforcement variance across jurisdictions to anticipate supply discontinuities and residual demand windows.
Market Dynamics
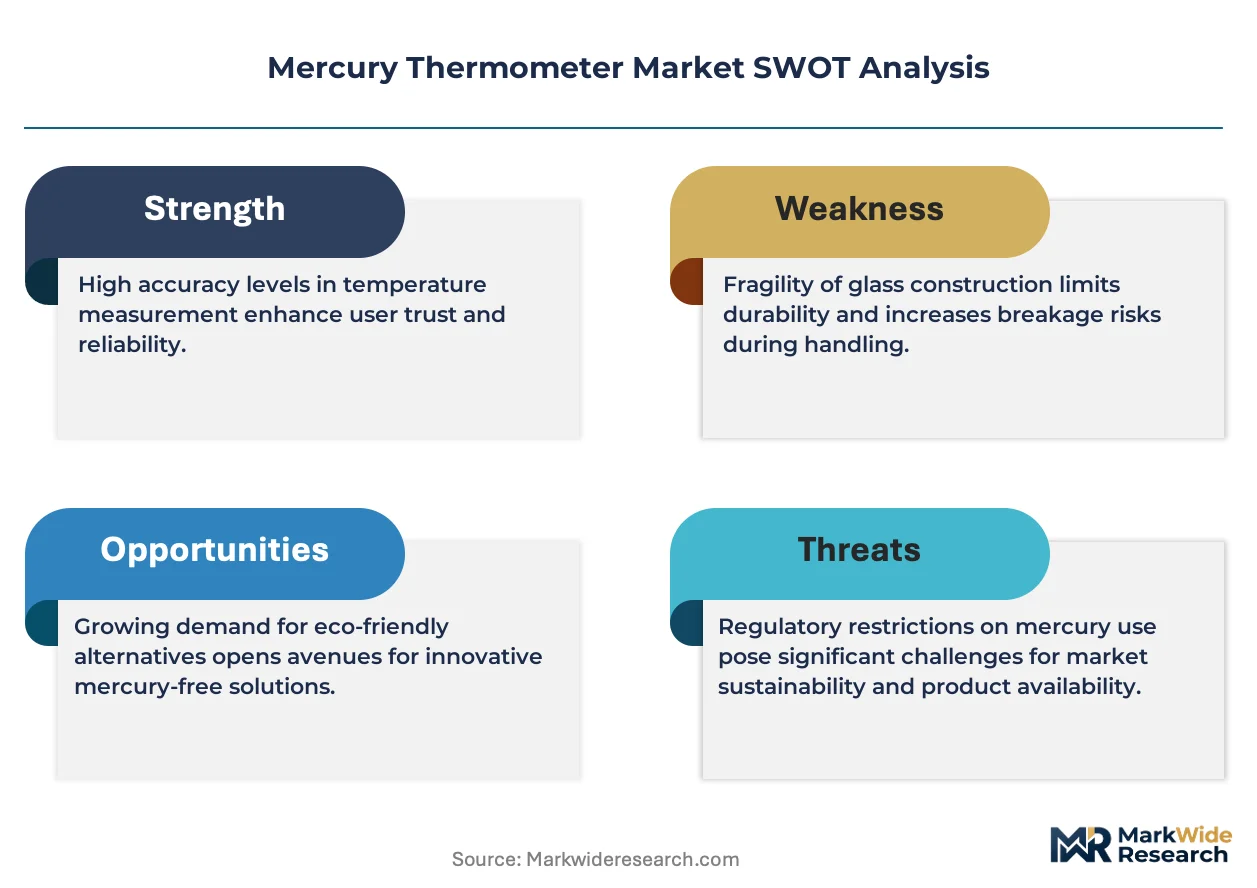
The mercury thermometer market confronts a structural deceleration as the Minamata Convention on Mercury imposes binding phase-down commitments on signatory nations, forcing manufacturers to navigate shrinking production windows while serving residual clinical demand in budget-constrained healthcare systems.
Growth Catalysts
- Calibration protocol persistence:Laboratory accreditation standards in Germany and Switzerland continue mandating mercury-based reference thermometers for NIST-traceable calibration chains, sustaining specialized procurement in metrology institutes.
- India's healthcare infrastructure gap:Primary health centers across Rajasthan, Uttar Pradesh, and Bihar prioritize mercury thermometers for maternal and pediatric screening due to zero battery dependency and sub-$1 unit economics.
- EMA Medical Device Regulation grandfathering:Existing CE-marked mercury clinical thermometers maintain market access through transitional provisions, extending commercial viability for legacy inventory holders.
Market Restraints
- Elemental mercury supply concentration:Refining capacity clusters in Kyrgyzstan and Algeria, exposing manufacturers to export quota volatility and geopolitical supply interruptions.
- Digital infrared substitution:Welch Allyn and Terumo infrared tympanic thermometers achieve sub-30-second readings with ±0.1°C accuracy, eroding mercury's clinical relevance in acute care.
- EPA hazardous waste disposal rules:US healthcare facilities face cradle-to-grave tracking costs for mercury thermometer breakage, converting apparent unit savings into total-cost-of-ownership penalties.
Strategic Opportunities
- Indonesia's archipelago logistics:Remote island clinics in Papua and Maluku provinces lack reliable electricity infrastructure, creating captive demand for passive thermal measurement instruments.
- Brazil's SUS procurement fragmentation:Municipal health secretariats in Northeastern states operate outside federal digitalization mandates, preserving decentralized mercury thermometer purchasing.
- CE marking MDR gap exploitation:Notified body bottlenecks delay competitor digital thermometer certifications, opening temporary residual demand windows for grandfathered mercury devices.
Industry Challenges
- Glassblower artisan scarcity:Precision-bore capillary fabrication requires master craftspeople trained in borosilicate manipulation, with apprenticeship pipelines collapsed across Czech and Italian manufacturing clusters.
- Calibration laboratory consolidation:ISO 17025-accredited temperature calibration facilities are shuttering mercury-based services, forcing manufacturers to transport instruments across national borders for recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mercury Thermometer Market |
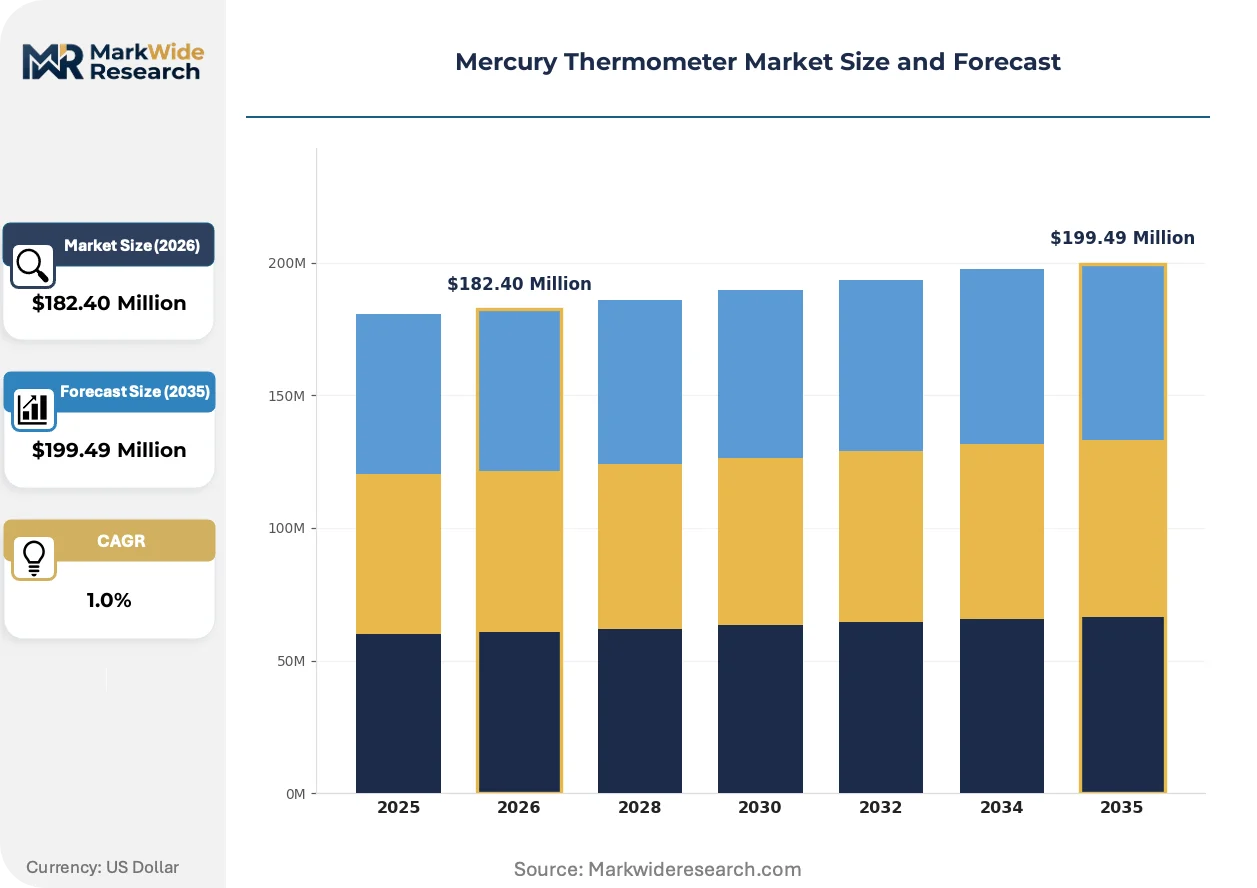
| Market Size in 2026 | $182.40 Million |
| Market Size in 2035 | $199.49 Million |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Thermometers, Laboratory Thermometers, Industrial Thermometers, Ambient Temperature Sensors End User: Hospitals, Clinics, Research Laboratories, Manufacturing Facilities Application: Patient Monitoring, Scientific Research, Equipment Testing, Environmental Monitoring Certification: ISO Certified, CE Marked, FDA Approved, Other Standards |
| Companies Covered | Geratherm Medical AG, Terumo Corporation, Medline Industries, Thermo Fisher Scientific, Microlife Corporation, Omron Healthcare, 3M, Welch Allyn, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mercury Thermometer Market Evolving Landscape
Mercury thermometer technology is hybridizing with digital interfaces as manufacturers attempt to bridge legacy measurement reliability with modern data capture requirements, while regulatory enforcement variance creates uneven innovation pressure across jurisdictions.
Hybrid mercury-digital calibration systems are hybridizing reference-grade mercury columns with semiconductor-based data logging modules. National metrology institutes in Japan and South Korea are adopting these instruments for pharmaceutical stability testing where thermal linearity documentation remains mandatory. The convergence is compressing pure mercury instrument demand to isolated calibration laboratory niches while expanding adjacent sensor integration markets.
The EU F-Gas Regulation and REACH annex XVII amendments are accelerating mercury thermometer decommissioning timelines across Scandinavian hospital networks. Industrial consequence includes forced asset write-downs for clinical engineering departments holding decade-scale mercury inventory reserves. German university hospitals are responding through centralized hazardous material collection cooperatives to pool disposal costs.
Hospital group purchasing organizations are consolidating temperature measurement procurement into multi-parameter vital signs contracts that bundle infrared, thermocouple, and chemical dot technologies. This bundling displaces standalone mercury thermometer purchasing in US integrated delivery networks. The shift is most visible in Texas and Florida health systems where Catholic Health Initiatives and HCA Healthcare have implemented mercury-free campus policies.
Mercury Thermometer Market Segmentation
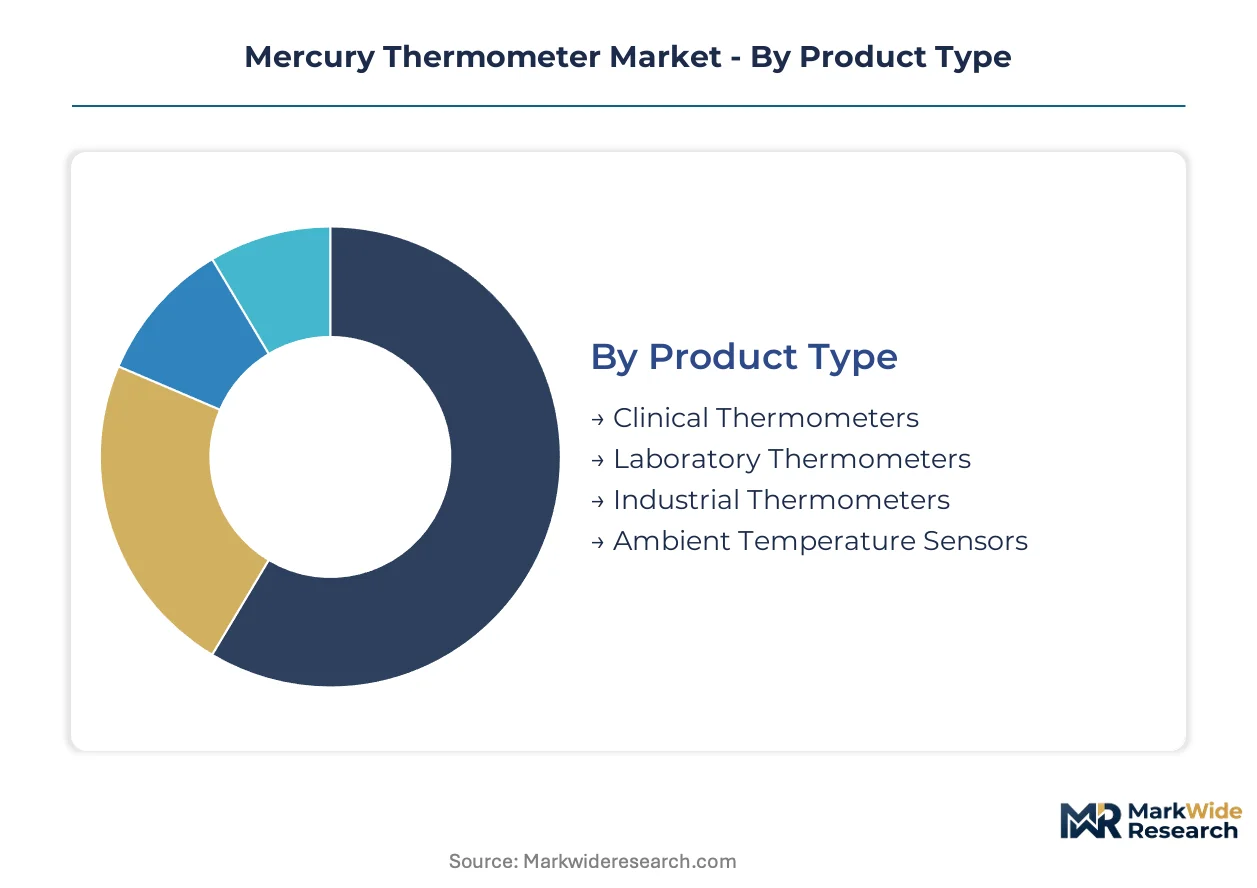
Segmentation in the mercury thermometer market reveals stark turnover disparities between legacy clinical instruments and specialized laboratory devices. Procurement cycles vary from months in acute care settings to decades in metrology reference installations, reshaping inventory strategies across manufacturer portfolios.
Product Type:
Replacement velocity diverges dramatically across this category, with clinical units cycling fastest due to breakage rates while laboratory instruments persist through multi-decade calibration chains.
- Clinical Thermometers:Precision-bored glass instruments with standardized 35-42°C ranges dominate maternal and pediatric screening across Rajasthan and Uttar Pradesh primary health centers. India's sub-$1 unit economics and zero battery dependency sustain residual procurement despite digital substitution pressure.
- Laboratory Thermometers:NIST-traceable reference-grade columns with 0.01°C resolution serve pharmaceutical stability testing in Japan and South Korea national metrology institutes. Hybrid mercury-digital data logging modules are compressing pure mercury demand to isolated calibration niches.
- Industrial Thermometers:Process measurement instruments face accelerated displacement from thermocouple alternatives in manufacturing environments.
- Ambient Temperature Sensors:Meteorological station deployments in Papua and Maluku provinces leverage mercury's thermal linearity where electrical infrastructure is unreliable.
Clinical Thermometers anchors the volume base while Ambient Temperature Sensors gains share at the steepest rate in electricity-constrained archipelago logistics.
End User:
Customer procurement sophistication spans from fragmented municipal health secretariats to centralized hospital group purchasing organizations, creating tiered pricing dynamics across account types.
- Hospitals:Acute care facilities in Texas and Florida integrated delivery networks face cradle-to-grave EPA tracking costs for mercury breakage, converting apparent unit savings into total-cost-of-ownership penalties. Catholic Health Initiatives and HCA Healthcare have implemented mercury-free campus policies.
- Clinics:Remote island clinics in Indonesia's Papua province lack reliable electricity, creating captive demand for passive thermal measurement instruments.
- Research Laboratories:ISO 17025-accredited temperature calibration facilities are shuttering mercury-based services, forcing cross-border instrument transport for recertification.
- Manufacturing Facilities:Industrial end-users face REACH and RoHS compliance burdens accelerating thermocouple migration.
Hospitals retain the largest installed base while Clinics demonstrates the most resilient replacement demand trajectory.
Application:
Use-case maturity varies from standardized vital signs capture to specialized environmental documentation, with regulatory documentation requirements determining instrument longevity.
- Patient Monitoring:Routine temperature capture in maternal screening programs across Bihar primary health centers prioritizes devices requiring no electrical infrastructure. Welch Allyn and Terumo infrared tympanic alternatives achieve sub-30-second readings with ±0.1°C accuracy.
- Scientific Research:Pharmaceutical stability testing protocols mandate thermal linearity documentation that hybrid mercury-digital systems now address.
- Equipment Testing:Calibration protocol persistence in German and Swiss metrology institutes sustains specialized procurement for NIST-traceable chains.
- Environmental Monitoring:Ambient sensing in Scandinavian hospital networks faces accelerated EU F-Gas Regulation and REACH annex XVII decommissioning timelines.
Patient Monitoring commands the widest deployment footprint while Environmental Monitoring contracts most sharply under regulatory pressure.
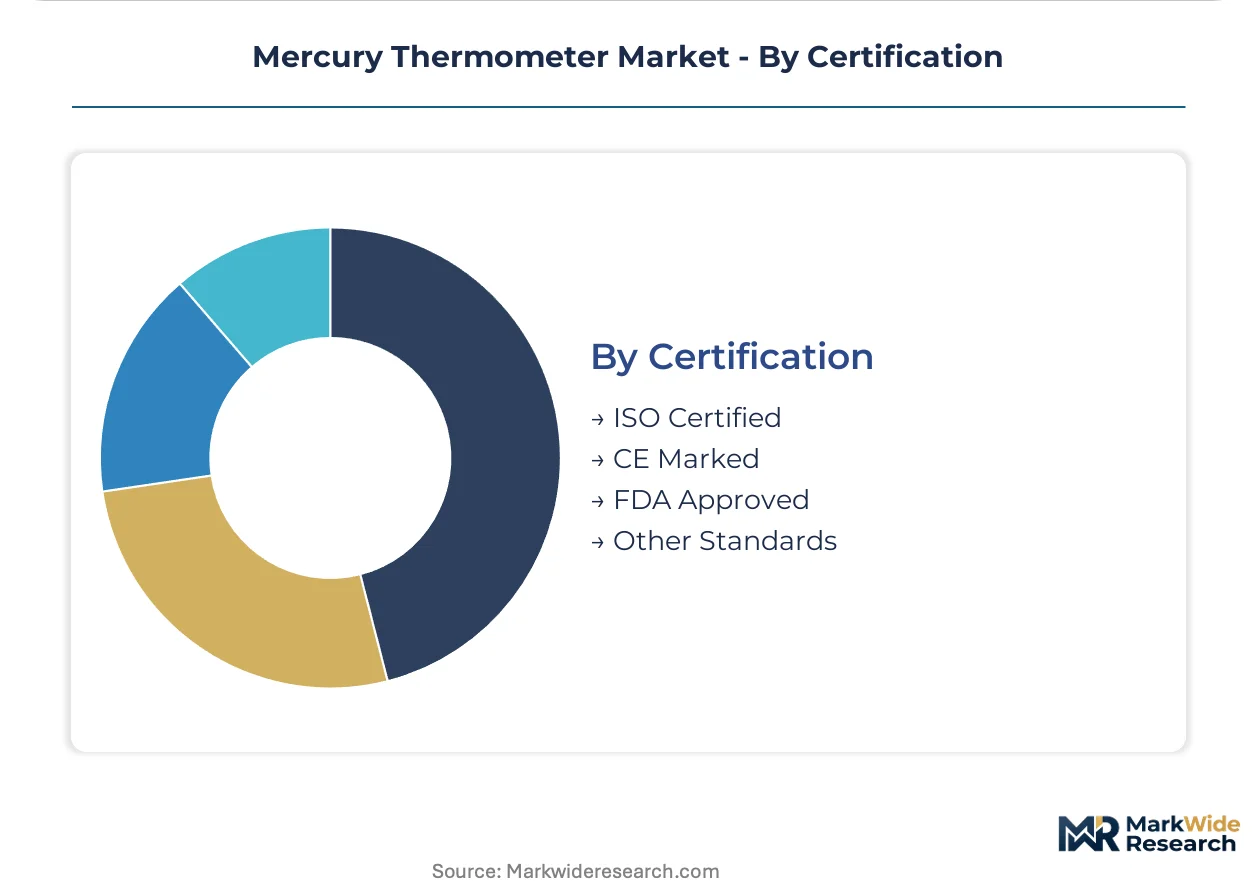
Certification:
Conformity assessment burdens fragment market access, with grandfathered legacy inventory holding temporary advantage over delayed digital certifications.
- ISO Certified:International standards compliance enables cross-border procurement for laboratory reference instruments in metrology institutes.
- CE Marked:EMA Medical Device Regulation grandfathering provisions extend commercial viability for existing mercury clinical thermometers through transitional windows.
- FDA Approved:Enforcement discretion shapes liquidation timelines and secondary market dynamics for US healthcare facility inventories.
- Other Standards:BIS compliance in India and ANVISA requirements in Brazil create jurisdiction-specific procurement channels outside harmonized frameworks.
CE Marked inventory carries the greatest near-term volume concentration while FDA Approved certifications face the most compressed residual demand horizon.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary health centers and municipal procurement offices concentrate residual mercury thermometer demand across developing economies with constrained healthcare infrastructure budgets. Calibration laboratories and metrology institutes sustain specialized procurement in industrialized nations where regulatory grandfathering preserves limited commercial windows.
India
Rajasthan, Uttar Pradesh, and Bihar primary health centers prioritize mercury thermometers for maternal and pediatric screening due to zero battery dependency and sub-dollar unit economics. The Bureau of Indian Standards maintains compliance pathways for clinical instruments while CDSCO oversees medical device quality frameworks. Glass thermometer fabrication clusters in Gujarat and Maharashtra supply domestic procurement channels serving rural healthcare infrastructure gaps.
Indonesia
Remote island clinics in Papua and Maluku provinces lack reliable electricity infrastructure, creating captive demand for passive thermal measurement instruments. The Ministry of Health operates decentralized procurement systems across the archipelago that sustain mercury device purchasing outside federal digitalization mandates. Manufacturing distribution centers in Jakarta and Surabaya coordinate logistics for healthcare facilities spanning seventeen thousand islands.
Brazil
Municipal health secretariats in Northeastern states operate outside federal SUS digitalization mandates, preserving decentralized mercury thermometer purchasing for routine patient monitoring. ANVISA maintains regulatory oversight of clinical instrument safety while grandfathering provisions extend market access for existing inventory. São Paulo-based medical supply distributors coordinate procurement fragmentation across regional healthcare networks with divergent budget capacities.
Germany
National metrology institutes and pharmaceutical stability testing laboratories sustain demand for NIST-traceable mercury reference thermometers where thermal linearity documentation remains mandatory. The EMA Medical Device Regulation imposes conformity assessment burdens while REACH annex XVII amendments accelerate hospital decommissioning timelines. Precision glassblowing craft clusters in Thuringia and Bavaria face artisan scarcity as apprenticeship pipelines collapse across Central European manufacturing bases.
United States
Texas and Florida integrated delivery networks face cradle-to-grave EPA tracking costs for mercury thermometer breakage, converting apparent unit savings into total-cost-of-ownership penalties. FDA enforcement discretion shapes liquidation timelines and secondary market dynamics for healthcare facility inventories. Catholic Health Initiatives and HCA Healthcare have implemented mercury-free campus policies across Southeastern and Southwestern hospital networks.
Mercury Thermometer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments where regulatory variance creates uneven competitive pressure. Hospital group purchasing organizations consolidate temperature measurement procurement into multi-parameter vital signs contracts that bundle alternative technologies. Three archetypes dominate: diversified medical device conglomerates with temperature management portfolios, precision glass instrument specialists serving calibration laboratory niches, and regional distributors exploiting logistics gaps in archipelago or rural healthcare systems. Competitive moves concentrate on portfolio diversification into infrared and semiconductor-based alternatives alongside geographic expansion into grandfathered regulatory windows.
Within the diversified conglomerate tier, Terumo Corporation and Welch Allyn exemplify channel control through hospital procurement relationships spanning conventional and electronic temperature platforms. Geratherm Medical AG represents the precision instrument specialist archetype, occupying a position sustained by European manufacturing infrastructure serving legacy clinical environments where calibration protocol persistence preserves residual demand. These three entities anchor the competitive structure while smaller regional distributors exploit municipal procurement fragmentation in Brazil's Northeastern states and Indonesia's outer island provinces.
| Leading Market Players |
|---|
| Geratherm Medical AG |
| Terumo Corporation |
| Medline Industries |
| Thermo Fisher Scientific |
| Microlife Corporation |
| Omron Healthcare |
| 3M |
| Welch Allyn |
| Medtronic |
| Others |
Value Network & Pricing Analysis
Elemental mercury export quota volatility from Kyrgyzstan and Algeria determines both pricing tier spreads and supply chain shape, compressing margins on economy-grade clinical instruments while concentrating premium laboratory-grade production in vertically integrated European glassblowing clusters.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate raw material procurement, with three-tier pricing structure across premium, standard, and economy levels separating NIST-traceable laboratory instruments from clinical units and disposable pediatric screening devices. Price differentiation rests on certification grade and volume scale, with ISO 17025-accredited reference thermometers commanding substantial premiums over BIS-compliant clinical units. Cost compression in the economy tier is intensifying because Indian primary health centers face fixed reimbursement ceilings under national health mission programs. Municipal health secretariats in Brazil's Northeastern states exhibit the highest price sensitivity, while German pharmaceutical stability testing laboratories demonstrate the least.
Supply Chain Analysis
Contract manufacturing concentrates in Thuringia and Bavaria precision glassblowing craft clusters, with secondary fabrication capacity in Gujarat and Maharashtra serving domestic Indian procurement channels. The supply chain draws from elemental mercury refining in Kyrgyzstan and Algeria, precision-bored borosilicate glass from Czech manufacturing bases, and calibrated capillary tubing from Italian artisan workshops. Single-source vulnerability in elemental mercury feedstock exposes manufacturers to export quota interruptions. Distribution runs through São Paulo-based medical supply distributors in Brazil, Jakarta and Surabaya coordination centers in Indonesia, and hospital group purchasing organizations in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is undergoing a cyclical recovery driven by grandfathered regulatory windows extending commercial viability for legacy inventory holders ahead of full Minamata Convention phase-down implementation.
For Market Incumbents: Pre-empt digital substitution pressure by accelerating portfolio diversification into infrared and semiconductor-based temperature management platforms while defending residual mercury instrument margins through CE marking MDR gap exploitation. Secure backward integration into precision glassblowing craft capacity in Central European manufacturing clusters before artisan scarcity intensifies. Channel control through hospital procurement relationships remains the critical defensive lever.
For New Entrants and Emerging Players: Build out specialized calibration laboratory service offerings targeting ISO 17025-accredited facilities facing cross-border recertification burdens as domestic mercury-based services shutter. Indonesia's Papua and Maluku provinces present the most penetrable geography given electricity infrastructure gaps and decentralized Ministry of Health procurement systems. A direct distribution partnership with Jakarta-based logistics coordinators offers the strongest go-to-market angle.
For Investors and Strategic Acquirers: EMA Medical Device Regulation transitional provisions reshapes the acquisition landscape by compressing residual demand windows for grandfathered mercury device inventory holders. Long-term viability favors precision instrument specialists with diversified temperature management portfolios spanning both legacy and electronic platforms. Monitor FDA enforcement discretion announcements as the critical inflection signal indicating secondary market liquidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Grandfathered provisions extend market access for legacy mercury clinical thermometers ahead of MDR full implementation. |
| Backward Integration | Captive precision glassblowing capacity in Thuringia insulates against artisan scarcity collapsing apprenticeship pipelines. |
| Hospital System Partnership | Multi-parameter vital signs bundling contracts displace standalone mercury thermometer purchasing in US integrated delivery networks. |
| Geographic Expansion | Indonesia's archipelago logistics gaps and electricity constraints sustain captive demand for passive thermal measurement instruments. |
| Product Portfolio Diversification | Infrared tympanic platforms with sub-30-second readings address acute care substitution pressure from Welch Allyn and Terumo. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement managers, biomedical engineers in calibration laboratories, municipal health secretariat officials, and precision glass instrument manufacturers. Secondary validation drew from FDA enforcement discretion memoranda, EMA Medical Device Regulation transitional provisions documentation, Minamata Convention national implementation reports, and Bureau of Indian Standards compliance filings. Bottom-up patient monitoring device shipment data was triangulated against top-down healthcare infrastructure budget allocations across priority states.
Calibration against historical regulatory phase-down patterns in comparable medical device categories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed product type, end user sophistication tier, application protocol requirements, and certification jurisdiction cluster. CAGRs were derived from installed base erosion rates and replacement cycle compression in acute care settings versus metrology reference installation persistence. Forecast inputs incorporated mercury refining capacity utilization and notified body certification backlog estimates.
Stress conditions across elemental mercury export quota interruptions, EMA MDR enforcement acceleration, and digital thermometer price parity achievement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding grandfathering provision durations and healthcare infrastructure budget trajectories. Quarterly review of FDA enforcement discretion announcements, REACH annex XVII amendment timelines, and ISO 17025 laboratory accreditation status is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Defibrillator Analyzers Market
Medical Equipment
Europe Nuclear Medicine Equipment Market
Medical Equipment
Durable Medical Equipment Rental Market
Medical Equipment
Clinical Microscopes Market
Medical Equipment
North America Durable Medical Equipment Market
Medical Equipment
Hospital-at-Home Equipment Rental Market
Medical Equipment
Automated Dialysis Concentrated Production Systems Market
Medical Equipment
Autopsy Saw Market
Medical Equipment
Cath Lab Market
Medical Equipment
Radiotherapy Motion Management Market
Medical Equipment
Global Medical Equipment Calibration Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
Birthing Beds Market
Medical Equipment
Global Surgical Lights Market
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
South Africa Radiotherapy Market