
 US Medical Carts Market | 2026-2036
US Medical Carts Market Size, Share, and Industry Trends Forecast 2026-2036
US Medical Carts Market Intelligence
The Hospital Sustainability Purchasing Consortium's vendor environmental scorecard is pivoting procurement criteria toward antimicrobial coatings and recyclable aluminum chassis. Medline Industries leverages its domestic manufacturing footprint to sustain rapid fulfillment for integrated delivery networks. Ergontronicompetes on ergonomic adjustability standards that reduce clinician injury claims. Capsa Healthcare anchors its position through specialized medication cart configurations that dominate hospital pharmacy automation partnerships.
US medical carts are mobile workstation platforms, typically constructed from steel or aluminum framing with polymer work surfaces, designed to transport medical supplies, electronic health records hardware, and pharmaceutical inventory within clinical environments. These units incorporate casters rated for hospital floor surfaces, integrated power systems for device charging, and configurable drawer configurations to satisfy specific department workflows. Medication carts command the largest revenue share due to controlled-substance security requirements and barcode medication administration integration, while procedure carts represent the fastest-expanding category as ambulatory surgical centers proliferate. Steel remains the dominant material selection for its durability and load capacity, though aluminum gains preference where weight reduction and corrosion resistance justify premium positioning.
FDA Center for Devices and Radiological Health oversight applies to carts incorporating powered medical devices or battery systems, while Joint Commission National Patient Safety Goals mandate specific cart configurations for emergency medication accessibility. OSHA ergonomic guidelines influence caster specification and work-surface height ranges to reduce musculoskeletal disorders among nursing staff. Stakeholders must monitor evolving CMS reimbursement policies for remote patient monitoring, as these programs directly determine whether health systems invest in telehealth-enabled cart fleets or maintain conventional non-powered configurations.
Market Dynamics
Point-of-care computing mandates from hospital systems are compressing cart replacement cycles, forcing suppliers to prioritize battery longevity and EHR hardware compatibility over chassis durability alone.
Growth Catalysts
- Joint Commission infection control standards:Antimicrobial coating requirements are expanding cart upgrade budgets across acute care facilities. Facilities must demonstrate compliance during accreditation surveys.
- Barcode medication administration integration:Hospital pharmacy automation partnerships are standardizing cart drawer configurations and electronic lock specifications. This drives fleet standardization among integrated delivery networks.
- Southeast hospital system consolidation:Regional health system mergers are creating centralized procurement offices with authority to mandate single-vendor cart fleets across multiple campuses.
Market Restraints
- Aluminum price volatility:Lightweight chassis demand exposes manufacturers to London Metal Exchange pricing swings. Steel alternatives sacrifice weight targets required for clinician ergonomics.
- FDA 510(k) pathway complexity:Powered cart submissions incorporating battery systems face extended review timelines. Smaller manufacturers lack regulatory affairs capacity to navigate premarket notification requirements.
- Fixed wireless infrastructure gaps:Rural hospital Wi-Fi dead zones limit telehealth-enabled cart deployment. These facilities default to non-powered configurations despite reimbursement pressure.
Strategic Opportunities
- CMS remote patient monitoring reimbursement expansion:Medicare billing code updates create capital budget justification for telehealth cart fleets. Health systems in the Midwest are piloting RPM-integrated configurations.
- Ambulatory surgical center proliferation:Procedure cart demand concentrates in outpatient settings with distinct workflow requirements from acute care. Specialized anesthesia and endoscopy configurations remain underserved.
- Battery chemistry convergence:Lithium iron phosphate systems meeting hospital fire safety codes are displacing sealed lead-acid in premium segments. This enables extended runtime without thermal management penalties.
Industry Challenges
- Biomedical engineering talent scarcity:Hospital systems lack staff to maintain cart power systems and caster assemblies. Deferred maintenance accelerates fleet replacement costs.
- EHR platform fragmentation:Cart mounting hardware must accommodate multiple monitor sizes and computing form factors across Cerner, Epic, and MEDITECH environments. Customization erodes manufacturing scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Medical Carts Market |
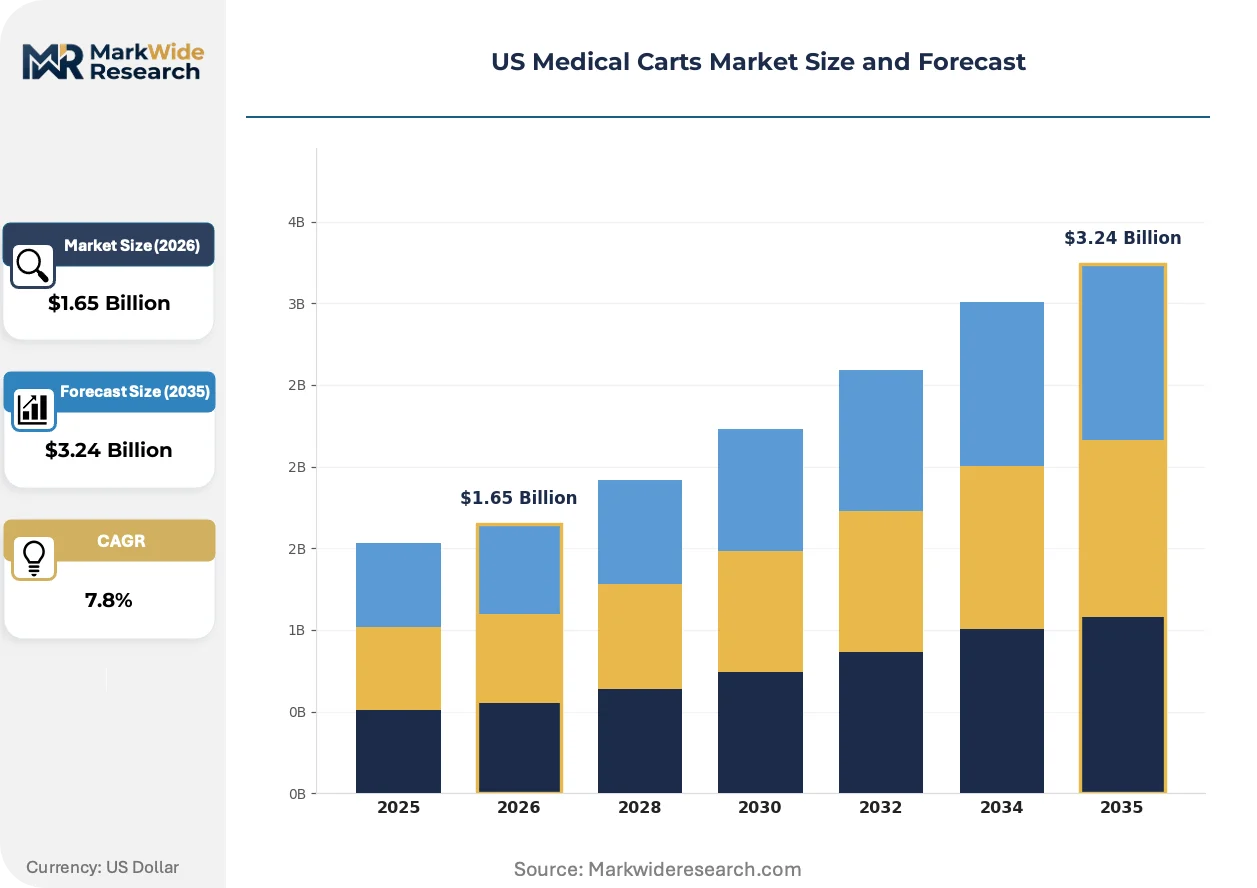
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.24 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication Carts, Procedure Carts, Emergency Carts, Anesthesia Carts End User: Hospitals, Clinics, Long-Term Care Facilities, Research Institutions Material: Steel, Aluminum, Plastic, Wood Application: Patient Care, Surgical Assistance, Inventory Management, Transport |
| Companies Covered | Medline Industries, Ergotron, Capsa Healthcare, Midmark Corporation, The Harloff Company, Waterloo Healthcare, AFC Industries, Enovate Medical, TouchPoint Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Medical Carts Market Strategic Shifts & Innovations
Workflow automation is compressing the physical distance between medication storage and patient bedside, reshaping cart architecture around real-time inventory tracking and nurse station bypass.
Hot-swappable battery architectures are decentralizing cart charging infrastructure across hospital floors. Nursing units in tertiary care centers are eliminating central battery rooms in favor of distributed charging stations. This shift reduces cart downtime during shift changes and enables continuous point-of-care availability without tethering to wall outlets.
OSHA ergonomic guidelines are mandating adjustable-height work surfaces and anti-fatigue caster specifications. Hospital risk management departments are incorporating these standards into vendor scorecards alongside infection control criteria. Facilities in California and Massachusetts are requiring documented musculoskeletal disorder reduction plans as a condition of cart fleet approval.
Consolidated procurement through group purchasing organizations is compressing vendor margins while standardizing specifications across member hospitals. Regional GPOs in the Southeast are issuing sole-source contracts for medication cart categories, displacing multi-vendor environments. Supplier qualification now requires demonstration of domestic manufacturing capacity and 48-hour fulfillment guarantees for replacement components.
US Medical Carts Market Segmentation
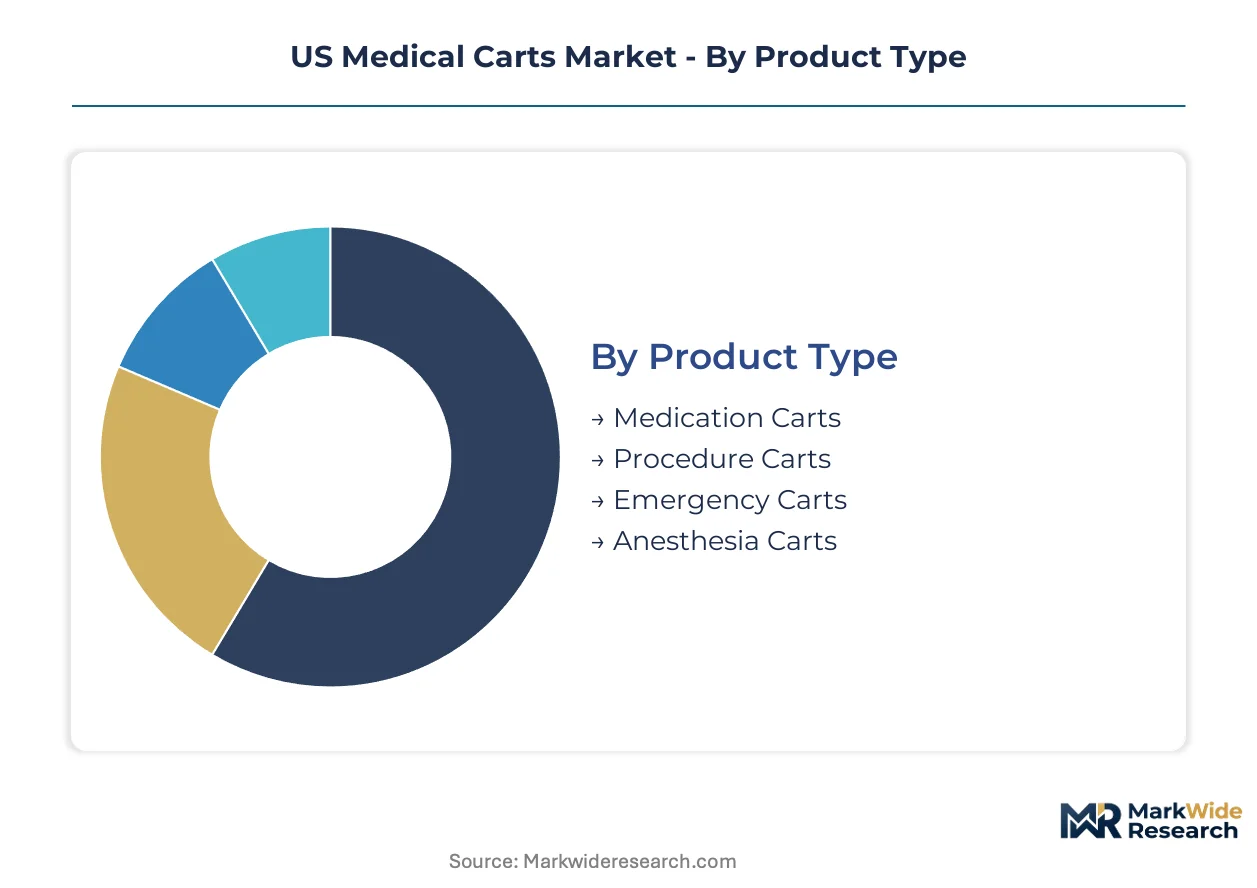
US medical carts segment across four critical dimensions that determine regulatory exposure, procurement patterns, and replacement cycles. Product type and material selection drive FDA oversight intensity, while end-user concentration shapes fleet standardization pressures across integrated delivery networks.
Product Type:
FDA 510(k) requirements and Joint Commission accreditation standards vary sharply across cart categories, with medication and emergency configurations facing the most stringent premarket notification burdens.
- Medication Carts:These units integrate controlled-substance security drawers, barcode medication administration hardware, and electronic locking systems compliant with DEA Schedule II-V storage requirements. Demand concentrates in acute care hospitals across the Midwest, where pharmacy automation partnerships are mandating standardized drawer configurations across multi-campus systems.
- Procedure Carts:Configured for specific clinical workflows including anesthesia delivery, endoscopy support, and minor surgical instrumentation. Ambulatory surgical centers in the Southeast are driving fastest expansion as outpatient procedural volume shifts away from inpatient settings.
- Emergency Carts:Crash carts engineered for rapid defibrillator access, emergency medication organization, and ACLS protocol compliance. These configurations face mandatory inspection cycles under Joint Commission National Patient Safety Goals.
- Anesthesia Carts:Specialized units with gas cylinder storage, vaporizer mounting, and suction system integration. Demand clusters in tertiary care centers with high surgical throughput.
Leading the category by volume: Medication Carts. Growing fastest: Procedure Carts.
End User:
Procurement authority and fleet replacement budgets diverge dramatically across care settings, with hospitals wielding capital for enterprise-wide standardization while smaller facilities prioritize unit-level acquisition.
- Hospitals:Acute care facilities command the dominant share of cart procurement, with centralized materials management offices driving sole-source vendor contracts. These buyers specify antimicrobial coatings, hot-swappable battery systems, and EHR-integrated mounting hardware as baseline requirements.
- Clinics:Outpatient and primary care settings favor lightweight aluminum configurations for clinician mobility between examination rooms. Budget constraints limit adoption of powered systems despite point-of-care computing mandates.
- Long-Term Care Facilities:Skilled nursing and assisted living operators prioritize medication management carts with simplified electronic lock interfaces for non-licensed staff. OSHA ergonomic guidelines influence caster and height-adjustment specifications to reduce injury claims among aging caregiver workforces.
- Research Institutions:Academic medical centers and clinical trial sites require specialized transport configurations for biological specimen handling and investigational drug storage. These segments operate outside standard hospital procurement channels.
Hospitals capture the greatest procurement volume. Clinics are expanding most quickly as outpatient migration accelerates.
Material:
Material selection trades off durability, weight, infection control compliance, and exposure to commodity price volatility.
- Steel:Cold-rolled carbon steel dominates chassis construction for load-bearing capacity and impact resistance. Hospital systems in the Southeast specify powder-coated steel for emergency and medication cart fleets subject to intensive daily use.
- Aluminum:Extruded aluminum alloys gain preference in procedure cart segments where corrosion resistance and weight reduction justify premium positioning. London Metal Exchange pricing volatility constrains margin stability for manufacturers.
- Plastic:High-density polymer work surfaces and drawer assemblies reduce surface bioburden in infection-sensitive environments. These components complement rather than replace metal framing.
- Wood:Limited to aesthetic applications in administrative or patient-facing non-clinical settings. Healthcare-grade laminates satisfy Joint Commission surface disinfection requirements where wood appears.
Steel commands the highest procurement volume. Aluminum demonstrates the steepest expansion trajectory among premium segments.
Application:
Workflow integration requirements determine cart architecture, with patient-facing applications demanding the most sophisticated power and computing integration.
- Patient Care:Bedside medication administration and vital signs documentation drive demand for powered carts with integrated battery systems and monitor mounting. These configurations face FDA oversight when incorporating powered medical devices.
- Surgical Assistance:Operating room and procedure suite applications require sterile field compatibility, anesthesia gas management, and rapid instrument accessibility. Specialized configurations resist standardization across surgical service lines.
- Inventory Management:Supply chain and pharmacy operations utilize non-powered transport carts for bulk material movement. These segments prioritize caster durability and drawer capacity over electronic integration.
- Transport:Specimen, pharmaceutical, and equipment movement between departments relies on basic platform carts with minimal configuration. Demand concentrates in large tertiary facilities with distributed campus layouts.
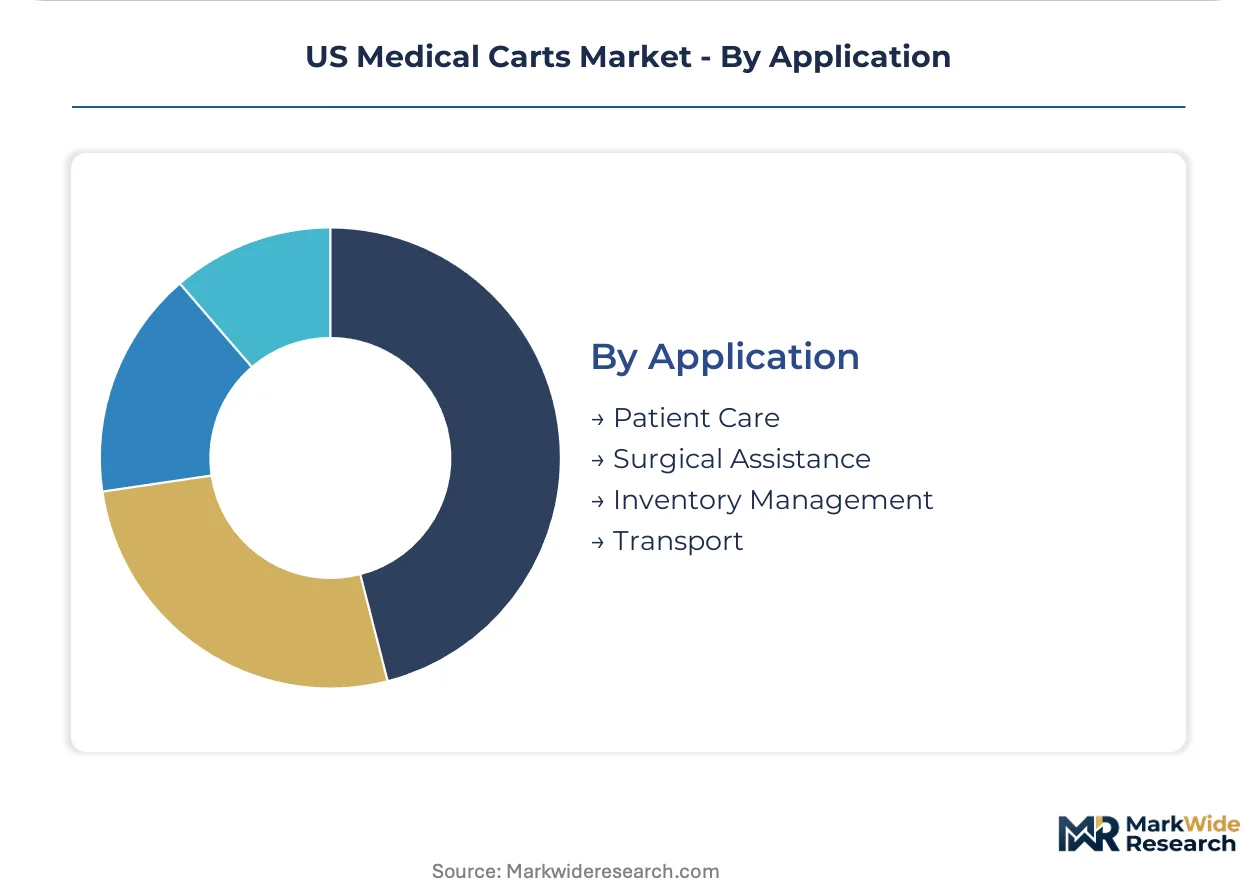
Patient Care leads procurement volume. Surgical Assistance is gaining share fastest as ambulatory procedural volume expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors US medical cart procurement concentration through its dense cluster of integrated delivery network headquarters and medical device distribution infrastructure serving the Midwest hospital corridor.
Southeast
Hospital system consolidation across Florida, Georgia, and the Carolinas is centralizing procurement authority through regional materials management offices. Joint Commission infection control surveys in this region are elevating antimicrobial coating specifications in vendor scorecards. Atlanta-based distribution centers are expanding 48-hour fulfillment guarantees for replacement caster and battery components.
Midwest
Pharmacy automation partnerships in Ohio, Illinois, and Michigan are mandating standardized medication cart drawer configurations across multi-campus health systems. OSHA ergonomic guidelines influence procurement criteria for adjustable-height work surfaces in Illinois and Wisconsin facilities. Cleveland Clinic and Mayo Clinic procurement offices are piloting hot-swappable battery architectures for point-of-care computing fleets.
Texas and Southwest
Ambulatory surgical center proliferation in Dallas-Fort Worth and Houston is accelerating demand for procedure cart configurations distinct from acute care specifications. Rural hospital Wi-Fi infrastructure gaps in West Texas limit telehealth-enabled cart deployment. San Antonio health systems are defaulting to non-powered configurations despite CMS remote patient monitoring reimbursement pressure.
California
OSHA ergonomic mandates and musculoskeletal disorder reduction plans are required conditions for cart fleet approval in Los Angeles and San Francisco Bay Area facilities. The Hospital Sustainability Purchasing Consortium's environmental scorecard is pivoting procurement toward recyclable aluminum chassis and antimicrobial coatings. Stanford Health Care and Kaiser Permanente are standardizing vendor qualification around domestic manufacturing capacity.
Northeast Corridor
Academic medical centers in Boston and New York are driving specialized transport configurations for biological specimen handling and investigational drug storage. EHR platform fragmentation across Epic, Cerner, and MEDITECH environments complicates cart mounting hardware standardization. Philadelphia and Baltimore hospital systems are consolidating procurement through regional group purchasing organizations with sole-source contract authority.
US Medical Carts Market Key Industry Players
Premium-margin players sit above commodity-margin players across battery system integration and EHR compatibility certification. The vendor base clusters around three strategic archetypes: integrated delivery network suppliers with domestic manufacturing footprints, ergonomic specialists emphasizing OSHA compliance differentiation, and pharmacy automation partners with controlled-substance security expertise. Consolidated procurement through group purchasing organizations is compressing margins while accelerating M&A activity among mid-tier fabricators. Strategic partnerships between cart manufacturers and EHR platform vendors are emerging as a dominant competitive move to lock in fleet standardization.
Among domestic manufacturers, Medline Industries, Ergotron, and Capsa Healthcare anchor the competitive structure. Medline Industries exemplifies the integrated delivery network supplier archetype through its rapid fulfillment infrastructure. Ergotron occupies a position within the ergonomic specialization tier, with its company name signaling adjustability-focused positioning. Capsa Healthcare represents the pharmacy automation partnership model, anchoring its market presence through medication cart configuration expertise. These three entities collectively illustrate how vendor qualification now requires simultaneous demonstration of infection control compliance, ergonomic certification, and 48-hour component replacement guarantees.
| Leading Market Players |
|---|
| Medline Industries |
| Ergotron |
| Capsa Healthcare |
| Midmark Corporation |
| The Harloff Company |
| Waterloo Healthcare |
| AFC Industries |
| Enovate Medical |
| TouchPoint Medical |
| Others |
Cost & Logistics Intelligence
London Metal Exchange aluminum pricing cascades through chassis fabrication costs into three-tier pricing structure across premium, standard, and economy levels for US medical cart procurement. Midwest hospital systems absorbing volatile lightweight material premiums compress margins for manufacturers lacking steel alternatives, while Southeast consolidated procurement offices exploit volume scale to lock in fixed-price multi-year contracts.
Pricing Analysis
Clinician injury claim reduction value anchors premium positioning for ergonomic configurations in California and Massachusetts facilities. Price differentiation separates FDA 510(k)-cleared powered systems with lithium iron phosphate batteries from non-powered economy tiers, with antimicrobial coating certification adding a mid-tier bracket. Cost compression in standard segments intensifies because group purchasing organizations centralize sole-source contracting authority. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraint, while academic medical centers demonstrate lowest sensitivity where investigational drug handling requirements mandate specialized configurations.
Supply Chain Analysis
Regional distribution centers in Chicago, Atlanta, and Dallas-Fort Worth anchor hub-and-spoke fulfillment networks serving hospital system clusters. Domestic manufacturing concentrates in the Midwest and Southeast, with aluminum extrusion and steel fabrication drawing from Ohio, Illinois, and Georgia production bases. Supply chain risk centers on London Metal Exchange pricing volatility for lightweight chassis materials and single-source vulnerability for lithium iron phosphate battery cells. Distribution runs through integrated delivery network materials management offices with 48-hour replacement component guarantees as the dominant downstream structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into battery system assembly and EHR platform certification represents the critical vertical-integration race as powered cart demand accelerates. Manufacturers capturing upstream cell supply and downstream software compatibility locks secure procurement preference in consolidated hospital system contracting.
For Market Incumbents: To counter group purchasing organization margin compression, Medline Industries and Capsa Healthcare should deepen captive supply of lithium iron phosphate battery architectures and secure exclusive EHR platform integration agreements with Epic and Cerner. Capacity addition in domestic aluminum extrusion facilities near Chicago and Atlanta reduces exposure to London Metal Exchange volatility while satisfying Hospital Sustainability Purchasing Consortium domestic manufacturing requirements. For New Entrants and Emerging Players: Ambulatory surgical center procedure cart specialization offers the most penetrable white-space target, with anesthesia and endoscopy configurations underserved by acute-care-focused incumbents. A go-to-market angle emphasizing rapid 48-hour fulfillment guarantees for replacement casters and battery components bypasses entrenched GPO relationships in the Southeast. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier ergonomic specialists in California and Texas facing OSHA compliance cost pressure but holding FDA 510(k) clearance assets. Long-term viability over a five-to-ten-year window hinges on telehealth-enabled cart fleet adoption as CMS remote patient monitoring reimbursement expands. The signal to watch is Midwest health system pilot conversion rates for RPM-integrated configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Footprint Expansion | Chicago and Atlanta facilities satisfy Hospital Sustainability Purchasing Consortium vendor qualification requirements. |
| Hot-Swappable Battery Architecture Development | Lithium iron phosphate systems meeting hospital fire safety codes displace sealed lead-acid in premium segments. |
| EHR Platform Integration Partnership | Epic and Cerner compatibility certification locks in fleet standardization across integrated delivery networks. |
| Antimicrobial Coating Certification Investment | Joint Commission infection control compliance elevates vendor scorecard positioning in Southeast accreditation surveys. |
| Ambulatory Surgical Center Specialized Configuration | Anesthesia and endoscopy cart designs capture outpatient procedural volume shifting from inpatient settings. |
Research Approach
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare reimbursement filings underwrites the qualitative findings in this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and cart fleet maintenance directors combined with secondary validation from FDA 510(k) premarket notification databases, Joint Commission accreditation survey records, and OSHA ergonomic guideline documentation. Bottom-up shipment data from domestic manufacturers and top-down health system capital expenditure tracking triangulate market sizing across product type, material, end user, and application dimensions.
Rate-of-change decomposition separates volume expansion from price movement effects across the projection horizon. The analytical framework models segmentation across medication cart, procedure cart, emergency cart, and anesthesia cart categories; steel, aluminum, plastic, and wood materials; hospital, clinic, long-term care facility, and research institution end users; and patient care, surgical assistance, inventory management, and transport applications. CAGRs derive from regression analysis of replacement cycle compression, point-of-care computing mandate penetration, and ambulatory surgical center facility growth. Industry-specific forecast inputs incorporate EHR hardware refresh timelines and pharmacy automation partnership standardization rates.
Caveats apply where FDA 510(k) review timeline extensions, aluminum price spike persistence, or rural hospital Wi-Fi infrastructure investment delays could materially shift the outlook. Forecasts reflect documented assumptions regarding reimbursement policy continuity and health system consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
Benchtop Platelet Agitator Market
Medical Equipment
India Massage Equipment Market
Medical Equipment
Global Blood Viscometer Market
Medical Equipment
X-Ray Machine Manufacturing Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
Hospital-at-Home Equipment Rental Market
Medical Equipment
MRI Transport Market
Medical Equipment
Diathermy Equipment Market
Medical Equipment
Bone Marrow Processing Systems Market
Medical Equipment
Global Medical Equipment Cooling Market
Medical Equipment
Global Medical Device Reprocessing Market
Medical Equipment
Global Oxygen Flow Meters Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
Medical Device and Equipment Tags Market
Medical Equipment
Europe Medical Carts Market