
 Medical Equipment Reimbursement Market | 2026-2036
Medical Equipment Reimbursement Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Equipment Reimbursement Market Foresight
HCPCS Level II coding certification is reorganizing competitive access across the reimbursement landscape, forcing payers to demonstrate precise equipment categorization or forfeit claims processing contracts. UnitedHealth Group leverages its Optum analytics arm to pre-validate device eligibility before submission. Cigna Healthcare anchors its position through direct contracts with orthopedic device manufacturers, streamlining prior authorization workflows. Humana competes aggressively in Medicare Advantage segments where supplemental benefits cover durable medical equipment.
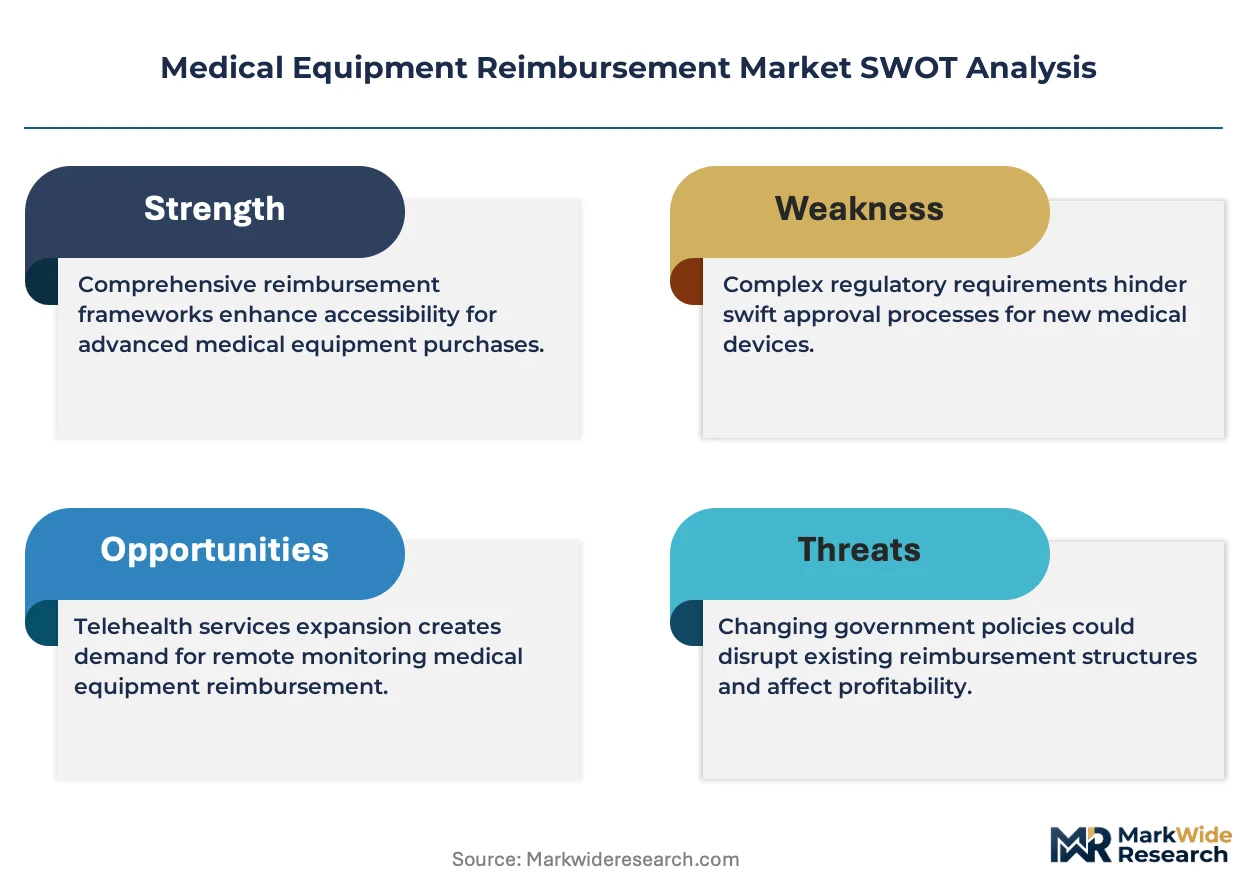
Medical equipment reimbursement encompasses the financial mechanisms through which insurers, government programs, and managed care organizations compensate providers for prescribed devices, typically governed by fee schedules that assign standardized payment values to thousands of distinct product codes. The process requires clinical documentation, prior authorization protocols, and post-payment audit trails to verify medical necessity and prevent fraud. Diagnostic equipment claims dominate transaction volumes due to imaging modality proliferation, while value-based care reimbursement models are expanding fastest as risk-sharing arrangements replace fee-for-service structures. Monitoring systems generate concentrated margin pools for payers who successfully integrate remote data streams into population health management programs.
The Centers for Medicare & Medicaid Services sets national coverage determination thresholds that directly shape manufacturer R&D priorities and provider purchasing patterns. FDA breakthrough device designation creates parallel reimbursement pathways through Medicare's transitional coverage framework, accelerating patient access but complicating actuarial risk assessment. Private payers must also navigate state insurance commissioner mandates that vary in prior authorization stringency and appeals timelines. Stakeholders should track evolving interoperability standards between electronic health records and payer claims systems, as seamless data exchange will determine which reimbursement platforms capture provider loyalty.
Market Dynamics
HCPCS Level II coding reorganization is compressing competitive access across the reimbursement landscape, forcing payers to demonstrate precise equipment categorization or forfeit claims processing contracts entirely.
Growth Catalysts
- Medicare reimbursement rule changes:CMS value-based care transitions accelerate risk-sharing arrangements that replace fee-for-service structures across United States provider networks.
- Remote patient monitoring platforms:Hospital systems expand coverage for connected diagnostic devices that stream real-time data into population health management programs.
- Germany's statutory health insurance modernization:Digital claims processing upgrades concentrate demand for automated prior authorization workflows in Western Europe's largest equipment market.
Market Restraints
- Prior authorization stringency variance:United States state insurance commissioner mandates create compliance fragmentation that complicates multi-state payer operations.
- Actuarial risk assessment complexity:FDA breakthrough device designation pathways accelerate patient access but destabilize traditional reimbursement modeling frameworks.
- Legacy EHR interoperability gaps:Electronic health record system incompatibility with payer claims platforms forces expensive custom integration projects.
Strategic Opportunities
- Transitional coverage framework expansion:Medicare's parallel reimbursement pathways for breakthrough devices create first-mover advantage for manufacturers with FDA designations.
- Remote data stream integration:Monitoring systems generate concentrated margin pools for payers who successfully embed continuous glucose monitors and cardiac event recorders into chronic disease management contracts.
- Direct manufacturer contracting:Orthopedic device makers seek streamlined prior authorization partnerships that bypass traditional distributor markup layers.
Industry Challenges
- Clinical documentation specialist shortages:Medical necessity verification requires trained coders who can navigate HCPCS Level II granularity and audit trail requirements.
- Post-payment audit defense costs:Fraud prevention protocols demand dedicated compliance infrastructure that strains mid-cap payer operating margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Equipment Reimbursement Market |
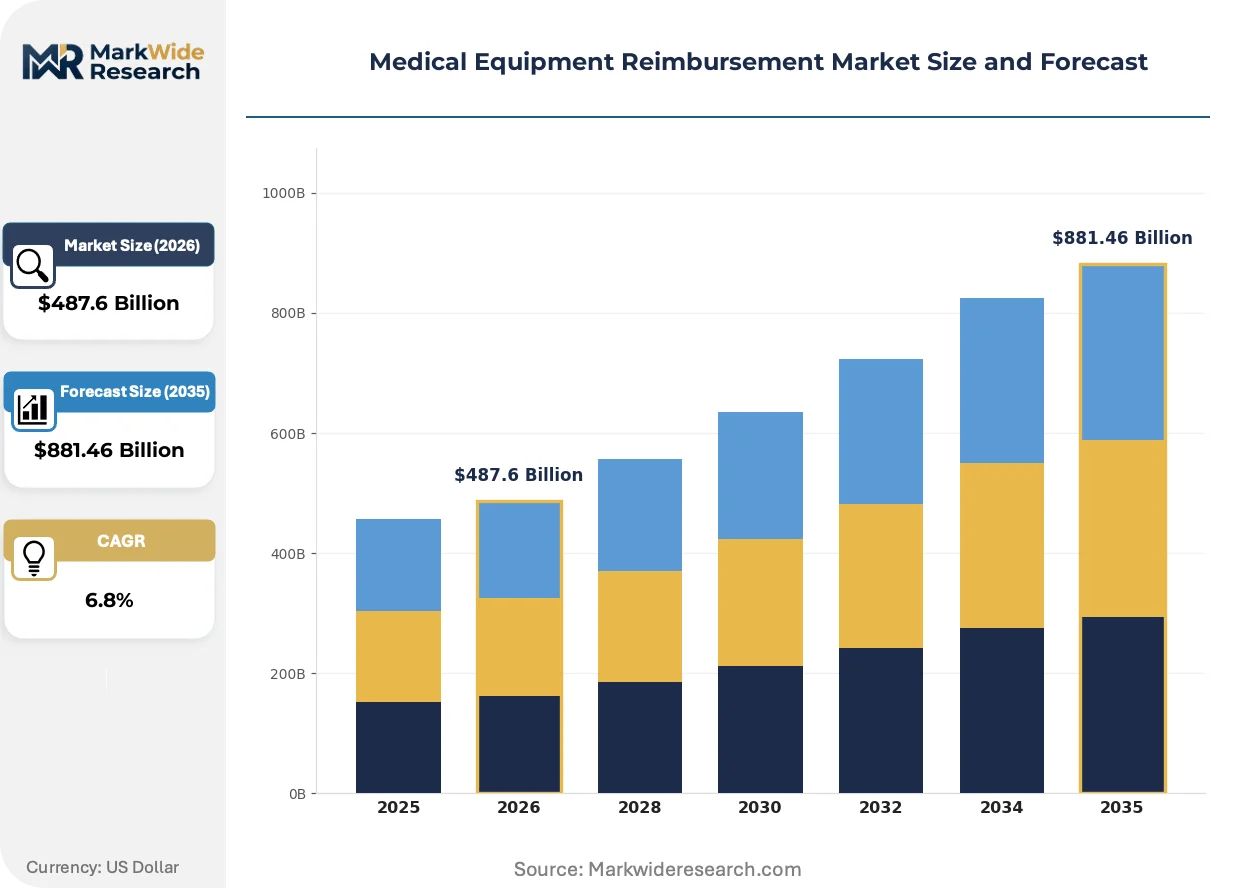
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Equipment, Surgical Instruments, Orthopedic Devices, Monitoring Systems End User: Hospitals, Clinics, Ambulatory Surgical Centers, Homecare Providers Reimbursement Model: Fee-for-Service, Capitation, Value-Based Care, Bundled Payments Technology: Telehealth Solutions, Wearable Devices, IoMT, Robotic Surgery Systems |
| Companies Covered | UnitedHealth Group, Cigna Healthcare, Humana, Aetna, Allianz, Anthem Insurance Companies, CVS Health, WellCare Health Plans, BNP Paribas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Equipment Reimbursement Market Shifts & Advancements
Reimbursement platforms are racing to embed real-time clinical data streams into automated claims adjudication, compressing the gap between device deployment and payment settlement.
Continuous glucose monitoring technology is miniaturizing sensor form factors while expanding metabolic data capture beyond diabetes into prediabetes and wellness segments. Medicare Advantage plans are adopting these devices at accelerating pace for supplemental benefit differentiation. The technology is miniaturizing hardware costs while amplifying software analytics value, shifting reimbursement toward per-patient-per-month capitation models.
REACH regulation compliance requirements in Europe are forcing medical device manufacturers to disclose full material composition for reimbursement eligibility. ECHA substance restrictions cascade into payer coverage determinations that exclude devices containing SVHC-listed components. Diagnostic imaging equipment with rare earth magnet dependencies faces concentrated exposure in German and French hospital procurement.
Hospital procurement departments are consolidating vendor relationships around integrated device-plus-reimbursement service bundles that unbundle traditional distributor roles. IDN-owned specialty pharmacies are capturing durable medical equipment dispensing that previously flowed through independent DME suppliers. This concentration is most visible in United States metropolitan health systems with captive Medicare Advantage plans.
Medical Equipment Reimbursement Market Segmentation
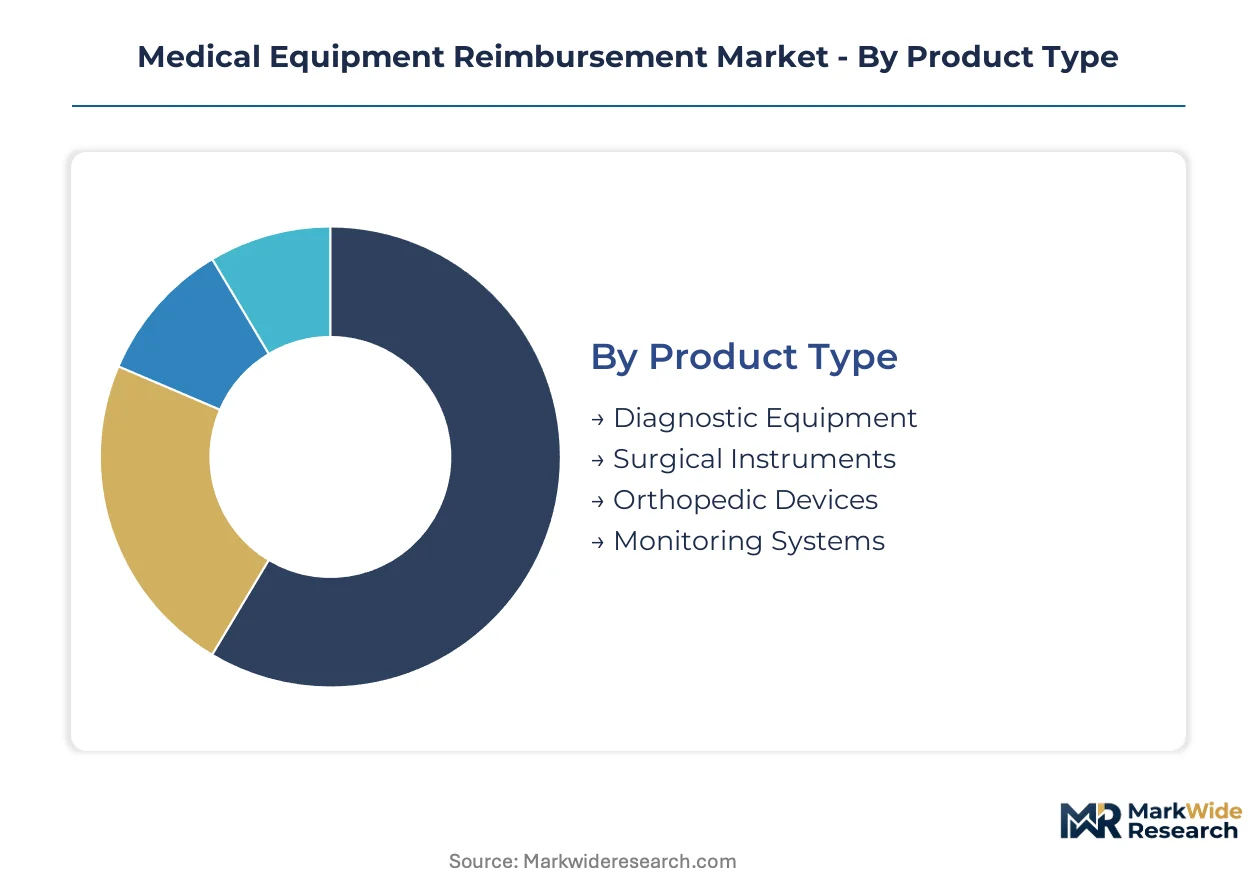
Reimbursement complexity varies sharply across equipment categories, with coding granularity determining which segments capture margin and which face commoditization pressure from substitute technologies. Payer coverage policies diverge most where clinical outcomes data remains thin, creating segmentation fault lines that reshape competitive positioning.
Product Type:
Substitution pressure concentrates in categories where software-enabled diagnostics displace hardware-centric modalities, compressing traditional equipment reimbursement windows.
- Diagnostic Equipment:Imaging modalities including MRI, CT, and ultrasound systems carry the highest per-procedure reimbursement rates under Medicare fee schedules. United States hospital systems concentrate procurement in metropolitan clusters where prior authorization automation reduces claims denial rates.
- Monitoring Systems:Continuous data capture devices for cardiac, respiratory, and metabolic parameters command expanding coverage under remote patient monitoring CPT codes. Germany's statutory health insurance system accelerates adoption through streamlined digital claims pathways.
- Surgical Instruments:Reusable and disposable instrument sets face pricing compression from bundled payment models.
- Orthopedic Devices:Implants and prosthetics navigate manufacturer-direct contracting trends that bypass distributor markups.
Diagnostic equipment anchors the volume base while monitoring systems gain share at the steepest rate.
End User:
Cost tier stratification separates high-acuity inpatient settings from distributed care sites, with reimbursement rates scaling inversely to facility overhead.
- Hospitals:Inpatient prospective payment systems govern device reimbursement through DRG-based bundling, creating incentive alignment for length-of-stay reduction. IDN consolidation in United States metropolitan markets concentrates purchasing power and squeezes supplier margins.
- Homecare Providers:Durable medical equipment dispensing faces channel shift toward captive specialty pharmacies owned by health systems. Medicare Advantage supplemental benefits expand coverage for mobility aids and respiratory equipment in patient residences.
- Clinics:Outpatient fee schedules apply distinct reimbursement rates for same procedures performed in office settings.
- Ambulatory Surgical Centers:Site-neutral payment policies compress reimbursement differentials versus hospital outpatient departments.
Hospitals retain the reimbursement volume base while homecare providers expand most quickly as site-of-care migration accelerates.
Reimbursement Model:
Margin structure varies by risk allocation, with models shifting financial exposure between payers and providers at different rates.
- Fee-for-Service:Traditional volume-based reimbursement dominates transaction counts but faces active displacement. CMS conversion to value-based arrangements targets specific device-intensive procedures for bundled payment pilots.
- Value-Based Care:Risk-sharing contracts tie device reimbursement to patient outcome metrics and total cost-of-care thresholds. Medicare ACO REACH models incorporate medical equipment utilization into shared savings calculations.
- Capitation:Per-member-per-month payments shift device cost risk to provider organizations.
- Bundled Payments:Episode-based reimbursement covers device and procedure costs in single prospective rates.
Fee-for-Service anchors current transaction volume while value-based care climbs the fastest as CMS accelerates mandatory participation timelines.
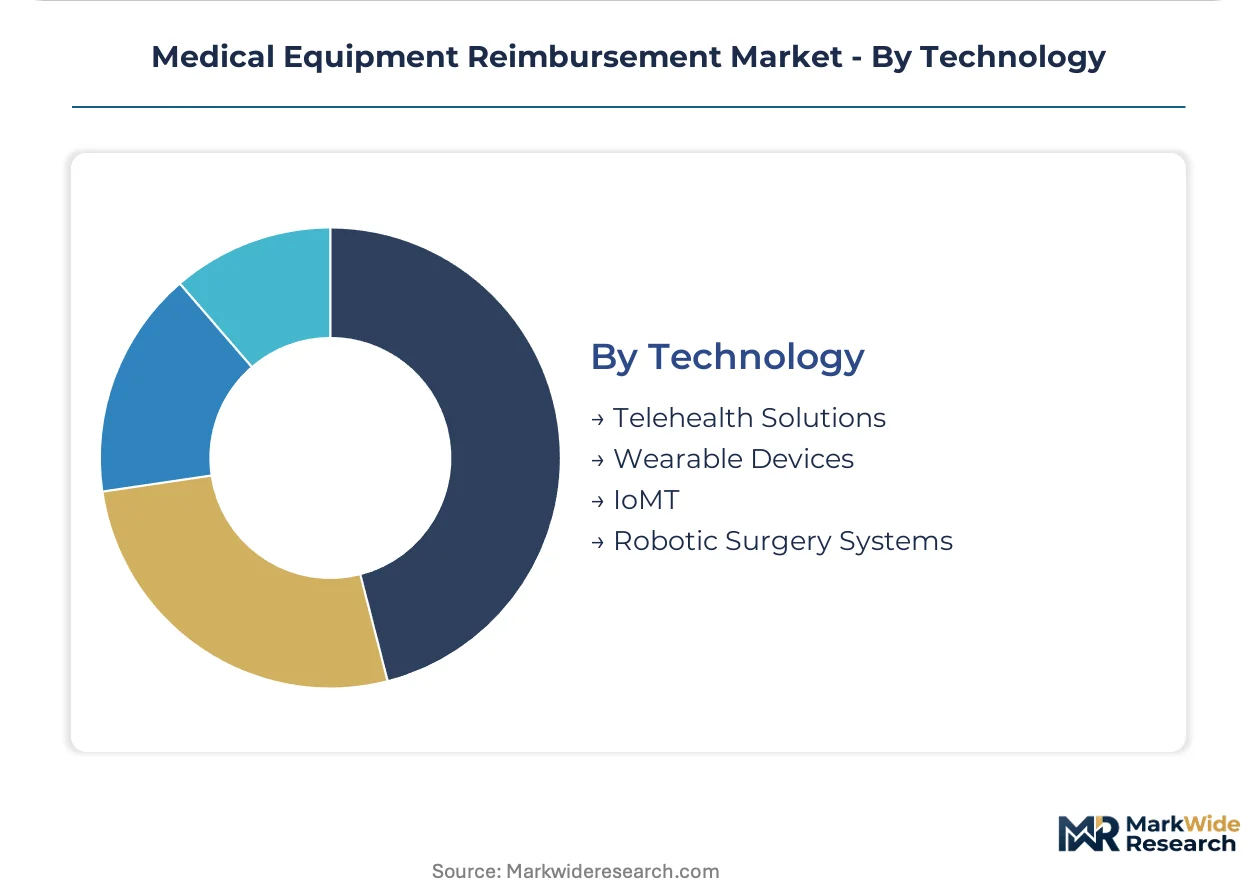
Technology:
Application focus determines reimbursement pathway clarity, with technologies embedding into existing codes moving faster than those requiring novel coverage determinations.
- Wearable Devices:Consumer-grade sensors with clinical validation bridge wellness and medical reimbursement categories. Continuous glucose monitors lead regulatory clearance pathways that private payers subsequently adopt.
- Telehealth Solutions:Synchronous and asynchronous remote care platforms integrate device data streams into reimbursable encounters. Medicare originating site restrictions have relaxed for specific monitoring integrations.
- IoMT:Connected device infrastructure faces interoperability standard gaps that delay claims system integration.
- Robotic Surgery Systems:Capital equipment and disposable instrument reimbursement spans multiple coding categories with inconsistent coverage.
Wearable devices anchor emerging volume while telehealth solutions gain coverage share at the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Interstate Highway System and transatlantic fiber corridors anchor North American reimbursement platform connectivity, while the Rhine-Main corridor and Channel Tunnel link European claims processing networks to hospital procurement hubs.
United States
CMS value-based care transitions and Medicare Advantage supplemental benefit expansion drive equipment coverage decisions. The FDA's breakthrough device designation creates parallel reimbursement pathways through Medicare's transitional coverage framework. Hospital procurement consolidation in Texas Medical Center and Mayo Clinic Rochester clusters concentrates purchasing power around integrated device-plus-reimbursement bundles.
Germany
Statutory health insurance digital claims processing modernization accelerates automated prior authorization adoption. REACH regulation compliance requirements through ECHA cascade into payer coverage determinations excluding SVHC-listed device components. Berlin-Brandenburg and North Rhine-Westphalia hospital networks lead procurement centralization around vendor-managed inventory programs.
United Kingdom
NHS Integrated Care Systems consolidate equipment procurement under single-payer reimbursement frameworks. NICE technology appraisals determine coverage thresholds for high-cost diagnostic devices. London and Greater Manchester health economies pilot episode-based bundled payments for orthopedic implant procedures.
Japan
Ministry of Health, Labour and Welfare biennial fee schedule revisions adjust device reimbursement rates under universal health coverage. PMDA regulatory harmonization with FDA pathways accelerates parallel market access for breakthrough-designated equipment. Tokyo-Osaka metropolitan hospital chains concentrate procurement through regional cooperative purchasing organizations.
India
Ayushman Bharat Pradhan Mantri Jan Arogya Yojana expansion drives demand for affordable medical device coverage in tier-2 and tier-3 cities. CDSCO medical device rules alignment with MDR principles reshape import-dependent reimbursement pathways. Maharashtra and Karnataka health technology assessment committees establish state-level coverage determination precedents for dialysis and cardiac equipment.
Medical Equipment Reimbursement Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and data analytics capabilities, creating a tiered structure where scale-driven payers anchor national contracts while regional specialists capture niche segments. Consolidation pressure concentrates claims processing volume among entities with captive pharmacy benefit management arms. Two strategic archetypes dominate: integrated health services conglomerates bundling insurance with care delivery, and pure-play payers outsourcing administrative functions to technology vendors. Competitive moves center on vertical integration into specialty pharmacy dispensing and strategic partnerships with device manufacturers bypassing distributor layers.
Within the integrated health services tier, UnitedHealth Group exemplifies the analytics-driven archetype through its Optum platform, while Cigna Healthcare occupies a position emphasizing direct manufacturer contracting. CVS Health represents the pharmacy-anchored model, situating reimbursement operations within retail clinic networks. These three entities anchor competitive dynamics across distinct strategic vectors without overlapping core positioning.
| Leading Market Players |
|---|
| UnitedHealth Group |
| Cigna Healthcare |
| Humana |
| Aetna |
| Allianz |
| Anthem Insurance Companies |
| CVS Health |
| WellCare Health Plans |
| BNP Paribas |
| Others |
Supply & Pricing Matrix
Ninety-day prior authorization processing windows concentrate pricing power among payers with automated claims adjudication infrastructure, compressing margins for mid-cap insurers still reliant on manual HCPCS Level II coding verification. Device manufacturers respond by bundling reimbursement support services into equipment contracts, effectively capturing margin that distributors previously extracted.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs device reimbursement, with FDA breakthrough designation and CMS national coverage determination status driving tier placement. Price differentiation rests on certification tier and after-sales clinical support bundling, while cost compression in standard tiers intensifies as software-enabled diagnostics displace hardware-centric modalities. Medicare Advantage plans exhibit highest price sensitivity due to supplemental benefit budget constraints; integrated health systems with captive specialty pharmacies demonstrate lowest sensitivity through volume aggregation.
Supply Chain Analysis
Sixty-to-ninety-day inventory cycles for implantable devices expose orthopedic manufacturers to working capital strain when prior authorization delays extend receivables. Supply concentrates in Germany, the United States, and Japan for high-value diagnostic equipment, while component sourcing draws from Taiwan for semiconductors and China for sensor assemblies. Single-source vulnerability concentrates in rare earth magnet supply for MRI systems. Distribution runs through IDN-owned specialty pharmacies that displace independent DME suppliers in metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around HCPCS Level II coding expertise creates switching costs that lock providers into established payer platforms.
For Market Incumbents: Consolidate claims processing volume through acquisition of regional payers lacking automated prior authorization infrastructure, while deepening backward integration into specialty pharmacy dispensing to capture distributor margin. Threat from software-native insurtech entrants with AI-powered coding validation demands preemptive investment in interoperability standards with Epic and Cerner EHR systems. For New Entrants and Emerging Players: Anchor in Medicare Advantage supplemental benefit administration for durable medical equipment, the most penetrable segment due to incumbent focus on commercial group contracts. White-space exists in remote patient monitoring platform integration for chronic disease management contracts, with go-to-market execution through direct hospital system partnerships bypassing traditional broker channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified health services conglomerates seeking to divest non-core reimbursement administration units with sub-scale technology infrastructure. Long-term viability favors entities with captive analytics capabilities bridging clinical data streams to population health contracts. Signal to watch: CMS mandatory bundled payment expansion timelines for device-intensive procedures.| Strategic Initiative | Industry Significance |
|---|---|
| HCPCS Coding Automation Investment | Reduces denial rates for UnitedHealth Group and Cigna through machine-learning pre-validation. |
| Direct Manufacturer Contracting | Streamlines prior authorization for orthopedic device makers bypassing distributor markup layers. |
| Remote Monitoring Platform Integration | Captures chronic disease management contracts through continuous glucose monitor data streams. |
| IDN Specialty Pharmacy Acquisition | Consolidates DME dispensing channel for CVS Health within captive Medicare Advantage networks. |
| Breakthrough Device Reimbursement Strategy | Accelerates Medicare coverage through transitional framework for FDA-designated equipment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of CMS Medicare claims data, FDA 510(k) and PMA filings, hospital GPO contract databases, and statutory health insurance reimbursement schedules. Interviews with payer reimbursement directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchor qualitative assessment. Secondary validation draws from HCPCS Level II coding manuals, NCD and LCD determination records, and SEC 10-K disclosures from listed health insurers. Bottom-up equipment transaction modeling triangulates against top-down payer premium and claims expenditure analysis.
Segmentation dimensions modeled span product type, end-user facility category, reimbursement model architecture, and technology platform across the projection horizon. CAGR derivation incorporates equipment replacement cycles, regulatory coverage determination velocity, and site-of-care migration patterns. Forecast inputs include Medicare Advantage enrollment trajectories and statutory health insurance digital claims processing adoption curves.
Material uncertainties — CMS rulemaking delays, FDA breakthrough designation volume, and ECHA REACH substance restriction expansions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding interoperability standard adoption and prior authorization automation penetration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Dual Energy X-Ray Absorptiometry (Dexa) Equipment Market
Medical Equipment
Tissue Culture Incubator Market
Medical Equipment
US ECG Equipment Market
Medical Equipment
Floor-Standing Platelet Agitator Market
Medical Equipment
Cell Washer Market
Medical Equipment
Sterilization Equipment Market
Medical Equipment
Clinical Microscopes Market
Medical Equipment
PMMA Healthcare Market
Medical Equipment
Solar Powered Vaccine Refrigerator Market
Medical Equipment
Global Surgical Table Market
Medical Equipment
CO2 Medical Laser Systems Market
Medical Equipment
Global Gynecological Examination Chairs Market
Medical Equipment
Global Bone Densitometer Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
Medical Carts and Workstations Market
Medical Equipment
Global Cardiopulmonary Stress Testing Systems Market