
 Asia-Pacific Medical Device Cleaning Market | 2026-2036
Asia-Pacific Medical Device Cleaning Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Medical Device Cleaning Market Analytics
Quaternary ammonium compounds are shifting toward peracetic acid and hydrogen peroxide formulations across the Asia-Pacific Medical Device Cleaning Market as facilities seek faster turnaround times with lower residue profiles. Steris plc anchors its regional position through automated endoscope reprocessor installations in Australian and Japanese hospital networks. Getinge AB leverages centralized sterile supply department contracts to sustain volume leadership across Southeast Asian markets. 3M Co competes through enzymatic detergent portfolios calibrated to local water hardness conditions.
Asia-Pacific medical device cleaning encompasses validated protocols, chemistries, and equipment engineered to remove biological soil and reduce microbial load on reusable instruments prior to terminal sterilization. Enzymatic detergents operate at neutral pH with surfactant blends targeting protein, lipid, and carbohydrate residues on complex instrument geometries. Surgical instruments command the largest product-type volume pool given procedural density in cardiac and orthopedic specialties across the region. Ultrasonic cleaning technology is expanding fastest as Chinese and Indian hospitals replace manual brushing protocols with cavitation-based systems that improve luminal device efficacy. Automatic cleaning systems concentrate margin pools where OEM service contracts bundle consumables, chemistry validation, and regulatory documentation.
Japan's PMDA and MHLW enforce high-level disinfection standards that shape product registration requirements and facility audit protocols across the domestic hospital sector. Australia's TGA and China's NMPA impose divergent biocompatibility and efficacy testing frameworks that manufacturers must navigate for multi-country product portfolios. Stakeholders should monitor how India's CDSCO harmonizes its medical device rules with ISO 17664 cleaning validation requirements as domestic manufacturing scales.
Market Dynamics
Japan's MHLW high-level disinfection standards are forcing tertiary hospitals across the Asia-Pacific region to replace manual cleaning protocols with automated endoscope reprocessors, compressing equipment replacement cycles and concentrating procurement authority in centralized sterile supply departments.
Growth Catalysts
- Cardiac and orthopedic procedural density:Surgical instrument cleaning volumes are climbing as China and India expand catheterization lab and joint replacement capacity in provincial hospital networks.
- Japan's MHLW reprocessing mandates:The ministry's 2024 technical guidance on automated high-level disinfection is compelling facilities to retire manual brushing stations.
- Ultrasonic cavitation systems:Chinese and Indian hospitals are replacing manual luminal brushing with automated cavitation technology that improves efficacy on complex device geometries.
Market Restraints
- Peracetic acid supply concentration:Formulation-grade chemical production clusters in select Chinese chemical manufacturing zones, creating input vulnerability for regional cleaning chemistry blenders.
- Water hardness calibration costs:Enzymatic detergent efficacy varies sharply across Southeast Asian municipal water supplies, forcing chemistry reformulation for local conditions.
- Legacy manual protocol inertia:Smaller Indian and Indonesian hospitals retain manual brushing due to capital constraints and technician familiarity, slowing automated system penetration.
Strategic Opportunities
- Vietnam and Philippines hospital construction:Greenfield tertiary facilities in these markets are specifying automated reprocessors in initial equipment procurement rather than retrofitting legacy spaces.
- Service contract bundling:OEMs are attaching multi-year consumables and validation documentation packages to equipment sales, capturing recurring revenue streams.
- India's CDSCO-ISO 17664 harmonization:The regulator's alignment with international cleaning validation standards is creating a compliance services market for domestic device manufacturers.
Industry Challenges
- Biomedical technician certification gaps:Automated reprocessor maintenance and chemistry validation require specialized training that outpaces technical education capacity in Indonesian and Vietnamese markets.
- Multi-regulatory portfolio complexity:Manufacturers must maintain parallel biocompatibility testing dossiers for Australia's TGA, China's NMPA, and Japan's PMDA, extending product registration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Medical Device Cleaning Market |
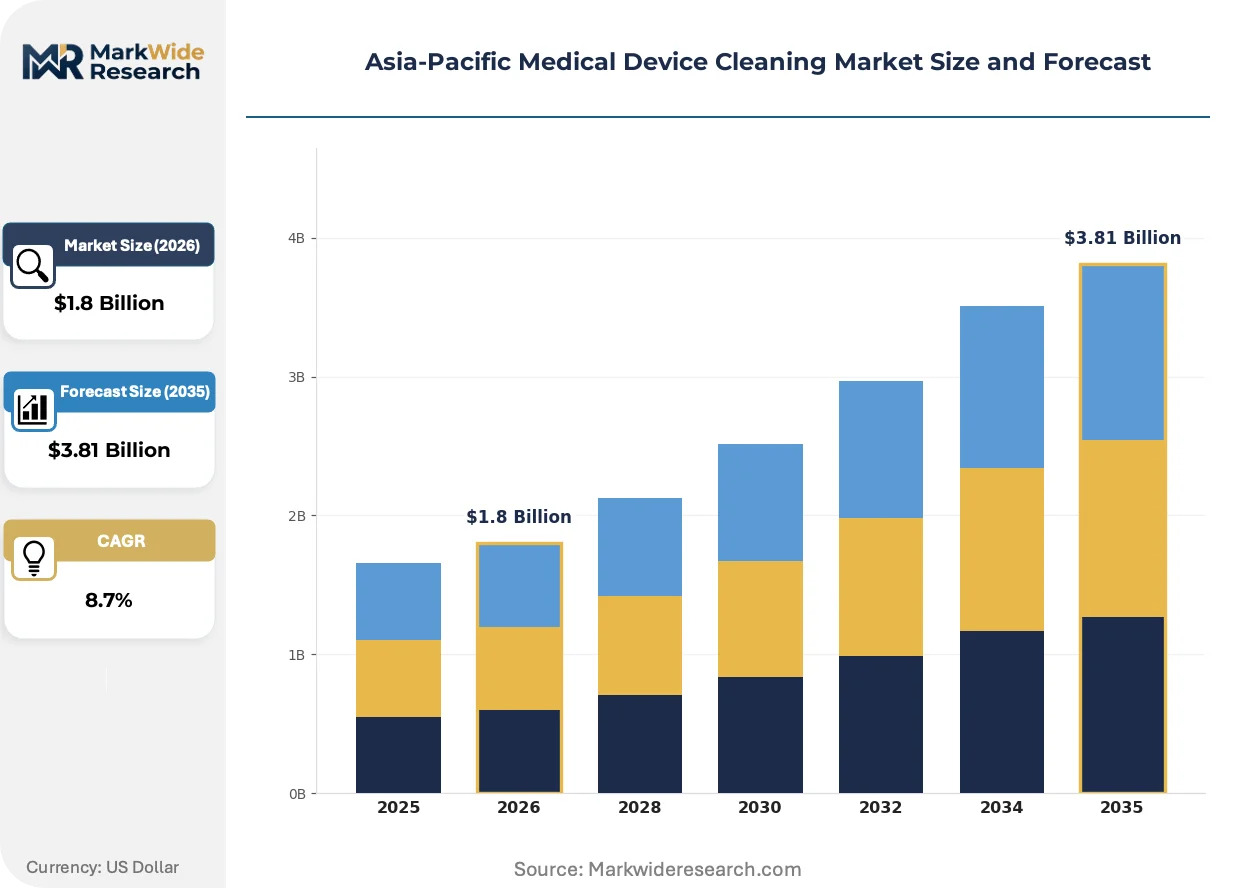
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Endoscopes, Diagnostic Equipment, Dental Tools Cleaning Technology: Ultrasonic Cleaning, Manual Cleaning, Automatic Cleaning, Chemical Cleaning End User: Hospitals, Clinics, Laboratories, Surgery Centers Application Area: Infection Control, Maintenance, Sterilization, Disinfection |
| Companies Covered | Steris plc, Getinge AB, 3M Co, Cantel Medical, Ecolab Inc, Sotera Health Co, Tuttnauer, Synergy Health, Ningbo Scientz Biotechnology Co., Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Medical Device Cleaning Market Evolving Landscape
Peracetic acid and hydrogen peroxide chemistries are displacing legacy quaternary ammonium formulations as facilities prioritize faster instrument turnaround with reduced residue profiles. Three interconnected developments are restructuring competitive positioning.
Automated endoscope reprocessors with integrated cleaning validation documentation are rewriting procurement criteria for Japanese and Australian hospital networks. Tertiary facilities in Osaka and Sydney are specifying systems that bundle chemistry delivery, cycle monitoring, and audit-ready compliance records. This technology compression is marginalizing standalone manual stations and concentrating vendor relationships around full-service OEM contracts.
China's NMPA is tightening biocompatibility testing requirements for cleaning chemistries used on implanted devices, extending registration timelines for enzymatic detergent formulations. Domestic manufacturers are responding by establishing in-house toxicology testing capabilities rather than relying on third-party laboratories. The surgical instrument segment faces the steepest compliance burden as implantable device reprocessing standards converge with pharmaceutical-grade material safety thresholds.
Centralized sterile supply departments in China's eastern province hospital networks are consolidating regional device cleaning volumes under single procurement umbrellas. These buyers are unbundling equipment, consumables, and service contracts to optimize total cost of ownership, pressuring vendors to disaggregate traditionally bundled offerings. The procurement model disruption is most visible in Jiangsu and Zhejiang province health systems where municipal hospital networks are merging sterilization operations.
Asia-Pacific Medical Device Cleaning Market Segmentation
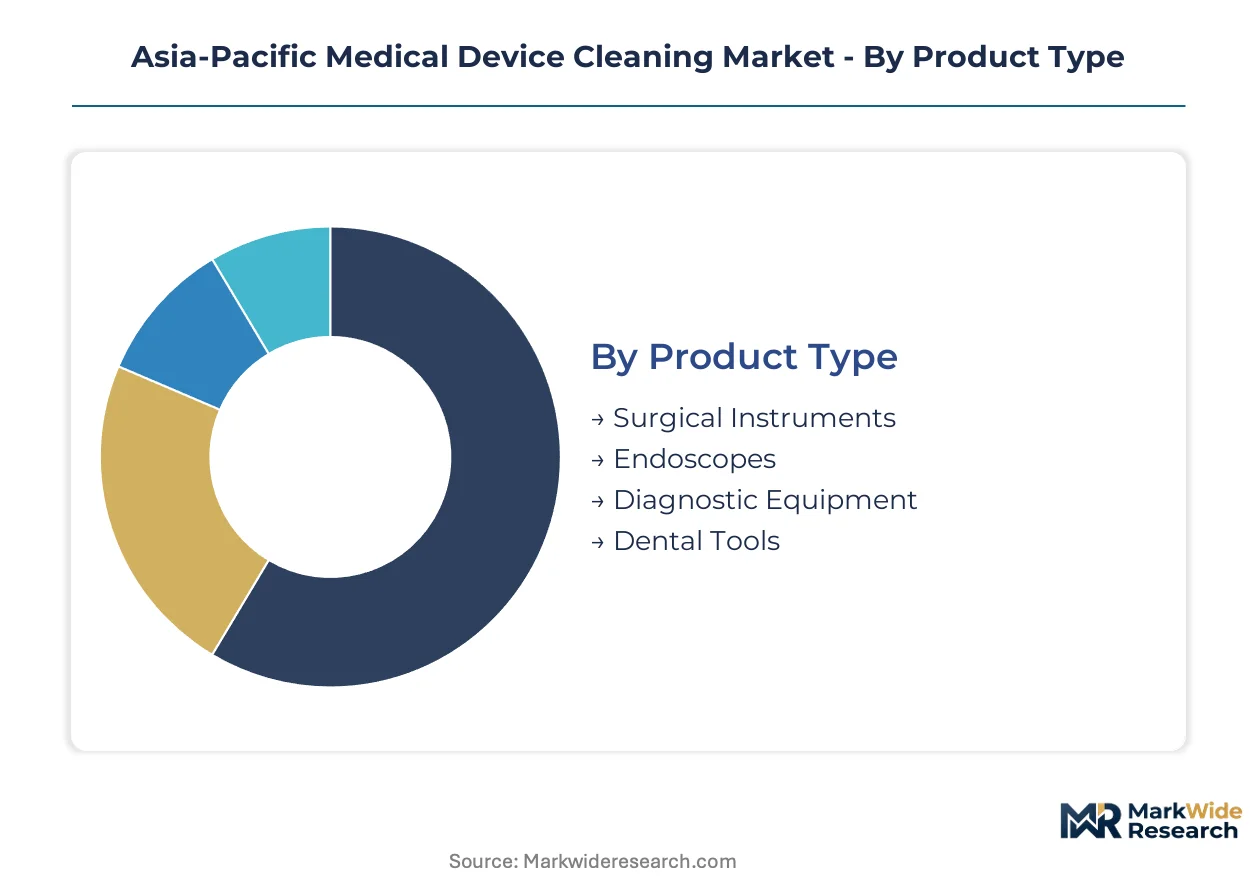
Cleaning protocol requirements diverge sharply across device complexity, facility scale, and regulatory jurisdiction in the Asia-Pacific Medical Device Cleaning Market. Segmentation reveals where automated systems displace manual workflows and which chemistry formulations command premium positioning.
Product Type:
Procurement scale and reprocessing risk profile separate buyers across device categories.
- Surgical Instruments:Complex geometries in cardiac and orthopedic sets demand enzymatic detergents with surfactant blends targeting protein and lipid residues. China's eastern province hospital networks are consolidating sterilization supply departments around high-volume instrument reprocessing, compressing vendor relationships toward full-service contracts.
- Endoscopes:Luminal device architecture necessitates automated reprocessors with integrated high-level disinfection cycles. Japan's MHLW technical guidance is compelling tertiary facilities in Osaka and Tokyo to retire manual brushing stations, accelerating replacement demand for validated automated systems.
- Diagnostic Equipment:Surface disinfection protocols dominate, with peracetic acid formulations gaining preference for faster turnaround.
- Dental Tools:Smaller scale reprocessing in clinic settings sustains manual protocol persistence despite automation trends elsewhere.
Volume sits with surgical instruments; growth tilts toward endoscopes.
Cleaning Technology:
Capital intensity and technician certification requirements stratify adoption patterns across facility tiers.
- Automatic Cleaning:Integrated washer-disinfector systems bundle chemistry delivery, cycle monitoring, and compliance documentation for audit-ready operations. Australian and Japanese hospital networks are specifying these systems in greenfield construction, marginalizing standalone manual stations.
- Ultrasonic Cleaning:Cavitation technology improves luminal device efficacy where manual brushing fails. Chinese and Indian hospitals are replacing legacy protocols with automated cavitation systems, particularly for complex instrument geometries in provincial networks.
- Manual Cleaning:Capital constraints and technician familiarity sustain persistence in smaller Indonesian and Vietnamese facilities.
- Chemical Cleaning:Peracetic acid and hydrogen peroxide formulations are displacing quaternary ammonium compounds for reduced residue profiles.
Automatic systems capture margin concentration; ultrasonic technology expands most quickly.
End User:
Regulatory scrutiny intensity and procurement centralization divide facility types.
- Hospitals:Tertiary institutions face the steepest compliance burden under Japan's PMDA and Australia's TGA frameworks. Centralized sterile supply departments in China's Jiangsu and Zhejiang provinces are unbundling equipment and consumable contracts to optimize total cost of ownership.
- Surgery Centers:Ambulatory settings prioritize turnaround speed, favoring rapid-cycle chemistries and compact automated systems.
- Clinics:Lower procedural volumes sustain manual protocol economics despite automation availability.
- Laboratories:Specialized device portfolios require customized validation documentation for research-grade equipment.
Hospitals anchor procurement volume; surgery centers drive fastest system replacement cycles.
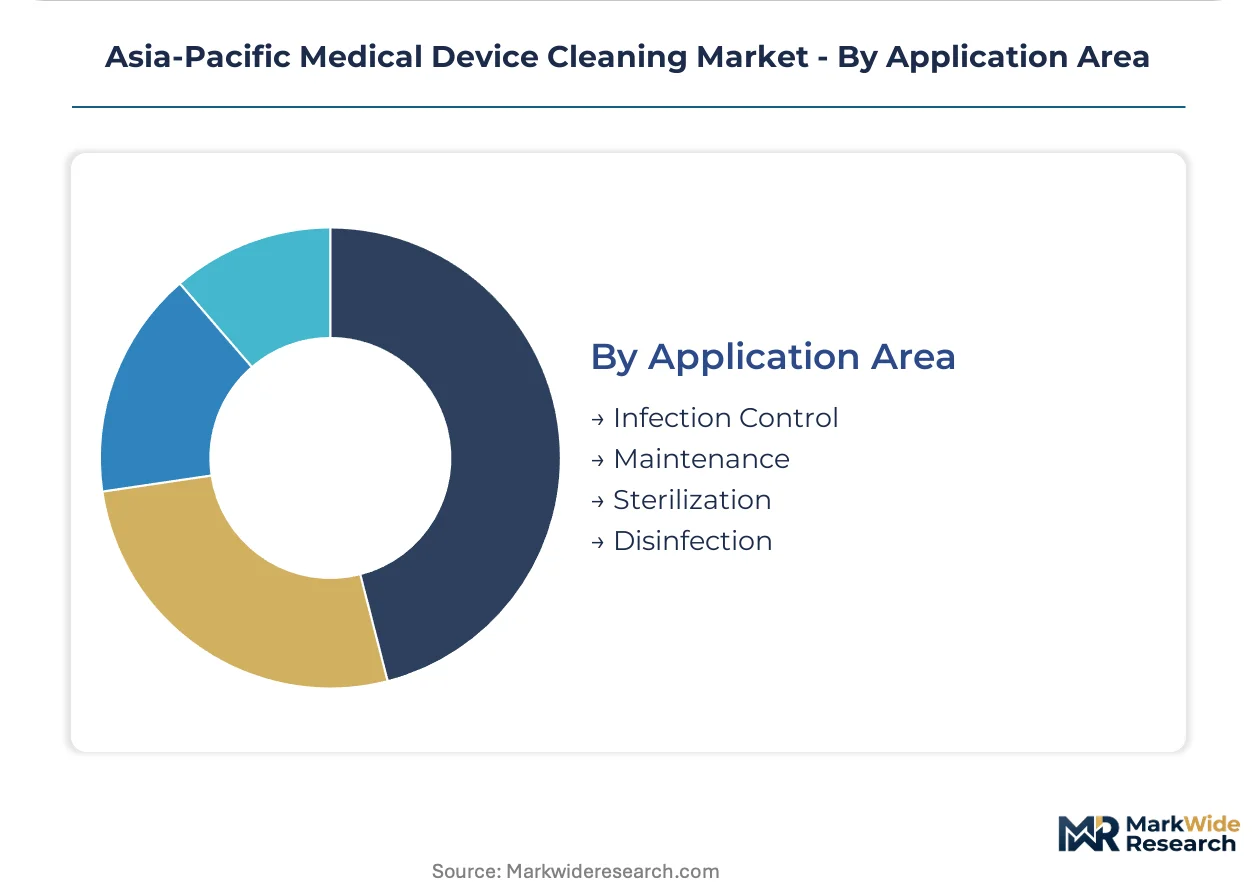
Application Area:
Microbial load reduction targets and documentation requirements shape chemistry and equipment selection.
- Sterilization:Terminal sterilization protocols demand validated cleaning as prerequisite, with enzymatic detergents operating at neutral pH to preserve instrument integrity.
- Disinfection:High-level disinfection standards under Japan's MHLW are forcing chemistry upgrades and automated system installations.
- Infection Control:Outbreak response protocols are accelerating peracetic acid adoption for sporicidal efficacy.
- Maintenance:Preventive cleaning extends device lifespan, particularly for capital-intensive endoscope inventories.
Sterilization preparation commands the largest chemistry volume; disinfection compliance drives equipment replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's eastern province hospital networks, where centralized sterilization supply departments are consolidating regional reprocessing volumes under unified procurement umbrellas.
China
Cardiac and orthopedic procedural density is climbing in provincial hospital networks across Jiangsu and Zhejiang provinces. The NMPA is tightening biocompatibility testing requirements for cleaning chemistries used on implanted devices. Municipal hospital networks in Shanghai are merging sterilization operations and unbundling equipment from consumable contracts.
Japan
Endoscopy departments in Osaka and Tokyo tertiary hospitals are expanding automated reprocessing capacity to replace manual brushing stations. The MHLW's 2024 technical guidance on automated high-level disinfection is compelling facilities to upgrade systems. Tokyo Medical University Hospital and comparable institutions are specifying integrated washer-disinfectors with audit-ready compliance documentation.
India
Ultrasonic cavitation systems are replacing manual luminal brushing in provincial hospital networks as catheterization lab capacity expands. The CDSCO is harmonizing medical device rules with ISO 17664 cleaning validation requirements. Smaller facilities in Kerala and Tamil Nadu retain manual protocols due to capital constraints, slowing automation penetration.
Australia
Tertiary facilities in Sydney are specifying automated endoscope reprocessors in greenfield construction projects. The TGA imposes biocompatibility and efficacy testing frameworks that shape product registration timelines. Royal Prince Alfred Hospital and comparable networks are procuring systems that bundle chemistry delivery with cycle monitoring.
Vietnam
Greenfield tertiary hospital construction in Ho Chi Minh City and Hanoi is specifying automated reprocessors in initial equipment procurement. The country's national pharmaceutical regulator is developing alignment with international cleaning validation standards. Biomedical technician certification gaps persist, creating maintenance capacity constraints for installed systems.
Asia-Pacific Medical Device Cleaning Market Competitive Landscape
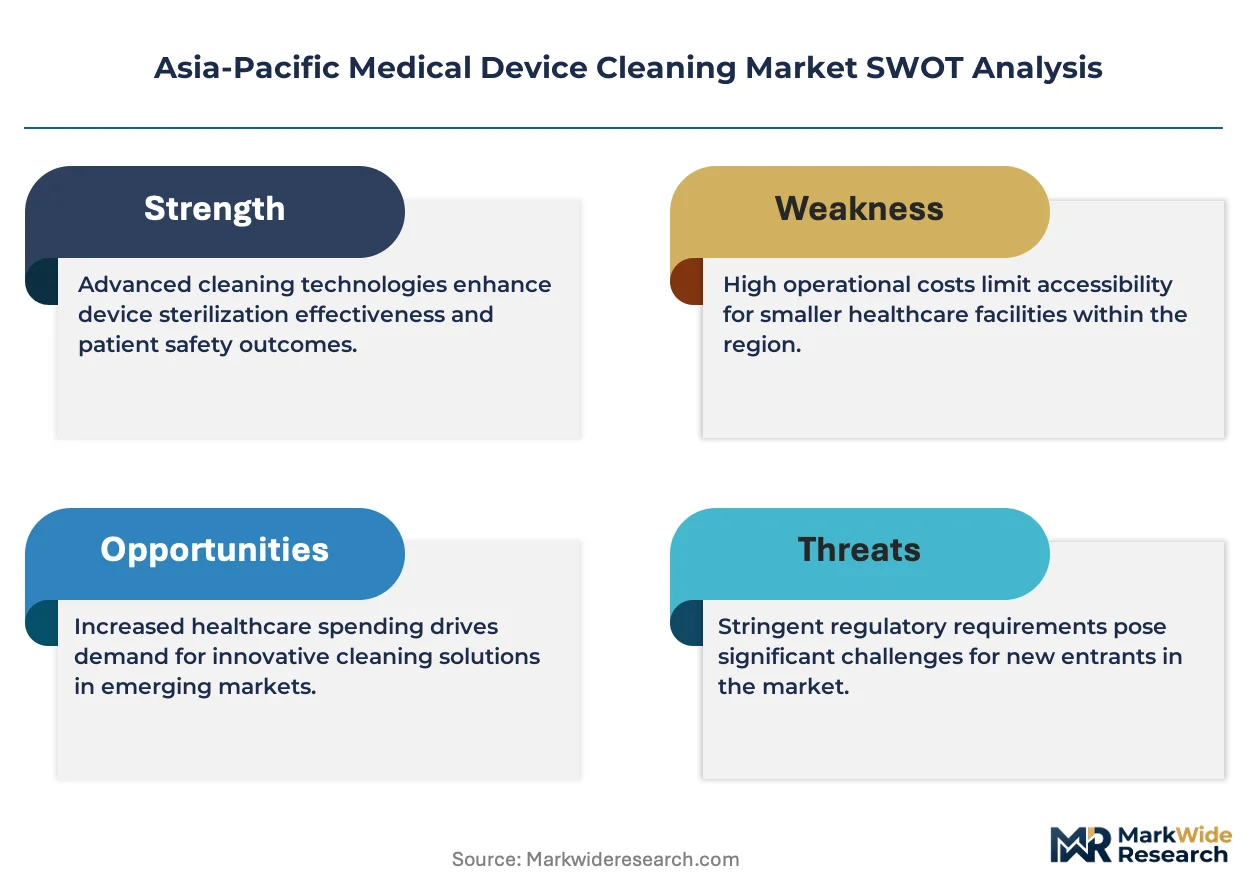
Service contract bundling dominates the current landscape as OEMs attach multi-year consumables and validation documentation packages to equipment sales. The vendor base stratifies across full-service system integrators, specialized chemistry blenders, and regional equipment distributors. Three archetypes anchor positioning: automated reprocessor manufacturers with captive chemistry portfolios, enzymatic detergent specialists calibrating to local water conditions, and sterile supply department contractors capturing recurring revenue streams. M&A activity and geographic expansion represent the dominant competitive vectors as players seek scale in consolidating procurement environments.
Within the full-service system integrator tier, Steris plc and Getinge AB exemplify positioning around automated endoscope reprocessor installations and centralized sterile supply department contracts. 3M Co occupies a position among chemistry specialists, with enzymatic detergent portfolios addressing water hardness calibration requirements across Southeast Asian municipal supplies. These three anchors represent divergent strategic bets: equipment-chemistry bundling versus consumable formulation specialization versus regional service infrastructure.
| Leading Market Players |
|---|
| Steris plc |
| Getinge AB |
| 3M Co |
| Cantel Medical |
| Ecolab Inc |
| Sotera Health Co |
| Tuttnauer |
| Synergy Health |
| Ningbo Scientz Biotechnology Co., Ltd |
| Others |
Value Network & Pricing Analysis
Biomedical technician certification concentration in Japan and Australia widens pricing-tier spreads between premium automated reprocessor bundles and economy manual chemistry kits, with labor-cost differentials compressing margins for vendors serving Indonesian and Vietnamese facilities.
Pricing Analysis
Volume concentrates in economy-tier enzymatic detergents for manual reprocessing, while margins pool in premium automated reprocessor systems with multi-year service contracts. Price differentiation hinges on ISO 17664 validation documentation and chemistry calibration to local water hardness conditions. Pricing pressure stems from Chinese hospital networks unbundling equipment from consumable contracts. Surgery centers exhibit highest price sensitivity; tertiary hospitals under Japan's MHLW mandates show lowest.
Supply Chain Analysis
Dual-sourcing requirements for peracetic acid and hydrogen peroxide formulations are forcing buyers to qualify secondary suppliers beyond dominant Chinese chemical manufacturing zones. Formulation-grade chemical production clusters in Jiangsu and Shandong provinces, with specialty surfactant inputs drawn from Japanese and South Korean suppliers. Single-source vulnerability concentrates in automated reprocessor electronics modules sourced from Taiwan. Distribution runs through centralized sterile supply departments consolidating regional procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Medical Device Cleaning Market sits in a technology-transition phase, with automated cavitation and integrated washer-disinfector systems displacing manual brushing protocols across tertiary hospital networks.
For Market Incumbents: Lock in service contract renewals with chemistry-consumable bundling to defend against unbundling pressure from Chinese centralized procurement umbrellas. Prioritize backward integration into peracetic acid formulation capacity to offset raw material supply concentration risks. The threat of domestic Chinese manufacturers gaining NMPA registration for competing automated systems demands accelerated certification investments in biocompatibility testing capabilities. For New Entrants and Emerging Players: CDSCO harmonization with ISO 17664 in India opens a window for compliance-services specialization targeting domestic device manufacturers seeking cleaning validation documentation. Target ultrasonic cavitation retrofits in Indian provincial hospital networks where catheterization lab expansion outpaces automated reprocessor capital budgets. A technical-training partnership model with Indonesian biomedical technician programs addresses certification gaps while embedding equipment. For Investors and Strategic Acquirers: Re-rating potential sits with enzymatic detergent specialists possessing water-hardness calibration expertise given Southeast Asian municipal supply fragmentation. Long-term viability favors acquisition targets with captive chemistry portfolios and regional service infrastructure rather than pure equipment plays. Watch India's CDSCO enforcement timeline as inflection indicator for compliance-services market scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Reprocessor Platform Launch | MHLW technical guidance in Japan accelerates replacement demand for validated systems with audit-ready documentation. |
| Chemistry Calibration Service Expansion | Water hardness variation across Southeast Asian municipal supplies creates recurring revenue attachment opportunities. |
| Biocompatibility Testing Capability Buildout | NMPA tightening on implanted device chemistries extends registration timelines for domestic Chinese manufacturers. |
| Centralized Sterile Supply Department Partnership | Jiangsu and Zhejiang province hospital network mergers consolidate procurement authority under unified umbrellas. |
| Biomedical Technician Certification Program | Training capacity gaps in Vietnam and Indonesia create maintenance contract stickiness for installed system bases. |
Research Methodology
Regulatory filings from Japan's PMDA, Australia's TGA, and China's NMPA formed the secondary backbone, supplemented by hospital procurement databases and GPO contract records. Primary interviews with biomedical engineers, sterile supply department managers, and GPO contracts managers validated chemistry demand patterns and equipment replacement cycles. Bottom-up and top-down triangulation cross-checked automated reprocessor installation rates against enzymatic detergent volume flows.
Bottom-up modeling built from device reprocessing volumes by hospital tier, procedure type, and cleaning protocol requirement. Top-down validation referenced healthcare capital expenditure surveys and medical device reprocessing regulatory compliance spending across the analysis window. Segmentation dimensions included device complexity, facility scale, cleaning technology type, and regional regulatory cluster. CAGRs derived from procedure growth trajectories and automation penetration curves calibrated to MHLW and CDSCO policy implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for manual-to-automated transition would alter the outlook if capital constraints in Indian and Indonesian facilities persist longer than projected. Deviation in peracetic acid supply chain concentration or NMPA biocompatibility testing timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Carbon Dioxide Incubators Market
Medical Equipment
ECG Equipment and Management Systems Market
Medical Equipment
MRI Transport Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Asia-Pacific Medical Device Reprocessing Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
X-Ray Machine Manufacturing Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
Floor-Standing Platelet Agitator Market
Medical Equipment
CO2 Medical Laser Systems Market
Medical Equipment
Mercury Thermometer Market
Medical Equipment
Terminal Sterilization Market
Medical Equipment
Patient Lifting Equipment Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
Global Optometry Equipment Market
Medical Equipment
ECG Equipment Market