
 Medical Gas Equipment Market | 2026-2036
Medical Gas Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Gas Equipment Market Analysis
The EU Green Deal's decarbonization mandates for healthcare supply chains is pivoting procurement criteria toward energy-efficient gas generation and low-loss distribution architectures. Air Liquide leverages its cryogenic technology leadership to anchor European hospital contracts for liquid oxygen storage and vaporization systems. Dragerwerk competes through integrated anesthesia workstations that bundle gas delivery with patient monitoring, while Linde extends its industrial gases expertise into medical-grade production networks spanning multiple continents.
Medical gas equipment encompasses the engineered systems, containment vessels, and control devices that store, purify, regulate, and deliver therapeutic gases to clinical environments, typically manufactured from chrome-molybdenum steel or aluminum alloys to withstand pressures exceeding 3,000 psi and maintain USP-grade purity thresholds. Pipeline systems dominate installed value in acute care facilities where centralized bulk supply eliminates cylinder changeout labor, while home healthcare represents the fastest-expanding application as portable concentrators and lightweight aluminum cylinders displace stationary systems in post-acute settings. Pressure regulators command disproportionate margin attention due to precision machining requirements and recurring replacement cycles tied to calibration protocols.
The FDA enforces Current Good Manufacturing Practice standards for medical gas equipment under 21 CFR Part 820, while the EPA regulates ozone-depleting refrigerants in cryogenic systems and OSHA mandates workplace exposure limits that shape gas handling protocols. The EU Medical Device Regulation imposes stricter clinical evidence requirements on Class IIa and IIb gas delivery devices, lengthening approval timelines for non-European manufacturers. Stakeholders must monitor evolving harmonization between FDA quality system regulations and MDR technical documentation standards to anticipate compliance cost trajectories and competitive repositioning.
Market Dynamics
Hospital procurement teams are consolidating vendor relationships under total-cost-of-ownership frameworks that bundle equipment, maintenance, and gas supply into single-source contracts, compressing supplier margins while locking in long-term service revenue streams.
Growth Catalysts
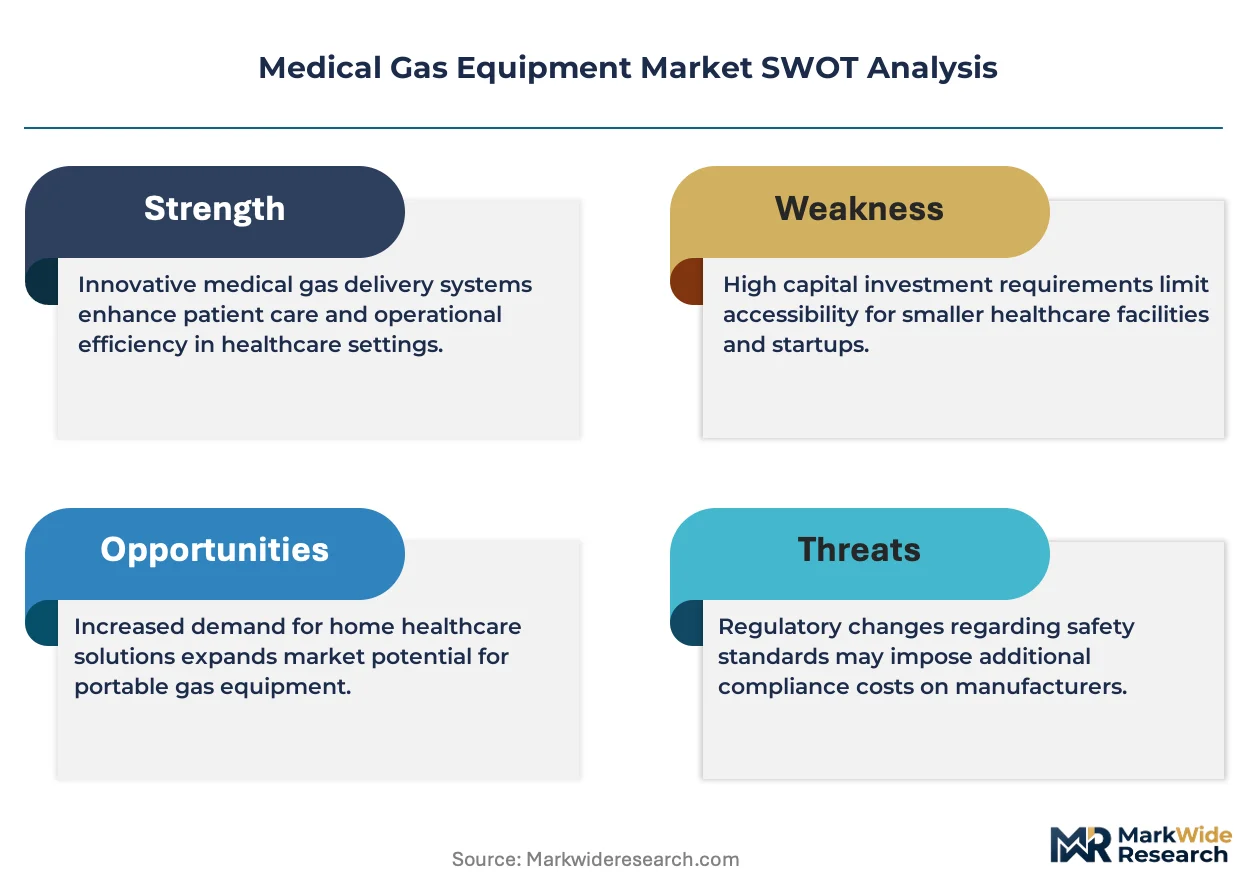
- Chronic respiratory disease prevalence:COPD and asthma patient volumes in the United States, Germany, and Japan are forcing hospital capital committees to expand oxygen delivery infrastructure and backup storage capacity.
- FDA Quality System Regulation updates:The 21 CFR Part 820 revisions mandate upgraded documentation and validation protocols, compelling equipment replacement cycles that favor suppliers with pre-validated product lines.
- Home healthcare expansion:Post-acute care migration toward residential settings is accelerating portable concentrator and lightweight aluminum cylinder procurement for aging populations managing oxygen therapy outside clinical facilities.
Market Restraints
- Chrome-molybdenum steel price volatility:Pressure vessel fabrication costs fluctuate with alloy commodity markets, squeezing margin predictability for cylinder and bulk storage manufacturers.
- Cryogenic refrigerant supply concentration:EPA-regulated ozone-depleting substance phase-outs under the Montreal Protocol have concentrated alternative refrigerant production among limited chemical suppliers, creating input bottlenecks for liquid oxygen vaporization systems.
- EU MDR clinical evidence requirements:Class IIa and IIb gas delivery devices face lengthened approval timelines for non-European manufacturers, creating competitive friction against established CE-marked incumbents.
Strategic Opportunities
- Energy-efficient gas generation:The EU Green Deal's decarbonization mandates for healthcare supply chains are pivoting procurement criteria toward low-loss distribution architectures and on-site generation systems that reduce liquid oxygen trucking emissions.
- Remote patient monitoring convergence:Integration of pulse oximetry and flow sensors with portable concentrators enables predictive maintenance and adherence tracking, opening subscription revenue models for equipment lessors.
- India hospital infrastructure buildout:Government schemes expanding tertiary care capacity in tier-2 and tier-3 cities are creating first-mover advantages for pipeline system installers and bulk storage providers.
Industry Challenges
- Precision machining talent scarcity:Pressure regulator manufacturing requires specialized CNC programming and calibration expertise that outpaces vocational training pipeline output in mature manufacturing economies.
- Legacy pipeline retrofit complexity:Acute care facilities with decades-old copper distribution infrastructure face disruptive installation timelines and infection control risks when upgrading to aluminum or stainless steel manifold systems.
- Harmonization friction between FDA and MDR standards:Divergent technical documentation and quality system requirements force manufacturers to maintain dual compliance infrastructures, elevating overhead without market expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Gas Equipment Market |
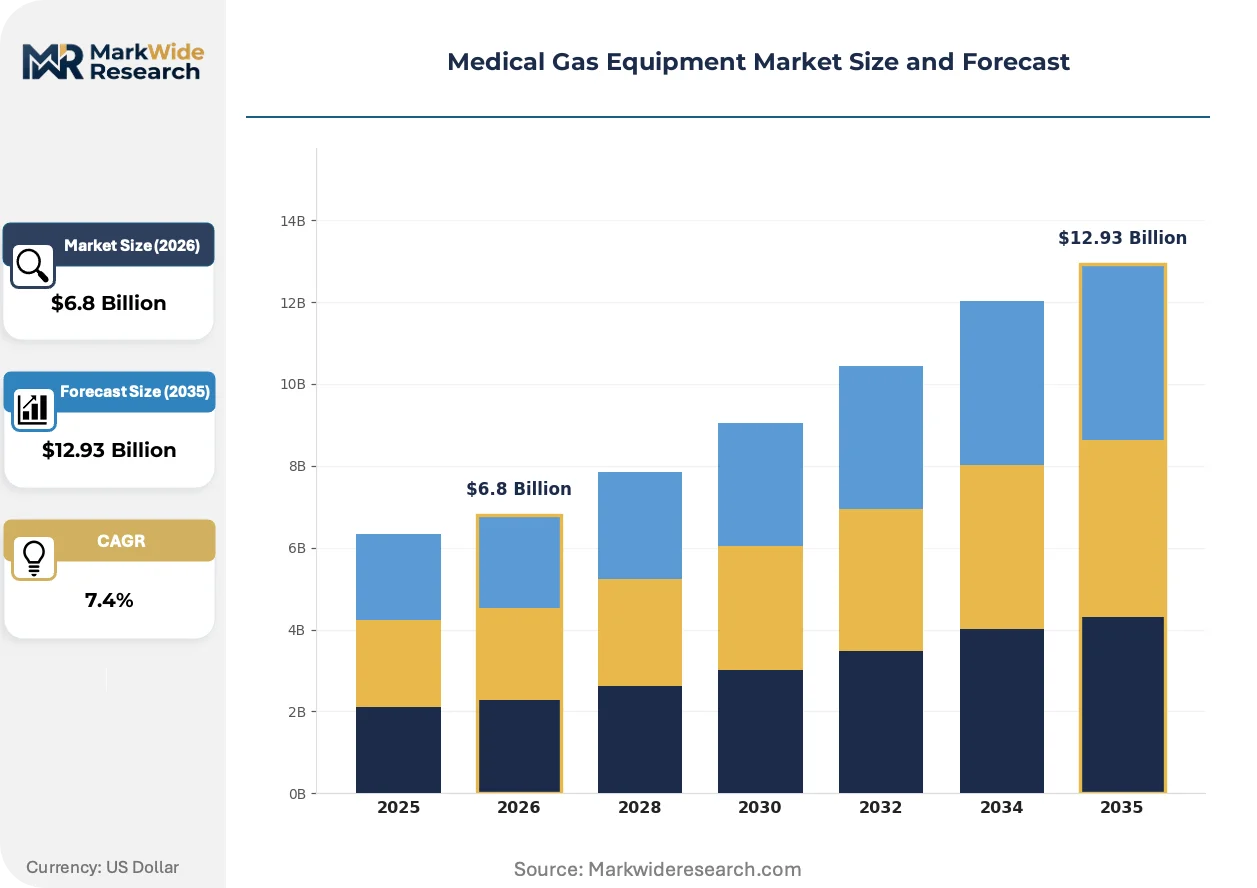
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pipeline Systems, Medical Gas Cylinders, Manifolds, Pressure Regulators Application: Emergency Care, Anesthesia, Critical Care, Home Healthcare End User: Hospitals, Clinics, Rehabilitation Centers, Medical Offices Delivery Mode: Liquid, Gas, Mixture, Cryogenic |
| Companies Covered | Allied Healthcare Products, Amico Corporation, Air Liquide, Dragerwerk, Taiyo Nippon Sanso Corporation, Atlas Copco Group, GCE Group, Ohio Medical, Linde, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Gas Equipment Market Emerging Trajectories
Equipment architecture is shifting from discrete component sales toward integrated system platforms that embed monitoring, predictive maintenance, and consumption analytics as standard features rather than premium add-ons.
Membrane-based oxygen concentrator technology is consolidating market share in home healthcare applications by eliminating the cryogenic supply chain entirely. Patients in Japan and Germany are adopting these systems for nocturnal oxygen therapy, reducing dependency on cylinder delivery logistics. The technology is consolidating stationary concentrator and portable device categories into single-platform solutions with modular battery configurations.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing cryogenic equipment redesigns toward natural refrigerant alternatives. Manufacturers serving European hospital networks must revalidate vaporization system performance under ammonia or carbon dioxide cycles, extending product development timelines by 18-24 months. German and French procurement authorities are prioritizing compliant systems in new-build hospital tenders, creating specification advantages for early redesign adopters.
Hospital supply chain directors are unbundling equipment procurement from gas supply contracts, reversing decades of bundled sourcing. Acute care facilities in the United States are separating capital equipment acquisition from liquid oxygen or cylinder management agreements, enabling competitive bidding on each cost layer. This pattern is most visible in multi-hospital systems in Texas and Florida where centralized procurement functions have matured sufficient analytical capabilities to evaluate total cost components independently.
Medical Gas Equipment Market Segmentation
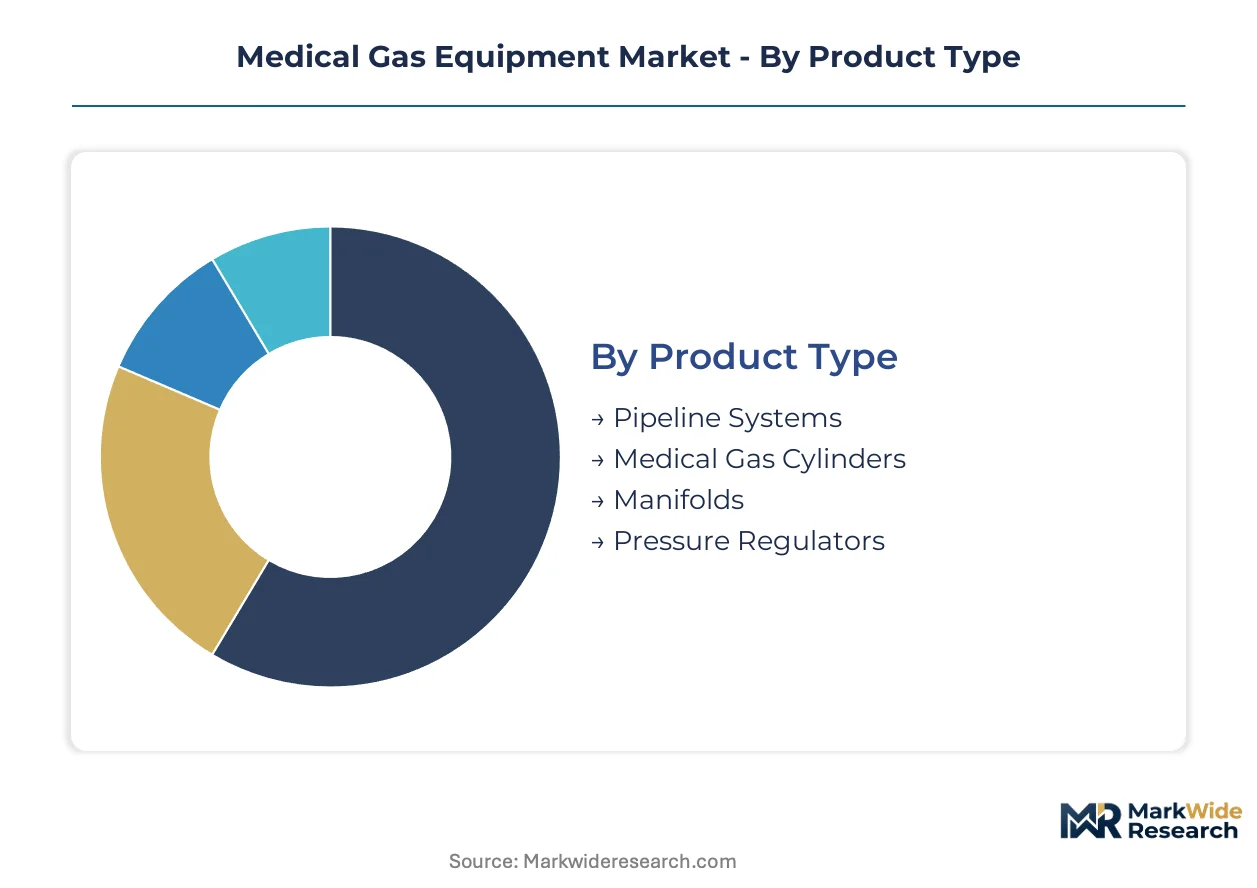
Medical gas equipment segmentation reveals stark differences between centralized infrastructure investments in acute care facilities and distributed portable systems serving post-acute patients. Procurement patterns diverge sharply across these boundaries, with hospital capital committees prioritizing total-cost-of-ownership frameworks while home healthcare purchasers emphasize device portability and subscription service models.
Product Type:
Equipment integration depth varies dramatically: pipeline systems embed permanently into hospital infrastructure while cylinders and regulators function as standalone, replaceable components.
- Pipeline Systems:Centralized copper or stainless steel distribution networks deliver USP-grade oxygen, nitrous oxide, and medical air from bulk storage to bedside outlets through zone valve boxes and alarm panels. Demand concentrates in United States tertiary care expansion projects where Joint Commission accreditation mandates redundant supply architecture and automated failover capabilities.
- Medical Gas Cylinders:Seamless chrome-molybdenum steel or aluminum alloy pressure vessels store therapeutic gases at pressures exceeding 3,000 psi for transportable deployment. German and Japanese home healthcare markets are driving lightweight aluminum cylinder procurement as aging populations manage COPD therapy outside clinical settings, though alloy commodity price volatility compresses manufacturer margins unpredictably.
- Manifolds:Automated cylinder switching assemblies ensure uninterrupted gas flow to critical care areas.
- Pressure Regulators:Precision-machined control devices reduce high-pressure supply to clinically safe delivery thresholds.
Pipeline systems lead volumes today; portable cylinders and regulators are gaining share fastest as post-acute care migrates residential.
Application:
Clinical risk tolerance shapes equipment specification intensity, with life-support applications demanding redundant engineering while routine therapy permits lighter-duty configurations.
- Emergency Care:High-flow oxygen delivery systems and portable resuscitation equipment for trauma bays and ambulance services require rapid-deployment portability and contamination-resistant surfaces.
- Anesthesia:Integrated gas delivery workstations combine precise flow control with scavenging systems and patient monitoring. United States surgical volume recovery is propelling workstation upgrades as hospitals replace aging pneumatic systems with electronic flowmeters under FDA 21 CFR Part 820 quality system mandates.
- Critical Care:Ventilator-compatible gas interfaces and humidification systems for intensive therapy.
- Home Healthcare:Patient-operated concentrators and lightweight cylinders for domiciliary oxygen therapy.
Anesthesia applications anchor revenue concentration; home healthcare shows the steepest expansion trajectory as payors push cost-reducing discharge protocols.
End User:
Capital availability and procurement sophistication create tiered demand patterns, with multi-hospital systems leveraging volume leverage unavailable to independent facilities.
- Hospitals:Acute care facilities with centralized biomedical engineering departments specifying integrated pipeline, bulk storage, and alarm infrastructure. United States health system consolidation is compressing vendor counts as procurement functions centralize across multi-state networks, favoring suppliers with national service capabilities and pre-validated FDA documentation packages.
- Clinics:Outpatient surgical and diagnostic centers requiring modular cylinder-based supply without permanent infrastructure.
- Rehabilitation Centers:Long-term respiratory therapy facilities balancing stationary concentrator deployment with patient mobility needs.
- Medical Offices:Primary care and specialty practices with intermittent procedural gas requirements.
Hospitals dominate absolute spend; clinics and medical offices are expanding most quickly as ambulatory surgical migration accelerates.
Delivery Mode:
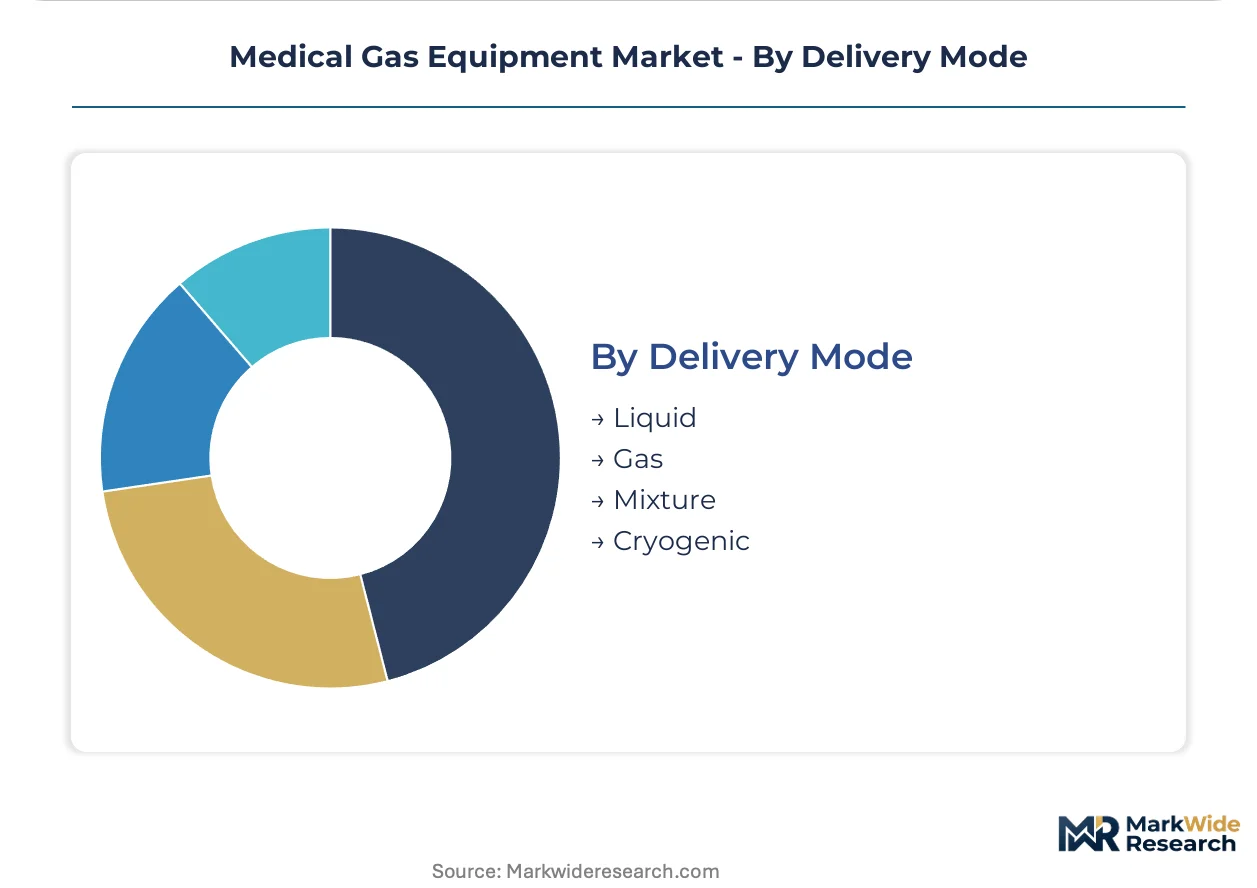
Physical state at point of use determines supply chain architecture, with cryogenic and liquid systems requiring specialized handling infrastructure absent from gas-phase alternatives.
- Liquid:Cryogenic oxygen and nitrogen stored at minus 183 degrees Celsius in vacuum-insulated vessels for high-volume vaporization. German hospital new-build projects under EU Green Deal decarbonization mandates are specifying energy-efficient vaporization systems with natural refrigerant cycles, extending equipment development timelines for compliant suppliers.
- Gas:Compressed therapeutic gases in cylinder or pipeline distribution for immediate clinical use.
- Mixture:Pre-blended helium-oxygen, carbon dioxide-oxygen, and nitrous oxide-oxygen formulations for specialized therapy.
- Cryogenic:Ultra-low temperature preservation systems for biological specimen storage and transport.
Liquid delivery leads installed value in acute settings; gas-phase systems are climbing the fastest as point-of-care generation displaces bulk supply in smaller facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The medical gas equipment industry traces its modern origins to German cryogenic engineering advances in the early twentieth century, with industrial gas specialists in the Ruhr Valley pioneering liquid oxygen vaporization systems that spread to hospital infrastructure worldwide.
United States
Hospital consolidation across Texas and Florida is centralizing procurement functions under multi-state health systems that demand national service capabilities. FDA 21 CFR Part 820 quality system mandates are compelling equipment replacement cycles favoring pre-validated suppliers. The Southeast corridor from Atlanta to Houston anchors bulk storage installation activity as tertiary care expansion accelerates.
Germany
EU Green Deal decarbonization mandates are pivoting hospital procurement toward energy-efficient vaporization systems with natural refrigerant cycles. The F-Gas Regulation's hydrofluorocarbon phasedown extends equipment development timelines by 18-24 months for compliant redesigns. Bavarian and North Rhine-Westphalian hospital networks are prioritizing compliant systems in new-build tenders, creating specification advantages for early adopters.
Japan
Aging demographics are driving portable concentrator adoption for nocturnal oxygen therapy as patients manage COPD outside clinical settings. METI industrial standards govern medical-grade gas purity thresholds and pressure vessel certification. The Kansai region around Osaka concentrates membrane-based concentrator manufacturing as domestic producers consolidate stationary and portable device categories.
India
Government schemes expanding tertiary care capacity in tier-2 and tier-3 cities are creating first-mover advantages for pipeline system installers. CDSCO medical device regulations impose import licensing requirements that favor local assembly partnerships. Maharashtra and Gujarat hospital infrastructure buildouts concentrate demand for bulk oxygen storage as critical care bed capacity scales.
United Kingdom
NHS procurement frameworks are unbundling equipment acquisition from gas supply contracts, enabling competitive bidding on capital components separately from liquid oxygen management. The Medicines and Healthcare products Regulatory Agency enforces EU MDR-aligned standards post-Brexit. London and Southeast England health systems lead analytical procurement sophistication in evaluating total cost components independently.
Medical Gas Equipment Market Vendor Landscape
Premium-margin players sit above commodity-margin players across precision machining depth and regulatory validation capabilities, with consolidated hospital procurement favoring suppliers bearing pre-cleared FDA documentation packages. The vendor base stratifies between integrated industrial gas conglomerates with cryogenic technology legacies, specialized medical device fabricators with anesthesia workstation expertise, and regional cylinder manufacturers competing on alloy sourcing agility. Three archetypes dominate: cryogenic system specialists anchoring European hospital contracts, integrated workstation bundlers capturing surgical suite upgrades, and portable concentrator innovators consolidating home healthcare categories. Competitive repositioning concentrates on M&A to secure national service footprints and vertical integration into precision regulator machining to defend margin predictability against alloy volatility.
Among integrated industrial gas conglomerates, Air Liquide and Linde occupy positions spanning cryogenic storage through distribution network operation, with the former leveraging French cryogenic engineering origins and the latter extending German industrial gases expertise across medical-grade production networks. Dragerwerk exemplifies the integrated workstation archetype through its Lübeck-based GmbH structure. Taiyo Nippon Sanso Corporation represents Japanese industrial gas consolidation with Tokyo-listed operations. Allied Healthcare Products and Ohio Medical sit within the specialized medical device fabricator tier, with St. Louis and Cleveland origins respectively indicating Midwestern US manufacturing concentration. Amico Corporation's Canadian Co. structure and GCE Group's European S.A. formation round out geographic diversification across the competitive set.
| Leading Market Players |
|---|
| Allied Healthcare Products |
| Amico Corporation |
| Air Liquide |
| Dragerwerk |
| Taiyo Nippon Sanso Corporation |
| Atlas Copco Group |
| GCE Group |
| Ohio Medical |
| Linde |
| Others |
Supply Flow & Price Mechanics
Chrome-molybdenum steel alloy indices cascade through medical gas equipment manufacturing, compressing margin structures for cylinder fabricators while amplifying pricing power for cryogenic system specialists with captive metallurgy sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with FDA pre-validated equipment commanding certification premiums and lightweight aluminum cylinders differentiating on alloy grade and portability specifications. Cost compression in economy-tier regulators is intensifying because precision machining talent scarcity elevates labor costs disproportionately. Hospital procurement committees exhibit lowest price sensitivity for pipeline infrastructure where failure risks dominate total-cost-of-ownership calculations, while independent clinics and home healthcare patients drive hardest bargain on portable concentrator subscriptions.
Supply Chain Analysis
Liquid oxygen trucking costs from bulk production facilities to hospital vaporization systems anchor distribution economics, with route density determining competitive viability for regional gas suppliers. Manufacturing concentrates in Germany, Japan, and the United States, where cryogenic engineering heritage and precision machining infrastructure cluster. Production draws from specialized chrome-molybdenum steel mills, CNC machining centers for regulator components, and concentrated refrigerant chemical suppliers. Single-source vulnerability in EPA-regulated alternative refrigerants following Montreal Protocol phase-outs creates input bottlenecks. Distribution runs through hospital GPO contracts, industrial gas distribution networks, and direct-to-patient home healthcare channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between EU Green Deal compliance costs in Germany and unbundled procurement sophistication in the United States, where hospital systems separate capital equipment from gas supply contracts.
For Market Incumbents: Extend cryogenic technology leadership into energy-efficient vaporization systems compliant with EU F-Gas Regulation natural refrigerant mandates, securing specification advantages in Bavarian and North Rhine-Westphalian hospital tenders. Backward integration into precision regulator machining defends margin predictability against chrome-molybdenum alloy volatility. Consolidate national service footprints through selective capability acquisition to meet multi-state health system procurement centralization in Texas and Florida. For New Entrants and Emerging Players: Membrane-based oxygen concentrator platforms offer technology-first wedge into Japanese and German home healthcare markets, where aging demographics and nocturnal oxygen therapy adoption outpace incumbent response. Target tier-2 and tier-3 Indian cities where government tertiary care expansion creates first-mover pipeline installation opportunities ahead of established cryogenic specialists. Pursue CDSCO licensing partnerships to circumvent import barriers while building local assembly credibility. For Investors and Strategic Acquirers: Asymmetric upside sits with precision machining specialists possessing CNC programming expertise and calibration protocols that outpace vocational training pipeline output in mature economies. Five-to-ten year viability favors suppliers with dual FDA and EU MDR documentation capabilities as harmonization friction persists. Watch for inflection signals in hospital procurement unbundling velocity, particularly multi-hospital system analytical maturity separating equipment from gas supply evaluation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Investment | Pre-validated technical documentation packages accelerate approval timelines for Class IIa and IIb gas delivery devices. |
| Natural Refrigerant System Redesign | Ammonia and carbon dioxide vaporization cycles meet EU F-Gas Regulation mandates in German hospital new-build tenders. |
| Remote Monitoring Integration | Pulse oximetry and flow sensor embedding enables predictive maintenance subscriptions for portable concentrator lessors. |
| India Local Assembly Partnership | CDSCO licensing compliance circumvents import restrictions while capturing tier-2 and tier-3 hospital infrastructure buildout. |
| Precision Machining Capability Acquisition | CNC programming and calibration expertise defends regulator margins against alloy commodity volatility and talent scarcity. |
Methodological Framework
Multiple input streams — hospital procurement committee interviews, biomedical engineering director consultations, GPO contracts manager discussions, and industrial gas supply executive briefings — were reconciled against secondary validation from FDA 21 CFR Part 820 filings, EU MDR technical documentation databases, hospital capital expenditure records, and chrome-molybdenum steel trade flow data. Bottom-up equipment shipment analysis and top-down healthcare infrastructure investment tracking were cross-referenced to establish market sizing boundaries.
Data-stream reconciliation across product type, application intensity, end-user capital availability, and delivery mode physical state anchored the analytical framework throughout the projection horizon. CAGRs were derived from segmented demand elasticity modeling and replacement cycle dynamics tied to regulatory mandate timelines. Industry-specific forecast inputs incorporated FDA quality system revision implementation pace, EU Green Deal procurement criteria adoption curves, and home healthcare reimbursement policy evolution.
The model holds under stable regulatory harmonization assumptions; deviation in FDA-MDR documentation convergence or accelerated F-Gas Regulation phasedown timelines would shift competitive positioning and equipment replacement velocity. Forecasts reflect underlying assumptions about chronic respiratory disease prevalence trajectories and hospital consolidation patterns. A model refresh is warranted upon material change in alloy commodity index volatility or cryogenic refrigerant supply concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Cryopreservation Systems Market
Medical Equipment
Global Indirect Calorimeter Market
Medical Equipment
Global Blood Viscometer Market
Medical Equipment
Global Carbon Dioxide Incubators Market
Medical Equipment
Medical Equipment Reimbursement Market
Medical Equipment
Hospital Stretchers Market
Medical Equipment
Global Hospital Equipment and Supplies Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Europe Medical Equipment Maintenance Market
Medical Equipment
Global Single-Arm Medical Pendant Market
Medical Equipment
US Radiotherapy Market
Medical Equipment
Global Countertop Platelet Incubator Market
Medical Equipment
North America Medical Device Reprocessing Market
Medical Equipment
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market
Medical Equipment
Global Surgical Table Market
Medical Equipment
Dial Thermometers Market