
 Homecare Oxygen Concentrators Market | 2026-2036
Homecare Oxygen Concentrators Market Size, Share, and Industry Trends Forecast 2026-2036
Homecare Oxygen Concentrators Market Analysis
The durable medical equipment channel is narrowing as direct-to-consumer platforms and online retail gain traction. Inogen, Inc. specializes in portable oxygen concentrators with pulse dose technology, sustaining brand loyalty among mobile patients. Koninklijke Philips N.V. leverages its respiratory care heritage to dominate hospital-to-home transitions. ResMed Inc. competes through integrated digital health ecosystems that extend beyond hardware sales.
Homecare oxygen concentrators are electromechanical devices that separate oxygen from ambient air through pressure swing adsorption or membrane filtration, delivering concentrated oxygen at flow rates typically ranging from 0.5 to 10 liters per minute for patients with chronic respiratory insufficiency. Portable concentrators now lead product type growth as lithium-ion battery improvements enable true ambulatory therapy, while stationary concentrators retain margin pools through long-term rental contracts with home medical equipment providers. Pulse dose technology captures the fastest expansion within technology segments by reducing power consumption and extending battery life for active users.
The FDA regulates these devices as Class II medical products under 21 CFR 868.5590, requiring 510(k) premarket notification for substantial equivalence, while ISO 80601-2-69 establishes particular safety and performance requirements for oxygen concentrator equipment. The EU Medical Device Regulation imposes stricter clinical evaluation and post-market surveillance obligations that reshape competitive access across European markets. Stakeholders must monitor reimbursement code revisions by Medicare and parallel national health systems, as coverage determinations directly influence patient access and manufacturer pricing power.
Market Dynamics
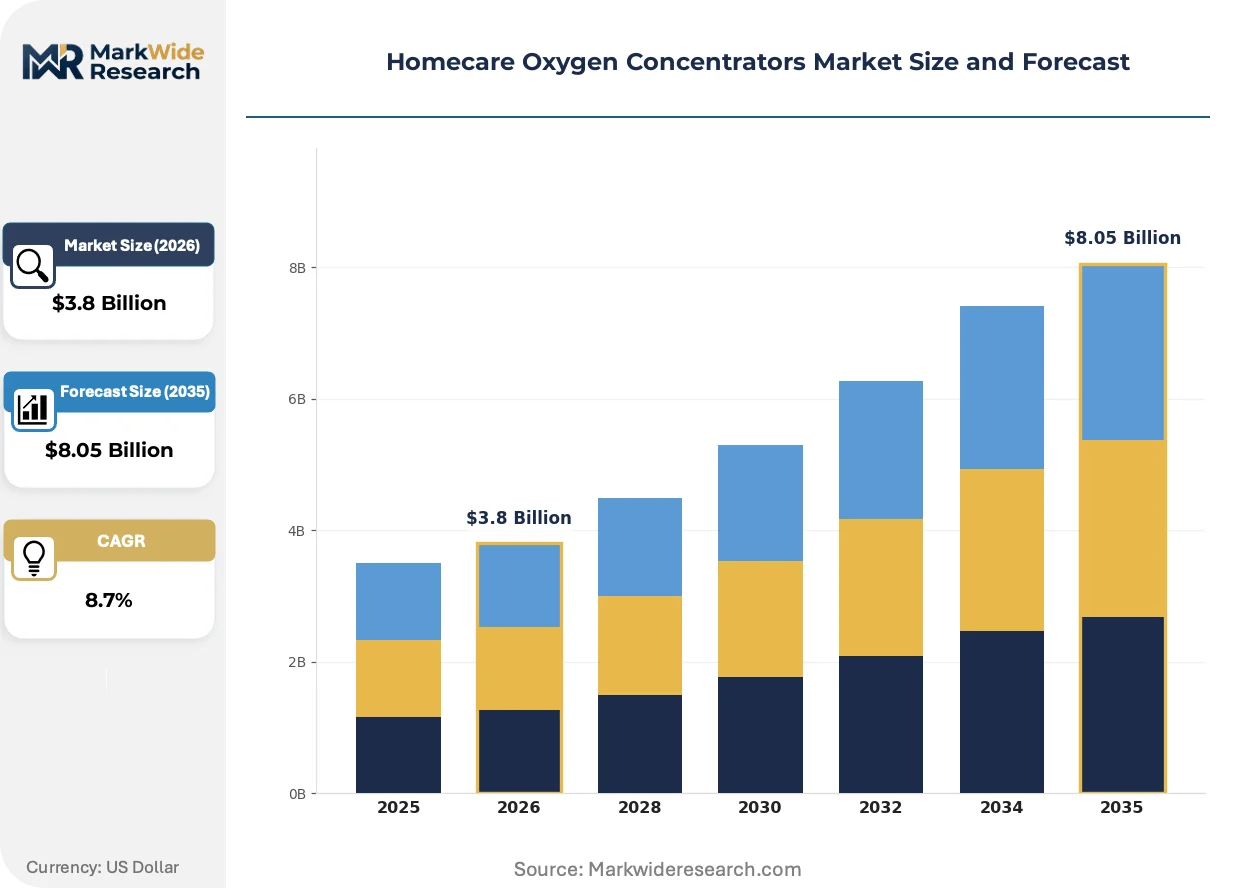
Pulse dose oxygen delivery is compressing stationary concentrator rentals as ambulatory patients demand mobility-equivalent therapy. Lithium-ion energy density gains enable this shift while Medicare reimbursement recalibration threatens legacy rental economics.
Growth Catalysts
- COPD prevalence expansion:Aging populations in the United States, Germany, and Japan expand the addressable patient base for long-term oxygen therapy.
- FDA 510(k) pathway efficiency:Substantial equivalence determinations accelerate product iteration cycles compared to de novo classification routes.
- Pulse dose technology maturation:Reduced power draw extends portable unit battery life, enabling true daytime ambulation without cylinder backup.
Market Restraints
- Lithium supply concentration:Battery raw material sourcing from limited geographies creates input cost volatility for portable unit manufacturers.
- Stationary rental contract lock-in:Home medical equipment providers hold multi-year Medicare Part B agreements that resist portable substitution.
- EU MDR clinical evaluation burdens:Stricter post-market surveillance obligations extend European market access timelines and compliance costs.
Strategic Opportunities
- Direct-to-consumer channel emergence:Online retail platforms bypass traditional durable medical equipment intermediaries, capturing margin and patient data.
- Digital health ecosystem integration:Remote monitoring convergence with pulse oximetry and adherence tracking creates subscription revenue layers beyond hardware.
- Japan's super-aged society:METI reimbursement frameworks for home-based respiratory care expand faster than Western equivalents.
Industry Challenges
- ISO 80601-2-69 testing complexity:Electromagnetic compatibility and alarm system validation extend engineering development cycles.
- Biomedical technician scarcity:Field service capacity constraints limit rapid deployment and maintenance scaling for direct-to-consumer models.
- Legacy EMR integration friction:Hospital-to-home data handoff protocols remain non-standardized, complicating continuity-of-care claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homecare Oxygen Concentrators Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Concentrators, Stationary Concentrators, Liquid Oxygen Systems, Others End User: Home Users, Hospitals, Nursing Homes, Rehabilitation Centers Technology: Pressure Swing Adsorption, Membrane Technology, Continuous Flow, Pulse Dose Distribution Channel: Direct Sales, Online Retail, Medical Supply Stores, Third-Party Distributors |
| Companies Covered | Inogen, Inc., Koninklijke Philips N.V., Invacare Corporation, CAIRE Inc., Drive DeVilbiss Healthcare, ResMed Inc., Chart Industries, Inc., Nidek Medical Products, Inc., GCE Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homecare Oxygen Concentrators Market Emerging Trajectories
Oxygen concentrator architecture is bifurcating between ultra-portable pulse dose units and connected stationary systems with predictive maintenance. This divergence reflects competing patient mobility demands and provider risk-management priorities.
Membrane filtration technology is hybridizing with pressure swing adsorption in next-generation portable units. Active patients with moderate flow requirements adopt these lighter systems for air travel and daily ambulation. The convergence is compressing the performance gap between portable and stationary delivery, threatening rental-based revenue models.
The EU Medical Device Regulation imposes clinical evaluation and post-market surveillance obligations that reshape competitive access. European notified bodies face capacity constraints, extending certification timelines for non-incumbent manufacturers. Smaller innovators are responding by prioritizing FDA 510(k) clearance first, deferring European commercialization.
Patient acquisition is migrating from physician referral to direct online research and purchase. Search-optimized educational content and telehealth prescription pathways disintermediate traditional home medical equipment dealers. This channel shift is most visible in the United States, where high-deductible health plans increase price transparency sensitivity among commercially insured patients.
Homecare Oxygen Concentrators Market Segmentation
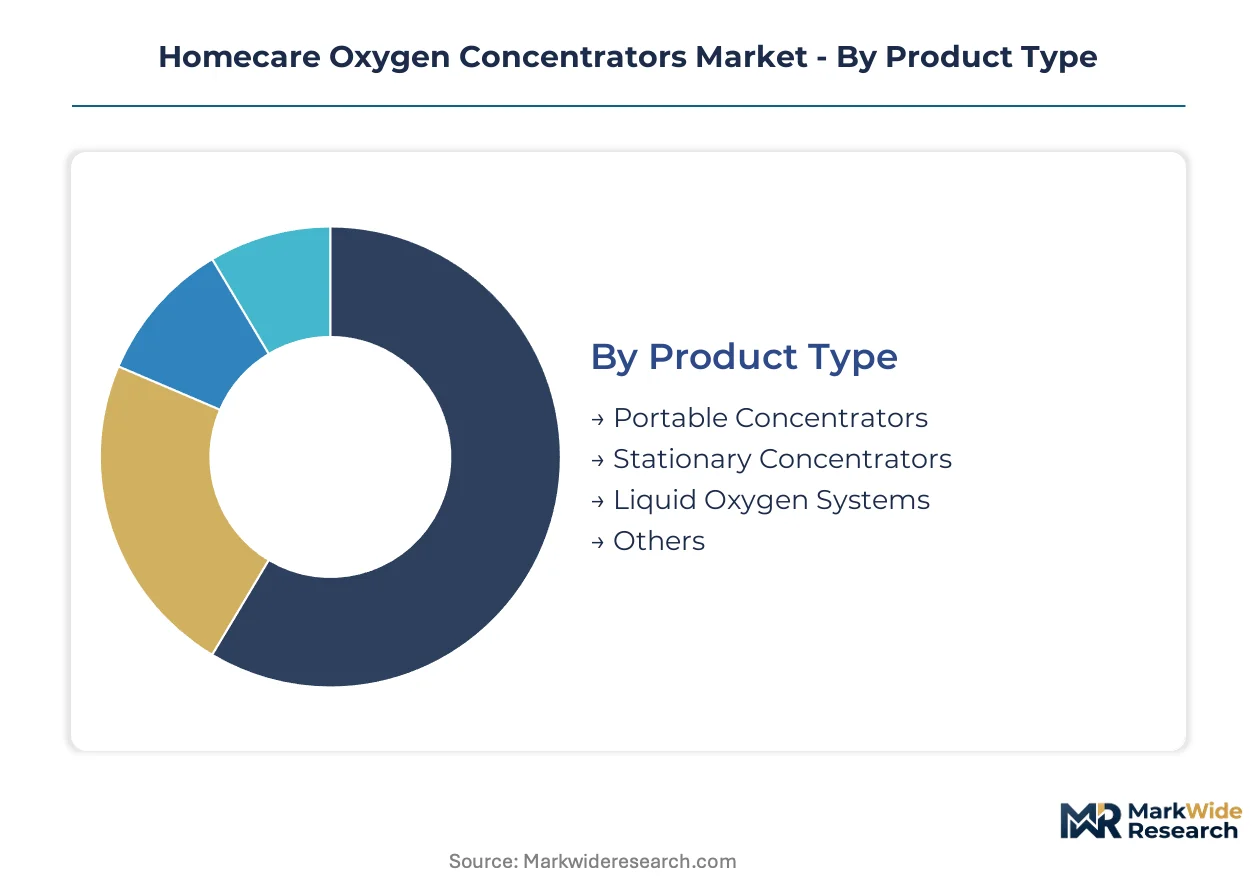
Segmentation reveals divergent service intensity profiles across the homecare oxygen concentrator landscape. Portable systems demand rapid field response for battery and mobility component failures, while stationary installations require scheduled preventive maintenance over multi-year rental contracts.
Product Type:
After-sales service intensity varies dramatically across product architectures, with portable units requiring frequent battery replacement cycles and mobile component servicing compared to stationary systems.
- Portable Concentrators:Lithium-ion powered pulse dose systems weigh under five pounds for daytime ambulation. Demand clusters among COPD patients in the United States seeking Medicare Part B reimbursement for travel-capable therapy, though battery degradation drives recurring service touchpoints.
- Stationary Concentrators:Pressure swing adsorption units delivering continuous flow up to ten liters per minute anchor long-term rental economics. German home medical equipment providers favor these for elderly patients with limited mobility, locking in predictable maintenance schedules.
- Liquid Oxygen Systems:Cryogenic reservoir-based delivery for high-flow requirements in nursing home settings.
- Others:Transfill systems and hybrid concentrator-cylinder combinations for specialized respiratory protocols.
By volume, stationary concentrators lead. By growth pace, portable units are gaining share fastest.
End User:
Customer type determines procurement authority and reimbursement pathway complexity, from direct patient purchase to institutional capital budgeting.
- Home Users:Individual patients with chronic respiratory insufficiency purchase or rent through Medicare Part B, private insurance, or out-of-pocket. Japanese METI reimbursement frameworks accelerate adoption among super-aged households seeking to avoid institutionalization.
- Hospitals:Discharge planning departments coordinate hospital-to-home transitions, favoring suppliers with integrated digital health platforms for remote monitoring.
- Nursing Homes:Long-term care facilities with centralized oxygen piping infrastructure.
- Rehabilitation Centers:Post-acute facilities managing temporary oxygen weaning protocols.
Home users generate the highest unit volume. Hospitals command the steepest expansion trajectory through bundled payment incentives.
Technology:
Underlying separation mechanism and delivery mode dictate power consumption, device weight, and clinical applicability across patient mobility levels.
- Pulse Dose:Bolus oxygen delivery synchronized with inhalation reduces power draw by sixty percent versus continuous flow. Active patients in the United States and Japan adopt these systems for air travel compatibility and daytime ambulation without cylinder backup.
- Pressure Swing Adsorption:Zeolite molecular sieve technology separates nitrogen from ambient air through cyclic pressure swings. This mature platform dominates stationary installations where electrical outlet access is assured and flow consistency outweighs portability.
- Membrane Technology:Polymer fiber filtration for lightweight portable applications with moderate flow requirements.
- Continuous Flow:Uninterrupted oxygen delivery for nocturnal use and patients unable to trigger pulse systems.
Pressure swing adsorption retains installed base dominance. Pulse dose is climbing the fastest among ambulatory patient segments.
Distribution Channel:
Channel selection determines margin capture, patient data ownership, and speed of prescription fulfillment.
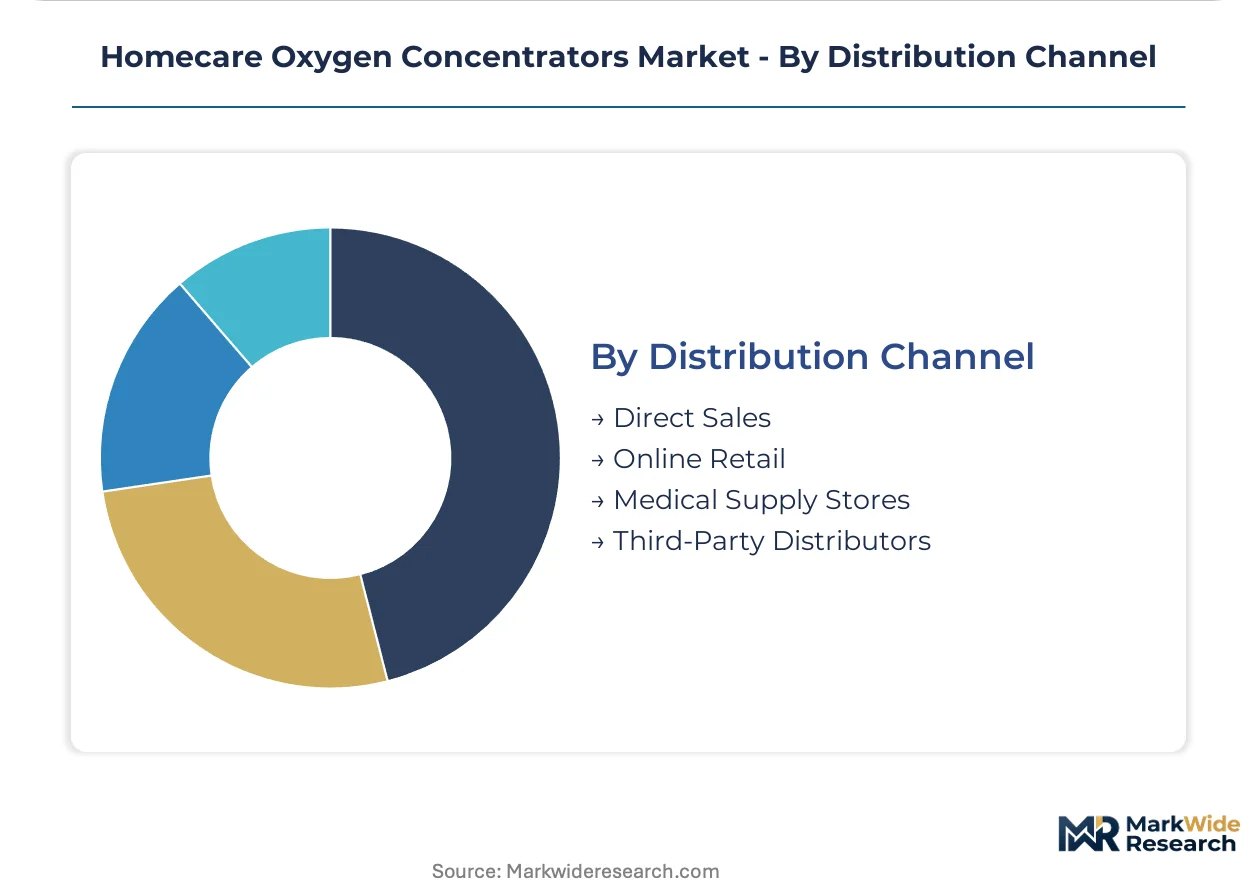
- Online Retail:Direct-to-consumer platforms bypass durable medical equipment intermediaries, capturing margin and adherence data. United States commercially insured patients with high-deductible plans drive this channel through price transparency and telehealth prescription integration.
- Direct Sales:Manufacturer field representatives contract with hospital discharge planners and pulmonology practices. This channel preserves clinical relationships and supports complex product configuration for high-acuity patients.
- Medical Supply Stores:Local brick-and-mortar providers offering same-day pickup and hands-on training.
- Third-Party Distributors:Regional wholesalers serving rural geographies and small independent home medical equipment dealers.
Third-party distributors move the highest unit volume. Online retail is expanding most quickly among digitally native patient cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany while Japanese manufacturers absorb compressed margins from METI reimbursement recalibration. Medicare Part B fee schedules in the United States sustain premium portable unit economics that European equivalents cannot match.
United States
COPD prevalence among Medicare beneficiaries and commercial high-deductible plan proliferation drive portable concentrator adoption through direct-to-consumer channels. FDA 510(k) clearance pathways accelerate product iteration cycles compared to de novo routes. California and Florida clusters concentrate home medical equipment providers managing hospital-to-home discharge volumes.
Germany
Super-aged household demographics and statutory health insurance long-term oxygen therapy coverage anchor stationary concentrator rental demand. EU MDR clinical evaluation obligations through notified bodies in Berlin and Munich extend market access timelines for non-incumbent manufacturers. Bavaria hosts precision engineering suppliers serving PSA component fabrication.
Japan
METI reimbursement frameworks for home-based respiratory care expand faster than Western equivalents as super-aged society pressures institutionalization avoidance. PMDA medical device regulations align with international harmonization initiatives while maintaining domestic clinical trial requirements. Osaka-Kobe industrial corridors concentrate lithium-ion battery pack assembly for portable unit supply chains.
United Kingdom
NHS England home oxygen service contracts consolidate procurement authority around regional clinical commissioning groups. MHRA post-Brexit regulatory autonomy maintains EU MDR equivalence recognition while streamlining UKCA marking pathways. Greater Manchester and West Midlands clusters house durable medical equipment distribution hubs serving aging industrial belt populations.
India
Chronic respiratory disease burden among urban pollution-exposed populations and expanding private health insurance penetration create addressable demand beyond government hospital provision. CDSCO medical device rules under Drugs and Cosmetics Act implementation tighten quality standards for imported concentrators. Gujarat and Maharashtra industrial corridors host contract manufacturers serving export markets.
Homecare Oxygen Concentrators Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying zeolite molecular sieves, compressor assemblies, and lithium-ion power management modules. The vendor base organizes around three archetypes: diversified respiratory care conglomerates with hospital-to-home service networks, pure-play portable concentrator innovators, and contract manufacturers serving private-label distributors. Consolidation pressure concentrates among mid-scale regional players lacking FDA clearance portfolios or direct-to-consumer fulfillment infrastructure. Dominant competitive moves include strategic partnerships with telehealth platforms and backward integration into battery cell sourcing.
Within the diversified respiratory care tier, Koninklijke Philips N.V. and ResMed Inc. exemplify platform integrators leveraging hospital discharge relationships and digital health ecosystems to extend beyond hardware margins. Inogen, Inc. occupies a position among pure-play portable specialists, its corporate structure reflecting concentrated focus on ambulatory patient mobility solutions. These three entities represent contrasting strategic postures: conglomerate breadth versus specialist depth, integrated service networks versus direct-to-consumer agility.
| Leading Market Players |
|---|
| Inogen, Inc. |
| Koninklijke Philips N.V. |
| Invacare Corporation |
| CAIRE Inc. |
| Drive DeVilbiss Healthcare |
| ResMed Inc. |
| Chart Industries, Inc. |
| Nidek Medical Products, Inc. |
| GCE Group |
| Others |
Supply Flow & Price Mechanics
Lithium supply concentration in Chile, Argentina, and Australia generates input cost volatility that compresses portable unit margins while widening the premium spread between FDA-cleared and uncertified stationary systems. This geographic dependency forces manufacturers to absorb commodity swings or push pricing tier differentiation, reshaping procurement toward long-term offtake contracts and captive battery assembly.
Pricing Analysis
The customization-premium spread separates configured-to-order pulse dose systems from standard stationary rentals. Three-tier pricing structure across premium, standard, and economy levels tracks FDA 510(k) clearance status and ISO 80601-2-69 certification grade. Cost compression in economy tiers is intensifying because Medicare reimbursement recalibration narrows rental yields. Home users with high-deductible commercial plans exhibit the highest price sensitivity, while hospital discharge departments prioritize clinical integration over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk for lithium-ion battery pack sourcing. Component fabrication concentrates in China, South Korea, and Japan, with zeolite molecular sieves drawing from specialized chemical processors in Germany and the United States. Single-source vulnerability for compressor assemblies creates chokepoint exposure. Distribution runs through third-party durable medical equipment providers, though direct-to-consumer platforms are capturing margin upstream.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering talent scarcity for ISO 80601-2-69 electromagnetic compatibility validation and FDA 510(k) submission expertise constrains product iteration velocity, favoring incumbents with established regulatory affairs infrastructure.
For Market Incumbents: Build certification moats by securing FDA 510(k) clearances for next-generation pulse dose architectures before EU MDR clinical evaluation obligations extend European timelines. Backward integration into lithium-ion battery cell sourcing reduces input cost volatility. Capture hospital-to-home transition workflows through embedded remote monitoring software to lock out substitute platforms. For New Entrants and Emerging Players: Direct-to-consumer online retail channels in the United States represent the most penetrable entry point, bypassing entrenched durable medical equipment rental contracts. Telehealth-integrated prescription pathways disintermediate traditional home medical equipment dealers. Target price-sensitive commercially insured patients with high-deductible plans through search-optimized educational content and transparent out-of-pocket pricing. For Investors and Strategic Acquirers: The market sits at a substitution-acceleration phase that favors pure-play portable specialists with direct-to-consumer fulfillment infrastructure over diversified respiratory conglomerates tethered to rental economics. Acquisition candidates with FDA clearance portfolios and lithium battery assembly capabilities offer superior long-term viability. Monitor Medicare Part B reimbursement recalibration announcements as the primary inflection signal for rental model compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Premarket notification pathways compress product launch timelines versus de novo classification routes. |
| CE Marking Pathway Investment | EU MDR clinical evaluation obligations through notified bodies reshape competitive access timelines. |
| Hospital System Partnership | Discharge planning integration captures bundled payment incentives for hospital-to-home transitions. |
| Software Companion Development | Remote monitoring convergence with pulse oximetry creates subscription revenue beyond hardware sales. |
| Reimbursement Strategy Optimization | Medicare Part B fee schedule alignment determines patient access and manufacturer pricing power. |
Methodological Framework
Desk research of FDA 510(k) clearance databases, ISO standards documentation, and CMS Medicare reimbursement filings preceded structured interviews with biomedical engineers, hospital purchasing committee members, home medical equipment provider operations directors, and GPO contracts managers. Secondary validation drew from SEC 10-K respiratory care segment disclosures, notified body certification registries, and lithium supply chain trade data. Bottom-up patient population modeling and top-down equipment replacement cycle analysis were triangulated.
Assumptions held COPD prevalence trajectories and Medicare Part B fee schedules fixed across the analysis window, while lithium commodity pricing and EU MDR notified body capacity were treated as variable inputs. Segmentation modeling tracked product type, technology mechanism, end user procurement authority, and distribution channel. CAGRs were derived from equipment replacement cycles, patient cohort expansion, and reimbursement elasticity estimates. Pulse dose adoption curves and battery energy density improvement rates informed portable unit projections.
Practitioners should monitor lithium carbonate spot price movements, FDA 510(k) clearance backlog durations, and Medicare reimbursement recalibration announcements for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Senior in-Home Care Services Market
Home Healthcare
UK Home Healthcare Market
Home Healthcare
Germany Home Healthcare Market
Home Healthcare
Chemotherapy at Home Services Market
Home Healthcare
Canada Home Healthcare Market
Home Healthcare
Outpatient Home Therapy Market
Home Healthcare
Home Care Service Market
Home Healthcare
Global Nursing Care Market
Home Healthcare
Smart Home Healthcare Market
Home Healthcare
Elderly Care Apps Market
Home Healthcare
Smart Pillow Market
Home Healthcare
Home Care Products Market
Home Healthcare
Adult Day Care Market
Home Healthcare
Smart Mattress Market
Home Healthcare
US House Calls Market
Home Healthcare
Home Care Market