
 ECG Equipment and Management Systems Market | 2026-2036
ECG Equipment and Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
ECG Equipment and Management Systems Market Intelligence
China is tilting toward domestic manufacturing of digital ECG systems through MIIT-backed medical device industrial parks. GE Healthcare leverages vertical integration in sensor fabrication to sustain cost advantages across portable monitor lines. Koninklijke Philips N.V. anchors its position through wireless ECG technology leadership in European hospital networks. Nihon Kohden Corporation dominates high-precision analogue-to-digital conversion modules for stress testing systems in Japanese diagnostic centers.
ECG equipment and management systems encompass electrocardiographic devices that capture, amplify, and record electrical activity from the heart surface through electrodes placed at standardized anatomical positions, typically sampling at 500 Hz with 12-lead configurations for diagnostic-grade resolution. These systems serve cardiology departments, emergency response units, and remote monitoring services by enabling arrhythmia detection, ischemia assessment, and longitudinal cardiac surveillance. Wireless ECG and cloud-based systems are capturing the fastest expansion as telemedicine reimbursement codes mature and hospital-at-home programs proliferate. Portable ECG maintains the largest installed base but faces margin compression from commoditized hardware. Holter monitors occupy a stable niche in ambulatory arrhythmia diagnosis where extended wear duration differentiates clinical utility.
FDA 510(k) clearance pathways and the EU MDR recertification timeline are reshaping product development cycles and market access requirements for device manufacturers. HIPAA in the United States and GDPR in Europe impose divergent data governance obligations on cloud-based ECG platforms that transmit patient biomarkers across jurisdictions. ISO 13485 quality management standards and IEC 60601-2-25 electrical safety specifications form baseline compliance thresholds for international commercialization. Stakeholders must monitor regulatory divergence between FDA digital health pre-certification pilots and EMDR conformity assessment procedures when allocating R&D budgets across geographic markets.
Market Dynamics
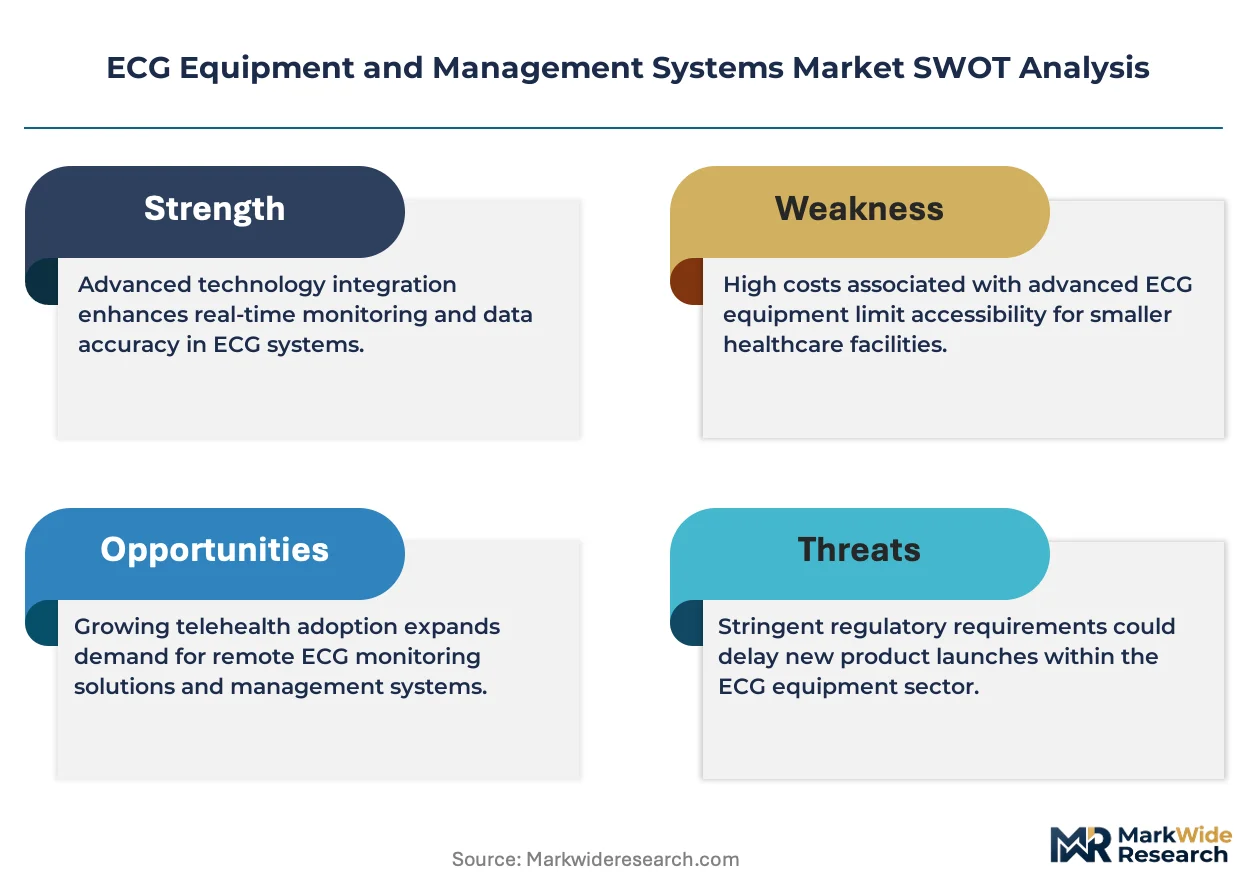
Wireless telemetry protocols are compressing the installed base of wired ECG systems while cloud-native diagnostic platforms reconfigure hospital procurement around subscription-based clinical decision support rather than capital equipment ownership.
Growth Catalysts
- CMS Remote Patient Monitoring Reimbursement:United States hospital systems expand ambulatory monitoring programs to avoid readmission penalties under Medicare reimbursement rules, accelerating wireless ECG deployment in transitional care settings.
- Cloud-Based Diagnostic Integration:German cardiology networks embed cloud-native ECG interpretation platforms into statutory health insurance workflows, reducing specialist interpretation bottlenecks in outpatient arrhythmia screening.
- MIIT Industrial Park Development:China's Ministry of Industry and Information Technology funds domestic manufacturing clusters for digital ECG device production, building captive supply chains for semiconductor and electrode components.
Market Restraints
- Precious Metal Electrode Costs:Silver-silver chloride electrode prices fluctuate with commodity markets, compressing margins on disposable consumables that dominate Holter monitor operating economics.
- EU MDR Recertification Burden:European Medical Device Regulation conformity assessment timelines extend product launch cycles by 18-24 months for Class IIa diagnostic ECG systems, freezing incremental innovation in European markets.
- Smartwatch ECG Substitution:Consumer-grade photoplethysmography and single-lead ECG in Apple Watch and Samsung Galaxy devices capture low-acuity screening demand that previously flowed to clinical-grade Holter systems.
Strategic Opportunities
- Hospital-at-Home Program Expansion:United States acute care systems deploy wireless ECG telemetry for post-discharge cardiac monitoring, capturing reimbursement under CMS Hospital-at-Home waivers that bypass traditional facility fees.
- AI-Assisted Interpretation Convergence:Machine learning arrhythmia classification algorithms integrate with cloud ECG platforms to reduce false-positive rates in atrial fibrillation screening programs.
- Subscription Revenue Migration:Device manufacturers pivot from hardware sales to per-study pricing models for cloud-based ECG interpretation services, locking recurring revenue from health system customers.
Industry Challenges
- Cross-Border Data Governance Friction:HIPAA and GDPR impose incompatible patient consent and data localization requirements on cloud ECG platforms transmitting cardiac biomarkers across United States-European jurisdictions.
- IEC 60601-2-25 Certification Complexity:Electrical safety testing for diagnostic ECG systems requires specialized EMC laboratories with limited global capacity, creating bottlenecks for new market entrants.
- Legacy System Interoperability:Hospital information systems with proprietary HL7 v2 interfaces resist seamless integration with cloud-native ECG platforms, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ECG Equipment and Management Systems Market |
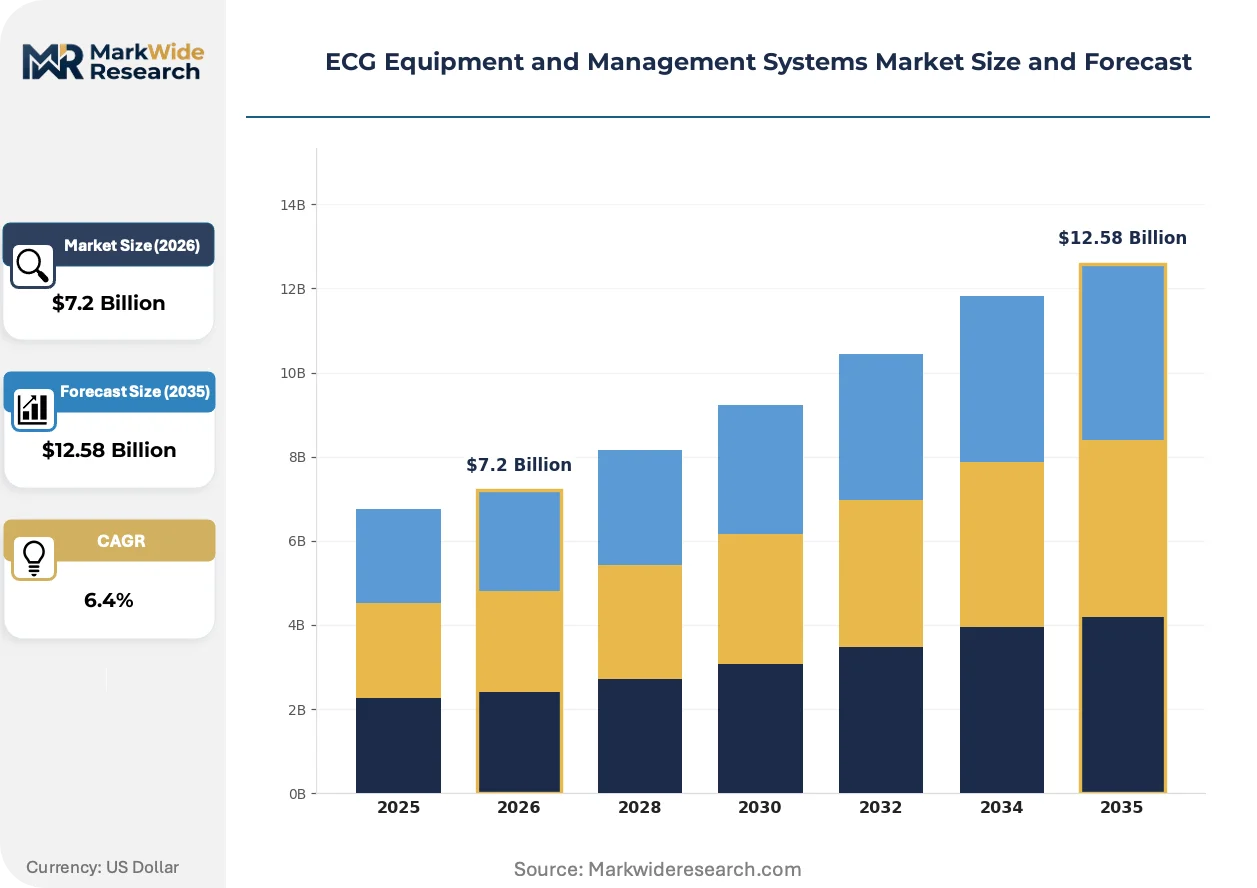
| Market Size in 2026 | $7.2 Billion |
| Market Size in 2035 | $12.58 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable ECG, Stress ECG, Holter Monitors, Cardiac Event Monitors Technology: Analogue ECG, Digital ECG, Wireless ECG, Cloud-Based Systems End User: Hospitals, Clinics, Homecare Settings, Diagnostic Centers Application: Cardiology, Telemedicine, Emergency Care, Remote Monitoring |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Nihon Kohden Corporation, Mindray Medical, BioTelemetry, Inc., Schiller AG, Hill-Rom, CompuMed, Inc., Spacelabs Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ECG Equipment and Management Systems Market Strategic Shifts & Innovations
Signal processing architectures are converging with artificial intelligence inference engines while regulatory frameworks force recalibration of product development roadmaps across major commercial markets.
Multi-lead ECG acquisition hardware is hybridizing with edge-computing inference chips that execute real-time arrhythmia detection without cloud connectivity. Emergency medical services in North American metropolitan systems adopt these hybrid devices for pre-hospital stroke and myocardial infarction triage. The technology is hybridizing capital equipment and consumables business models into unified per-patient episode pricing.
The European Union Medical Device Regulation (MDR) recertification timeline compresses viable product lifecycles for legacy ECG systems that lack clinical evidence packages meeting post-market surveillance requirements. Manufacturers face portfolio rationalization decisions between investing in MDR technical documentation or withdrawing from European markets. High-precision stress testing systems with analogue-to-digital conversion modules face the steepest conformity assessment burdens due to their Class IIa risk classification.
Health system purchasing committees now bundle ECG hardware procurement with multi-year cloud platform subscriptions, displacing traditional capital equipment RFP processes. Group purchasing organizations negotiate enterprise-wide telemetry contracts that span inpatient, ambulatory, and remote monitoring settings. This concentration is most visible in United States integrated delivery networks consolidating vendor relationships under single-source agreements covering diagnostic cardiology service lines.
ECG Equipment and Management Systems Market Segmentation
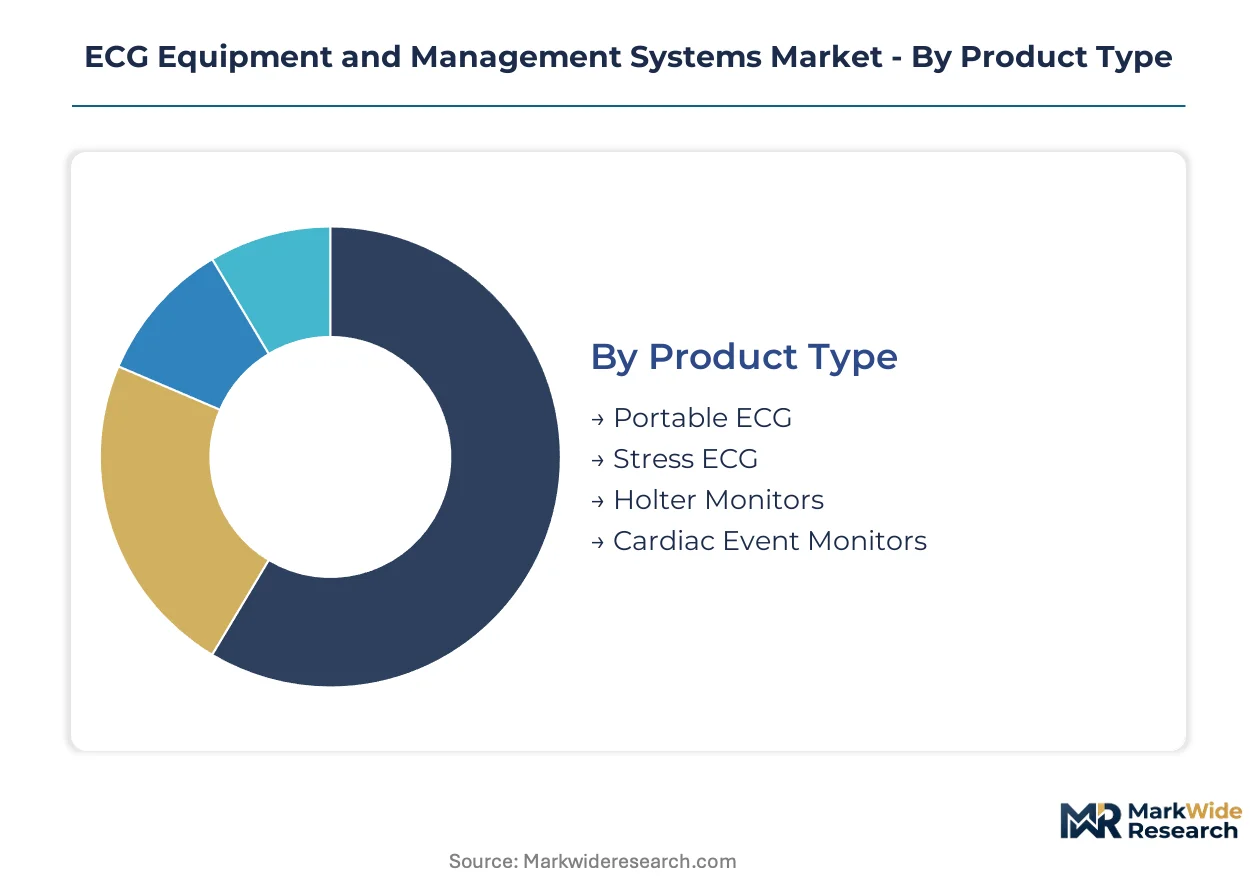
ECG equipment segmentation reflects divergent procurement logics across acute care, ambulatory, and consumer-adjacent settings. Technology choices cascade into reimbursement eligibility, regulatory classification, and service revenue models.
Product Type:
Use-case spectrum spans bedside diagnosis, exercise physiology, extended ambulatory surveillance, and intermittent symptom correlation.
- Portable ECG:Battery-powered devices with integrated displays enable point-of-care acquisition in emergency departments and physician offices. Demand concentrates in United States integrated delivery networks consolidating diagnostic cardiology service lines under single-source agreements. These systems maintain the largest installed base but face margin compression from commoditized hardware.
- Holter Monitors:Wearable recorders capture 24-48 hours of continuous rhythm data via 3-12 lead configurations for ambulatory arrhythmia detection. German statutory health insurance workflows embed these into outpatient screening programs, reducing specialist interpretation bottlenecks. Extended wear duration differentiates clinical utility from consumer-grade alternatives.
- Stress ECG:Treadmill or pharmacologic stress testing systems with high-precision analogue-to-digital conversion modules.
- Cardiac Event Monitors:Patient-activated or auto-triggered devices for intermittent symptom correlation over weeks to months.
Established volume favors Portable ECG; emerging adoption favors Holter Monitors.
Technology:
Signal processing architectures determine connectivity, inference location, and recurring revenue potential.
- Wireless ECG:Bluetooth and proprietary radio protocols transmit real-time waveforms to central monitoring stations or cloud platforms. United States hospital systems deploy these for post-discharge cardiac monitoring under CMS Hospital-at-Home waivers. The segment is expanding most quickly as telemedicine reimbursement codes mature.
- Cloud-Based Systems:Native SaaS platforms host storage, interpretation algorithms, and longitudinal analytics on remote infrastructure. German cardiology networks integrate these into statutory health insurance workflows. Subscription pricing models displace capital equipment ownership.
- Digital ECG:Microprocessor-based acquisition with software-defined filtering and automated measurements.
- Analogue ECG:Legacy galvanometer or thermal array recorders with limited connectivity.
Procurement momentum concentrates in Wireless ECG; Cloud-Based Systems are climbing the fastest.
End User:
Facility type dictates device specification, throughput requirements, and integration complexity.
- Hospitals:Multi-parameter telemetry systems with enterprise IT integration and 24/7 technical support. United States acute care systems anchor demand through integrated delivery network purchasing committees. These facilities bundle hardware procurement with multi-year platform subscriptions.
- Homecare Settings:Simplified devices for patient-operated acquisition with remote clinician oversight. CMS Remote Patient Monitoring reimbursement accelerates deployment in transitional care settings. Hospital-at-home programs proliferate across metropolitan health systems.
- Clinics:Lower-throughput systems for scheduled diagnostic procedures.
- Diagnostic Centers:Specialized stress testing and imaging-correlated ECG services.
Revenue concentration favors Hospitals; patient volume migration favors Homecare Settings.
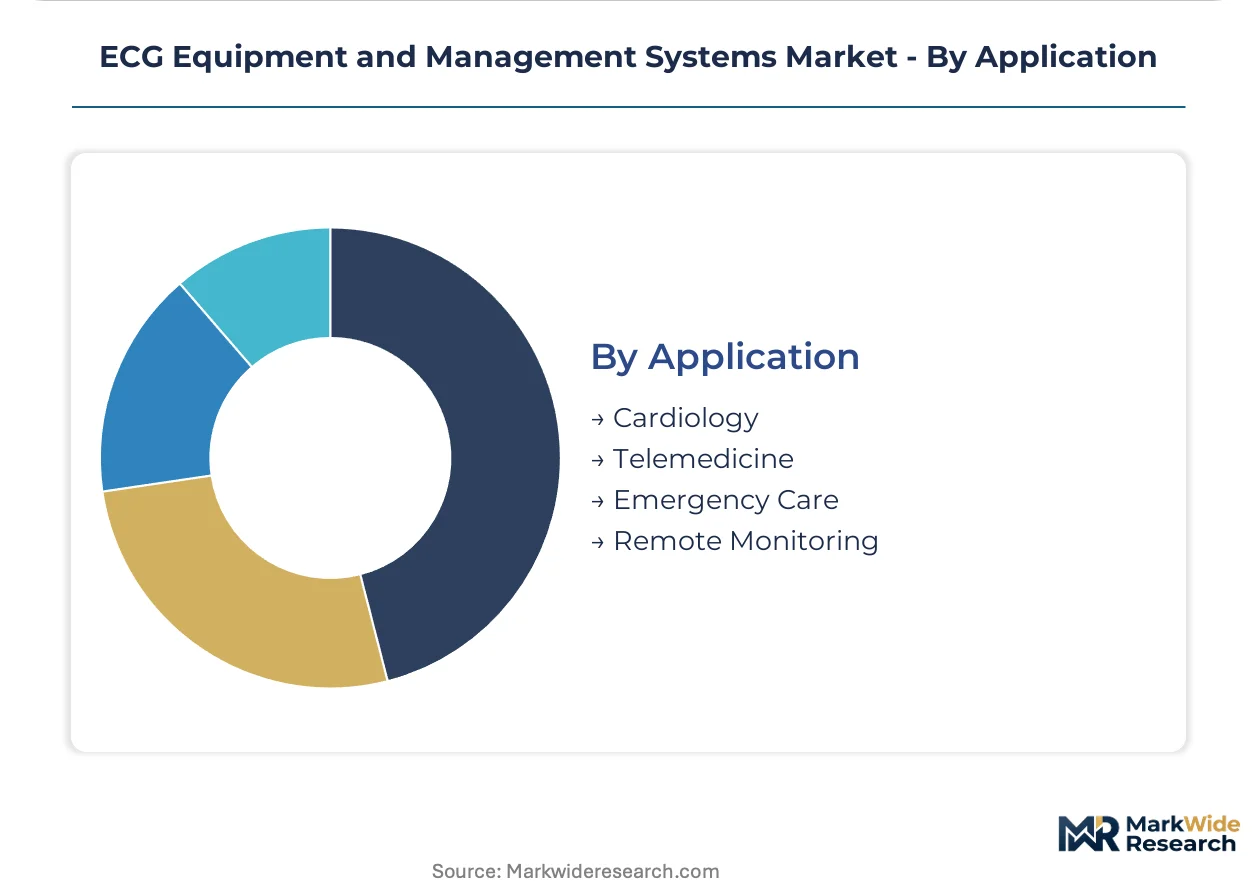
Application:
Clinical context shapes lead configuration, sampling rate, and decision urgency.
- Telemedicine:Asynchronous or synchronous ECG transmission enabling remote specialist consultation. Cloud-native interpretation platforms reduce false-positive rates in atrial fibrillation screening programs. Reimbursement code maturation drives health system investment.
- Emergency Care:Pre-hospital and ED systems requiring rapid ST-elevation detection for myocardial infarction triage. North American metropolitan EMS systems adopt hybrid edge-computing devices for real-time arrhythmia classification without connectivity dependency.
- Cardiology:Comprehensive diagnostic and longitudinal surveillance in specialist practice.
- Remote Monitoring:Extended post-discharge surveillance for heart failure and arrhythmia patients.
Service line integration favors Cardiology; reimbursement innovation favors Telemedicine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA digital health pre-certification pilots and CMS reimbursement rules anchor United States demand, while EU MDR recertification timelines and MIIT industrial park funding reshape competitive access across Atlantic and Pacific markets.
United States
Hospital systems deploy wireless ECG telemetry for post-discharge cardiac monitoring under CMS Hospital-at-Home waivers that bypass traditional facility fees. FDA 510(k) clearance pathways compress product development cycles for Class II diagnostic systems. Integrated delivery networks in metropolitan health systems consolidate vendor relationships under single-source agreements spanning diagnostic cardiology service lines.
Germany
Cardiology networks embed cloud-native ECG interpretation platforms into statutory health insurance workflows, reducing specialist interpretation bottlenecks in outpatient arrhythmia screening. EU MDR conformity assessment procedures extend recertification timelines by 18-24 months for Class IIa diagnostic systems. Medical technology clusters in Baden-Württemberg concentrate high-precision stress testing system manufacturing with analogue-to-digital conversion module specialization.
China
MIIT-backed medical device industrial parks fund domestic manufacturing clusters for digital ECG device production, building captive supply chains for semiconductor and electrode components. NMPA regulatory pathways prioritize innovation approvals for AI-assisted diagnostic software. Manufacturing gravity concentrates in Yangtze River Delta parks where vertical integration into sensor fabrication sustains cost advantages across portable monitor lines.
Japan
Diagnostic centers demand high-precision analogue-to-digital conversion modules for stress testing systems where measurement fidelity determines clinical utility. PMDA quality management standards align with ISO 13485 baseline thresholds for international commercialization. Tokyo-Osaka metropolitan corridors host concentrated procurement committees for multi-parameter telemetry systems with enterprise IT integration requirements.
United Kingdom
NHS long-term plan targets expand remote patient monitoring for heart failure and atrial fibrillation populations, accelerating wireless ECG deployment in community settings. MHRA post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment requirements for device manufacturers. London-Southeast health systems pilot subscription-based clinical decision support models that displace capital equipment ownership structures.
ECG Equipment and Management Systems Market Key Industry Players
Vertically integrated conglomerates and wireless telemetry specialists split the market between hardware scale economies and software recurring revenue capture. Consolidation pressure concentrates among integrated delivery network purchasing committees that negotiate enterprise-wide telemetry contracts. Three archetypes dominate: diversified medical technology conglomerates with sensor fabrication capabilities, pure-play cardiac monitoring specialists with cloud-native platforms, and regional device manufacturers with cost-optimized portable lines. Competitive moves center on backward integration into electrode and semiconductor supply chains and subscription revenue migration from per-unit hardware sales to per-study pricing models.
Among diversified medical technology conglomerates, GE Healthcare and Koninklijke Philips N.V. occupy positions exemplifying vertical integration archetypes, while Nihon Kohden Corporation represents precision instrumentation specialization. These entities anchor competitive dynamics through differential control over upstream component supply and downstream health system purchasing relationships.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Nihon Kohden Corporation |
| Mindray Medical |
| BioTelemetry, Inc. |
| Schiller AG |
| Hill-Rom |
| CompuMed, Inc. |
| Spacelabs Healthcare |
| Others |
Cost & Logistics Intelligence
China's Yangtze River Delta semiconductor foundries and electrode component clusters concentrate upstream manufacturing gravity, directing margin capture toward device OEMs with backward integration into sensor fabrication and captive consumables supply.
Pricing Analysis
German statutory health insurance reimbursement rates for cloud-based ECG interpretation sit 15-20 percent below United States CMS fee schedules for comparable remote monitoring services. Pricing stratifies across premium diagnostic-grade systems with FDA 510(k) clearance and IEC 60601-2-25 certification, standard hospital-grade configurations, and economy portable monitors for emerging market clinics. Cost compression in Holter monitor consumables intensifies as silver-silver chloride electrode commodity volatility squeezes disposable margins. Homecare settings and rural diagnostic centers exhibit highest price sensitivity, while integrated delivery networks in metropolitan United States markets prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Flex, Jabil, and Sanmina hold contract manufacturing capacity for ECG device assembly across Malaysia, Mexico, and Poland facilities serving regional demand clusters. Semiconductor inputs for analogue-to-digital conversion modules draw from Taiwan and South Korea foundries, while silver-silver chloride electrode materials rest on precious metal suppliers in China and Germany. Single-source vulnerability concentrates in high-precision ADC chip supply for stress testing systems. Distribution runs through group purchasing organizations and regional medical device distributors with hospital system integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of FDA-cleared AI-assisted arrhythmia classification algorithms and IEC 60601-2-25 certified manufacturing capacity constrains competitive entry, privileging incumbents with established regulatory dossiers and specialized EMC laboratory relationships.
For Market Incumbents: Insulate cloud-native platform revenue by embedding AI interpretation services into multi-year hospital system subscriptions, reducing churn risk from hardware commoditization. Deepen backward integration into electrode semiconductor fabrication to offset silver price volatility and defend consumables margins against emerging Asian competitors. For New Entrants and Emerging Players: Establish a beachhead in United States hospital-at-home program telemetry contracts, where CMS reimbursement waivers create procurement flexibility outside traditional GPO structures. Target mid-sized integrated delivery networks lacking enterprise-wide ECG standardization as initial reference customers, then scale through subscription pricing models that displace capital equipment RFP processes. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed cardiac monitoring specialists holding cloud platform subscriptions but lacking AI development capabilities. Long-term viability hinges on software recurring revenue ratio and regulatory clearance breadth across FDA, CE marking, and NMPA jurisdictions. Watch FDA digital health pre-certification pilot expansion as inflection signal for accelerated product development cycles.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Interpretation Development | Machine learning arrhythmia classification reduces false-positive rates in atrial fibrillation screening programs. |
| Hospital System Partnership | Single-source agreements with integrated delivery networks lock recurring revenue across inpatient and ambulatory settings. |
| CE Marking Pathway Investment | EU MDR technical documentation capabilities determine European market access viability for Class IIa diagnostic systems. |
| Backward Integration into Sensor Fabrication | In-house electrode and semiconductor production sustains cost advantages against commoditized portable monitor competitors. |
| Reimbursement Strategy Execution | CMS Remote Patient Monitoring code optimization drives health system procurement decisions for wireless telemetry deployment. |
Research Approach
Operator-level perspectives from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and cloud platform product directors anchored the qualitative base. These interviews combined with secondary validation from FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, EU MDR notified body documentation, and MIIT industrial park investment disclosures. Bottom-up unit economics and top-down macroeconomic triangulation cross-checked segment-level assumptions.
Scenario-bracketing framed the analytical approach across the analysis window, modeling volume and value outputs through product type, technology architecture, end-user facility tier, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves applied to base-year estimates, with inputs from hospital capital expenditure surveys and telemedicine reimbursement code maturation timelines.
Sensitivities concentrate around EU MDR recertification timeline extensions, silver commodity price volatility, and FDA digital health pre-certification pilot scope expansion. Forecasts embed assumptions regarding CMS Hospital-at-Home waiver permanence and cloud platform subscription adoption curves. Quarterly review of notified body capacity constraints, precious metal futures, and health system purchasing committee vendor consolidation indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
Global Intraoperative Radiation Therapy Market
Medical Equipment
Asia-Pacific Nuclear Medicine Equipment Market
Medical Equipment
Medical Equipment Calibration Services Market
Medical Equipment
Medical Filter Market
Medical Equipment
Medical Whirlpool Market
Medical Equipment
Global Cardiopulmonary Stress Testing Systems Market
Medical Equipment
Surgical Lighting System Market
Medical Equipment
Medical Gas Cylinders Market
Medical Equipment
Bone Marrow Processing Systems Market
Medical Equipment
Urodynamic Equipment Market
Medical Equipment
Dial Thermometers Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
Europe Nuclear Medicine Equipment Market
Medical Equipment
Minor Surgical Lights Market