
 Global Pet Obesity Management Market | 2026-2036
Global Pet Obesity Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pet Obesity Management Market Foresight
Veterinary clinic consolidation is expanding across North America and Western Europe as corporate chains acquire independent practices. Mars Incorporated leverages its vertical integration from ingredient sourcing to clinic distribution networks. Hill's Pet Nutrition sustains its prescription diet dominance through embedded relationships with veterinary professionals. Zoetis Inc. competes by extending its pharmaceutical expertise into nutraceutical formulations for metabolic disorders.
Pet obesity management encompasses clinically supervised weight reduction protocols, calibrated nutritional interventions, and biomechanical activity regimens designed to restore optimal body condition scores in companion animals. Prescription diets incorporate precise macronutrient ratios formulated under veterinary metabolic research protocols to induce controlled weight loss while preserving lean muscle mass. Dietary supplements capture expanding margin pools as pet owners seek adjunct therapies to complement core nutritional programs. Weight management devices are gaining traction among rehabilitation centers requiring objective activity quantification for treatment validation.
The FDA regulates veterinary prescription diets as animal drugs under specific intended-use claims, creating compliance barriers for new entrants. The EU Green Deal's sustainability mandates are reshaping ingredient sourcing requirements for pet food manufacturers operating across European markets. REACH chemical safety protocols govern additive approvals in weight management formulations distributed throughout the European Union. Stakeholders must monitor evolving veterinary telehealth regulations that could democratize access to professional obesity assessment protocols.
Market Dynamics
Veterinary clinic consolidation is compressing distribution channels as corporate chains acquire independent practices, concentrating purchasing power among fewer buyers and reshaping supplier negotiation leverage across the pet obesity management value chain.
Growth Catalysts
- FDA Veterinary Feed Directives:The FDA's regulatory framework for prescription diets creates defined commercialization pathways that clarify market entry requirements for therapeutic nutrition products in the United States.
- Urban Pet Humanization:Metropolitan centers in the United States, United Kingdom, and Japan exhibit concentrated demand for premium weight management solutions as companion animal ownership rises among affluent households.
- Telehealth Regulatory Evolution:Expanding veterinary telehealth permissions across multiple jurisdictions is democratizing access to professional obesity assessment protocols previously limited to physical clinic visits.
Market Restraints
- Protein Input Volatility:Specialized lean protein sourcing for prescription diets faces price instability tied to agricultural commodity cycles and sustainable sourcing mandates.
- European Supply Concentration:REACH chemical safety protocols and EU Green Deal sustainability requirements concentrate compliant ingredient suppliers in select Northern European processing hubs.
- Metabolic Research Gaps:Species-specific feline metabolic pathway understanding remains incomplete, limiting formulation precision for cat-specific weight management products.
Strategic Opportunities
- Indian Market Underpenetration:Rising companion animal ownership in Indian metropolitan areas creates first-mover potential for veterinary weight management service establishment.
- Wearable Technology Convergence:Integration of accelerometry sensors with cloud-based veterinary platforms enables remote activity monitoring and treatment validation.
- Subscription Distribution Models:Direct-to-consumer recurring delivery channels bypass traditional veterinary clinic intermediaries for maintenance-phase nutritional products.
Industry Challenges
- Veterinary Nutritionist Shortage:Board-certified veterinary nutrition specialists remain scarce relative to clinic expansion rates, constraining service capacity.
- Multi-Jurisdictional Compliance Burden:Manufacturers distributing across FDA, EFSA, and PMDA regulated markets face divergent substantiation requirements for weight loss claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pet Obesity Management Market |
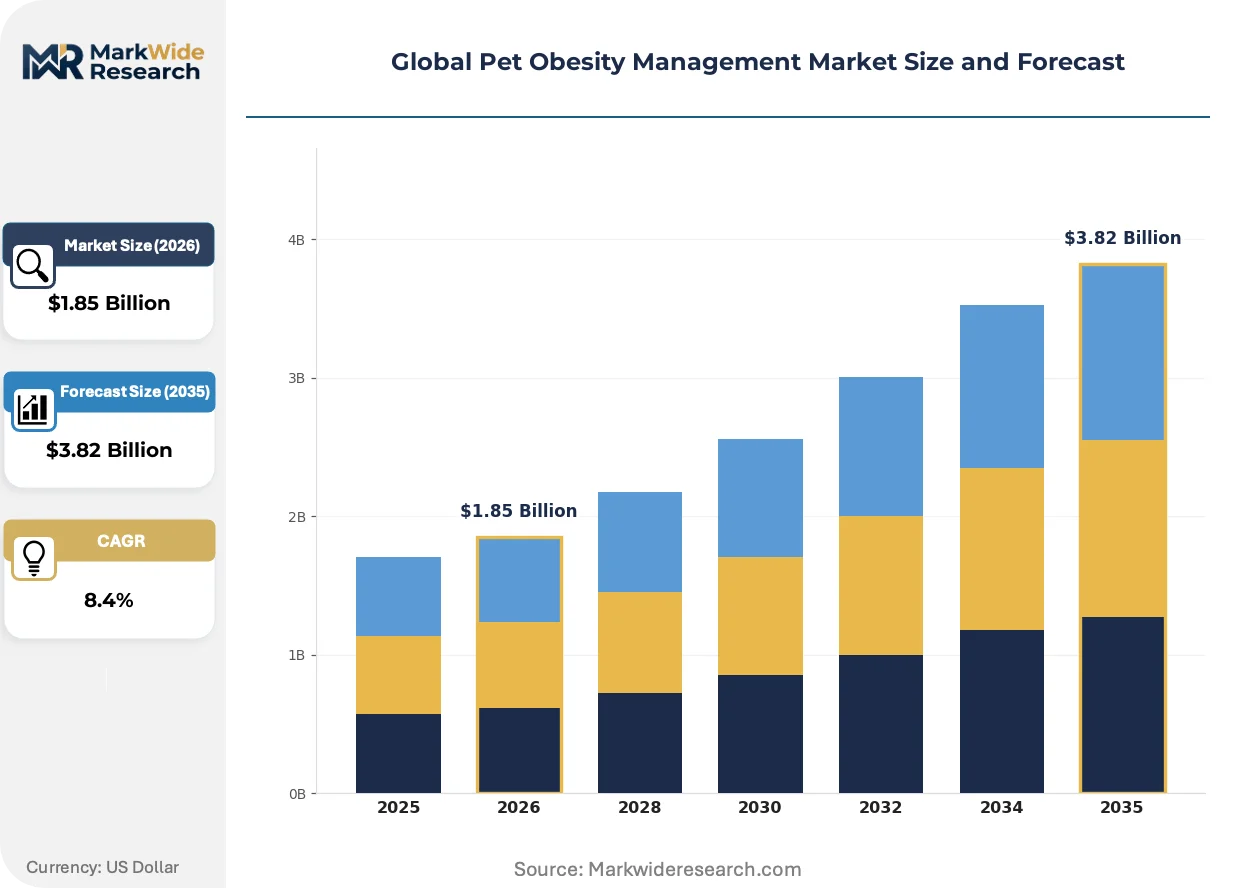
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Supplements, Prescription Diets, Exercise Equipment, Weight Management Devices, Behavioral Therapy Tools Application: Weight Loss Programs, Nutritional Counseling, Physical Therapy, Activity Monitoring, Bariatric Surgery End User: Veterinary Clinics, Animal Hospitals, Pet Owners, Rehabilitation Centers, Grooming Centers Distribution Channel: Veterinary Retail Stores, Online Pet Stores, Specialty Clinics, Direct Sales, Pharmacies |
| Companies Covered | Mars Incorporated, Nestlé S.A., Hill's Pet Nutrition, Zoetis Inc., Virbac S.A., Farmina Pet Foods, NOW Foods, Neogen Corporation, Dechra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pet Obesity Management Market Shifts & Advancements
Digital biomonitoring tools are penetrating veterinary workflows, enabling objective measurement of treatment efficacy that was previously dependent on subjective clinical assessment and owner-reported behavioral data.
Continuous glucose monitoring adapted from human diabetes management is rewriting metabolic assessment protocols in companion animal obesity treatment. Specialty veterinary hospitals in Germany and the United States are deploying interstitial glucose sensors to map individual metabolic responses to dietary interventions. This precision approach is compressing the trial-and-error period traditionally required to calibrate weight loss protocols.
REACH chemical safety protocols and the EU Green Deal are mandating ingredient provenance documentation that extends through supply chain tiers. European manufacturers must now validate sustainable sourcing claims with third-party certification. Formulators operating across EU member states are reformulating products to eliminate additives requiring extensive safety dossiers.
Pet owners are fragmenting across service delivery preferences, with younger demographics favoring mobile veterinary units and teleconsultation over traditional clinic visits. Retail channels in Australian and Canadian urban markets are capturing maintenance-phase nutritional product purchases previously controlled by veterinary dispensing. This channel shift is most visible in subscription-based home delivery segments where convenience overrides professional recommendation dependency.
Global Pet Obesity Management Market Segmentation
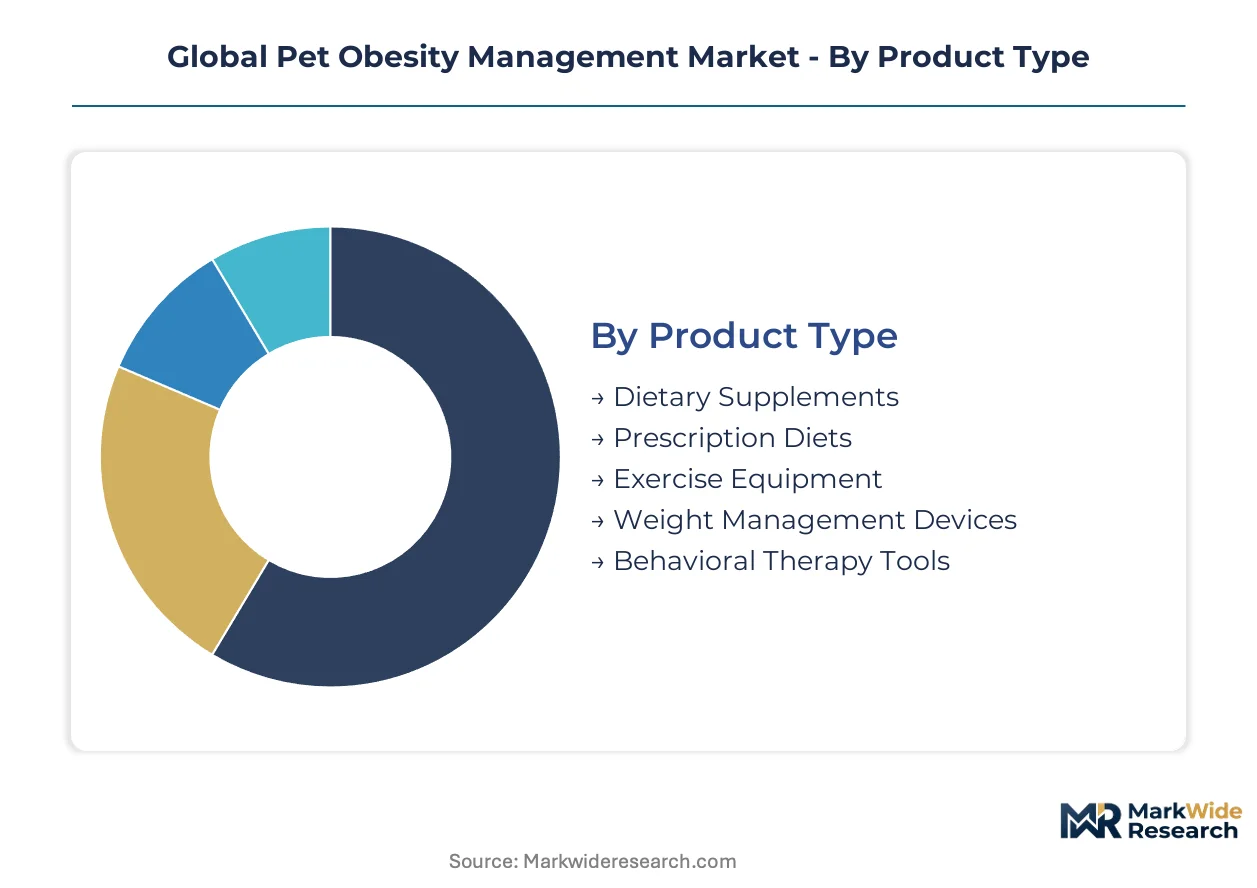
Segmentation in pet obesity management reveals how purchasing authority concentrates among professional intermediaries rather than end consumers. Veterinary gatekeeping shapes product development priorities across formulation science and service delivery models. Understanding these divides exposes where margin pools accumulate and where channel conflict threatens profitability.
Product Type:
Cost tier determines accessibility and margin structure, with prescription-grade formulations commanding premium positioning against over-the-counter alternatives.
- Prescription Diets:Therapeutic nutrition formulations manufactured under FDA veterinary feed directive compliance, requiring veterinary authorization for dispensing. Demand concentrates in United States metropolitan veterinary clinic chains where corporate purchasing agreements lock in formulary placement. Regulatory substantiation barriers protect incumbent positions against generic challengers.
- Dietary Supplements:Adjunct nutritional products including omega fatty acids, L-carnitine, and fiber blends positioned alongside core dietary interventions. Growth accelerates in Japanese and Australian direct-to-consumer channels where pet owners self-direct maintenance-phase purchases. E-commerce platforms bypass traditional veterinary intermediaries for reorder fulfillment.
- Exercise Equipment:Biomechanical devices including underwater treadmills and resistance harnesses deployed in clinical rehabilitation settings. Specialized veterinary hospitals in Germany and the United Kingdom represent primary procurement channels.
- Weight Management Devices:Digital scales, body condition scoring tools, and metabolic monitoring equipment used for objective treatment validation. Rehabilitation centers in Canada and Switzerland drive adoption of precision measurement technologies.
- Behavioral Therapy Tools:Environmental enrichment products and feeding puzzle devices addressing psychological drivers of overconsumption. Pet owner direct purchases through specialty retailers dominate this accessible price tier.
Prescription diets lead on scale; dietary supplements lead on momentum.
Application:
Application focus shifts with treatment phase, from acute intervention protocols to long-term maintenance monitoring.
- Weight Loss Programs:Comprehensive clinical protocols combining nutritional restriction, activity prescription, and progress monitoring under veterinary supervision. United States specialty veterinary hospitals and corporate clinic chains concentrate demand for structured program enrollment. Insurance reimbursement expansion in select markets reduces owner cost barriers to professional intervention.
- Nutritional Counseling:Individualized dietary assessment and feeding plan development delivered by veterinary professionals or credentialed nutritionists. Scarcity of board-certified veterinary nutritionists in the United Kingdom and France constrains service capacity expansion. Telehealth regulatory evolution enables remote consultation delivery across multiple jurisdictions.
- Physical Therapy:Structured exercise rehabilitation for obese animals with comorbid orthopedic compromise. Specialty referral hospitals in Germany and Japan maintain dedicated rehabilitation departments with certified therapists.
- Activity Monitoring:Objective quantification of energy expenditure through wearable accelerometry and GPS tracking. Younger pet owner demographics in Australian and Canadian urban markets favor technology-enabled remote monitoring solutions.
- Bariatric Surgery:Surgical intervention for morbid obesity cases failing conservative management. Limited to university teaching hospitals and specialty surgical centers in the United States and select European markets.
Weight loss programs capture the largest addressable base; activity monitoring climbs the fastest as wearable technology penetrates veterinary workflows.
End User:
Customer type segmentation exposes a bifurcation between professional service providers controlling acute-phase decisions and pet owners assuming maintenance-phase autonomy.
- Veterinary Clinics:Primary care practices serving as gatekeepers for prescription product access and program enrollment. Consolidation across United States and Western European markets concentrates purchasing power among fewer corporate entities. Independent practice acquisition trends reshape supplier negotiation leverage.
- Animal Hospitals:Multi-specialty referral centers managing complex obesity cases with metabolic comorbidities. German and Japanese university-affiliated hospitals lead adoption of continuous glucose monitoring and advanced metabolic assessment.
- Pet Owners:End consumers exercising growing autonomy in maintenance-phase product selection and reorder behavior. Subscription delivery channels and online pet stores capture recurring purchases previously controlled by clinic dispensing.
- Rehabilitation Centers:Dedicated facilities providing structured exercise therapy and objective outcome measurement. Growth concentrates in Canadian and Swiss markets with established veterinary rehabilitation certification pathways.
- Grooming Centers:Ancillary service providers identifying obesity-related mobility limitations during routine care. Limited direct product revenue but significant referral generation for clinical services.
Veterinary clinics dominate transaction volume; pet owners are gaining share fastest as channel control fragments.
Distribution Channel:
Channel structure reflects regulatory stratification, with prescription-controlled products flowing through professional intermediaries and maintenance products migrating to retail accessibility.
- Veterinary Retail Stores:Clinic-affiliated dispensaries maintaining prescription diet inventory and related product assortments. United States corporate clinic chains leverage centralized procurement to optimize formulary economics.
- Online Pet Stores:E-commerce platforms capturing maintenance-phase nutritional product reorders and supplement sales. Australian and Canadian markets exhibit highest penetration of subscription-based auto-delivery models.
- Specialty Clinics:Nutrition-focused veterinary practices and weight management centers with dedicated retail operations. Boutique positioning in Japanese and United Kingdom urban centers supports premium pricing.
- Direct Sales:Manufacturer-controlled channels bypassing intermediaries for institutional contract fulfillment. Large corporate clinic chain purchasing agreements favor direct manufacturer relationships.
- Pharmacies:Human retail pharmacy chains expanding into veterinary product categories in select European markets. Regulatory complexity limits United States pharmacy participation in prescription diet distribution.
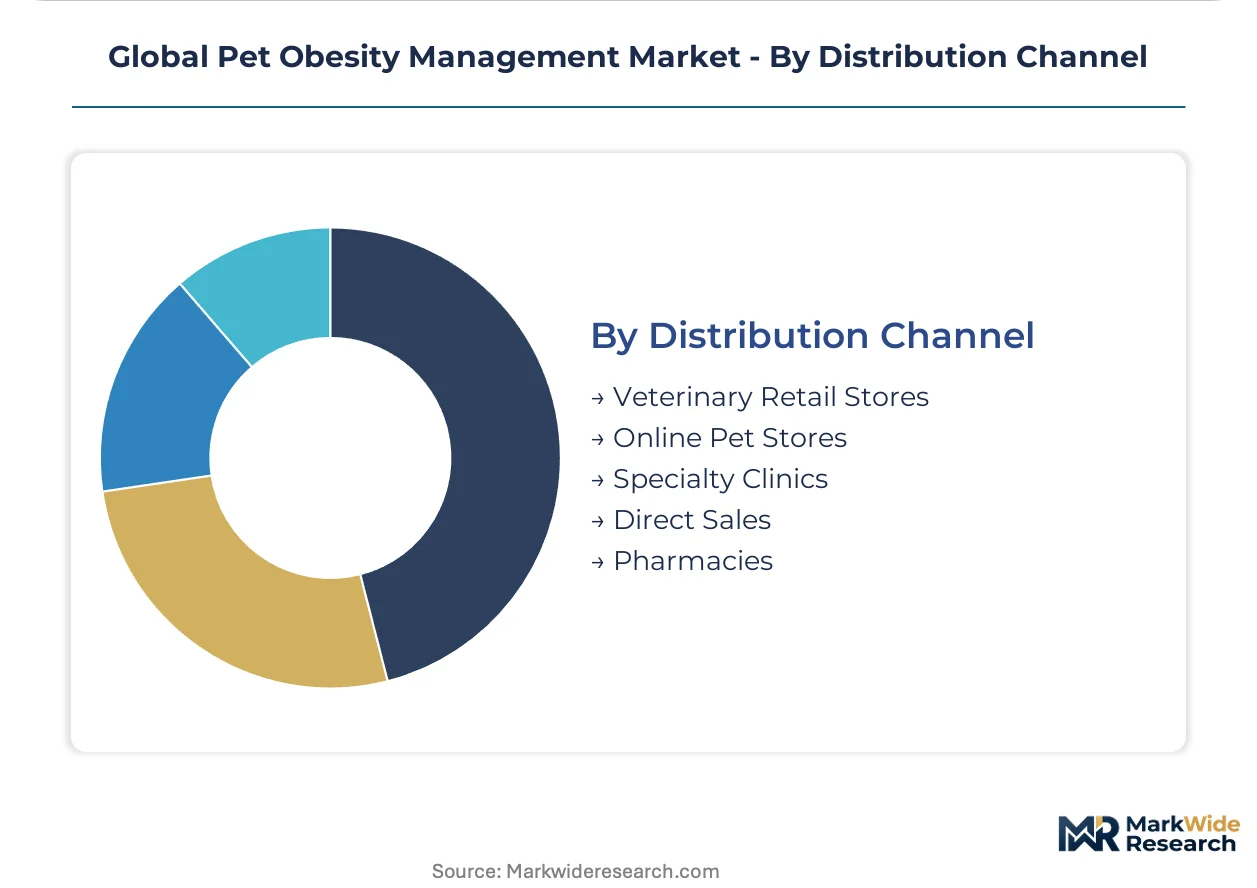
Veterinary retail stores anchor current volume; online pet stores show steepest expansion trajectory as convenience preferences reshape repurchase behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates higher per-capita veterinary spending on weight management than Germany, yet German specialty hospitals deploy more advanced metabolic monitoring technologies. Market maturity diverges sharply across national regulatory environments and companion animal demographic profiles.
United States
FDA veterinary feed directives structure prescription diet commercialization pathways while corporate clinic chains consolidate purchasing power. The agency's oversight of therapeutic nutrition claims creates compliance barriers that protect incumbent formulary positions. Mars Petcare and Hill's Pet Nutrition maintain dominant positions in metropolitan veterinary networks across Texas and California.
Germany
Specialty referral hospitals in Bavaria and North Rhine-Westphalia lead European adoption of continuous glucose monitoring for feline metabolic assessment. REACH chemical safety protocols and EU Green Deal sustainability mandates reshape ingredient sourcing requirements for manufacturers distributing across German markets. Munich and Berlin veterinary teaching hospitals pioneer interstitial sensor deployment for precision weight protocol calibration.
Japan
PMDA regulatory frameworks govern veterinary pharmaceutical and nutraceutical product approvals, creating distinct substantiation requirements for weight management claims. METI industrial policy supports domestic pet food manufacturing modernization. Tokyo and Osaka metropolitan areas concentrate demand for premium therapeutic nutrition as companion animal ownership rises among aging demographics.
United Kingdom
Board-certified veterinary nutritionist scarcity constrains service capacity expansion despite rising obesity prevalence in companion animals. The British Small Animal Veterinary Association promotes standardized body condition scoring protocols. London and Southeast England urban centers drive premium spending on weight management solutions through corporate clinic chain networks.
Australia
TGA veterinary product regulations align with international standards while state-level veterinary practice acts govern telehealth service delivery. Subscription-based auto-delivery models capture maintenance-phase nutritional product purchases in Sydney and Melbourne. Younger pet owner demographics favor mobile veterinary units and remote activity monitoring technologies over traditional clinic visits.
Global Pet Obesity Management Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Conglomerate players leverage cross-category brand equity and captive distribution through veterinary clinic networks, while specialists concentrate formulation expertise in narrow metabolic indications. Three archetypes dominate: vertically integrated nutrition-to-clinic operators, pharmaceutical-extenders applying drug development rigor to nutraceuticals, and ingredient-grade suppliers feeding private-label channels. Consolidation through corporate practice acquisition and direct-to-consumer channel establishment represent the dominant competitive vectors reshaping supplier-buyer leverage dynamics.
Within the diversified nutrition conglomerate tier, Mars Incorporated and Nestlé S.A. occupy positions defined by cross-category brand portfolios and clinic network penetration. Hill's Pet Nutrition exemplifies the prescription-focused specialist archetype through embedded veterinary professional relationships. Zoetis Inc. represents pharmaceutical-origin extension into metabolic disorder formulations, applying regulatory substantiation capabilities developed in animal drug development to adjacent nutritional therapeutics.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestlé S.A. |
| Hill's Pet Nutrition |
| Zoetis Inc. |
| Virbac S.A. |
| Farmina Pet Foods |
| NOW Foods |
| Neogen Corporation |
| Dechra |
| Others |
Supply & Pricing Matrix
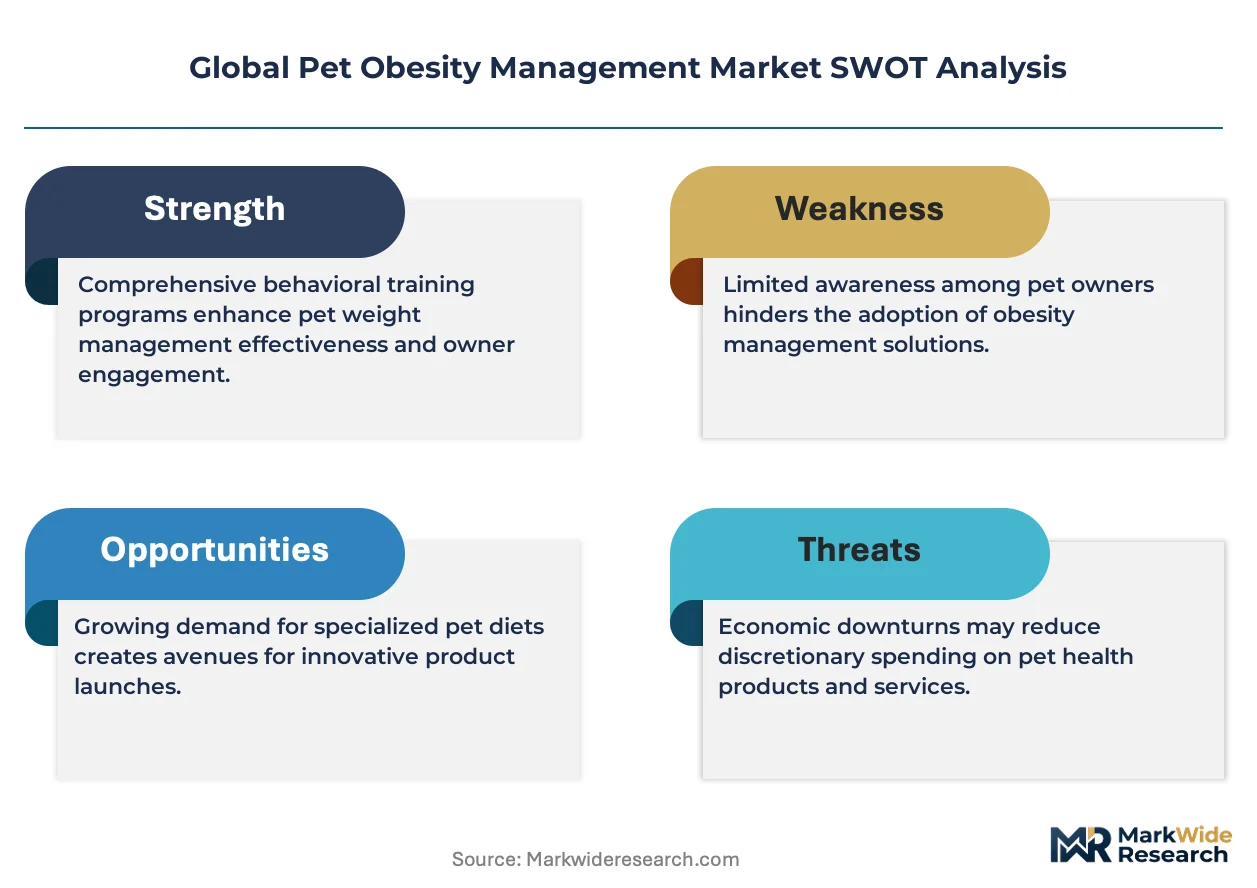
Continuous glucose monitoring sensor integration into veterinary metabolic assessment protocols is compressing trial-and-error calibration periods while concentrating procurement leverage among German and United States specialty hospitals capable of absorbing capital equipment costs. This technology shift simultaneously elevates service pricing power for advanced protocol providers and fragments margin pools across equipment manufacturers, sensor suppliers, and data platform operators.
Pricing Analysis
Capacity additions in Indian metropolitan veterinary networks are reshaping price floors for maintenance-phase nutritional counseling services. Three-tier pricing structure across premium, standard, and economy levels separates university-affiliated specialty hospitals from corporate clinic chains and independent practices. Price differentiation rests on certification density and embedded veterinary nutritionist staffing. Cost compression in the economy tier is intensifying because telehealth-enabled remote consultations displace physical visit revenues. Corporate clinic chains exhibit lowest price sensitivity due to centralized procurement scale; independent single-practitioner clinics face acute margin pressure.
Supply Chain Analysis
Reverse logistics for prescription diet returns and expired therapeutic nutrition products flow through specialized veterinary distributors in the United States and Germany with temperature-controlled refurbishment capabilities. Geographic supply concentration centers on the United States, Germany, and Japan for FDA, EFSA, and PMDA-compliant manufacturing. Raw material dependencies draw from North American lean protein processing, European sustainable carbohydrate sourcing, and Japanese omega fatty acid refinement. Single-source vulnerability concentrates in board-certified veterinary nutritionist staffing for formulation oversight. Distribution runs through corporate clinic chain centralized procurement with direct manufacturer contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with FDA veterinary feed directive expansion into telehealth prescribing permissions creating new demand generation pathways for therapeutic nutrition products.
For Market Incumbents: Hedge formulary erosion by embedding continuous glucose monitoring hardware into service bundles, locking in recurring sensor revenue streams. Deepen backward integration into sustainable protein sourcing to neutralize EU Green Deal compliance cost penalties. Channel control through corporate clinic acquisition remains the priority defensive lever against direct-to-consumer subscription entrants. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting Australian and Canadian urban pet owner demographics with maintenance-phase supplement portfolios. White-space concentrates in Indian metropolitan veterinary weight management service establishment and wearable technology platform integration for remote activity monitoring. The most penetrable entry angle pairs accelerometry sensor hardware with cloud-based veterinary data platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among independent veterinary nutrition consultancies with embedded academic research relationships and proprietary metabolic assessment protocols. Long-term viability across the analysis window favors targets with regulatory substantiation capabilities spanning FDA, EFSA, and PMDA jurisdictions. Watch for telehealth reimbursement code expansion as the inflection signal for service delivery model profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | FDA regulatory evolution enables remote prescription diet authorization, expanding addressable veterinary consultation volume. |
| Continuous Glucose Monitoring Deployment | German specialty hospitals pioneer interstitial sensor protocols, establishing precision weight management service differentiation. |
| Sustainable Sourcing Certification | EU Green Deal mandates reshape ingredient provenance requirements, concentrating compliant supplier relationships. |
| Corporate Clinic Acquisition | United States consolidation concentrates purchasing power, reshaping supplier negotiation leverage dynamics. |
| Direct-to-Consumer Subscription Launch | Australian and Canadian markets exhibit highest auto-delivery penetration, bypassing traditional veterinary intermediaries. |
Research Methodology
Direct dialogue with veterinary nutrition specialists, corporate clinic chain procurement directors, regulatory affairs leads at therapeutic nutrition manufacturers, and telehealth platform developers grounded qualitative insights. Secondary validation drew from FDA veterinary feed directive filings, EFSA additive safety assessments, PMDA pharmaceutical approval databases, and corporate clinic chain SEC disclosures. Bottom-up service volume modeling and top-down therapeutic nutrition revenue estimates were triangulated against veterinary practice management system data.
Bottom-up demand estimation segmented across prescription diet formulation tiers, dietary supplement adjunct categories, wearable technology deployment models, and service delivery channel types. The analytical framework applied growth rate derivation across the projection horizon, weighting veterinary clinic consolidation velocity and telehealth regulatory evolution as primary demand drivers. Species-specific metabolic pathway research investment levels and board-certified nutritionist supply constraints informed capacity-side modeling.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt telehealth permission reversals or sustained protein commodity price volatility. Forecasts reflect assumptions regarding regulatory harmonization pace and corporate clinic acquisition cadence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Orthopedic Veterinary Implants Market
Veterinary
Global Animal Vaccine Market
Veterinary
Veterinary Point-Of-Care Diagnostics Market
Veterinary
US Companion Animal Diagnostics Market
Veterinary
Feline Atopic Dermatitis Treatment Market
Veterinary
Global Animal Intestinal Health Market
Veterinary
Global Canine Atopic Dermatitis Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Veterinary Biologicals Biobank Market
Veterinary
Veterinary Immunodiagnostics Market
Veterinary
Vet Software Market
Veterinary
Mastitis Market
Veterinary
Pet Veterinary Diet Market
Veterinary
Bovine Collagen Market
Veterinary
Global Veterinary Grooming Aids Market
Veterinary
CBD Pet Market