
 Tanning Units Market | 2026-2036
Tanning Units Market Size, Share, and Industry Trends Forecast 2026-2036
Tanning Units Market Analytics
UV-LED phosphor coatings is restructuring lamp economics across tanning unit manufacturing, trimming energy draw and extending service intervals versus legacy mercury-vapor tubes. Ergoline GmbH leverages captive German engineering to dominate high-end commercial tanner deployments across European wellness chains. SunQuest Corporation sustains North American aftermarket parts revenue through proprietary lamp socket architectures. Daavlin Company, Inc. anchors its position in dermatology-adjacent phototherapy crossover units, a segment with distinct reimbursement dynamics.
Tanning units are enclosed irradiation systems engineered to deliver controlled ultraviolet-A and ultraviolet-B emissions, typically calibrated between 280 nm and 400 nm wavelength output, designed for cosmetic skin pigmentation or prescribed dermatological treatment. Stand-up tanners occupy premium salon floor space due to faster session throughput and lower maintenance surface area compared to lay-down cabin designs. Hybrid UV-LED technology captures the fastest-growing technology slot as salon operators seek to market reduced-burn positioning, while spray tan technology serves a parallel demand stream among UV-averse consumers. Commercial units command the dominant end-user channel, though home units are gaining traction through direct-to-consumer online distribution.
The U.S. FDA enforces 21 CFR 1040.20 performance standards on sunlamp products, mandating warning labels and timer mechanisms that elevate product development overhead for entrants. Germany's Federal Institute for Radiation Protection (BfS) and the EU's Ecodesign Directive together restrict mercury-content thresholds and mandate efficiency minimums, pushing manufacturers toward LED migration. REACH compliance across the European Union further constrains phosphor and coating chemistries in lamp production. Stakeholders must monitor divergence between U.S. and EU lamp classification regimes, as divergent compliance pathways could fragment product portfolios and raise inventory carrying costs for multinational suppliers.
Market Dynamics
UV-LED phosphor coating technology is compressing lamp replacement cycles while elevating energy efficiency minimums, forcing incumbent mercury-vapor suppliers to absorb retooling costs or cede salon network placements to LED-native entrants.
Growth Catalysts
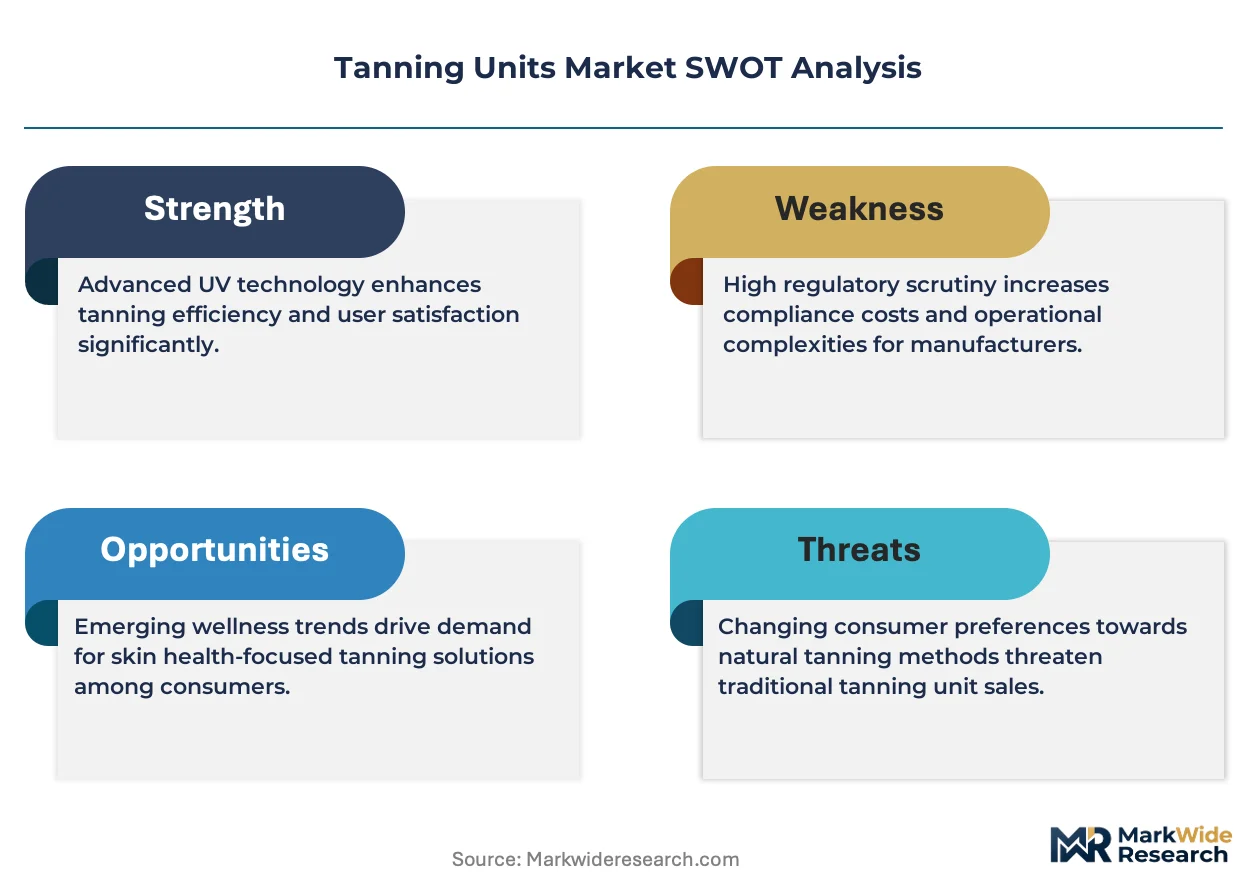
- EU Ecodesign Directive efficiency mandates:Germany's Federal Institute for Radiation Protection enforces mercury-content thresholds that accelerate LED migration across commercial salon fleets.
- Dermatology crossover demand:Phototherapy units calibrated for psoriasis and vitiligo treatment expand addressable demand beyond cosmetic pigmentation into reimbursed medical channels.
- Brazilian salon density concentration:São Paulo and Rio de Janeiro sustain replacement cycles through high aesthetic spending per capita and established tanning culture.
Market Restraints
- Mercury supply concentration:Phosphor-grade mercury sourcing concentrates in limited refining jurisdictions, exposing lamp manufacturers to input volatility and export licensing friction.
- REACH coating chemistry constraints:EU restrictions on phosphor and coating substances elevate formulation compliance costs and compress supplier margins.
- Spray tan substitution:UV-averse consumers increasingly divert to DHA-based spray systems, capping addressable demand for irradiation-based equipment.
Strategic Opportunities
- Home unit direct-to-consumer channels:Online distribution bypasses salon intermediaries, capturing consumers seeking privacy and session flexibility.
- UV-LED hybrid convergence:Combined ultraviolet-A and ultraviolet-B LED arrays enable precise wavelength tuning for reduced-burn positioning.
- U.S. FDA 21 CFR 1040.20 compliance services:Third-party certification consulting addresses entrant overhead from timer mechanism and warning label mandates.
Industry Challenges
- Optical engineer scarcity:Phosphor deposition and LED array calibration expertise concentrates in German and Japanese industrial clusters, constraining rapid scaling.
- Legacy socket architecture integration:Proprietary lamp interfaces in installed base equipment complicate aftermarket parts standardization and elevate inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tanning Units Market |
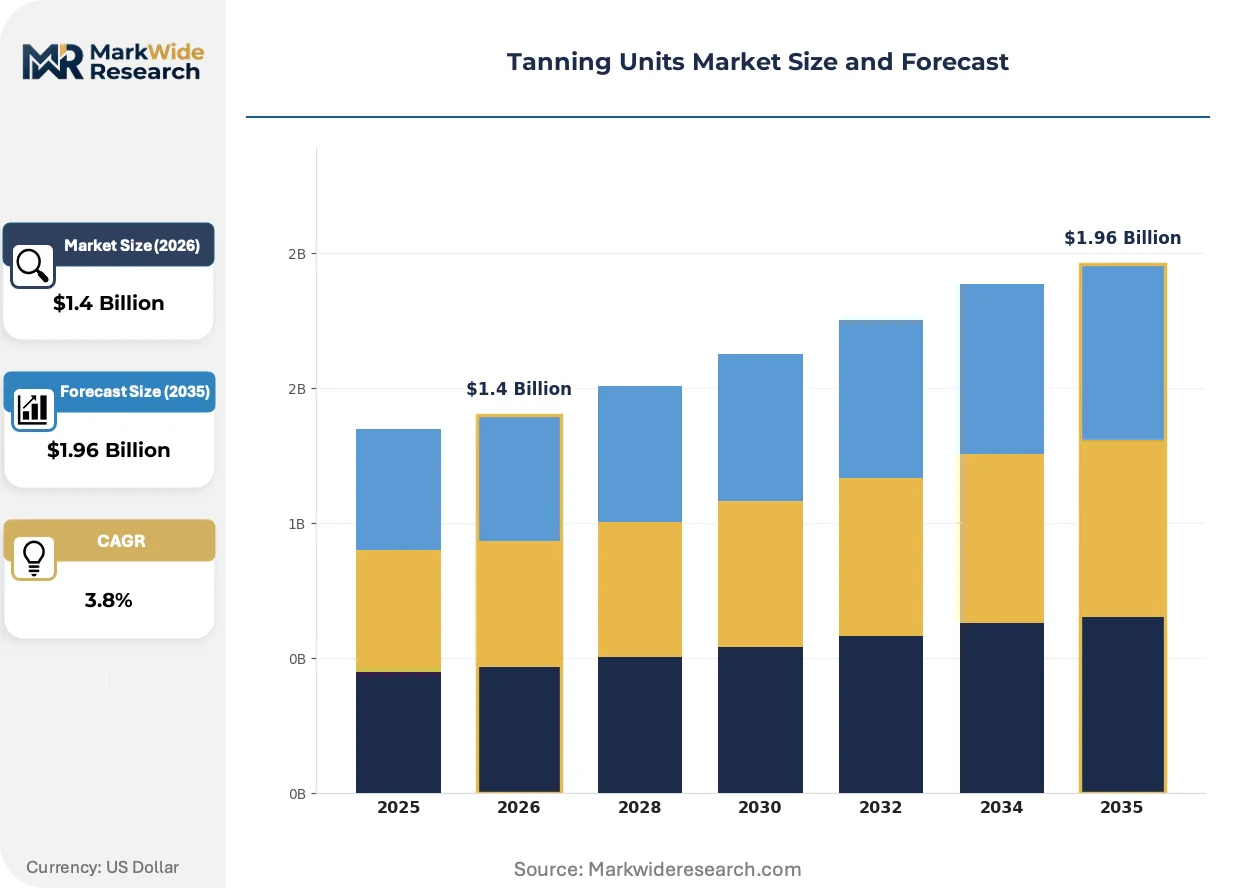
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $1.96 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up Tanners, Lay-down Tanners, Home Units, Commercial Units Technology: UV Lamps, LED, Hybrid, Spray Tan Technology End User: Salons, Spas, Fitness Centers, Home Users Distribution Channel: Online Stores, Specialty Retail, Direct Sales, Wholesalers |
| Companies Covered | Soltron, Inc., SunQuest Corporation, Ergoline GmbH, ProSun International, National Sun Industries, Inc., Hapro Sun Systems B.V., Daavlin Company, Inc., ETS Tan LLC, Cosmedico GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tanning Units Market Evolving Landscape
Equipment architecture is fragmenting into interchangeable subsystems as salon operators demand flexibility across session types, while regulatory pressure and procurement rationalization reshape competitive priorities.
UV-LED phosphor coating systems deliver calibrated wavelength output between 280 nm and 400 nm through solid-state arrays rather than gas-discharge tubes. Commercial wellness chains in Germany and the United States are adopting these systems at accelerating replacement cycles. This technology is modularizing lamp architecture into swappable LED banks, compressing field service requirements and enabling salon operators to upgrade wavelength profiles without full cabin replacement.
Germany's Federal Institute for Radiation Protection and the EU Ecodesign Directive jointly restrict mercury-content thresholds and mandate efficiency minimums for electrical equipment. Lamp manufacturers face divergent compliance pathways between EU and U.S. classification regimes, fragmenting product portfolios. High-end commercial tanner deployments absorb these costs through premium positioning, while mid-market entrants confront elevated inventory carrying burdens.
Salon procurement is consolidating toward outcome-based service contracts that bundle equipment, maintenance, and consumables into per-session fees. This displaces traditional capital purchase models among North American wellness chains. The shift is most visible in United States metropolitan markets where private equity-backed salon rollups standardize fleet management across multiple locations.
Tanning Units Market Segmentation
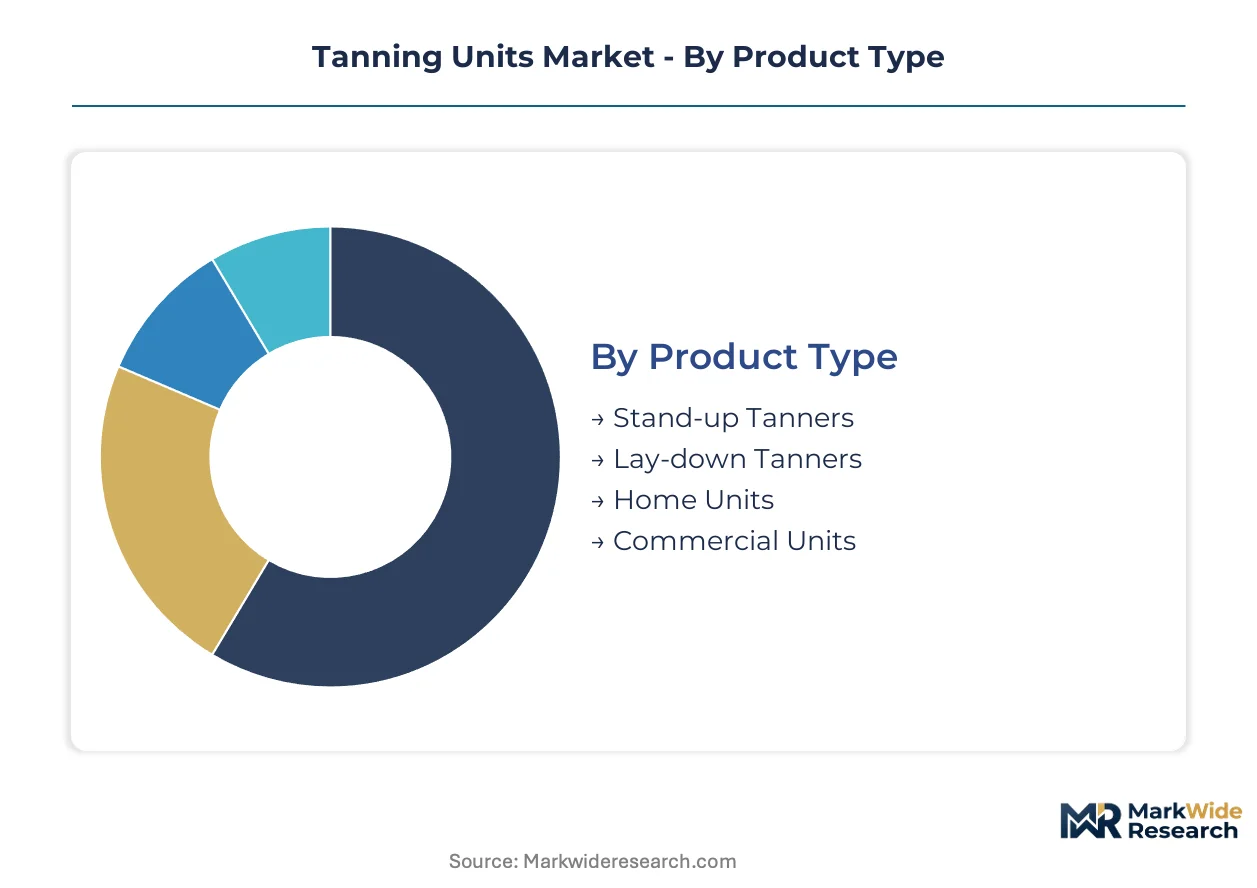
Tanning unit segmentation reveals divergent compliance burdens across product architectures, with commercial installations facing FDA 21 CFR 1040.20 mandates while home units navigate lighter consumer product frameworks. Technology choices further stratify regulatory exposure, as mercury-based UV lamps trigger REACH restrictions that LED-native designs largely bypass.
Product Type:
FDA 21 CFR 1040.20 applies differentially across product types, with commercial stand-up and lay-down units facing full sunlamp product classification while home units occupy a lighter regulatory tier under general consumer appliance standards.
- Stand-up Tanners:Vertical cabin designs deliver 360-degree irradiation through high-output lamp arrays arranged in cylindrical configurations. German wellness chains and São Paulo salon clusters drive replacement demand for these units, prioritizing session throughput and reduced floor-space occupancy over acquisition cost.
- Lay-down Tanners:Horizontal bed architectures distribute UV exposure across reclined body positioning, historically dominating installed base volumes through ergonomic familiarity. The segment faces accelerated replacement pressure in North American markets as LED-retrofit compatibility becomes a procurement criterion.
- Home Units:Compact single-user designs prioritize storage convenience and session privacy over commercial-grade output specifications.
- Commercial Units:Heavy-duty chassis and extended-duty cycle ratings serve high-frequency salon operations with modular lamp bank architectures.
Commercial Units sit at the top of the volume ranking, with Home Units climbing the fastest.
Technology:
Cost tier stratification separates legacy mercury-vapor systems from premium LED-native and hybrid configurations, with spray alternatives occupying a parallel non-irradiation category entirely outside UV regulatory scope.
- UV Lamps:Conventional mercury-vapor tube assemblies emit calibrated UV-A and UV-B through gas-discharge physics, constrained by EU Ecodesign Directive mercury-content thresholds and REACH phosphor chemistry restrictions that elevate compliance overhead.
- Hybrid:Combined mercury-LED architectures enable graduated wavelength tuning and reduced-burn marketing positioning. United States metropolitan salon rollups absorb hybrid premiums through outcome-based service contracts that bundle equipment and maintenance.
- LED:Solid-state phosphor-coated arrays eliminate mercury entirely while compressing field service intervals through modular bank replacement.
- Spray Tan Technology:DHA-based aerosol deposition systems serve UV-averse consumers through cosmetic pigmentation without irradiation exposure.
UV Lamps retain dominant installed base share, though Hybrid configurations gain share fastest among new commercial placements.
End User:
Customer type determines procurement sophistication, with institutional buyers leveraging fleet standardization and service contracting while individual consumers prioritize convenience and privacy.
- Salons:Dedicated tanning establishments concentrate equipment density and sustain replacement cycles through aesthetic service bundling.
- Spas:Wellness-integrated operations demand premium cabin aesthetics and reduced-burn technology positioning to align with holistic health branding.
- Fitness Centers:Gym-ancillary tanning services prioritize compact footprint and rapid session turnover to minimize space opportunity cost.
- Home Users:Privacy-seeking individuals bypass institutional intermediaries through direct-to-consumer online channels.
Salons command the top volume position, with Home Users expanding most quickly through e-commerce penetration.
Distribution Channel:
Supply concentration varies sharply by channel, with direct sales capturing institutional fleet contracts while online stores fragment toward individual consumers.
- Online Stores:Direct-to-consumer platforms bypass salon intermediaries for home unit sales, capturing privacy-motivated buyers.
- Specialty Retail:Dedicated beauty equipment showrooms serve small salon operators with hands-on evaluation and financing arrangements.
- Direct Sales:Manufacturer field teams secure multi-unit fleet contracts with wellness chain procurement departments.
- Wholesalers:Regional distributors aggregate mid-market salon demand with inventory carrying and logistics services.
Direct Sales leads volume for commercial placements, with Online Stores accelerating fastest on home unit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering clusters around Stuttgart and Cologne anchor commercial tanning unit production, with regulatory pressure from the Federal Institute for Radiation Protection accelerating LED technology migration across European salon networks.
United States
Metropolitan salon rollups in Miami, Los Angeles, and Dallas sustain replacement cycles through private equity-backed fleet standardization. FDA 21 CFR 1040.20 compliance costs elevate barriers for new entrants, particularly around timer mechanism and warning label mandates. SunQuest Corporation anchors aftermarket parts distribution from its North American operational base.
Germany
Wellness chains in Berlin, Hamburg, and Munich absorb premium equipment pricing through outcome-based service contracting. The Federal Institute for Radiation Protection enforces mercury-content thresholds that compress legacy lamp economics. Ergoline GmbH leverages captive engineering from Baden-Württemberg to dominate high-end commercial deployments.
Brazil
São Paulo and Rio de Janeiro salon density sustains replacement demand through established aesthetic spending patterns and cultural tanning adoption. ANVISA regulates device safety classifications for commercial irradiation equipment. National Sun Industries, Inc. positions within Latin American distribution channels serving this concentrated coastal demand.
United Kingdom
London and Manchester wellness operators prioritize reduced-burn technology positioning to align with holistic health branding trends. REACH compliance constrains phosphor chemistry sourcing for mercury-based lamp imports. Specialty retail channels in the Southeast aggregate mid-market salon procurement with financing arrangements.
Netherlands
Randstad region tanning establishments consolidate procurement toward modular LED-native systems with compressed field service intervals. EU Ecodesign Directive efficiency minimums drive equipment turnover in Rotterdam and Amsterdam clusters. Hapro Sun Systems B.V. occupies a position within Dutch-engineered commercial unit fabrication.
Tanning Units Market Competitive Landscape
Global majors compete with regional champions across technology licensing and salon network placements, producing a tiered structure where LED-native entrants challenge incumbent mercury-vapor suppliers. The vendor base stratifies into three archetypes: German-engineered premium specialists, North American aftermarket parts anchors, and dermatology-crossover phototherapy providers. Competitive moves concentrate on M&A for salon chain fleet contracts and vertical integration into phosphor coating supply.
Among German-engineered fabricators, Ergoline GmbH exemplifies the premium-tier specialist archetype through its Baden-Württemberg engineering concentration. SunQuest Corporation anchors North American aftermarket positioning through proprietary lamp socket architectures. Daavlin Company, Inc. occupies the dermatology-adjacent phototherapy segment with distinct reimbursement dynamics from cosmetic tanning.
| Leading Market Players |
|---|
| Soltron, Inc. |
| SunQuest Corporation |
| Ergoline GmbH |
| ProSun International |
| National Sun Industries, Inc. |
| Hapro Sun Systems B.V. |
| Daavlin Company, Inc. |
| ETS Tan LLC |
| Cosmedico GmbH |
| Others |
Value Network & Pricing Analysis
Phosphor-grade mercury spot pricing cascades through tanning unit manufacturing into three distinct equipment tiers, with EU Ecodesign Directive compliance costs compressing margins on legacy lamp architectures while LED-native suppliers capture premium positioning through reduced field service obligations.
Pricing Analysis
Input-cost pass-through from mercury volatility and REACH-compliant coating chemistry elevates landed costs for conventional UV lamp assemblies, forcing manufacturers to absorb margin compression or push pricing stratification across premium, standard, and economy equipment tiers. Certification-grade differentiation separates FDA 21 CFR 1040.20-compliant commercial units from lighter-regulated home equipment, with German-engineered systems commanding brand premiums. Pricing pressure stems from spray tan substitution diverting UV-averse consumers, while home unit buyers exhibit highest price sensitivity compared to institutional salon procurement.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Cologne, and Rotterdam anchor hub-and-spoke fulfillment patterns for European salon networks, with North American aftermarket parts flowing through SunQuest Corporation's proprietary socket architecture. Manufacturing concentrates in Germany, the United States, and the Netherlands, drawing from phosphor-grade mercury, LED substrate wafers, and specialized optical coatings as critical inputs. Single-source vulnerability around Japanese and German optical engineering talent constrains rapid scaling, while distribution runs through direct sales for institutional fleet contracts and online stores for home unit penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in tanning units hinges on LED technology migration compressing field service costs and enabling outcome-based service contracting that locks in recurring revenue streams.
For Market Incumbents: Deepen captive control over phosphor coating supply through backward integration into LED substrate preparation, defending installed base positions against LED-native entrants while accelerating hybrid system deployment to capture salon fleet replacement cycles. Invest in FDA 21 CFR 1040.20 compliance certification infrastructure to elevate barriers for mid-market challengers. For New Entrants and Emerging Players: Launch via direct-to-consumer online channels into home unit segments where institutional procurement relationships matter less and privacy positioning commands premium pricing. Target fitness center ancillary tanning services as the most penetrable institutional channel, where rapid session turnover requirements favor compact LED-native designs over legacy cabin architectures. For Investors and Strategic Acquirers: Asymmetric upside sits with dermatology-crossover phototherapy specialists holding distinct reimbursement dynamics and regulatory moats separate from cosmetic tanning volatility. Five-to-ten year viability favors equipment-as-a-service platforms bundling maintenance and consumables into per-session fees. Monitor ANVISA regulatory harmonization progress in Brazil as inflection signal for Latin American market structure consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| LED-Native Platform Migration | Eliminates mercury compliance costs while reducing field service intervals for salon operators. |
| Outcome-Based Service Contracting | Transforms capital equipment sales into recurring revenue streams across United States metropolitan salon rollups. |
| Phototherapy Segment Expansion | Captures reimbursed medical demand through psoriasis and vitiligo treatment calibration. |
| Direct-to-Consumer Channel Buildout | Bypasses salon intermediaries for privacy-motivated home unit buyers through e-commerce infrastructure. |
| Regulatory Compliance Certification Services | Addresses entrant overhead from FDA timer mechanism and EU Ecodesign Directive mandates. |
Research Methodology
Direct dialogue with salon chain procurement directors, equipment maintenance technicians, dermatology clinic administrators, and phosphor coating suppliers grounded qualitative findings, cross-validated against FDA 21 CFR 1040.20 filings, EU Ecodesign Directive implementation guidance, REACH substance restriction updates, and customs trade data for lamp component flows. Bottom-up unit placement estimates across commercial and home segments triangulated with top-down market sizing from wellness industry expenditure surveys.
Segment-level value outputs across the projection horizon reflect modeled replacement cycles, technology migration curves, and regulatory compliance cost absorption rates. Segmentation dimensions include product architecture, lamp technology type, end-user category, and distribution channel. CAGRs derive from fitted technology adoption S-curves and salon fleet standardization patterns observed in private equity-backed rollup activity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt mercury export licensing restrictions or accelerated EU mercury-content bans. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Southern Europe and Middle East Medical Robotics Market
Medical Equipment
Medical Physics Market
Medical Equipment
Global Laminar Airflow Cabinets Market
Medical Equipment
Next Generation Centrifuge Market
Medical Equipment
Global Stereotactic Radiosurgery (Gamma Knife) Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Solar Powered Vaccine Refrigerator Market
Medical Equipment
Cell Culture Incubator Market
Medical Equipment
Benchtop Platelet Agitator Market
Medical Equipment
Global Operating Table Mattresses Market
Medical Equipment
Floor-Standing Platelet Agitator Market
Medical Equipment
Medical Equipment Reimbursement Market
Medical Equipment
Asia-Pacific Medical Carts Market
Medical Equipment
X-Ray Machine Manufacturing Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
Global Surgical Lights Market