
 Global Microtome Market | 2026-2036
Global Microtome Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microtome Market Foresight
The split between premium automated systems and entry-level manual units is shifting as diagnostic laboratories recalibrate capital budgets against throughput requirements. Leica Biosystems leverages its histopathology heritage to sustain pricing power in high-volume clinical settings. Thermo Fisher Scientific anchors its position through integrated workflow solutions spanning sample preparation to imaging. Sakura Finetek differentiates via embedded blade technology and service density in Asia-Pacific markets.
A microtome is a precision cutting instrument that sections biological or material specimens into slices typically ranging from 0.5 to 100 micrometers thick, using either a rotary crank mechanism or automated motorized advance to drive the sample past a fixed or oscillating blade. Its primary purpose spans histopathology diagnostics, neuroscience research, and materials characterization where thin-section analysis enables microscopic examination of tissue architecture and structural composition. Rotary microtomes occupy the mature core of installed bases in routine histology labs, while cryostat microtomes command margin premiums in intraoperative frozen section workflows where speed determines clinical utility. Ultramicrotomes serve the fastest-growing niche in electron microscopy sample preparation for pharmaceutical nanomaterial characterization.
The FDA's 510(k) pathway and the EU MDR's tightened clinical evidence requirements for Class I devices shape product registration timelines and aftermarket service obligations for manufacturers. ISO 13485 quality management mandates and IEC 61010 safety standards govern design controls and electromagnetic compatibility across all commercial jurisdictions. Pathology laboratories must weigh total cost of ownership against digital pathology integration timelines when replacing aging microtome fleets.
Market Dynamics
Digital pathology integration timelines are compressing replacement cycles for aging microtome fleets as laboratories reconcile capital budgets with automated sectioning throughput requirements. Leica Biosystems and Thermo Fisher Scientific compete for installed base lock-in through service bundling and workflow software anchoring.
Growth Catalysts
- Frozen section workflow expansion:Intraoperative pathology demand in oncology centers drives cryostat microtome adoption where speed determines surgical margin assessment utility.
- EU MDR Class I device pathways:Tightened clinical evidence requirements accelerate aftermarket service obligations and certified refurbishment programs for installed base retention.
- Electron microscopy sample preparation:Pharmaceutical nanomaterial characterization requirements expand ultramicrotome demand in contract research organizations.
Market Restraints
- High-precision blade supply concentration:Specialized tungsten carbide and diamond blade manufacturing clusters in Germany and Japan create single-source vulnerability for OEMs.
- Capital intensity of automated systems:Motorized advance mechanisms with integrated sectioning feedback require precision machining capabilities concentrated in Swiss and German supplier networks.
- ISO 13485 certification timelines:Quality management system audits for design controls extend product registration cycles by 12-18 months for new market entrants.
Strategic Opportunities
- India's CDSCO device registration streamlining:Central Drugs Standard Control Organization pathway simplification opens access to hospital network procurement in tier-2 cities.
- AI-assisted section quality monitoring:Machine vision integration with rotary microtomes enables real-time thickness verification and blade wear prediction.
- Direct-to-laboratory consumables subscription:Blade and embedding medium replenishment programs bypass distributor markups in price-sensitive Asia-Pacific markets.
Industry Challenges
- Histotechnologist training pipeline gaps:Specialized tissue sectioning expertise shortages in US academic medical centers extend equipment commissioning timelines.
- Legacy system interoperability:Proprietary data formats from 1990s-era microtomes block seamless integration with modern laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microtome Market |
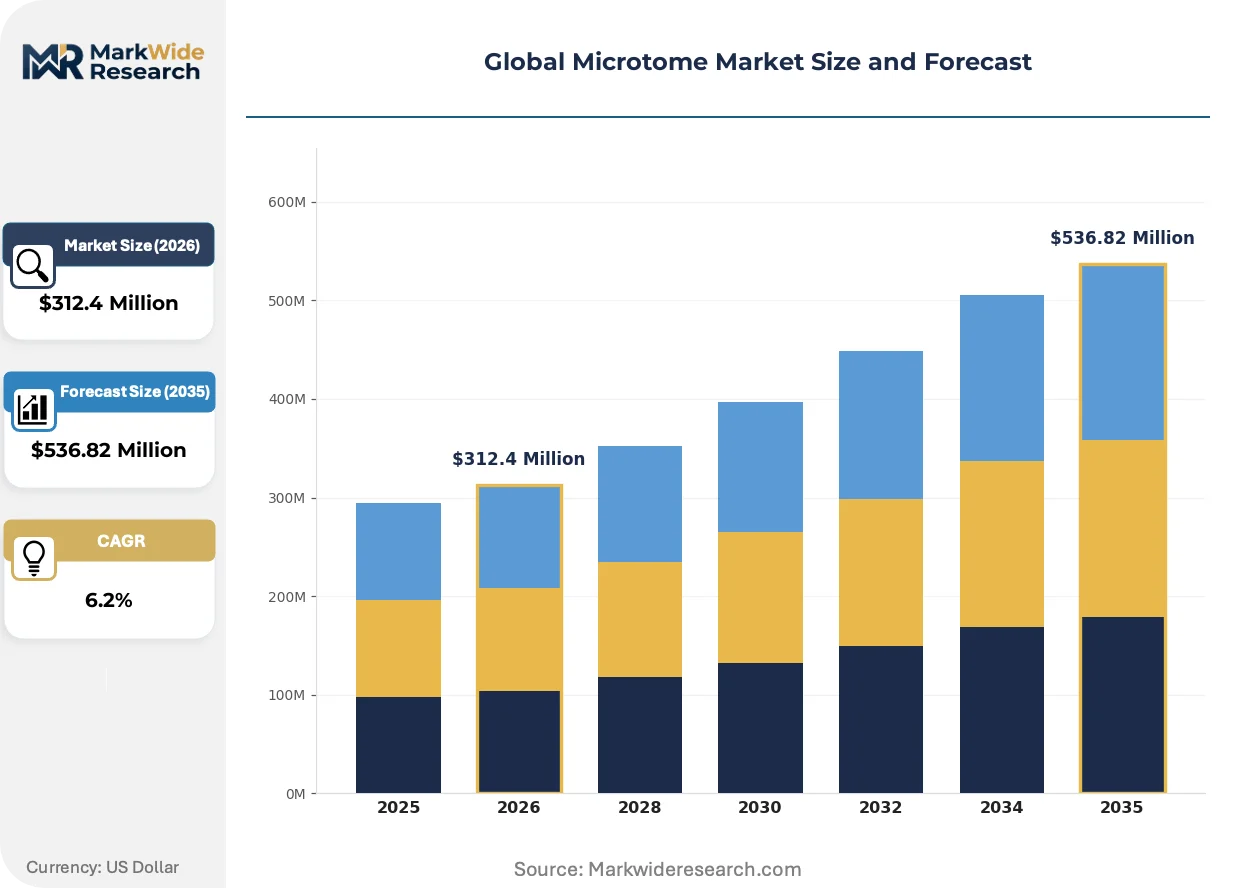
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $536.82 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Microtomes, Cryostat Microtomes, Ultramicrotomes, Sliding Microtomes, Frozen Section Microtomes Application: Histopathology, Neuroscience Research, Material Science, Botany, Forensic Analysis End User: Academic Institutions, Pharmaceutical Researchers, Diagnostic Laboratories, Biotechnology Firms Deployment: Laboratory Instruments, Research Equipment, Clinical Settings, Quality Control Units |
| Companies Covered | Thermo Fisher Scientific, Leica Biosystems, Sakura Finetek, Danaher Corporation, PHC Holdings Corporation, SLEE medical GmbH, Boeckeler Instruments, MEDITE Medical GmbH, Histo-Line Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microtome Market Shifts & Advancements
Automation architectures are fragmenting across standalone motorized units, semi-automated cranks with digital feedback, and fully integrated slide preparation systems. Vendors differentiate through blade technology, service density, and software ecosystem anchoring rather than hardware specifications alone.
Sectioning automation is modularizing as manufacturers decouple motorized advance mechanisms from base microtome platforms. Mid-volume diagnostic laboratories in Germany and the United States retrofit existing rotary frames with motorized kits rather than full system replacement. This modularity compresses capital expenditure cycles and extends installed base lifespans while creating aftermarket attachment revenue streams for incumbent suppliers.
The EU MDR's Class I device clinical evidence requirements are reshaping aftermarket service obligations across European markets. Manufacturers must now maintain technical documentation and post-market surveillance for refurbished units sold through certified pre-owned programs. High-volume clinical laboratories in France and the Netherlands respond by extending service contracts to ensure compliance documentation continuity.
Consolidated procurement through hospital network central purchasing departments is displacing individual laboratory autonomy in capital equipment selection. Integrated delivery networks in the United States and National Health Service trusts in the United Kingdom standardize on single-vendor workflows to reduce training complexity and consumables inventory. This concentration shifts negotiating leverage toward buyers and compresses margin structures for mid-tier equipment suppliers.
Global Microtome Market Segmentation
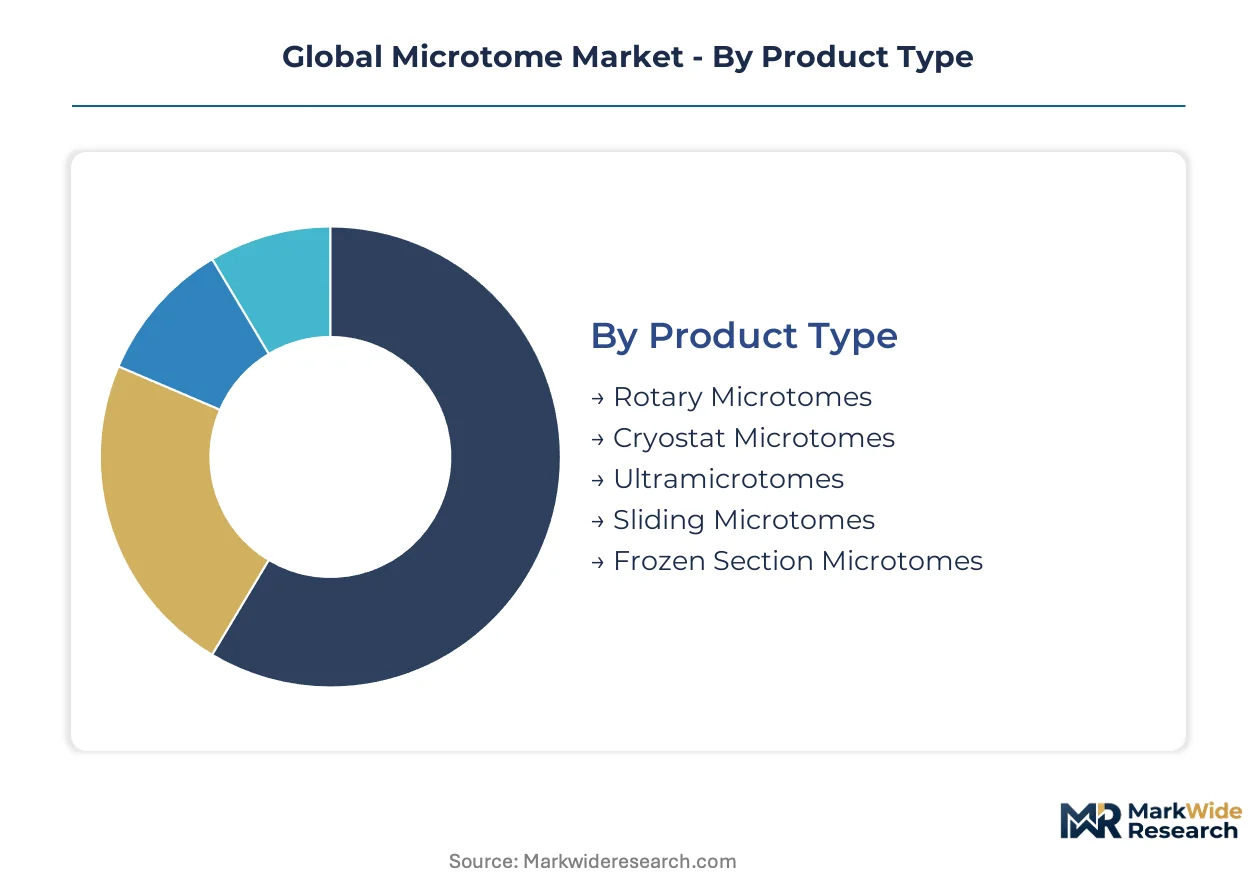
Microtome procurement patterns diverge sharply across use cases, with replacement cycles and integration requirements dicting capital allocation priorities. Laboratories segment their investments by throughput demands, regulatory compliance burdens, and digital pathology readiness timelines.
Product Type:
Upgrade decisions pivot on whether laboratories prioritize throughput automation or preserve capital through modular retrofits of existing frames.
- Rotary Microtomes:These crank-driven or motorized units section paraffin-embedded specimens through a rotating wheel mechanism, achieving thickness precision down to 0.5 micrometers. Diagnostic laboratories in Germany's Heidelberg-Mannheim medical device cluster favor these for routine histopathology workflows where volume justifies dedicated units.
- Cryostat Microtomes:Equipped with enclosed freezing chambers maintaining temperatures between -20°C and -30°C, these systems enable rapid intraoperative sectioning of unfixed tissue. Oncology centers in the United States drive placements where surgical margin assessment speed determines clinical utility and reimbursement capture.
- Ultramicrotomes:Specialized units for electron microscopy sample preparation, employing diamond knives to achieve nanometer-scale sectioning for pharmaceutical nanomaterial characterization.
- Sliding Microtomes:Manual or semi-automated systems where the specimen block moves horizontally against a fixed blade, preferred for large-format sections in botanical and materials applications.
- Frozen Section Microtomes:Compact units optimized for rapid deployment in operating suite environments, with simplified blade exchange and minimal warm-up protocols.
Volume placements concentrate in Rotary Microtomes; the faster expansion belongs to Cryostat Microtomes.
Application:
End-use differentiation reflects divergent specification requirements across specimen types and analytical endpoints.
- Histopathology:Clinical diagnostic workflows demand consistent section thickness, ribbon quality, and blade longevity under high-throughput conditions. Hospital network laboratories in France and the Netherlands prioritize ISO 13485-certified systems to satisfy EU MDR documentation requirements.
- Neuroscience Research:Brain tissue sectioning for connectivity mapping and optogenetic applications requires specialized specimen holders and vibration-dampening architectures. Academic medical centers in the United States face commissioning delays due to histotechnologist training pipeline gaps.
- Material Science:Hard specimen sectioning for metals, ceramics, and composites employs diamond blade configurations and reinforced mechanical structures.
- Botany:Large-section plant tissue preparation utilizes sliding microtome architectures with extended specimen travel ranges.
- Forensic Analysis:Post-mortem tissue examination combines routine histology with specialized staining protocols, driving demand for versatile blade systems.
Histopathology commands the dominant placement share; Neuroscience Research is climbing the fastest as brain mapping initiatives expand.
End User:
Procurement autonomy varies by institutional scale, with consolidated purchasing departments displacing individual laboratory decision-making.
- Academic Institutions:University pathology departments balance research flexibility against teaching mission requirements, often maintaining mixed fleets of manual and automated units. Budget constraints in US public university systems extend replacement cycles beyond typical depreciation schedules.
- Pharmaceutical Researchers:Contract research organizations in India and China expand ultramicrotome capacity to support nanomaterial characterization for regulatory submission packages.
- Diagnostic Laboratories:Independent and hospital-affiliated labs face margin compression from reimbursement rate pressures, driving interest in certified pre-owned equipment and extended service contracts.
- Biotechnology Firms:Venture-backed companies prioritize workflow integration and software ecosystem compatibility over standalone hardware specifications.
Diagnostic Laboratories anchor current volume; Pharmaceutical Researchers are gaining share fastest as outsourced microscopy services expand.
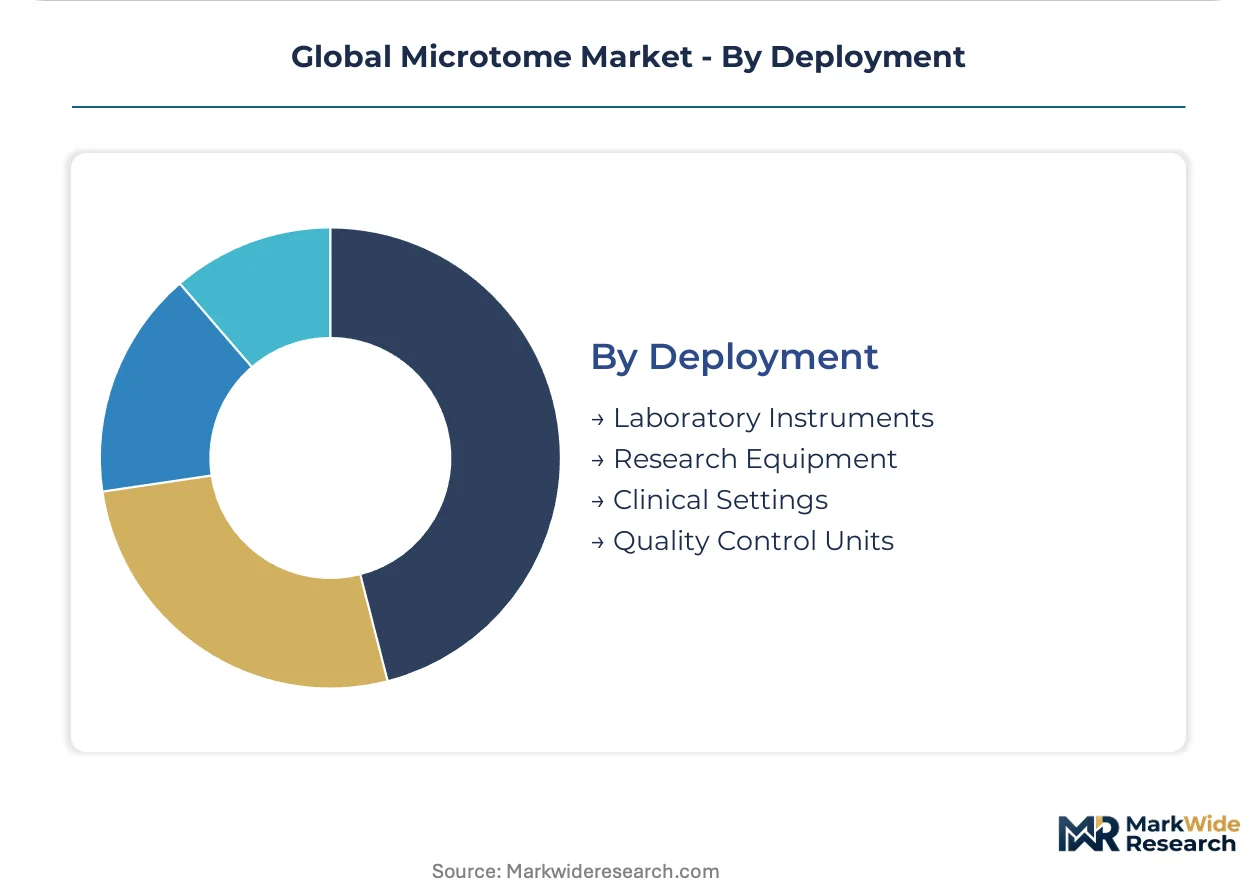
Deployment:
Facility classification determines environmental controls, operator certification requirements, and maintenance protocols.
- Laboratory Instruments:Dedicated histology suites with controlled temperature and humidity specifications, requiring electromagnetic compatibility certification under IEC 61010 standards.
- Research Equipment:Multi-user environments with flexible configuration requirements and emphasis on interoperability with imaging systems.
- Clinical Settings:Point-of-care and operating suite deployments prioritize rapid startup, minimal maintenance, and intuitive operator interfaces.
- Quality Control Units:Industrial microscopy applications in pharmaceutical manufacturing and materials testing, with emphasis on audit trail documentation and calibration traceability.
Laboratory Instruments dominate current placements; Clinical Settings are expanding most quickly as intraoperative pathology services proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heidelberg and Mannheim anchor the medical device cluster where precision machining capabilities concentrate for microtome blade manufacturing. Hospital network laboratories across Germany's Baden-Württemberg region drive replacement cycles for automated sectioning systems. The EU MDR compliance timelines reshape aftermarket service obligations throughout European markets.
United States
Oncology centers in Boston and Houston expand intraoperative frozen section workflows, driving cryostat microtome placements where surgical margin assessment speed determines reimbursement capture. The FDA's 510(k) pathway governs device registration timelines for new market entrants. Academic medical centers in California face histotechnologist training pipeline gaps that extend equipment commissioning schedules.
Germany
Diagnostic laboratories in the Heidelberg-Mannheim corridor prioritize ISO 13485-certified rotary microtomes to satisfy EU MDR documentation requirements for high-throughput histopathology. The country's national medical device regulator enforces tightened clinical evidence standards for Class I device recertification. Precision machining suppliers in Baden-Württemberg dominate motorized advance mechanism production for automated systems.
China
Contract research organizations in Shanghai and Suzhou expand ultramicrotome capacity for pharmaceutical nanomaterial characterization supporting regulatory submission packages. The National Medical Products Administration streamlines device registration pathways for imported histology equipment. Domestic manufacturers in the Yangtze River Delta region develop localized blade supply chains to reduce import dependency.
India
Hospital networks in Mumbai and Bangalore accelerate procurement of entry-level manual units as tier-2 city diagnostic infrastructure expands. The Central Drugs Standard Control Organization pathway simplification opens access to centralized procurement programs for refurbished equipment. Regional distributors in Maharashtra and Karnataka build service density to support aftermarket blade replenishment programs.
Japan
Neuroscience research institutes in Tokyo and Osaka drive demand for vibration-dampening microtome architectures in brain tissue connectivity mapping applications. The Pharmaceuticals and Medical Devices Agency maintains stringent quality management audits that extend product registration cycles for foreign manufacturers. Specialized tungsten carbide blade manufacturing concentrates in Nagoya-area supplier networks serving domestic OEMs.
Global Microtome Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and service bundling dimensions. The vendor base stratifies between integrated life science conglomerates with workflow software ecosystems and specialized histology equipment fabricators with regional service density. Three archetypes dominate: precision instrument manufacturers with histopathology heritage, diversified laboratory technology conglomerates with sample-to-imaging portfolios, and regional specialists with embedded blade technology. Competitive moves concentrate on certified refurbishment program expansion and direct consumables subscription models that bypass distributor markups.
Among precision instrument manufacturers with histopathology heritage, Leica Biosystems and SLEE medical GmbH exemplify the premium-tier archetype through sustained pricing power in high-volume clinical settings. Thermo Fisher Scientific anchors the diversified conglomerate position through integrated workflow solutions spanning sample preparation to imaging. Sakura Finetek occupies the regional specialist tier with differentiated service density in Asia-Pacific markets. Boeckeler Instruments and MEDITE Medical GmbH represent mid-scale German fabricators competing on modular retrofit kits rather than full system replacement. PHC Holdings Corporation and Danaher Corporation sit within the life science platform category where microtome portfolios complement broader diagnostic equipment offerings.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Leica Biosystems |
| Sakura Finetek |
| Danaher Corporation |
| PHC Holdings Corporation |
| SLEE medical GmbH |
| Boeckeler Instruments |
| MEDITE Medical GmbH |
| Histo-Line Laboratories |
| Others |
Supply & Pricing Matrix
Precision machinist concentrations in Baden-Württemberg and Nagoya create labor-cost differentials that spread pricing tiers across automated rotary systems, semi-motorized retrofits, and entry-level manual units. Swiss and German supplier networks for motorized advance mechanisms command premium positioning against Asian fabrication alternatives serving price-sensitive diagnostic laboratories.
Pricing Analysis
Value-based pricing anchors on throughput guarantees and uptime commitments in service contracts rather than hardware list prices alone. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified automated systems from modular retrofit kits and basic manual units. Cost compression in the economy tier intensifies as Indian and Chinese domestic manufacturers expand localized blade supply chains. Price sensitivity concentrates among independent diagnostic laboratories facing reimbursement rate pressures, while hospital network procurement departments prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Freight costs for precision-machined motorized advance mechanisms from Switzerland and Germany elevate landed costs for automated systems in Asia-Pacific markets. Manufacturing concentrates in Germany, Japan, and China for blades, motorized components, and base frames respectively. Specialized tungsten carbide and diamond blade production draws from Nagoya-area and Heidelberg-Mannheim supplier networks. Single-source vulnerability in high-precision blade supply creates structural risk for OEMs dependent on German and Japanese specialty metallurgy. Distribution runs through authorized service distributors with certified technician networks for installation and maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microtome market sits in a technology-transition phase where motorized retrofit kits and AI-assisted section quality monitoring displace legacy manual rotary systems. Laboratories recalibrate capital allocation toward modular automation rather than full-system replacement.
For Market Incumbents: Deepen certified refurbishment program expansion to capture installed base retention under EU MDR documentation requirements. Strengthen captive blade supply through backward integration into tungsten carbide manufacturing or long-term offtake agreements with Nagoya suppliers. Incumbent positioning faces erosion from domestic Chinese manufacturers with localized cost structures.
For New Entrants and Emerging Players: Launch via direct-to-laboratory consumables subscription models that bypass distributor markups in price-sensitive India and Southeast Asia markets. Target tier-2 city hospital networks in Maharashtra and Karnataka with entry-level manual units supported by regional service density. White-space opportunity concentrates in AI-assisted section quality monitoring as a standalone software module compatible with existing rotary frames.
For Investors and Strategic Acquirers: Re-rating potential sits with regional specialists possessing embedded blade technology and Asia-Pacific service density given digital pathology integration timelines compressing replacement cycles. Long-term viability favors manufacturers with software ecosystem anchoring rather than standalone hardware positioning. Watch hospital network consolidation rates as the signal indicating procurement leverage shifts toward buyers or suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Refurbishment Program Expansion | EU MDR documentation requirements for Class I devices extend service contract attach rates in European markets. |
| AI-Assisted Section Quality Module Development | Machine vision integration enables real-time thickness verification addressing histotechnologist training pipeline gaps. |
| Direct Consumables Subscription Launch | Blade replenishment programs bypass distributor markups capturing margin in price-sensitive Asia-Pacific laboratories. |
| Modular Motorized Retrofit Kit Introduction | Mid-volume diagnostic laboratories in Germany and the United States compress capital expenditure cycles through frame extension. |
| Localized Blade Supply Chain Development | Domestic manufacturing in China and India reduces import dependency and freight cost exposure for OEMs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with histopathology laboratory directors, biomedical equipment procurement managers, GPO contracts specialists, and aftermarket service technicians combined with secondary validation from FDA 510(k) databases, EU MDR technical documentation, and ISO 13485 certification registries. Bottom-up triangulation across product-type shipment estimates and top-down reconciliation against hospital network capital expenditure disclosures ensured cross-validation.
Granularity-level modeling operated at the intersection of product type, application, end user, and deployment configuration dimensions throughout the forecast period. CAGRs derived from regression analysis against diagnostic procedure volume growth and digital pathology adoption curves. Forecast inputs incorporated EU MDR compliance timeline impacts on replacement cycles and cryostat microtome penetration rates in oncology center expansion programs.
Regulatory pathway delays, hospital network consolidation velocity, and blade supply chain disruptions are the dominant revision risks for projections across the analysis window. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Forensic Equipment and Supplies Market
Medical Equipment
Global Medical Vacuum System Market
Medical Equipment
Medical Oxygen Cylinders Market
Medical Equipment
Defibrillator Analyzers Market
Medical Equipment
Cryopreservation Systems Market
Medical Equipment
Air Fluidized Therapy Beds Market
Medical Equipment
Faecal Extraction System Market
Medical Equipment
PMMA Healthcare Market
Medical Equipment
Proctologic Table Market
Medical Equipment
Global Indirect Calorimeter Market
Medical Equipment
Global Cardiopulmonary Stress Testing Systems Market
Medical Equipment
Global Carbon Dioxide Incubators Market
Medical Equipment
Global Renal Dialysis Equipment Market
Medical Equipment
Medical Physics Market
Medical Equipment
Hospital Stretchers Market
Medical Equipment
Medical Cart Battery Market