
 Durable Medical Equipment Rental Market | 2026-2036
Durable Medical Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Durable Medical Equipment Rental Market Intelligence
Modular rental bundles that combine hospital beds with preventive maintenance and delivery logistics is rebalancing procurement economics for health systems. Hill-Rom Holdings leverages its manufacturing scale to anchor long-term fleet contracts with integrated service tiers. Stryker Corporation competes through technology leadership in pressure-relief surfaces embedded within rental bed platforms. Medline Industries specializes in distribution density, controlling same-day delivery networks that reduce hospital capital lock-up.
Durable medical equipment rental encompasses the temporary provision of reusable therapeutic and diagnostic apparatus—typically rated for multi-year service life and subject to biomedical validation protocols—on a contracted-use basis rather than outright sale. The primary commercial purpose is to convert fixed capital expenditures into operational outlays while ensuring equipment uptime through vendor-managed maintenance. Hospital beds and respiratory machines capture the deepest margin pools due to high unit values and recurring calibration requirements. Home care end users represent the fastest-expanding demand channel as discharge planning prioritizes domestic recovery settings. Subscription-based payment models are displacing traditional insurance-funded structures among private-pay patients seeking cost predictability.
The FDA governs device safety and refurbishment standards for rental circulation, while Medicare reimbursement rules administered by CMS directly determine rental-versus-purchase incentives for eligible beneficiaries. State-level home care licensing boards add facility-based compliance layers that rental providers must navigate for fleet placement. Stakeholders should monitor evolving value-based care contracts that tie equipment rental duration to patient outcome metrics rather than fixed-term agreements.
Market Dynamics
Medicare reimbursement rules administered by CMS are compressing rental-versus-purchase economics for post-acute care, converting hospital capital expenditures into operational outlays while vendors absorb maintenance liability through fleet contracts.
Growth Catalysts
- CMS Rental Reimbursement:Medicare Part B's capped rental payment structure incentivizes beneficiaries to rent rather than purchase high-value equipment such as hospital beds and ventilators.
- Home Care Licensing:State-level facility accreditation requirements for home health agencies are mandating vendor-managed equipment provisioning with documented biomedical validation.
- Refurbishment Pathways:The FDA's 510(k) clearance process for reprocessed medical devices accelerates rental fleet redeployment cycles.
Market Restraints
- Biomedical Technician Scarcity:Calibration and preventive maintenance of respiratory equipment requires certified specialists concentrated in urban hospital clusters.
- Fleet Depreciation Concentration:Rental providers bear residual value risk on pressure-relief surfaces and infusion pumps with shortened Medicare allowable lifespans.
- State-by-State Licensing Friction:Home care facility regulations vary across jurisdictions, complicating interstate fleet logistics and compliance documentation.
Strategic Opportunities
- Rural Hospital Partnerships:Critical access hospitals in underserved counties lack capital budgets for equipment acquisition, creating demand for vendor-managed rental programs.
- Subscription Payment Models:Private-pay patients outside Medicare eligibility seek fixed monthly outlays for home oxygen and mobility equipment.
- Integrated Logistics Networks:Same-day delivery infrastructure for hospital bed deployment reduces acute care discharge delays and readmission penalties.
Industry Challenges
- Biomedical Validation Backlogs:FDA 510(k) submissions for refurbished device categories accumulate review delays, freezing fleet rotation timelines.
- Legacy EHR Integration:Rental equipment utilization data must interface with hospital electronic health record systems for outcome tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Durable Medical Equipment Rental Market |
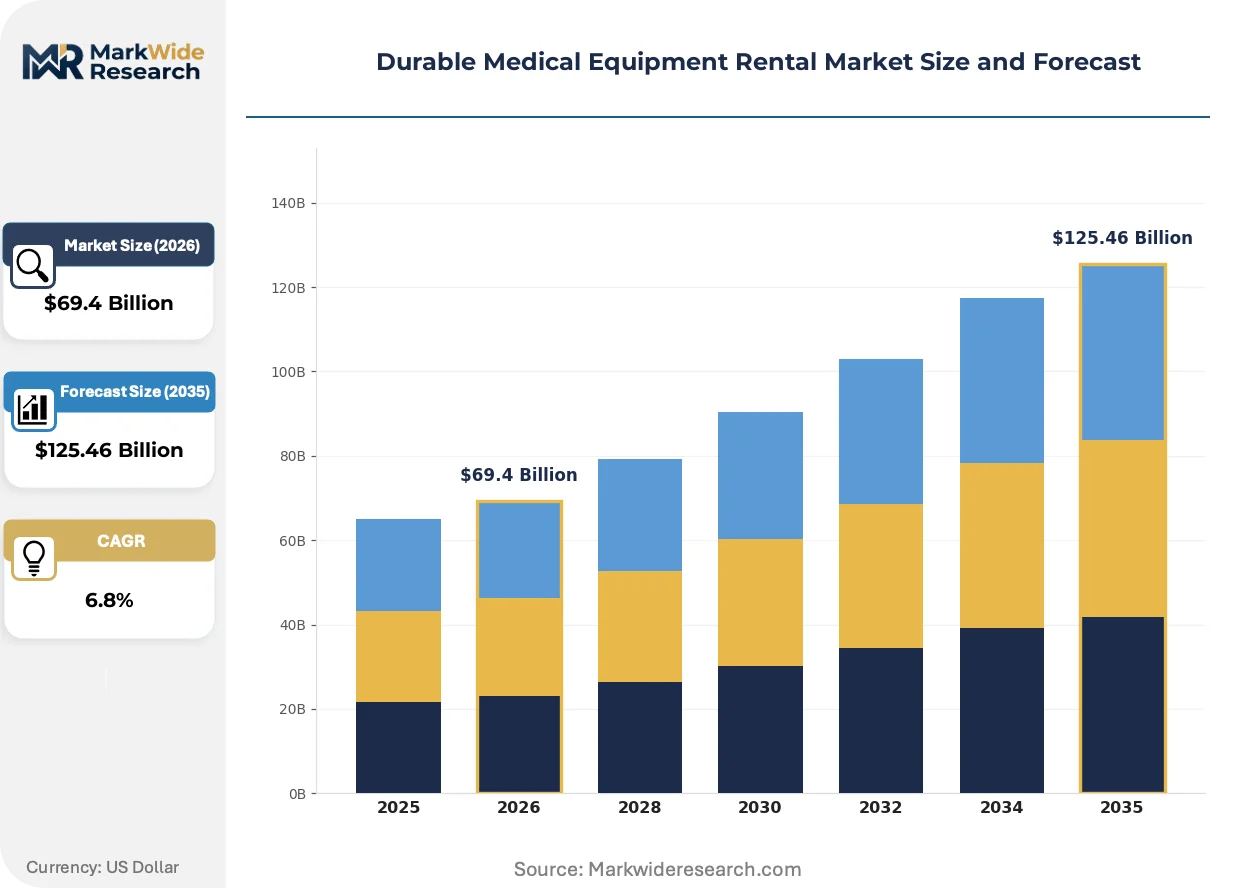
| Market Size in 2026 | $69.4 Billion |
| Market Size in 2035 | $125.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hospital Beds, Wheelchairs, Respiratory Machines, Mobility Scooters End User: Home Care, Hospitals, Rehabilitation Centers, Long-Term Care Facilities Service Type: Short-Term Rental, Long-Term Rental, Maintenance Service, Delivery Service Payment Model: Insurance-Funded, Out-of-Pocket, Subscription-Based, Government Assistance |
| Companies Covered | Hill-Rom Holdings Inc., Stryker Corporation, GE Healthcare, Siemens Financial Services, Medline Industries Inc., Universal Hospital Services Inc., Getinge AB, Woodley Equipment Company Ltd., Block Imaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Durable Medical Equipment Rental Market Strategic Shifts & Innovations
Remote monitoring capabilities embedded in rental equipment are transforming vendor-customer relationships from transactional lessors to outcome-accountable service partners.
IoT-enabled asset tracking is overtaking manual fleet management in rental respiratory and mobility equipment. Home care providers now demand real-time location and utilization dashboards. This visibility compression is enabling predictive maintenance scheduling and reducing emergency replacement costs.
The FDA's quality system regulation for refurbished medical devices is tightening documentation requirements for rental redeployment. Manufacturers must maintain device history records through multiple use cycles. Rental providers with captive refurbishment capabilities are capturing margin that previously flowed to third-party reprocessors.
Value-based care contracts are unbundling equipment rental from clinical service reimbursement. Health systems now negotiate per-patient equipment costs tied to length-of-stay reduction targets. This pricing compression is most visible in Medicare Advantage plans where hospitals retain readmission risk.
Durable Medical Equipment Rental Market Segmentation
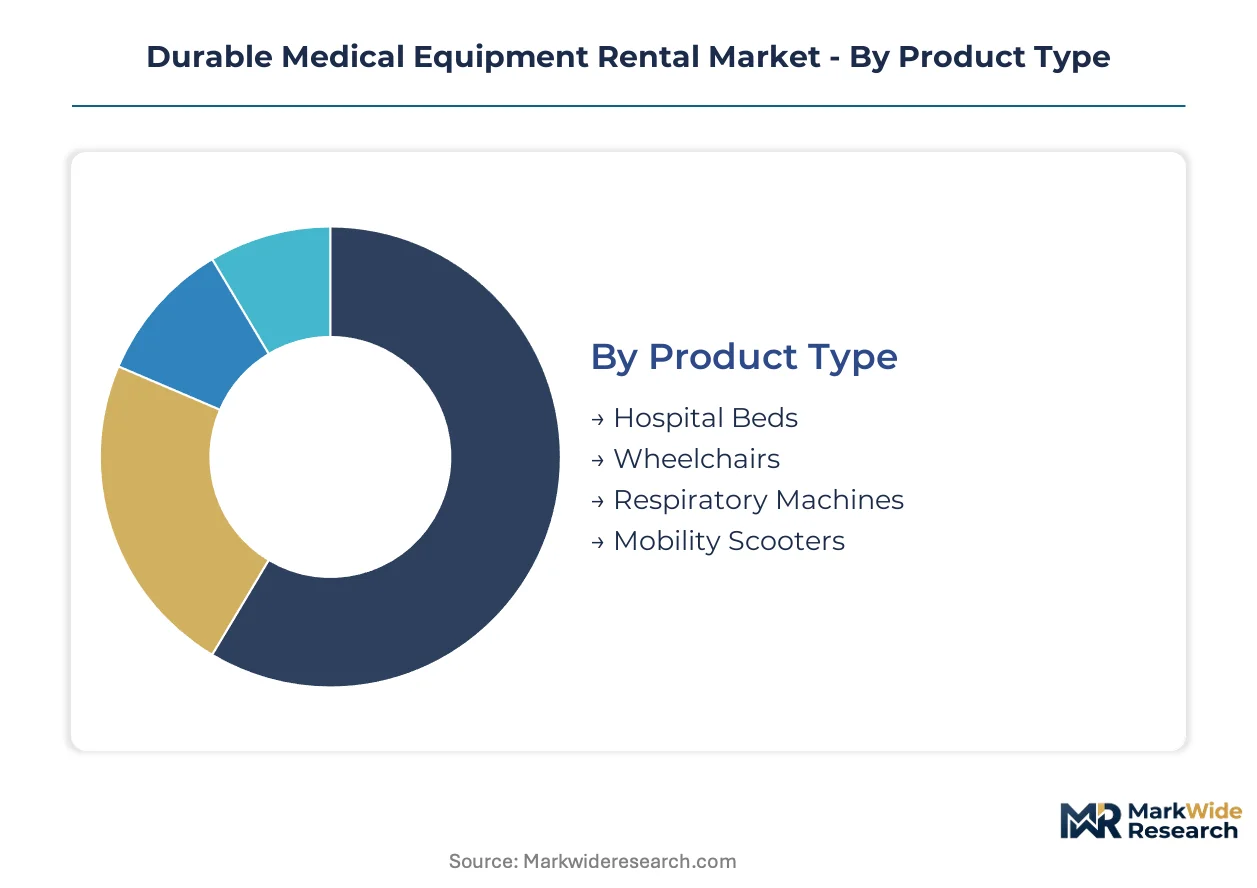
Segmentation in durable medical equipment rental determines capital allocation strategies for fleet operators and reimbursement pathways for end users. Product mix and payment models directly shape margin profiles, while service tier differentiation separates commodity lessors from integrated care partners.
Product Type:
Hospital beds command premium rental rates due to embedded pressure-relief technology and mandatory preventive maintenance schedules, while wheelchairs operate at volume scale with compressed margins.
- Hospital Beds:Multi-function electric beds with integrated side rails and Trendelenburg positioning require biomedical validation after each deployment. Demand concentrates in post-acute home care settings where CMS capped rental payments favor vendor-managed fleet models over patient purchase.
- Respiratory Machines:Ventilators and continuous positive airway pressure devices carry the highest per-unit rental values and strictest calibration protocols. Home oxygen therapy expansion is driving fastest volume growth among Medicare Part B beneficiaries transitioning from hospital to domestic recovery.
- Wheelchairs:Standard manual and power chair rentals serve short-term rehabilitation needs with rapid inventory turnover. Medicaid state programs represent the dominant demand channel with compressed reimbursement rates.
- Mobility Scooters:Four-wheel and travel-class scooters target ambulatory-limited seniors seeking community access. Private-pay retail channels outside insurance networks capture margin premiums.
Mature deployment sits with hospital beds. Newer deployment is concentrated in respiratory machines.
End User:
Institutional purchasers prioritize total cost of ownership and uptime guarantees, while individual consumers optimize for monthly payment predictability and rapid delivery logistics.
- Home Care:Discharge planning protocols now mandate domestic equipment provisioning before hospital release, creating vendor-managed rental demand with same-day delivery requirements. Medicare Advantage readmission penalties are forcing tighter coordination between rental providers and home health agencies.
- Hospitals:Acute care facilities rent surge capacity beds and specialty respiratory equipment to manage census spikes without capital expansion. Hill-Rom and Stryker anchor multi-year fleet contracts with integrated preventive maintenance tiers.
- Rehabilitation Centers:Skilled nursing facilities require short-term mobility equipment rentals with flexible term structures matching patient length-of-stay variability. State Medicaid waiver programs determine reimbursement eligibility.
- Long-Term Care Facilities:Nursing homes operate hybrid models combining owned base inventory with rented surge capacity for pressure-relief surfaces and bariatric beds. CMS five-star quality ratings influence equipment upgrade cycles.
Volume concentration remains with hospitals. Margin expansion is climbing the fastest in home care.
Service Type:
Contract duration and service bundling separate transactional rental from strategic partnerships that capture maintenance and logistics value pools.
- Long-Term Rental:Extended contracts spanning six months to multi-year terms cover hospital beds and home oxygen equipment with embedded preventive maintenance. CMS capped rental periods create predictable revenue streams for fleet operators.
- Maintenance Service:Biomedical calibration and repair contracts generate recurring revenue independent of rental term, with respiratory equipment requiring certified technician labor concentrated in urban markets.
- Short-Term Rental:Weekly and monthly terms serve post-surgical recovery and temporary disability needs with higher per-day rates offset by elevated logistics costs.
- Delivery Service:Same-day and next-day deployment logistics command premium pricing for hospital discharge coordination and emergency replacement scenarios.
Recurring revenue concentrates in long-term rental. Service innovation is gaining share fastest in integrated maintenance contracts.
Payment Model:
Reimbursement source determines pricing flexibility, contract complexity, and collection risk exposure across the rental portfolio.
- Insurance-Funded:Medicare Part B and commercial payer rental reimbursement follows strict documentation requirements and allowable charge schedules. Prior authorization delays create working capital pressure for providers.
- Subscription-Based:Fixed monthly payments for home oxygen and mobility equipment appeal to private-pay seniors seeking cost predictability outside Medicare eligibility windows.
- Government Assistance:Medicaid state programs and Veterans Affairs equipment provisions operate with procurement bidding requirements and compressed margins.
- Out-of-Pocket:Direct consumer payment captures premium pricing for convenience-oriented delivery and premium equipment tiers, particularly in mobility scooter categories.
Established volume sits with insurance-funded channels. Steepest expansion trajectory is visible in subscription-based structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters concentrate in the United States and Germany, while consumption spreads across aging populations in Japan and Southern Europe. Fleet operators source beds and respiratory devices from these production hubs, then deploy through regional distribution networks shaped by reimbursement rules.
United States
Medicare Part B capped rental payments and Medicare Advantage readmission penalties drive demand for vendor-managed home care equipment. The FDA's 510(k) clearance pathway for refurbished devices accelerates fleet redeployment cycles. Houston and Phoenix anchor major rental logistics hubs serving Sun Belt retirement corridors.
Germany
Statutory health insurance funds favor rental over purchase for hospital beds and mobility equipment, compressing capital expenditure timelines for acute care facilities. The EU Medical Device Regulation (MDR) imposes stricter documentation requirements on refurbished equipment circulation. The Rhine-Ruhr metropolitan region hosts dense networks of biomedical service technicians supporting rental fleet maintenance.
Japan
Super-aged demographics and government long-term care insurance expansion fuel demand for home-based rental equipment. The Pharmaceuticals and Medical Devices Agency (PMDA) governs refurbishment standards for multi-cycle device use. Osaka and Nagoya concentrate rental fleet operations serving Kansai and Chubu regional hospital systems.
United Kingdom
NHS England's capital constraints push acute trusts toward operational expenditure models for surge capacity beds. The Medicines and Healthcare products Regulatory Agency (MHRA) aligns with EU MDR transition timelines for device recertification. London's home care provider density creates same-day delivery infrastructure for hospital discharge coordination.
India
Private hospital chains in tier-1 cities adopt rental models to preserve working capital for expansion. The Central Drugs Standard Control Organisation (CDSCO) regulates medical device import and refurbishment standards. Maharashtra and Karnataka host emerging rental fleet operators targeting medical tourism recovery centers in Mumbai and Bengaluru.
Durable Medical Equipment Rental Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across equipment rental tiers. Hospital bed manufacturers with captive financing arms anchor multi-year fleet contracts, while independent service organizations capture maintenance revenue through third-party logistics networks. Two strategic archetypes dominate: integrated manufacturing-rental hybrids and distribution-density specialists. Competitive moves concentrate on same-day delivery infrastructure buildout and predictive maintenance technology licensing.
Among integrated manufacturing-rental hybrids, Hill-Rom Holdings Inc. and Stryker Corporation exemplify the archetype of production-scale players leveraging in-house fabrication to anchor long-term hospital fleet agreements. Medline Industries Inc. occupies a position within the distribution-density specialist tier, controlling fulfillment networks that reduce customer capital lock-up through rapid equipment deployment logistics.
| Leading Market Players |
|---|
| Hill-Rom Holdings Inc. |
| Stryker Corporation |
| GE Healthcare |
| Siemens Financial Services |
| Medline Industries Inc. |
| Universal Hospital Services Inc. |
| Getinge AB |
| Woodley Equipment Company Ltd. |
| Block Imaging |
| Others |
Cost & Logistics Intelligence
Certified biomedical technician concentration in the Rhine-Ruhr metropolitan region and the US Sun Belt creates labor-cost differentials that widen pricing-tier spreads between premium vendor-managed contracts and economy self-service rentals. CMS reimbursement compression and EU MDR compliance burdens amplify these spreads as providers pass through specialized labor and documentation costs.
Pricing Analysis
Margin tightening in economy-tier wheelchair rentals reflects Medicaid rate compression and rapid inventory turnover requirements. Three-tier pricing structure across premium, standard, and economy levels separates Hill-Rom's integrated fleet contracts from Medline's distribution-density plays and commodity manual chair lessors. Price differentiation rests on FDA 510(k) certification grade and same-day delivery geographic coverage. Cost-down pressure on standard-tier respiratory equipment accelerates because Medicare Part B capped rental periods limit revenue recovery windows. Home care agencies exhibit highest price sensitivity; hospital purchasing committees prioritize uptime guarantees over per-unit rates.
Supply Chain Analysis
Dual-sourcing requirements from hospital GPOs and Medicare Advantage plans mandate multi-supplier qualification for pressure-relief surfaces and infusion pump fleets. Manufacturing concentrates in the United States, Germany, and China, with FDA 510(k) and EU MDR recertification creating regional captive supply zones. Raw material dependencies span medical-grade polymers, precision motors, and sensor arrays. Supply chain risk centers on FDA 510(k) review backlogs freezing fleet rotation timelines. Distribution runs through same-day delivery networks anchored in Houston, Phoenix, and London discharge coordination hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The durable medical equipment rental market is consolidating as CMS reimbursement compression and FDA refurbishment documentation burdens force sub-scale operators toward exit. Capital discipline separates survivors from distressed assets.
For Market Incumbents: Extend predictive maintenance technology licensing to capture recurring revenue independent of rental term. Deepen backward integration into captive refurbishment capabilities to recapture margin from third-party reprocessors. Biomedical validation backlogs threaten fleet velocity; anchor multi-year hospital contracts with embedded preventive maintenance tiers to lock in capacity utilization.
For New Entrants and Emerging Players: Home health agency partnerships offer the most penetrable channel wedge. Rural critical access hospitals lack capital budgets and vendor coverage, creating white-space demand for vendor-managed rental programs. Target subscription-based private-pay models outside Medicare eligibility windows with fixed monthly outlays for home oxygen and mobility equipment.
For Investors and Strategic Acquirers: Re-rating potential sits with distribution-density specialists given same-day delivery infrastructure scarcity. Long-term viability favors operators with integrated logistics networks spanning hospital discharge coordination and home care placement. Watch Medicare Advantage readmission penalty severity as inflection indicator for vendor-managed equipment demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year fleet contracts with Hill-Rom and Stryker lock in recurring maintenance revenue streams. |
| FDA 510(k) Submission | Clearance pathway for refurbished devices accelerates rental fleet redeployment cycles and margin capture. |
| Reimbursement Strategy | Medicare Part B capped rental structures convert capital expenditures into predictable operational outlays. |
| Software Companion Development | IoT-enabled asset tracking transforms transactional lessors into outcome-accountable service partners. |
| CE Marking Pathway | EU MDR compliance opens statutory health insurance rental channels in Germany and adjacent markets. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital purchasing committee members, biomedical engineers, home health agency administrators, GPO contracts managers, and FDA regulatory affairs specialists combined with CMS Medicare reimbursement databases, FDA 510(k) submission records, and EU MDR transition documentation. Bottom-up fleet operator revenue triangulation against top-down reimbursement flow analysis validated market sizing.
Data-stream reconciliation across product type, end user category, service tier, and payment model dimensions shaped the analytical framework over the projection horizon. CAGRs derived from Medicare beneficiary growth trajectories, hospital discharge planning protocol adoption curves, and refurbishment cycle velocity assumptions. Home care licensing expansion and value-based care contract penetration served as industry-specific forecast inputs.
Caveats apply where FDA 510(k) review duration extensions or CMS reimbursement rate resets could materially shift the outlook. Forecasts reflect documented assumptions regarding Medicare Advantage readmission penalty enforcement and EU MDR implementation timelines. Deviation in biomedical technician labor availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Lasers Market
Medical Equipment
Medical Vending Machines Market
Medical Equipment
Medical X-Ray Generators Market
Medical Equipment
Electron Beam Linear Accelerators Market
Medical Equipment
Medical Tubing Market
Medical Equipment
Global Radiation Therapy Equipment Market
Medical Equipment
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market
Medical Equipment
ECG Equipment Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Europe Nuclear Medicine Equipment Market
Medical Equipment
Cryopreservation Systems Market
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
North America Radiotherapy Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
Apheresis Equipment Market