
 Global Examination Lights Market | 2026-2036
Global Examination Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Global Examination Lights Market Foresight
Hospital procurement consortiums is tilting toward multi-year service contracts bundled with LED fixture upgrades. Stryker leverages its surgical workflow integration to anchor premium ceiling-mounted installations in integrated delivery networks. STERIS competes through infection control protocols that bundle examination lighting with sterilization equipment packages.
Examination lights are medical-grade luminaires engineered to deliver color rendering indices exceeding 90 and adjustable color temperatures between 3,000 K and 6,700 K for accurate tissue visualization during diagnostic and minor surgical procedures. LED examination lights dominate current revenue pools due to superior energy efficiency and lumen maintenance over 50,000 hours, while halogen examination lights retain residual demand in cost-constrained veterinary and primary care settings. Ceiling-mounted technology leads hospital infrastructure deployments, whereas portable and mobile stand configurations are expanding fastest in ambulatory surgical centers and diagnostic imaging centers where room flexibility governs capital planning.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for manufacturers targeting North American and European buyers. China's NMPA medical device classification and GB 9706.1 electrical safety standards create parallel compliance obligations for firms sourcing components from or selling into that market. Stakeholders must monitor regulatory divergence between IEC harmonization efforts and jurisdiction-specific testing protocols when configuring regional product portfolios and certification budgets.
Market Dynamics
Hospital infrastructure modernization programs across the United States, Germany, and China are compressing replacement cycles for legacy halogen examination lights while elevating optical performance requirements tied to IEC 60601-1 third edition compliance.
Growth Catalysts
- EU MDR technical documentation:Compliance mandates are accelerating hospital procurement of LED-based examination luminaires with validated biocompatibility testing and traceable optical performance data.
- Ambulatory surgical centers:Outpatient volume expansion across developed and emerging healthcare systems is driving demand for portable and mobile stand configurations with room flexibility.
- LED lumen maintenance:Superior energy efficiency and 50,000-hour operational lifespans are displacing halogen units in cost-sensitive primary care and veterinary settings.
Market Restraints
- GB 9706.1 electrical safety standards:China's NMPA medical device classification creates parallel certification obligations that extend product development timelines and inflate market access costs for component suppliers.
- Optical component concentration:Specialized LED chip and heat-dissipation substrate manufacturing concentrates in East Asian supply bases, exposing procurement planners to logistics volatility and tariff exposure.
- Halogen residual demand:Cost-constrained veterinary clinics and rural primary care facilities continue specifying legacy incandescent technology, fragmenting volume concentration and complicating manufacturer portfolio rationalization.
Strategic Opportunities
- India's hospital infrastructure buildout:Central government health spending expansion and private diagnostic chain proliferation create unmet demand for mid-tier ceiling-mounted examination luminaires with localized service support.
- Surgical workflow integration:Convergence of examination lighting with operating room navigation systems and centralized control architectures enables premium positioning in integrated delivery networks.
- Multi-year service bundling:Hospital procurement consortiums are unbundling capital expenditure from maintenance obligations, creating recurring revenue streams for manufacturers with field service density.
Industry Challenges
- Optical engineering talent scarcity:Specialized expertise in color temperature calibration, heat management, and IEC 60601-1-10 electromagnetic compatibility testing concentrates at a limited number of medical device engineering centers.
- Legacy infrastructure integration:Ceiling-mounted LED retrofits frequently require structural assessment of suspended support systems and electrical conduit reconfiguration, complicating installation scheduling and cost estimation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Examination Lights Market |
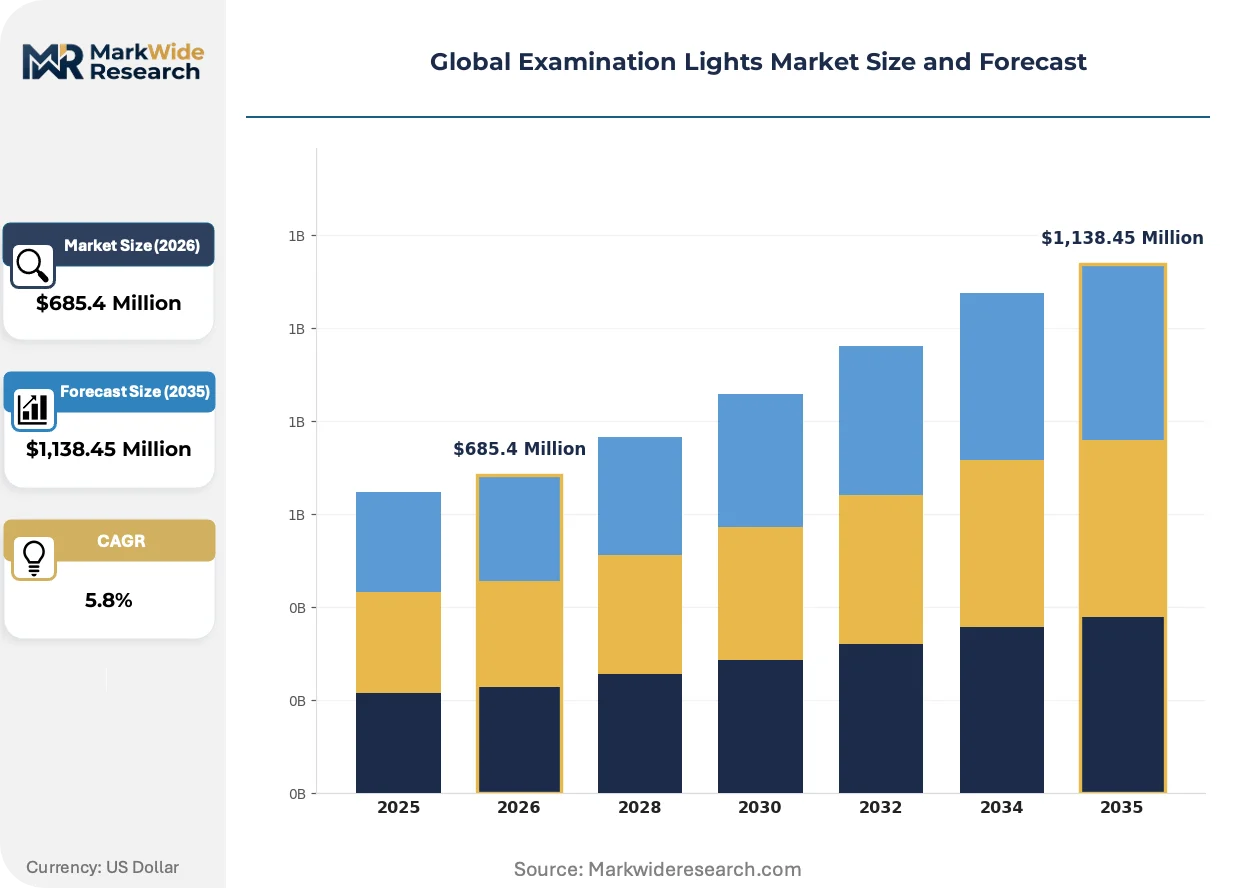
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Examination Lights, Halogen Examination Lights, Xenon Examination Lights, OLED Examination Lights Technology: Portable, Ceiling-Mounted, Wall-Mounted, Mobile Stand, Head-Mounted Application: Outpatient Care, Diagnostic Labs, Dental Procedures, Dermatology Clinics, Veterinary Clinics End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Diagnostic Imaging Centers |
| Companies Covered | Stryker, STERIS, Hillrom Services Inc., Getinge AB, Dr. Mach GmbH and Co. KG, Skytron, SIMEON Medical, Daray Medical, Brandon Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Examination Lights Market Shifts & Advancements
Examination lighting technology is converging with digital health infrastructure and intelligent building systems, reshaping how hospitals specify, procure, and operate diagnostic luminaires across acute and ambulatory settings.
Wireless control architectures and embedded sensor networks are digitizing examination light operation. Integrated delivery networks in the United States are specifying ceiling-mounted units with centralized dimming and scene preset capabilities. This connectivity layer is digitizing maintenance scheduling and enabling predictive replacement of LED arrays before lumen degradation affects tissue visualization accuracy.
EU MDR Article 10 technical documentation requirements are intensifying post-market surveillance obligations for manufacturers. Economic operators must now maintain systematic procedures for gathering and reviewing experience from devices in production. German hospital procurement consortiums are prioritizing suppliers with established vigilance systems and notified body rapporteur relationships.
Hospital buying committees are consolidating vendor relationships around full-room equipment packages. STERIS and Stryker are anchoring examination lighting within broader infection control and surgical workflow portfolios, displacing standalone luminaire specialists. This bundling dynamic is most pronounced in United States integrated delivery networks where capital committees favor single-source accountability for operating room infrastructure.
Global Examination Lights Market Segmentation
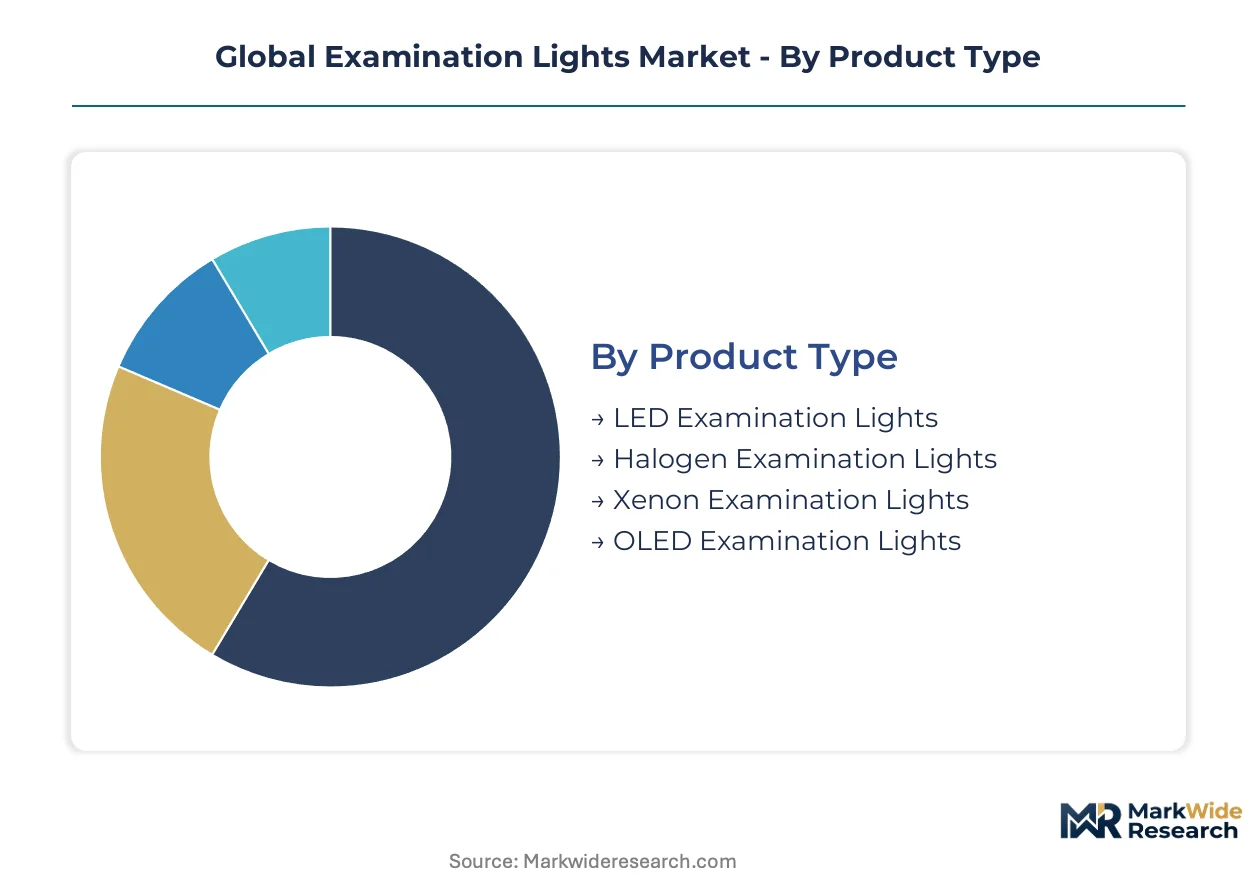
Examination light procurement patterns diverge sharply across installation configurations, light source technologies, and care delivery settings. Understanding these segment boundaries clarifies where manufacturers must configure distinct product portfolios and where bundling strategies capture cross-selling economics.
Product Type:
Cost tier differentiation across light source technologies determines replacement cycle timing and service contract attach rates in hospital capital planning.
- LED Examination Lights:Solid-state semiconductor arrays deliver color rendering indices above 90 with 50,000-hour lumen maintenance. Demand concentrates in United States integrated delivery networks where IEC 60601-1 third edition compliance elevates optical performance specifications.
- Halogen Examination Lights:Tungsten-halogen incandescent sources remain specified in cost-constrained veterinary clinics and rural primary care facilities across India and Southeast Asia. Procurement volume fragments as LED pricing compression narrows the first-cost gap.
- Xenon Examination Lights:High-intensity discharge technology retains niche deployment in surgical suites requiring maximum illuminance density.
- OLED Examination Lights:Organic semiconductor panels enable ultra-thin form factors for space-constrained examination rooms.
LED holds installed capacity. OLED is rotating up the share rankings.
Technology:
Application context governs installation modality selection, with room flexibility requirements in ambulatory settings diverging from fixed infrastructure in acute care.
- Ceiling-Mounted:Suspended rail systems with centralized power delivery dominate hospital operating suites and procedure rooms in Germany and China. Structural assessment requirements for retrofits complicate replacement scheduling.
- Mobile Stand:Castor-based configurations with battery backup enable rapid room reconfiguration in ambulatory surgical centers across the United States. Outpatient volume expansion accelerates procurement of units with wireless control integration.
- Portable:Handheld and clip-mounted units serve field medicine and home health applications.
- Wall-Mounted:Articulating arm designs maximize floor space in compact examination rooms.
- Head-Mounted:Loupe-integrated illumination supports precision procedures in dental and microsurgical settings.
Ceiling-mounted anchors revenue concentration. Mobile stand is climbing the fastest.
Application:
Procedure-specific illumination requirements shape color temperature and intensity specifications across diagnostic and therapeutic settings.
- Outpatient Care:General examination rooms require adjustable 3,000 K to 6,700 K color temperature for tissue visualization accuracy. United States ambulatory networks standardize on LED retrofits with centralized dimming protocols.
- Diagnostic Labs:Pathology workstations demand consistent color rendering for specimen analysis. German laboratory accreditation standards drive specification of validated optical performance data.
- Dental Procedures:Chair-mounted integration requires compact headlamp designs with shadow reduction.
- Dermatology Clinics:Polarized and UV-augmented configurations support lesion examination protocols.
- Veterinary Clinics:Cost sensitivity sustains halogen residual demand in companion animal practices.
Outpatient care commands volume leadership. Diagnostic labs is gaining share fastest.
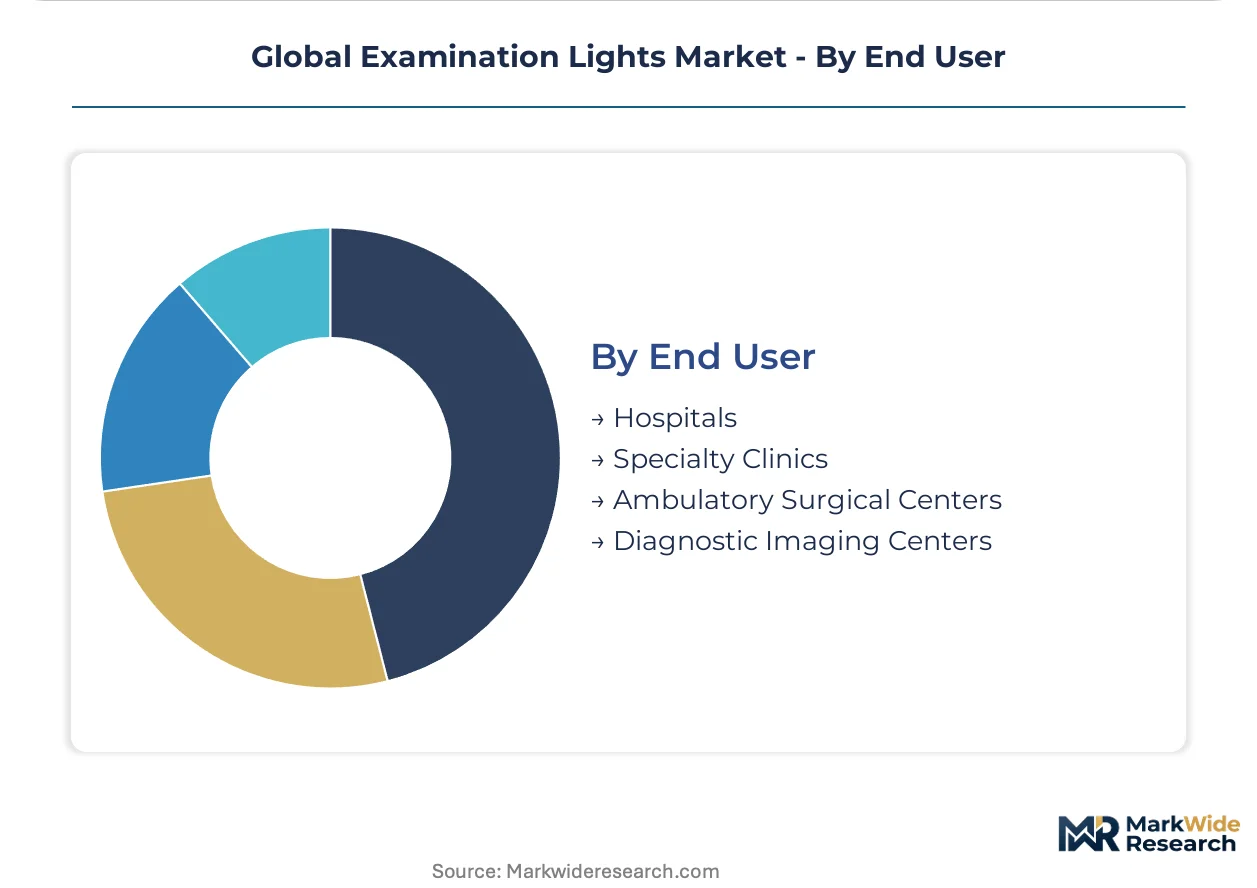
End User:
Customer type determines procurement authority structures, with consolidated buying committees in hospital systems diverging from individual practice decisions in specialty clinics.
- Hospitals:Capital committees in United States integrated delivery networks bundle examination lighting with surgical workflow and infection control portfolios. Multi-year service contracts displace standalone equipment purchases.
- Ambulatory Surgical Centers:Freestanding outpatient facilities in China and India prioritize portable and mobile configurations with rapid deployment capability. Central government health spending expansion accelerates infrastructure buildout.
- Specialty Clinics:Dermatology, ophthalmology, and ENT practices specify procedure-optimized illumination with minimal installation disruption.
- Diagnostic Imaging Centers:Radiology and pathology co-location drives demand for consistent optical environments across examination and analysis zones.
Hospitals retain procurement volume dominance. Ambulatory surgical centers is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal hospital infrastructure programs across the United States, Germany, and China are compressing replacement cycles for legacy halogen examination lights while elevating optical performance requirements tied to IEC 60601-1 third edition compliance.
United States
Integrated delivery networks in Texas and Florida are bundling LED examination luminaires with multi-year service contracts. FDA 510(k) clearance pathways shape product development timelines for manufacturers targeting hospital procurement consortiums. The Greater Boston medical device cluster anchors premium ceiling-mounted installations in academic medical centers.
Germany
Hospital procurement consortiums in Bavaria and North Rhine-Westphalia prioritize suppliers with established EU MDR vigilance systems. The EU MDR Article 10 technical documentation requirements intensify post-market surveillance obligations for manufacturers. The Stuttgart-Heilbronn medical technology corridor concentrates optical engineering expertise for color temperature calibration systems.
China
Central government health spending expansion accelerates infrastructure buildout in ambulatory surgical centers across Jiangsu and Zhejiang provinces. NMPA medical device classification and GB 9706.1 electrical safety standards create parallel certification obligations for component suppliers. The Yangtze River Delta manufacturing base concentrates specialized LED chip and heat-dissipation substrate production.
India
Private diagnostic chain proliferation in Maharashtra and Karnataka creates unmet demand for mid-tier ceiling-mounted examination luminaires. CDSCO medical device rules govern import and registration requirements for foreign manufacturers. The Delhi-NCR corridor attracts localized service support investments from multinational suppliers.
Japan
Metropolitan hospital districts in Tokyo and Osaka specify examination lighting with centralized dimming protocols for aging facility retrofits. PMDA medical device regulations align with IEC harmonization efforts while maintaining jurisdiction-specific testing protocols. The Nagoya medical equipment cluster supports precision optical component sourcing for domestic manufacturers.
Global Examination Lights Market Competitive Landscape
On the supply side, the industry is consolidating around surgical workflow integrators and infection control specialists that bundle examination lighting within broader equipment portfolios. Three strategic archetypes dominate: integrated medical technology conglomerates with full-room solutions, standalone luminaire specialists with optical engineering depth, and regional fabricators serving cost-constrained veterinary and primary care segments. Competitive positioning depends on multi-year service contract density and backward integration into LED array sourcing.
Within the integrated technology tier, Stryker and STERIS exemplify vendors anchoring premium ceiling-mounted installations through surgical workflow and sterilization equipment bundling. SIMEON Medical and Dr. Mach GmbH and Co. KG occupy positions among German optical engineering specialists with established notified body relationships for EU MDR compliance. Hillrom Services Inc. and Getinge AB represent diversified medical equipment manufacturers with field service networks spanning hospital procurement consortiums.
| Leading Market Players |
|---|
| Stryker |
| STERIS |
| Hillrom Services Inc. |
| Getinge AB |
| Dr. Mach GmbH and Co. KG |
| Skytron |
| SIMEON Medical |
| Daray Medical |
| Brandon Medical |
| Others |
Supply & Pricing Matrix
Tariff exposure on specialized LED chip imports from East Asian manufacturing bases determines both pricing tier spreads and supply chain configuration for examination luminaire producers. Procurement planners face compressed margins when component sourcing concentrates in tariff-vulnerable jurisdictions, forcing tiered pricing stratification that separates IEC 60601-1 certified premium fixtures from standard-grade alternatives.
Pricing Analysis
Certification level creates the primary spread across examination light pricing tiers, with FDA 510(k) cleared and EU MDR compliant units commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects optical performance grade, after-sales service bundling, and geographic delivery cost differentials. Cost compression in economy tiers is intensifying because LED pricing compression narrows the first-cost gap with legacy halogen units. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraint structures, while United States integrated delivery networks prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Export control regimes on advanced semiconductor manufacturing equipment limit technology transfer for high-efficiency LED chip production, constraining supply base expansion outside established East Asian centers. Component manufacturing concentrates in China, South Korea, and Taiwan, with specialized heat-dissipation substrates and precision optical lenses drawing from concentrated regional production. Single-source vulnerability persists for medical-grade LED arrays certified to IEC 60601-1-10 electromagnetic compatibility standards. Distribution runs through hospital procurement consortiums and specialized medical equipment distributors serving ambulatory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital procurement consortium consolidation in United States integrated delivery networks and German hospital alliances, fragmenting vendor access and elevating service contract requirements as table stakes.
For Market Incumbents: Pre-empt margin erosion from bundled equipment competition by anchoring multi-year service contracts with predictive maintenance capabilities and LED array replacement scheduling. Deepen backward integration into heat-dissipation substrate sourcing to insulate against tariff volatility on East Asian component imports. Fortify notified body relationships for EU MDR vigilance system compliance to defend procurement eligibility in German consortium tenders.
For New Entrants and Emerging Players: Build out localized service infrastructure in India's Maharashtra and Karnataka corridors where private diagnostic chain proliferation outpaces established vendor field density. Target mid-tier ceiling-mounted configurations for cost-sensitive ambulatory surgical centers in China's Jiangsu and Zhejiang provinces. Pursue regulatory sandbox partnerships with CDSCO to accelerate import registration timelines for foreign manufacturers.
For Investors and Strategic Acquirers: EU MDR Article 10 technical documentation requirements reshape the acquisition landscape toward targets with established post-market surveillance systems and notified body rapporteur relationships. Five-to-ten year viability hinges on software-integrated lighting architectures converging with operating room navigation platforms. Acquisition target archetype: German optical engineering specialists with IEC 60601-1-10 testing capabilities and sparse field service coverage in India. Signal to monitor: hospital GPO contract consolidation velocity in Texas and Florida markets.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Vigilance System Investment | Establishes notified body rapporteur relationships required for German hospital consortium eligibility. |
| Hospital System Partnership | Locks in multi-year service contracts with integrated delivery networks in Texas and Florida. |
| Software Companion Development | Enables centralized dimming protocols and predictive maintenance scheduling for LED arrays. |
| CE Marking Pathway Acceleration | Compresses technical documentation timelines for EU MDR Article 10 compliance obligations. |
| Backward Integration into Substrates | Captive supply of heat-dissipation components insulates margin from East Asian tariff exposure. |
Research Methodology
Cross-validation between primary interviews with hospital procurement managers, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, and hospital capital expenditure records. Bottom-up and top-down triangulation reconciles equipment shipment data with procurement consortium contract disclosures. Field intelligence from ambulatory surgical center administrators and optical engineering specialists in the Stuttgart-Heilbronn corridor supplements quantitative segmentation modeling.
Calibration against historical replacement cycle data for legacy halogen units and LED adoption curves in United States integrated delivery networks informs the projection framework across the analysis window. Segmentation dimensions span light source technology, installation configuration, application setting, and end-user procurement authority structure. CAGRs derive from installed base depreciation schedules, regulatory compliance-driven replacement mandates, and outpatient volume expansion trajectories. Industry-specific inputs include IEC 60601-1 third edition adoption timelines and NMPA medical device classification processing rates.
Stress conditions across tariff rate volatility, LED component supply disruption, and EU MDR notified body capacity constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hospital infrastructure modernization program continuity and ambulatory surgical center buildout rates in China and India. Cross-checking against CMS Medicare outpatient procedure volume data and German hospital procurement consortium contract award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
Mercury Thermometer Market
Medical Equipment
Medical Gas Cylinders Market
Medical Equipment
Medical Physics Market
Medical Equipment
China Radiotherapy Market
Medical Equipment
North America Medical Device Reprocessing Market
Medical Equipment
Global Medical Equipment Cooling Market
Medical Equipment
Medical Ultrasonic Baths Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market
Medical Equipment
Medical Oxygen Gas Cylinder Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
Global Laminar Airflow Cabinets Market
Medical Equipment
Global Latex Medical Gloves Market