
 Durable Medical Equipment Market | 2026-2036
Durable Medical Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Durable Medical Equipment Market Analysis
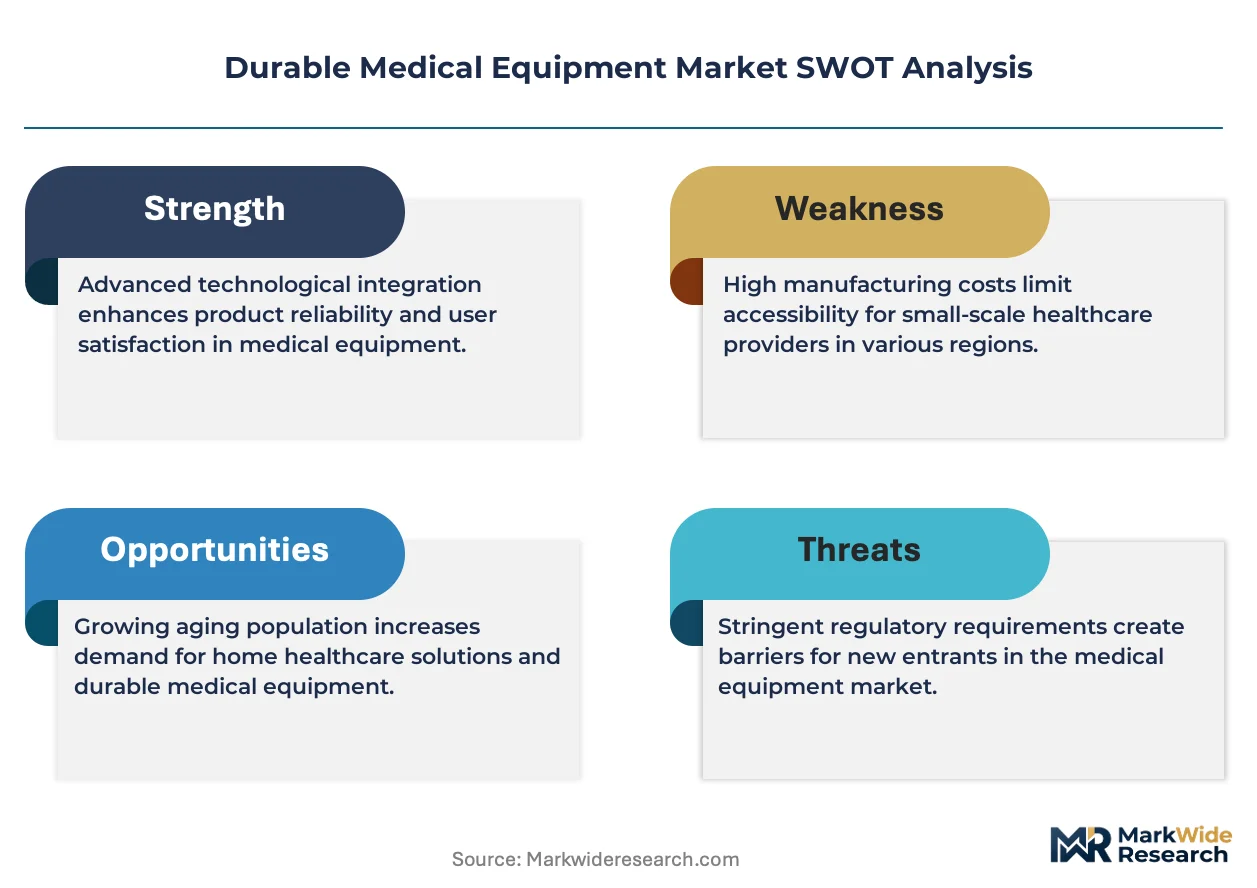
The EU Medical Device Regulation (MDR) is shifting procurement criteria across European healthcare systems toward devices with demonstrable long-term clinical evidence. Medtronic leverages its deep regulatory affairs infrastructure to navigate expanded notified body requirements across multiple member states. Stryker anchors its competitive position through in-house manufacturing of powered mobility bases and hospital bed frames. Philips Healthcare differentiates via integrated remote patient monitoring ecosystems that pair hardware with cloud-based analytics platforms.
Durable medical equipment encompasses reusable devices designed for repeated application in patient care over extended periods, typically constructed from medical-grade polymers, aluminum alloys, and electronic control systems engineered for multi-year operational lifecycles. These products serve primarily to support therapeutic intervention, functional mobility, and physiological monitoring outside or alongside acute clinical settings. Wheelchairs and oxygen equipment command the largest revenue pools due to chronic condition prevalence and established reimbursement codes, while smart technology variants represent the fastest-expanding margin segment as sensor integration and connectivity commands premium positioning. Manual equipment retains volume dominance in emerging markets where cost constraints limit electric and hybrid penetration.
The FDA oversees premarket notification and quality system regulation for US-distributed devices, while the EU MDR and ISO 13485 harmonize design controls and post-market surveillance expectations across international supply chains. These frameworks elevate compliance costs for new entrants but protect incumbents with established quality management systems and clinical data libraries. Stakeholders must weigh capital allocation between smart technology R&D and geographic expansion into markets where reimbursement reform is pending.
Market Dynamics
Home-based care migration is compressing hospital procurement cycles while expanding direct-to-patient distribution channels for mobility and respiratory devices. This structural reconfiguration elevates reimbursement complexity as payers negotiate device lifecycle costs against institutional alternatives.
Growth Catalysts
- Japan's LTCI Expansion:The Long-Term Care Insurance program subsidizes powered wheelchairs and home oxygen systems, accelerating residential device penetration among elderly populations.
- Remote Patient Monitoring:Cloud-connected pulse oximeters and CPAP machines enable real-time clinical intervention, reducing emergency admissions and extending reimbursement eligibility.
- Aluminum Alloy Substitution:Lightweight frame materials reduce caregiver injury rates and transport costs, expanding addressable demand among bariatric and pediatric segments.
Market Restraints
- Semiconductor Supply Concentration:Taiwan and South Korea fabs control microcontroller supply for powered mobility bases, creating 16-24 week lead time volatility.
- EU MDR Clinical Evidence Burden:Stricter notified body requirements extend 510(k)-equivalent clearance timelines by 8-14 months for Class IIa respiratory devices.
- Refurbished Equipment Substitution:Certified pre-owned wheelchairs and concentrators capture price-sensitive demand in Medicaid-dependent segments, compressing new unit margins.
Strategic Opportunities
- Germany's Hospital Structural Reform:The Krankenhausreform mandates ambulatory care expansion, creating procurement windows for home-ventilation and mobility rental fleets.
- India's PLI Medical Devices Scheme:Production-linked incentives for domestic manufacturing of oxygen concentrators and nebulizers reduce import dependency for tier-2 and tier-3 hospital networks.
- AI-Enabled Predictive Maintenance:Sensor-embedded hospital beds and wheelchairs converge machine learning with hardware, enabling subscription-based service revenue models.
Industry Challenges
- Biomedical Technician Scarcity:Repair certification for respiratory and infusion equipment requires specialized training that community colleges and vocational programs underproduce.
- Legacy EMR Integration:Homecare device data streams lack standardized APIs, forcing custom middleware development for each hospital system deployment.
- Notified Body Bottlenecks:EU MDR designation delays strand products in regulatory queues, freezing R&D amortization schedules and capital recovery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Durable Medical Equipment Market |
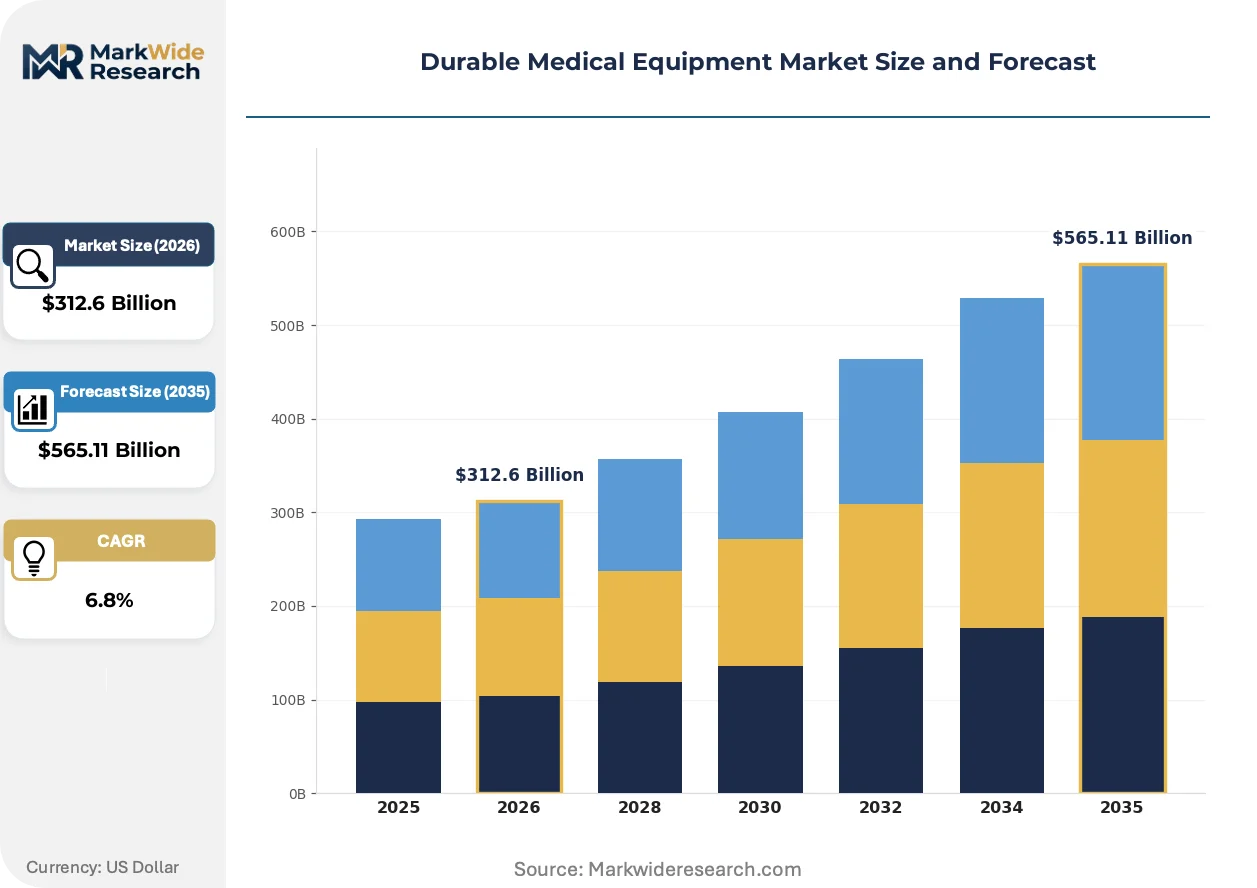
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheelchairs, Hospital Beds, Walkers, Oxygen Equipment End User: Homecare, Hospitals, Rehabilitation Centers, Nursing Facilities Technology: Manual, Electric, Smart, Hybrid Application: Mobility Assistance, Respiratory Support, Patient Monitoring, Rehabilitation |
| Companies Covered | Medtronic, Stryker, Invacare Corporation, GE HealthCare, Cardinal Health, Medline Industries, Baxter International, Philips Healthcare, Sunrise Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Durable Medical Equipment Market Emerging Trajectories
Sensor miniaturization and cellular connectivity are redefining device value propositions from hardware ownership to continuous clinical data delivery. This transformation elevates software architecture and cybersecurity compliance to parity with mechanical engineering.
Implantable-grade pressure sensors adapted for wheelchair seating surfaces are decentralizing pressure ulcer prevention from specialized wound clinics to residential settings. Skilled nursing facilities in the United States are deploying these systems at 40% annual volume expansion. The technology is decentralizing clinical monitoring labor while compressing specialist consultation frequency.
The EU MDR's Post-Market Clinical Follow-up requirements are extending surveillance obligations from 2-3 years to full device lifecycle coverage. Manufacturers must now fund registry studies and periodic safety update reports for oxygen concentrators and infusion pumps. Germany and France lead enforcement, with notified bodies rejecting technical files lacking prospective clinical data commitments.
Hospital purchasing cooperatives are consolidating procurement authority for durable medical equipment across multi-state health systems. Group Purchasing Organizations now negotiate frame-of-reference pricing for powered wheelchairs and hospital beds, displacing individual facility contracts. This concentration is most pronounced in the southeastern United States, where Catholic health networks and for-profit chains dominate acute care bed supply.
Durable Medical Equipment Market Segmentation
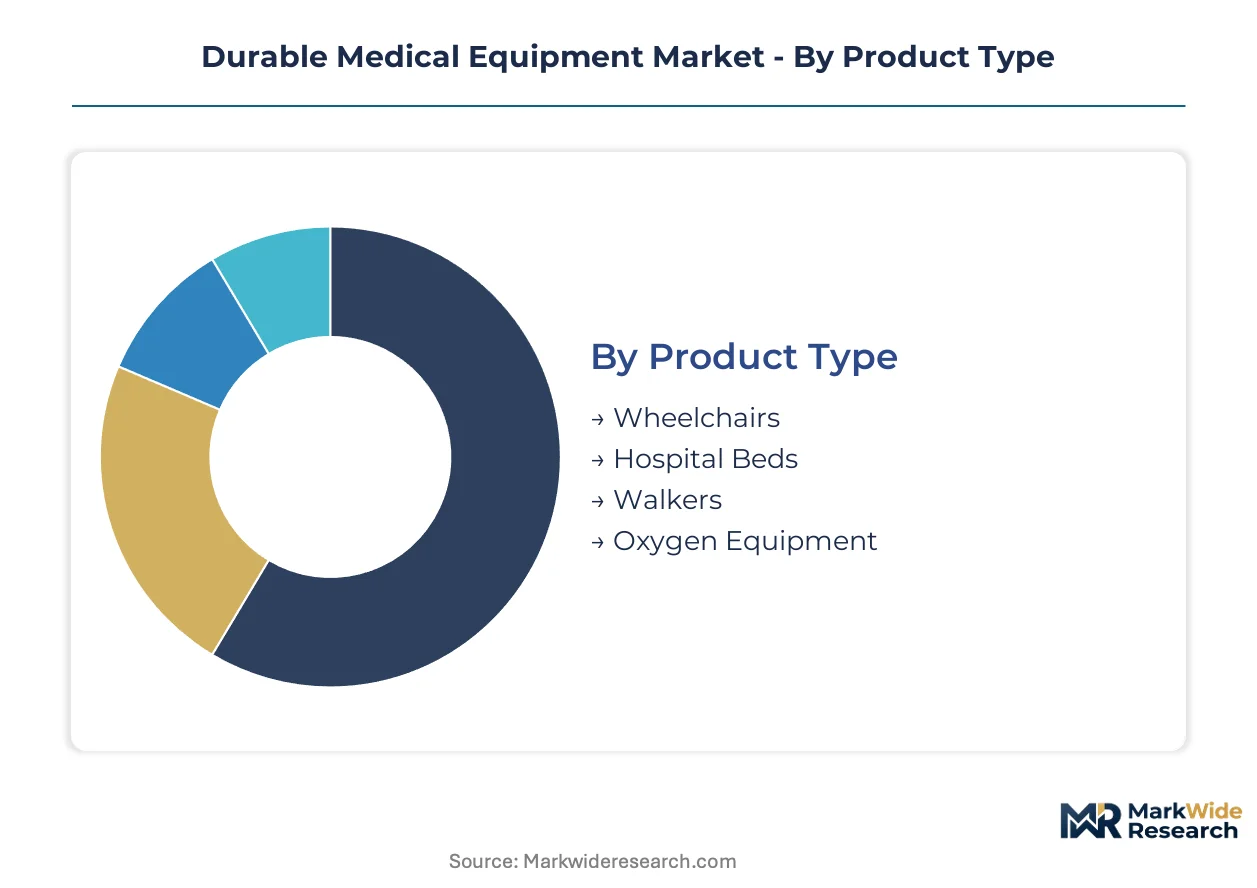
Durable medical equipment segmentation reveals divergent margin profiles across customization intensity. Standardized configurations dominate volume, while patient-specific adaptations command premium positioning in reimbursement-sensitive categories.
Product Type:
Customization intensity spans from commodity frame assemblies to patient-molded seating systems, with reimbursement codes increasingly favoring clinically justified specifications over catalog configurations.
- Wheelchairs:Constructed from aluminum alloys and medical-grade polymers with configurable seat widths, back angles, and drive controls. Demand concentrates in homecare channels across the United States and Germany, where LTCI and Medicare Advantage plans subsidize powered configurations for ambulatory-impaired elderly populations.
- Hospital Beds:Steel-reinforced frames with electric height adjustment and integrated siderail controls. Procurement clusters in southeastern US health systems, where Catholic networks and for-profit chains consolidate purchasing through Group Purchasing Organizations that negotiate frame-of-reference pricing.
- Walkers:Lightweight aluminum or steel frame mobility aids with adjustable height and folding mechanisms. Volume demand persists in Medicaid-dependent segments where cost constraints limit electric alternatives.
- Oxygen Equipment:Stationary concentrators and portable delivery systems with pulse-dose and continuous-flow modes. India's tier-2 and tier-3 hospital networks drive import substitution under the PLI Medical Devices Scheme.
Leading the category by volume: Walkers. Expanding most quickly: Wheelchairs with sensor-embedded seating surfaces.
End User:
Procurement authority decentralization is shifting volume toward direct-to-patient channels, compressing traditional hospital-centric distribution models.
- Homecare:Direct-to-patient delivery of mobility and respiratory devices with remote monitoring integration. Japan's LTCI expansion accelerates residential penetration for powered wheelchairs and home oxygen systems among elderly populations.
- Hospitals:Acute care procurement of powered beds and patient transfer equipment. Germany's Krankenhausreform mandates ambulatory care expansion, creating rental fleet demand for home-ventilation and mobility equipment.
- Rehabilitation Centers:Specialized equipment for post-acute functional recovery. Skilled nursing facilities in the United States deploy pressure-sensing wheelchair seating at accelerated volume expansion.
- Nursing Facilities:Long-term residential care equipment with durability specifications for multi-year operational lifecycles. Bariatric and pediatric segments drive aluminum alloy substitution for caregiver injury reduction.
Volume concentration: Homecare. Steepest expansion trajectory: Rehabilitation Centers with sensor-integrated monitoring protocols.
Technology:
Margin stratification follows electrification depth, with software-enabled connectivity commanding subscription revenue models beyond hardware ownership.
- Manual:Human-powered mechanical systems without electronic components. Emerging markets in India and Southeast Asia retain volume dominance where cost constraints limit electric penetration.
- Electric:Battery-powered actuation for height adjustment, recline, and mobility drive systems. Medicare Advantage and commercial payers in the United States favor electric wheelchairs for independent living eligibility.
- Smart:Sensor-embedded devices with cellular connectivity and cloud-based analytics platforms. Philips Healthcare and integrated ecosystem providers differentiate via real-time clinical intervention capabilities that reduce emergency admissions.
- Hybrid:Dual-mode systems combining manual override with electric assist. Germany and France lead EU MDR enforcement for Class IIa respiratory and mobility devices with prospective clinical data requirements.
Revenue share leader: Electric. Gaining share fastest: Smart technology with AI-enabled predictive maintenance subscriptions.
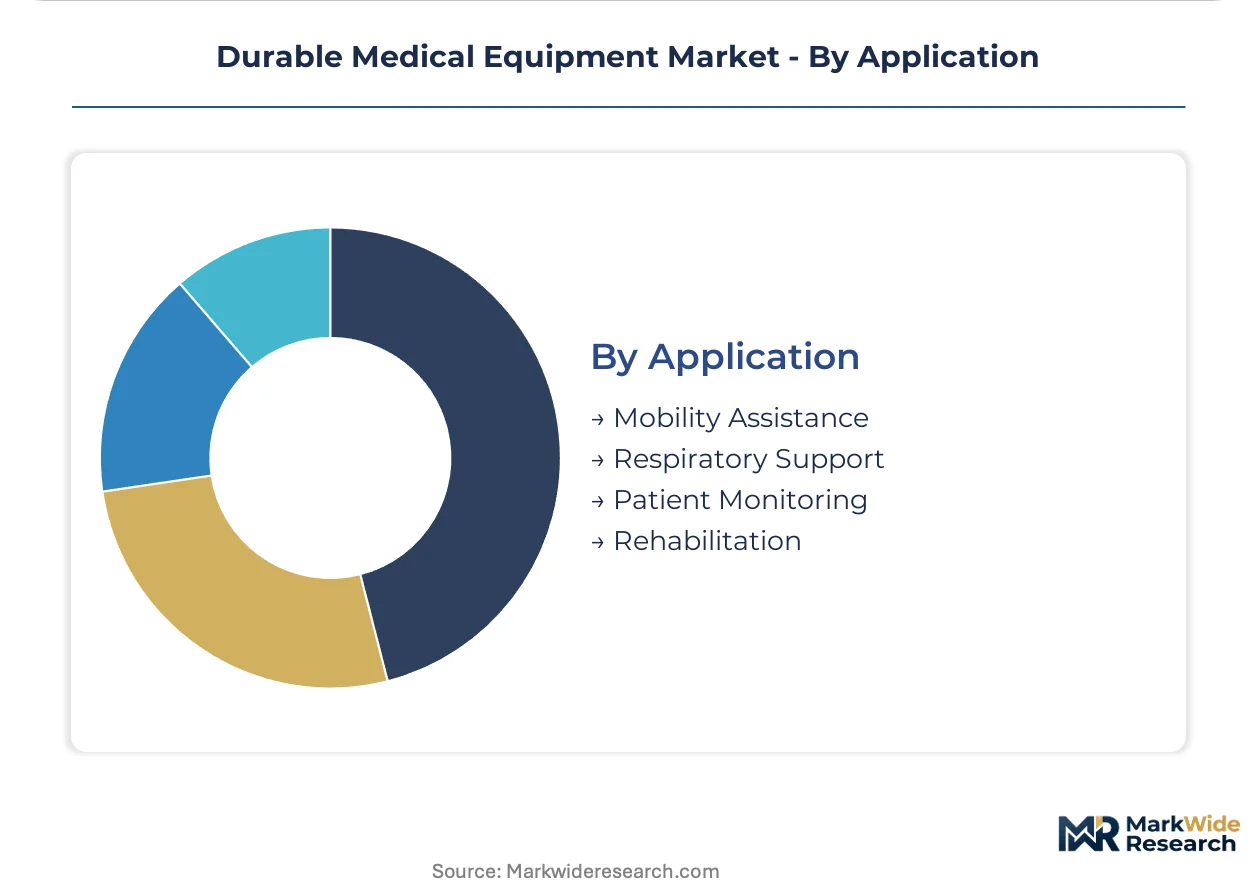
Application:
Clinical outcome measurement is reshaping procurement criteria toward demonstrable episode cost reduction and readmission prevention.
- Mobility Assistance:Functional movement support for ambulatory impairment. Powered bases and seating systems in the United States and Japan dominate reimbursement-eligible categories.
- Respiratory Support:Oxygen delivery and ventilation management for chronic pulmonary conditions. Cloud-connected CPAP machines and pulse oximeters extend reimbursement eligibility through remote patient monitoring integration.
- Patient Monitoring:Continuous physiological data collection outside acute settings. Pressure ulcer prevention via implantable-grade sensors decentralizes monitoring from specialized wound clinics to residential settings.
- Rehabilitation:Therapeutic intervention equipment for functional recovery. Post-market clinical follow-up requirements under EU MDR extend surveillance obligations to full device lifecycle coverage for infusion pumps and concentrators.
Procurement volume leader: Mobility Assistance. Climbing the fastest: Patient Monitoring with decentralized clinical labor substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American durable medical equipment manufacturing, with Medtronic and regional suppliers clustering around the Twin Cities medical technology corridor for regulatory proximity and specialized workforce access.
United States
Medicare Advantage expansion and hospital purchasing cooperative consolidation drive procurement volume for powered wheelchairs and hospital beds. FDA 510(k) clearance pathways govern premarket notification for respiratory and mobility devices. Southeastern health systems in Florida and Georgia deploy Group Purchasing Organization-negotiated frame-of-reference pricing for acute care bed fleets.
Germany
Krankenhausreform mandates shift acute episodes to ambulatory settings, expanding rental demand for home-ventilation equipment. EU MDR notified body requirements extend Class IIa device clearance timelines with prospective clinical data obligations. North Rhine-Westphalia medical technology clusters around Düsseldorf and Cologne concentrate notified body infrastructure and contract manufacturing capacity.
Japan
Long-Term Care Insurance subsidies accelerate residential penetration of powered wheelchairs and home oxygen systems among elderly populations. METI coordinates industrial policy for medical device domestic production targets. Kanto region manufacturers in Saitama and Tokyo prefectures supply LTCI-reimbursed mobility bases to homecare distributors.
India
Tier-2 and tier-3 hospital networks drive import substitution for oxygen concentrators and nebulizers under PLI Medical Devices Scheme incentives. CDSCO regulates device quality standards and import licensing for respiratory equipment. Gujarat pharmaceutical and medical device manufacturing zones in Ahmedabad and Vadodara expand domestic concentrator assembly capacity.
United Kingdom
NHS Integrated Care Systems consolidate procurement authority for community-based mobility and respiratory equipment. MHRA post-Brexit regulatory framework maintains alignment with EU MDR clinical evidence standards. Midlands manufacturing corridors around Birmingham and Coventry host hospital bed frame fabrication and refurbishment operations.
Durable Medical Equipment Market Vendor Landscape
The competitive structure tilts toward diversified health technology conglomerates with regulatory affairs infrastructure and integrated manufacturing capabilities. Incumbents with established quality management systems and clinical data libraries command clearance timeline advantages under stricter EU MDR and FDA frameworks. Two strategic archetypes dominate: vertically integrated manufacturers controlling frame and electronics production, and ecosystem providers bundling hardware with cloud-based analytics platforms. Competitive moves concentrate on M&A for regulatory data libraries and capacity expansion into India PLI-eligible production zones.
Among diversified medical technology conglomerates, Medtronic, Stryker, and Philips Healthcare occupy positions exemplifying regulatory scale and integrated portfolio breadth. Medtronic represents the archetype of deep notified body relationships across multiple EU member states. Stryker anchors the in-house manufacturing archetype for powered mobility bases and acute care frames. Philips Healthcare exemplifies the ecosystem provider model converging sensor-embedded hardware with remote patient monitoring subscriptions.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Invacare Corporation |
| GE HealthCare |
| Cardinal Health |
| Medline Industries |
| Baxter International |
| Philips Healthcare |
| Sunrise Medical |
| Others |
Supply Flow & Price Mechanics
Sensor-embedded smart device architectures are simultaneously elevating R&D amortization burdens and concentrating component sourcing among semiconductor-qualified contract manufacturers. This dual transformation compresses margins on manual equipment while expanding pricing power for connectivity-integrated systems that command subscription revenue models.
Pricing Analysis
Value-based pricing anchored to readmission reduction metrics and episode cost outcomes governs smart wheelchair and remote monitoring categories. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared Class IIa respiratory devices from 510(k)-exempt manual mobility aids and refurbished concentrator alternatives. Pricing pressure stems from Medicaid reimbursement compression in US homecare channels and India's PLI scheme driving domestic cost parity. Price sensitivity concentrates among Medicaid-dependent patient segments and tier-3 hospital networks, while Medicare Advantage and commercial payers absorb connectivity premiums.
Supply Chain Analysis
India's PLI Medical Devices Scheme and domestic-content mandates for oxygen concentrator assembly are reshaping sourcing patterns away from concentrated East Asian component hubs. Microcontroller supply draws from Taiwan and South Korea fabs, aluminum alloy extrusions from Chinese and German mills, and medical-grade polymers from US and European compounders. Single-source vulnerability in semiconductor foundry capacity creates procurement queue risk for powered mobility base manufacturers. Distribution runs through Group Purchasing Organizations in southeastern US health systems and direct-to-patient channels in Japan's LTCI-reimbursed homecare networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The durable medical equipment sector is transitioning from hardware ownership models to continuous clinical data delivery platforms, with sensor-embedded connectivity architectures displacing legacy mechanical-only configurations across reimbursement-eligible categories.
For Market Incumbents: Deploy regulatory data library leverage to extend clearance timeline advantages under EU MDR's expanded clinical evidence requirements. Incumbents should deepen backward integration into aluminum alloy frame production and sensor module assembly to defend margin position against refurbished equipment substitution in price-sensitive segments. Channel control through GPO contracting and direct-to-patient logistics infrastructure represents the priority defensive perimeter. For New Entrants and Emerging Players: Skilled nursing facilities deploying pressure-sensing wheelchair seating at accelerated volume expansion represent the most penetrable buyer archetype for sensor-integrated monitoring protocols. New entrants should target India's tier-2 hospital networks under PLI scheme incentives for oxygen concentrator domestic assembly, and pursue white-space positioning in AI-enabled predictive maintenance subscriptions for hospital bed fleets. Go-to-market execution through regional homecare distributors with LTCI billing expertise unlocks Japan's residential penetration channels. For Investors and Strategic Acquirers: Exit pathways concentrate in diversified health technology conglomerates seeking regulatory scale and integrated manufacturing capabilities. Long-term viability favors targets with established notified body relationships across multiple EU member states and cloud-based analytics platform architecture. The signal to watch is EU MDR designation delays resolving at notified bodies, which would unlock stranded product queues and accelerate R&D amortization recovery.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Investment | Prospective registry studies satisfy notified body requirements for Class IIa respiratory clearance. |
| Sensor-Integrated Product Development | Implantable-grade pressure sensors enable decentralized pressure ulcer prevention in skilled nursing facilities. |
| India PLI Manufacturing Footprint | Domestic oxygen concentrator assembly reduces import dependency for tier-2 and tier-3 hospital networks. |
| Cloud Platform Integration | Cellular-connected CPAP machines extend reimbursement eligibility through remote patient monitoring integration. |
| GPO Contracting Consolidation | Multi-state health system purchasing cooperatives displace individual facility contracts in southeastern US markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this durable medical equipment market assessment. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and homecare distributor operations heads combined with FDA 510(k) databases, EU MDR notified body technical file registries, CMS Medicare reimbursement schedules, and Japan LTCI utilization statistics. Bottom-up unit volume modeling across wheelchair, hospital bed, walker, and oxygen equipment categories triangulated against top-down expenditure flows from national health accounts.
Segment-level granularity modeled technology tiers across manual, electric, smart, and hybrid configurations; end-user channels spanning homecare, hospitals, rehabilitation centers, and nursing facilities; and application categories including mobility assistance, respiratory support, patient monitoring, and rehabilitation. CAGRs were derived from fitted growth curves against demographic aging trajectories and reimbursement policy shifts across the analysis window. Forecast inputs incorporated aluminum alloy price indices, semiconductor lead time volatility, and notified body capacity constraints.
Revisions become necessary when EU MDR designation delays extend beyond current queues, when semiconductor fab capacity expansions resolve microcontroller shortages, or when India's PLI scheme eligibility criteria shift. Forecasts reflect assumptions regarding LTCI subsidy continuity, Medicare Advantage penetration rates, and GPO contracting concentration trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Gas Cylinders Market
Medical Equipment
Global Surgical Lights Market
Medical Equipment
X-Ray Machine Manufacturing Market
Medical Equipment
Global Medical Equipment Calibration Market
Medical Equipment
Global Cardiopulmonary Stress Testing Systems Market
Medical Equipment
Southern Europe and Middle East Medical Robotics Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
Global Kidney Dialysis Equipment and Supplies Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market
Medical Equipment
Europe Medical Automation Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Water Bath Market
Medical Equipment
Medical Pediatric Bed Market
Medical Equipment
Medical Equipment Calibration Services Market
Medical Equipment
Animal Operating Table Market
Medical Equipment
US Medical Carts Market