
 Southern Europe and Middle East Medical Robotics Market | 2026-2036
Southern Europe and Middle East Medical Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Southern Europe and Middle East Medical Robotics Market Analytics
Aftermarket service revenue is reconfiguring margin capture across the Southern Europe and Middle East Medical Robotics landscape. Intuitive Surgical leverages its installed base of da Vinci systems to sustain recurring service contracts across Italian and Saudi hospital networks. Medtronic anchors its competitive position through specialized training ecosystems that lock in clinician loyalty.
Medical robotics encompasses electromechanical systems with sub-millimeter positional accuracy, multi-arm articulation, and real-time haptic feedback loops designed to augment or automate surgical, rehabilitative, and pharmaceutical dispensing procedures. Surgical robots occupy the dominant value share given capital intensity and procedure volume concentration in tertiary hospitals across the region. Rehabilitation robots represent the fastest-expanding product category as aging demographics in Portugal and Greece amplify demand for neurorehabilitation and exoskeleton-assisted mobility programs.
EMA's Medical Device Regulation and the UAE's Ministry of Health and Prevention device registration pathways shape product entry timelines and clinical evidence requirements for manufacturers targeting European and Gulf markets. Saudi Food and Drug Authority oversight of robotic surgery platforms adds a compliance layer that filters non-specialized vendors from premium hospital tenders. Stakeholders must monitor reimbursement harmonization between Southern European social health systems and Middle Eastern private insurance frameworks to anticipate purchasing cycle shifts.
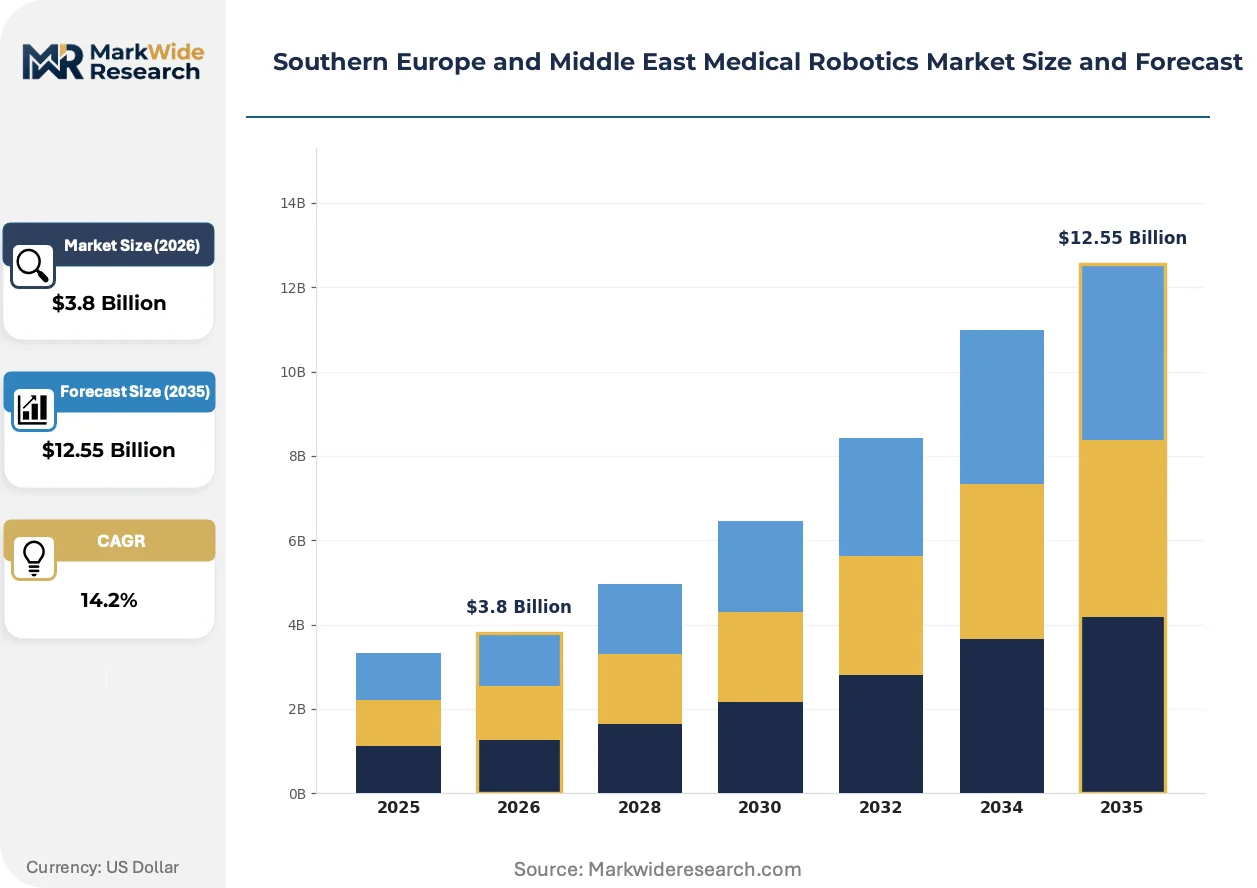
Market Dynamics
EU MDR conformity requirements are compressing product entry timelines while Gulf health ministries accelerate robotic surgery procurement, creating a bifurcated compliance landscape across the Southern Europe and Middle East Medical Robotics Market.
Growth Catalysts
- EMA Medical Device Regulation:Stricter clinical evidence requirements are filtering non-specialized vendors from premium hospital tenders, concentrating procurement among validated platforms.
- Neurorehabilitation demand:Aging demographics in Portugal and Greece are amplifying exoskeleton-assisted mobility program adoption across public rehabilitation centers.
- UAE health infrastructure investment:The Emirates' advanced surgical infrastructure buildout is concentrating demand for capital-intensive robotic platforms in tertiary facilities.
Market Restraints
- Capital intensity:Multi-million euro system acquisition costs restrict robotic surgery program expansion to well-capitalized tertiary hospitals in Italy and Saudi Arabia.
- Specialized component supply:Precision servo motors and haptic feedback sensors concentrate sourcing from East Asian contract manufacturers, exposing lead time volatility.
- SFDA registration pathways:Saudi Food and Drug Authority oversight adds procedural layers that extend product authorization timelines beyond European benchmarks.
Strategic Opportunities
- Greece rehabilitation underpenetration:Public health system modernization funding is opening procurement windows for neurorehabilitation robot vendors previously excluded from Southern European tenders.
- Telepresence surgery convergence:Integration of 5G low-latency networks with robotic platforms is enabling remote procedure assistance across dispersed Gulf hospital networks.
- MOHAP fast-track registration:UAE Ministry of Health and Prevention accelerated pathways reward manufacturers with prior EU MDR certification, compressing market entry cycles.
Industry Challenges
- Robotic surgery specialist scarcity:Certified console operator training programs in Spain and Italy lag installed base expansion, creating utilization bottlenecks.
- Legacy HIS integration:Hospital information system interoperability gaps in Portuguese and Greek facilities complicate robotic platform data exchange implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southern Europe and Middle East Medical Robotics Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Robots, Rehabilitation Robots, Pharmacy Automation, Telepresence Robots End User: Hospitals, Clinics, Research Institutions, Ambulatory Surgical Centers Technology: AI Integration, Motion Control, Haptic Feedback, Imaging Systems Application: Orthopedics, Neurology, Urology, General Surgery |
| Companies Covered | Intuitive Surgical, Stryker Corporation, Medtronic, Accuray Incorporated, Asensus Surgical, KUKA AG, CMR Surgical, Ekso Bionics, Avateramedical GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southern Europe and Middle East Medical Robotics Market Evolving Landscape
Autonomous suturing algorithms and single-port platform miniaturization are compressing the gap between laparoscopic and open surgery recovery metrics across Mediterranean and Gulf hospital systems.
Single-incision robotic platforms with integrated fluorescence imaging are rendering obsolete multi-port laparoscopic towers in Italian and Spanish gynecology departments. Tertiary hospitals in Milan and Barcelona are consolidating procurement around these systems to reduce postoperative complication rates. The shift is compressing capital equipment refresh cycles from seven-year to four-year intervals.
EU MDR post-market surveillance requirements are mandating real-world performance data submission for class III surgical robots. Manufacturers must now maintain clinical follow-up registries across Italian and Spanish implantation sites. Rehabilitation robot vendors face lighter documentation burdens, creating divergent compliance cost structures across product categories.
After-sales service unbundling is disrupting traditional capital-plus-maintenance bundled contracts in UAE private hospital chains. Procurement teams in Dubai and Abu Dhabi are negotiating discrete training, spare parts, and software upgrade agreements. The fragmentation is pressuring vendor pricing transparency and compressing service margin capture rates.
Southern Europe and Middle East Medical Robotics Market Segmentation
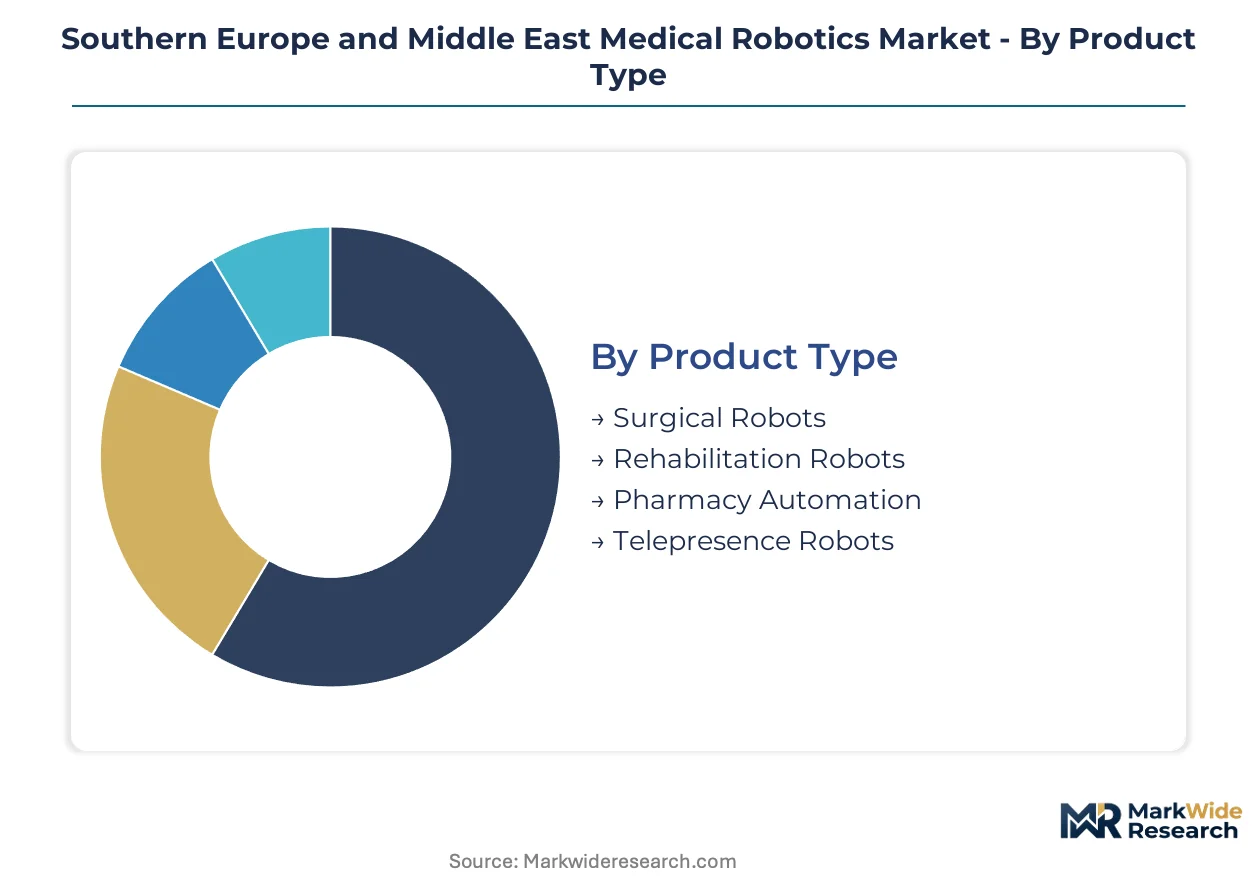
Segmentation reveals divergent capital cycles across the Southern Europe and Middle East Medical Robotics Market. Surgical platforms command seven-year depreciation schedules while rehabilitation systems turn over in four-year windows, reshaping vendor cash flow patterns.
Product Type:
Cycle times vary dramatically across product categories, with surgical systems locking capital for extended periods while rehabilitation and pharmacy automation refresh at compressed intervals.
- Surgical Robots:Electromechanical platforms with sub-millimeter positional accuracy and multi-arm articulation designed for minimally invasive procedures. Tertiary hospitals in Milan and Riyadh concentrate procurement as these institutions absorb multi-million euro acquisition costs and specialized infrastructure requirements.
- Rehabilitation Robots:Exoskeleton and neurorehabilitation systems with adaptive motor learning algorithms and real-time biomechanical feedback. Public rehabilitation centers in Portugal and Greece are expanding procurement as aging demographics amplify demand for mobility restoration programs.
- Pharmacy Automation:Robotic dispensing and inventory management systems with barcode verification and controlled substance tracking. Hospital pharmacies in Dubai and Abu Dhabi are prioritizing these systems to reduce medication error liability.
- Telepresence Robots:Remote consultation and surgical assistance platforms with 5G-integrated low-latency streaming. Gulf hospital networks are deploying these systems to extend specialist coverage across dispersed geographic footprints.
Surgical robots anchor the volume base while rehabilitation robots gain share at the steepest rate.
End User:
Customer type determines procurement sophistication, with tertiary hospitals demanding integrated service ecosystems while smaller facilities prioritize standalone system accessibility.
- Hospitals:Tertiary and secondary acute care facilities with dedicated robotic surgery suites and specialized nursing staff. Italian and Spanish hospital networks are consolidating purchasing through regional procurement consortia to extract volume discounts.
- Ambulatory Surgical Centers:Same-day procedure facilities with streamlined workflows and lower capital absorption capacity. ASCs in Greece and the UAE are selectively adopting compact robotic platforms for high-volume outpatient procedures.
- Clinics:Outpatient diagnostic and minor procedure facilities with limited surgical infrastructure. Rehabilitation-focused clinics in Portugal represent emerging demand for lower-cost exoskeleton leasing arrangements.
- Research Institutions:Academic medical centers and university hospitals with clinical trial mandates and training program obligations. Saudi research hospitals are prioritizing platforms with open API architectures for protocol customization.
Hospitals anchor the volume base while ambulatory surgical centers gain share at the steepest rate.
Technology:
Technology stack differentiation separates premium platform pricing from commoditized hardware configurations, with AI and haptic systems commanding substantial service premiums.
- AI Integration:Machine learning algorithms for surgical planning, tissue recognition, and autonomous suturing pathway optimization. Spanish and Italian hospitals are prioritizing AI-enabled platforms to reduce procedure variability and training time.
- Haptic Feedback:Force-sensing and tactile response systems that translate tissue resistance to surgeon console controls. Tertiary facilities in the UAE are demanding haptic-enabled systems for complex microsurgical applications.
- Motion Control:Precision servo motor arrays with collision detection and tremor filtration capabilities. This foundational technology underlies all articulated robotic platforms across the region.
- Imaging Systems:Integrated fluorescence, 3D visualization, and intraoperative navigation overlays. Italian gynecology departments are consolidating procurement around imaging-integrated single-port platforms.
Motion control anchors the volume base while AI integration gains share at the steepest rate.
Application:
Procedure type concentration determines installed base utilization rates, with high-volume specialties justifying capital investment through throughput economics.
- General Surgery:Cholecystectomy, hernia repair, and colorectal procedures with established robotic protocols and reimbursement pathways. Spanish hospital networks are expanding general surgery robotic programs to reduce length-of-stay metrics.
- Urology:Prostatectomy and nephrectomy procedures with demonstrated oncologic equivalence to open techniques. Saudi tertiary hospitals are prioritizing urology robotics to address rising prostate cancer incidence.
- Orthopedics:Joint replacement and spine procedures with robotic-assisted implant positioning. Greek public hospitals are selectively adopting orthopedic robotics through EU modernization funding windows.
- Neurology:Deep brain stimulation and tumor resection with sub-millimeter targeting requirements. Italian academic centers are concentrating neurology robotics in specialized neurosurgical institutes.
General surgery anchors the volume base while neurology gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision component sourcing clusters in East Asian manufacturing hubs, while tertiary hospital networks across Southern Europe and the Gulf states absorb the bulk of system deployment. EMA's Medical Device Regulation and national health procurement frameworks create divergent compliance timelines that vendors must navigate simultaneously.
Italy
Italian hospital networks in Milan and Rome are consolidating robotic surgery procurement through regional consortia to extract volume discounts from capital-intensive platform vendors. The National Agency for Regional Healthcare Services enforces post-market surveillance protocols that align with EU MDR requirements. The Lombardy cluster anchors the country's highest da Vinci system density, with San Raffaele Hospital expanding its single-port platform fleet.
Spain
Spanish tertiary centers in Barcelona and Madrid are prioritizing AI-integrated surgical platforms to reduce procedure variability and training time for resident surgeons. The Spanish Agency for Medicines and Health Products coordinates device registration with EMA timelines while maintaining national reimbursement formularies. Hospital Clínic de Barcelona is consolidating its gynecology robotics program around fluorescence-imaging single-port systems.
United Arab Emirates
UAE health infrastructure investment is concentrating demand for capital-intensive robotic platforms in Dubai and Abu Dhabi tertiary facilities. The Ministry of Health and Prevention operates fast-track registration pathways that reward manufacturers with prior EU MDR certification. Cleveland Clinic Abu Dhabi and Dubai's Mediclinic City Hospital are deploying telepresence-integrated systems to extend specialist coverage across dispersed emirate networks.
Saudi Arabia
Saudi tertiary hospitals in Riyadh and Jeddah are expanding urology robotics programs to address rising prostate cancer incidence among aging demographics. The Saudi Food and Drug Authority imposes procedural oversight layers that extend product authorization timelines beyond European benchmarks. King Faisal Specialist Hospital anchors the kingdom's deepest robotic surgery specialist training pipeline.
Greece
Greek public rehabilitation centers in Athens and Thessaloniki are expanding exoskeleton-assisted mobility program procurement through EU modernization funding windows. The National Organization for Medicines regulates device entry while social health system reimbursement harmonization remains incomplete. Attica region hospitals are selectively adopting orthopedic robotics for joint replacement procedures.
Southern Europe and Middle East Medical Robotics Market Competitive Landscape
Integrated platform vendors and specialized component suppliers split the market into distinct competitive spheres. Surgical system manufacturers anchor the premium tier through installed base lock-in and recurring service contract structures. Rehabilitation robotics specialists occupy a fragmented mid-tier characterized by shorter capital cycles and leasing-oriented commercial models. Dominant competitive moves include strategic training ecosystem development and aftermarket service unbundling.
Among US-based integrated platform vendors, Intuitive Surgical and Stryker Corporation exemplify the capital-intensive surgical robotics archetype through extensive installed base cultivation. Medtronic occupies a position spanning surgical and rehabilitation modalities. European specialists including KUKA AG and Avateramedical GmbH represent the precision engineering tier, while CMR Surgical anchors the emerging single-port platform segment. Asensus Surgical and Accuray Incorporated sit within the technology-differentiated tier, with Ekso Bionics exemplifying the rehabilitation-focused archetype.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Stryker Corporation |
| Medtronic |
| Accuray Incorporated |
| Asensus Surgical |
| KUKA AG |
| CMR Surgical |
| Ekso Bionics |
| Avateramedical GmbH |
| Others |
Value Network & Pricing Analysis
Suez Canal freight corridors shape landed cost differentials for precision servo motors and haptic feedback sensors, concentrating supply leverage among East Asian contract manufacturers while forcing tiered pricing stratification across Italian hospital networks and UAE private chains.
Pricing Analysis
After-sales service contracts—including spare parts, software upgrades, and extended technical support—generate lifetime value multiples exceeding initial system acquisition. Three-tier pricing structure across premium, standard, and economy levels separates integrated platform vendors from specialized component suppliers and refurbished system brokers. Price differentiation hinges on EU MDR certification tier and geographic delivery infrastructure. Cost compression in the mid-tier intensifies because Gulf procurement teams unbundle traditional capital-plus-maintenance agreements. Ambulatory surgical centers in Greece exhibit highest price sensitivity; tertiary hospitals in Riyadh and Milan demonstrate lowest sensitivity due to amortization across high procedure volumes.
Supply Chain Analysis
East Asian contract manufacturers in Taiwan, South Korea, and Japan hold dominant capacity for precision servo motors, force-sensing arrays, and optical encoders. Component sourcing draws from specialized foundries for haptic feedback sensors, rare-earth magnet suppliers for actuator assemblies, and German optics houses for fluorescence imaging modules. Single-source vulnerability concentrates in sub-millimeter positional encoder supply. Distribution runs through regional medical device distributors with EMA-authorized quality management systems, feeding hospital procurement consortia in Southern Europe and direct-to-facility logistics for Gulf tertiary networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers—training ecosystems, software subscriptions, and predictive maintenance contracts—are expanding faster than hardware shipments across the Southern Europe and Middle East Medical Robotics landscape.
For Market Incumbents: Harden installed base lock-in through captive training certification programs that create switching costs for hospital robotics committees. Deepen backward integration into precision motion control component supply to reduce lead time volatility from East Asian contract manufacturers. Anchor defensive positioning against emerging single-port platform entrants by accelerating fluorescence imaging integration roadmaps. For New Entrants and Emerging Players: Pursue Greece's public rehabilitation center modernization funding windows, where exoskeleton-assisted mobility programs remain underpenetrated relative to Portuguese and Spanish adoption curves. Target telepresence-integrated platforms for UAE hospital network dispersion challenges. Lead with leasing-oriented commercial models that bypass capital intensity barriers blocking direct sales to Greek and Portuguese public health systems. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial automation parents with dormant medical robotics divisions possessing ISO 13485 certification infrastructure. Long-term viability centers on platforms with open API architectures enabling protocol customization for Saudi research hospital trials. Monitor EU MDR post-market surveillance registry completion rates as inflection indicator for vendor filtering intensity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity accelerates UAE MOHAP fast-track registration for Gulf market entry. |
| Hospital System Partnership | Regional procurement consortia in Lombardy and Catalonia extract volume discounts from platform vendors. |
| Software Companion Development | AI-integrated surgical planning modules reduce training time for Spanish resident surgeons. |
| Reimbursement Strategy | Harmonization between Southern European social health systems and Gulf private insurance frameworks shapes purchasing cycles. |
| Specialist Training Pipeline | King Faisal Specialist Hospital anchors Saudi Arabia's deepest certified console operator program. |
Research Methodology
Desk research of EMA Medical Device Regulation guidance documents, SFDA registration pathway manuals, and hospital procurement databases preceded structured interviews with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads at platform manufacturers. Secondary validation drew from EU MDR post-market surveillance registries, UAE Ministry of Health and Prevention device listings, and trade flow records for precision motion control components. Bottom-up installed base modeling and top-down health infrastructure spending analysis were triangulated against procedure volume estimates.
Assumptions held fixed include EU MDR regulatory enforcement intensity, Gulf health ministry procurement acceleration timelines, and East Asian contract manufacturing capacity allocation. Segmentation dimensions modeled encompass product type, end user facility tier, technology stack, and application specialty across the projection horizon. CAGRs were derived from procedure volume growth curves weighted by system utilization rates and capital replacement cycle compression. Forecast inputs incorporated aging demographic trajectories in Portugal and Greece, plus 5G network deployment schedules enabling telepresence surgery convergence.
Sensitivities concentrate around EU MDR post-market surveillance cost escalation, SFDA registration timeline extensions, and East Asian logistics chokepoint disruptions. Forecasts reflect assumptions about reimbursement harmonization progress and specialist training pipeline expansion. Quarterly review of EMA guidance updates, Gulf hospital tender announcements, and precision component lead time indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Urodynamics Equipment and Disposables Market
Medical Equipment
Global Blood Viscometer Market
Medical Equipment
Global Medical Power Supply Market
Medical Equipment
Medical Oxygen Systems Market
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
Global Medical Vacuum System Market
Medical Equipment
Medical Oxygen Gas Cylinder Market
Medical Equipment
Medical Filter Market
Medical Equipment
Global Countertop Platelet Incubator Market
Medical Equipment
Electron Beam Linear Accelerators Market
Medical Equipment
Diathermy Equipment Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Floor-Standing Platelet Agitator Market
Medical Equipment
Dial Thermometers Market
Medical Equipment
Global Medical Lasers Market
Medical Equipment
Global Plasma Sterilizers Market