
 Global Medical Ventilator Market | 2026-2036
Global Medical Ventilator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Ventilator Market Foresight
Hospital procurement consolidation across North America is rebalancing vendor negotiation leverage toward multi-year service contracts. Koninklijke Philips N.V. leverages its installed base of monitoring-ventilator integration to sustain recurring revenue streams. Hamilton Medical anchors European demand through its intensive care specialization and closed-loop ventilation algorithms. Medtronic plc competes on geographic breadth, with manufacturing and regulatory footprints spanning the FDA, EMA, and Japan's PMDA jurisdictions.
A medical ventilator is an electromechanical device that delivers breathable air into and out of a patient's lungs through positive pressure, typically operating at tidal volumes of 200-2000 mL and respiratory rates of 1-150 breaths per minute depending on clinical indication. Its primary purpose is to provide full or partial respiratory support for patients with compromised spontaneous breathing due to trauma, infection, neurological injury, or surgical intervention. Invasive ventilators occupy the highest margin pool due to ICU dependency and regulatory complexity, while portable ventilators represent the fastest-expanding category as home care settings and long-term care facilities build post-acute capacity. Dual-mode technology leads R&D investment because clinicians demand seamless transitions between pressure-controlled and volume-controlled protocols without circuit changes.
The FDA's 510(k) premarket notification framework and the EU Medical Device Regulation (MDR) govern ventilator safety, software validation, and post-market surveillance, with MDR's stricter clinical evidence requirements extending certification timelines for new entrants. China's NMPA enforces GB standards for respiratory device electromagnetic compatibility and biocompatibility, creating separate testing burdens for manufacturers without in-country regulatory partnerships. Japan's METI and PMDA coordinate industrial policy with healthcare technology assessment, influencing reimbursement rates that shape vendor profitability. Stakeholders must monitor how FDA draft guidance on artificial intelligence-enabled ventilation adjustments interacts with existing quality system regulations to determine whether adaptive algorithms trigger new premarket submission categories.
Market Dynamics
Hospital procurement consortiums in North America are consolidating purchasing power for ICU-grade ventilator systems, forcing vendors to restructure pricing around multi-year service contracts rather than equipment margins alone.
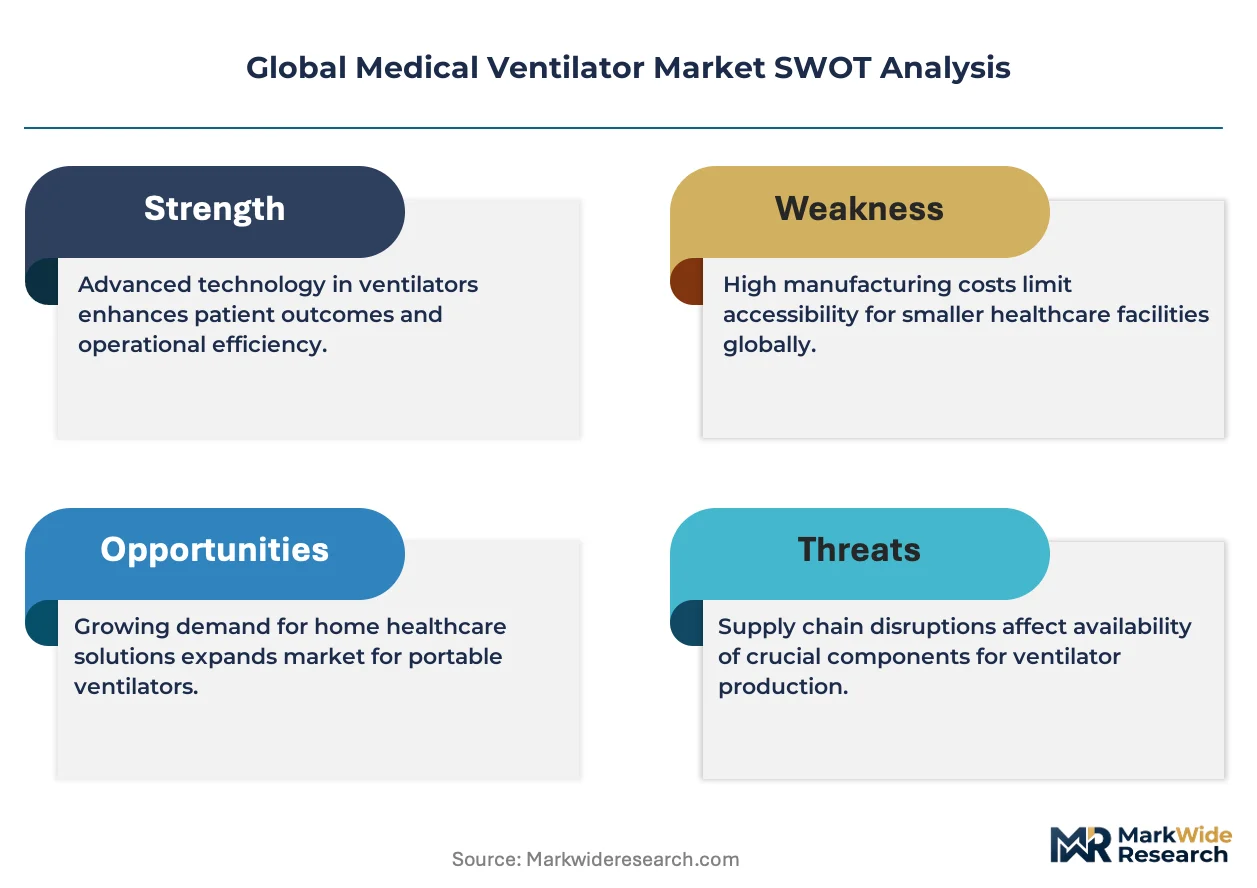
Growth Catalysts
- FDA 510(k) Software Pathway:The FDA's streamlined premarket notification for software-as-medical-device ventilator controls accelerates product iteration cycles and reduces time-to-market for algorithmic ventilation management systems.
- Home Care Infrastructure:Post-acute care facilities across the United States are building dedicated respiratory therapy wings, generating pull-through demand for portable ventilator platforms with extended battery autonomy.
- Dual-Mode Protocol Standardization:German university hospital networks are mandating seamless pressure-to-volume control transitions without circuit changes, creating specification pull for advanced ventilator architectures.
Market Restraints
- EU MDR Certification Burden:The European Medical Device Regulation's stricter clinical evidence requirements extend certification timelines for new ventilator entrants, concentrating market access among established manufacturers with legacy dossiers.
- Semiconductor Supply Concentration:Critical microcontroller and sensor component production concentrates in East Asian foundries, exposing ventilator OEMs to geopolitical supply disruption risks and extended lead times.
- Biocompatibility Testing Costs:China's NMPA enforces separate GB standards for respiratory device electromagnetic compatibility and biocompatibility, duplicating validation expenditures for manufacturers lacking in-country regulatory partnerships.
Strategic Opportunities
- AI-Enabled Ventilation Adjustment:Adaptive algorithms for real-time respiratory parameter optimization represent white space, with FDA draft guidance on artificial intelligence-enabled controls creating a regulatory pathway for differentiated positioning.
- Long-Term Care Channel Expansion:Skilled nursing facilities in the United States are unbundling ventilator service contracts from acute-care vendors, opening distribution entry points for specialized respiratory equipment suppliers.
- Japan METI Industrial Coordination:Japan's Ministry of Economy, Trade and Industry coordinates healthcare technology assessment with PMDA reimbursement rate-setting, creating policy tailwinds for ventilator vendors who align R&D with national respiratory disease management priorities.
Industry Challenges
- Closed-Loop Algorithm Validation:Developing clinical evidence packages for autonomous ventilation adjustment algorithms requires specialized biomedical engineering talent scarce outside academic medical center research divisions.
- Legacy System Interoperability:ICU information system integration demands HL7 FHIR compliance and proprietary hospital network authentication protocols, complicating ventilator deployment in mixed-vendor monitoring environments.
- Software Quality System Overlap:Manufacturers must reconcile FDA quality system regulations for hardware with emerging premarket submission categories for AI-enabled control software, creating compliance documentation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Ventilator Market |
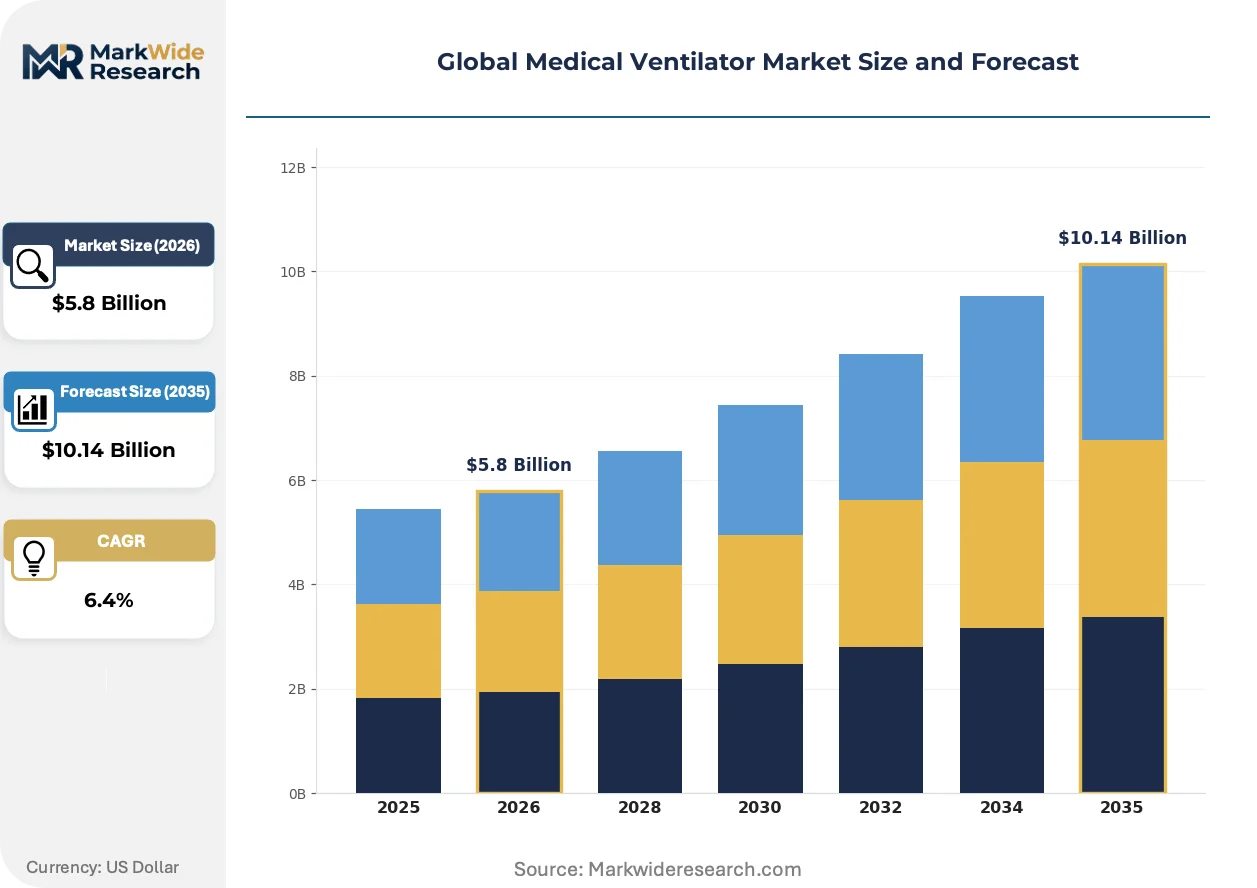
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive Ventilators, Non-invasive Ventilators, Portable Ventilators, ICU Ventilators Technology: Pressure Controlled, Volume Controlled, Dual Mode, High Frequency Oscillatory Application: Respiratory Failure, Chronic Obstructive Pulmonary Disease, Acute Respiratory Distress Syndrome, Sleep Apnea End User: Hospitals, Ambulatory Surgery Centers, Home Care Settings, Long-Term Care Facilities |
| Companies Covered | Koninklijke Philips N.V., Hamilton Medical, Getinge AB, Medtronic plc, ResMed, GE Healthcare, Drägerwerk AG & Co. KGaA, Vyaire Medical, Inc., Fisher & Paykel Healthcare Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Ventilator Market Shifts & Advancements
Software-defined ventilation control architectures are displacing fixed-function hardware platforms, enabling remote algorithm updates and predictive maintenance models that reshape vendor-customer relationships across acute and post-acute care settings.
Closed-loop ventilation algorithms with real-time respiratory mechanics feedback are overtaking conventional open-loop pressure and volume control modes in German and Austrian university hospital ICUs. These systems reduce clinician intervention frequency for ARDS protocol management. The technology is compressing differentiation timelines among ventilator OEMs and forcing accelerated R&D cycles to maintain clinical specification relevance.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic clinical follow-up data collection for ventilator software updates. Manufacturers must now maintain active implantable device-style vigilance systems for non-implantable respiratory equipment. High-acuity invasive ventilator categories face the steepest compliance cost escalation, advantaging incumbent players with established quality management infrastructure.
Multi-year total cost of ownership contracts are displacing capital equipment purchase models in North American hospital procurement consortiums. These agreements unbundle hardware acquisition from preventive maintenance, remote monitoring, and consumables replenishment into subscription structures. The shift is most visible in United States-based IDN purchasing coalitions, where CFO-driven standardization favors vendors with integrated service platform capabilities over point-product specialists.
Global Medical Ventilator Market Segmentation
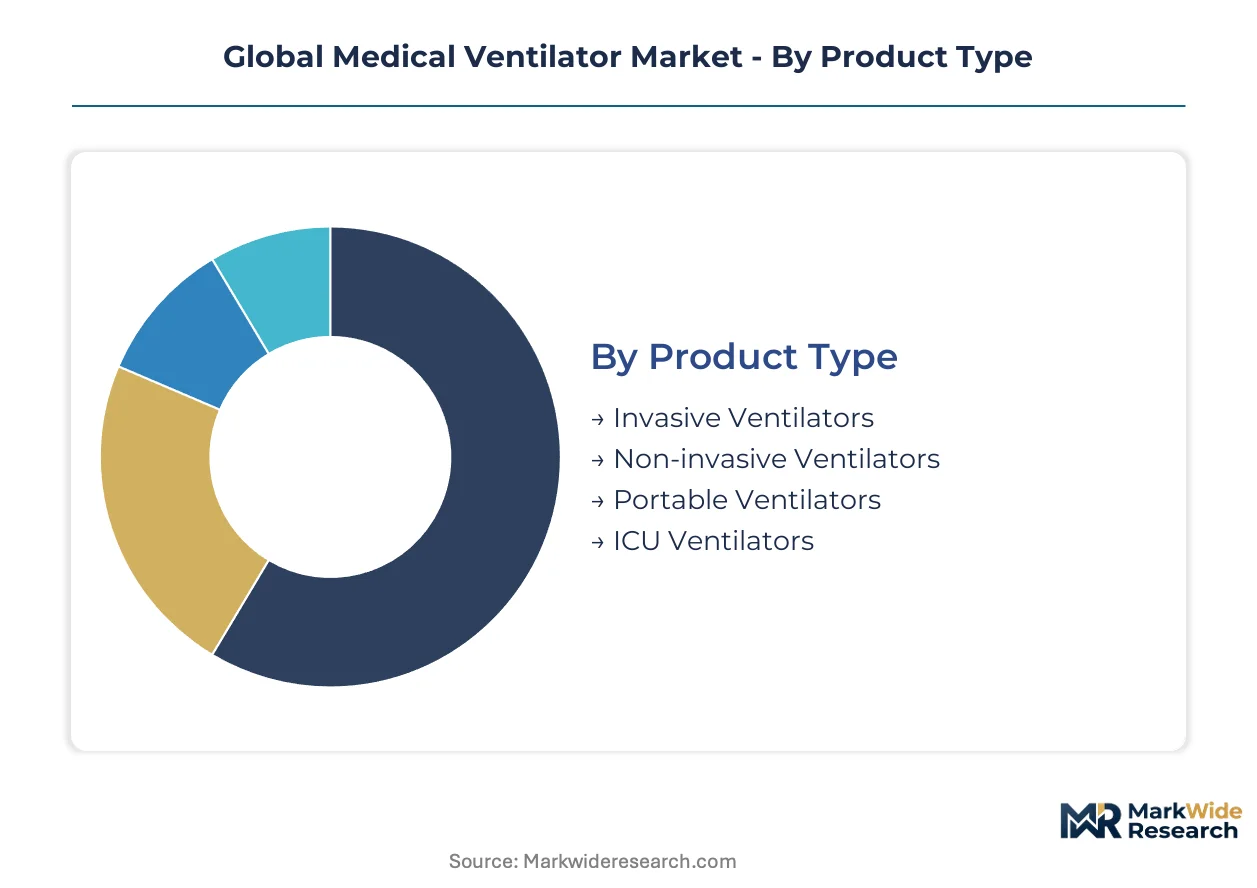
Ventilator procurement patterns diverge sharply across clinical settings, with ICU-grade systems commanding multi-year service contracts while portable platforms drive volume expansion in post-acute channels. Technology selection increasingly hinges on protocol standardization mandates from university hospital networks rather than individual clinician preference.
Product Type:
Hospital procurement consortiums differentiate purchasing power based on acuity tier and total cost of ownership horizons rather than upfront capital expenditure alone.
- Invasive Ventilators:These systems deliver breathable air through endotracheal or tracheostomy tubes, operating at tidal volumes of 200-2000 mL with respiratory rates up to 150 breaths per minute. Demand concentrates in German university hospital networks standardizing on dual-mode platforms for respiratory failure protocols, where closed-loop algorithm validation requirements favor established OEMs with legacy quality infrastructure.
- Portable Ventilators:Battery-powered platforms weighing under 10 kilograms enable intra-hospital transport and home-based respiratory support. United States post-acute care facilities are building dedicated respiratory therapy wings, generating pull-through demand for units with extended battery autonomy and simplified caregiver interfaces.
- Non-invasive Ventilators:Mask-delivered positive pressure systems support spontaneous breathing without airway instrumentation, dominating sleep apnea and early-stage COPD management in outpatient settings.
- ICU Ventilators:High-acuity platforms integrate multi-parameter monitoring and advanced weaning protocols, anchoring vendor recurring revenue through preventive maintenance contracts and consumables replenishment.
Volume sits with invasive ventilators; growth tilts toward portable ventilators.
Technology:
Control architecture selection determines regulatory pathway complexity and software update velocity under FDA 510(k) and EU MDR frameworks.
- Dual Mode:Seamless pressure-to-volume control transitions without circuit changes represent the dominant R&D investment target. German and Austrian university hospital ICUs are mandating this capability for ARDS protocol management, compressing differentiation timelines among OEMs and forcing accelerated development cycles.
- Pressure Controlled:Constant airway pressure delivery with variable tidal volumes serves neonatal and lung-protective ventilation strategies, retaining share in pediatric and trauma applications where barotrauma avoidance is paramount.
- Volume Controlled:Fixed tidal volume delivery with variable pressure remains standard for surgical anesthesia and routine post-operative ventilation where minute ventilation targets are predictable.
- High Frequency Oscillatory:Ultra-rapid small-volume breath delivery at frequencies exceeding 150 cycles per minute addresses refractory hypoxemia in specialized ARDS centers, constrained by limited clinical evidence and specialized training requirements.
Installed base concentrates in volume controlled; specification momentum favors dual mode.
Application:
Clinical indication severity shapes reimbursement coding and device feature requirements across acute and chronic care pathways.
- Acute Respiratory Distress Syndrome:Severe inflammatory lung injury requiring precise PEEP titration and prone positioning coordination. Hamilton Medical's closed-loop ventilation algorithms are overtaking conventional open-loop modes in German ICUs, reducing clinician intervention frequency.
- Respiratory Failure:Broad category encompassing hypoxic and hypercapnic decompensation from trauma, infection, or neurological injury. North American hospital procurement consortiums are consolidating purchasing power for ICU-grade systems, restructuring vendor pricing around multi-year service contracts.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation driving home ventilation adoption for chronic hypercapnic respiratory failure, with reimbursement rates influencing vendor profitability in United States Medicare channels.
- Sleep Apnea:Obstructive and central breathing disturbances during sleep, served primarily by non-invasive bilevel positive airway pressure systems with automated pressure adjustment algorithms.
Case volume concentrates in respiratory failure; technology intensity peaks in acute respiratory distress syndrome.
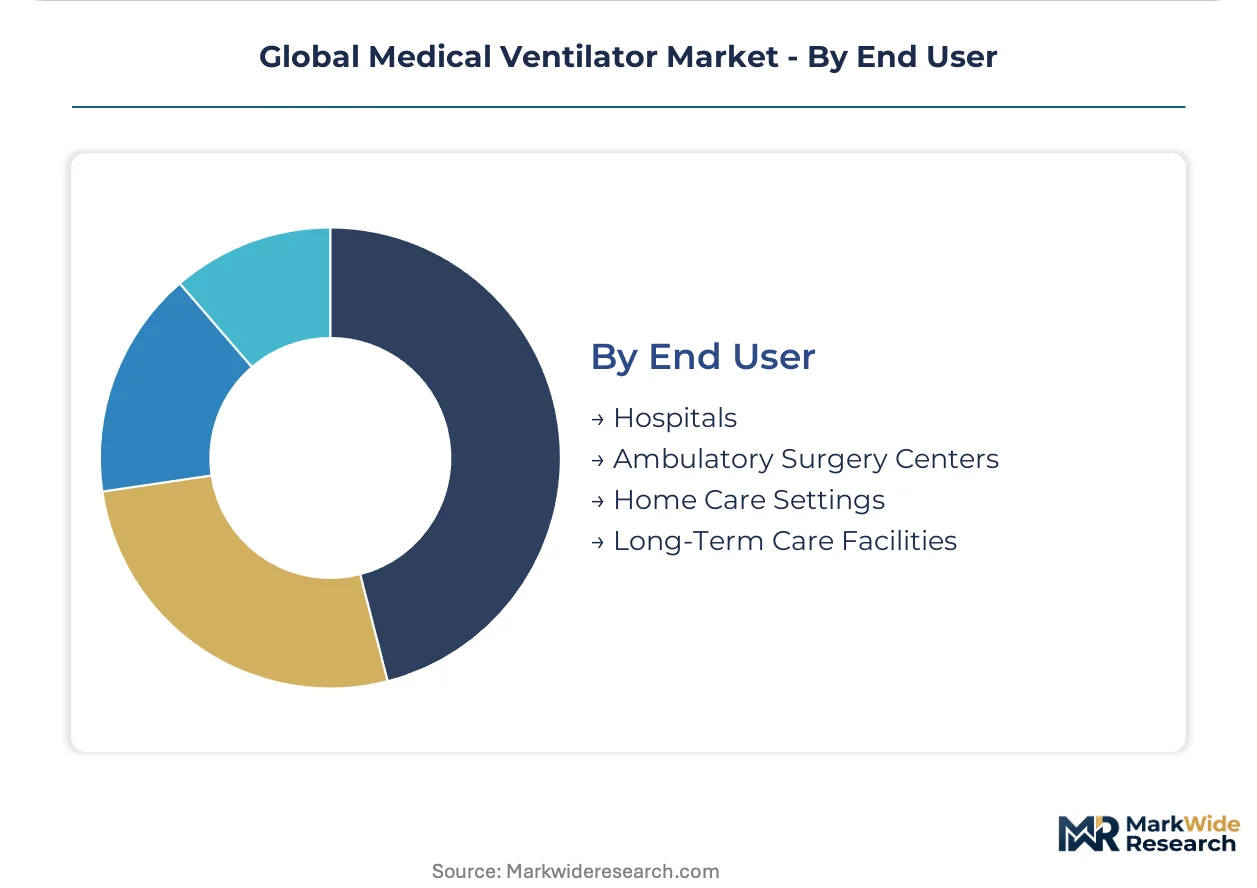
End User:
Facility type determines service model expectations, from 24/7 biomedical engineering support in tertiary centers to remote monitoring reliance in dispersed home care networks.
- Hospitals:Acute care institutions with centralized biomedical engineering and respiratory therapy departments. IDN purchasing coalitions in the United States favor vendors with integrated service platform capabilities over point-product specialists.
- Home Care Settings:Patient residences and dedicated respiratory therapy wings in post-acute facilities. Skilled nursing facilities are unbundling ventilator service contracts from acute-care vendors, opening distribution entry points for specialized respiratory equipment suppliers.
- Ambulatory Surgery Centers:Short-stay surgical facilities requiring rapid induction and emergence ventilation capabilities with minimal footprint and simplified disinfection protocols.
- Long-Term Care Facilities:Nursing homes and chronic disease management centers building ventilator-dependent patient capacity, driving demand for caregiver-friendly interfaces and remote physician oversight connectivity.
Revenue concentrates in hospitals; channel expansion is accelerating fastest in home care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian semiconductor foundries anchor component supply for ventilator microcontroller and sensor production, while German university hospital networks drive clinical specification standards for dual-mode respiratory platforms.
United States
IDN purchasing coalitions consolidate procurement power for ICU-grade systems, restructuring vendor relationships around multi-year service contracts. The FDA's streamlined 510(k) pathway for software-as-medical-device ventilator controls accelerates algorithmic product iterations. Post-acute facilities in Florida and Texas are building dedicated respiratory therapy wings, generating pull-through demand for portable platforms with extended battery autonomy.
Germany
University hospital networks in Bavaria and Baden-Württemberg mandate seamless pressure-to-volume control transitions without circuit changes for ARDS protocol management. The EU Medical Device Regulation's stricter clinical evidence requirements extend certification timelines, concentrating market access among established manufacturers with legacy quality infrastructure. Berlin-Brandenburg hosts regulatory consulting clusters supporting MDR compliance documentation for ventilator software updates.
China
NMPA enforcement of GB standards for respiratory device electromagnetic compatibility and biocompatibility creates separate validation burdens for manufacturers lacking in-country regulatory partnerships. The Yangtze River Delta concentrates microcontroller and sensor component production, exposing ventilator OEMs to geopolitical supply disruption risks. Shanghai-based hospital procurement is standardizing on domestic ventilator platforms for routine respiratory support.
Japan
METI coordinates healthcare technology assessment with PMDA reimbursement rate-setting, influencing vendor profitability through industrial policy alignment. The Kanto region around Tokyo anchors demand for high-acuity invasive ventilators with integrated multi-parameter monitoring. Osaka-based respiratory equipment distributors are expanding into long-term care facility channels as skilled nursing capacity for ventilator-dependent patients grows.
India
CDSCO regulatory pathways for imported respiratory devices create entry barriers for ventilator OEMs without local manufacturing partnerships or clinical trial infrastructure. Maharashtra and Karnataka host medical device manufacturing zones attracting contract assembly operations for portable ventilator platforms. Delhi-NCR hospital procurement is consolidating around price-competitive dual-mode systems for government hospital respiratory failure protocols.
Global Medical Ventilator Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-enabled ventilation adjustment and closed-loop algorithm specialization. The market structures around three tiers: multinational conglomerates with integrated monitoring-ventilator platforms, mid-scale specialists in intensive care ventilation, and regional assemblers serving price-sensitive procurement channels. Strategic archetypes include software-defined control architects, dual-mode protocol specialists, and service-contract integrators. Competitive moves concentrate on M&A for algorithmic capabilities and geographic expansion through regulatory footprint extension.
Among diversified health technology conglomerates, Koninklijke Philips N.V. and Medtronic plc exemplify scale-driven positions spanning FDA, EMA, and PMDA jurisdictions. Hamilton Medical represents the European specialist archetype, with its intensive care focus and closed-loop ventilation algorithms anchoring German and Austrian university hospital procurement. These three companies illustrate how installed base integration, geographic regulatory breadth, and clinical specialization respectively structure competitive positioning in high-acuity ventilator segments.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Hamilton Medical |
| Getinge AB |
| Medtronic plc |
| ResMed |
| GE Healthcare |
| Drägerwerk AG & Co. KGaA |
| Vyaire Medical, Inc. |
| Fisher & Paykel Healthcare Limited |
| Others |
Supply & Pricing Matrix
North American hospital procurement consortiums are consolidating purchasing power for ICU-grade ventilator systems, forcing vendors to restructure pricing around multi-year service contracts rather than equipment margins alone and compressing supplier choice toward established manufacturers with integrated service platforms.
Pricing Analysis
Multi-year total cost of ownership contracts unbundle hardware acquisition from preventive maintenance, remote monitoring, and consumables replenishment into subscription structures. Price differentiation hinges on software update velocity under FDA 510(k) pathways and geographic regulatory breadth spanning FDA, EMA, and PMDA jurisdictions. Cost compression in portable ventilator tiers is intensifying because post-acute care facilities are unbundling service contracts from acute-care vendors. Skilled nursing facilities exhibit highest price sensitivity; German university hospital networks show lowest sensitivity due to protocol standardization mandates.
Supply Chain Analysis
China's NMPA enforcement of GB standards for respiratory device electromagnetic compatibility and biocompatibility is reshaping sourcing toward domestic manufacturers with in-country regulatory partnerships. Critical microcontroller and sensor component production concentrates in China, Taiwan, and South Korea, exposing ventilator OEMs to geopolitical supply disruption risks. Semiconductor foundry capacity feeds from East Asian production clusters. Distribution runs through hospital procurement consortiums in North America and GPO contracts in United States IDN purchasing coalitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry concentration for ventilator microcontrollers and sensors is constraining component availability, propping pricing power for manufacturers with captive supply agreements or legacy inventory positions.
For Market Incumbents: Hedge against algorithmic disruption by acquiring closed-loop ventilation software specialists before FDA draft guidance on AI-enabled controls solidifies submission categories. Deepen backward integration into sensor component supply through partnerships with Yangtze River Delta foundries. Fortify position against emerging software-defined ventilation entrants by accelerating preventive maintenance contract penetration in United States IDN purchasing coalitions. For New Entrants and Emerging Players: AI-enabled ventilation adjustment algorithms represent the most penetrable white space, with FDA draft guidance creating regulatory runway for differentiated positioning. Target United States skilled nursing facility channels where ventilator service contracts are unbundling from acute-care vendors. Pursue Japan METI industrial coordination alignment for reimbursement rate tailwinds in Kanto region high-acuity demand. For Investors and Strategic Acquirers: The window for entry favors software-defined control architects with EU MDR quality infrastructure already deployed. Five-to-ten year viability hinges on regulatory dossier depth rather than hardware scale alone. Watch FDA final guidance on artificial intelligence-enabled ventilation adjustments as inflection indicator for premarket submission category consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software Pathway Expansion | Accelerates algorithmic product iterations for software-as-medical-device ventilator controls. |
| EU MDR Quality Infrastructure Investment | Extends certification timelines for new entrants, concentrating access among established manufacturers. |
| Hospital System Partnership Consolidation | Restructures vendor relationships around multi-year service contracts in North American IDN coalitions. |
| Closed-Loop Algorithm Development | Reduces clinician intervention frequency for ARDS protocol management in German university hospital ICUs. |
| Long-Term Care Channel Expansion | Opens distribution entry points as skilled nursing facilities unbundle ventilator service contracts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and respiratory therapy directors. FDA 510(k) premarket notification databases, EU MDR technical documentation, and Japan PMDA reimbursement schedules provided regulatory validation. Bottom-up ventilator unit shipment estimates triangulated against top-down hospital procurement spend data.
Shipment volume and revenue outputs reflect reconciliation across product type, technology architecture, clinical application, and end-user facility tiers throughout the forecast period. CAGRs were derived from weighted regression of historical procurement patterns and protocol standardization mandates. Industry-specific inputs included German university hospital network specification requirements and United States post-acute care facility respiratory therapy wing buildout rates.
Several conditions sit outside the modeled scope, including pandemic-driven demand surges, geopolitical semiconductor export restrictions, and radical platform shifts in ventilation control architectures. Forecasts reflect documented assumptions about regulatory pathway stability and hospital capital expenditure continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Lower Respiratory Tract Infection Treatment Market
Respiratory Care
Aspirin Exacerbated Respiratory Disease Market
Respiratory Care
Respiratory Distress Syndrome Management Market
Respiratory Care
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Global Respiratory Care Devices Market
Respiratory Care
Lung Management Products Market
Respiratory Care
Global Chronic Obstructive Pulmonary Disease Market
Respiratory Care
Asthma and COPD Drugs Market
Respiratory Care
Budesonide Inhaler Market
Respiratory Care
Global Respiratory Disposable Market
Respiratory Care
Global Respiratory Heaters Market
Respiratory Care
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Ventilator-Associated Pneumonia (VAP) Market
Respiratory Care
Global Neonatal Intensive Care Respiratory Devices Market
Respiratory Care
Emphysema Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market