
 Global Bariatric Walking Aids Market | 2026-2036
Global Bariatric Walking Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bariatric Walking Aids Market Intelligence
A shift from institutional settings to home healthcare environments is rebalancing the end-use customer mix for bariatric walking aids. Drive DeVilbiss Healthcare leverages its extensive distribution network to serve both channels effectively. In contrast, Invacare Corporation specializes in durable medical equipment tailored for complex patient needs in residential care. GF Health Products competes on the basis of manufacturing scale and product line breadth, targeting a wide range of institutional and individual buyers.
Bariatric walking aids are mobility support devices engineered to safely support individuals with body weights exceeding standard equipment limits, often rated for 500 to 1,000 pounds. Their primary purpose is to enhance stability and reduce load on lower limbs during ambulation. Within product types, bariatric rollators are gaining preference over traditional walkers due to their wheeled design and integrated seating. Material composition determines cost and performance, with aluminum dominating the mass market while carbon fiber defines the premium category.
Regulatory compliance is a critical market barrier, governed by agencies like the FDA in the United States and through CE marking requirements under the EU's Medical Device Regulation (MDR). These frameworks mandate specific testing for weight capacity, structural integrity, and material safety to ensure user protection. Future competitive advantage will hinge on manufacturers' ability to innovate with lighter, stronger materials while navigating evolving reimbursement policies from public and private payers.
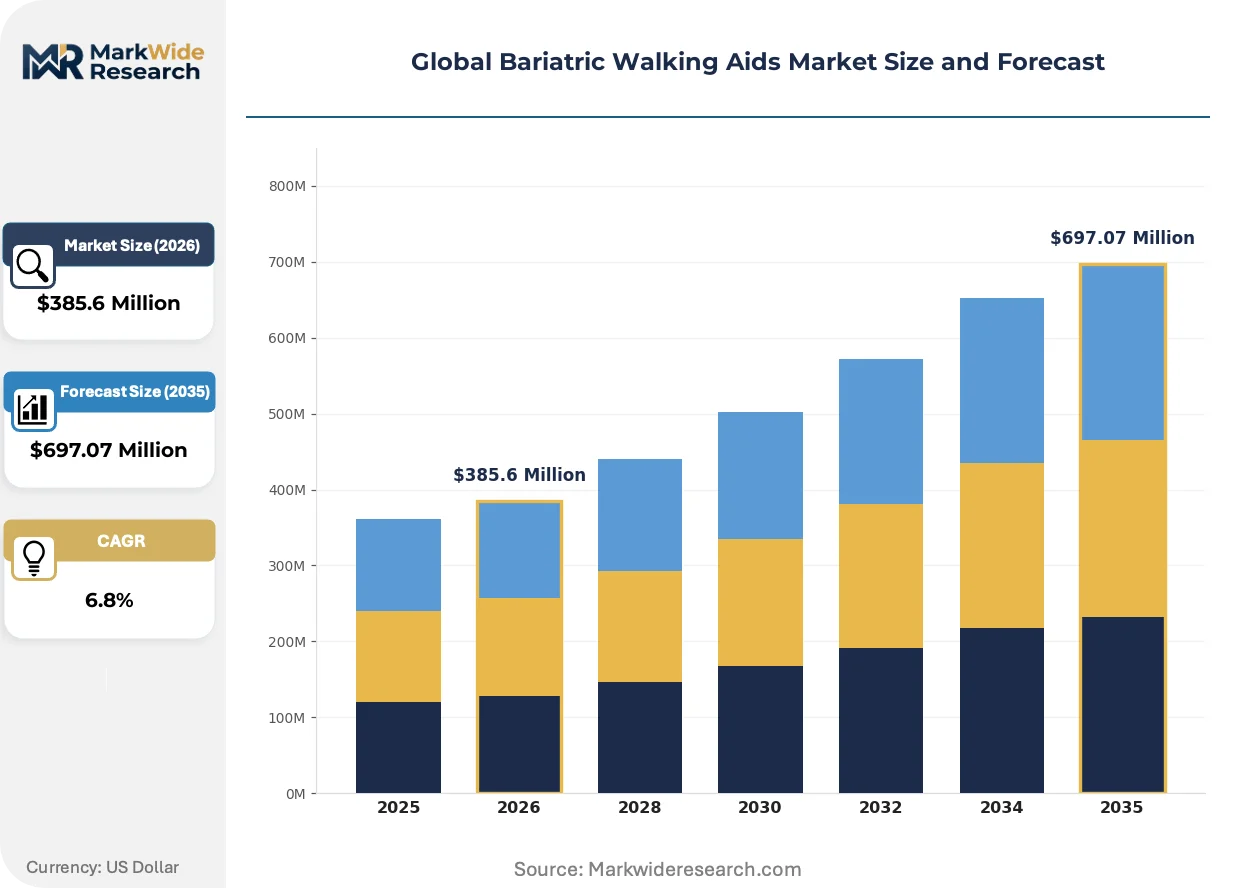
Market Dynamics
The growing prevalence of obesity worldwide, coupled with the systemic shift of patient care from institutional settings to home environments, is the primary force shaping demand and product development in the bariatric walking aids market.
Growth Catalysts
- Favorable Reimbursement:Government and private insurance reimbursement frameworks, such as Medicare coverage for durable medical equipment in the United States, reduce the out-of-pocket cost for patients, stimulating demand.
- Rising Obesity Rates:Increasing obesity and morbid obesity rates in developed nations, including Germany and the United Kingdom, directly expand the addressable patient population requiring specialized mobility support.
- Material Advancements:The commercialization of high-strength, lightweight materials like carbon fiber and advanced aluminum alloys enables the design of more user-friendly and portable bariatric aids.
Market Restraints
- High Input Costs:The specialized materials required for high weight capacity, particularly carbon fiber and reinforced aluminum, carry a significant cost premium that translates to higher end-product prices.
- Regulatory Hurdles:Stringent regulatory pathways, including the FDA's clearance process in the US and CE marking under the EU's MDR, create significant barriers to entry and lengthen time-to-market.
- Alternative Mobility Solutions:Bariatric walking aids face competition from powered mobility devices, such as scooters and wheelchairs, which may be preferred by individuals with more severe ambulatory limitations.
Strategic Opportunities
- Geographic Expansion:Significant opportunity exists in markets with rapidly aging populations and rising incomes, such as Japan and South Korea, where demand for specialized durable medical equipment is growing.
- Direct-to-Consumer Channels:The development of robust e-commerce platforms allows manufacturers to bypass traditional distribution channels and engage directly with end-users, offering greater choice and customization.
- Smart Device Integration:Incorporating digital technologies like fall detection sensors, GPS tracking, and connectivity to telehealth platforms represents a major avenue for product differentiation and value creation.
Industry Challenges
- Supply Chain Volatility:Manufacturers face challenges in managing complex global supply chains for components, making them vulnerable to geopolitical tensions, shipping disruptions, and tariff fluctuations affecting parts from China.
- Post-Market Surveillance:Adhering to the continuous post-market surveillance and reporting requirements mandated by regulations like the EU's MDR imposes a significant and ongoing operational burden.
- Scaled Customization:Balancing the manufacturing efficiencies of mass production with the growing patient demand for personalized and custom-fitted walking aids presents a persistent operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bariatric Walking Aids Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walkers, Rollators, Canes, Crutches, Wheelchairs User Age Group: Adults, Seniors, Teenagers, Middle-Aged, Geriatric Material Composition: Aluminum, Stainless Steel, Carbon Fiber, Plastic, Composite Distribution Channel: Online Stores, Specialty Clinics, Medical Supply Stores, Pharmacies, Home Healthcare Providers |
| Companies Covered | Invacare Corporation, Medline Industries, GF Health Products, Nova Medical Products, Drive DeVilbiss Healthcare, Ottobock, Sunrise Medical, Compass Health Brands, Performance Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bariatric Walking Aids Market Strategic Shifts & Innovations
Product evolution in bariatric walking aids is driven by material science advancements aimed at reducing weight and by the integration of digital technologies. These innovations focus on enhancing user safety, comfort, and connectivity with healthcare providers.
Carbon fiber composites provide a superior strength-to-weight ratio, a critical feature for bariatric users who need both robust support and portability. The premium home healthcare segment is adopting these materials for high-end rollators and walkers. This focus on advanced composites is absorbing development resources that were previously dedicated to incremental improvements in traditional aluminum designs.
The European Union's Medical Device Regulation (MDR) mandates more rigorous clinical evaluation and post-market surveillance for all medical devices, including bariatric aids. This regulation forces manufacturers to generate more robust data on product safety and performance throughout the device lifecycle. The bariatric rollator category, with its higher complexity and integrated features, faces the most significant compliance burden.
A notable shift is occurring where end-users and their families are increasingly involved in product selection, often researching and purchasing directly through online channels. This consumer-driven behavior disrupts the traditional B2B sales model focused on institutional procurement by hospitals and long-term care facilities. This trend is most prominent in the United States home healthcare market.
Global Bariatric Walking Aids Market Segmentation
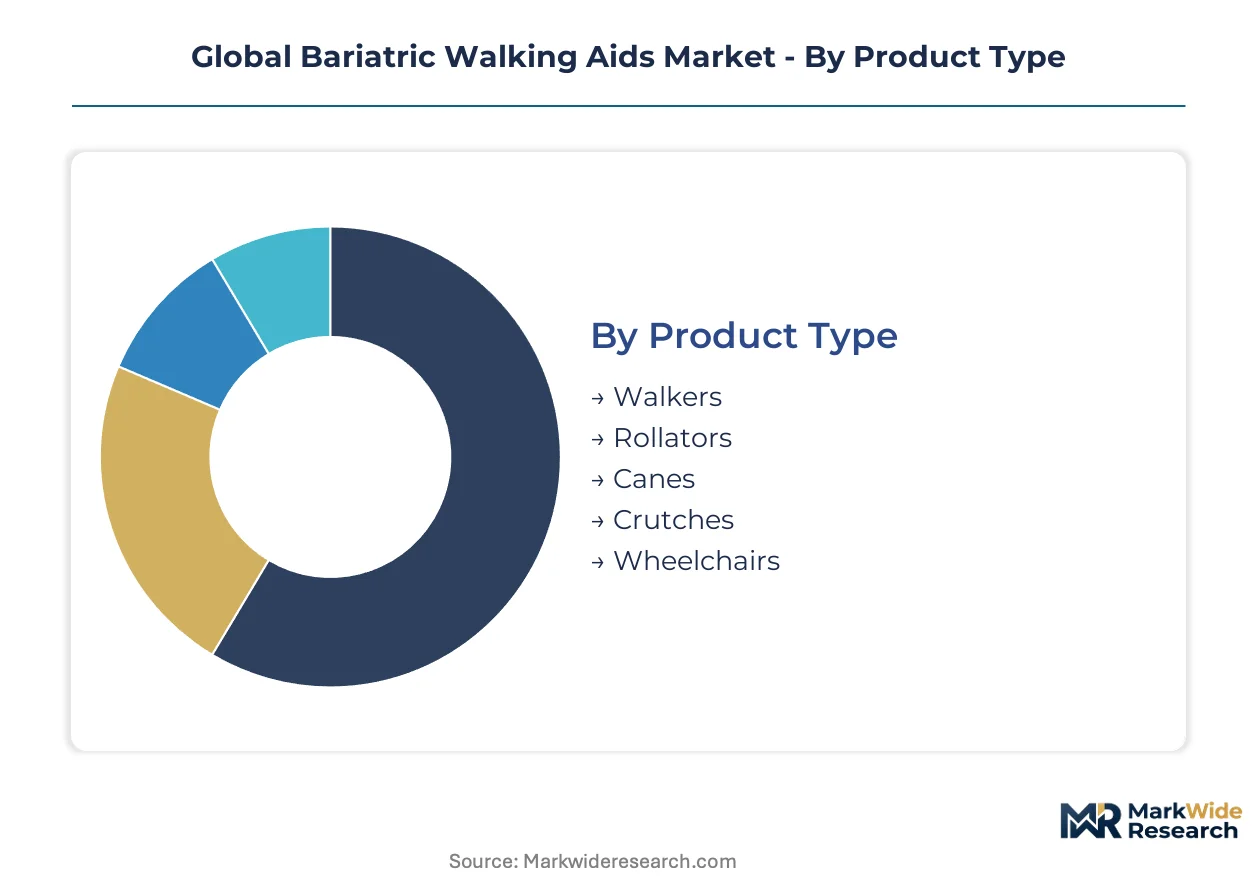
The bariatric walking aids market is highly segmented, reflecting the diverse needs of patients, varied product functionalities, and complex distribution ecosystems. Understanding these segmentations is critical for manufacturers to align product development with specific demand pockets and for providers to optimize patient care solutions.
Product Type:
The capital intensity of manufacturing bariatric walking aids varies significantly across product types, influencing market entry and production scale for different manufacturers.
- Rollators:These wheeled devices feature integrated seating and brakes, offering enhanced mobility and resting options for users. Demand from home healthcare providers and individuals seeking greater independence drives this segment.
- Wheelchairs:Designed for individuals with more severe ambulatory limitations, bariatric wheelchairs offer robust support and can be manual or powered. They represent a higher investment for both manufacturers and end-users due to their complexity and material requirements.
- Walkers:Traditional four-legged frames provide basic stability and support during ambulation.
- Canes:Single-point or quad-base canes offer minimal support, typically for balance assistance.
- Crutches:Used for temporary support, often post-injury, to offload weight from lower limbs.
Most installed capacity flows through Walkers. Expansion is steepest in Rollators.
User Age Group:
Demand for bariatric walking aids is highly stratified by user age group, reflecting distinct mobility challenges and care requirements across different life stages.
- Seniors:This demographic represents a substantial user base, often requiring bariatric aids due to age-related mobility decline compounded by obesity. Home healthcare settings frequently serve this patient cohort.
- Geriatric:Very elderly individuals, often with multiple comorbidities, require highly specialized and robust bariatric equipment for maximum support and safety. Their complex needs drive demand for advanced features.
- Adults:This broad segment includes individuals who may temporarily require bariatric aids due to surgery or injury.
- Middle-Aged:Patients in this group often seek aids for chronic conditions or early-onset mobility issues.
- Teenagers:A smaller, specialized segment for younger bariatric patients requiring mobility support.
The largest patient cohort resides within the Seniors group. The Geriatric segment is climbing the fastest.
Material Composition:
Material composition directly influences the cost, performance, and durability of bariatric walking aids, establishing distinct product tiers across the market.
- Aluminum:Dominates the mass market due to its optimal balance of strength, lightweight properties, and cost-effectiveness. This material is widely utilized in standard bariatric walkers and rollators.
- Carbon Fiber:This advanced material defines the premium category, offering a superior strength-to-weight ratio for enhanced user comfort and portability. It is increasingly adopted in high-end bariatric rollators and specialized aids.
- Stainless Steel:Offers high durability and corrosion resistance, often used for heavy-duty bariatric equipment where maximum structural integrity is paramount.
- Plastic:Primarily used in non-load-bearing components or for very basic, lightweight bariatric aids.
- Composite:Blends different materials to optimize properties, balancing performance with cost.
Aluminum materials account for the largest volume. Carbon Fiber materials are gaining share fastest.
Distribution Channel:
The distribution channel landscape for bariatric walking aids is rebalancing, reflecting shifts in patient care settings and consumer purchasing behaviors across various geographies.
- Home Healthcare Providers:These entities are critical for delivering bariatric equipment directly to patients in their residences, driven by the systemic shift from institutional care in the United States and Europe. They require reliable, user-friendly devices.
- Online Stores:Enable direct-to-consumer sales, offering greater choice, customization, and price comparison, particularly prominent in the United States home healthcare market. This channel bypasses traditional distribution.
- Medical Supply Stores:Traditional brick-and-mortar retail points for durable medical equipment, offering product trials and expert advice to end-users.
- Specialty Clinics:These facilities provide specialized assessment, fitting services, and product recommendations for complex bariatric patient needs.
- Pharmacies:Offer convenient access for basic mobility aids and related supplies, often catering to immediate or less complex needs.
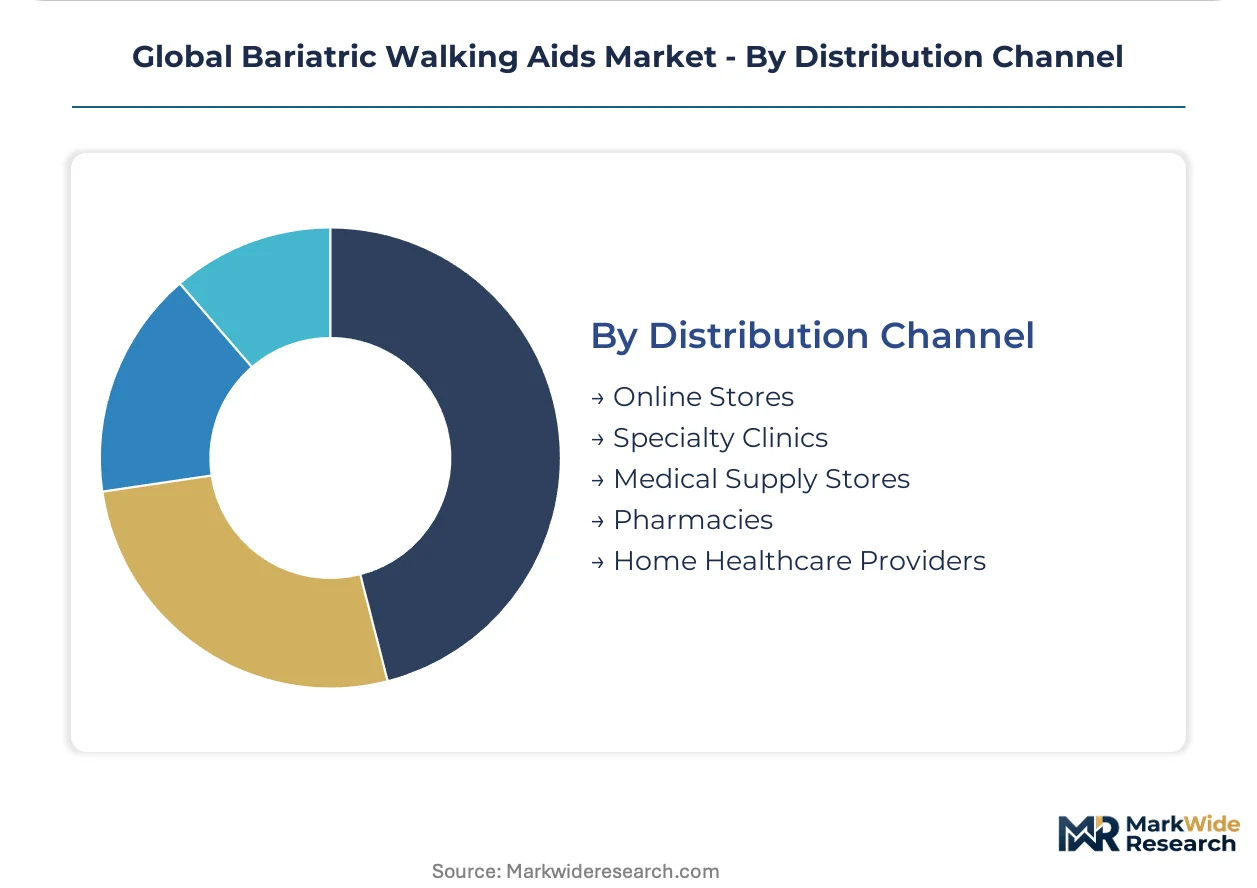
Medical Supply Stores traditionally handle the bulk of sales. Online Stores show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory compliance costs significantly influence manufacturing locations for bariatric walking aids, creating a dynamic of regulatory arbitrage where production migrates to optimize cost-of-compliance gaps. This phenomenon affects the global supply chain, particularly for devices requiring stringent certifications. Market expansion also depends on local healthcare infrastructure and reimbursement policies.
United States
High obesity rates and a robust home healthcare sector drive substantial demand for bariatric walking aids. Medicare coverage for durable medical equipment reduces patient out-of-pocket expenses, further stimulating market activity. Medical device clusters in regions like Minneapolis actively innovate in advanced bariatric mobility solutions, focusing on user comfort and safety.
Germany
An aging population combined with increasing obesity rates across Europe underpins demand for specialized mobility solutions in Germany. CE marking under the EU's Medical Device Regulation (MDR) sets rigorous standards for product safety and performance. The Stuttgart region, a hub for medical technology, leads in developing carbon fiber components for lightweight bariatric rollators.
China
Rising incomes and an expanding middle class contribute to increasing demand for bariatric walking aids, particularly in urban areas. National Medical Products Administration (NMPA) approval is mandatory for market entry, ensuring product quality and safety. Shenzhen's extensive manufacturing infrastructure produces a wide range of cost-effective bariatric aids for both domestic consumption and international export.
Japan
Japan's rapidly aging population creates a strong imperative for independent living solutions, including bariatric walking aids. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees device approvals, while a comprehensive long-term care insurance system supports patient access. Osaka, a prominent medical device center, specializes in compact and ergonomically designed aids suited for dense urban environments.
United Kingdom
The United Kingdom faces rising obesity rates, placing pressure on the National Health Service (NHS) to support home-based care. Post-Brexit, UKCA marking is required for medical devices, alongside adherence to NHS procurement guidelines. The Cambridge biotech cluster explores digital integration for bariatric mobility devices, enhancing user connectivity and monitoring capabilities.
Global Bariatric Walking Aids Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with a clear tiered structure emerging in the global bariatric walking aids market. This market structure features premium innovators focusing on advanced materials and digital integration, alongside mass-market producers emphasizing cost-effectiveness and broad distribution. Strategic partnerships for technology licensing and geographic expansion represent dominant competitive moves among market participants.
Within the premium and specialized solutions tier, Invacare Corporation represents a key player, focusing on durable medical equipment tailored for complex patient needs in residential care environments. Drive DeVilbiss Healthcare occupies a significant position through its extensive distribution network, effectively serving both institutional settings and home healthcare channels. GF Health Products anchors the market with its substantial manufacturing scale and broad product line, targeting a wide spectrum of institutional and individual buyers.
| Leading Market Players |
|---|
| Invacare Corporation |
| Medline Industries |
| GF Health Products |
| Nova Medical Products |
| Drive DeVilbiss Healthcare |
| Ottobock |
| Sunrise Medical |
| Compass Health Brands |
| Performance Health |
Cost & Logistics Intelligence
Family-owned mid-caps often navigate the bariatric walking aids market with a focus on specialized product lines, influencing both their procurement strategies and pricing flexibility in niche segments.
Pricing Analysis
Distributor margins significantly influence the final cost of bariatric walking aids. The dominant pricing model remains per-unit transactional, reflecting direct product sales. Price differentiation stems from material composition and FDA certification levels. Cost compression in the mass market is intensifying due to competition, making home healthcare providers particularly price-sensitive.
Supply Chain Analysis
Regional distribution centers facilitate the efficient flow of bariatric aids to various end-users. The supply chain for components draws from China for parts and raw materials, with final assembly often occurring in the United States and Germany. Key dependencies include advanced aluminum alloys and carbon fiber composites. Geopolitical tensions represent a structural risk to the global supply chain. The dominant distribution model is a hybrid of B2B sales and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market acts as a regulatory compounder, with the EU's Medical Device Regulation (MDR) driving demand for enhanced product safety and performance across Europe.
For Market Incumbents: Extend existing distribution networks, particularly within the United States home healthcare sector, to counter the threat of direct-to-consumer models. Invest in advanced materials R&D, focusing on carbon fiber composites for premium bariatric rollators, to maintain product differentiation against mass-market producers. Pursue vertical integration into key component manufacturing for supply chain resilience.
For New Entrants and Emerging Players: CE marking under the EU's MDR in Europe opens a window for new entrants to differentiate through rigorous compliance and documented clinical performance. Target the geriatric segment with specialized, feature-rich bariatric rollators offering advanced fall detection. A direct-to-consumer e-commerce model provides an effective go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with strong local distribution but limited international reach. Long-term viability hinges on companies that can balance regulatory compliance costs with material innovation. Target acquisition archetypes include mid-sized manufacturers specializing in carbon fiber components. Watch for increasing private insurance reimbursement rates in the United States as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Extension | Broadens offerings to capture diverse bariatric patient needs. |
| Direct-to-Consumer Channel Development | Bypasses traditional distributors, improving margin and customer insights. |
| Carbon Fiber Material R&D | Enables lighter, stronger bariatric aids, enhancing user comfort and portability. |
| Regulatory Compliance Investment | Ensures market access and builds trust with healthcare providers in Europe. |
| Telehealth Platform Integration | Adds value through remote monitoring and connectivity for bariatric users. |
Research Approach
Coverage spans the United States, Germany, and Japan, with primary inputs from each country combining interviews with industry stakeholders and secondary validation. Stakeholder roles included medical device engineers, hospital procurement managers, home healthcare administrators, and regulatory affairs specialists. Secondary sources comprised FDA filings, EU MDR guidance documents, and durable medical equipment market reports. Bottom-up and top-down triangulation ensured data accuracy.
Market dimensions were modeled at granular levels, including product type, user age group, material composition, and distribution channel. The analytical framework projects market growth across the analysis window, deriving CAGRs from historical trends and future demand projections. Industry-specific inputs included obesity prevalence rates and healthcare expenditure forecasts.
Revisions become necessary when significant shifts in reimbursement policies or material costs materialize. Forecasts reflect assumptions regarding regulatory stability and technological innovation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
South Korea Bariatric Surgery Market
Bariatric Surgery
Italy Bariatric Surgery Market
Bariatric Surgery
Bariatric Patient Room Market
Bariatric Surgery
United States Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgical Devices Market
Bariatric Surgery
Bariatric Medical Chairs Market
Bariatric Surgery
North America Bariatric Surgery Devices Market
Bariatric Surgery
South Africa Bariatric Surgery Market
Bariatric Surgery
Bariatric Lifts Market
Bariatric Surgery
Bariatric Transport Wheelchairs Market
Bariatric Surgery
US Medical Weight Loss Clinics Market
Bariatric Surgery
Spain Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Market
Bariatric Surgery
Brazil Bariatric Surgery Market
Bariatric Surgery
Australia Bariatric Surgery Market