
 Active Wheelchair Market | 2026-2036
Active Wheelchair Market Size, Share, and Industry Trends Forecast 2026-2036
Active Wheelchair Market Intelligence
Carbon fiber is expanding its share in high-performance frame construction as manufacturers trade steel weight penalties for stiffness-to-mass ratios that improve propulsion efficiency. TiLite leverages captive titanium supply chains to dominate ultralight racing and everyday active segments. Sunrise Medical sustains broad geographic coverage through diversified aluminum and carbon fiber portfolios across European and North American rehabilitation channels.
An active wheelchair is a manually propelled mobility device engineered for users with sufficient upper-body function, typically featuring cambered rear wheels, adjustable axle plates, and frame angles optimized for forward propulsion biomechanics rather than attendant pushing. The primary purpose is to restore independent community mobility and sports participation for individuals with spinal cord injuries, amputations, or neurological conditions. Manual configurations still occupy the largest volume position, though carbon fiber variants within this category command disproportionate margin pools due to material scarcity and fabrication complexity. Powered technology integrating joystick control and adjustable seating systems represents the fastest-expanding segment as aging users with progressive conditions seek to preserve independence without sacrificing active-frame ergonomics.
The FDA enforces 21 CFR 890 wheelchair standards for US market access, while ISO 7176 technical specifications govern European and Asian certification pathways, creating divergent testing burdens for multinational suppliers. REACH chemical regulations and EU MDR device classification rules increasingly frame material selection and biocompatibility documentation for frames and seating components. Stakeholders must monitor how FDA predicate device pathways and evolving ISO suspension testing protocols reshape R&D allocation between ultralight manual platforms and sensor-enabled powered alternatives.
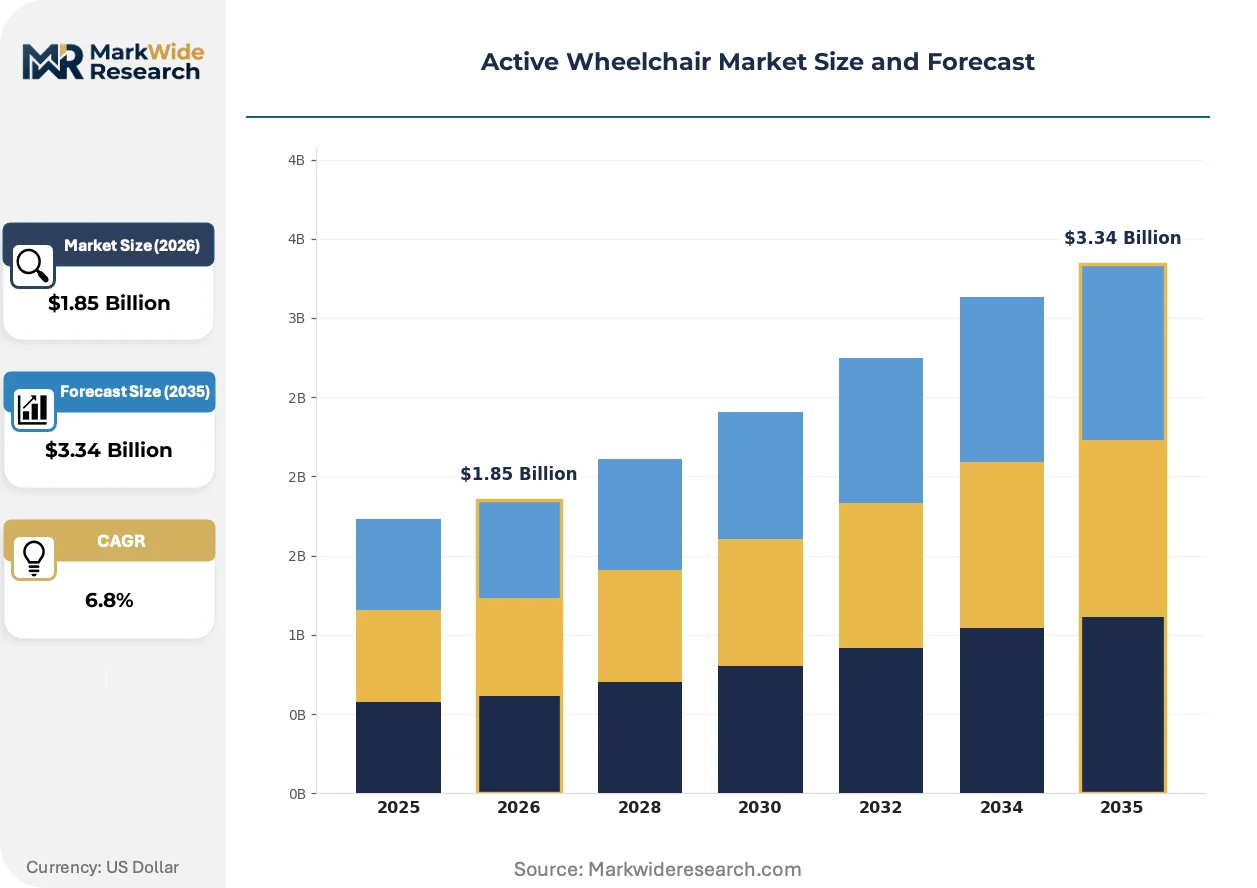
Market Dynamics
Carbon fiber fabrication complexity and titanium supply chain concentration are compressing margin pools for mid-tier manufacturers while rewarding vertically integrated specialists with captive material access.
Growth Catalysts
- Paralympic Sports Expansion:Adaptive athletics programs in Germany, Australia, and Japan are creating sustained replacement cycles for ultralight racing configurations as competitive participation broadens beyond elite tiers.
- ISO 7176 Suspension Testing:Updated certification protocols for vibration damping and impact resistance are forcing performance upgrades across European distribution channels, accelerating product refresh rates.
- Powered Manual Hybrids:Joystick-enabled active frames with detachable power assist modules are capturing aging users with progressive neurological conditions who resist full transition to conventional powerchairs.
Market Restraints
- Titanium Feedstock Concentration:Sponge supply from Russian and Kazakh producers faces export licensing volatility, compressing availability for ultralight frame producers dependent on Ti-3Al-2.5V alloy.
- REACH Chemical Compliance:ECHA restrictions on hexavalent chromium plating processes for axle hardware are forcing costly conversion to trivalent alternatives or ceramic coatings.
- Home-Based Care Substitution:Full-electric indoor powerchairs with standing function are displacing manual active frames among non-ambulatory users with adequate upper-body function but limited community mobility goals.
Strategic Opportunities
- Indian Rehabilitation Infrastructure:Central government disability pension expansion and state-level assistive device distribution schemes are creating first-time user pools in tier-2 cities previously served only by donated hospital equipment.
- 3D-Printed Titanium Lattices:Topology-optimized seat pans and backrest components from electron beam melting processes are converging with parametric design software to enable mass-customization at mid-market price points.
- US Veterans Affairs Prosthetic Procurement:VA centralized contracting for adaptive sports equipment is consolidating demand into multi-year framework agreements favoring suppliers with ISO 13485 medical device quality systems.
Industry Challenges
- Biomechanics Specialist Shortage:Certified wheelchair seating and positioning clinicians capable of prescribing camber, center-of-gravity, and frame angle combinations are concentrated in major metropolitan rehabilitation centers, limiting rural and ex-urban fitting quality.
- FDA Predicate Device Pathway Compression:510(k) clearance timelines for novel suspension geometries are extending as the agency narrows acceptable predicate comparisons, delaying commercialization of iterative frame innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Wheelchair Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Powered, Standing, Folding End User: Individuals, Hospitals, Rehabilitation Centers, Nursing Homes Material: Aluminum, Carbon Fiber, Steel, Titanium Technology: Joystick Control, Bluetooth Enabled, Smart Navigation, Adjustable Seating |
| Companies Covered | Invacare, Karman Healthcare, TiLite, Invictus Active, MEYRA, Sunrise Medical, Permobil, Mountain Trike, Ottobock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Wheelchair Market Strategic Shifts & Innovations
Sensor integration and additive manufacturing are dissolving the traditional boundary between manual propulsion and powered assistance, creating hybrid categories that resist conventional segmentation.
Carbon fiber layup automation is converging with robotic fiber placement systems originally developed for aerospace stringers. Tier-one suppliers in Germany and Italy are adopting these platforms to reduce hand-labor content in monocoque frame production. The structural consequence is converging with price compression in premium segments as throughput rises and scrap rates fall below 8%.
EU MDR device classification rules are reclassifying certain powered-assist active wheelchairs from Class I to Class IIa, triggering notified body involvement and clinical evidence requirements previously avoided. Manufacturers with existing ISO 13485 quality systems are absorbing compliance costs more readily than aluminum-frame specialists lacking medical device experience. German and Dutch rehabilitation channels are responding by consolidating supplier lists around MDR-ready portfolios.
Rental and subscription models for high-performance active wheelchairs are emerging in Nordic markets where municipal assistive technology centers face capital budget constraints. Oslo and Copenhagen pilot programs lease titanium racing configurations to adolescent users with growth-related frame size changes, replacing traditional purchase-with-resale cycles. Sports clubs and adaptive recreation programs in Sweden are adopting similar structures for seasonal equipment access.
Active Wheelchair Market Segmentation
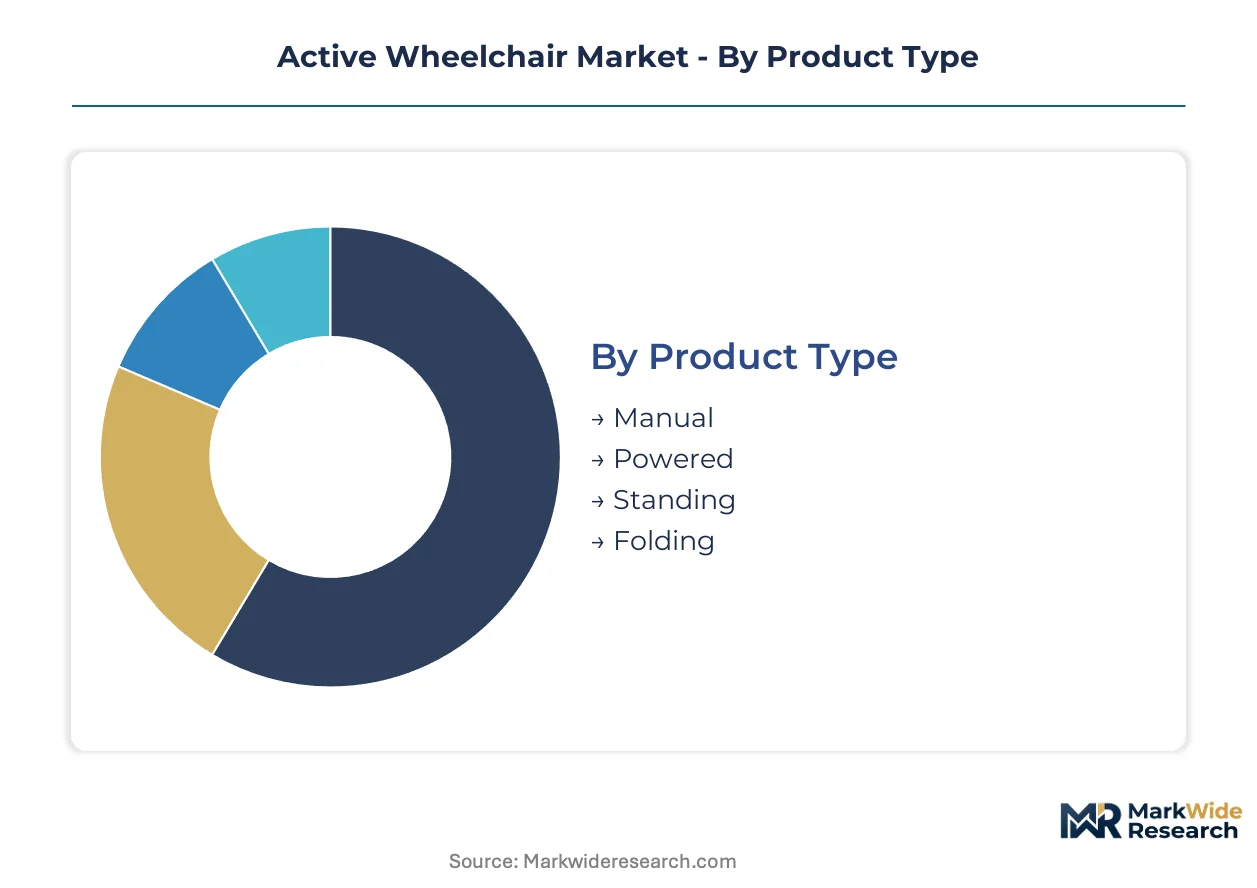
Active wheelchair segmentation reveals how material scarcity and fabrication complexity concentrate margin capture among specialists with captive supply chains. Manufacturers align product architecture with specific user mobility profiles and reimbursement pathways rather than pursuing universal designs.
Product Type:
Supply concentration in titanium and carbon fiber feedstocks favors manufacturers with backward integration into aerospace-grade material sourcing.
- Manual:Ultralight configurations dominate competitive athletics and everyday active mobility, with propulsion efficiency determined by camber angle and center-of-gravity adjustability. Demand concentrates in German and Australian Paralympic feeder programs where replacement cycles accelerate with competitive participation expansion. Aluminum variants serve price-sensitive institutional procurement, while carbon fiber commands premium positioning in racing segments.
- Powered:Joystick-controlled active frames with detachable power-assist modules are climbing the fastest among aging users with progressive neurological conditions who resist full transition to conventional indoor powerchairs. FDA 21 CFR 890 and ISO 7176 certification requirements create divergent testing burdens that favor multinational suppliers with established quality systems.
- Standing:Hydraulic or electric lift mechanisms enable weight-bearing and pressure relief for spinal cord injury users with retained upper-body function.
- Folding:Hinge-frame designs prioritize transportability for intermittent users and travel scenarios where rigid-frame performance is secondary.
Today's leader: Manual. Tomorrow's challenger: Powered.
End User:
Cost tier differentiation separates premium individualized fitting from volume institutional procurement.
- Individuals:Personalized prescription by certified seating clinicians determines frame geometry, with biomechanical optimization concentrated in major metropolitan rehabilitation centers. VA centralized contracting in the United States and Nordic municipal leasing programs are consolidating demand into multi-year framework agreements.
- Hospitals:Acute care discharge planning drives short-term rental and purchase decisions, with procurement favoring durable steel and aluminum configurations over performance-optimized materials.
- Rehabilitation Centers:Outpatient seating clinics in Germany, the Netherlands, and Japan anchor prescription volume for ultralight titanium and carbon fiber platforms.
- Nursing Homes:Long-term care facilities prioritize attendant-propelled and powered options over user-propelled active frames due to staff availability and liability considerations.
Reimbursement concentration in Germany and the United States shapes where premium configurations gain traction fastest.
Material:
Margin pool distribution reflects fabrication complexity and feedstock access rather than volume scale.
- Aluminum:6000-series and 7000-series alloys balance weldability, fatigue resistance, and cost for mid-market institutional procurement. Volume production concentrates in European and North American channels with established rehabilitation infrastructure.
- Carbon Fiber:Automated fiber placement from aerospace-adjacent supply chains is compressing hand-labor content and scrap rates below 8% for monocoque frame production.
- Steel:Chromoly and mild steel variants serve durability-focused institutional procurement and donated equipment programs in emerging markets.
- Titanium:Ti-3Al-2.5V alloy dependence on Russian and Kazakh sponge supply creates availability volatility for ultralight racing and everyday active segments.
Aluminum retains volume leadership. Carbon fiber is gaining share fastest in premium positioning.
Technology:
EU MDR reclassification of powered-assist configurations from Class I to Class IIa is reshaping competitive positioning toward medical device quality systems.
- Joystick Control:Proportional and switched input systems enable independent mobility for users with limited hand function, with FDA predicate device pathways narrowing acceptable comparisons for novel geometries.
- Bluetooth Enabled:Smartphone connectivity for parameter adjustment and usage tracking is expanding among tech-adaptive user segments in Nordic and North American markets.
- Smart Navigation:Sensor-enabled obstacle detection and autonomous routing remain developmental for active wheelchair platforms, with powerchair manufacturers leading integration.
- Adjustable Seating:Modular backrest angles, seat depths, and cushion interfaces accommodate progressive conditions and growth-related changes without full frame replacement.
Joystick control dominates functional adoption. Bluetooth connectivity shows steepest expansion trajectory in user-facing features.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's rehabilitation infrastructure and manufacturing clusters anchor active wheelchair demand and supply concentration. Regional markets diverge sharply based on reimbursement systems, regulatory frameworks, and the maturity of adaptive sports ecosystems.
Germany
Paralympic feeder programs and Ottobock's Duderstadt production cluster sustain ultralight titanium demand. The EU MDR reclassification of powered-assist devices triggers notified body involvement for Class IIa compliance. Baden-Württemberg's seating clinics concentrate prescription volume for carbon fiber racing configurations.
United States
VA centralized contracting consolidates adaptive sports procurement into multi-year framework agreements. FDA 21 CFR 890 standards govern predicate device pathways for novel suspension geometries. The Intermountain West and Pacific Northwest host competitive athletics programs driving replacement cycles for performance-optimized frames.
Japan
Aging demographics with progressive neurological conditions expand powered-assist hybrid adoption. METI industrial standards and PMDA device classification frame certification requirements for joystick-enabled active frames. The Kansai region's rehabilitation hospitals anchor prescription volume for adjustable seating systems.
Australia
Adaptive athletics programs in Victoria and New South Wales create sustained demand for ultralight racing configurations. The TGA medical device framework governs market access for imported titanium and carbon fiber platforms. Brisbane's Paralympic training facilities concentrate competitive user pools with accelerated replacement cycles.
India
Central government disability pension expansion and state-level assistive device schemes create first-time user pools in tier-2 cities. CDSCO medical device regulations increasingly frame import requirements for powered configurations. Tamil Nadu and Karnataka rehabilitation infrastructure supports premium product uptake in metropolitan corridors.
Active Wheelchair Market Key Industry Players
Global majors compete with regional champions across material specialization and certification breadth. The market structures around three tiers: vertically integrated titanium specialists, diversified aluminum-carbon fiber portfolios, and emerging powered-assist hybrid developers. Strategic moves concentrate on M&A for captive material access and geographic expansion into reimbursement-rich rehabilitation channels.
Among German fabricators, Ottobock GmbH and MEYRA anchor the premium-tier vector through rehabilitation channel dominance and ISO 13485 quality systems. TiLite exemplifies the ultralight specialist archetype through titanium supply chain positioning. Sunrise Medical occupies a diversified portfolio position spanning European and North American institutional procurement.
| Leading Market Players |
|---|
| Invacare |
| Karman Healthcare |
| TiLite |
| Invictus Active |
| MEYRA |
| Sunrise Medical |
| Permobil |
| Mountain Trike |
| Ottobock |
| Others |
Cost & Logistics Intelligence
Automated fiber placement systems migrating from aerospace manufacturing are compressing hand-labor content in carbon fiber monocoque frames while concentrating production among German and Italian tier-one suppliers with capital access for robotic platforms. This technology transition simultaneously reduces scrap rates below 8% and widens the cost-performance gap between captive aerospace-adjacent supply chains and mid-tier aluminum fabricators lacking comparable automation.
Pricing Analysis
Input-cost pass-through from titanium sponge volatility and REACH-compliant coating conversions is intensifying margin pressure across mid-market manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified MDR-ready portfolios from aluminum-frame institutional procurement and donated equipment programs. Price differentiation hinges on certification tier and customization depth, with VA framework agreements and Nordic municipal leasing programs showing lowest price sensitivity. Cost compression in titanium-dependent ultralight segments is accelerating due to Russian and Kazakh export licensing volatility.
Supply Chain Analysis
Freight cost escalation and container availability constraints are amplifying landed cost differentials between German production clusters and Asian assembly points for powered-assist modules. Feedstock dependence draws from Russian and Kazakh titanium sponge, Japanese carbon fiber precursors, and German automotive-grade aluminum extrusions. Single-source vulnerability in Ti-3Al-2.5V alloy supply creates exposure to export licensing disruptions. Distribution runs through rehabilitation channel specialists in Germany, VA centralized contracting in the United States, and emerging state-level procurement schemes in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The active wheelchair market functions as a regulatory compounder where EU MDR reclassification of powered-assist devices from Class I to Class IIa is accelerating demand consolidation around ISO 13485 quality systems.
For Market Incumbents: Hedge against titanium feedstock volatility through backward integration into aerospace-grade material sourcing or long-term offtake agreements with Kazakh producers. Defensive positioning requires MDR certification investment and channel control in German rehabilitation infrastructure to offset margin compression from aluminum-frame competitors. For New Entrants and Emerging Players: EU MDR in Europe opens a window for powered-assist hybrid configurations among aging users with progressive neurological conditions who resist full powerchair transition. White-space targets include Indian tier-2 cities with expanding disability pension coverage and 3D-printed titanium lattice components for mass-customization at mid-market price points. Go-to-market leverage should emphasize VA framework agreement eligibility and ISO 13485 quality system development. For Investors and Strategic Acquirers: Valuations sit cheapest among aluminum-frame specialists lacking medical device experience but holding established institutional procurement relationships. Long-term viability favors targets with captive carbon fiber or titanium supply chains and MDR-ready powered-assist portfolios. The signal to watch is consolidation velocity in German rehabilitation channels as notified body involvement raises compliance barriers.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Pathway | Class IIa reclassification triggers notified body involvement and clinical evidence requirements for powered-assist devices. |
| Titanium Supply Agreement | Long-term offtake contracts with Kazakh sponge producers hedge against export licensing volatility for ultralight frame manufacturing. |
| Rehabilitation Channel Partnership | Baden-Württemberg seating clinic alliances concentrate prescription volume for carbon fiber racing configurations. |
| 3D-Printed Component Development | Electron beam melting processes enable topology-optimized seat pans at mid-market price points through parametric design software. |
| VA Framework Agreement Eligibility | ISO 13485 quality system compliance qualifies suppliers for multi-year adaptive sports equipment procurement consolidation. |
Research Approach
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with certified seating clinicians, rehabilitation center procurement directors, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, ISO 7176 certification registries, CMS Medicare durable medical equipment data, and EU MDR notified body documentation. Triangulation between patient-level prescription patterns and manufacturer production disclosures ensures consistency across volume and value estimates.
Historical trendline analysis of replacement cycles, competitive participation rates, and reimbursement policy shifts anchored the projection framework across the analysis window. Segmentation dimensions modeled include product architecture, material grade tier, end-user setting, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating Paralympic program expansion, aging demographics with progressive conditions, and certification requirement evolution. Industry-specific forecast inputs encompass titanium sponge availability indices and VA procurement cycle timing.
Revisions become necessary when titanium export licensing regimes shift, MDR implementation timelines accelerate, or alternative standing powerchair technologies displace manual active frame demand. Forecasts reflect documented assumptions regarding rehabilitation infrastructure development rates and competitive participation growth trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Ventilator Market
Medical Devices
Russia Massage Equipment Market
Medical Devices
Capsulotomy Market
Medical Devices
Face Mask Device Market
Medical Devices
Electrical Stimulation Devices (Esds) Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
Global Vascular Access Devices Market
Medical Devices
Disposable Medicine Measuring Cups Market
Medical Devices
Electrosurgery Devices Market
Medical Devices
North America General Surgical Devices Market
Medical Devices
Thrombectomy System Market
Medical Devices
Wrist Fixator Procedure Kit Market
Medical Devices
Electronic Skin Patch Market
Medical Devices
Lacrimal Duct Stent Tube Market
Medical Devices
Chest Drainage Devices Market
Medical Devices
Invisible Orthodontics Market