
 Global Hospital Equipment and Supplies Market | 2026-2036
Global Hospital Equipment and Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hospital Equipment and Supplies Market Foresight
China's medical device manufacturing base is tilting toward domestic substitution for high-end imaging modalities. GE Healthcare leverages its established service networks to sustain installed-base loyalty across tier-one hospitals. Medtronic anchors its position through deep catheter and cardiac rhythm portfolios. Becton, Dickinson and Company differentiates via integrated medication management systems spanning safety-engineered devices.
Hospital equipment and supplies encompass electromechanical diagnostic apparatus, precision surgical tools, continuous physiological monitors, thermal and chemical sterilization systems, and assisted locomotion devices engineered to ISO 13485 quality management standards with biocompatibility testing per ISO 10993. These products serve acute intervention, chronic disease management, and perioperative care workflows across institutional settings. Diagnostic imaging devices command the largest revenue pool among product types, though patient monitoring systems register the fastest structural expansion driven by ICU digitization and step-down unit proliferation. Ambulatory surgical facilities represent an ascendant end-user channel as same-day procedures migrate from inpatient settings, while tender procurement channels concentrate volume for public hospital systems.
The FDA's 510(k) clearance framework and the EU MDR's clinical evidence requirements shape product development timelines and market access costs for manufacturers targeting the United States and European Union. China's NMPA innovation approval pathways and India's CDSCO quality control orders for notified medical devices are recalibrating Asia-Pacific competitive dynamics. Stakeholders must monitor regulatory divergence between major jurisdictions as a determinant of portfolio prioritization and localization investments.
Market Dynamics
EU MDR clinical evidence requirements and FDA 510(k) pathway updates are compressing product development cycles while forcing manufacturers to retire legacy SKUs faster than planned obsolescence schedules intended.
Growth Catalysts
- ICU Digitization Mandates:Tertiary hospitals across India and Brazil are procuring integrated monitoring suites to meet new accreditation standards for critical care units.
- County-Level Medical Center Upgrades:China's NMPA innovation approval pathways are accelerating domestic substitution for high-end imaging modalities in previously import-dependent facilities.
- Ambulatory Surgical Migration:Same-day procedure volumes are shifting from inpatient settings to standalone surgical centers, creating demand for compact sterilization and anesthesia equipment.
Market Restraints
- Semiconductor Component Volatility:Patient monitoring systems and imaging modalities face input cost instability from concentrated foundry capacity in Taiwan and South Korea.
- EU MDR Transition Friction:Notified body capacity constraints are extending certification timelines for Class IIb and III devices, freezing portfolio refresh investments.
- Reprocessed Single-Use Device Substitution:FDA-cleared third-party reprocessors are capturing share in cardiac catheters and orthopedic blades, compressing OEM replacement revenue.
Strategic Opportunities
- India's Hospital Infrastructure Build-Out:CDSCO quality control orders for notified medical devices are creating first-mover advantages for manufacturers establishing local testing partnerships.
- AI-Enabled Predictive Maintenance:Convergence of edge computing and vibration sensing is hybridizing service contracts toward uptime guarantees rather than scheduled PM visits.
- Direct-to-Hospital E-Procurement Platforms:Consolidated purchasing consortia in Germany and France are bypassing traditional distributor markups for commodity consumables.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993-18 chemical characterization requirements are extending material qualification timelines for polymer-intensive device categories.
- Legacy System Integration Complexity:New monitoring platforms must interface with 15-20 year-old patient data architectures without disrupting accreditation-dependent workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hospital Equipment and Supplies Market |
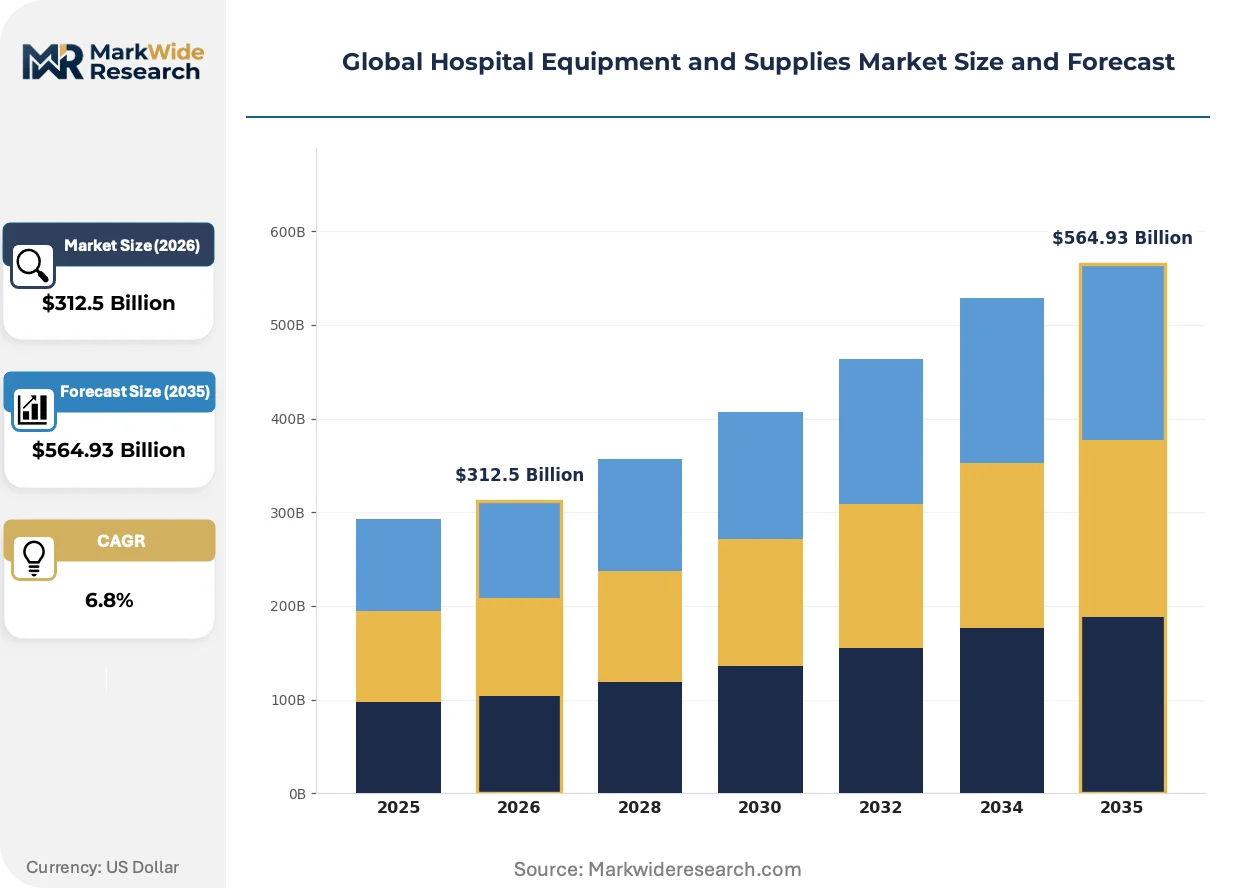
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $564.93 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Imaging Devices, Surgical Instruments, Patient Monitoring Systems, Sterilization Equipment, Mobility Aids Application: Emergency Care, Intensive Care, Outpatient Services, General Surgery, Rehabilitation End User: Medical Centers, Ambulatory Surgical Facilities, Specialized Clinics, Diagnostic Labs, Home Healthcare Providers Distribution Channel: Direct Sales, E-commerce Platforms, Wholesale Distributors, Medical Equipment Dealers, Tender Procurement |
| Companies Covered | GE Healthcare, Cardinal Health, Medtronic, Johnson & Johnson, Becton, Dickinson and Company, Stryker Corporation, B. Braun, 3M Company, Baxter International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hospital Equipment and Supplies Market Shifts & Advancements
Continuous physiological monitoring is migrating from bedside tethered units toward wearable patch formats, while sterilization modalities are converging on low-temperature hydrogen peroxide systems to accommodate heat-sensitive endoscopes and robotic instruments.
Sensor fusion architectures combining photoplethysmography, accelerometry, and bioimpedance spectroscopy are hybridizing patient monitoring into single-patch platforms capable of multi-parameter telemetry. Step-down units in US health systems are piloting these formats to reduce nurse rounding burden. The structural consequence is compression of dedicated single-purpose monitor SKUs into consolidated platform contracts.
EU MDR Article 10 clinical evidence requirements are forcing manufacturers to retire predicate-device reliance strategies that sustained 510(k) clearances for decades. Class III implantable manufacturers face particular pressure to generate prospective data rather than equivalence arguments. Cardiac rhythm management and orthopedic joint categories are responding with post-market registry investments to satisfy notified body scrutiny.
Hospital procurement consortia are consolidating vendor panels around integrated medication management ecosystems rather than discrete device categories. Safety-engineered syringes, smart infusion pumps, and barcode verification systems are being bundled under single-source agreements with penalty clauses for interoperability failures. This pattern is most visible in National Health Service England tender structures and emerging German hospital alliance frameworks.
Global Hospital Equipment and Supplies Market Segmentation
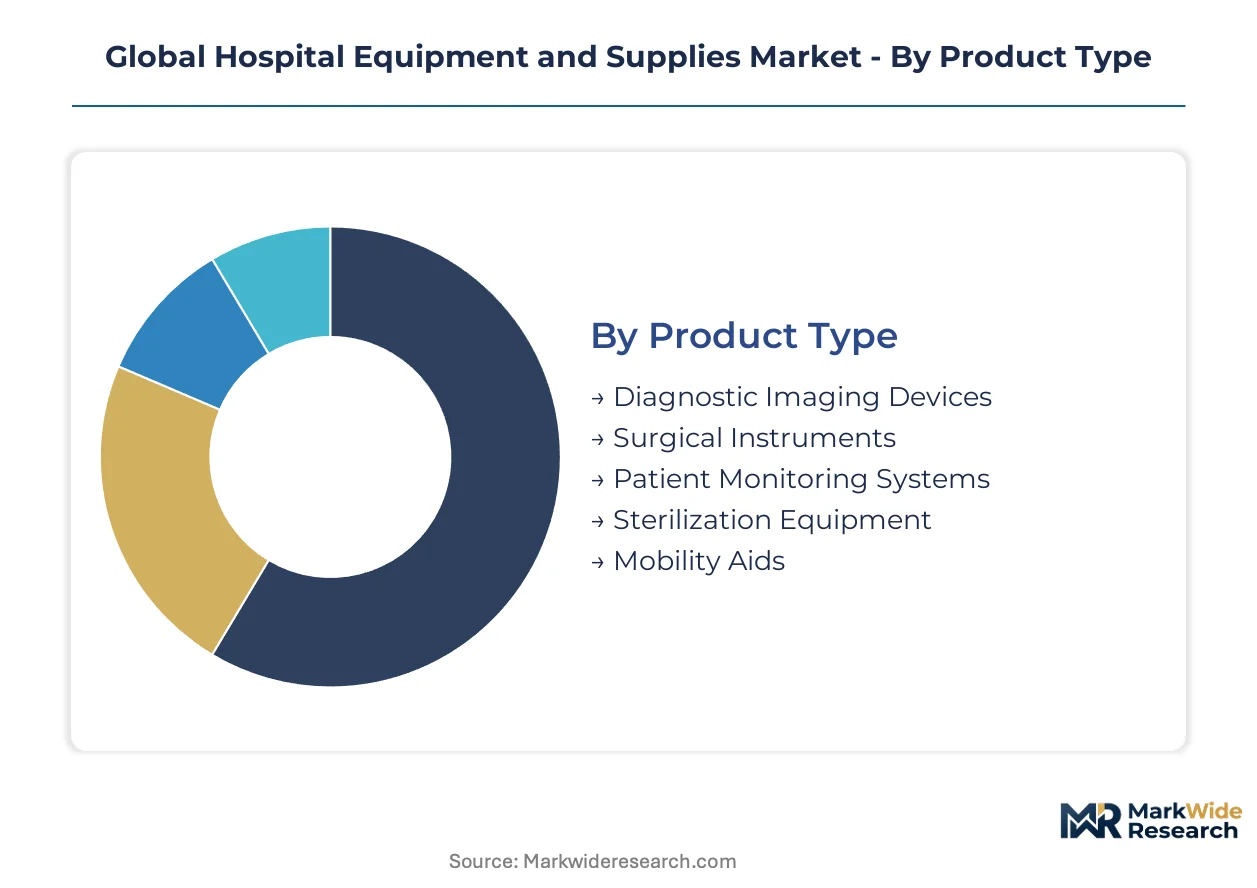
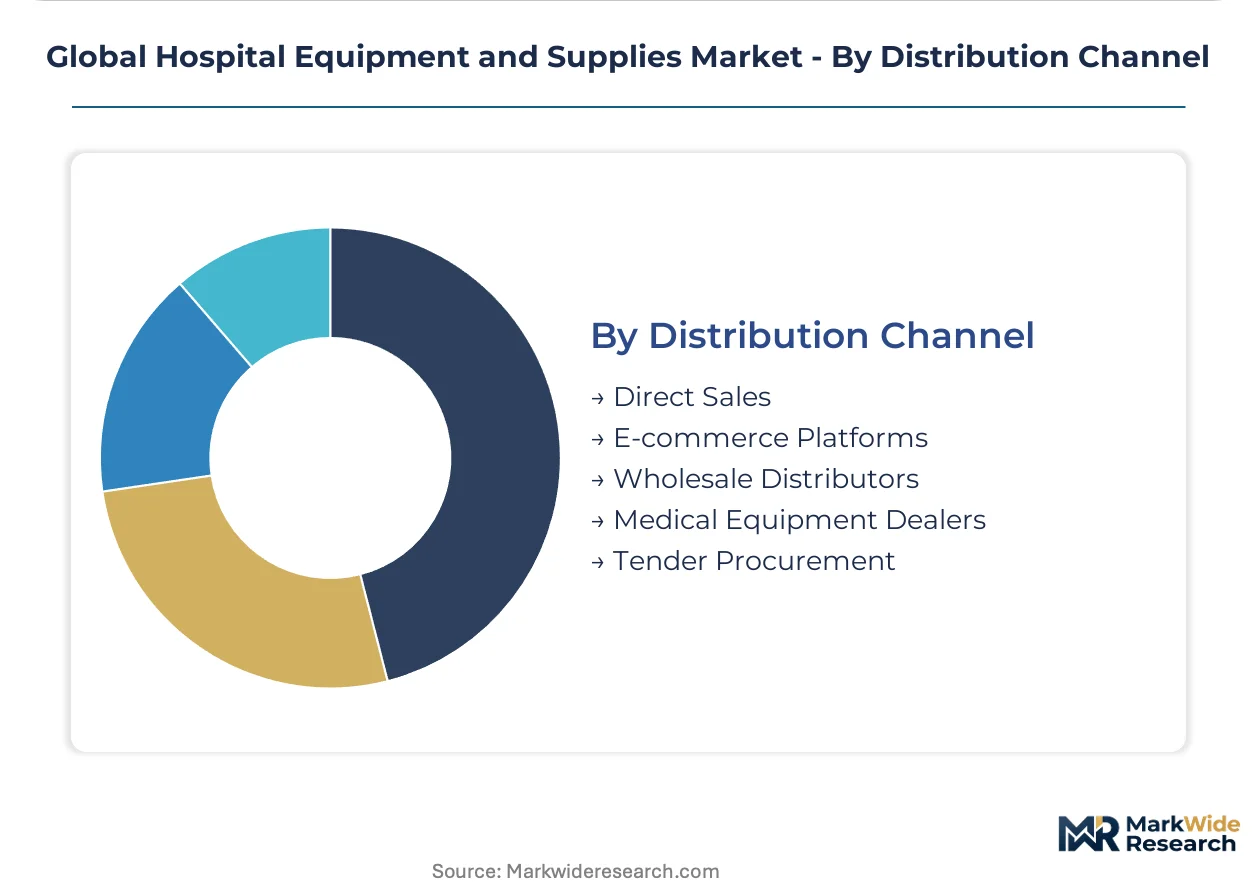
Segmentation in hospital equipment and supplies reveals how procurement authority, clinical setting, and regulatory pathway reshape vendor access. Manufacturers must align product portfolios against distinct buying centers rather than treating hospitals as monolithic customers.
Product Type:
Mature modalities dominate capital allocation cycles while emerging formats exploit gaps in legacy infrastructure.
- Diagnostic Imaging Devices:Magnetic resonance, computed tomography, and ultrasound systems engineered to IEC 60601-1-2 electromagnetic compatibility standards. Demand concentrates in China's county-level medical centers upgrading from analog radiography under NMPA innovation pathways.
- Patient Monitoring Systems:Multi-parameter bedside units and wearable patch formats integrating photoplethysmography with accelerometry. ICU digitization mandates in India and Brazil are accelerating integrated suite procurement for tertiary accreditation compliance.
- Surgical Instruments:Precision cutting, grasping, and retracting tools manufactured to ISO 13485 quality management with biocompatibility validation per ISO 10993.
- Sterilization Equipment:Steam autoclaves and low-temperature hydrogen peroxide systems accommodating heat-sensitive endoscopes and robotic instruments.
- Mobility Aids:Powered wheelchairs, patient lifts, and ambulatory assistance devices serving perioperative and rehabilitation workflows.
Diagnostic imaging devices handle the majority of throughput; patient monitoring systems are expanding most quickly on share.
Application:
Acute intervention settings command premium pricing while ambulatory migration reconfigures equipment form factors.
- Intensive Care:Continuous physiological monitoring, mechanical ventilation, and infusion management for hemodynamically unstable patients. Step-down unit proliferation in US health systems is driving demand for compact multi-parameter platforms.
- Emergency Care:Resuscitation equipment, point-of-care diagnostics, and trauma stabilization systems requiring rapid deployment protocols.
- General Surgery:Operating tables, surgical lighting, and electrosurgical generators supporting open and minimally invasive procedures.
- Outpatient Services:Diagnostic examination tools and minor procedure equipment optimized for high patient throughput.
- Rehabilitation:Therapeutic exercise systems and functional assessment devices for post-acute recovery protocols.
Intensive care absorbs the largest equipment investment per bed; emergency care is climbing the fastest as pre-hospital networks expand.
End User:
Institutional scale determines service contract structures and regulatory scrutiny intensity.
- Medical Centers:Tertiary hospitals with comprehensive service lines requiring integrated device ecosystems and 24/7 technical support. India's hospital infrastructure build-out under CDSCO quality control orders is creating procurement volume concentration.
- Ambulatory Surgical Facilities:Standalone same-day procedure centers demanding compact anesthesia and sterilization equipment with rapid turnover capability.
- Specialized Clinics:Cardiology, orthopedics, and oncology focused practices with modality-specific equipment needs.
- Diagnostic Labs:Imaging and laboratory testing facilities operating under distinct accreditation frameworks from acute care settings.
- Home Healthcare Providers:Portable monitoring and therapeutic devices for post-discharge chronic disease management.
Medical centers maintain the deepest vendor relationships; ambulatory surgical facilities are gaining share fastest as procedure migration accelerates.
Distribution Channel:
Channel selection reflects product complexity, procurement scale, and regulatory documentation requirements.
- Tender Procurement:Public hospital systems in Germany, France, and India consolidating volume through competitive bidding with interoperability penalty clauses. NHS England structures increasingly bundle medication management ecosystems under single-source agreements.
- Direct Sales:Capital equipment manufacturers maintaining field service organizations for installation, training, and maintenance of imaging and monitoring platforms.
- Wholesale Distributors:Regional inventory buffers for consumables and replacement parts serving mid-tier hospital networks.
- Medical Equipment Dealers:Localized sales and service coverage for secondary cities and rural facilities.
- E-commerce Platforms:Direct-to-hospital procurement consortia in Germany and France bypassing traditional distributor markups for commodity consumables.
Tender procurement channels handle the greatest absolute volume; e-commerce platforms are expanding most rapidly as purchasing consortia consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for semiconductor components concentrates in Taiwan and South Korea, creating input cost volatility that ripples through patient monitoring and imaging modality supply chains. Procurement patterns diverge sharply across regulatory jurisdictions, with EU MDR transition friction freezing investments in some markets while NMPA innovation pathways accelerate domestic substitution in others.
United States
ICU digitization mandates and step-down unit proliferation drive integrated monitoring suite procurement across tertiary health systems. FDA's updated 510(k) pathway requirements compress product development timelines while accelerating legacy SKU retirements. The Greater Boston and Minneapolis-St. Paul clusters anchor cardiac rhythm management and surgical instrument manufacturing respectively.
China
County-level medical center upgrades generate demand for high-end imaging modalities previously dependent on imports. NMPA innovation approval pathways enable domestic manufacturers to substitute foreign equipment in tier-two and tier-three cities. The Yangtze River Delta manufacturing base around Shanghai tilts production toward domestic substitution for MRI and CT systems.
Germany
Hospital procurement consortia consolidate vendor panels around integrated medication management ecosystems under single-source agreements. EU MDR notified body capacity constraints extend certification timelines for Class IIb and III devices. The Baden-Württemberg industrial corridor sustains precision surgical instrument and sterilization equipment manufacturing clusters.
India
Tertiary care hospital expansion under infrastructure build-out programs creates procurement volume for advanced monitoring systems. CDSCO quality control orders for notified medical devices establish compliance barriers favoring manufacturers with local testing partnerships. The Maharashtra-Gujarat pharmaceutical and medical device corridor concentrates domestic assembly and import distribution operations.
Brazil
Critical care unit accreditation standards drive integrated monitoring suite adoption across tertiary hospitals in São Paulo and Rio de Janeiro. ANVISA regulatory harmonization with FDA and EU MDR standards elevates documentation requirements for imported devices. The São Paulo metropolitan area anchors Latin American distribution and technical service operations for multinational manufacturers.
Global Hospital Equipment and Supplies Market Competitive Landscape
Diversified conglomerates and specialized device manufacturers split the market across capital equipment and consumable categories. Tier-one imaging and monitoring platforms command premium pricing through integrated service contracts, while commodity consumables face margin compression from reprocessors and purchasing consortia. Strategic archetypes span installed-base service anchors, safety-engineered portfolio bundlers, and regional compliance specialists. Competitive moves concentrate on M&A for technology gaps and backward integration into critical component supply.
Among diversified health technology conglomerates, GE Healthcare and Medtronic occupy positions spanning imaging modalities and cardiac rhythm portfolios respectively. Becton, Dickinson and Company exemplifies the safety-engineered portfolio archetype through integrated medication management ecosystems. These three entities represent distinct competitive vectors: installed-base service loyalty, deep catheter specialization, and compliance-driven bundling under single-source agreements.
| Leading Market Players |
|---|
| GE Healthcare |
| Cardinal Health |
| Medtronic |
| Johnson & Johnson |
| Becton, Dickinson and Company |
| Stryker Corporation |
| B. Braun |
| 3M Company |
| Baxter International |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor's container rate volatility cascades through semiconductor-intensive device categories, amplifying price spreads between ISO 13485-certified premium tiers and economy-grade alternatives while compressing margins for manufacturers lacking captive component sourcing.
Pricing Analysis
EU MDR dictates the pricing tier structure across the Global Hospital Equipment and Supplies Market, separating CE-marked Class III implantables from unbundled commodity consumables. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Cost compression in patient monitoring systems intensifies because foundry capacity constraints elevate sensor module costs. Ambulatory surgical facilities exhibit highest price sensitivity; tertiary medical centers with GPO contracts show lowest.
Supply Chain Analysis
Foundry concentration at TSMC and Samsung Electronics in Taiwan and South Korea anchors semiconductor supply for imaging modalities and monitoring platforms. Raw material dependencies span rare earth magnets for MRI systems, polymer resins for disposable devices, and specialized glass for endoscope optics. Single-source vulnerability in Taiwan Strait logistics threatens just-in-time delivery schedules for ICU digitization projects. Distribution runs through hospital procurement consortia in Germany and France alongside tender channels for India's public hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the Global Hospital Equipment and Supplies Market creates entry niches as procurement authority shifts from monolithic hospital systems toward specialized ambulatory networks and purchasing consortia.
For Market Incumbents: Pre-empt reprocessor encroachment in cardiac catheter and orthopedic blade categories by embedding safety-engineered features that resist third-party sterilization validation. Deepen backward integration into sensor module production to offset Taiwan foundry pricing power. Lock in tier-one hospital loyalty through predictive maintenance service contracts with uptime guarantees.
For New Entrants and Emerging Players: Build out localized testing partnerships under India's CDSCO quality control orders to capture first-mover accreditation before multinational competitors establish compliance infrastructure. Target county-level medical centers in China's tier-two cities where NMPA innovation pathways favor domestic substitution. Deploy direct-to-hospital e-procurement platforms to bypass distributor markups in consolidated German and French purchasing consortia.
For Investors and Strategic Acquirers: Regional compliance specialists with EU MDR technical documentation capabilities and FDA 510(k) predicate strategies represent priority acquisition targets as certification timelines extend. Long-term viability hinges on post-market registry investments for Class III devices rather than equivalence-based clearances. Watch notified body capacity expansion announcements as inflection indicators for portfolio refresh investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates market access for Class IIb and III devices amid notified body capacity constraints. |
| Hospital System Partnership | Secures integrated medication management ecosystem contracts with interoperability penalty clauses under NHS England structures. |
| Software Companion Development | Enables AI-enabled predictive maintenance contracts replacing scheduled PM visits with uptime guarantees. |
| Reimbursement Strategy | Aligns device pricing with DRG categories and value-based care metrics in US health systems. |
| CE Marking Pathway | Opens tender procurement channels across German and French hospital consortia consolidating vendor panels. |
Research Methodology
A spread of perspectives from hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs directors converged on the working assumptions underlying this analysis. Primary fieldwork with clinicians and purchasing committees combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up equipment shipment tracking and top-down healthcare expenditure triangulation anchored volume estimates.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation modeling incorporated product type, application setting, end-user scale, and distribution channel complexity. CAGRs derived from equipment replacement cycles, regulatory transition timelines, and infrastructure build-out program commitments. Forecast inputs included ICU digitization mandate compliance schedules and NMPA innovation approval pathway throughput rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by domestic Chinese imaging manufacturers or third-party device reprocessors would shift outcomes beyond modeled ranges. Quarterly review of notified body capacity expansion, foundry utilization rates, and tender award volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Electric Bed Market
Medical Equipment
Marijuana Drying and Curing Equipment Market
Medical Equipment
Medical Ultrasonic Baths Market
Medical Equipment
X-Ray Machine Manufacturing Market
Medical Equipment
Global Bone Densitometer Market
Medical Equipment
Floor-Standing Platelet Agitator Market
Medical Equipment
Asia-Pacific Nuclear Medicine Equipment Market
Medical Equipment
US Radiotherapy Market
Medical Equipment
Fluoroscopy Equipment Market
Medical Equipment
Medication Pouch Inspection Systems Market
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Medical Ethylene Oxide Sterilization Equipment Market
Medical Equipment
Contact Lens Inspection Equipment Market
Medical Equipment
Forensic Equipment and Supplies Market
Medical Equipment
Operating Light Market