
 US Corrugated and Folding Boxboard Market | 2026-2036
US Corrugated and Folding Boxboard Market Size, Share, and Industry Trends Forecast 2026-2036
US Corrugated and Folding Boxboard Market Analysis
E-commerce fulfillment channels are rewriting procurement patterns across the US corrugated supply base. Smurfit WestRock leverages its integrated mill-to-box network to control fiber supply across the Midwest and Southeast. International Paper Company anchors national volume through its extensive containerboard mill footprint. Packaging Corporation of America competes aggressively on short-run customizability for regional consumer brands.
US corrugated and folding boxboard comprises paper-based packaging materials manufactured from fluted corrugated sheets and flat linerboards, typically constructed from kraft pulp with recycled fiber percentages ranging from 35% to 100% depending on grade and end-use requirements. These materials primarily serve to protect goods during distribution while providing printable surfaces for brand communication and regulatory labeling. Single-Wall and Double-Wall product types dominate current tonnage as established workhorses for retail packaging and shipping containers, while Folding Boxboard captures premium margin pools in pharmaceuticals and personal care where print fidelity and structural rigidity command higher unit values. Protective Packaging applications are expanding fastest as electronics manufacturers demand anti-static and shock-absorbing configurations for direct-to-consumer shipment.
The EPA enforces emissions standards at pulp and paper mills that shape capital allocation toward cleaner combustion and wastewater recovery systems, while OSHA mandates govern machine guarding and dust control on corrugator lines. State-level extended producer responsibility frameworks in California and Oregon are beginning to impose post-consumer recycled content floors that filter back to board specifications. FDA food-contact regulations under 21 CFR 176.170 constrain coating and adhesive chemistries for food and beverage applications. Stakeholders must monitor how fragmented state environmental rules consolidate into de facto national standards that could reshape mill economics and converter sourcing territories.
Market Dynamics
State-level recycled content mandates from California and Oregon are forcing converters to re-engineer board specifications faster than mill R&D cycles can accommodate, compressing the window between regulatory announcement and commercial compliance.
Growth Catalysts
- E-commerce fulfillment networks:Direct-to-consumer shipment volumes are pulling demand for protective shipping formats across electronics and personal care verticals. Amazon, Target, and Walmart distribution centers now specify crush-resistant double-wall constructions for last-mile durability.
- Extended Producer Responsibility frameworks:California's SB 54 and Oregon's Plastic Pollution and Recycling Modernization Act impose post-consumer recycled content floors that filter back to folding boxboard specifications for pharmaceuticals and cosmetics.
- Lighter-weight high-strength constructions:Advanced fluting profiles and micro-fibrillated cellulose additives enable source reduction without performance loss, satisfying brand sustainability scorecards while cutting fiber costs.
Market Restraints
- Old corrugated container price volatility:OCC spot markets swing 40-60% annually, shredding converter margin predictability and forcing hedging costs that smaller players cannot absorb.
- Containerboard mill concentration:Four integrated producers control 70% of US kraft linerboard capacity, creating supply vulnerability when unplanned downtime occurs at Gulf Coast or Pacific Northwest mills.
- Plastic substitution in moisture barrier applications:Polyethylene-coated folding cartons and flexible pouches retain cost advantages for frozen food and wet-grocery segments where fiberboard faces grease penetration limits.
Strategic Opportunities
- Pharmaceutical cold chain expansion:Insulin and biologics distribution is creating demand for insulated corrugated shippers with phase-change material integration, a white space beyond standard ambient shipping.
- Digital print convergence with structural design:HP Indigo and EFI Nozomi presses enable run-of-one customization with 3D pop-up features, collapsing minimum order quantities for regional craft spirits and limited-edition cosmetics.
- US Southeast mill belt proximity:Georgia and Alabama containerboard capacity expansions position converters within 300 miles of major e-commerce fulfillment nodes, compressing drayage costs and delivery windows.
Industry Challenges
- Corrugator operator skill shortages:Experienced machine tenders with warp control and glue line calibration expertise are retiring faster than technical training programs at community colleges can replenish.
- Food-contact certification timelines:FDA 21 CFR 176.170 compliance for new barrier coatings requires 18-24 month migration testing cycles, delaying commercialization of mineral oil-free alternatives.
- Legacy enterprise resource planning integration:Converter scheduling systems from the 1990s cannot ingest real-time e-commerce order streams, forcing manual workarounds that inflate administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Corrugated and Folding Boxboard Market |
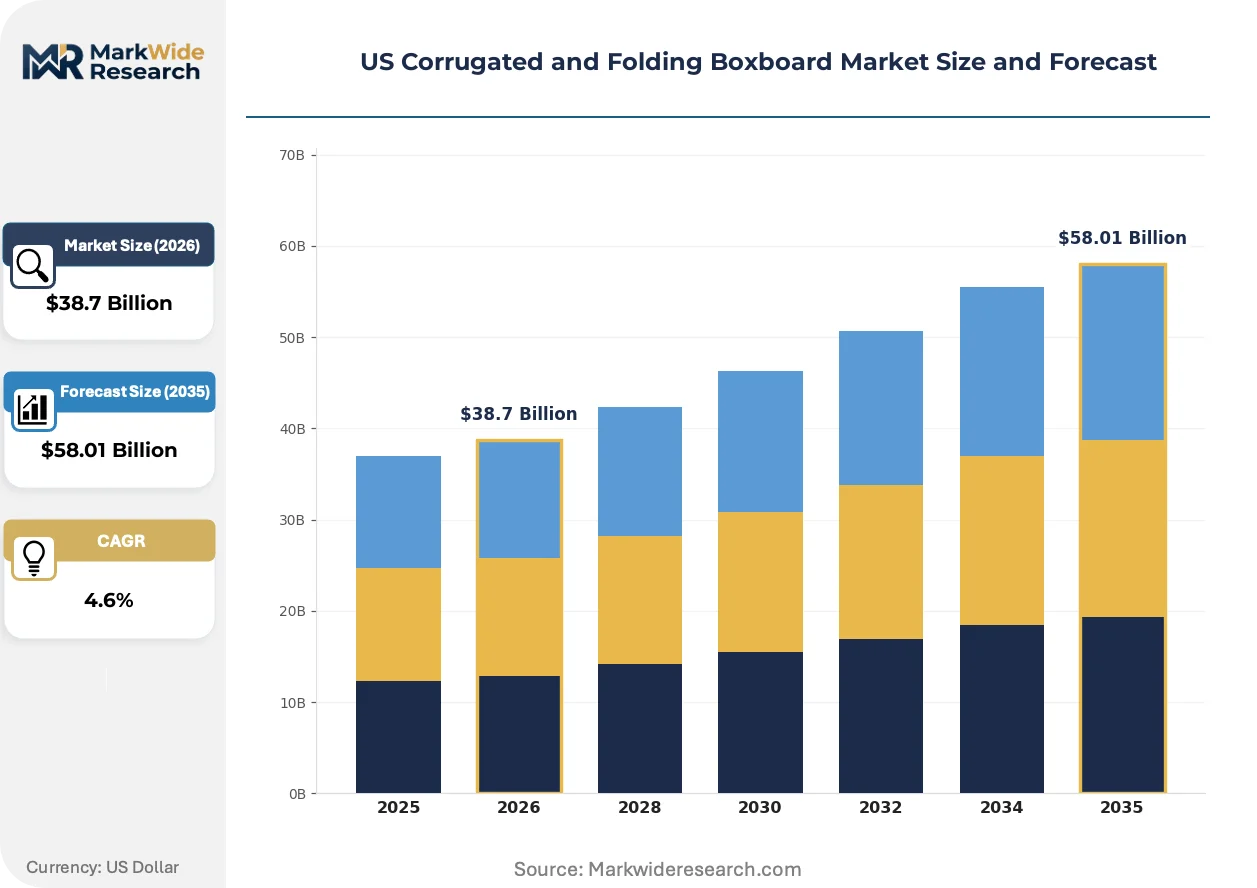
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Wall, Double-Wall, Triple-Wall, Folding Boxboard End User: Food & Beverage, Pharmaceuticals, Electronics, Personal Care Manufacturing Stage: Raw Material Processing, Printing, Assembly, Packaging Application: Retail Packaging, Shipping Containers, Protective Packaging, Storage Solutions |
| Companies Covered | Smurfit WestRock, International Paper Company, Packaging Corporation of America, Graphic Packaging International, Sonoco Products Company, Georgia-Pacific LLC, WestRock Company, DS Smith Plc, U.S. Corrugated Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Corrugated and Folding Boxboard Market Emerging Trajectories
Digital manufacturing workflows and bio-based barrier technologies are collapsing traditional boundaries between commodity board production and specialty packaging performance, enabling mass customization at scale economics previously reserved for long runs.
Nano-cellulose reinforcement additives are collapsing the strength-to-weight ratio gap between virgin kraft and recycled fiber constructions. Beverage multipack and electronics OEM buyers are specifying these formulations for source reduction credits. The technology is collapsing virgin fiber dependence in premium folding boxboard grades that previously required fresh pulp.
EPA effluent limitation guidelines for pulp and paper mills are tightening biochemical oxygen demand and color discharge standards. Capital allocation is shifting toward anaerobic digester installations and closed-loop cooling systems. Integrated producers in the Great Lakes corridor face the steepest retrofit timelines due to aging wastewater infrastructure and stricter Great Lakes Water Quality Agreement protocols.
Brand procurement teams are consolidating supplier panels and demanding vendor-managed inventory programs with point-of-use replenishment. Regional consumer packaged goods companies are replacing spot-buying with multi-year fiberboard supply agreements indexed to OCC futures. The shift is most visible in Midwest food manufacturing clusters where just-in-time packaging lines cannot tolerate stockout risk.
US Corrugated and Folding Boxboard Market Segmentation
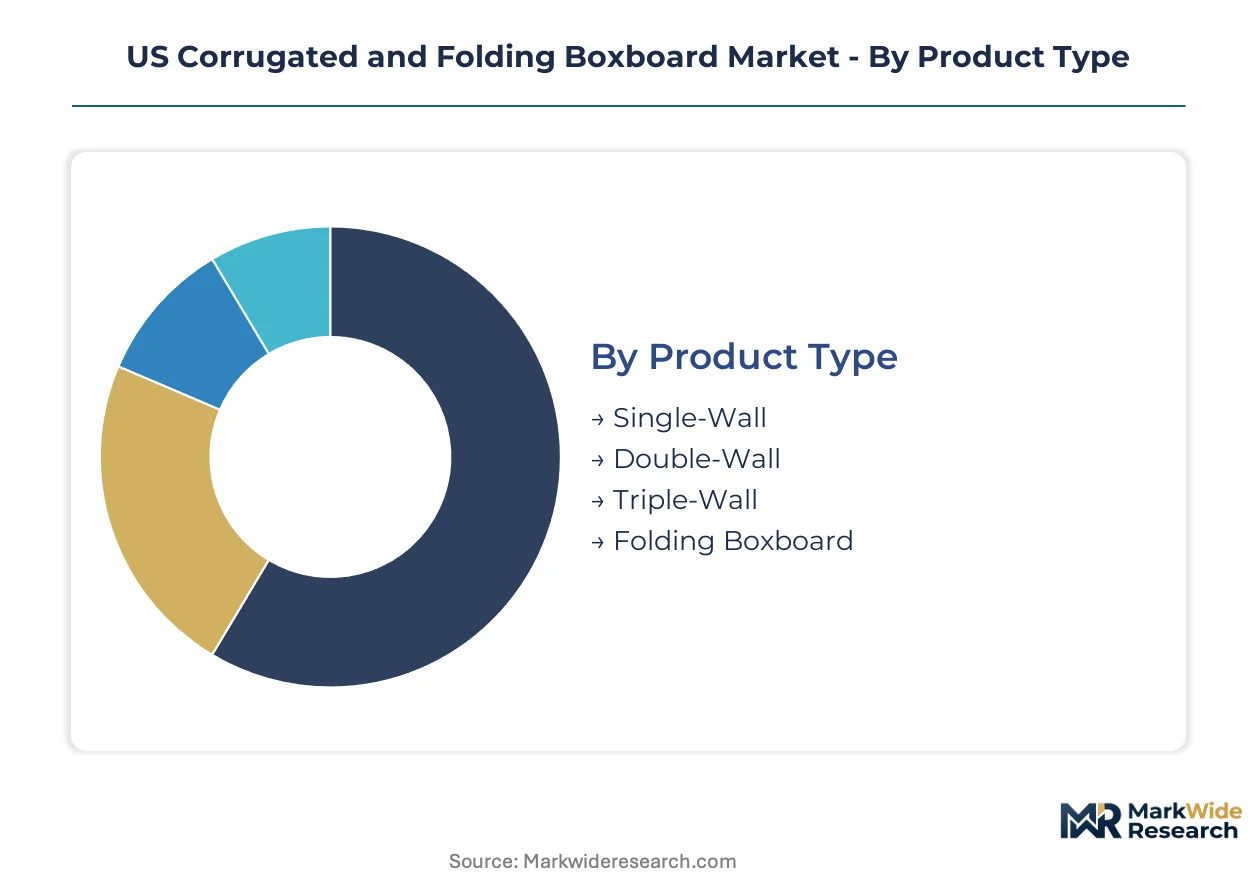
US corrugated and folding boxboard procurement patterns diverge sharply across product construction, end-use performance requirements, and supply chain position. Converters must align mill specifications with the durability, print fidelity, and barrier properties each downstream application demands.
Product Type:
Cost tier stratification separates commodity shipping grades from premium folding boxboard constructions where fiber quality and surface finish command price premiums.
- Single-Wall:One fluted medium sandwiched between two linerboards provides baseline crush resistance for lightweight consumer goods. Amazon fulfillment centers in the Great Lakes corridor specify this grade for apparel and soft-goods shipment where dimensional stability matters less than cube efficiency.
- Double-Wall:Two fluted layers bonded between three linerboards deliver stack strength for heavier electronics and beverage multipacks. Target and Walmart distribution nodes in the Southeast require this construction for last-mile durability against conveyor system impacts.
- Triple-Wall:Heavy-duty industrial bulk bins and export crating for machinery components.
- Folding Boxboard:Solid bleached sulfate and coated unbleached kraft grades for pharmaceutical inserts and cosmetic cartons demanding offset lithography reproduction.
Single-Wall holds installed capacity. Folding Boxboard is rotating up the share rankings.
End User:
Application intensity varies by sector—food manufacturing drives volume, while pharmaceuticals and electronics extract premium pricing for certified performance.
- Food & Beverage:Frozen pizza, ready-meal trays, and beverage carriers require grease-resistant barriers and FDA 21 CFR 176.170 compliance. Midwest dairy processors and Southeast poultry packers represent the densest demand clusters.
- Pharmaceuticals:Cold-chain insulin shippers and unit-dose blister card cartons demand dimensional precision and mineral oil-free substrates. California and Massachusetts biologics distribution hubs are pulling specialized insulated corrugated formats.
- Electronics:Anti-static coatings and shock-absorbing fluting profiles for direct-to-consumer smartphone and laptop shipment.
- Personal Care:Premium folding cartons for skincare and fragrance with embossed and foil-stamped finishes.
Food & Beverage anchors tonnage throughput. Pharmaceuticals is climbing the fastest on value-per-pound metrics.
Manufacturing Stage:
Supply concentration at the raw material processing stage creates margin capture upstream, while downstream stages fragment across regional converter networks.
- Raw Material Processing:Pulping, stock preparation, and linerboard formation at integrated mills in Georgia, Alabama, and the Pacific Northwest. OCC sorting and de-inking operations face California SB 54 recycled content mandates.
- Printing:Flexographic and lithographic lamination for branded retail graphics. HP Indigo digital presses enable run-of-one customization at mid-Atlantic converter facilities.
- Assembly:Corrugator line gluing, die-cutting, and folder-gluer finishing into knocked-down case blanks.
- Packaging:Point-of-use replenishment and vendor-managed inventory programs for Midwest food manufacturing clusters.
Raw Material Processing holds installed capacity. Printing is rotating up the share rankings.
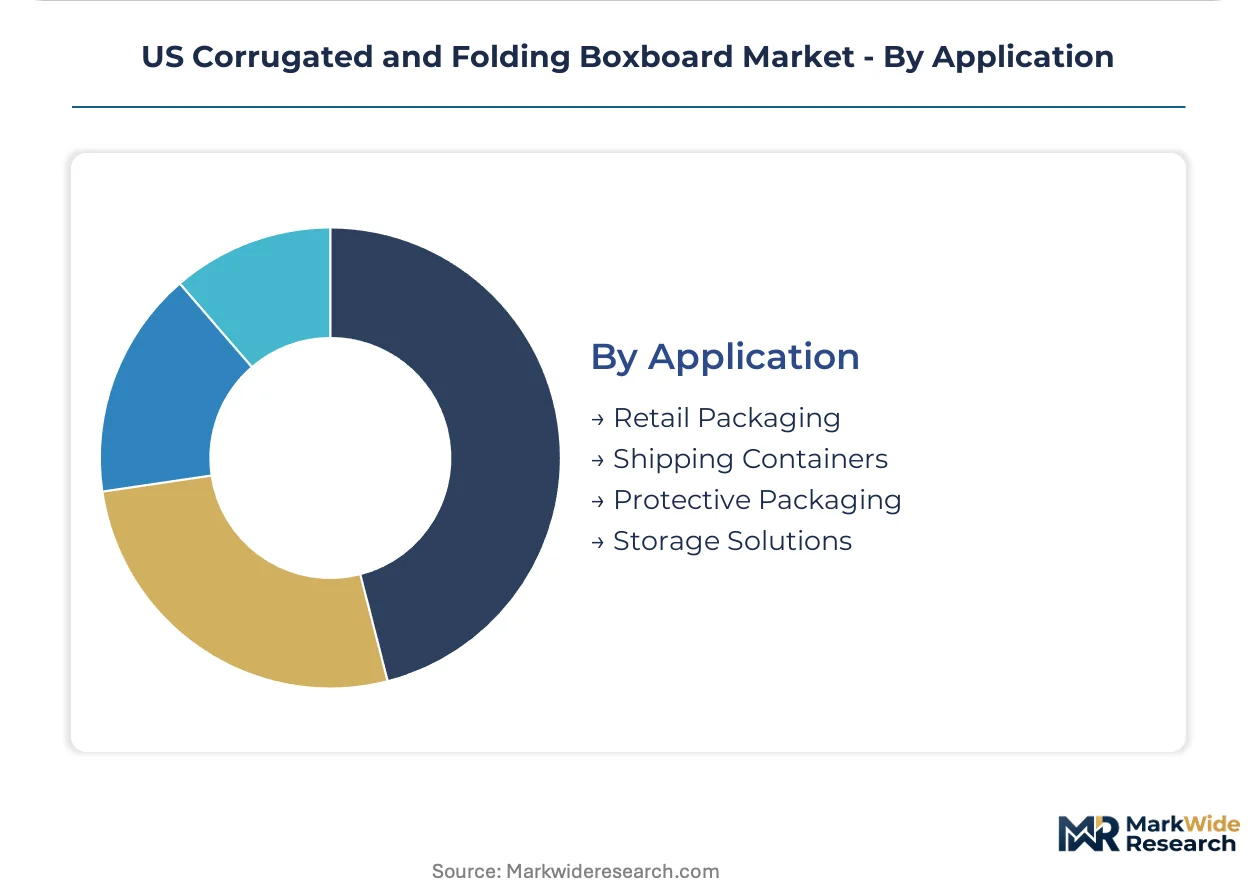
Application:
Volume scale concentrates in retail and shipping formats, while protective packaging expands most quickly as e-commerce penetration deepens.
- Retail Packaging:Shelf-ready trays and display-ready cases for club store and mass merchandise formats. Coca-Cola and PepsiCo bottlers in the Southeast specify high-graphic pre-print linerboard for point-of-sale impact.
- Shipping Containers:RSC cases and die-cut mailers for B2B and B2C distribution. UPS and FedEx sortation hub specifications drive burst strength and edge crush test minimums.
- Protective Packaging:Engineered foam-in-place and suspension inserts for fragile electronics. Texas and Arizona fulfillment nodes for direct-to-consumer brands are specifying anti-static and shock-absorbing configurations.
- Storage Solutions:Archive boxes and document storage containers for financial services and healthcare records retention.
Shipping Containers holds installed capacity. Protective Packaging is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions standards and OSHA workplace mandates anchor regulatory pressure across the US corrugated supply base, with state-level recycled content rules layering additional compliance burdens on mill and converter operations.
Southeast
E-commerce fulfillment nodes in Georgia and Alabama pull crush-resistant double-wall constructions for last-mile durability. Georgia-Pacific operates containerboard mills subject to EPA effluent limitation guidelines for biochemical oxygen demand. The Savannah-Richmond corridor hosts dense converter networks serving Coca-Cola and PepsiCo bottlers with high-graphic pre-print linerboard.
Great Lakes
Midwest food manufacturers demand just-in-time packaging lines with vendor-managed inventory programs. Wisconsin and Michigan face stricter Great Lakes Water Quality Agreement protocols on wastewater discharge. Chicago and Milwaukee dairy processors anchor demand clusters for FDA 21 CFR 176.170-compliant grease-resistant barriers.
Pacific Northwest
Oregon's Plastic Pollution and Recycling Modernization Act imposes post-consumer recycled content floors filtering back to folding boxboard specifications. Washington State mills retrofit aging wastewater infrastructure under tightening EPA color discharge standards. Seattle-Tacoma logistics hubs specify anti-static corrugated for electronics distribution.
California
SB 54 mandates force converters to re-engineer board specifications faster than mill R&D cycles accommodate. Los Angeles and San Diego biologics distribution hubs pull specialized insulated corrugated formats with phase-change material integration. California Air Resources Board rules compound federal EPA requirements for combustion emissions at pulp facilities.
Southwest
Texas and Arizona fulfillment centers for direct-to-consumer brands specify shock-absorbing fluting profiles for fragile electronics shipment. Arizona community colleges struggle to replenish corrugator operator skill shortages as experienced machine tenders retire. Phoenix-Tucson industrial corridors concentrate die-cutting and folder-gluer finishing capacity.
US Corrugated and Folding Boxboard Market Vendor Landscape
Integrated mill-to-box networks and regional custom converters split the market between scale-driven fiber control and agile short-run responsiveness. Four producers dominate US kraft linerboard capacity, creating supply vulnerability at Gulf Coast and Pacific Northwest mills. Strategic archetypes include captive fiber integrators, independent converters, and specialty barrier coaters. Competitive moves concentrate on capacity expansion in the Southeast mill belt and M&A consolidation of regional converter networks.
Among integrated producers with captive mill capacity, Smurfit WestRock and International Paper Company exemplify the fiber-control archetype through extensive containerboard footprints. Packaging Corporation of America occupies a position emphasizing short-run customizability for regional consumer brands. These three entities anchor the competitive structure, with Smurfit WestRock representing Midwest-Southeast network density, International Paper Company exemplifying national volume scale, and Packaging Corporation of America sitting within the responsiveness tier.
| Leading Market Players |
|---|
| Smurfit WestRock |
| International Paper Company |
| Packaging Corporation of America |
| Graphic Packaging International |
| Sonoco Products Company |
| Georgia-Pacific LLC |
| WestRock Company |
| DS Smith Plc |
| U.S. Corrugated Inc |
| Others |
Supply Flow & Price Mechanics
The Georgia-Alabama mill belt concentrates containerboard capacity within 300 miles of major e-commerce fulfillment nodes, compressing drayage costs and granting integrated producers outsized leverage over regional spot pricing. This geographic clustering allows Smurfit WestRock and International Paper Company to capture margin premiums on double-wall constructions demanded by Amazon and Walmart distribution centers.
Pricing Analysis
Price spreads between the Southeast and Pacific Northwest run 8-12% for comparable linerboard grades, reflecting freight differentials and OCC collection density. Three-tier pricing structure across premium folding boxboard, standard shipping grades, and economy recycled-content tiers separates pharmaceutical buyers from commodity e-commerce procurement. Cost compression in single-wall grades is intensifying because lightweight high-strength formulations are collapsing virgin fiber dependence. Regional consumer brands show highest price sensitivity, while pharmaceutical cold-chain buyers absorb premiums for insulated corrugated with phase-change material integration.
Supply Chain Analysis
Integrated producers in Georgia, Alabama, and the Pacific Northwest hold 70% of US kraft linerboard capacity, with Smurfit WestRock and International Paper Company anchoring mill-to-box networks. Raw material flows draw from OCC spot markets, virgin kraft pulp, and nano-cellulose reinforcement additives. Single-source vulnerability concentrates at Gulf Coast and Pacific Northwest mills where unplanned downtime ripples through national supply. Distribution runs through vendor-managed inventory programs with point-of-use replenishment for Midwest food manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US corrugated and folding boxboard market sits in early-cycle expansion as e-commerce fulfillment networks pull demand for protective shipping formats faster than converter capacity can respond. This adoption tailwind justifies strategic positioning ahead of recycled content mandate deadlines.
For Market Incumbents: Build captive fiber moats through backward integration into OCC collection networks and de-inking operations. Smurfit WestRock and International Paper Company should expand Georgia-Alabama mill capacity to capture Southeast e-commerce node proximity. Defensive consolidation of regional converter networks in the Great Lakes corridor protects against Packaging Corporation of America's short-run customizability threat. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical cold-chain insulated shippers, the fastest-climbing value-per-pound segment where FDA 21 CFR 176.170 compliance creates certification barriers for commodity players. Target California and Massachusetts biologics distribution hubs with phase-change material integration capabilities. Go-to-market through direct relationships with insulin and biologics 3PLs rather than competing for standard ambient shipping contracts. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because four integrated producers control 70% of capacity while downstream converter networks fragment regionally. Target acquisition archetype: mid-Atlantic digital print converters with HP Indigo or EFI Nozomi presses enabling run-of-one customization. Watch California SB 54 enforcement timelines as the inflection signal—compliance windows compressing below mill R&D cycles force distressed asset sales.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Georgia-Alabama mill additions position converters within 300 miles of Amazon and Walmart fulfillment nodes. |
| Backward Integration | OCC collection network control insulates Smurfit WestRock from 40-60% annual spot price volatility. |
| Digital Print Convergence | HP Indigo presses enable run-of-one customization for regional craft spirits and limited-edition cosmetics. |
| Cold Chain Specialization | Phase-change material integration captures insulin and biologics distribution beyond standard ambient shipping. |
| Regulatory Certification Investment | FDA 21 CFR 176.170 compliance for mineral oil-free barriers delays competitor commercialization by 18-24 months. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with corrugator operators, mill procurement directors, e-commerce fulfillment center managers, and FDA regulatory consultants; and secondary validation through EPA effluent filings, OCC spot market data, state-level extended producer responsibility rulemakings, and SEC 10-K disclosures from integrated producers. Bottom-up tonnage estimates from converter capacity utilization triangulated against top-down demand modeling from e-commerce shipment volumes and pharmaceutical distribution growth.
Forecast inputs span product construction tiers, end-use performance requirements, manufacturing stage positioning, and regional regulatory cluster severity. CAGRs were derived from segment-level demand elasticity modeling and mill capacity expansion pipelines across the analysis window. Industry-specific inputs include e-commerce penetration trajectories, California SB 54 compliance cost curves, and nano-cellulose additive adoption rates in premium folding boxboard grades.
Sensitivities concentrate around OCC price volatility, unplanned mill downtime at concentrated Gulf Coast facilities, and state environmental rule consolidation into de facto national standards. Quarterly review of California Air Resources Board enforcement actions, Amazon fulfillment center construction permits, and community college corrugator technician program enrollment is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Postage Stamp Paper Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Europe Mailer Packaging Market
Paper & Paperboard Packaging
Coated Duplex Board Market
Paper & Paperboard Packaging
C1S Packaging Paper Market
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
Polycoated Paper Packaging Market
Paper & Paperboard Packaging
Silicone Release Paper Market
Paper & Paperboard Packaging
Wrapping Paper Market
Paper & Paperboard Packaging
Paper Packaging Market
Paper & Paperboard Packaging
Chipboard Box Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
Stationery Films Packaging Market