
 Compostable Paper Tray Market | 2026-2036
Compostable Paper Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Compostable Paper Tray Market Outlook
BPI certification is unwinding competitive access across North American supply channels, filtering out uncertified converters and reshaping vendor qualification protocols. Huhtamaki leverages its integrated fiber molding capacity across multiple continents to sustain volume commitments to multinational foodservice accounts. Vegware anchors its position through direct control of compostable coating formulations, while BioPak competes aggressively in Australasian institutional procurement through localized production and distributor exclusivity arrangements.
Compostable paper trays are rigid fiber-based containers engineered from bleached or unbleached kraft pulp, often laminated with PLA or water-based barrier coatings to achieve grease resistance between 30 and 60 minutes under hot-food contact. They serve primarily as single-use serving vessels in foodservice environments where end-of-life composting diverts waste from landfill or incineration streams. Rectangular trays dominate commercial procurement due to standardized footprint compatibility with warming cabinets and display cases across fast-casual chains. Sugarcane bagasse variants are capturing margin pools in premium catering segments where fiber opacity and structural rigidity command price premiums over recycled paper alternatives. Wheat straw material supply remains structurally constrained by seasonal collection windows and regional fiber processing capacity, limiting segment expansion outside established agricultural processing corridors.
FDA food contact substance notifications govern barrier coating approvals in the United States, while EU REACH and the Packaging and Packaging Waste Regulation set migration limits and extended producer responsibility obligations across European member states. BIS certification requirements in India are tightening import pathways for uncertified tray stock, redirecting regional procurement toward domestic molded fiber converters. Stakeholders must monitor compost facility acceptance criteria, as industrial versus home compostability distinctions increasingly determine product viability in municipal tender specifications and retail shelf placement decisions.
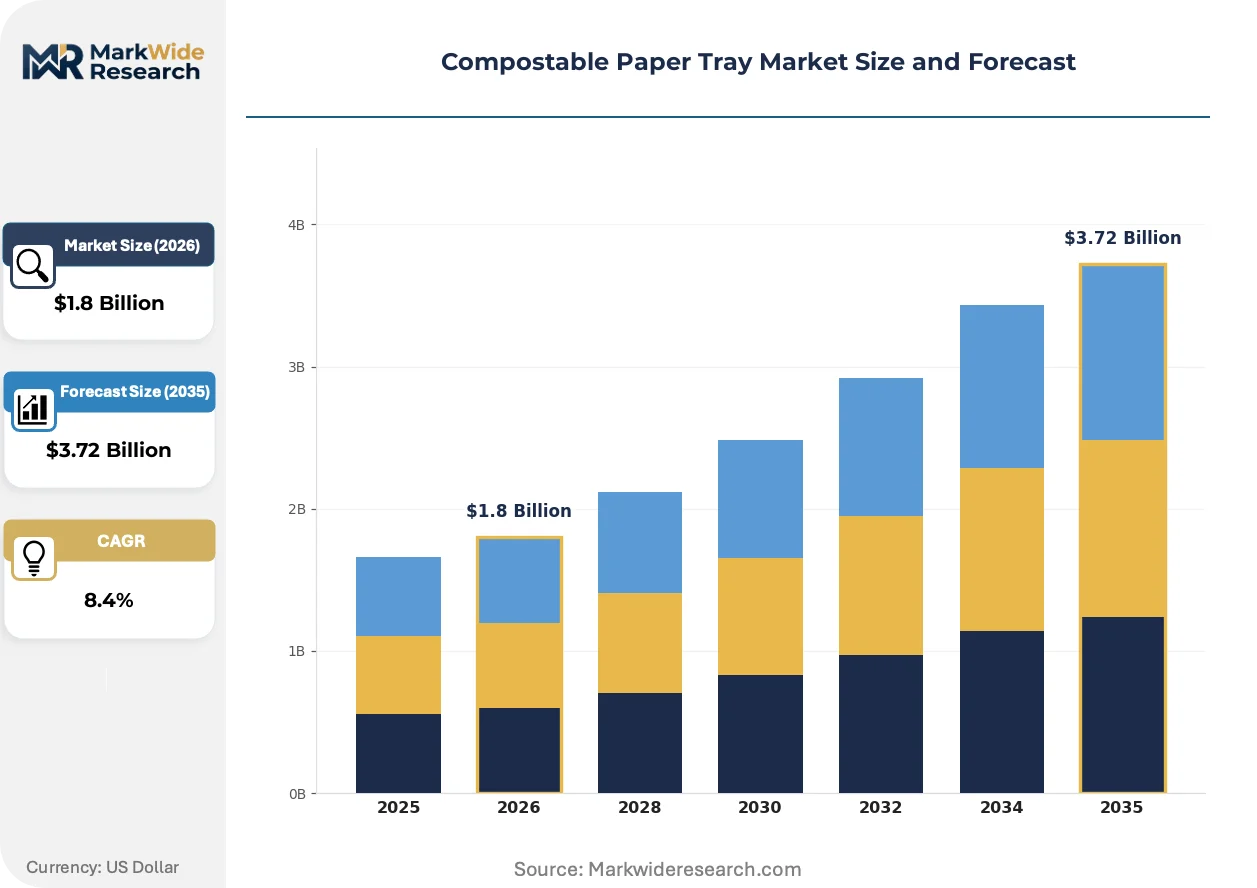
Market Dynamics
Certification mandates are restructuring competitive access across compostable paper tray supply channels, filtering out uncertified converters and elevating compliance costs as the primary barrier to market entry.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory phase-outs of conventional plastic foodservice items are accelerating institutional procurement timelines for certified compostable alternatives across cafeterias and quick-service chains.
- Bagasse fiber technology:Sugarcane residue processing advances are expanding raw material availability for molded fiber trays with superior grease resistance and structural rigidity.
- German municipal composting infrastructure:Standardized industrial composting acceptance criteria have created a functional reference market that neighboring jurisdictions are adopting for procurement specifications.
Market Restraints
- PLA resin price volatility:Polylactic acid coating costs fluctuate with corn starch feedstock markets, compressing converter margins during agricultural commodity spikes.
- Wheat straw supply seasonality:Fiber collection windows limit year-round production capacity outside established agricultural processing corridors in North American grain belts.
- Industrial composting facility scarcity:End-of-life infrastructure gaps in most US municipalities render certified compostable trays functionally non-compostable, undermining value propositions.
Strategic Opportunities
- Indian institutional catering:BIS certification requirements are redirecting procurement toward domestic molded fiber converters, creating protected market access for compliant local manufacturers.
- Water-based barrier coatings:PFAS-free formulations meeting FDA food contact substance notifications are opening premium positioning in health-conscious foodservice segments.
- Direct distributor arrangements:Bypassing traditional paper merchant channels through exclusive foodservice supply contracts is capturing margin pools previously absorbed by intermediaries.
Industry Challenges
- BPI certification timelines:Third-party compostability verification processes extend product launch cycles by 8-14 months, delaying revenue recognition for new tray specifications.
- Coating application equipment retrofitting:Converting legacy polyethylene lamination lines to PLA or aqueous barrier systems requires capital deployment that mid-scale converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compostable Paper Tray Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rectangular Trays, Round Trays, Divided Trays, Clamshell Trays Material: Bamboo, Sugarcane, Wheat Straw, Recycled Paper End User: Food Service, Retail, Catering, Takeaway Distribution Channel: Online Retail, Direct Sales, Wholesale, Supermarkets |
| Companies Covered | Greenwave, Huhtamaki, BioPak, Green Paper Products, World Centric, Bioleader, Ecoware, Sumkoka, Vegware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compostable Paper Tray Market Strategic Shifts
Barrier coating chemistry is diverging into competing technical pathways, with regulatory pressure on per- and polyfluoroalkyl substances forcing rapid formulation turnover and equipment reinvestment across converter networks.
PLA-laminated kraft pulp is fragmenting the premium tray segment as quick-service chains accelerate specification switches ahead of pending state-level packaging mandates. Chains with centralized procurement functions are consolidating supplier lists around dual-certified BPI and CMAI converters, compressing viable vendor pools and elevating compliance documentation requirements. The technology is fragmenting legacy supply relationships that previously prioritized unit cost over end-of-life verification.
REACH restrictions on persistent organic pollutants are tightening migration limits for food-contact barriers across EU member states, compelling coating suppliers to reformulate without fluorinated chemistries. Extended producer responsibility obligations under the Packaging and Packaging Waste Regulation are shifting compliance costs onto brand owners, who are responding by consolidating procurement around pre-certified tray stock. Quick-service restaurant chains with pan-European footprints are most affected, accelerating internal sustainability audit frequencies.
Foodservice buyers are consolidating vendor qualification around dual-certification standards that satisfy both industrial composting facility requirements and corporate sustainability reporting needs. Traditional distributor relationships emphasizing SKU breadth and logistics efficiency are giving way to direct converter partnerships that provide chain-of-custody documentation for Scope 3 emissions calculations. This pattern is most visible in Germany, where municipal tender specifications now mandate cradle-to-grave traceability for institutional cafeteria procurement.
Compostable Paper Tray Market Segmentation
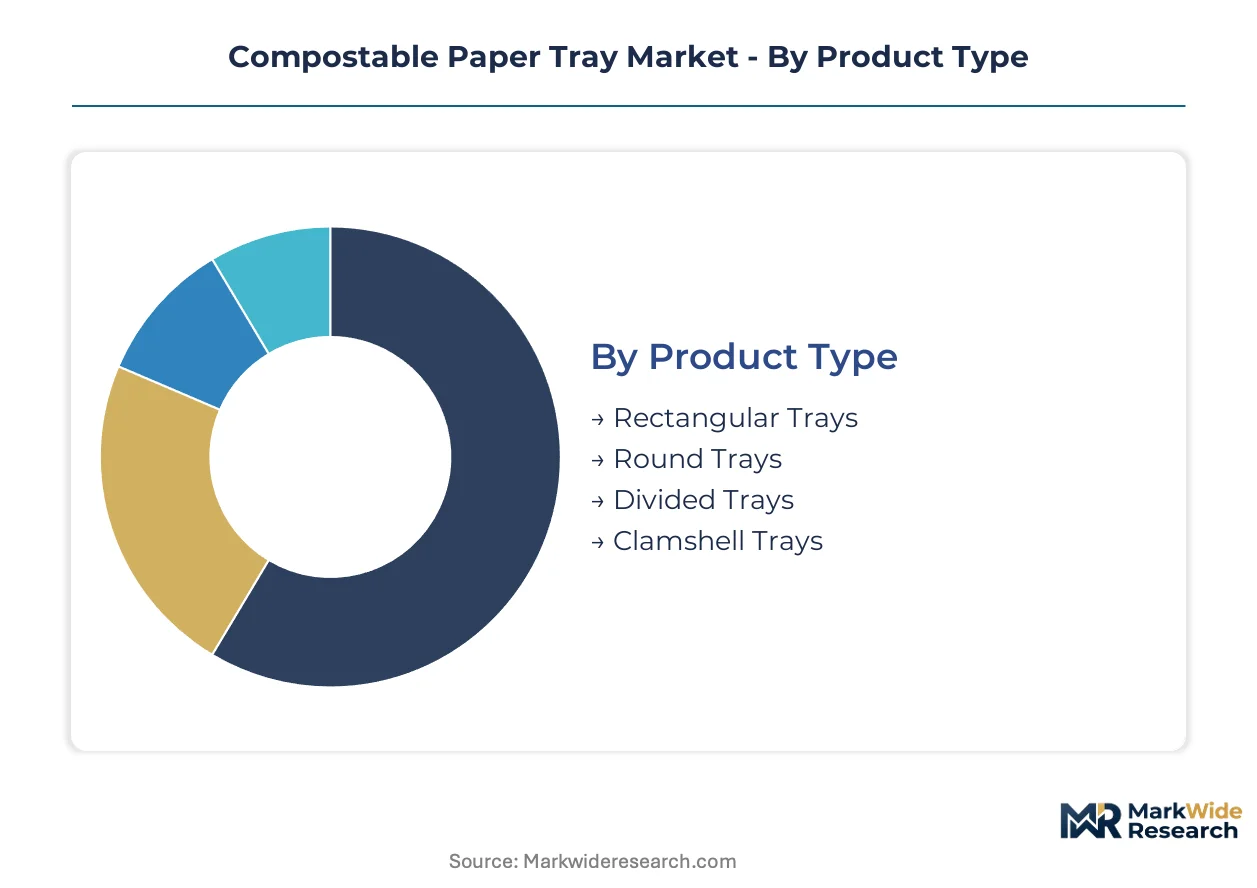
Segmentation in compostable paper trays reveals how substitution pressure from plastic alternatives concentrates in specific product formats and material grades. Procurement patterns diverge sharply between institutional buyers prioritizing certification compliance and foodservice operators optimizing for unit economics.
Product Type:
Rectangular formats face the most intense substitution threat from conventional plastic as quick-service chains consolidate warming cabinet footprints and demand standardized dimensions.
- Rectangular Trays:Engineered from bleached kraft pulp with PLA barrier lamination to achieve 30-60 minute grease resistance under hot-food contact. Quick-service restaurant chains in Germany and France are consolidating procurement around this format to align with municipal composting infrastructure and display case standardization.
- Round Trays:Molded fiber construction optimized for circular food presentation in premium catering and institutional cafeteria settings. Demand concentrates in Nordic countries where industrial composting acceptance criteria favor rigid fiber structures over flexible alternatives.
- Divided Trays:Compartmentalized designs serving school lunch programs and healthcare foodservice with portion control requirements.
- Clamshell Trays:Hinged-lid configurations capturing takeaway and grab-and-go segments where leak resistance and stackability determine procurement decisions.
Rectangular trays anchor the volume base while clamshell configurations gain share at the steepest rate.
Material:
Cost tier differentiation separates agricultural residue fibers from recycled paper alternatives, with premium positioning commanded by opacity and structural rigidity performance.
- Bamboo:Rapid-renewable grass fiber processed into high-opacity molded pulp with superior wet strength characteristics. Japanese institutional caterers and Australian quick-service chains specify bamboo-based trays for premium sustainability positioning and extended holding times.
- Sugarcane:Bagasse residue from sugar processing converted into rigid molded fiber with natural grease resistance and fiber density that commands price premiums over recycled alternatives. Indian domestic converters leverage local sugar belt proximity to supply BIS-certified stock for protected institutional procurement.
- Wheat Straw:Agricultural residue fiber constrained by seasonal collection windows and regional processing capacity limitations in North American grain belts.
- Recycled Paper:Post-consumer fiber pulp serving cost-sensitive segments where certification compliance outweighs performance specifications.
Recycled paper anchors the volume base while sugarcane gains share at the steepest rate.
End User:
Application-specific requirements drive divergence between high-volume institutional contracts and fragmented retail channels with divergent certification documentation needs.
- Food Service:Quick-service restaurants and institutional cafeterias procuring through direct converter partnerships with chain-of-custody documentation for Scope 3 emissions reporting. German municipal tender specifications now mandate cradle-to-grave traceability for this segment.
- Retail:Supermarket deli and prepared food sections requiring retail-ready packaging with shelf presence and barcode compatibility.
- Catering:Event and hospitality services prioritizing premium aesthetics and structural rigidity for transport and presentation.
- Takeaway:Delivery-optimized formats with leak resistance and stackability for third-party platform compatibility.
Food service anchors the volume base while takeaway gains share at the steepest rate.
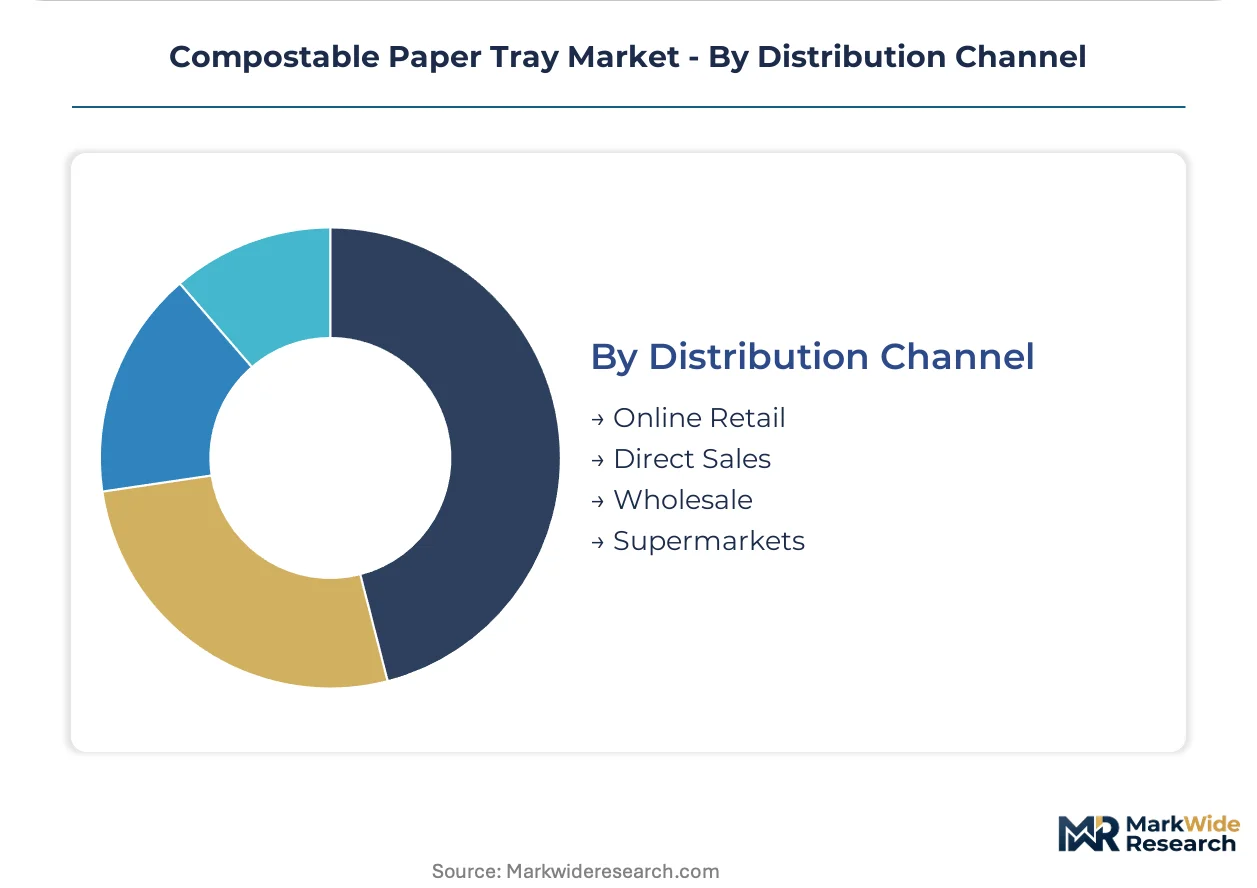
Distribution Channel:
Customer type fragmentation separates large-account direct relationships from fragmented wholesale intermediation with divergent margin absorption patterns.
- Online Retail:E-commerce platforms serving small-scale foodservice operators and specialty buyers with SKU breadth and rapid fulfillment.
- Direct Sales:Exclusive supply contracts bypassing traditional paper merchant channels to capture margin pools previously absorbed by intermediaries. Huhtamaki and Vegware leverage this channel for multinational account consolidation.
- Wholesale:Traditional distributor networks emphasizing logistics efficiency and SKU breadth over certification documentation.
- Supermarkets:Retail procurement for private-label and branded compostable housewares with consumer-facing sustainability claims.
Wholesale anchors the volume base while direct sales gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for compostable foodservice packaging, channeling certified tray stock through the continent's densest municipal composting network. German procurement standards now function as the de facto reference specification for neighboring jurisdictions.
Germany
Municipal composting infrastructure in Hamburg and Berlin processes industrial volumes of certified fiber trays, creating functional end-of-life verification for institutional buyers. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility obligations that redirect procurement toward pre-certified stock. Bavarian converters cluster around Augsburg to supply quick-service chains with cradle-to-grave traceability documentation.
United States
California's SB 54 implementation and pending state-level packaging mandates accelerate specification switches across quick-service restaurant chains. FDA food contact substance notifications govern barrier coating approvals, filtering out uncertified imports. Pacific Northwest fiber molding capacity concentrates around Portland and Seattle to serve institutional cafeteria contracts with BPI-certified alternatives.
India
BIS certification requirements tighten import pathways for uncertified tray stock, redirecting regional procurement toward domestic molded fiber converters. The FSSAI framework governs food-contact safety standards for institutional catering applications. Uttar Pradesh sugar belt proximity supplies bagasse fiber to converters in Ghaziabad and Noida for protected market access.
France
Quick-service chains with pan-European footprints consolidate procurement around dual-certified converters to satisfy corporate sustainability reporting requirements. ANSM and ECHA REACH restrictions tighten migration limits for food-contact barriers. Lyon and Marseille industrial zones host coating formulation specialists serving the premium catering segment.
Australia
Localized production and distributor exclusivity arrangements capture margin pools in Australasian institutional procurement. The TGA framework influences food-contact safety expectations, though state-level composting infrastructure varies significantly. Victorian converters around Melbourne supply quick-service accounts with certified stock aligned to municipal facility acceptance criteria.
Compostable Paper Tray Market Competitive Environment
Listed leaders compete with private specialists across certification compliance and coating formulation control. The vendor base stratifies around integrated fiber molding capacity, proprietary barrier chemistry, and direct foodservice account relationships. Three archetypes dominate: multinational converters with continental production footprints, regional specialists with captive coating technology, and domestic players leveraging protected certification pathways. Capacity expansion and exclusive distributor arrangements constitute the dominant competitive moves, displacing traditional paper merchant intermediation.
Within the integrated multinational tier, Huhtamaki and Vegware exemplify divergent strategic positions. Huhtamaki leverages its multi-continent fiber molding footprint to sustain volume commitments to centralized procurement functions at quick-service chains. Vegware anchors its positioning through direct control of compostable coating formulations, occupying a specialist role that commands premium positioning in certification-intensive segments. BioPak represents the regional specialist archetype, competing through localized Australasian production and distributor exclusivity arrangements that bypass traditional wholesale channels.
| Leading Market Players |
|---|
| Greenwave |
| Huhtamaki |
| BioPak |
| Green Paper Products |
| World Centric |
| Bioleader |
| Ecoware |
| Sumkoka |
| Vegware |
| Others |
Value Chain & Pricing Dynamics
Converter-scale fiber molding capacity in Germany and the United States anchors price floors for certified compostable trays, as multi-continent equipment utilization rates determine whether smaller players can absorb PLA resin volatility without margin collapse. BPI certification compliance costs stratify supply tiers, forcing uncertified converters toward economy positioning or exit while accredited producers capture institutional contract premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates BPI-CMAI dual-certified stock from single-certified alternatives and uncertified imports. Premium tiers command valuation from quick-service chains requiring cradle-to-grave traceability documentation, while economy tiers serve cost-sensitive retail deli segments where certification compliance outweighs performance specifications. Pricing pressure stems from corn starch feedstock volatility in PLA barrier coatings, compressing converter margins during agricultural commodity spikes. Institutional cafeteria buyers exhibit lowest price sensitivity due to mandated sustainability procurement quotas, whereas independent takeaway operators prioritize unit economics over certification grade.
Supply Chain Analysis
Inventory lead times for bagasse fiber extend 60-90 days beyond recycled pulp alternatives due to seasonal collection windows in Indian and Brazilian sugar belts. Raw material sourcing concentrates in Germany, India, and the United States, with Uttar Pradesh bagasse supply feeding domestic BIS-certified converters and Pacific Northwest fiber molding capacity serving North American institutional contracts. Supply chain risk centers on single-source vulnerability for PLA resin coating formulations, where limited qualified suppliers create bottleneck exposure. Distribution runs through direct converter partnerships that bypass traditional paper merchant channels, capturing margin pools previously absorbed by wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The compostable paper tray market represents a high-growth disruption propelled by EU Single-Use Plastics Directive enforcement, which mandates phase-outs of conventional plastic foodservice items and redirects procurement toward certified alternatives with verified end-of-life pathways.
For Market Incumbents: Consolidate supplier qualification protocols around dual BPI-CMAI certification to defend against emerging coating formulation specialists. Expand captive fiber molding capacity in Germany and the United States to secure volume commitments from multinational quick-service accounts facing centralized procurement consolidation. Vertical integration into PLA barrier coating production mitigates resin price volatility exposure. For New Entrants and Emerging Players: Water-based PFAS-free coating formulation gaps in the premium health-conscious segment present white-space entry points where incumbents under-serve. Target Indian institutional catering procurement protected by BIS certification requirements, where domestic converter capacity lags demand growth. Pursue direct distributor exclusivity arrangements in Australasian markets to bypass entrenched wholesale channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with direct foodservice account relationships and proprietary barrier chemistry control. Long-term viability favors integrated players with multi-continent production footprints and certification documentation capabilities. Acquisition target archetype: regional specialists with captive coating technology and established municipal composting facility acceptance. Monitor state-level packaging mandate adoption frequency as inflection indicator for procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | BPI-CMAI accreditation unlocks multinational quick-service chain procurement eligibility. |
| Backward Integration into Coating | In-house PLA formulation production buffers margin compression from agricultural commodity spikes. |
| Direct Distributor Exclusivity | Bypassing paper merchant channels captures 12-18 point margin pools in foodservice procurement. |
| Regional Capacity Expansion | Localized molding facilities in India and Australia satisfy BIS and municipal composting traceability requirements. |
| PFAS-Free Formulation Launch | Water-based barrier coatings meet FDA food contact substance notifications for health-conscious segments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with foodservice procurement directors, molded fiber plant managers, composting facility operators, and barrier coating R&D specialists. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, BPI certification databases, FDA food contact substance notification records, and municipal tender specification archives. Bottom-up tray volume estimates triangulated against top-down foodservice packaging spend allocations.
Across the analysis window, forecasts segmented by product format, material grade, end-user application, and distribution channel structure. CAGRs derived from substitution elasticity modeling against plastic tray phase-out timelines, incorporating PLA resin price correlation coefficients and municipal composting infrastructure build-out rates. Industry-specific inputs included bagasse fiber harvest yield variability and quick-service chain centralized procurement consolidation patterns.
Underlying assumptions cover sustained EU directive enforcement and BPI certification pathway stability, with deviation risk concentrated in industrial composting facility acceptance criteria fragmentation and corn starch feedstock supply shocks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
US Paper Cups and Paper Plates Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Kraft Bubble Mailers Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Box Liners Market
Paper & Paperboard Packaging
Middle East and Africa Paper Cone Market
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market
Paper & Paperboard Packaging
Food Wrapping Paper Market
Paper & Paperboard Packaging
Super Calendered Kraft Papers Market
Paper & Paperboard Packaging
Coated Duplex Board Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
Tacky Transfer Paper Market
Paper & Paperboard Packaging
Paper Coaster Market
Paper & Paperboard Packaging
Global Paper Bags Market
Paper & Paperboard Packaging
Cold Seal Paper Market