
 Clay Coated Recycled Boxboard Market | 2026-2036
Clay Coated Recycled Boxboard Market Size, Share, and Industry Trends Forecast 2026-2036
Clay Coated Recycled Boxboard Market Analysis
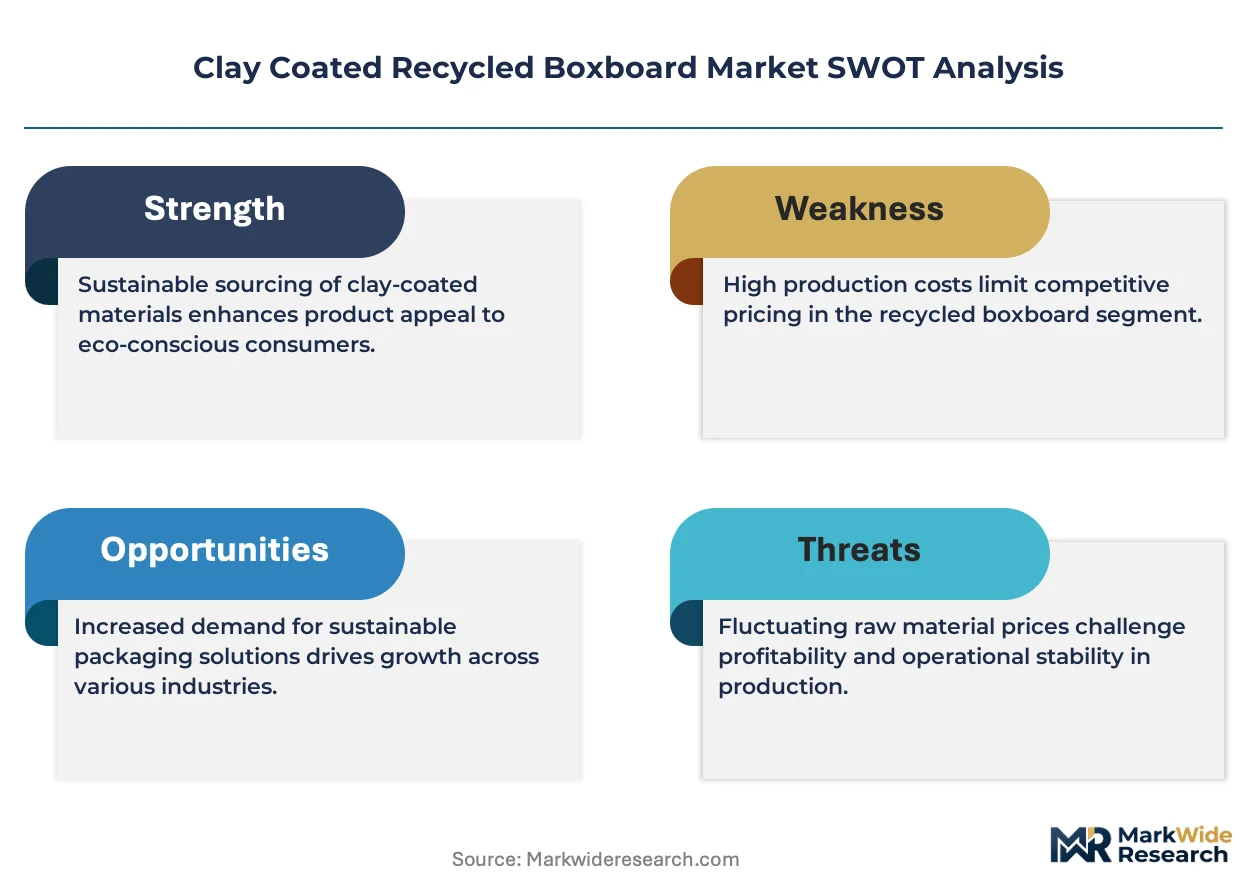
FSC chain-of-custody certification is unwinding competitive access across European and North American supply chains, forcing smaller mills to absorb audit costs or exit branded packaging tiers. International Paper Company leverages its integrated pulp-to-boxboard footprint across the southeastern United States to sustain volume commitments to multinational consumer goods accounts. Stora Enso Oyj anchors Nordic supply through its Oulu and Imatra mills, where renewable energy integration lowers carbon intensity scores that retailers now screen. DS Smith Plc competes on closed-loop recycling partnerships with UK grocery chains, collecting used boxes directly from store backrooms.
Clay coated recycled boxboard is a multilayer paperboard product manufactured from recovered fiber streams, with a refined clay mineral coating applied to one or both surfaces to achieve printable smoothness and controlled ink holdout; the board typically ranges from 200 to 400 grams per square meter and serves as the structural substrate for folding cartons, point-of-purchase displays, and premium packaging applications. The food and beverage end use segment dominates volume offtake as shelf-stable and chilled product lines convert from plastic to fiber-based formats. Litho-laminate product types command margin premiums where high-resolution photographic printing is required for cosmetics and confectionery positioning. Water-based coating formulations are gaining formulation share against oil-based alternatives as converters respond to volatile organic compound restrictions and brand owner clean-label packaging pledges.
The EPA oversees recovered fiber content claims under its Comprehensive Procurement Guidelines, while the EU Green Deal's packaging waste targets and REACH chemical registration requirements shape coating chemistry choices across export-bound production. FDA food contact substance notifications govern the barrier properties required for direct-food applications in the United States, creating a dual-track compliance burden for global suppliers. Stakeholders must monitor how extended producer responsibility fee structures in pending state-level US legislation reshape the cost calculus between virgin and recycled fiber sourcing.
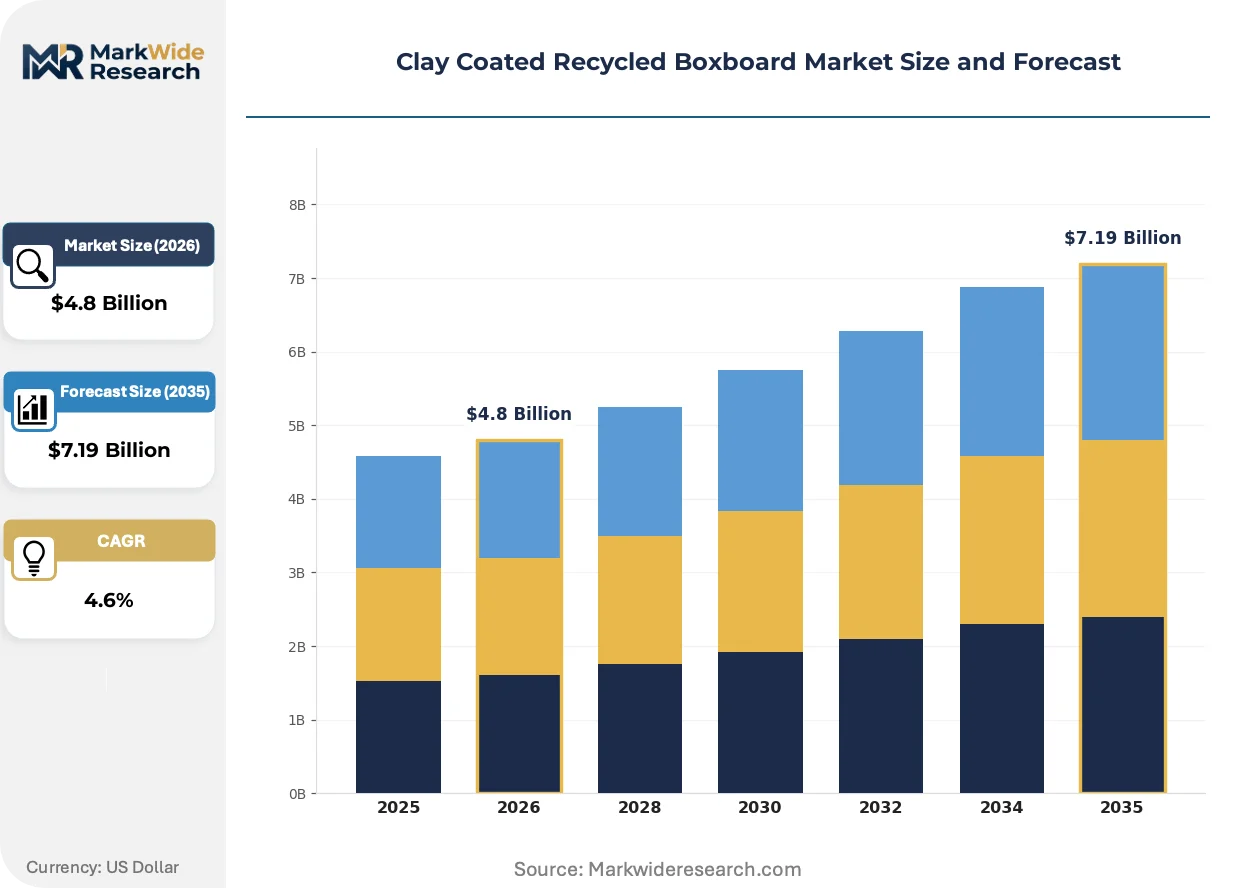
Market Dynamics
Brand sustainability mandates and the EU Packaging and Packaging Waste Regulation are compressing demand timelines for recycled-content folding cartons, forcing converters to secure FSC-certified supply chains ahead of mandatory recycled content thresholds.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Minimum recycled content thresholds favor clay coated recycled grades over virgin alternatives across European consumer goods supply chains.
- Food and beverage packaging conversion:Shelf-stable and chilled product lines are accelerating fiber-based format adoption as plastic displacement intensifies.
- German converter concentration:Paperboard converters serving central European supply chains are consolidating offtake agreements with Nordic and North American mills.
Market Restraints
- Recovered fiber cost volatility:Post-consumer fiber collection rates fluctuate with municipal budget cycles, squeezing margin predictability at integrated mills.
- FSC audit cost absorption:Smaller mills face binary choices between certification investment and exit from branded packaging tiers.
- Barrier coating technical limitations:Water-based formulations struggle to match oil-based alternatives for high-moisture food contact applications.
Strategic Opportunities
- Extended producer responsibility tailwinds:Pending state-level US legislation reshapes cost calculus between virgin and recycled fiber sourcing.
- Cosmetics litho-laminate white space:High-resolution photographic printing requirements command margin premiums in premium positioning segments.
- Closed-loop grocery partnerships:Direct collection from store backrooms creates captive fiber streams for integrated converters.
Industry Challenges
- Dual-track compliance complexity:FDA food contact substance notifications and REACH chemical registration create overlapping burden for global suppliers.
- Coating chemistry capex intensity:Volatile organic compound restrictions demand reformulation investment at multiple production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clay Coated Recycled Boxboard Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Wall, Double-Wall, Triple-Wall, Litho-Laminate End Use Industry: Food & Beverage, Personal Care, Electronics, Household Goods Thickness: Lightweight, Standard, Heavyweight, Extra Heavyweight Coating Type: Water-Based, Oil-Based, Waxed, Others |
| Companies Covered | International Paper Company, Stora Enso Oyj, WestRock Company, Pratt Industries, Graphic Packaging International, Smurfit Kappa Group, DS Smith Plc, GreenPaper, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clay Coated Recycled Boxboard Market Emerging Trajectories
Coating technology and regulatory chemistry standards are compressing formulation development cycles while procurement models favor certified supply chain transparency.
Water-based barrier coatings are miniaturizing the performance gap with conventional oil-based alternatives. Folding carton converters serving chilled food lines are adopting these formulations at accelerated pace to meet clean-label packaging pledges. This chemistry shift is miniaturizing the addressable market for legacy coating suppliers while expanding formulation partnerships between mills and specialty chemical providers.
REACH chemical registration requirements are tightening coating ingredient disclosure standards across export-bound production. ECHA substance evaluation processes extend lead times for new barrier chemistries entering European markets. Food contact applications face the steepest compliance burden, with converters pre-qualifying suppliers against evolving SVHC candidate lists.
Buyer concentration around multinational consumer goods accounts is consolidating specification-setting power. Tier-one retailers now screen supplier carbon intensity scores alongside price, displacing spot-market purchasing for long-term volume commitments. This preference shift is most visible in Nordic and German supply chains, where renewable energy integration at mill level commands procurement priority.
Clay Coated Recycled Boxboard Market Segmentation
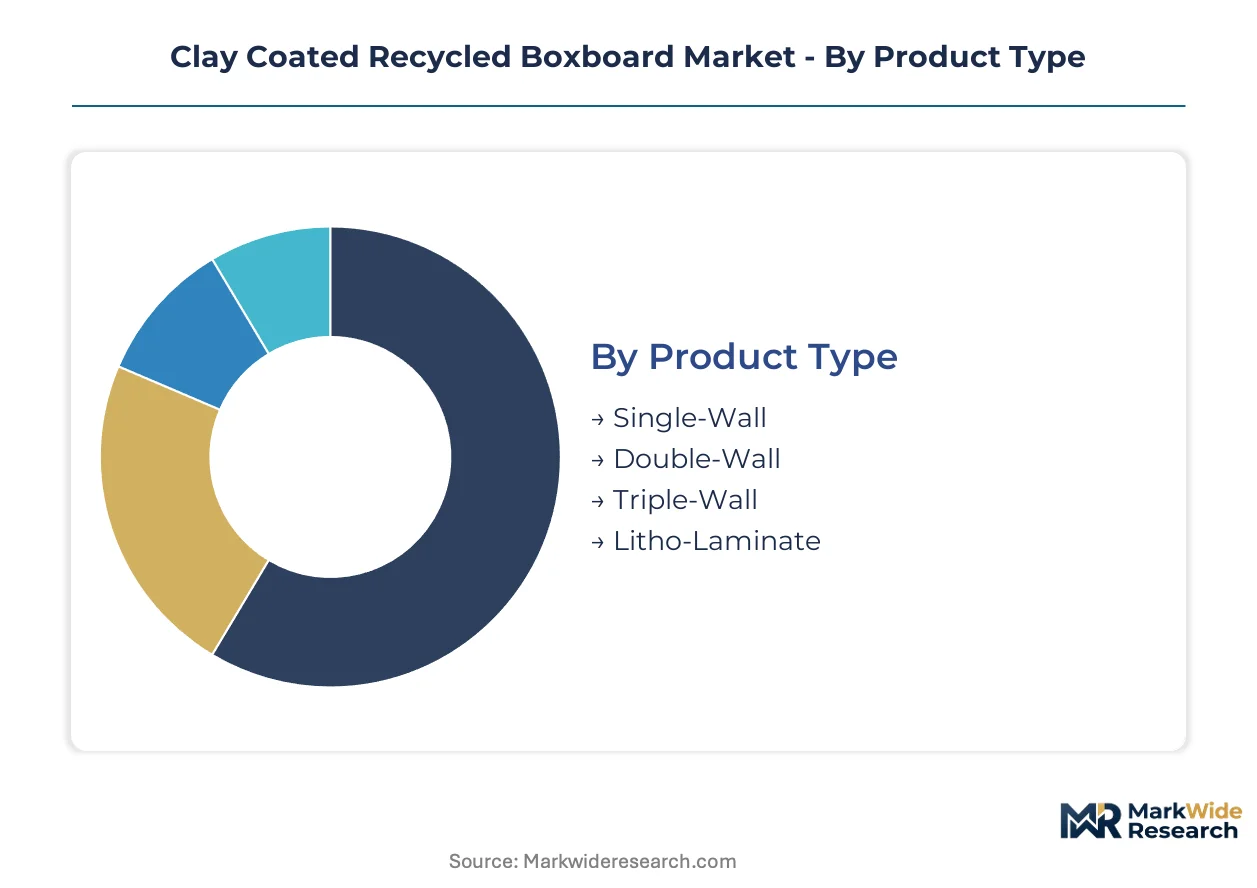
Segmentation in clay coated recycled boxboard reveals how technical specifications align with divergent supply chain requirements across food safety, print quality, and structural load-bearing applications. Procurement patterns fragment across converters serving multinational consumer goods accounts versus regional packaging specialists.
Product Type:
Single-wall grades dominate domestic North American supply chains for lightweight consumer goods, while litho-laminate and multi-wall structures concentrate in export-oriented European production.
- Single-Wall:A single-layer board construction ranging from 200-280 gsm, engineered for dry food cartons and lightweight retail packaging. Demand concentrates in US Southeast integrated mill networks supplying quick-serve restaurant chains and dry grocery lines, constrained by limited moisture resistance for chilled applications.
- Litho-Laminate:A premium composite structure combining clay coated recycled boxboard with lithographic printed facings, achieving photographic reproduction quality. Orders cluster in German and French cosmetics supply chains where high-resolution brand imagery commands specification priority, driven by shelf differentiation requirements in premium retail.
- Double-Wall:Twin-fluted corrugated medium laminated to clay coated liners, specified for heavier consumer electronics and glass bottle shipments.
- Triple-Wall:Three-layer corrugated construction for industrial bulk packaging and heavy appliance crating, primarily sourced from Nordic mills with renewable energy credentials.
Single-Wall holds the largest share; momentum sits with Litho-Laminate.
End Use Industry:
Food and beverage converters absorb volume at standard margin tiers, while personal care and electronics buyers extract premium pricing for certified supply chain documentation.
- Food & Beverage:The dominant consumption segment spanning shelf-stable dry goods, chilled dairy, and frozen product lines. FDA food contact substance notifications and EU Framework Regulation compliance create dual-track qualification burdens for global suppliers, with German converters consolidating offtake from Nordic FSC-certified mills.
- Personal Care:Premium positioning segments including cosmetics, skincare, and fragrance packaging requiring high-gloss print surfaces and structural rigidity. Specification-setting power concentrates with L'Oréal and Unilever procurement teams screening supplier carbon intensity scores alongside unit economics.
- Electronics:Anti-static and cushioning specifications for consumer device and accessory packaging, with demand clustering in Shenzhen and Dongguan manufacturing corridors.
- Household Goods:Detergent, cleaning product, and home care cartons requiring chemical resistance and stack strength for warehouse distribution.
Food & Beverage anchors volume throughput; Personal Care generates the steepest expansion trajectory.
Thickness:
Lightweight specifications serve air-freight cosmetics and e-commerce subscription boxes where dimensional weight pricing dominates logistics calculus, while heavyweight grades concentrate in palletized beverage distribution.
- Lightweight:Sub-250 gsm constructions optimized for dimensional weight reduction in direct-to-consumer shipping channels. E-commerce fulfillment centers in the Netherlands and northern Germany specify these grades for subscription beauty boxes, balancing protection with postal tariff minimization.
- Standard:250-320 gsm range serving mainstream folding carton applications across cereal, cracker, and dry pasta lines.
- Heavyweight:320-400 gsm boards for multi-pack beverage carriers and club store bulk formats requiring enhanced stack compression resistance.
- Extra Heavyweight:Above-400 gsm specialty grades for point-of-purchase displays and retail-ready packaging with direct shelf placement.
Standard thickness commands baseline volume; Lightweight grades are gaining share fastest.
Coating Type:
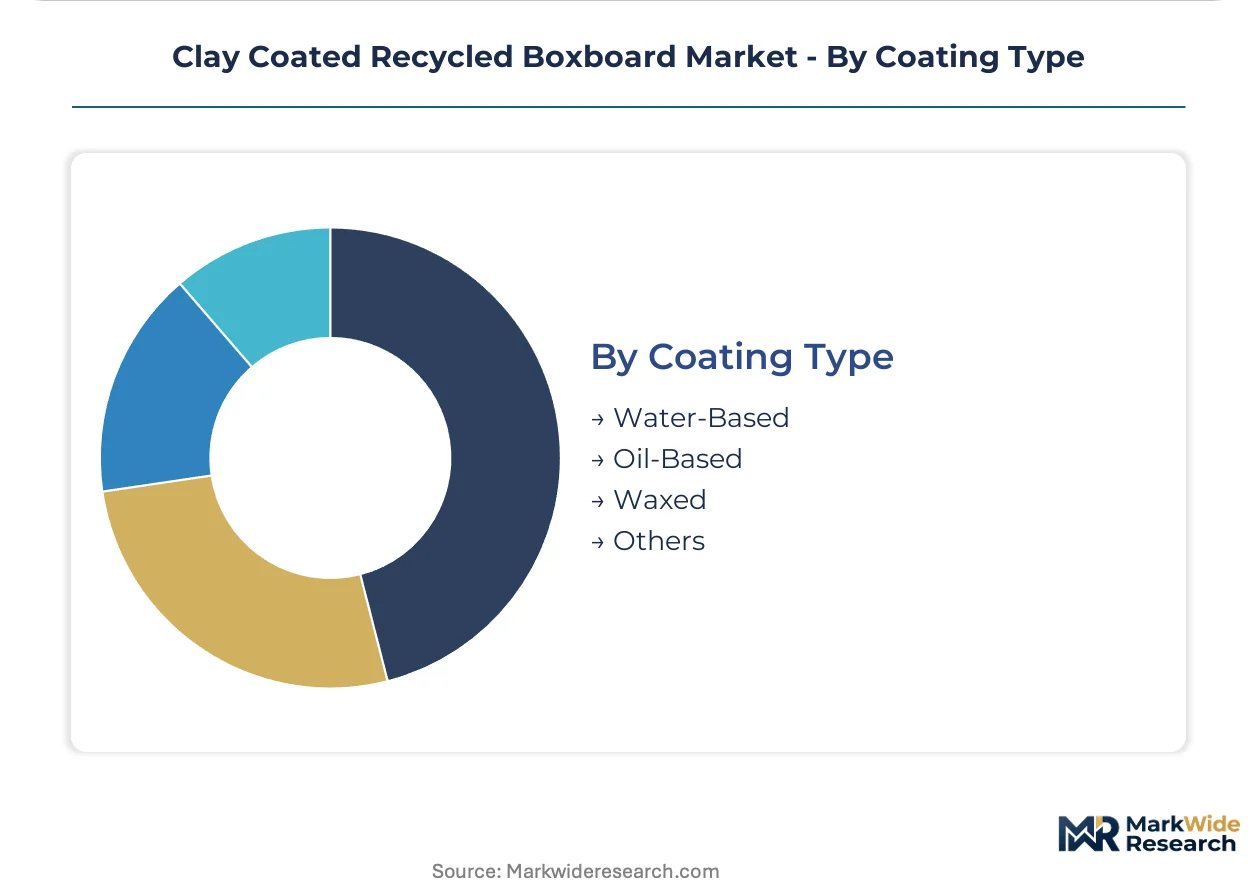
Water-based formulations displace oil-based alternatives in EU-bound production as REACH volatile organic compound restrictions tighten, while waxed coatings retain niche positions in moisture-critical US food applications.
- Water-Based:Acrylic and styrene-acrylic emulsion coatings achieving grease and moisture resistance without petroleum derivatives. ECHA substance evaluation processes extend qualification timelines for new chemistries, favoring incumbent suppliers with existing REACH dossiers.
- Oil-Based:Conventional polyethylene and extruded barrier coatings facing formulation pressure from clean-label packaging pledges.
- Waxed:Paraffin and vegetable-based wax treatments for high-moisture produce and chilled meat applications, concentrated in US Pacific Northwest fruit export corridors.
- Others:Bio-based PLA and cellulose nanofiber experimental coatings in pilot production at Finnish and Swedish research mill facilities.
Water-Based coatings hold the largest share; bio-based alternatives in the Others category show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Packaging and Packaging Waste Regulation is compressing demand timelines across European supply chains, while US state-level extended producer responsibility legislation reshapes fiber sourcing economics. Mills with renewable energy integration and FSC-certified supply chains command procurement priority from multinational consumer goods accounts.
Germany
Paperboard converters serving central European supply chains are consolidating offtake agreements with Nordic mills ahead of mandatory recycled content thresholds. The EU Green Deal's packaging waste targets enforce minimum recycled fiber quotas that favor clay coated recycled grades. Production clusters in the Rhine-Ruhr region and Bavaria anchor folding carton supply to FMCG distribution networks.
United States
Integrated pulp-to-boxboard operations across the southeastern states sustain volume commitments to quick-serve restaurant and dry grocery chains. EPA Comprehensive Procurement Guidelines oversee recovered fiber content claims, creating compliance benchmarks for federal procurement. The Georgia-South Carolina corridor concentrates mill capacity serving domestic consumer goods accounts.
Sweden
Nordic mills leverage renewable energy integration to lower carbon intensity scores that tier-one retailers now screen during supplier qualification. REACH chemical registration requirements shape coating chemistry choices for export-bound production. The Oulu and Imatra mill complexes anchor supply to German and French cosmetics packaging converters.
United Kingdom
Closed-loop recycling partnerships with grocery chains collect used boxes directly from store backrooms, creating captive fiber streams. DS Smith Plc competes on this model, securing long-term supply agreements with major retailers. The Midlands and Greater London areas concentrate converting capacity for e-commerce and subscription box fulfillment.
Netherlands
E-commerce fulfillment centers specify lightweight sub-250 gsm constructions to minimize dimensional weight pricing in direct-to-consumer shipping channels. ECHA substance evaluation processes extend lead times for new barrier chemistries entering European markets. Rotterdam and Amsterdam logistics hubs drive specification demand for postal-optimized packaging formats.
Clay Coated Recycled Boxboard Market Vendor Landscape
Player mix skews toward integrated multinational paperboard producers with captive pulp and recycling operations. Three structural tiers have crystallized: scale-driven integrated giants with renewable energy portfolios, mid-cap regional specialists with FSC-certified niche positioning, and private-label converters serving spot-market demand. Competitive moves concentrate on backward integration into recovered fiber collection networks and strategic partnerships with grocery retailers for closed-loop supply.
Among North American integrated producers, International Paper Company and WestRock Company exemplify the scale-driven archetype with southeastern US mill networks. DS Smith Plc anchors the European closed-loop recycling model through UK grocery partnerships. Stora Enso Oyj occupies the Nordic renewable energy positioning tier with Oulu and Imatra operations.
| Leading Market Players |
|---|
| International Paper Company |
| Stora Enso Oyj |
| WestRock Company |
| Pratt Industries |
| Graphic Packaging International |
| Smurfit Kappa Group |
| DS Smith Plc |
| GreenPaper |
| Mondi Group |
| Others |
Supply Flow & Price Mechanics
FSC chain-of-custody certification gates both supplier qualification and price differentiation simultaneously, forcing converters to absorb audit costs or forfeit access to multinational consumer goods accounts while certified mills command premium positioning in procurement negotiations.
Pricing Analysis
Certification level creates the primary spread between FSC-certified premium grades and uncertified commodity board. Contract-based long-term offtake agreements dominate volume procurement, with price differentiation hinging on carbon intensity scores and renewable energy credentials that retailers now screen. Cost compression in standard grades is intensifying because recovered fiber collection rates fluctuate with municipal budget cycles. Regional packaging specialists exhibit the highest price sensitivity, while L'Oréal and Unilever procurement teams prioritize certified supply chain documentation over unit economics.
Supply Chain Analysis
Germany and Sweden anchor clay coated recycled boxboard production for European consumer goods supply chains. German converters in the Rhine-Ruhr region draw from Nordic mills with captive pulp operations, while raw material streams rest on post-consumer fiber collection networks and specialty clay mineral inputs. Single-source vulnerability concentrates around municipal recycling contract renewals that interrupt fiber flow. Distribution runs through integrated mill-to-converter direct shipments and third-party logistics hubs serving quick-serve restaurant and grocery retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The clay coated recycled boxboard market tracks a cyclical recovery as brand sustainability mandates tighten procurement specifications and compress demand timelines for certified supply chains.
For Market Incumbents: Shield margin position by deepening backward integration into recovered fiber collection networks before municipal contract renewals disrupt supply. Prioritize certification investment at Imatra and Oulu mill complexes to defend against emerging Nordic competitors with renewable energy portfolios. Channel control through closed-loop grocery partnerships creates defensive moats against spot-market converters.
For New Entrants and Emerging Players: Differentiate on bio-based barrier coating formulations that REACH pre-qualification processes have not yet fully evaluated. Target lightweight sub-250 gsm specifications for Dutch e-commerce fulfillment centers where dimensional weight pricing dominates logistics calculus. A direct-to-converter technical sales model bypasses incumbent mill relationships in the UK Midlands converting cluster.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across water-based coating reformulation lines as volatile organic compound restrictions demand facility-level capex. Long-term viability favors integrated producers with captive recycling operations and FSC-certified supply chains. Acquisition target archetypes include mid-cap regional specialists with German grocery chain relationships. The signal to watch is pending US state-level extended producer responsibility fee structures that reshape virgin versus recycled fiber sourcing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Collection | Captive post-consumer streams insulate German converters from municipal budget volatility. |
| Water-Based Coating Reformulation | REACH compliance positions mills ahead of ECHA substance evaluation timeline extensions. |
| Closed-Loop Grocery Partnership | DS Smith's UK store backroom model secures long-term supply agreements with tier-one retailers. |
| Renewable Energy Certification | Nordic mills leverage Oulu and Imatra carbon intensity scores to win Unilever procurement screens. |
| Lightweight Grade Capacity Addition | Netherlands fulfillment center demand for sub-250 gsm postal-optimized formats accelerates. |
Methodological Framework
A spread of perspectives from paperboard mill operations directors, folding carton procurement managers at FMCG accounts, FSC certification auditors, and specialty chemical formulation scientists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against EU Packaging and Packaging Waste Regulation drafts, EPA Comprehensive Procurement Guidelines, ECHA REACH dossier filings, and trade customs data. Bottom-up volume estimates from mill capacity utilization and top-down demand segmentation from end-use industry consumption patterns were triangulated to establish market sizing.
Segmentation dimensions modeled span product type, end-use industry, thickness specification, and coating chemistry across the projection horizon. CAGRs were derived from trend extrapolation of recovered fiber cost trajectories, regulatory compliance timeline compression, and brand sustainability pledge acceleration. Industry-specific forecast inputs include municipal recycling collection rate variability and retailer carbon intensity screening adoption curves.
Material uncertainties — abrupt shifts in EU Green Deal implementation schedules, FDA food contact substance notification delays, and post-consumer fiber collection disruption from municipal fiscal stress — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory continuity and brand owner commitment durability. Recalibration cycles align with material shifts in extended producer responsibility legislation and coating chemistry approval timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
Butchers Paper Market
Paper & Paperboard Packaging
Paperboard Container Market
Paper & Paperboard Packaging
White Sack Kraft Paper Market
Paper & Paperboard Packaging
Middle-East and Africa Corrugated Packaging Market
Paper & Paperboard Packaging
Food Contact Paper and Board Market
Paper & Paperboard Packaging
Cold Waxed Paper Cups Market
Paper & Paperboard Packaging
Paper and Paperboard Trays Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
Impregnated Paper Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
United Kingdom Corrugated Packaging Market
Paper & Paperboard Packaging
Australia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Kraft Paper SOS Bag Market
Paper & Paperboard Packaging
Waxing Base Paper Market