
 Canada Paper Packaging Market | 2026-2036
Canada Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Paper Packaging Market Outlook
Green bond issuance and sustainability-linked credit facilities are reshaping capital access for mid-scale packaging converters in Canada. Cascades Inc. leverages its Quebec-based recycled fiber network to anchor supply security for corrugated producers. Kruger Packaging L.P. sustains cost discipline through captive pulp integration at its Trois-Rivières complex. Smurfit WestRock competes by extending its North American containerboard footprint into Prairie distribution nodes.
Canada paper packaging comprises engineered paper-based structures—corrugated fiberboard, folding cartons, boxboard, and paper bags—manufactured from virgin kraft, recycled post-consumer fiber, or coated specialty stocks, with basis weights, burst strengths, and moisture barriers calibrated to protect goods through distribution and retail display. Corrugated boxes dominate tonnage flows, reflecting e-commerce palletization standards and produce shipping requirements from British Columbia's agricultural valleys. Folding cartons capture premium positioning in Ontario's pharmaceutical and personal care contract manufacturing sector, where child-resistant and tamper-evident specifications command margin premiums over standard industrial grades.
Health Canada enforces food-contact safety standards under the Food and Drugs Act, while the Canadian Environmental Protection Act governs recycled content claims and compostability labeling that shape procurement specifications for national grocery chains. The Competition Act's greenwashing provisions, enforced by the Competition Bureau, constrain unsubstantiated recyclability assertions on retail packaging. Stakeholders must monitor how extended producer responsibility frameworks under development in Alberta and Manitoba will alter post-collection cost allocation between converters and brand owners.
Market Dynamics
Health Canada's single-use plastics prohibition is redirecting food service procurement toward molded fiber and paper-based alternatives, while e-commerce fulfillment centers in Ontario and British Columbia are expanding corrugated container specifications to meet palletization standards.
Growth Catalysts
- Regulatory prohibition:Health Canada's ban on single-use plastics is eliminating competing substrates from food service applications. Food retailers and quick-service chains are accelerating paper packaging adoption to maintain compliance.
- E-commerce infrastructure:Third-party logistics providers in the Greater Toronto Area are specifying sustainable packaging tiers for fulfillment operations. Corrugated shipping containers are capturing expanded volume from automated warehouse systems.
- Extended producer responsibility:Provincial frameworks under development in Alberta and Manitoba are creating cost-recovery mechanisms that favor recyclable paper substrates over multi-material alternatives.
Market Restraints
- Recycled fiber cost volatility:Post-consumer OCC pricing fluctuates with Chinese import policy shifts and domestic collection infrastructure gaps. Converters face margin compression when fiber costs spike without corresponding price pass-through mechanisms.
- Quebec supply concentration:Cascades Inc. and Kruger Packaging L.P. control substantial recycled fiber network capacity in the province. Mid-scale converters face supply security risks from this geographic and corporate concentration.
- Moisture barrier limitations:Paper-based alternatives lack the grease and liquid resistance of plastic laminates for certain food applications. Hot-fill and high-fat content products remain technically challenging for uncoated fiber solutions.
Strategic Opportunities
- Prairie distribution expansion:Smurfit WestRock is extending North American containerboard footprint into Prairie distribution nodes. Underpenetrated Saskatchewan and Manitoba markets offer volume growth for corrugated producers with logistics optimization.
- Pharmaceutical folding cartons:Ontario's contract manufacturing sector for pharmaceuticals and personal care commands premium specifications. Child-resistant and tamper-evident carton requirements create margin differentiation opportunities.
- Green bond financing:Sustainability-linked credit facilities are reshaping capital access for mid-scale packaging converters. Eligible projects for recycled content expansion and energy efficiency retrofits attract preferential rates.
Industry Challenges
- Competition Act compliance:The Competition Bureau's greenwashing provisions constrain unsubstantiated recyclability assertions on retail packaging. Brand owners and converters must validate environmental claims through third-party certification.
- Food-contact safety certification:Health Canada's Food and Drugs Act requirements for direct food contact create lengthy approval timelines. New barrier coatings and adhesive formulations require extensive migration testing.
- Legacy equipment integration:Prairie converters operating older corrugators face technical barriers to producing high-performance board grades. Capital requirements for flute profile modernization strain regional operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Paper Packaging Market |
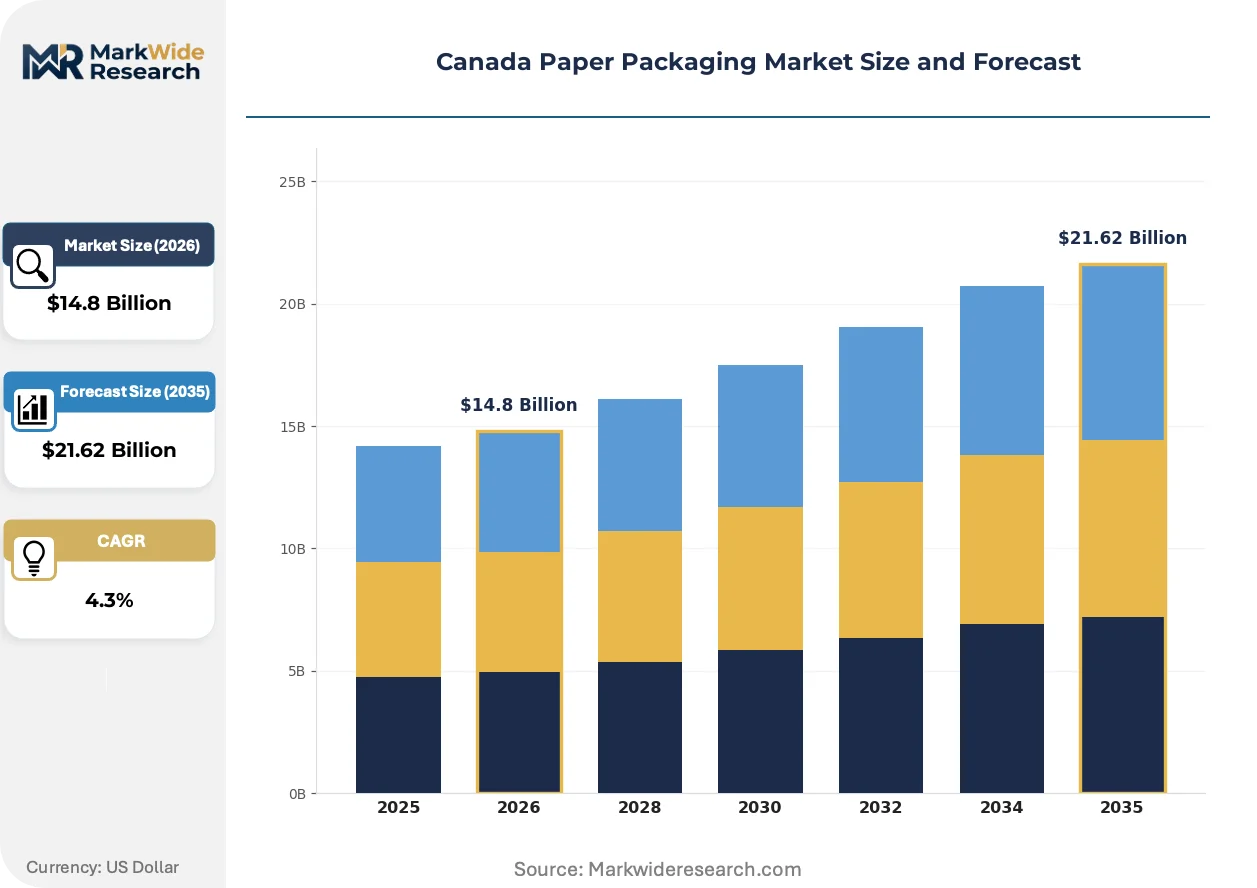
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $21.62 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxboard, Corrugated Boxes, Paper Bags, Folding Cartons Application: Food Packaging, Beverage Packaging, Consumer Goods, Industrial Packaging End User: Retail, E-Commerce, Food Service, Manufacturing Material Type: Kraft Paper, Recycled Paper, Coated Paper, Specialty Paper |
| Companies Covered | Crown Holdings Inc., Canadian Kraft Paper Industries Limited, Cascades Inc., Kruger Packaging L.P., Maritime Paper Products Limited Partnership, Smurfit WestRock, Tetra Pak International SA, International Paper Company, Graphic Packaging Holding Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Paper Packaging Market Strategic Shifts
Digital production technologies and regulatory compliance automation are compressing lead times and enabling mass customization in corrugated and folding carton manufacturing.
High-speed digital printing is digitizing short-run corrugated production for e-commerce brands requiring variable graphics and regional versioning. Ontario-based fulfillment centers are adopting this technology to reduce inventory carrying costs and enable promotional responsiveness. The technology is digitizing what was previously a high-minimum, long-lead commodity business into a responsive, on-demand supply model.
Health Canada's compostability labeling requirements under the Canadian Environmental Protection Act are forcing substrate standardization across national grocery chains. Retailers are consolidating supplier bases to those with certified industrial composting pathways. British Columbia's agricultural shipping corridors are most affected, with produce exporters retrofitting packaging lines to meet dual recyclable-compostable specifications.
Third-party logistics providers are consolidating packaging specifications across their Ontario and British Columbia networks to reduce SKU complexity. Tiered sustainability requirements are replacing transactional procurement with multi-year framework agreements. The Greater Toronto Area's manufacturing corridor exhibits the most visible concentration of this shift, where Loblaws and Metro specify annual packaging performance targets with penalty clauses for non-compliance.
Canada Paper Packaging Market Segmentation
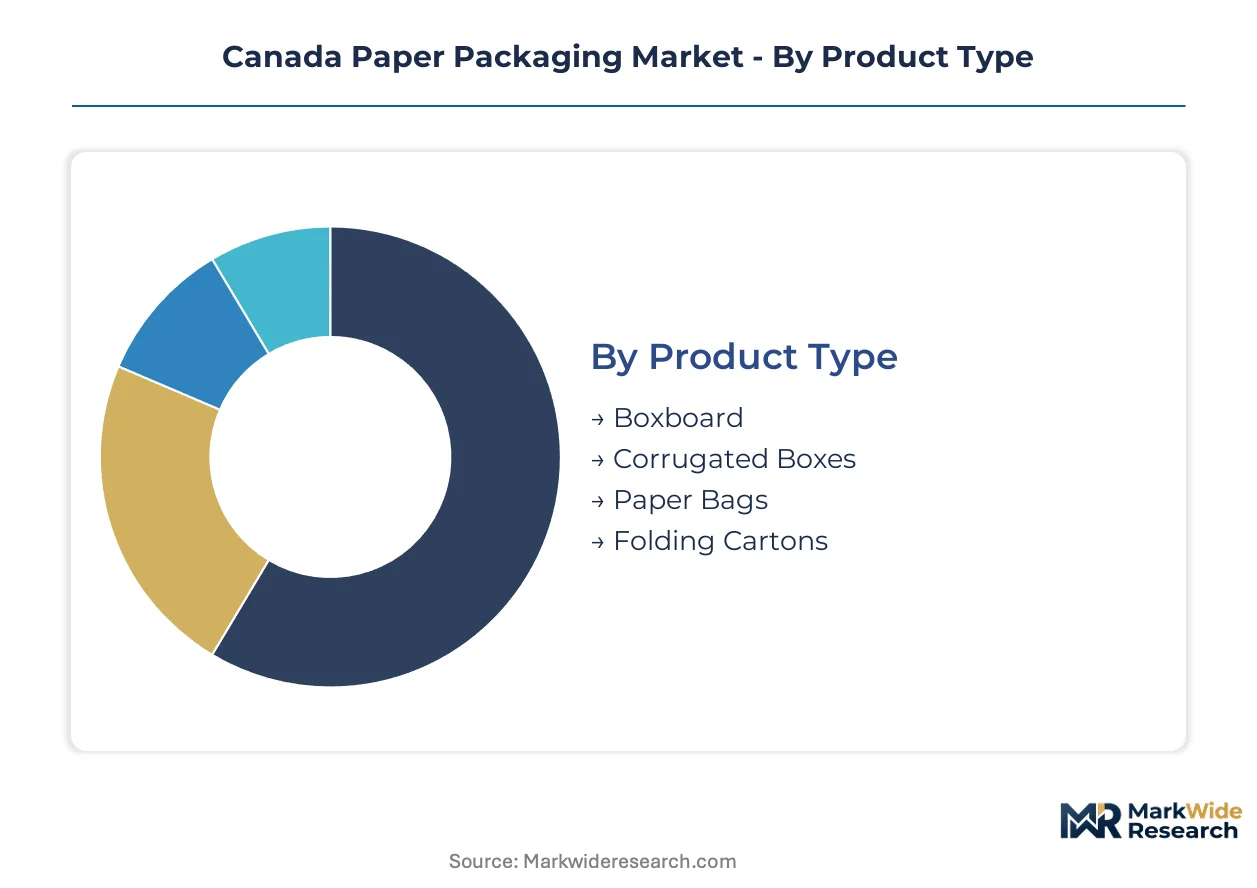
Paper packaging segmentation in Canada reveals how substrate selection and end-use requirements drive equipment investment cycles and service intensity. Converters must align product portfolios with provincial regulatory frameworks and channel-specific performance standards.
Product Type:
After-sales service intensity varies sharply across product categories, with automated corrugated lines demanding continuous technical support while folding carton operations emphasize die maintenance and color management services.
- Corrugated Boxes:Multi-layer fluted fiberboard structures engineered for stacking strength and palletization efficiency. Demand concentrates in Ontario's Greater Toronto Area fulfillment corridors, where third-party logistics providers specify burst strength and edge crush test certifications for automated warehouse systems. Health Canada's single-use plastics prohibition is redirecting food service procurement toward corrugated alternatives for takeout and delivery applications.
- Folding Cartons:Precision-cut paperboard containers with glued or locking closures, often incorporating child-resistant or tamper-evident features. Ontario's pharmaceutical and personal care contract manufacturing sector commands premium specifications, with Health Canada's Food and Drugs Act compliance requirements creating extended validation timelines for new barrier coatings.
- Boxboard:Solid bleached or unbleached paperboard for retail-ready packaging and display applications. British Columbia's produce exporters specify moisture-resistant grades for agricultural shipping corridors.
- Paper Bags:Single or multi-wall sacks for grocery, retail, and food service carryout. Quick-service chains across Quebec and Ontario are retrofitting packaging lines to meet compostability labeling requirements under the Canadian Environmental Protection Act.
By volume, Corrugated Boxes leads. By growth pace, Folding Cartons is climbing the fastest.
Application:
Cost tier differentiation separates commodity food packaging from specification-driven pharmaceutical and industrial segments, with margin structures reflecting barrier complexity and regulatory compliance burdens.
- Food Packaging:Direct-contact paper structures requiring grease resistance, moisture barriers, and migration-compliant coatings. Health Canada's Food and Drugs Act enforcement creates lengthy approval timelines for new adhesive formulations in hot-fill and high-fat content applications.
- Consumer Goods:Premium presentation packaging for personal care, cosmetics, and electronics. Ontario's contract manufacturing sector specifies folding cartons with metallic stamping and embossing for shelf differentiation.
- Beverage Packaging:Carrier packs, bottle wraps, and multi-pack sleeves for alcoholic and non-alcoholic drinks. Quebec's captive pulp integration at Trois-Rivières supplies cost-competitive kraft grades for this segment.
- Industrial Packaging:Heavy-duty corrugated and paper-based protective structures for machinery, automotive parts, and building materials. Prairie distribution nodes in Saskatchewan and Manitoba offer underpenetrated expansion opportunities.
Food Packaging captures the largest share of tonnage. Industrial Packaging is expanding most quickly as Prairie manufacturing activity accelerates.
End User:
Customer type determines specification stringency, with national grocery chains and third-party logistics providers imposing tiered sustainability frameworks that smaller regional players do not match.
- E-Commerce:Automated fulfillment operations specifying corrugated containers with dimensional optimization for parcel carrier dimensional weight pricing. Ontario and British Columbia fulfillment centers are consolidating supplier bases to reduce SKU complexity.
- Retail:National grocery chains including Loblaws and Metro specify annual packaging performance targets with penalty clauses for non-compliance. British Columbia's agricultural shipping corridors are retrofitting lines to meet dual recyclable-compostable specifications.
- Food Service:Quick-service chains and institutional caterers replacing plastic with molded fiber and paper-based alternatives under Health Canada's single-use plastics prohibition.
- Manufacturing:Industrial and automotive producers sourcing protective packaging for inbound components and finished goods distribution. Extended producer responsibility frameworks under development in Alberta and Manitoba will alter post-collection cost allocation.
E-Commerce leads by volume commitment. Food Service is gaining share fastest as regulatory displacement accelerates.
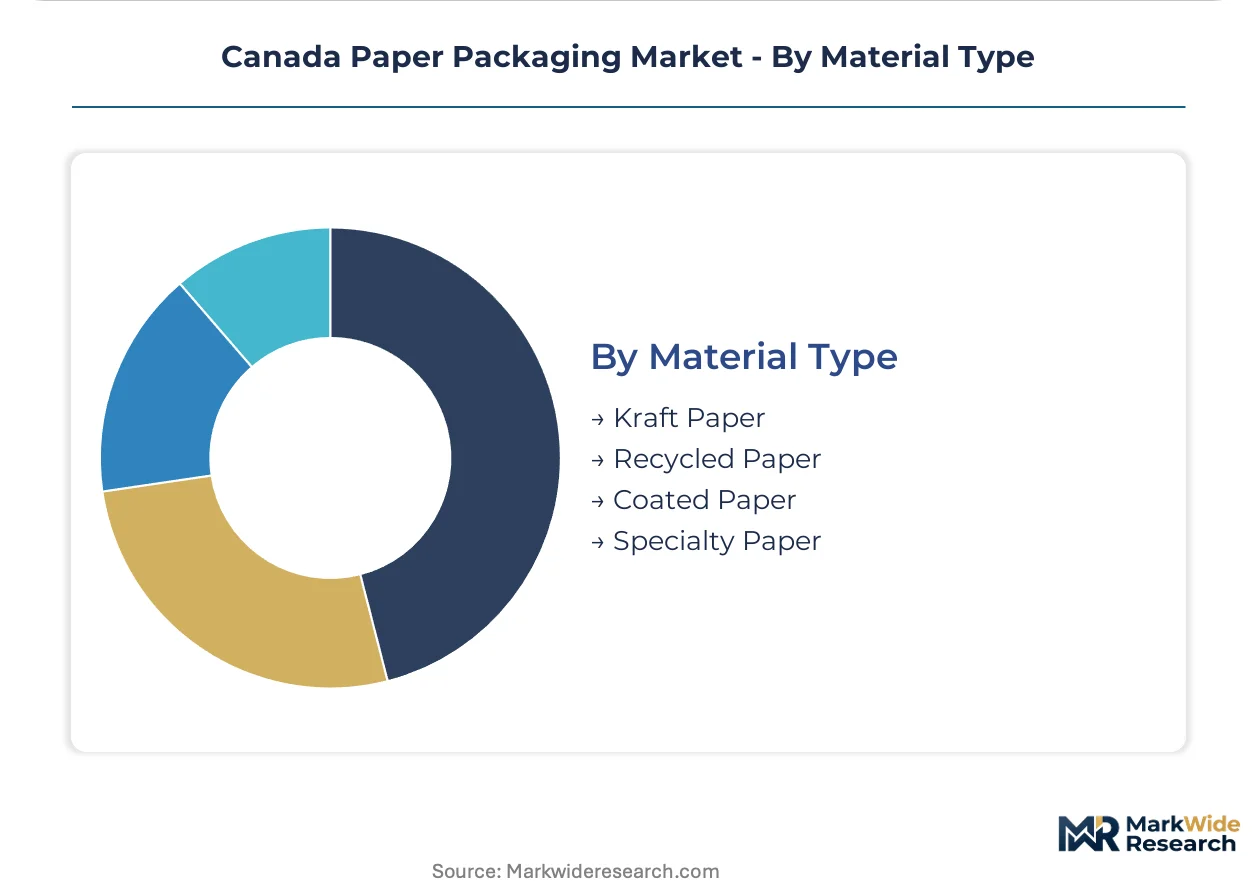
Material Type:
Supply concentration in Quebec's recycled fiber network shapes material availability, with Cascades Inc. and Kruger Packaging L.P. controlling substantial capacity that mid-scale converters must navigate for security.
- Recycled Paper:Post-consumer OCC and mixed paper pulps processed for corrugated medium and linerboard. Chinese import policy shifts create price volatility that converters must manage through inventory positioning.
- Kraft Paper:Virgin unbleached pulp with high tear strength and printability. Quebec's integrated pulp operations provide cost discipline for beverage and industrial packaging applications.
- Coated Paper:Clay or polymer-coated stocks for moisture and grease resistance in food-contact applications. Health Canada's migration testing requirements constrain rapid formulation changes.
- Specialty Paper:Glassine, greaseproof, and metallized grades for barrier-critical pharmaceutical and premium consumer applications. Ontario's pharmaceutical contract manufacturers specify certified industrial composting pathways.
Recycled Paper dominates by tonnage. Specialty Paper shows the steepest expansion trajectory as barrier performance requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's paper packaging trade flows reflect regional specialization, with Quebec and Ontario anchoring production capacity while British Columbia and the Prairie provinces drive demand growth through e-commerce and agricultural exports.
Ontario
The Greater Toronto Area's third-party logistics corridor specifies sustainable packaging tiers for automated fulfillment operations. Health Canada's Food and Drugs Act enforcement creates extended validation timelines for pharmaceutical folding cartons produced in Mississauga and Brampton contract manufacturing clusters. Loblaws and Metro impose annual packaging performance targets with penalty clauses across their Ontario distribution networks.
Quebec
Recycled fiber network concentration in Trois-Rivières and Montreal anchors supply security for corrugated producers serving Quebec's beverage and industrial markets. Cascades Inc. and Kruger Packaging L.P. control substantial integrated pulp capacity that shapes regional cost structures. The province's captive kraft integration supports competitive positioning for multi-pack sleeves and carrier packs.
British Columbia
Agricultural exporters in the Fraser Valley and Okanagan retrofit packaging lines to meet dual recyclable-compostable specifications under the Canadian Environmental Protection Act. E-commerce fulfillment centers in Vancouver and Surrey expand corrugated container specifications for dimensional weight pricing compliance. Produce shipping requirements from the province's agricultural valleys drive moisture-resistant boxboard demand.
Alberta
Extended producer responsibility frameworks under provincial development redirect post-collection cost allocation toward brand owners and converters. Calgary and Edmonton's industrial manufacturing base sources protective corrugated for machinery and building materials distribution. Underpenetrated Prairie markets offer volume growth for producers optimizing logistics into Saskatchewan and Manitoba distribution nodes.
Atlantic Canada
Maritime Paper Products Limited Partnership anchors regional converting capacity in Nova Scotia for food service and retail applications. Seafood exporters face compostability labeling requirements that favor certified industrial pathways. The region's smaller scale limits automated corrugated investment, preserving manual folding carton operations for specialty short runs.
Canada Paper Packaging Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in fiber supply and specialty coatings. The Canadian market exhibits tiered concentration, with Quebec-based integrated producers controlling recycled fiber networks while regional converters compete on service proximity. Three archetypes dominate: captive pulp integrators, recycled fiber network operators, and regional fulfillment specialists. Competitive moves center on Prairie distribution expansion and green bond financing for energy efficiency retrofits.
Among Quebec-based integrated producers, Cascades Inc. and Kruger Packaging L.P. exemplify the captive pulp archetype through Trois-Rivières complex operations. Smurfit WestRock represents the North American containerboard platform extending into Prairie distribution nodes. These three companies anchor competitive positioning across the corrugated and folding carton tiers without exhaustive market share claims.
| Leading Market Players |
|---|
| Crown Holdings Inc. |
| Canadian Kraft Paper Industries Limited |
| Cascades Inc. |
| Kruger Packaging L.P. |
| Maritime Paper Products Limited Partnership |
| Smurfit WestRock |
| Tetra Pak International SA |
| International Paper Company |
| Graphic Packaging Holding Company |
| Others |
Value Chain & Pricing Dynamics
Trois-Rivières' integrated pulp complexes anchor North American containerboard cost structures, with Quebec's captive kraft production conferring pricing power on corrugated linerboard shipments into Ontario fulfillment corridors. Downward pressure on folding carton margins intensifies when Health Canada's Food and Drugs Act validation timelines extend barrier coating approval cycles.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for heavy-duty corrugated, with pricing stratifying across premium, standard, and economy tiers based on burst strength certification and volume scale. Price differentiation hinges on after-sales technical support intensity and geographic delivery cost to Prairie distribution nodes. Cost compression in standard-grade boxboard is intensifying because Chinese import policy shifts spike post-consumer OCC pricing without corresponding pass-through mechanisms. National grocery chains exhibit lowest price sensitivity due to penalty-clause procurement frameworks, while regional food service operators face acute margin pressure from compostability certification requirements.
Supply Chain Analysis
Tariff exposure between Canada and the United States dominates supply chain risk calculus for cross-border containerboard flows. Geographic supply concentration centers on Quebec, Ontario, and the US Pacific Northwest for virgin kraft pulp. Raw material dependencies rest on post-consumer OCC, unbleached softwood pulp, and clay-coated specialty stocks. Single-source vulnerability from Cascades Inc. and Kruger Packaging L.P. controlling Trois-Rivières fiber network capacity creates supply security exposure for mid-scale converters. Distribution runs through third-party logistics consolidation hubs in the Greater Toronto Area and Vancouver-Surrey corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's paper packaging sector reads as a service-attach opportunity because die maintenance and color management contracts for pharmaceutical folding cartons are expanding faster than base material tonnage.
For Market Incumbents: Pre-empt Prairie distribution expansion by securing Saskatchewan and Manitoba logistics nodes before Smurfit WestRock's footprint extension completes. Backward integration into captive pulp supply at underutilized Quebec mill capacity defends margin position against recycled fiber cost volatility from Chinese import policy shifts. For New Entrants and Emerging Players: Saskatchewan's underpenetrated industrial packaging market offers white-space access for corrugated producers serving machinery and building materials distribution. Alberta's extended producer responsibility framework development creates compliance-service arbitrage for converters offering post-collection cost allocation consulting to brand owners. Target food service quick-service chains with certified industrial composting pathway bundling. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because Quebec's recycled fiber network concentration favors scaled operators with supply security. Acquisition targets should display captive pulp integration or digital printing capability for short-run e-commerce responsiveness. The signal to watch is Health Canada migration testing backlog duration as inflection indicator for barrier coating approval velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Networks | Cascades Inc.'s Quebec-based OCC collection infrastructure secures linerboard supply against import policy volatility. |
| Digital Production Technology Deployment | Ontario fulfillment centers adopt high-speed digital printing to enable variable graphics for regional e-commerce versioning. |
| Prairie Distribution Node Expansion | Smurfit WestRock extends containerboard footprint into Saskatchewan and Manitoba logistics corridors. |
| Green Bond Financing for Energy Retrofits | Mid-scale converters access preferential rates for recycled content expansion under sustainability-linked credit facilities. |
| Pharmaceutical Barrier Coating Certification | Health Canada's Food and Drugs Act compliance creates margin differentiation for validated migration-tested adhesives. |
Study Parameters
Cross-validation between primary interviews with corrugated plant managers, pharmaceutical contract manufacturing procurement leads, and third-party logistics sustainability officers anchors the qualitative findings. Secondary validation draws from Canadian Environmental Protection Act regulatory filings, Health Canada Food and Drugs Act guidance documents, Competition Bureau greenwashing enforcement records, and provincial extended producer responsibility framework consultations. Bottom-up volume modeling across material type and application segments triangulates against top-down macroeconomic demand drivers.
Calibration against historical capacity utilization rates and fiber price index movements informs the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application, end user, and material grade tier. CAGRs derive from trend extrapolation of e-commerce fulfillment growth, regulatory displacement velocity, and Prairie manufacturing acceleration. Industry-specific forecast inputs incorporate Health Canada single-use plastics prohibition implementation pace and provincial compostability labeling adoption curves.
Macroeconomic conditions sit as an overlay; deviation in Canadian dollar exchange rates, pulp futures pricing, and cross-border trade policy would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline execution and fiber collection infrastructure investment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Global Food Contact Papers Market
Paper & Paperboard Packaging
Italy Honeycomb Paper Market
Paper & Paperboard Packaging
Air Fryer Paper Liners Market
Paper & Paperboard Packaging
Cellular Paper Cardboard Market
Paper & Paperboard Packaging
Postage Stamp Paper Market
Paper & Paperboard Packaging
Food Contact Paper and Board Market
Paper & Paperboard Packaging
Paper Bag Box Market
Paper & Paperboard Packaging
Ultraflute Paper Market
Paper & Paperboard Packaging
Boxboard Packaging Market
Paper & Paperboard Packaging
Disposable Paper Plates Market
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
MMA Film & Sheet Market
Paper & Paperboard Packaging
Global Solid Board Market
Paper & Paperboard Packaging
Paper Bottles Market