
 Folding Cartons Market | 2026-2036
Folding Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Folding Cartons Market Analysis
The direct-to-retail channel is narrowing as e-commerce fulfillment centers demand smaller batch sizes and faster turnaround times. Smurfit Westrock leverages its integrated paperboard mills to control substrate costs across North American and European markets. Mondi Group anchors its position through specialty kraft paper grades engineered for frozen food applications. Huhtamaki competes by extending its digital printing footprint to serve regional craft brands with shorter runs.
Folding cartons are paper-based packaging containers manufactured from bleached or unbleached paperboard, typically ranging from 200 to 500 gsm, and formed through cutting, creasing, and folding operations without permanent adhesives. They serve as primary or secondary packaging for consumer goods, providing printable surfaces for branding, regulatory labeling, and tamper-evident features. The paperboard segment dominates value capture due to its recyclability credentials and established recovery infrastructure across developed economies. Digital printing within the printing technology dimension represents the fastest-expanding margin pool, as pharmaceutical and personal care brands shift from gravure to variable-data-capable platforms for serialization and regional customization.
The EU Green Deal and F-Gas Regulation shape substrate selection by penalizing non-recyclable multi-material laminates, while FDA food contact regulations in the United States govern barrier coating chemistries for direct-food applications. China's GB standards and SAMR enforcement on packaging minimization are tightening dimensional tolerances for e-commerce cartons. Stakeholders must monitor how divergent extended producer responsibility schemes across these jurisdictions alter total cost of ownership calculations for multinational brand owners.
Market Dynamics
Single-use plastic bans across the European Union, China, and select US states are redirecting brand-owner procurement toward fiber-based primary packaging, compressing conversion timelines and reshaping substrate supplier relationships.
Growth Catalysts
- EU Green Deal packaging mandates:The directive requires all packaging to be recyclable or reusable by 2030, forcing food and beverage brands to eliminate multi-material laminates in favor of monomaterial paperboard cartons.
- Pharmaceutical serialization requirements:Track-and-trace regulations in the United States and Europe are accelerating gravure-to-digital printing conversions, creating demand for variable-data-capable carton platforms.
- Frozen food shelf-life extension:Barrier-coated kraft paper grades now match polyethylene performance for ice cream and ready-meal applications, opening carton penetration in categories historically dominated by plastic tubs.
Market Restraints
- Pulp price volatility:Northern bleached softwood kraft pulp trades on commodity indexes that swung 40% between 2022-2024, compressing converter margins and forcing pass-through pricing disputes with brand owners.
- Recycling infrastructure gaps:Food-contact cartons with polyethylene or aluminum barriers require specialized hydro-pulping facilities concentrated in Germany, Sweden, and Finland, limiting circular-economy claims in Southern and Eastern Europe.
- Competing fiber formats:Molded fiber trays and bag-in-box systems are capturing shelf-ready produce and wine applications that folding cartons previously dominated.
Strategic Opportunities
- India organized retail expansion:Reliance Retail and D-Mart are adopting shelf-ready packaging for private-label staples, creating first-mover advantage for converters with digital print and short-run capabilities.
- Cellulose nanofiber barrier coatings:This emerging material converges with enzymatic deinking to eliminate plastic layers entirely, enabling home-compostable certification for premium organic food brands.
- E-commerce secondary packaging:Direct-to-consumer fulfillment centers demand right-sized cartons with integrated return logistics, a channel bypassing traditional retail distribution entirely.
Industry Challenges
- Pre-press automation talent scarcity:Digital workflow management and color consistency across hybrid gravure-digital presses require skill sets concentrated in aging specialist workforces in Germany and Japan.
- FDA food-contact notification timelines:Novel barrier coating chemistries face 180-240 day review cycles, delaying product launches and freezing R&D pipelines for export-oriented converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Folding Cartons Market |
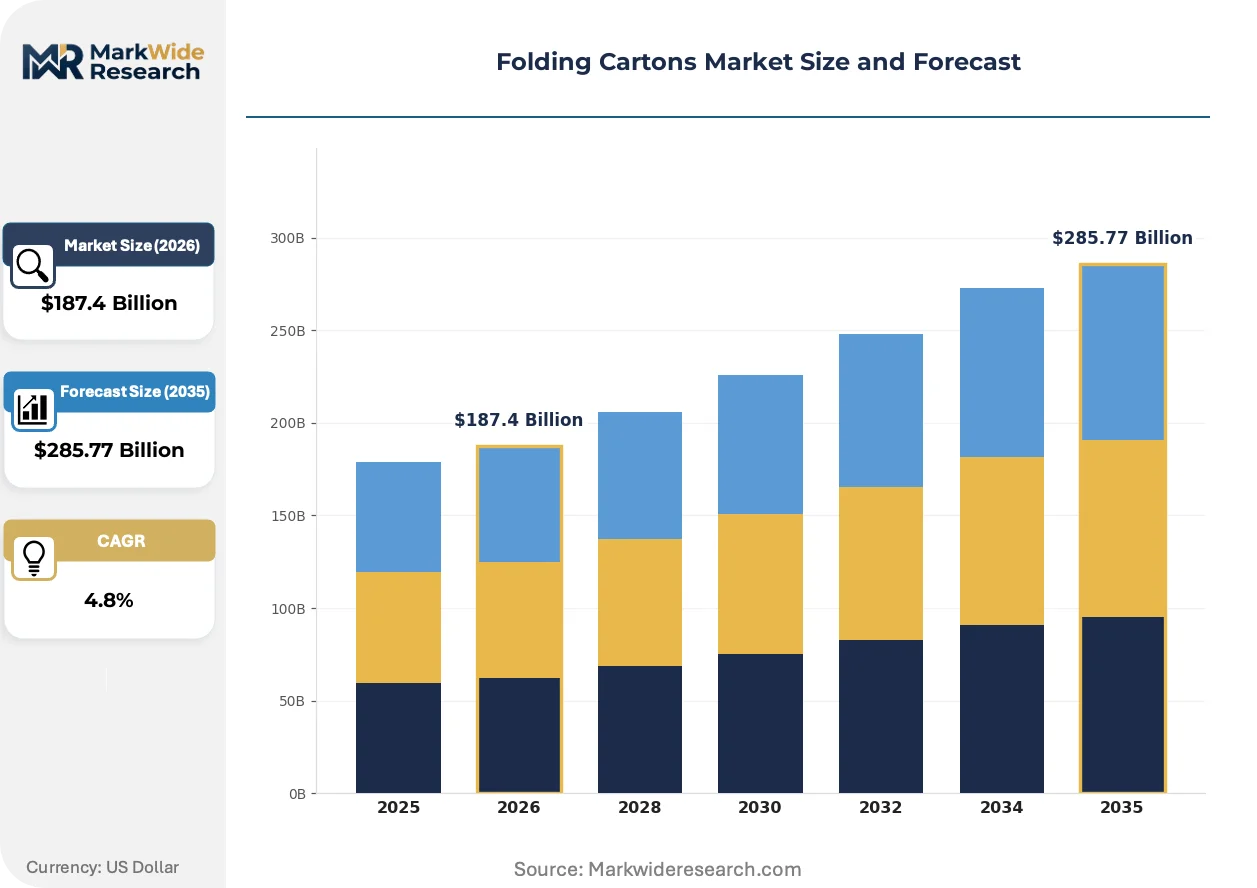
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paperboard, Plastic, Kraft Paper, Coated Paper End Use: Food & Beverage, Pharmaceuticals, Personal Care, Consumer Electronics Closure Type: Locking, Foldable, Tuck, Hang Tab Printing Technology: Flexography, Digital Printing, Lithography, Gravure |
| Companies Covered | Huhtamaki, Mondi Group, Smurfit Westrock, Stora Enso Oyj, DS Smith Plc, Graphic Packaging International, Mayr-Melnhof Karton AG, Oji Holdings Corporation, International Paper Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Folding Cartons Market Emerging Trajectories
Converting equipment and substrate engineering are converging to collapse minimum order quantities while preserving line-speed economics, enabling mass-customization capabilities previously restricted to narrow specialty applications.
Water-based flexographic printing with extended gamut inks is collapsing the cost gap versus gravure for medium-run pharmaceutical and personal care cartons. Brand owners in cosmetics and nutraceuticals are adopting this platform for seasonal SKU proliferation without cylinder engraving delays. The technology is collapsing traditional volume thresholds that once separated digital from conventional economics.
The EU F-Gas Regulation and parallel US EPA SNAP program are phasing out fluorinated barrier coatings used in grease-resistant food cartons. Converters are reformulating with clay-based and bio-wax alternatives that meet compostability certifications but require recalibration of heat-seal parameters. Frozen food and quick-service restaurant segments face the steepest compliance timelines and are consolidating supplier relationships to secure qualified substrate supply.
Brand-owner sustainability scorecards now weight packaging circularity metrics above unit cost in supplier selection protocols. Procurement teams at multinational consumer goods companies are unbundling carton specifications from legacy print vendors and awarding contracts to integrated paperboard producers with certified fiber sourcing. This behavioral shift is most pronounced in Germany, where retailer-led extended producer responsibility schemes impose visible eco-modulated fees at point of sale.
Folding Cartons Market Segmentation
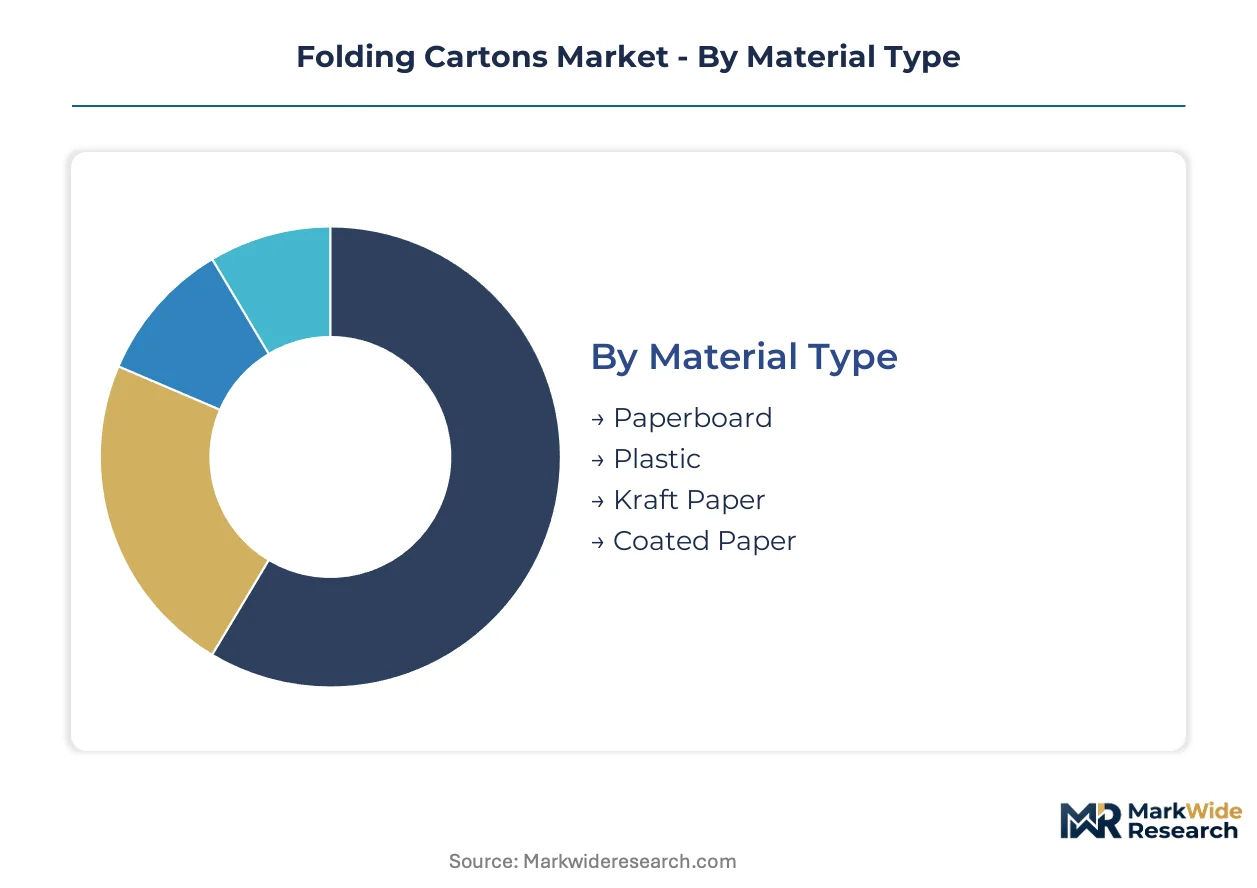
Segmentation in folding cartons reveals how substrate selection, closure mechanics, and print platforms align with distinct supply chain economics. Each dimension carries different margin profiles and capital intensity requirements that reshape converter specialization.
Material Type:
Use-case spectrum spans frozen food barrier demands at one extreme and lightweight dry-goods containment at the other.
- Paperboard:Bleached and unbleached grades ranging 200-500 gsm provide structural rigidity for shelf-ready packaging. Demand concentrates in Germany where retailer-led extended producer responsibility schemes penalize non-recyclable alternatives.
- Kraft Paper:Unbleached virgin and recycled fiber grades engineered with clay or bio-wax barrier coatings for grease and moisture resistance. Frozen food brands in Scandinavia specify this substrate to meet EU F-Gas Regulation compliance timelines.
- Plastic:Polyethylene and polypropylene laminates applied as thin films or extrusion coatings for high-barrier pharmaceutical blister packs. The segment contracts under EU Green Deal recyclable-by-2030 mandates.
- Coated Paper:Clay-coated or cast-coated surfaces optimized for high-fidelity lithographic reproduction in premium cosmetics and confectionery. Japanese converters dominate specialty grades for regional luxury brands.
Established volume favors paperboard; emerging adoption favors kraft paper with cellulose nanofiber barriers.
End Use:
Customer type splits between high-frequency replenishment categories and regulated serialization environments.
- Food & Beverage:Primary and secondary packaging for dry goods, frozen meals, and ready-to-drink beverages. E-commerce fulfillment centers in the United States demand right-sized formats with integrated return logistics.
- Pharmaceuticals:Cartonization of vials, blister packs, and auto-injectors with tamper-evident and child-resistant features. FDA track-and-trace regulations drive gravure-to-digital conversions for variable data serialization.
- Personal Care:Premium skincare and haircare cartons requiring extended gamut printing for seasonal SKU proliferation. Water-based flexography collapses cost thresholds versus gravure for medium runs.
- Consumer Electronics:Protective cartons for smartphones, wearables, and accessories with anti-static and cushioning inserts. China's SAMR packaging minimization rules tighten dimensional tolerances for e-commerce shipments.
Regulatory stringency concentrates in pharmaceuticals; margin expansion concentrates in personal care.
Closure Type:
Volume scale separates high-speed automated lines from manual assembly or specialty retail presentations.
- Locking:Interlocking tabs and friction-fit mechanisms for repeated access in pharmaceutical and nutraceutical applications. German pharmaceutical packagers prioritize certified recyclable substrates with locking integrity.
- Tuck:Straight-tuck and reverse-tuck styles dominating high-volume food and beverage runs on rotary cartoners. The format accelerates most quickly in India where organized retail expansion demands shelf-ready packaging.
- Foldable:Collapsible designs for flat-packed shipping and point-of-sale assembly in promotional displays. Regional craft brands specify short-run digital production for seasonal campaigns.
- Hang Tab:Integrated die-cut hooks for pegboard retail in hardware, electronics accessories, and impulse confectionery. The segment faces displacement from molded fiber trays in produce applications.
Speed economics favor tuck closures; customization value favors locking mechanisms.
Printing Technology:
Margin pool distribution reflects the collision of setup cost amortization against variable-data capability.
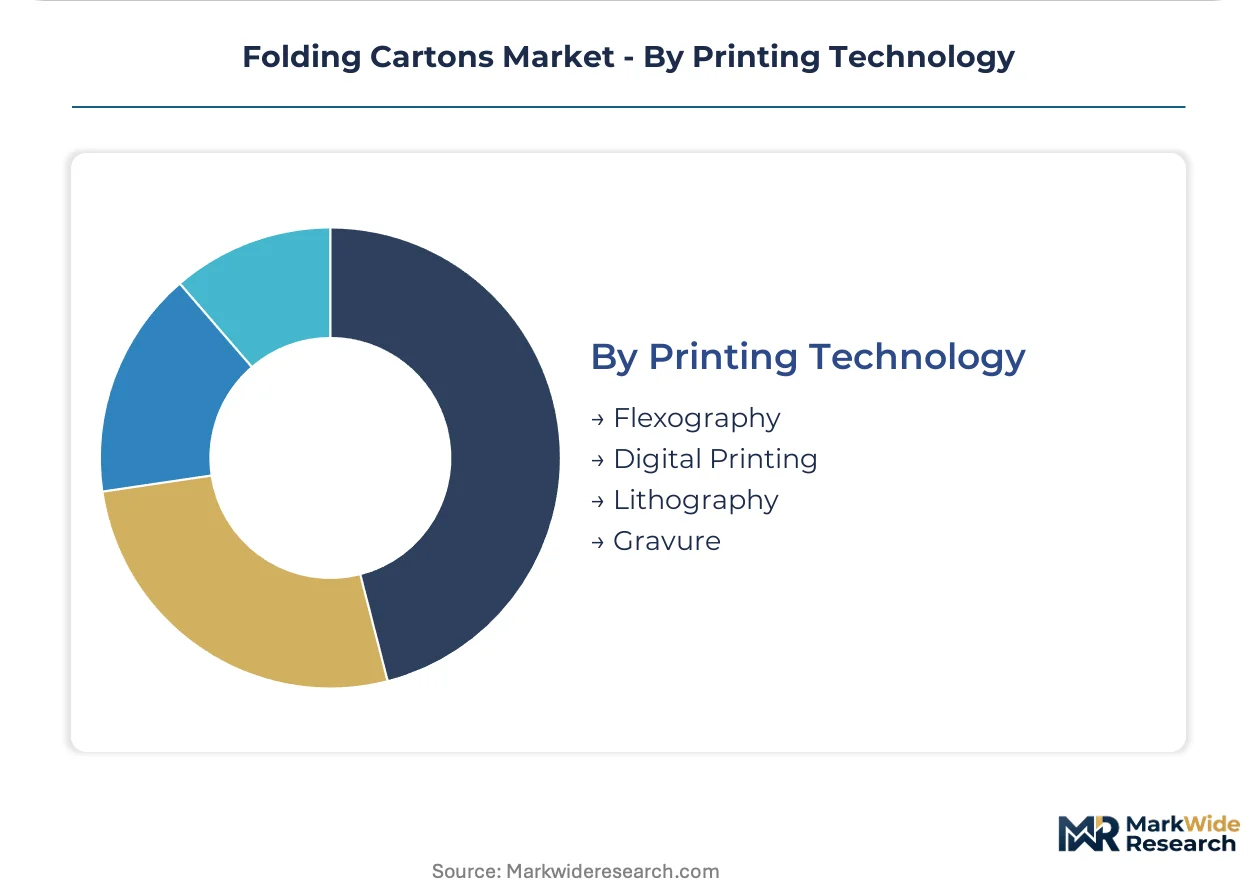
- Digital Printing:Inkjet and toner platforms enabling serialization, regional versioning, and short-run economics without cylinder engraving. Pharmaceutical brands in the United States and Europe adopt this for DSCSA and FMD compliance.
- Flexography:Water-based and UV-curable ink systems with extended gamut capability narrowing the quality gap versus gravure. The technology gains share fastest in cosmetics and nutraceuticals for seasonal SKU proliferation.
- Gravure:Cylinder-based high-volume production for long-run food and tobacco cartons with consistent color matching. Pulp price volatility compresses converter margins and extends equipment payback periods.
- Lithography:Offset printing for premium coated paper substrates in luxury goods and high-end confectionery. Japanese and German converters maintain specialist workforces for color consistency across hybrid presses.
Capital efficiency favors flexography; compliance capability favors digital.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters command pricing premiums through certified fiber sourcing that Southern European competitors cannot replicate. Indian demand accelerates fastest but at compressed margins due to fragmented supplier bases. Chinese regulatory tightening on e-commerce packaging dimensions reshapes carton specifications across Asia-Pacific supply chains.
Germany
Food retailers and pharmaceutical packagers prioritize certified recyclable substrates with locking integrity for tamper-evident applications. The EU Green Deal packaging mandates enforce recyclable-by-2030 requirements that eliminate multi-material laminates. The Rhine-Ruhr and Baden-Württemberg clusters concentrate hydro-pulping infrastructure for food-contact carton recovery.
United States
E-commerce fulfillment centers demand right-sized formats with integrated return logistics for direct-to-consumer channels. FDA track-and-trace regulations for pharmaceutical serialization accelerate gravure-to-digital printing conversions. The Midwest paperboard corridor around Wisconsin and Michigan anchors integrated mill-to-converter operations.
China
Consumer electronics brands require anti-static protective cartons with precise dimensional tolerances for cross-border shipments. SAMR enforcement on packaging minimization tightens specifications for e-commerce secondary packaging. The Yangtze River Delta manufacturing belt generates volume demand for flat-packed promotional displays.
India
Organized retail chains adopt shelf-ready packaging for private-label staples across dry goods and beverages categories. FSSAI food contact regulations govern barrier coating approvals for direct-food applications. The Maharashtra-Gujarat industrial corridor attracts first-mover converters with digital print and short-run capabilities.
Japan
Premium cosmetics and confectionery brands specify high-fidelity lithographic reproduction on clay-coated surfaces. METI circular economy guidelines promote enzymatic deinking compatibility for home-compostable certification. The Kanto and Kansai regions maintain specialist workforces for color consistency across hybrid gravure-digital presses.
Folding Cartons Market Vendor Landscape
Integrated paperboard producers and regional digital specialists split the market into consolidated upstream supply and fragmented downstream conversion tiers. Scale-driven players with captive pulp supply compete against agile converters serving craft brands with variable-data capabilities. The dominant competitive moves involve backward integration into substrate production and geographic expansion through mill acquisitions in high-growth Asian markets.
Within the integrated producer tier, Smurfit Westrock and Mondi Group exemplify scale-driven positioning through captive paperboard supply across North American and European markets. Huhtamaki occupies a specialist position serving regional craft brands with shorter digital print runs. These three entities represent the strategic spectrum from substrate-controlled cost leadership to agile customization capability.
| Leading Market Players |
|---|
| Huhtamaki |
| Mondi Group |
| Smurfit Westrock |
| Stora Enso Oyj |
| DS Smith Plc |
| Graphic Packaging International |
| Mayr-Melnhof Karton AG |
| Oji Holdings Corporation |
| International Paper Company |
| Others |
Supply Flow & Price Mechanics
German hydro-pulping infrastructure concentration for food-contact carton recovery anchors margin capture downstream, as converters with certified fiber sourcing command premiums that Southern European competitors cannot replicate. This upstream specialization shapes how pricing power distributes between integrated paperboard producers and fragmented regional converters.
Pricing Analysis
The customization-premium spread separates configured-to-order digital print runs from standard gravure production, with contract-based long-term offtake dominating volume procurement for multinational brand owners. Price differentiation hinges on certification grade (FSC chain-of-custody, EU Ecolabel) and volume scale, with smaller craft brands absorbing 15-25% premiums for short-run flexibility. Cost compression in standard grades is intensifying because pulp price volatility forces pass-through disputes. Private-label procurement teams at organized retailers exhibit highest price sensitivity, while premium cosmetics brands prioritize circularity metrics over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with integrated paperboard producers Smurfit Westrock and Mondi Group, which control captive pulp supply across Germany, the United States, and Sweden. Raw material dependencies draw from northern bleached softwood kraft pulp, clay-based barrier coatings, and enzymatic deinking chemistries. Single-source vulnerability concentrates in specialized hydro-pulping facilities limited to Germany, Sweden, and Finland. Distribution runs through direct mill-to-converter relationships for high-volume food and beverage accounts, supplemented by regional distribution hubs serving pharmaceutical and personal care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated multinational brand owners unbundling carton specifications from legacy print vendors, while fragmented regional craft brands create countervailing demand for agile conversion capacity.
For Market Incumbents: Pre-empt displacement from molded fiber trays and bag-in-box systems by securing certified fiber sourcing lock-ins with German retailer-led extended producer responsibility schemes. Backward integration into cellulose nanofiber barrier coating R&D defends margin position against commodity pulp volatility. Channel control through mill acquisitions in Maharashtra-Gujarat industrial corridor captures India organized retail expansion. For New Entrants and Emerging Players: India's Maharashtra-Gujarat corridor offers the most penetrable geography, where fragmented supplier bases and FSSAI food contact regulatory gaps create white-space for digital print specialists. Short-run craft beverage and regional organic food brands represent the least contested application segment. A direct-to-brand-owner go-to-market angle bypassing traditional print vendor relationships accelerates customer acquisition. For Investors and Strategic Acquirers: Capital is best deployed toward integrated mid-cap converters with hydro-pulping access and digital workflow capabilities, as these assets compound over the medium-term projection horizon. Watch for EU Green Deal packaging mandate enforcement timelines as the inflection signal triggering accelerated gravure-to-digital conversion capex cycles. Acquisition targets should demonstrate certified fiber sourcing and established relationships with German pharmaceutical packagers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Paperboard Mills | Captive pulp supply insulates Smurfit Westrock from commodity index volatility across North American markets. |
| Digital Print Platform Expansion | Huhtamaki's regional craft brand focus captures pharmaceutical serialization compliance demand in Europe. |
| Cellulose Nanofiber Barrier Development | Eliminates plastic layers entirely, enabling home-compostable certification for EU F-Gas Regulation compliance. |
| Geographic Manufacturing Footprint | India organized retail expansion by Reliance Retail and D-Mart creates first-mover advantage for local converters. |
| Sustainability Repositioning | Mondi Group's specialty kraft paper grades anchor frozen food shelf-life extension in Scandinavian markets. |
Methodological Framework
A standing panel of procurement directors at multinational consumer goods companies, plant managers at integrated paperboard mills, category buyers at German food retailers, and regulatory affairs leads at pharmaceutical packagers provided ongoing calibration. Primary interviews combined with secondary validation from EU Green Deal directive texts, FDA food contact notification databases, FSSAI barrier coating approval registers, and customs trade data for pulp and paperboard flows. Bottom-up volume modeling triangulated against top-down macroeconomic indicators.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning material type, end-use application, closure mechanics, and printing technology platform. CAGRs derived from installed converting equipment capacity, pulp price index trajectories, and regulatory compliance timeline assumptions. Forecast inputs incorporated e-commerce carton dimensional specification tightening by China's SAMR and extended producer responsibility fee structures in Germany.
Practitioners should monitor EU Green Deal packaging mandate enforcement, FDA track-and-trace regulation expansion, and pulp commodity index volatility for early signals requiring forecast revision. Quarterly review of hydro-pulping facility utilization rates and digital press installation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Carton Liners Market
Cartons
Global Folding Carton Packaging Market
Cartons
Thailand Folding Carton Packaging Market
Cartons
Beverage Cartons Market
Cartons
Japan Corrugated Boxes Market
Cartons
Metallized Folding Cartons Market
Cartons
Asia Pacific Folding Carton Market
Cartons
Child-Resistant Carton Box Market
Cartons
Cupcake Box Market
Cartons
Braille Cartons Packaging Market
Cartons
GCC Corrugated Box Packaging Market
Cartons
Global Cartonboard Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
Tetrahedron Carton Market
Cartons
Europe Corrugated Box Market
Cartons
Thailand Folding Cartons and Corrugated Packaging Market