
 Chipboard Box Market | 2026-2036
Chipboard Box Market Size, Share, and Industry Trends Forecast 2026-2036
Chipboard Box Market Outlook
India is narrowing the cost gap between domestic chipboard production and imported corrugated alternatives through expanded recycled fiber capacity. Smurfit Kappa leverages integrated pulp-to-box operations across multiple continents to sustain margin stability. DS Smith anchors its competitive position through specialized e-commerce packaging design capabilities that reduce dimensional weight penalties.
Chipboard boxes are paper-based rigid or semi-rigid containers manufactured from layered recycled paperboard typically ranging from 0.4 to 2.5 mm thickness, formed through calendering, lamination, and die-cutting processes to provide structural protection for consumer goods during transit and shelf presentation. Folding boxes occupy the largest volume share due to their flat-ship efficiency and automated assembly compatibility with high-speed packaging lines. Die-cut boxes represent the fastest-growing product type as unboxing experience design becomes a priority for direct-to-consumer brands seeking differentiation through custom insert configurations.
EPA recycled content guidelines and EU REACH chemical compliance frameworks shape material certification requirements for export-bound chipboard packaging. FDA food contact substance regulations govern barrier coatings used in food-grade chipboard applications. Stakeholders must monitor evolving extended producer responsibility schemes that will determine cost allocation between packaging manufacturers and brand owners.
Market Dynamics
E-commerce fulfillment networks are compressing packaging cycle times while EU recycled content mandates force material recertification across export supply chains. The collision of dimensional weight optimization and regulatory compliance is restructuring sourcing decisions.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recycled fiber mandates under the revised PPWR framework are pulling investment into domestic chipboard capacity across Central European manufacturing zones.
- Automated fulfillment centers:High-speed pick-and-pack operations favor die-cut chipboard configurations that integrate with robotic handling systems and reduce manual assembly labor.
- Lightweighting imperatives:Parcel carriers' dimensional weight pricing models are accelerating substitution from heavier corrugated alternatives to calendered chipboard below 1.2 mm thickness.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container price swings in European spot markets compress converter margins during demand surges.
- Barrier coating supply concentration:Polyethylene extrusion capacity for moisture-resistant food-grade applications clusters among specialized chemical processors in Germany and Benelux.
- REACH chemical compliance:ECHA substance evaluation cycles extend material qualification timelines for export-bound packaging by 8-14 months.
Strategic Opportunities
- Indian e-commerce expansion:Domestic platform fulfillment networks in Maharashtra and Karnataka are underpenetrated by structured chipboard suppliers versus corrugated incumbents.
- Pharmaceutical cold chain:Insulated chipboard with phase-change material integration addresses temperature-controlled last-mile delivery for biologics distribution.
- Extended Producer Responsibility schemes:French and German EPR fee structures reward lightweight recyclable packaging with reduced compliance levies versus plastic alternatives.
Industry Challenges
- Digital print integration:Converter workforce gaps in variable-data inkjet operation and color management slow short-run customization adoption.
- Legacy ERP migration:Mid-tier box plants face capex burdens replacing die-cutting scheduling software to support lot-size-one production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chipboard Box Market |
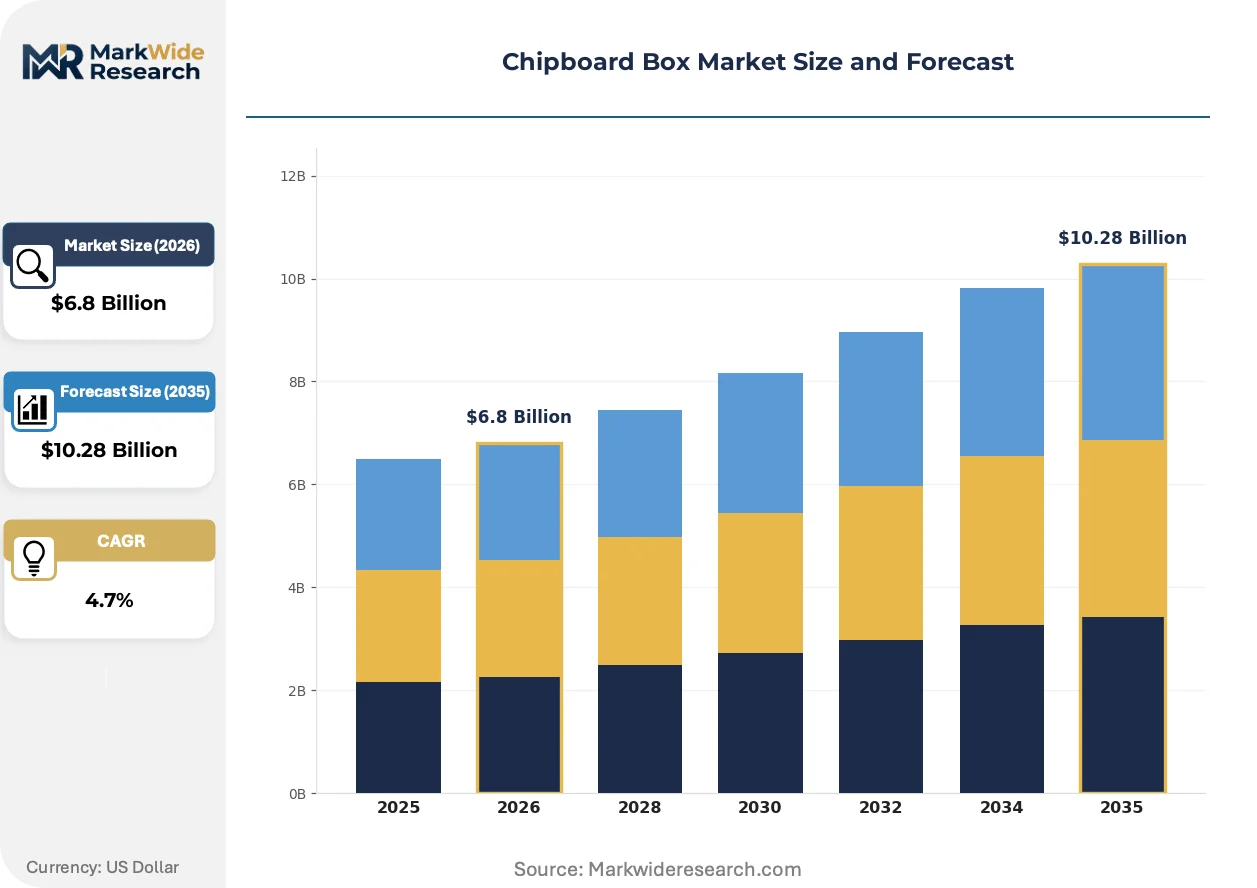
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Die-Cut Boxes, Folding Boxes, Rigid Boxes, Specialty Boxes End User: Retail, E-Commerce, Food & Beverage, Electronics Grade: Recycled, Virgin, High-Density, Low-Density Application: Packaging, Shipping, Storage, Display |
| Companies Covered | Smurfit Kappa, DS Smith, GMS Industries, International Paper, Packaging Corporation of America, WestRock, Mondi Group, Stora Enso, Graphic Packaging International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chipboard Box Market Strategic Shifts
Digital manufacturing workflows and bio-based barrier technologies are collapsing traditional trade-offs between customization speed and unit economics. These shifts are redrawing competitive boundaries between commodity converters and specialized solution providers.
Water-based barrier coatings derived from cellulose nanofibrils are rendering obsolete conventional polyethylene-laminated chipboard in premium food contact applications. Specialty coffee and craft chocolate brands in Scandinavia are specifying these substrates at 15-20% volume premiums. The technology is compressing qualification cycles from 18 months to under 6 months for export-ready packaging.
REACH Annex XIV authorization requirements for fluorinated substances are forcing reformulation of grease-resistant coatings used in fast-food chipboard clamshells. ECHA's 2023 restriction proposal on PFAS is accelerating migration to plant-based alternatives. German quick-service restaurant chains are pre-qualifying bio-wax barriers to secure supply continuity ahead of enforcement deadlines.
Direct-to-brand procurement platforms are disintermediating traditional merchant distributor networks for standardized folding box formats. Mid-sized cosmetics companies in France and Italy are sourcing 10,000-unit runs through online configurators with 72-hour turnaround guarantees. This channel shift is most visible in personal care verticals where packaging aesthetic refresh cycles have compressed from annual to quarterly rhythms.
Chipboard Box Market Segmentation
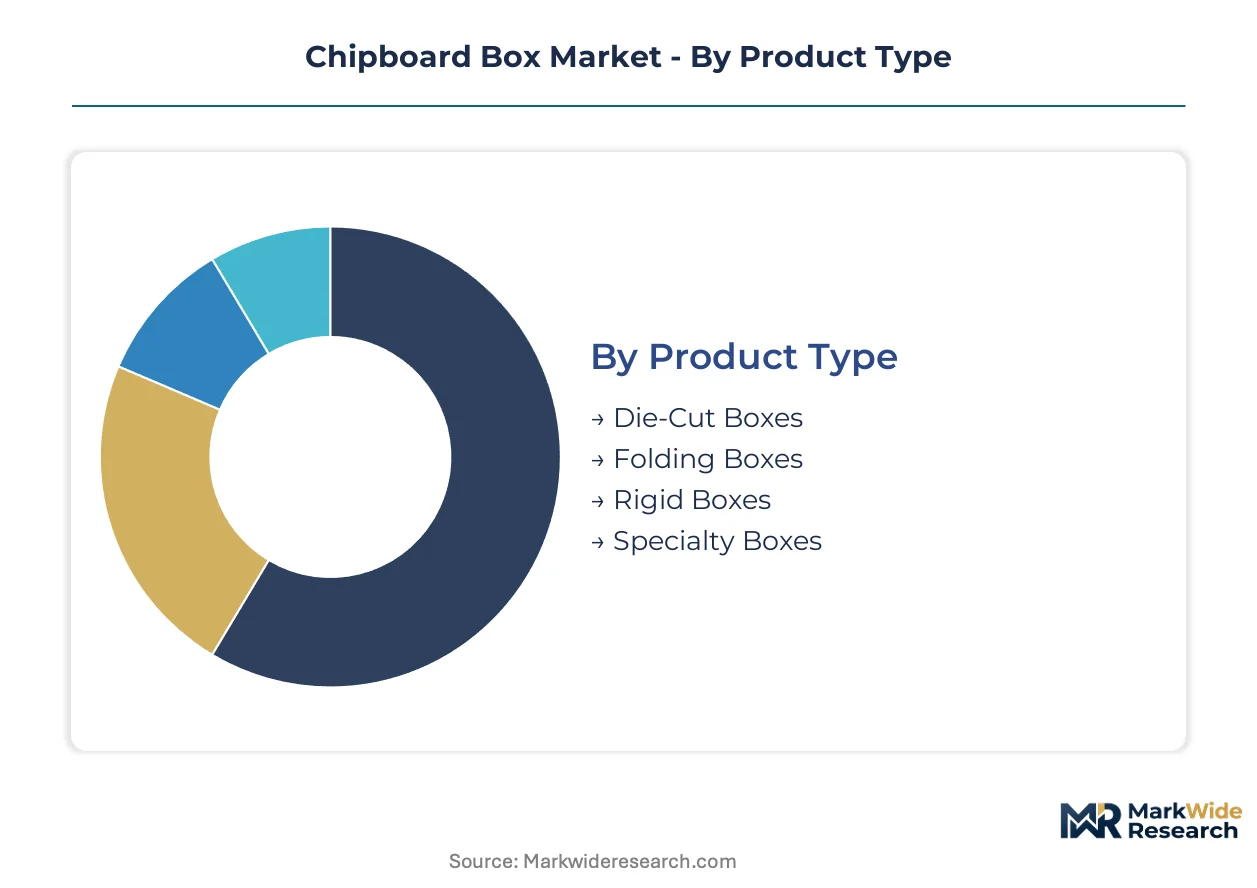
Chipboard box segmentation reveals divergent margin profiles and capital intensity across product architectures, with cycle times ranging from same-day digital print runs to multi-week rigid box tooling programs. Understanding these velocity differentials shapes capacity planning and customer targeting for converters navigating compressed e-commerce fulfillment windows.
Product Type:
Cycle times compress dramatically from rigid box multi-week tooling to folding box same-day digital runs, with die-cut formats occupying the middle ground where unboxing customization justifies moderate lead times.
- Folding Boxes:Flat-ship configurations manufactured from 0.4–1.2 mm calendered paperboard enable automated high-speed assembly on packaging lines. Demand concentrates in German retail cosmetics and pharmaceutical blister pack applications where shelf-ready presentation meets logistics efficiency. The format's compatibility with existing corrugated converting infrastructure sustains margin stability during volume surges.
- Die-Cut Boxes:Custom-contoured structures formed through steel-rule die processing accommodate complex insert geometries for product protection. Direct-to-consumer brands in France and Italy specify these for quarterly packaging refreshes that differentiate unboxing experiences. E-commerce fulfillment centers favor die-cut formats for robotic pick-and-pack compatibility.
- Rigid Boxes:Thick-walled structures built from laminated greyboard wrapped in printed paper or fabric, requiring dedicated tooling and hand-finishing stages. Premium spirits and luxury watch brands in Switzerland specify these for gift-set applications.
- Specialty Boxes:Engineered configurations including telescoping lids, hinged closures, or magnetic catches for archival and presentation functions. Museum conservation supply chains in the Netherlands represent a concentrated niche.
Folding boxes anchor the volume base while die-cut boxes gain share at the steepest rate.
End User:
Cost tiers stratify sharply between commodity shipping applications and value-added retail presentation, with regulatory compliance layering additional qualification burdens on food contact and electronics segments.
- E-Commerce:Direct-to-consumer fulfillment drives specifications for dimensional weight optimization below 1.2 mm calendered thickness. Indian platform networks in Maharashtra and Karnataka represent underpenetrated demand relative to corrugated incumbents. Automated sortation systems require crush-resistant structures that survive multiple handling cycles.
- Food & Beverage:Barrier-coated configurations for moisture and grease resistance face REACH chemical compliance timelines extending material qualification by 8–14 months. Scandinavian specialty coffee brands specify cellulose nanofibril coatings at volume premiums for sustainable positioning.
- Retail:Shelf-ready packaging with high-graphic litho lamination serves mass-market cosmetics and consumer electronics. German drugstore chains drive standardization toward modular footprint efficiencies.
- Electronics:Anti-static and cushioning-integrated designs protect high-value components during international distribution. Semiconductor packaging in South Korea demands particulate-controlled cleanroom-compatible materials.
E-Commerce commands the largest procurement volumes while food and beverage applications expand most quickly under regulatory pressure for plastic substitution.
Grade:
Supply concentration varies dramatically across fiber sourcing models, with recycled content mandates under EU PPWR reshaping availability curves for virgin and high-density alternatives.
- Recycled:Post-consumer fiber content ranging from 80–100% satisfies EU packaging waste regulation mandates for circular economy compliance. Central European converting corridors near German OCC collection hubs benefit from logistics-advantaged fiber flows.
- Virgin:Unbleached or bleached kraft fiber delivers superior print surface and structural consistency for high-graphic retail applications. Food-grade specifications requiring FDA compliance for direct contact drive residual demand.
- High-Density:Calendered structures above 1.5 mm thickness provide stack strength for heavy-goods distribution. Industrial parts packaging in Belgium and the Netherlands favors these specifications.
- Low-Density:Lightweight configurations below 0.8 mm optimize parcel economics under dimensional weight pricing. Fast-fashion reverse logistics in the UK deploy these for return-ready garment mailers.
Recycled grade dominates procurement tonnage while high-density specifications climb the fastest under industrial heavy-goods requirements.
Application:
Customer type fragmentation separates high-velocity shipping specifications from engineered storage and display applications with divergent durability and aesthetic requirements.
- Packaging:Primary and secondary containment functions spanning consumer goods protection through retail shelf presentation. EU EPR fee structures in France and Germany reward lightweight recyclable formats with reduced compliance levies versus plastic alternatives.
- Shipping:Transit-optimized designs emphasizing cube efficiency and damage resistance across multi-node distribution networks. Parcel carrier dimensional weight models accelerate substitution from corrugated alternatives.
- Storage:Archival-grade acid-free configurations for document preservation and museum collection management. Institutional procurement in Italy and Spain concentrates demand for conservation-certified materials.
- Display:Temporary point-of-sale structures with high-impact graphics and rapid assembly features for promotional campaigns. Seasonal retail cycles in the UK drive concentrated demand windows.
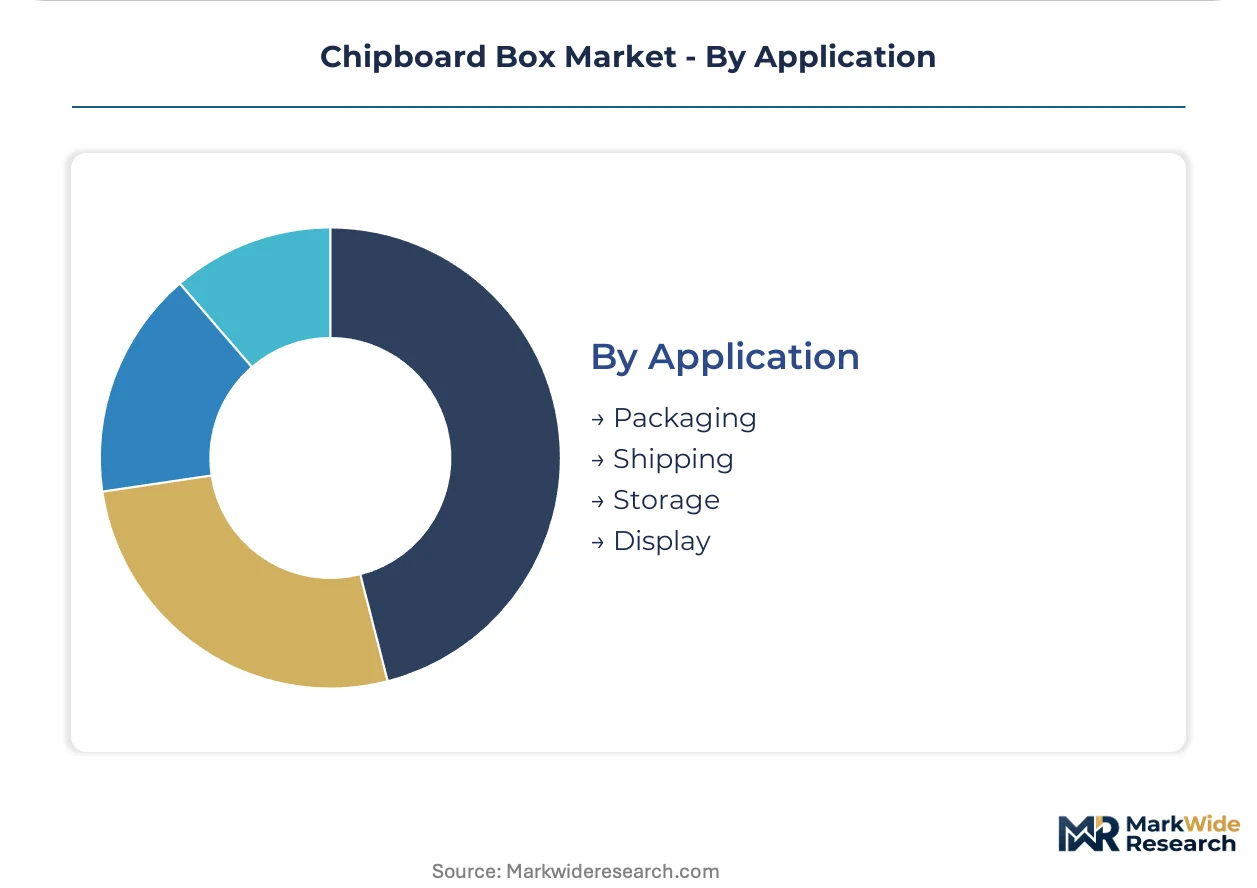
Packaging absorbs the majority of volume while display applications gain share fastest under compressed promotional refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes chipboard boxes predominantly for industrial protective packaging, while India deploys them for e-commerce fulfillment and the United States emphasizes retail shelf-ready formats. This consumption-mix differential shapes regional investment patterns and regulatory compliance priorities.
Germany
Automotive component suppliers in Baden-Württemberg specify high-density chipboard for precision parts distribution, driving demand for calendered structures above 1.5 mm. The EU Packaging and Packaging Waste Regulation mandates recycled fiber thresholds that reshape converter sourcing across Bavaria's industrial corridor. Stuttgart's machine-building cluster anchors domestic capacity expansion for heavy-goods specifications.
India
Maharashtra's platform fulfillment networks in Mumbai-Pune corridor are narrowing the cost gap between domestic chipboard and imported corrugated alternatives. BIS certification requirements for food-grade packaging extend material qualification timelines for export-bound converters. Karnataka's recycled fiber capacity expansion near Bangalore is pulling investment away from traditional corrugated incumbents.
United States
EPA recycled content guidelines govern barrier coating specifications for food-contact chipboard applications, particularly in California's specialty coffee roasting cluster. FDA regulations on direct food contact drive residual demand for virgin fiber grades in premium retail formats. The Pacific Northwest's e-commerce logistics hubs favor lightweight configurations under parcel carrier dimensional weight pricing models.
France
Extended producer responsibility fee structures reward lightweight recyclable packaging with reduced compliance levies versus plastic alternatives in Île-de-France cosmetics distribution. ANSM food contact substance evaluations extend material qualification cycles for pharmaceutical blister pack applications. Lyon-Auvergne's industrial packaging corridor concentrates demand for automated assembly-compatible folding box formats.
Netherlands
Museum conservation supply chains in Amsterdam-Rotterdam corridor drive niche demand for archival-grade acid-free chipboard configurations. REACH chemical compliance frameworks reshape barrier coating sourcing for moisture-resistant applications. Randstad's pharmaceutical distribution networks specify insulated chipboard with phase-change material integration for biologics cold chain requirements.
Chipboard Box Market Competitive Environment
Capability concentration sits with integrated pulp-to-box operators; scale advantage sits with merchant converters serving fragmented end-use demand. The market structures around three tiers: multinational integrated producers with captive fiber supply, regional specialists in die-cut customization, and commodity converters competing on corrugated infrastructure overlap. Strategic moves center on backward integration into recycled fiber collection and geographic expansion into underpenetrated e-commerce fulfillment corridors.
Within the integrated producer tier, Smurfit Kappa and DS Smith exemplify operations spanning multiple continents with margin stability through captive pulp supply. Mondi Group occupies a position among diversified packaging conglomerates with exposure to both industrial protective and retail presentation segments. These anchors represent the capability-scale tradeoff that defines competitive positioning: integrated fiber control versus customization velocity.
| Leading Market Players |
|---|
| Smurfit Kappa |
| DS Smith |
| GMS Industries |
| International Paper |
| Packaging Corporation of America |
| WestRock |
| Mondi Group |
| Stora Enso |
| Graphic Packaging International |
| Others |
Value Chain & Pricing Dynamics
Stuttgart's machine-building cluster anchors German capacity for high-density chipboard above 1.5 mm, concentrating pricing power among converters serving automotive component suppliers in Baden-Württemberg. This geographic concentration feeds downstream cost structures across Central European manufacturing zones, where recycled fiber mandates under EU PPWR reshape input cost allocation between virgin and post-consumer grades.
Pricing Analysis
European spot markets for old corrugated containers exhibit 15-25% price spreads between Nordic collection hubs and Mediterranean ports, compressing converter margins unevenly across the continent. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—REACH-compliant food-contact coatings command substantial premiums over industrial shipping specifications. Pricing pressure stems from Indian domestic capacity expansion narrowing cost gaps with imported alternatives. Commodity e-commerce fulfillment buyers exhibit highest price sensitivity; pharmaceutical cold-chain specifications show lowest.
Supply Chain Analysis
REACH chemical compliance frameworks function as de facto export controls, restricting barrier coating flows to qualified converters meeting ECHA substance evaluation timelines. Supply concentrates in Germany, Belgium, and the Netherlands for polyethylene extrusion capacity serving moisture-resistant food-grade applications. Raw material dependencies center on post-consumer OCC flows, cellulose nanofibril coating precursors, and phase-change materials for insulated configurations. Single-source vulnerability clusters among specialized chemical processors in Benelux. Distribution runs through merchant converter networks and direct-to-brand procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as direct-to-brand procurement platforms disintermediate traditional distributor networks, compressing refresh cycles from annual to quarterly rhythms in cosmetics and personal care verticals.
For Market Incumbents: Entrench position through backward integration into recycled fiber collection near German OCC hubs, securing margin stability against Old Corrugated Container price volatility. Add die-cutting automation capacity in Maharashtra to defend against Indian domestic challengers narrowing cost gaps. Prioritize cellulose nanofibril coating certification investments ahead of PFAS restriction enforcement deadlines.
For New Entrants and Emerging Players: Pursue white-space opportunities in Karnataka's platform fulfillment networks, where structured chipboard penetration lags corrugated incumbents. Target pharmaceutical cold-chain specifications in Randstad biologics distribution, where insulated chipboard with phase-change material integration remains underdeveloped. Lead with 72-hour digital print turnaround capabilities through online configurators.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because merchant converter fragmentation across mid-tier box plants creates roll-up opportunities for ERP modernization and lot-size-one production capability. Target die-cut customization specialists with robotic handling compatibility. Watch EPR fee structure harmonization across France and Germany as inflection signal for lightweight recyclable packaging adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Collection | Captive OCC supply near Stuttgart insulates margins from European spot market volatility. |
| Digital Manufacturing Workflow Deployment | Variable-data inkjet capability enables 72-hour turnaround for quarterly packaging refreshes. |
| Bio-Based Barrier Coating Qualification | Cellulose nanofibril certification secures premium positioning ahead of PFAS restrictions. |
| Geographic Expansion into Indian E-Commerce Corridors | Maharashtra and Karnataka fulfillment networks remain underpenetrated by structured chipboard suppliers. |
| ERP Migration for Lot-Size-One Production | Modernized die-cutting scheduling software supports short-run customization at commodity economics. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with packaging procurement managers at e-commerce fulfillment networks, converter plant managers in German industrial corridors, barrier coating R&D directors at specialty chemical processors, and brand owners in cosmetics and specialty food verticals. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, ECHA substance evaluation databases, BIS certification records for Indian food-grade applications, and customs trade data for OCC fiber flows. Bottom-up capacity assessments triangulated against top-down demand modeling across end-use segments.
Calibration anchored volume and value outputs to historical capacity utilization rates at integrated pulp-to-box operations, with segmentation modeled across product architecture, grade tier, end-use industry, and regional production hub. CAGRs were derived from elasticity-adjusted demand projections incorporating e-commerce fulfillment velocity trends and regulatory compliance cost pass-through assumptions. Industry-specific forecast inputs included dimensional weight pricing model adoption curves and EPR fee structure implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in parcel carrier fuel surcharges, recycled fiber spot prices, or EU carbon border adjustment mechanisms would shift the trajectory. Forecasts reflect documented assumptions on PPWR recycled content threshold enforcement and REACH authorization timelines. Material shifts in PFAS restriction scope or Indian domestic capacity commissioning schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Carrier Bags Market
Paper & Paperboard Packaging
Paper Bubble Wrap Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Countertop Paper Napkin Dispenser Market
Paper & Paperboard Packaging
Tea Filter Paper Market
Paper & Paperboard Packaging
Paper Release Liners Market
Paper & Paperboard Packaging
Silicone Release Paper Market
Paper & Paperboard Packaging
Global Cooking and Baking Papers Market
Paper & Paperboard Packaging
Paper Waste Strippers Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Postal Tubes Market
Paper & Paperboard Packaging
France Paper Packaging Market