
 Machine Glazed Paper Market | 2026-2036
Machine Glazed Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Glazed Paper Market Analysis
Maintenance and technical service contracts is rebalancing how machine glazed paper producers capture recurring revenue beyond tonnage sales. Mondi Group leverages its integrated pulp-to-paper infrastructure across Central European mills to sustain margin stability. BillerudKorsnäs anchors its competitive stance through specialty-grade R&D intensity in Nordic operations. Stora Enso differentiates via bio-based coating innovations that reduce petrochemical dependency.
Machine glazed paper denotes a supercalendered kraft paper with one highly polished surface and one matte surface, typically manufactured from bleached or unbleached sulfate pulp at basis weights between 30 and 80 gsm for superior printability and barrier performance. Its primary commercial purpose centers on premium packaging, release liner substrates, and decorative applications requiring controlled gloss and dimensional stability. Uncoated paper grades dominate volume throughput in mature European markets where cost-sensitive industrial wrapping prevails. Specialty paper segments command disproportionate margin pools in Japan and South Korea through precision-release applications for electronics and medical adhesives.
EMA chemical safety assessments and EU Green Deal packaging directives tighten material traceability requirements across European machine glazed paper supply chains. REACH substance restrictions and F-Gas Regulation phase-outs compel coating chemistry reformulation toward water-based and bio-derived alternatives. Stakeholders must monitor how ECHA substance evaluation timelines intersect with converter qualification cycles to avoid supply disruptions.
Market Dynamics
REACH substance restrictions and EU Green Deal packaging mandates are forcing coating chemistry reformulation across European machine glazed paper supply chains, compressing qualification timelines and elevating technical service intensity as a competitive differentiator.
Growth Catalysts
- REACH Compliance Deadlines:European converters accelerate material substitutions away from plastic films toward machine glazed paper substrates. Food industry buyers in Germany and France expand sustainable packaging adoption.
- Electronics Release Liner Demand:Precision-release applications for medical adhesives and electronics manufacturing concentrate margin pools in Japan and South Korea. Specialty-grade specifications command premium positioning.
- Water-Based Coating Chemistry:Bio-derived barrier formulations reduce petrochemical dependency while maintaining printability standards. Nordic mills invest in integrated pulp-to-paper infrastructure to sustain margin stability.
Market Restraints
- Sulfate Pulp Input Volatility:Energy-intensive kraft pulping exposes producers to natural gas and electricity price swings. Central European mills face compressed operating leverage during input cost spikes.
- Coating Supplier Concentration:Specialty chemical providers for release coatings cluster in Germany and Switzerland. Qualification bottlenecks emerge when ECHA substance evaluations intersect with converter approval cycles.
- Plastic Film Substitution Limits:High-moisture barrier applications retain synthetic substrates where machine glazed paper performance gaps persist. Technical specifications in frozen food packaging resist full material conversion.
Strategic Opportunities
- Indian Pharmaceutical Packaging:CDSCO serialization mandates and cold-chain expansion create demand for release liner substrates in transdermal patch manufacturing. Domestic converter capacity remains underdeveloped.
- F-Gas Regulation Phase-Out:EU regulatory pressure on fluorinated barrier chemistries opens market share for bio-based coating innovators. Water-based alternatives capture qualification windows ahead of compliance deadlines.
- Digital Print Compatibility:Hybrid inkjet-flexo convergence enables short-run premium packaging without plate costs. Brand owners in Italian and Spanish markets test variable-data decorative applications.
Industry Challenges
- Coating Formulation Expertise Scarcity:Water-based barrier chemistry development requires polymer science and paper physics cross-training. European mills compete for limited talent pools with specialty chemical sectors.
- Dual Certification Burden:Food-contact compliance under EFSA frameworks and pharmaceutical-grade release liner qualifications demand parallel documentation systems. Converter audits extend lead times by four to six months.
- Legacy Calendering Asset Retrofit:Supercalendering equipment designed for solvent-based coating lines requires capital-intensive modification for water-based chemistry compatibility. Mid-cap producers face constrained balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Glazed Paper Market |
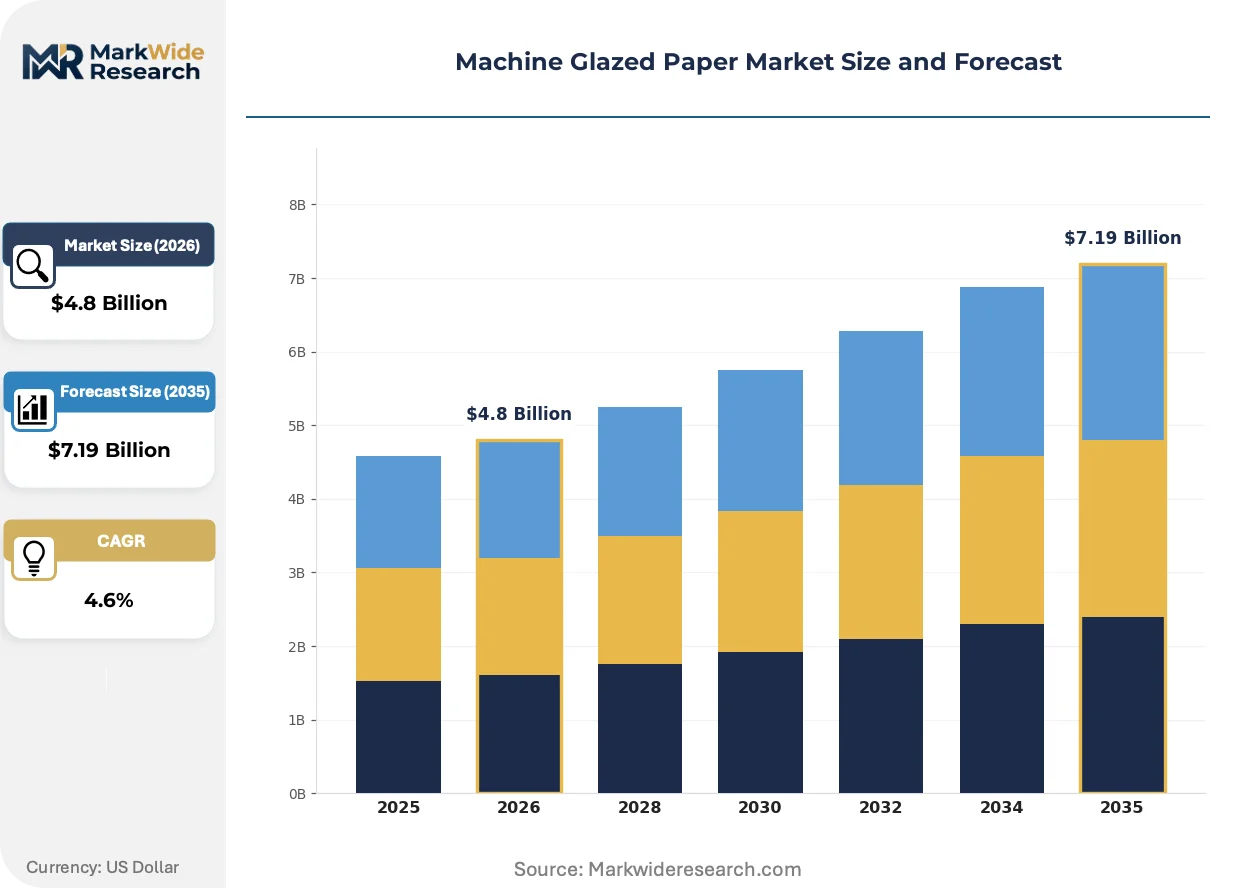
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Paper, Uncoated Paper, Recycled Paper, Specialty Paper End User: Packaging Industry, Stationery, Printing and Publishing, Food Industry Application: Gift Wrapping, Labels, Book Covers, Notebooks Thickness: Lightweight, Medium Weight, Heavy Weight, Extra Heavy Weight |
| Companies Covered | Mondi Group, BillerudKorsnäs, Nippon Paper Industries, Stora Enso, Smurfit Kappa Group, International Paper, Sappi Limited, Segezha Group, Oji Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Glazed Paper Market Emerging Trajectories
Bio-based coating technologies and digital print infrastructure are restructuring how machine glazed paper producers capture value beyond commodity tonnage, while regulatory chemistry mandates compress product development timelines.
Water-based bio-derived barrier coatings is overtaking solvent-based petrochemical formulations in European food-contact applications. German and French premium packaging converters specify these substrates for sustainable brand positioning. The technology is overtaking incumbent coating systems by eliminating F-Gas Regulation compliance exposure while maintaining grease resistance and heat-seal performance.
F-Gas Regulation phase-out timelines and REACH substance evaluation acceleration are compelling coating chemistry reformulation across EU supply chains. ECHA substance restriction proposals target persistent organic pollutants in conventional release liners. Specialty-grade producers in Nordic operations respond with accelerated R&D intensity to secure qualification ahead of converter specification lock-ins.
Brand owner sustainability scorecards now weight packaging material circularity in supplier selection criteria. Italian and Spanish food industry buyers prioritize machine glazed paper with certified fiber sourcing and recyclable barrier systems. Procurement teams in premium confectionery and ready-meal segments consolidate supplier bases around integrated pulp-to-paper producers with verified chain-of-custody documentation.
Machine Glazed Paper Market Segmentation
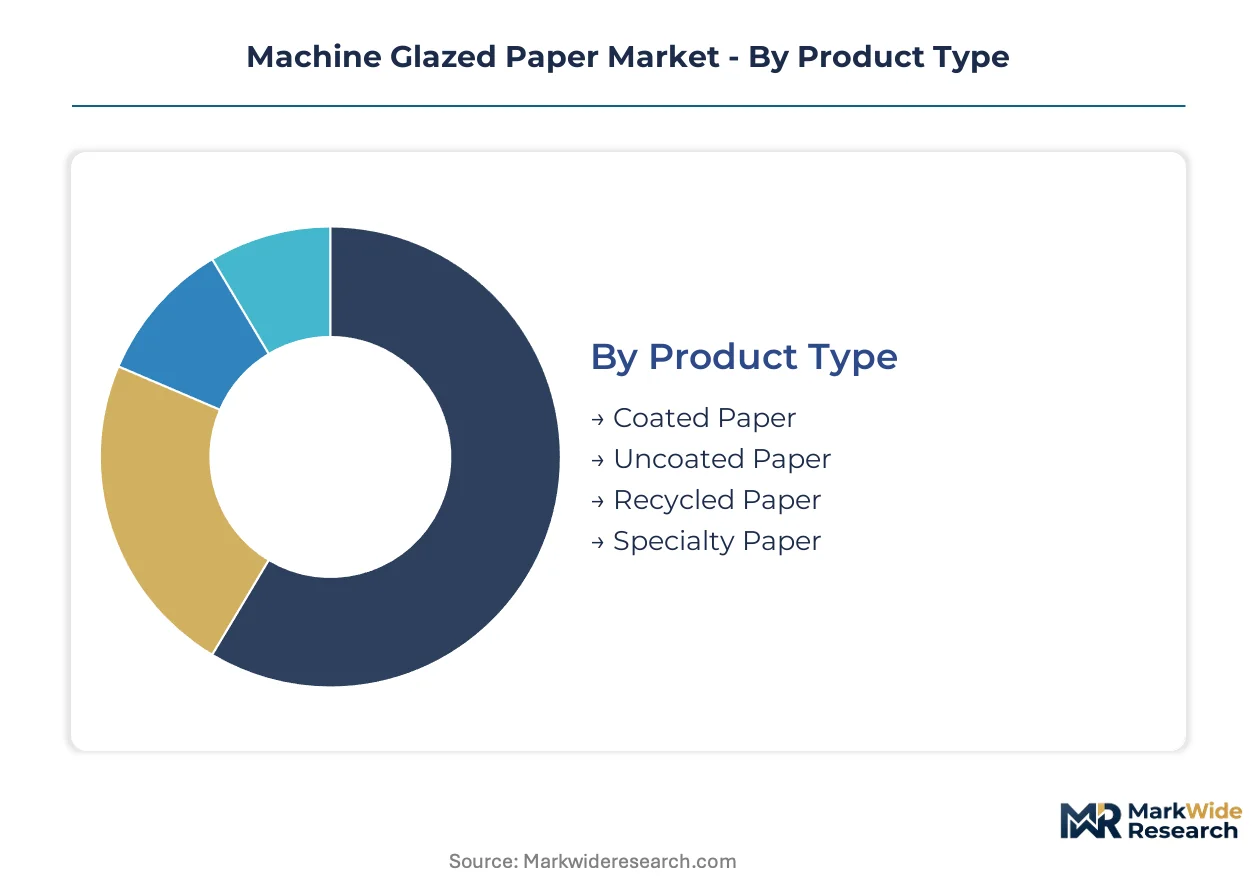
Machine glazed paper producers calibrate product portfolios across four intersecting dimensions—surface finish, end-use performance, decorative function, and caliper specifications—to capture divergent margin pools in packaging and industrial release applications.
Product Type:
Customization intensity spans from commodity uncoated grades to engineered specialty surfaces requiring polymer science integration.
- Uncoated Paper:Supercalendered kraft with natural matte finish serves cost-sensitive industrial wrapping and basic protective packaging. Demand concentrates in German and French converters supplying bakery and dry goods sectors where grease resistance requirements remain moderate.
- Specialty Paper:Precision-calendered substrates with controlled release properties anchor electronics and medical adhesive applications in Japan and South Korea. Premium positioning reflects exacting silicone hold-out specifications and dimensional stability under thermal stress.
- Coated Paper:Clay or bio-based barrier coatings enhance printability for premium confectionery and cosmetics packaging.
- Recycled Paper:Post-consumer fiber content meets sustainability procurement criteria in Italian and Spanish brand owner scorecards.
Leading the category by volume: Uncoated Paper. Expanding most quickly: Specialty Paper.
End User:
Customer technical requirements stratify from standardized industrial procurement to regulated food-contact compliance systems.
- Food Industry:REACH-compliant substrates with water-based barrier coatings displace plastic films in ready-meal and premium confectionery segments. German buyers specify certified fiber chain-of-custody documentation under EU Green Deal packaging directives.
- Packaging Industry:Release liner substrates for transdermal patches and electronics manufacturing command qualification-intensive supply relationships. CDSCO serialization mandates in Indian pharmaceutical cold chains drive substrate specification tightening.
- Printing and Publishing:Digital print-compatible surfaces enable short-run decorative applications without plate costs.
- Stationery:Notebook and office product manufacturers prioritize cost-optimized medium-weight calipers.
Volume concentration: Packaging Industry. Steepest expansion trajectory: Food Industry.
Application:
Functional performance requirements range from aesthetic presentation to adhesive engineering precision.
- Labels:Pressure-sensitive adhesive substrates demand controlled release force consistency across temperature and humidity bands. Nordic mills invest in supercalendering asset retrofit to meet water-based coating compatibility requirements.
- Gift Wrapping:High-gloss polished surfaces with decorative printability anchor premium retail positioning in Italian and Spanish markets.
- Book Covers:Durable scuff-resistant finishes protect educational and trade publications through distribution handling.
- Notebooks:Matte writing surfaces balance ink absorption with tactile quality for stationery brands.
Dominant volume segment: Labels. Gaining share fastest: Gift Wrapping.
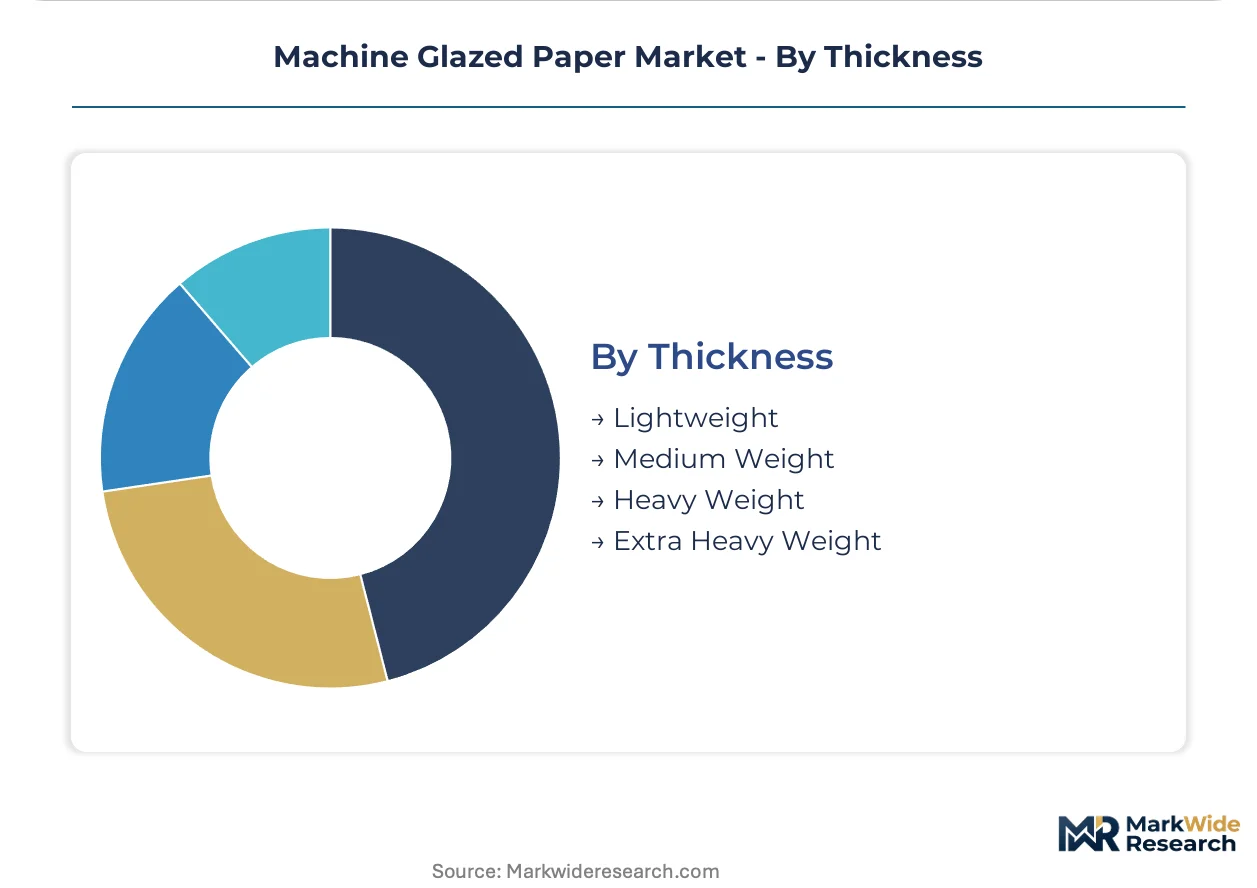
Thickness:
Caliper selection maps directly to structural rigidity requirements and converting equipment compatibility.
- Lightweight:30-45 gsm basis weights serve label face stock and flexible wrapping applications where conformability matters.
- Medium Weight:45-60 gsm specifications balance printability with handling durability for notebook and publishing applications.
- Heavy Weight:60-80 gsm calipers provide structural integrity for rigid box wrapping and premium gift packaging.
- Extra Heavy Weight:Above-80 gsm specialty grades address industrial release liner and protective interleaving functions.
Volume leadership: Medium Weight. Climbing the fastest: Heavy Weight.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf and the Rhine-Ruhr industrial corridor anchor European machine glazed paper procurement, with converter clusters demanding REACH-compliant substrates for premium food packaging applications.
Germany
Bavarian confectionery brands and Baden-Württemberg automotive suppliers drive specialty-grade demand for precision-release liners. ECHA substance evaluation timelines compress qualification windows for water-based coating formulations. The Stuttgart industrial zone concentrates converter capacity for medical adhesive substrates.
France
Parisian luxury packaging houses and Lyonnaise ready-meal producers specify certified fiber chain-of-custody documentation. EU Green Deal packaging directives mandate plastic film substitution in food-contact applications. The Grand Est region hosts integrated pulp-to-paper mills serving premium chocolate and cosmetics segments.
Japan
Osaka-Kobe electronics manufacturers and Tokyo medical device clusters command exacting silicone hold-out specifications for release liner substrates. METI industrial standards govern dimensional stability under thermal stress. The Chubu region around Nagoya concentrates precision-calendering capacity for semiconductor tape applications.
South Korea
Seoul Capital Area display panel producers and Busan pharmaceutical exporters anchor demand for specialty-grade machine glazed paper. MFDS medical device regulations tighten substrate qualification requirements for transdermal patch manufacturing. The Gyeonggi-do corridor houses converter operations serving regional electronics supply chains.
India
Maharashtra pharmaceutical exporters and Gujarat food processors expand substrate adoption for serialization-compliant packaging. CDSCO mandates for cold-chain traceability drive release liner specification tightening. The Mumbai-Pune industrial belt develops domestic converter capacity for transdermal patch substrates.
Machine Glazed Paper Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the machine glazed paper value chain. Integrated pulp-to-paper operators maintain margin stability through captive fiber supply, while specialty coating developers capture premium positioning through formulation expertise. Three archetypes dominate: Nordic integrated producers with backward timber control, Central European mid-cap specialists with regional converter relationships, and Asia-Pacific precision-grade developers serving electronics release applications. Capacity expansion and water-based coating chemistry partnerships constitute the primary competitive moves.
Among Nordic integrated producers, Stora Enso and BillerudKorsnäs occupy positions exemplifying bio-based coating innovation archetypes, while Mondi Group represents the Central European integrated mill model with Rhine-Ruhr logistics proximity. These three entities anchor tiered competitive positioning without dominating share concentration.
| Leading Market Players |
|---|
| Mondi Group |
| BillerudKorsnäs |
| Nippon Paper Industries |
| Stora Enso |
| Smurfit Kappa Group |
| International Paper |
| Sappi Limited |
| Segezha Group |
| Oji Holdings Corporation |
| Others |
Supply Flow & Price Mechanics
Specialty-grade certification divergence separates premium machine glazed paper from commodity uncoated grades, with REACH-compliant water-based coatings commanding supply chain prioritization from Nordic integrated mills while cost-sensitive industrial buyers in Germany and France source standard kraft through spot-market channels. This tier split manifests in contract structures: premium converters lock multi-year offtake agreements with pulp-to-paper operators, whereas commodity procurement runs through distributor networks with volatile sulfate pulp pass-through clauses.
Pricing Analysis
Cost-down pressure on uncoated grades accelerates because energy-intensive kraft pulping exposes Central European mills to natural gas price spikes, compressing operating leverage during input volatility. Contract-based long-term offtake dominates premium specialty segments where EFSA food-contact and pharmaceutical-grade qualifications create switching costs, while spot-market transactional pricing governs industrial wrapping volumes. Price differentiation hinges on certification tier—REACH-compliant bio-based coatings versus conventional solvent-based formulations—and captive fiber integration. Food industry buyers in Italy and Spain exhibit highest price sensitivity for certified fiber documentation, whereas Japanese electronics manufacturers absorb premium positioning for precision-release specifications.
Supply Chain Analysis
Dual-sourcing mandates from German automotive and French luxury packaging converters require qualification of at least two coating chemistry suppliers to mitigate ECHA substance evaluation disruption risks. Supply concentrates in Finland, Sweden, and Germany where integrated pulp-to-paper infrastructure anchors sulfate kraft production, with specialty chemical inputs for release coatings clustering in Switzerland and Germany. Raw material dependency on bleached sulfate pulp, bio-based barrier polymers, and silicone release agents creates vulnerability to F-Gas Regulation phase-out timelines. Distribution runs through Rhine-Ruhr logistics corridors for European converter clusters, with Asia-Pacific precision-grade volumes shipping through Busan and Nagoya port hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive timber supply and in-house coating formulation capabilities constitutes the decisive vertical-integration race, with water-based chemistry partnerships determining qualification windows ahead of REACH compliance deadlines.
For Market Incumbents: Extend supercalendering asset retrofit programs to capture water-based coating compatibility before ECHA substance restrictions tighten, while consolidating regional converter relationships in the Rhine-Ruhr corridor to defend against Nordic integrated producers. Prioritize bio-based barrier R&D intensity to maintain premium positioning as F-Gas Regulation phase-outs eliminate fluorinated coating competitors. For New Entrants and Emerging Players: Begin with Indian pharmaceutical packaging white space where CDSCO serialization mandates and underdeveloped domestic converter capacity create qualification-intensive entry points. Target Maharashtra and Gujarat transdermal patch substrate demand through technical service partnerships with European coating chemistry licensors, leveraging cold-chain expansion as the primary go-to-market anchor. For Investors and Strategic Acquirers: Re-rating potential sits with Nordic integrated producers with backward timber control given EU Green Deal packaging directive acceleration and brand owner sustainability scorecard weighting. Five-to-ten-year viability favors specialty-grade developers with precision-calendering expertise over commodity uncoated operators exposed to sulfate pulp volatility. Monitor ECHA substance evaluation timelines intersecting with converter qualification cycles as the critical inflection signal for coating chemistry market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Supply | Captive fiber sourcing insulates Nordic mills from sulfate pulp price volatility. |
| Water-Based Coating Chemistry Partnership | Bio-derived barrier formulations secure REACH compliance ahead of F-Gas phase-outs. |
| Supercalendering Asset Retrofit | Equipment modification enables water-based chemistry qualification for premium converters. |
| Long-Term Converter Supply Agreement | Multi-year offtake contracts lock in Rhine-Ruhr and Parisian packaging house demand. |
| Specialty-Grade R&D Intensity | Precision-release specifications capture margin pools in Japanese electronics manufacturing. |
Methodological Framework
Trade association filings, customs export records, and ECHA substance evaluation databases formed the secondary backbone, supplemented by primary interviews with mill operations directors, coating chemistry R&D leads, European packaging procurement managers, and pharmaceutical converter technical directors. Bottom-up volume estimates from individual mill capacity disclosures triangulated against top-down demand modeling by end-use segment.
Historical trendline analysis across machine glazed paper production volumes established baseline growth patterns, with forward projections incorporating segmentation across surface finish type, end-use performance tier, and caliper specification. CAGRs derived from regression analysis of pulp input costs, coating chemistry adoption curves, and regulatory compliance timeline impacts. Forecast inputs included EU Green Deal packaging directive implementation schedules and METI industrial standard revision cycles for Japanese electronics applications.
Underlying measurement precision varies by segment; specialty-grade release liner specifications carry tighter precision than commodity uncoated grades where spot-market volatility introduces uncertainty. Forecasts reflect assumptions regarding ECHA substance evaluation timelines, natural gas price normalization, and converter qualification cycle durations. Deviation in F-Gas Regulation enforcement intensity or REACH restriction acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper IBC Container Market
Paper & Paperboard Packaging
Russia Paper Packaging Market
Paper & Paperboard Packaging
Middle East and Africa Coated Paper Market
Paper & Paperboard Packaging
Egypt Paper Packaging Market
Paper & Paperboard Packaging
Anti-Slip Coated Paper Market
Paper & Paperboard Packaging
Wrapping Paper Market
Paper & Paperboard Packaging
Food Contact Paper and Board Market
Paper & Paperboard Packaging
Corrugated Board Market
Paper & Paperboard Packaging
Self-Sealing Paper Bands Market
Paper & Paperboard Packaging
Honeycomb Mailers Market
Paper & Paperboard Packaging
Asia-Pacific Coated Paper Market
Paper & Paperboard Packaging
Medical Packaging Paper Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Dunnage Paper Bags Market
Paper & Paperboard Packaging
South Korea Paper Packaging Market