
 Archive Boxes Market | 2026-2036
Archive Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Archive Boxes Market Analysis
FSC chain-of-custody certification is rotating as the primary gatekeeping standard for archive box suppliers serving institutional buyers in North America and Western Europe. Fellowes Brands leverages its broad office-channel footprint to sustain volume leadership in the mid-tier cardboard segment. Smurfit Kappa anchors its competitive position through captive containerboard supply and European recycling infrastructure. Gaylord Archival specializes in museum-grade lignin-free boards, competing on material purity rather than unit cost.
Archive boxes are rigid containment vessels engineered from corrugated fiberboard, solid board, or polymer substrates, typically rated for 200–1,200 lb stacking load and pH neutrality for document longevity; their core function is to protect paper-based records from environmental degradation while enabling efficient high-density storage. Cardboard variants dominate unit volume due to cost scalability and recyclability, though plastic segments are gaining structural share in humid climates where moisture resistance overrides fiber economics. Closure type segmentation reveals stacking mechanisms command premium positioning in warehouse automation environments, while lift-off lid formats retain dominance in manual-access archive facilities.
EPA guidelines on recycled content thresholds and the EU Packaging and Packaging Waste Regulation jointly shape material sourcing compliance costs for multi-region suppliers. FDA indirect food-contact standards influence polymer-grade box production for records co-located with pharmaceutical documentation. Stakeholders must weigh virgin fiber price volatility against regulatory mandates for post-consumer recycled content when configuring their procurement and manufacturing footprints.
Market Dynamics
Federal and municipal archive modernization programs across Germany are compressing replacement cycles and forcing suppliers to align with EU Packaging and Packaging Waste Regulation compliance timelines.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightening material compliance requirements are pulling acid-free corrugated solutions into legal services and government record-keeping departments.
- FSC chain-of-custody certification:Institutional buyers in Western Europe and North America now gate procurement through verified sustainable fiber sourcing standards.
- Humid climate storage requirements:Moisture-resistant polymer substrates are penetrating tropical and coastal archival facilities where fiber economics fail.
Market Restraints
- Recycled fiber cost volatility:Post-consumer corrugated availability fluctuates with municipal collection economics, squeezing margin predictability for mid-tier producers.
- German supply concentration:Federal archive modernization programs cluster demand geographically, creating regional capacity bottlenecks.
- Polymer substitution ceiling:FDA indirect food-contact standards limit polymer-grade box applications in pharmaceutical documentation co-location.
Strategic Opportunities
- Underpenetrated museum conservation:Lignin-free board specifications remain underserved outside North American and Western European institutional buyers.
- Warehouse automation convergence:Stacking mechanism closures paired with robotic retrieval systems open premium positioning in automated high-density facilities.
- Indian federal digitization mandates:Hybrid physical-digital record retention policies are creating parallel demand for certified archival containers.
Industry Challenges
- pH neutrality certification timelines:Laboratory validation for acid-free claims extends product development cycles by 8-14 months.
- Legacy manual-access facility retrofitting:Lift-off lid archive boxes dominate existing installations, complicating automated closure system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Archive Boxes Market |
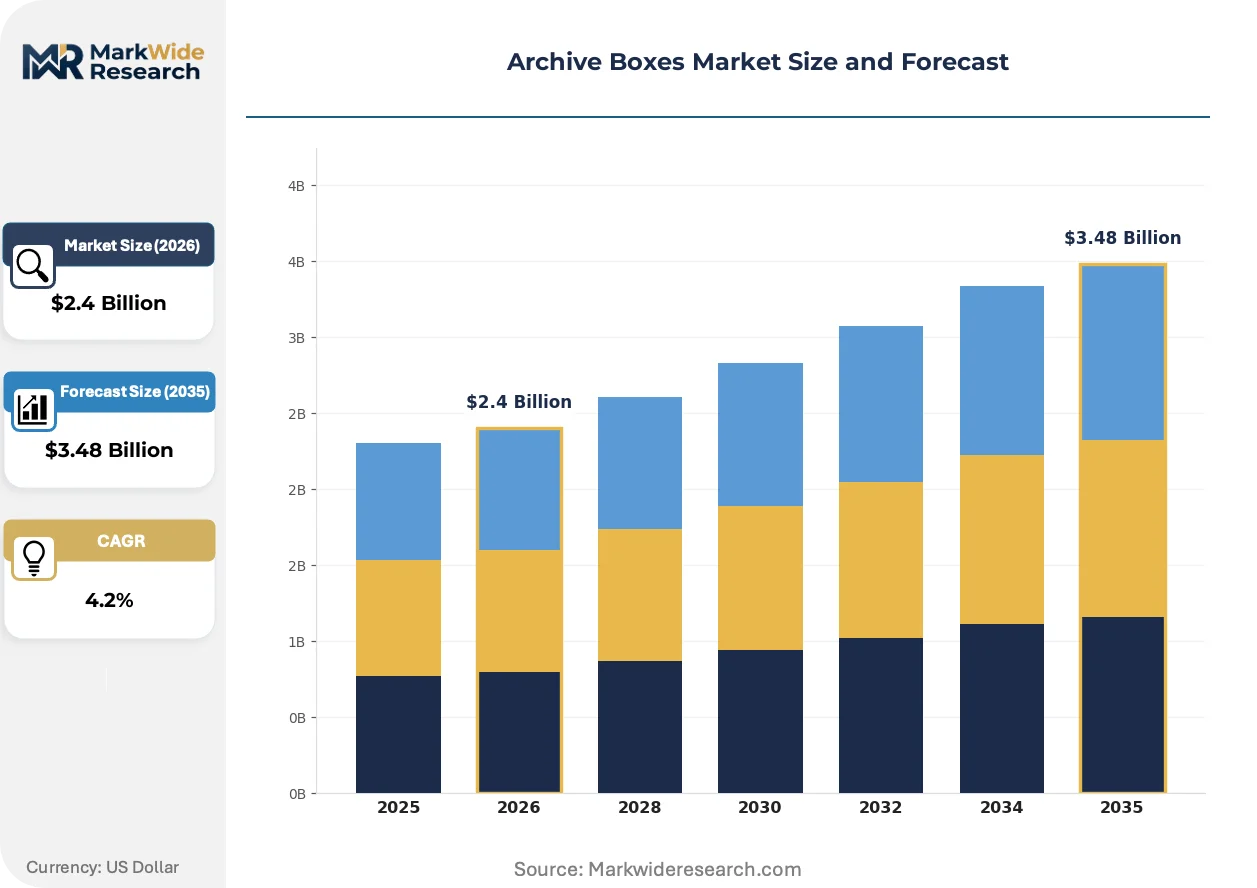
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardboard, Plastic, Metal, Wood Size: Small, Medium, Large, Extra Large Closure Type: Lift-Off Lid, Stacking, Snap-On, Secure Lock End User: Households, Offices, Libraries, Archives |
| Companies Covered | Fellowes Brands, Bankers Box, Smead Manufacturing Company, Staples Inc., Uline, Smurfit Kappa, Office Depot, StorePak, Gaylord Archival, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Archive Boxes Market Emerging Trajectories
Material science advances and regulatory tightening are splitting the market between premium certified solutions and commodity fiber alternatives, with automation compatibility becoming the decisive design parameter.
Smart humidity-sensing polymer substrates with embedded RFID tracking are bifurcating the high-value segment from standard corrugated offerings. Museum conservation departments and pharmaceutical record facilities are adopting these at triple the pace of general government archives. The technology is bifurcating supplier portfolios into connected, premium-tier solutions versus cost-optimized fiber alternatives.
REACH substance restrictions and EU Green Deal circularity targets are forcing reformulation of adhesives and surface treatments in corrugated production. Containerboard mills face capital reinvestment decisions to eliminate restricted chemistries from coating lines. German and French archival suppliers are absorbing compliance costs fastest, while Southern European producers lag certification timelines.
Specification-driven procurement through centralized procurement frameworks is displacing fragmented departmental purchasing in federal and university archive systems. Third-party logistics providers now bundle box supply with climate-controlled storage contracts, compressing direct manufacturer relationships. This pattern concentrates most visibly in German municipal archive networks and Dutch heritage institution consortia.
Archive Boxes Market Segmentation
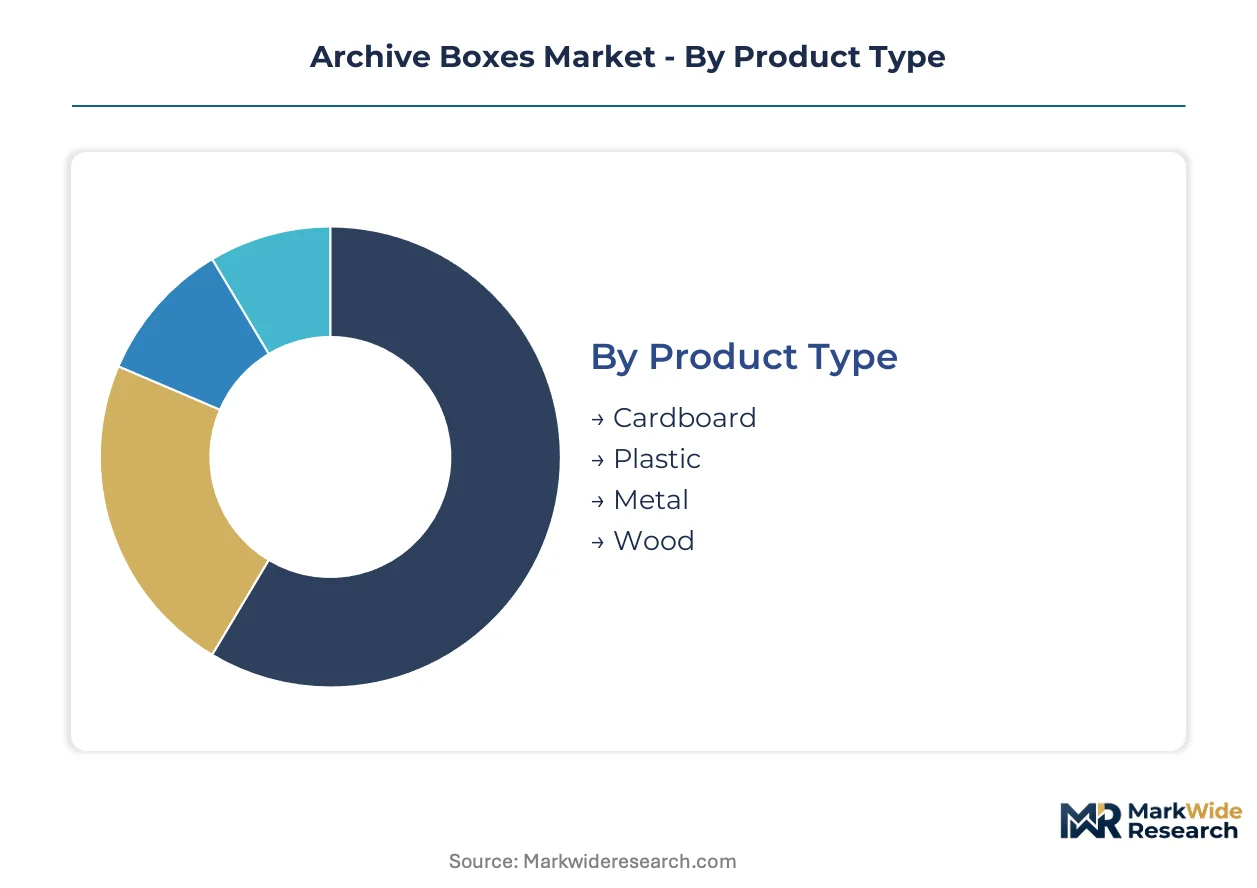
Archive box procurement channels diverge sharply by institutional versus consumer demand, with certified suppliers dominating government and museum tenders while office-channel distributors capture volume sales. Segmentation strategy determines compliance burden, margin structure, and automation compatibility across these parallel routes to market.
Product Type:
Channel mix splits between institutional specification buyers demanding certified fiber provenance and cost-driven commercial purchasers prioritizing unit economics over archival longevity.
- Cardboard:Corrugated fiberboard and solid board variants rated for 200-1,200 lb stacking loads, with acid-free and lignin-free grades commanding premium positioning in German federal archive tenders. Municipal modernization programs across Berlin, Munich, and Hamburg are compressing replacement cycles and pulling FSC-certified corrugated into legal services departments.
- Plastic:Polymer substrates engineered for moisture resistance in humid climates, embedding RFID tracking and humidity sensors in pharmaceutical documentation facilities. FDA indirect food-contact standards constrain formulation options, limiting penetration in records co-located with drug manufacturing documentation.
- Metal:Steel and aluminum containment systems for high-security document storage, deployed in financial services vaults and classified government facilities requiring fire resistance.
- Wood:Solid timber and engineered wood products for heritage institution display and conservation-grade storage, concentrated in museum conservation departments prioritizing aesthetic integration.
By volume, cardboard leads. By growth pace, plastic is gaining share fastest.
Size:
Application-driven demand patterns concentrate large-format units in warehouse automation environments while smaller dimensions dominate office-channel replenishment.
- Small:Compact formats for individual document collections and personal record retention, moving through retail and e-commerce channels.
- Medium:Standard office dimensions compatible with filing cabinet systems and manual-access shelving, capturing the largest share of commercial procurement.
- Large:Bulk storage configurations for high-density archive facilities, optimized for palletized handling and climate-controlled warehouse deployment.
- Extra Large:Oversized units for architectural drawings, maps, and oversized document formats, concentrated in government cartographic archives and engineering record repositories.
Medium formats generate the highest unit volume. Extra large formats command the steepest price premiums per cubic meter of storage capacity.
Closure Type:
Automation readiness now separates premium-tier positioning from commodity supply, with robotic retrieval systems demanding standardized stacking interfaces.
- Lift-Off Lid:Traditional manual-access design dominating legacy archive installations, creating retrofit friction for automation conversion.
- Stacking:Interlocking mechanisms engineered for robotic handling systems, penetrating automated high-density facilities at triple the pace of manual-access formats.
- Snap-On:Quick-assembly closures for temporary storage and transit applications, prevalent in commercial office moves and project-based document relocation.
- Secure Lock:Tamper-evident and keyed locking systems for confidential records, deployed in legal services and financial compliance environments.
Lift-off lid retains installed base dominance. Stacking mechanisms are climbing the fastest in new facility specification.
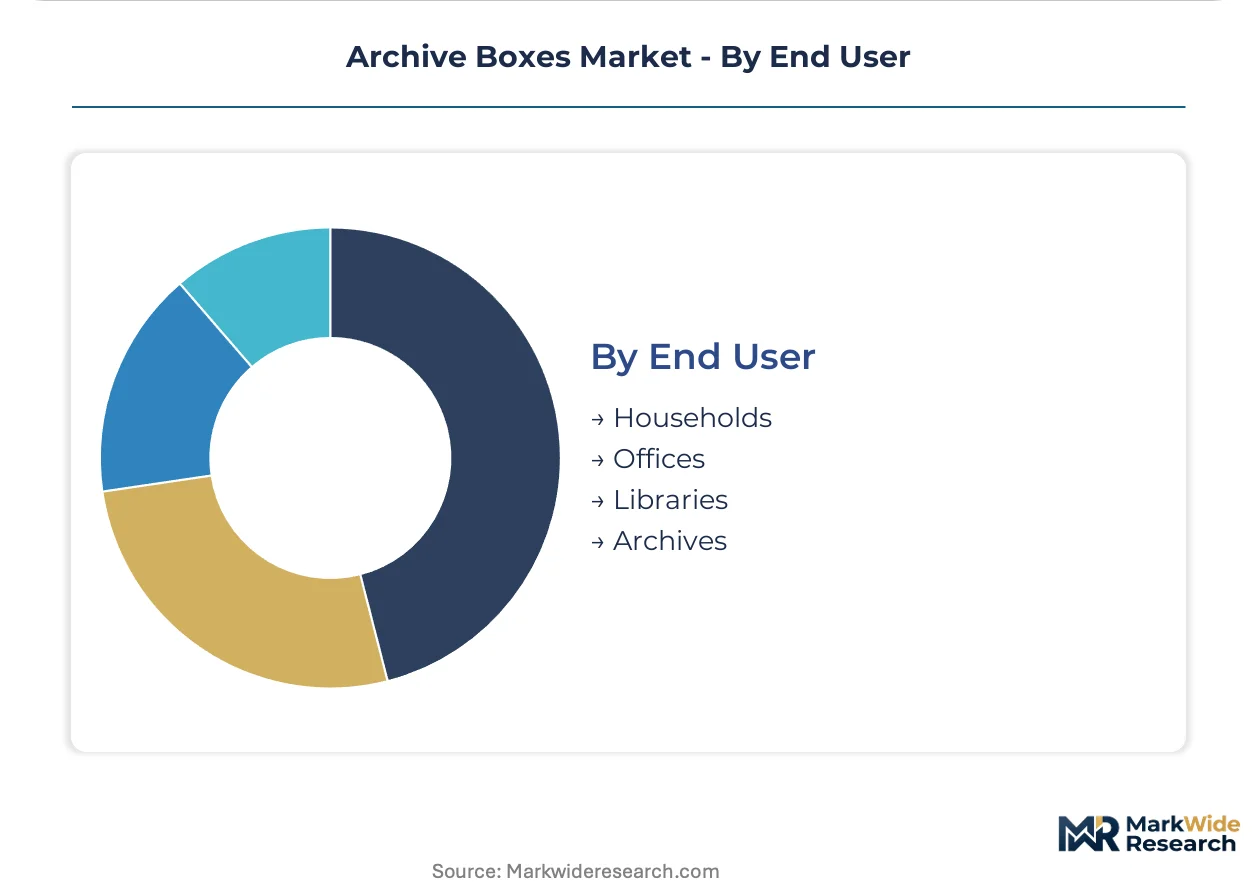
End User:
Procurement centralization is displacing fragmented purchasing across federal and university systems, compressing direct manufacturer relationships into bundled third-party logistics contracts.
- Households:Consumer-grade demand through retail and e-commerce channels, price-sensitive and specification-light compared to institutional segments.
- Offices:Commercial document retention driving mid-tier cardboard volume, with centralized procurement frameworks consolidating supplier relationships.
- Libraries:Heritage institution requirements for acid-free and lignin-free specifications, concentrated in Dutch consortia and German municipal networks.
- Archives:Federal and government record-keeping departments with mandatory compliance to EU Packaging and Packaging Waste Regulation and FSC chain-of-custody certification.
Offices generate the highest transaction volume. Archives impose the most stringent certification requirements and longest validation timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Packaging and Packaging Waste Regulation compliance timelines are compressing replacement cycles across institutional buyers. Federal archive modernization programs in Germany are pulling acid-free corrugated solutions into legal services departments. Municipal procurement centralization is reshaping supplier relationships in heritage institution networks.
Germany
Federal and municipal archive modernization programs across Berlin, Munich, and Hamburg are accelerating demand for FSC-certified corrugated fiberboard. The EU Packaging and Packaging Waste Regulation mandates material compliance thresholds that favor acid-free archival storage. Smurfit Kappa anchors supply through captive containerboard production and European recycling infrastructure.
United States
EPA recycled content guidelines shape material sourcing decisions for multi-region suppliers serving government and university archive systems. FDA indirect food-contact standards influence polymer-grade box production for pharmaceutical documentation facilities. Fellowes Brands leverages broad office-channel distribution to sustain volume leadership in mid-tier cardboard segments.
France
REACH substance restrictions and EU Green Deal circularity targets are forcing reformulation of adhesives in corrugated production. Containerboard mills face capital reinvestment decisions to eliminate restricted chemistries from coating lines. French archival suppliers are absorbing compliance costs faster than Southern European competitors.
United Kingdom
Heritage institution consortia are consolidating procurement through centralized frameworks that bundle box supply with climate-controlled storage contracts. Third-party logistics providers are compressing direct manufacturer relationships in federal and university archive systems. Gaylord Archival specializes in museum-grade lignin-free boards for conservation departments prioritizing material purity.
India
Federal digitization mandates are creating parallel demand for certified archival containers under hybrid physical-digital record retention policies. BIS standards influence domestic manufacturing specifications for acid-free storage solutions. Maharashtra and Karnataka state archives are modernizing facilities with imported FSC-certified corrugated systems.
Archive Boxes Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and channel reach. The vendor base spans three tiers: integrated containerboard producers with captive recycling infrastructure, office-channel distributors leveraging scale economies, and conservation-grade specialists competing on material purity rather than unit cost. Strategic moves concentrate on portfolio diversification into smart sensing substrates and geographic expansion through bundled logistics contracts.
Within the conservation-grade tier, Gaylord Archival exemplifies material-purity positioning for museum and heritage institution buyers. Among integrated producers, Smurfit Kappa occupies a position anchored by European recycling infrastructure and captive containerboard supply. Fellowes Brands represents the office-channel archetype, sustaining volume leadership through broad distribution reach in commercial document retention segments.
| Leading Market Players |
|---|
| Fellowes Brands |
| Bankers Box |
| Smead Manufacturing Company |
| Staples Inc. |
| Uline |
| Smurfit Kappa |
| Office Depot |
| StorePak |
| Gaylord Archival |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German federal archive programs and FSC-certified containerboard mills lock in both fiber supply access and price visibility across acid-free corrugated grades, insulating institutional buyers from post-consumer fiber volatility while compressing margin flexibility for mid-tier producers serving spot-market purchasers.
Pricing Analysis
Certification level creates the primary spread between museum-grade lignin-free boards and commodity corrugated alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects FSC chain-of-custody validation, pH neutrality laboratory testing, and automation-compatible stacking mechanisms. Cost compression in standard cardboard tiers is intensifying because recycled fiber availability fluctuates with municipal collection economics. Household and small-office segments exhibit highest price sensitivity; archives and pharmaceutical documentation facilities demonstrate lowest sensitivity due to compliance mandates.
Supply Chain Analysis
Strategic stockpiling of acid-free containerboard prevails among German and French archival suppliers facing REACH substance restriction deadlines, while just-in-timer approaches dominate office-channel distributors replenishing retail and e-commerce stocks. Manufacturing concentrates in Germany, France, and the United States, drawing from virgin pulp mills, post-consumer corrugated recovery networks, and polymer resin producers. Single-source vulnerability runs through European containerboard capacity concentrated at integrated mills. Distribution runs through third-party logistics providers bundling climate-controlled storage with box supply in municipal and heritage institution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized laboratory capacity for pH neutrality certification represents the binding constraint in this market, with validation timelines extending product development cycles and creating scarcity rents for accredited testing facilities.
For Market Incumbents: Shield market position by deepening captive containerboard supply through backward integration into European recycling infrastructure, and accelerate FSC chain-of-custody certification coverage ahead of EU Packaging and Packaging Waste Regulation enforcement timelines. Polymer substitution threats from humidity-sensing substrates necessitate defensive R&D investment in smart fiberboard alternatives. For New Entrants and Emerging Players: Accelerated FSC certification pathways open access to German municipal archive modernization programs currently underserved by conservation-grade specialists. Target Indian state archives modernizing under federal digitization mandates with hybrid physical-digital retention policies. Pursue bundled logistics contracts pairing certified box supply with climate-controlled warehousing to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Conservation-grade specialists with established museum relationships and validated lignin-free board formulations represent the most defensible acquisition archetype. Long-term viability hinges on automation compatibility and regulatory certification depth rather than unit cost scale. Watch for inflection when warehouse automation penetration in high-density archive facilities crosses threshold adoption rates among federal and university systems.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Chain-of-Custody Certification | Unlocks German federal and municipal archive tenders under EU Packaging and Packaging Waste Regulation compliance mandates. |
| Smart Substrate Development | Embedded RFID and humidity sensors penetrate pharmaceutical documentation facilities at triple the pace of government archives. |
| Backward Integration into Recycling | Captive containerboard supply insulates Smurfit Kappa from post-consumer fiber cost volatility squeezing mid-tier competitors. |
| Automation-Compatible Closure Engineering | Stacking mechanisms command premium positioning in robotic retrieval systems displacing legacy lift-off lid installations. |
| Bundled Logistics Contracting | Third-party providers compress direct manufacturer relationships in Dutch heritage consortia and German municipal networks. |
Methodological Framework
Desk research of trade association publications, customs and trade flow databases, and regulatory filing repositories preceded structured interviews with archive directors at federal and municipal institutions, procurement leads at containerboard mills, conservation specialists at museum heritage departments, and distribution channel managers at office-product wholesalers. Secondary validation drew from EU Packaging and Packaging Waste Regulation compliance disclosures, FSC certification registries, and EPA recycled content guideline documentation. Bottom-up demand modeling triangulated against top-down containerboard consumption forecasts.
Variance decomposition across product type, closure mechanism, end-user segment, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from logistic diffusion curves fitted to automation adoption patterns and certification penetration timelines. Industry-specific inputs included German federal archive modernization program expenditure schedules and Indian state-level digitization policy implementation rates.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory enforcement and stable virgin fiber pricing; material deviation would warrant model refresh. Revision becomes warranted when warehouse automation adoption in high-density archive facilities or REACH substance restriction compliance timelines cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Aluminum Beverage Bags Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Anti-Corrosion Bags Market
Bags and Containers
Isothermal Bags and Containers Market
Bags and Containers
Garbage Bag Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Type-C Bulk Bags Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
PE Jumbo Bags Market
Bags and Containers
Waterproof Bags Market
Bags and Containers
Side Weld Bags Market
Bags and Containers
North America Retail Bags Market
Bags and Containers
Textile Bags Market
Bags and Containers
Commodity Liners Market
Bags and Containers
Wicketless Bags Market