
 Wrapping Paper Market | 2026-2036
Wrapping Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Wrapping Paper Market Outlook
Modular gift-set configurations is decoupling bulk wrapping from individual item presentation, forcing converters to stock multiple roll widths and print formats for the same retail account. International Paper leverages its North American containerboard footprint to supply integrated wrapping substrates for e-commerce bundling. Mondi Group anchors European demand through kraft-based sustainable alternatives certified under forest stewardship programs. Smurfit Kappa competes by controlling the corrugated-to-wrapping value chain from recycled pulp through finished reel goods.
Wrapping paper denotes a thin, flexible paper substrate engineered for decorative enclosure of consumer goods, typically manufactured through Fourdrinier or cylinder machines at basis weights between 30 and 80 gsm, with clay coatings or polymer films added for gloss retention and print fidelity. Kraft paper dominates volume flows across the thickness spectrum as brand owners prioritize unbleached, fiber-based aesthetics aligned with circular-economy positioning. Specialty paper occupies the margin pool where foil-stamped and embossed finishes command premium pricing from luxury retailers and seasonal gift merchants.
The EU Packaging and Packaging Waste Regulation and the US EPA recycled-content guidelines are reshaping substrate specifications, compelling mills to certify post-consumer fiber ratios and eliminate heavy-metal pigments from decorative inks. China's GB standards for packaging materials and Japan's METI resource-circulation policies add compliance layers for exporters serving Asian consumer markets. Stakeholders must monitor how extended-producer-responsibility schemes alter cost allocation between paper mills, converters, and retail brands before committing to capacity expansions or formulation lock-ins.
Market Dynamics
E-commerce fulfillment networks are fragmenting order sizes into micro-batches, forcing converters to retool for shorter runs and faster changeovers while absorbing premium substrate costs.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandated recycled-content thresholds are pulling virgin kraft substitution into certified post-consumer fiber streams across German and French retail supply chains.
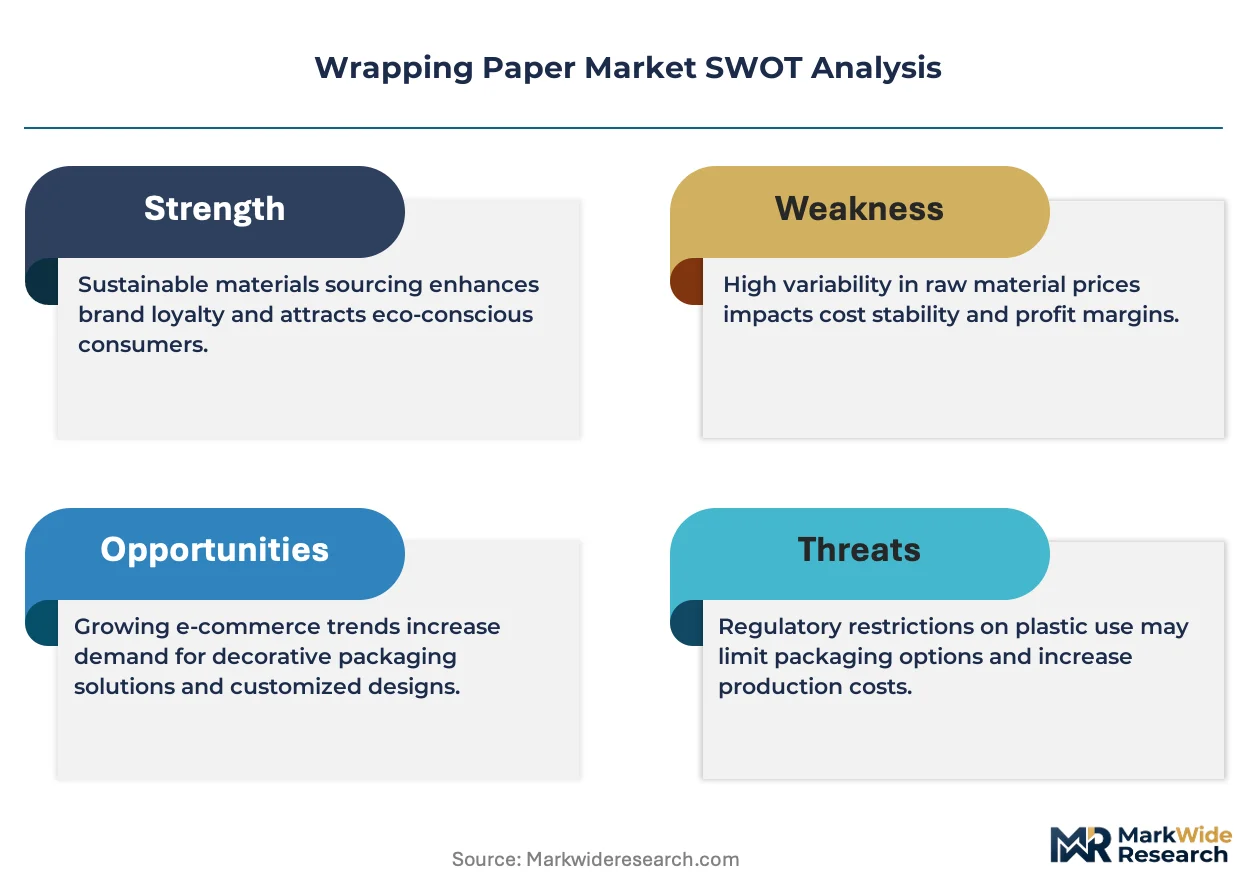
- Unboxing experience monetization:Direct-to-consumer brands are commissioning bespoke wrap designs to drive social media shareability, expanding addressable spend per shipment.
- Seasonal gift-set modularization:Holiday merchandise programs are splitting bulk warehouse wraps from individual consumer-facing presentation layers, doubling roll consumption per SKU.
Market Restraints
- Pulp cost volatility:Northern bleached softwood kraft pulp pricing swings are compressing converter margins on fixed-price annual contracts with big-box retailers.
- Asian supply concentration:Decorative paper finishing capacity clusters in Zhejiang and Guangdong provinces, exposing European buyers to shipping rate spikes and customs delays.
- Plastic film substitution:Polypropylene gift bags and reusable fabric wraps are capturing premium gift occasions where durability matters more than disposability.
Strategic Opportunities
- Indian festive-gift expansion:Diwali and wedding-season consumption patterns in Maharashtra and Gujarat remain underpenetrated by branded wrap suppliers relative to unorganized local production.
- Digital print convergence:Inkjet web presses are enabling run-length-one customization for corporate gifting programs without plate costs.
- Extended producer responsibility schemes:France's Citeo eco-modulation bonuses are rewarding higher recycled-content wraps with reduced compliance fees.
Industry Challenges
- Rotogravure cylinder lead times:Seasonal peak demand collides with eight-week engraving queues, forcing converters to pre-position inventory on speculative designs.
- Heavy-metal pigment phase-outs:Reformulating crimson and metallic decorative inks to meet REACH Annex XVII restrictions requires reformulation cycles that miss single-season product windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wrapping Paper Market |
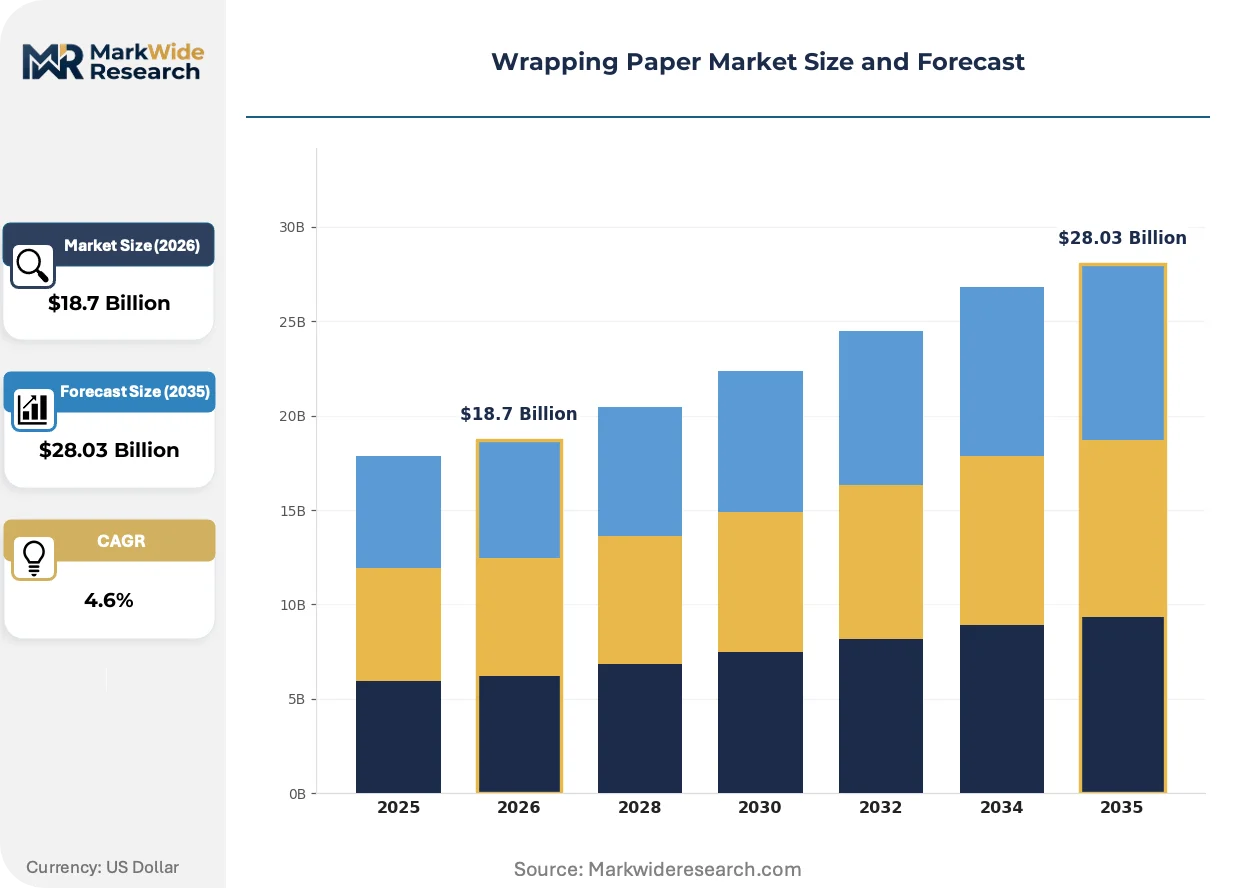
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glossy Paper, Kraft Paper, Recycled Paper, Specialty Paper Thickness: Lightweight, Medium, Heavyweight, Ultra-Heavyweight Print Type: Plain, Printed, Embossed, Foil Stamped End User: Retail Stores, E-commerce, Gift Shops, Individuals |
| Companies Covered | International Paper, Mondi Group, WestRock, Smurfit Kappa Group, DS Smith, Stora Enso, Sappi Limited, Hallmark Cards, Oji Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wrapping Paper Market Strategic Shifts
Substrate engineering and regulatory compliance are converging to redefine what constitutes premium presentation, with functional performance displacing pure aesthetics as the primary specification driver.
Seed-embedded plantable papers are absorbing ceremonial and corporate gifting volumes as event marketers seek zero-waste credentials. Wedding planners and sustainability officers at Fortune 500 firms are specifying these substrates for employee recognition programs. The technology is absorbing share from conventional foil-stamped wraps in occasions where disposal guilt shapes recipient perception.
REACH Annex XVII restrictions on chromium VI compounds in packaging inks are forcing reformulation of metallic decorative finishes across EU-sourced wrapping papers. Mills serving German and French retail accounts are accelerating water-based pigment substitutions ahead of enforcement deadlines. Luxury fragrance and cosmetics houses are most exposed, as their seasonal gift-with-purchase programs rely heavily on reflective print effects.
Bulk procurement of unprinted kraft rolls for in-house digital overprinting is displacing pre-printed seasonal stock at mid-market e-commerce fulfillment centers. Operations teams at apparel and home goods direct-to-consumer brands are bringing print capability in-house to compress campaign launch cycles. This pattern is most visible in Netherlands and UK distribution hubs where labor costs justify capital deployment against third-party converter margins.
Wrapping Paper Market Segmentation
Converters must align substrate specifications with divergent fulfillment models. Retail replenishment demands long-run efficiency while e-commerce micro-batches require rapid changeover capability. These tensions fragment capacity planning across the value chain.
Product Type:
Customization intensity varies from commodity kraft rolls to bespoke specialty finishes with engraved cylinders and metallic overlays.
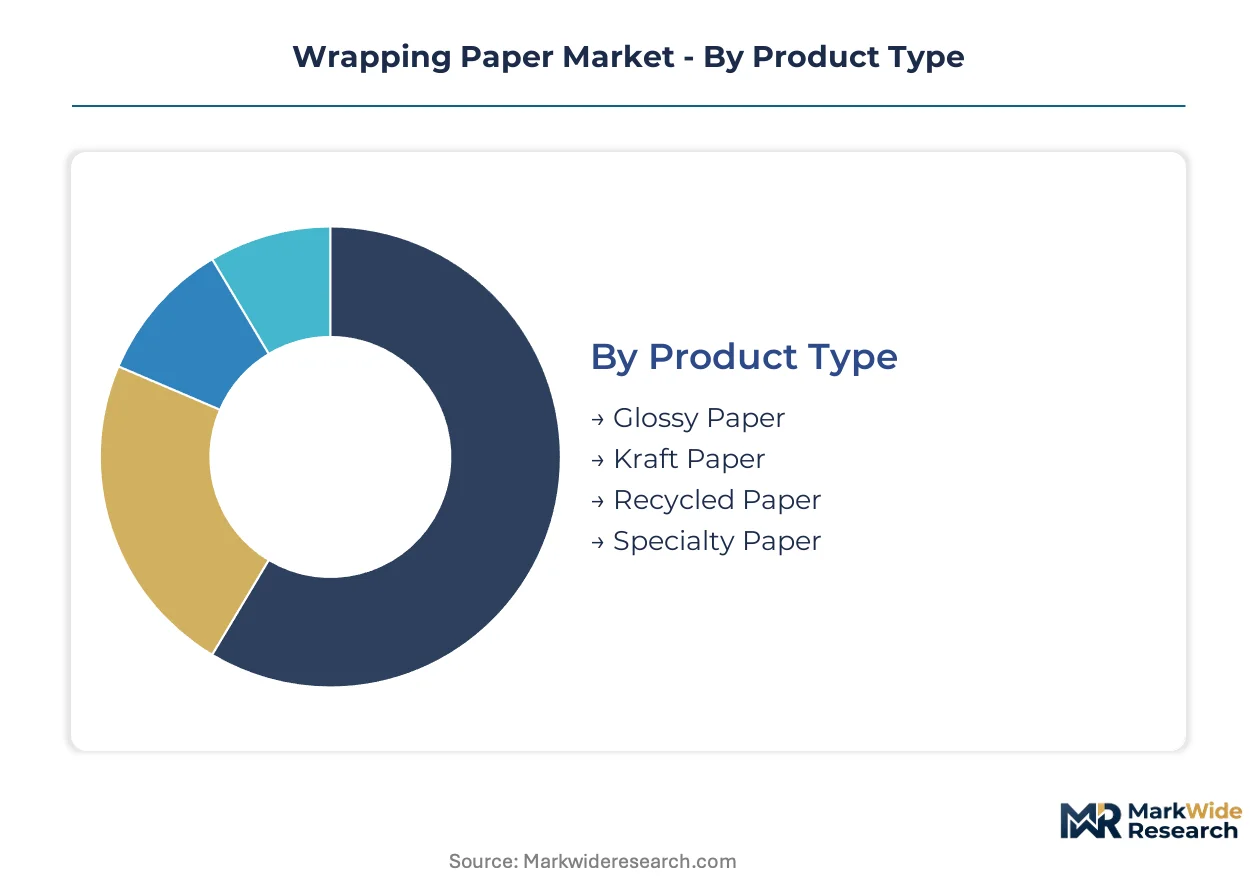
- Glossy Paper:Clay-coated mechanical pulp substrates deliver high print fidelity for photographic imagery and brand color matching. Demand clusters in cosmetics and fragrance gift-with-purchase programs where shelf impact drives specification. REACH Annex XVII heavy-metal restrictions are forcing water-based coating migrations that extend drying cycles.
- Kraft Paper:Unbleached sulfate pulp provides tear resistance and natural fiber aesthetics aligned with circular-economy positioning. German retail chains specify certified post-consumer fiber ratios above regulatory minimums to capture Citeo eco-modulation bonuses. The segment absorbs volume flows across e-commerce bundling and industrial protective wrapping.
- Recycled Paper:Post-consumer deinked pulp with controlled contamination thresholds for direct food-contact adjacent applications.
- Specialty Paper:Seed-embedded plantable substrates and handmade cotton rag variants for ceremonial and corporate gifting occasions.
Most installed capacity flows through Kraft Paper. Expansion is steepest in Specialty Paper.
Thickness:
Basis weight selection maps directly to protection requirements and postal cost optimization across fulfillment networks.
- Lightweight:30-40 gsm tissue grades for single-use decorative enclosure of non-fragile items. E-commerce apparel brands in Netherlands distribution hubs specify lightweight kraft for poly-mailer interior wrapping to reduce dimensional weight charges. The segment sacrifices durability for cost efficiency in high-volume subscription box programs.
- Medium:50-60 gsm utility grades balancing printability with handling integrity for standard gift occasions.
- Heavyweight:70-80 gsm structures for premium unboxing experiences requiring rigidity and multiple reuse cycles.
- Ultra-Heavyweight:90+ gsm board-like constructions for architectural model wrapping and luxury presentation cases.
Volume concentration sits in Medium thickness. The steepest expansion trajectory belongs to Lightweight grades.
Print Type:
Decorative complexity determines converter equipment utilization and inventory risk exposure across seasonal demand spikes.
- Plain:Unprinted substrates for in-house digital overprinting at mid-market fulfillment centers. UK apparel direct-to-consumer brands are bulk-procuring plain kraft rolls to compress campaign launch cycles through internal inkjet web presses. The pattern displaces pre-printed seasonal stock and reduces obsolescence risk.
- Printed:Rotogravure or flexographic reproduction of repeat patterns with eight-week cylinder engraving lead times forcing speculative pre-positioning.
- Embossed:Calendered relief textures adding tactile differentiation without ink coverage for understated premium positioning.
- Foil Stamped:Metallic transfer films requiring heat-activated adhesives and precise registration for luxury fragrance and cosmetics applications.
Plain substrates command the largest volume share. Foil Stamped is gaining share fastest among premium positioning tiers.
End User:
Procurement scale and specification authority diverge sharply between centralized retail buying and fragmented individual purchasing.
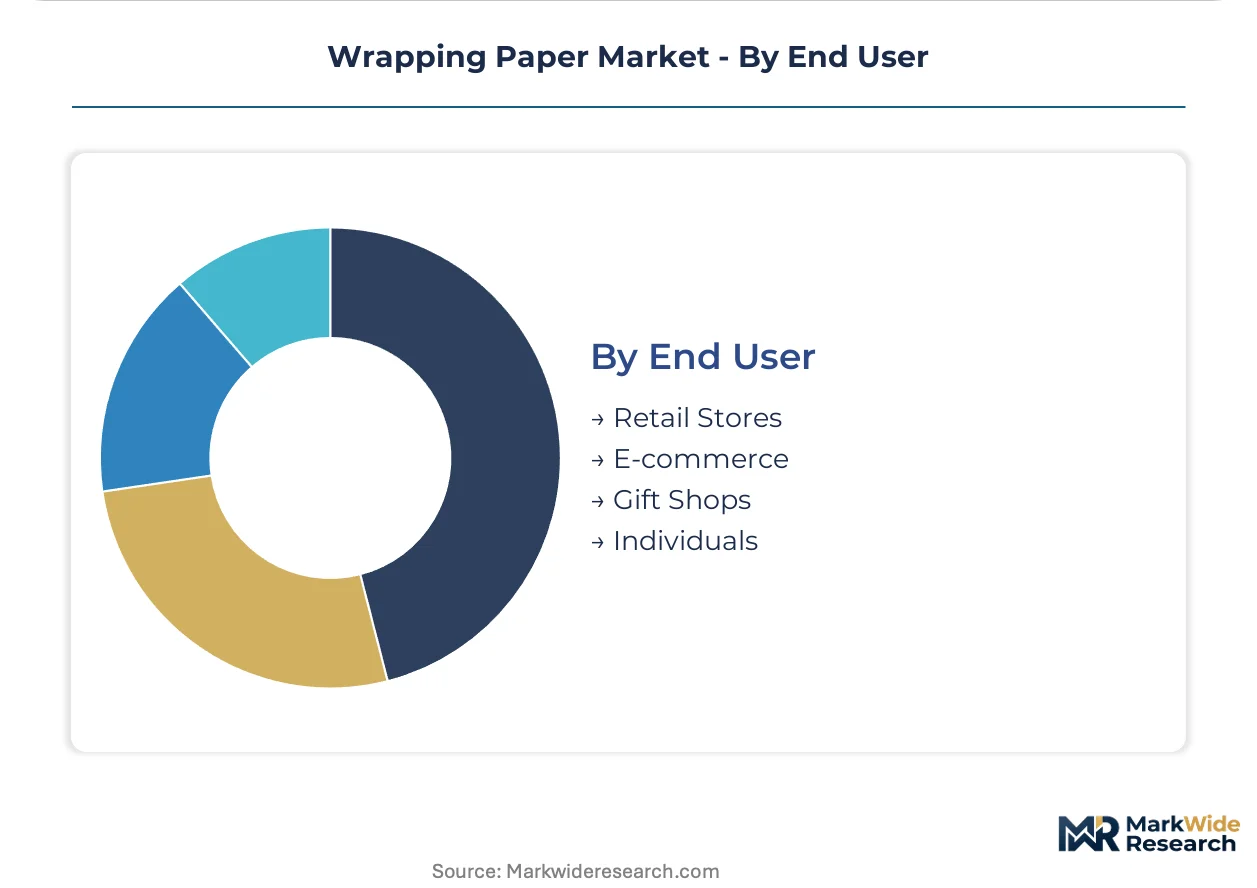
- Retail Stores:Seasonal bulk programs with fixed annual contracts and speculative design commitments ahead of peak demand. German department stores coordinate wrapping material specifications across regional distribution centers to maintain brand consistency.
- E-commerce:Micro-batch fulfillment with run-length-one customization requirements and rapid design iteration cycles.
- Gift Shops:Curated artisanal sourcing with emphasis on local design narratives and small minimum order quantities.
- Individuals:Occasional purchasing through mass-market stationery and craft supply channels with price sensitivity dominating selection.
Retail Stores absorb the majority of mill-direct volume. E-commerce is climbing the fastest as a demand channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial gift-wrapping culture through department store traditions dating to the late 19th century. This heritage established premium paper specifications that still circulate through European retail supply chains. Contemporary demand patterns now diverge between heritage markets and emerging fulfillment economies.
Germany
Premium gift-giving rituals sustain per-capita consumption above European averages, with department store chains coordinating specifications across regional distribution centers. The EU Packaging and Packaging Waste Regulation enforces recycled-content thresholds that pull virgin kraft into certified post-consumer fiber streams. Mills in North Rhine-Westphalia capture Citeo eco-modulation bonuses by exceeding minimum recycled ratios for French retail accounts.
United States
E-commerce fulfillment networks fragment order sizes into micro-batches, forcing converters toward shorter runs and faster changeovers. EPA recycled-content guidelines reshape substrate specifications for exporters serving domestic consumer markets. Distribution hubs in the Pacific Northwest and Southeast absorb bulk kraft rolls for in-house digital overprinting by direct-to-consumer apparel brands.
China
Decorative paper finishing capacity clusters in Zhejiang and Guangdong provinces, exposing European buyers to shipping rate volatility and customs delays. GB standards for packaging materials add compliance layers for exporters serving Asian consumer markets. Shenzhen and Ningbo converters supply foil-stamped and embossed finishes for luxury fragrance seasonal programs.
India
Diwali and wedding-season consumption patterns in Maharashtra and Gujarat remain underpenetrated by branded wrap suppliers relative to unorganized local production. The country's national packaging regulator enforces evolving standards for food-contact adjacent applications. Mumbai and Ahmedabad distribution nodes handle rising import volumes of certified sustainable substrates for corporate gifting programs.
Japan
Traditional furoshiki fabric wrapping competes with paper alternatives for ceremonial gift occasions where durability matters. METI resource-circulation policies mandate extended producer responsibility schemes that alter cost allocation between mills and retail brands. Osaka-based converters specialize in ultra-lightweight tissue grades for poly-mailer interior wrapping in subscription box programs.
Wrapping Paper Market Competitive Environment
Premium-margin players sit above commodity-margin players across substrate certification tiers, with sustainable forest stewardship credentials commanding price premiums of 15-25 percent. The vendor base concentrates among integrated pulp-to-paper operators and specialized decorative converters serving seasonal peak demand. Three archetypes dominate: North American containerboard giants, European kraft specialists, and Asian decorative finishers. Consolidation proceeds through backward integration into recycled pulp supply and geographic expansion into underpenetrated festive-gift markets.
Within the integrated pulp-to-paper tier, International Paper exemplifies North American containerboard scale, while Mondi Group anchors European sustainable kraft positioning. Smurfit Kappa occupies a position spanning corrugated-to-wrapping value chain control. These three represent distinct strategic postures: transatlantic substrate supply, continental sustainability certification, and captive recycled fiber integration.
| Leading Market Players |
|---|
| International Paper |
| Mondi Group |
| WestRock |
| Smurfit Kappa Group |
| DS Smith |
| Stora Enso |
| Sappi Limited |
| Hallmark Cards |
| Oji Paper |
| Others |
Value Chain & Pricing Dynamics
Captive integration into recycled pulp supply anchors converter pricing power across European and North American markets, with mills controlling fiber flows from collection through finished reel goods commanding margin premiums of 15-25 percent over non-integrated competitors serving identical retail accounts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and volume commitment. Forest stewardship credentials and post-consumer fiber ratios drive price differentiation between Mondi Group's certified kraft and commodity Asian imports. Cost compression in standard-grade kraft intensifies as Northern bleached softwood pulp pricing swings compress converter margins on fixed-price annual contracts. Big-box retailers exhibit highest price sensitivity, while luxury fragrance houses absorb premium foil-stamped finishes without volume negotiation.
Supply Chain Analysis
EU Packaging and Packaging Waste Regulation domestic-content mandates are reshaping sourcing patterns across German and French retail supply chains. Decorative finishing capacity concentrates in China's Zhejiang and Guangdong provinces, with European buyers drawing from Shenzhen and Ningbo converters despite shipping rate volatility. Raw material flows hinge on Northern bleached softwood kraft pulp, post-consumer recovered fiber, and water-based pigment formulations. Single-source vulnerability runs through Asian decorative finishing clusters exposed to customs delays and tariff exposure. Distribution runs through regional mill-direct relationships for retail store accounts and third-party logistics hubs for e-commerce micro-batch fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU regulatory compliance costs and Asian manufacturing scale creates margin capture opportunities for converters with dual-hemisphere sourcing flexibility.
For Market Incumbents: Anchor sustainable certification leadership by exceeding EU Packaging and Packaging Waste Regulation minimums to capture Citeo eco-modulation bonuses in France. Backward integration into recycled pulp supply defends margin position against Northern bleached softwood kraft price volatility. Digital print capability investments counter rotogravure cylinder lead time risks that force speculative inventory pre-positioning.
For New Entrants and Emerging Players: Capture white-space in India's Maharashtra and Gujarat festive-gift markets where Diwali and wedding-season consumption patterns remain underpenetrated by branded suppliers. Seed-embedded plantable papers offer the most penetrable premium positioning tier as event marketers seek zero-waste credentials. Direct-to-consumer brand partnerships provide go-to-market velocity without legacy retail distribution overhead.
For Investors and Strategic Acquirers: Roll-up economics work for mid-market decorative converters with seasonal peak capacity because fragmented gift-shop and corporate gifting demand lacks national-scale suppliers. Five-to-ten year viability hinges on regulatory compliance infrastructure that smaller players cannot replicate. Watch Citeo eco-modulation bonus expansions across additional EU member states as inflection signal for certified-content premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Pulp Supply | Captive fiber flows insulate margins from Northern bleached softwood kraft volatility. |
| Digital Print Capability Deployment | Inkjet web presses enable run-length-one customization without rotogravure cylinder lead times. |
| Sustainability Certification Investment | Forest stewardship credentials command 15-25 percent price premiums from German retail chains. |
| Geographic Expansion into Indian Festive Markets | Maharashtra and Gujarat Diwali consumption patterns outpace branded supplier penetration. |
| Extended Producer Responsibility Compliance Infrastructure | Citeo eco-modulation bonus capture requires systems smaller competitors cannot deploy. |
Study Parameters
Bottom-up e-commerce and retail store modeling reconciled against top-down pulp-to-paper capacity tracking forms the analytical core of this study. Primary interviews with paper mill operations directors, converter procurement leads, retail category buyers, and sustainability officers at Fortune 500 firms combined with secondary validation from EU Packaging and Packaging Waste Regulation filings, EPA recycled-content guidelines, customs trade data, and forest stewardship certification databases. Triangulation across stakeholder perspectives and documentary sources ensures cross-verified demand and supply estimates.
Historical trendline analysis across installed capacity, seasonal demand patterns, and regulatory compliance cost trajectories informed projection frameworks. Segmentation dimensions modeled include product type, thickness grade, print complexity, and end-user channel across the analysis window. CAGRs derived from weighted average of demand-side adoption curves and supply-side capacity expansion schedules. Industry-specific forecast inputs incorporated EU recycled-content mandate phase-ins and e-commerce fulfillment network growth trajectories.
Pulp cost volatility, regulatory enforcement timing variations, and substitution acceleration by polypropylene gift bags are the dominant revision risks to forward projections. Forecasts reflect assumptions about extended producer responsibility scheme implementations and digital print adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Postal Papers Market
Paper & Paperboard Packaging
Kraft Envelopes Market
Paper & Paperboard Packaging
Self-Sealing Paper Bands Market
Paper & Paperboard Packaging
United Kingdom Corrugated Packaging Market
Paper & Paperboard Packaging
Coated Paper Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Corrugated Fish Box Market
Paper & Paperboard Packaging
Waxed Paper Packaging Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
Chipboard Box Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Coated Recycled Paperboard Market
Paper & Paperboard Packaging
Kraft Paper Bags Market
Paper & Paperboard Packaging
Composite Paper Cans Market