
 Postage Stamp Paper Market | 2026-2036
Postage Stamp Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Postage Stamp Paper Market Analytics
Modular booklet packaging is realigning how postal authorities procure stamp paper, shifting volume from bulk sheets toward pre-assembled retail units. Security Papers Limited leverages its integrated cotton-linen pulp supply chain to sustain premium-grade output for high-denomination issues. Glatfelter anchors North American demand through specialized wet-laid nonwoven substrates that resist chemical tampering. FNMT-RCM dominates Iberian and Latin American markets with engraved watermarking technology that differentiates its product from standard offset-printed alternatives.
Postage stamp paper denotes a security-grade substrate engineered with cotton or alpha-cellulose fibers, incorporating watermarks, fluorescent tagging, and controlled porosity measured in Gurley seconds to prevent forgery and ensure ink adhesion. Its primary purpose is to serve as a value-bearing medium for postal revenue collection and philatelic commemoration. Self-adhesive formats now lead volume as postal operators phase out moisture-activated gums, while specialty coating grades capture margin pools through UV-fluorescent and thermochromic security layers. Thermal substrates represent the fastest-growing niche, driven by on-demand printing at automated postal kiosks.
ISO 1874 governs paper permanence standards for archival-grade stamps, while the EU Green Deal's due diligence rules on deforestation-free supply chains constrain raw material sourcing for European converters. India's BIS certification requirements for security paper and the US Postal Service's material specifications jointly shape cross-border supplier qualification barriers. Stakeholders must monitor how postal digitization and declining letter-mail volumes reshape procurement volumes against commemorative and collector-segment resilience.
Market Dynamics
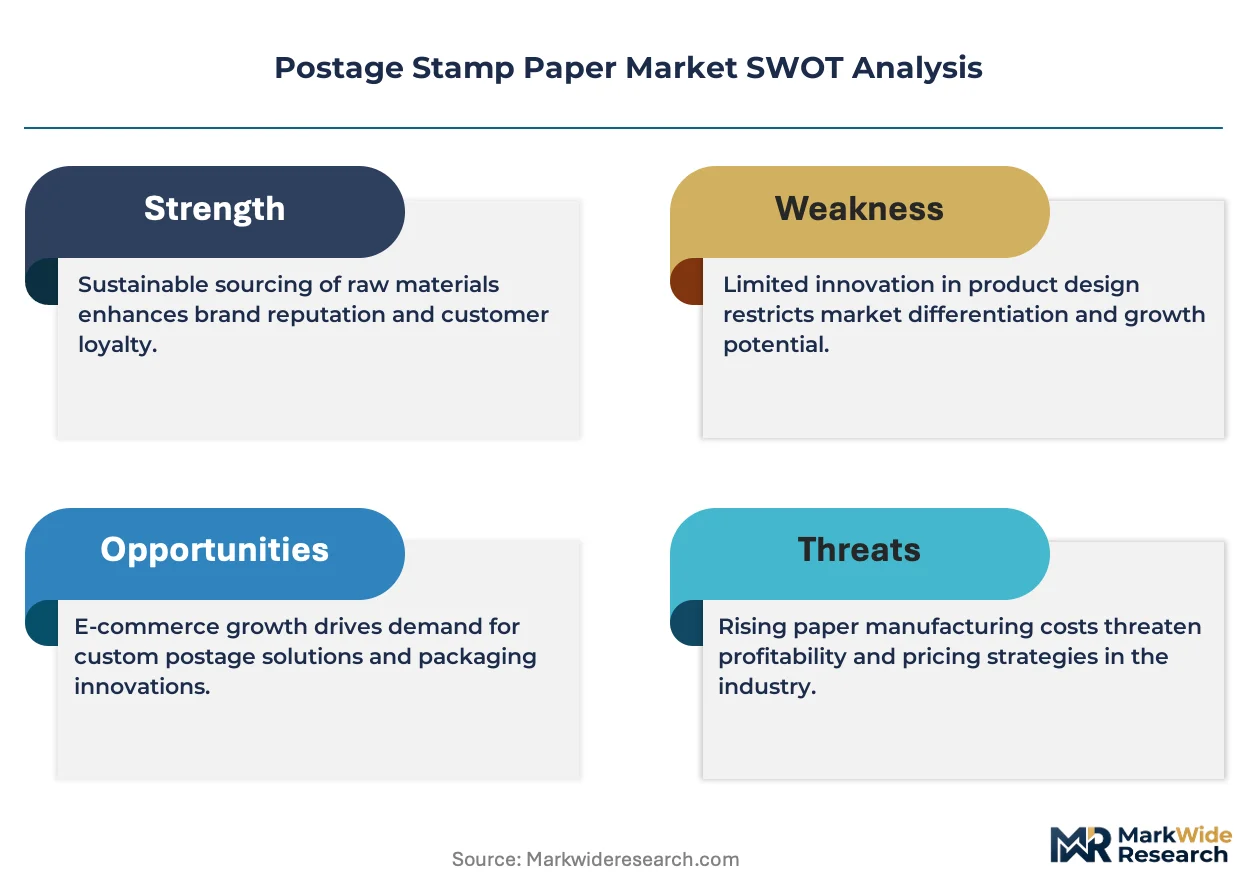
Postal digitization is compressing transactional stamp volumes while commemorative and philatelic segments sustain substrate demand through premium security specifications and limited-edition releases.
Growth Catalysts
- EU Green Deal due diligence rules:Deforestation-free supply chain mandates are accelerating certified pulp sourcing among European converters, creating qualification barriers that favor established security paper manufacturers with traceable cotton-linen supply chains.
- Thermal substrate adoption:On-demand printing infrastructure at automated postal kiosks is pulling demand for heat-sensitive stamp papers that enable variable denomination issuance without pre-printed inventory.
- India:BIS certification requirements for security paper are sustaining domestic procurement volumes as the Department of Posts modernizes retail distribution through self-adhesive booklet formats.
Market Restraints
- Cotton pulp cost volatility:Long-staple cotton fiber prices fluctuate with agricultural commodity cycles, compressing margins for premium-grade substrates that require 80-100% cotton content.
- Letter-mail volume decline:Electronic communication substitution is structurally reducing transactional stamp consumption in Germany, Japan, and other developed postal markets.
- Watermark engraving capital intensity:Cylinder engraving for multi-tonal watermarks requires specialized equipment with 15-20 year depreciation horizons, limiting supplier entry.
Strategic Opportunities
- Brazil:Correios' ongoing retail modernization presents white space for pre-assembled commemorative booklets with integrated UV-fluorescent security layers.
- ISO 1874 archival certification:Permanent paper standards for philatelic preservation are creating premium tier differentiation that commands price multiples over standard grades.
- RFID-nanoparticle convergence:Embedding trackable micro-tags within cotton substrates enables authentication at postal sorting centers and collector verification.
Industry Challenges
- Cylinder engraver skill scarcity:Multi-generational craftsmanship in tonal watermark design is concentrating among retiring specialists in Portugal and Spain without adequate apprenticeship pipelines.
- Legacy gum-line retooling:Converting moisture-activated coating equipment to hot-melt self-adhesive application requires extended downtime that postal authorities resist during peak issuance periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Postage Stamp Paper Market |
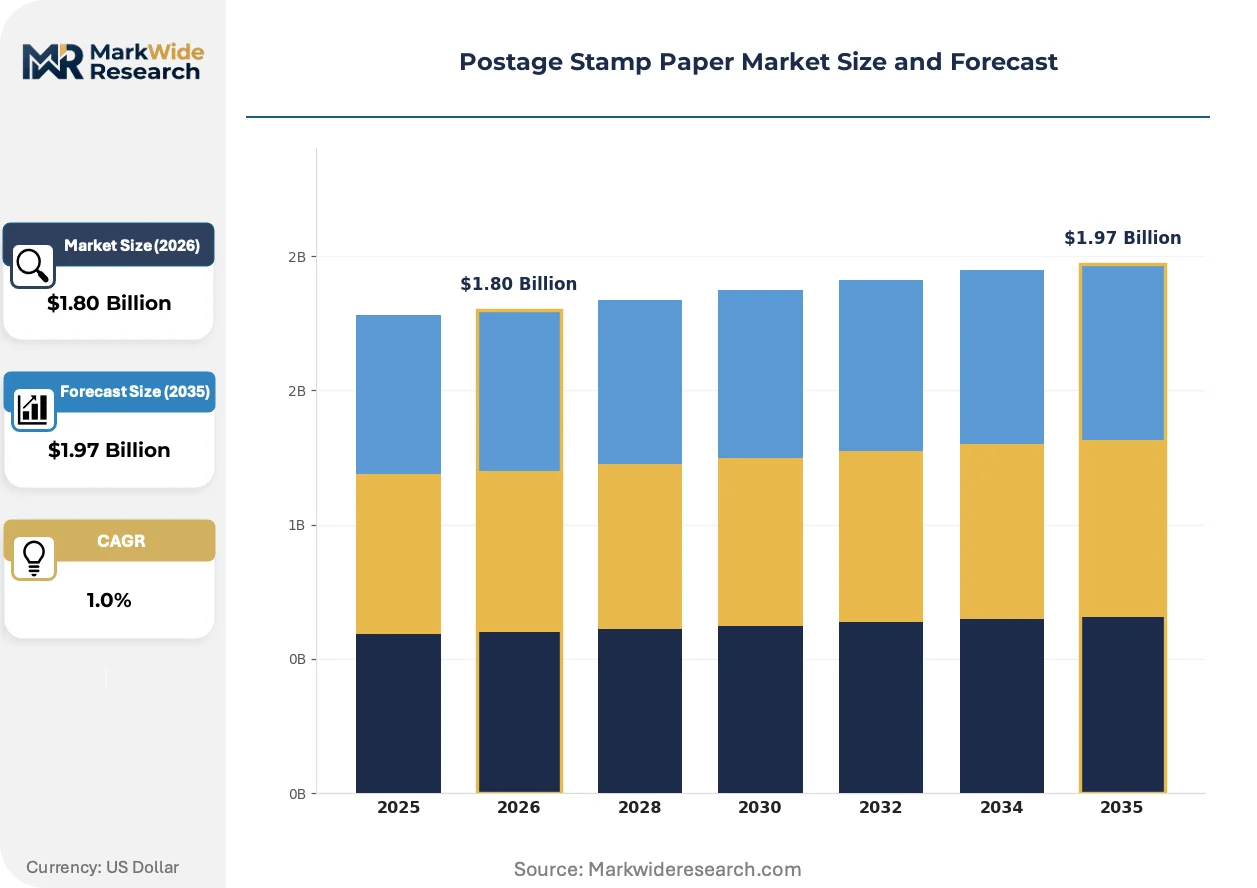
| Market Size in 2026 | $1.80 Billion |
| Market Size in 2035 | $1.97 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive, Non-Adhesive, Pre-Printed, Thermal Material: Paper, Polymer, Specialty Coating, Greaseproof End User: Government, Collectors, Wholesale Distributors, Retailers Packaging Type: Sheets, Rolls, Booklets, Custom Bundles |
| Companies Covered | Security Papers Limited, Glatfelter, Tullis Russell, Stamped Paper Co., FNMT-RCM, UPM Raflatac, Kaizen Metal Forming, August Engraving Ltd, Goznak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Postage Stamp Paper Market Evolving Landscape
Security substrate evolution now centers on machine-readable authentication layers and sustainable fiber sourcing, with postal operators demanding traceability from pulp to finished stamp.
Thermal-reactive stamp papers with embedded leuco-dye chemistry are automating denomination printing at unmanned postal kiosks across Germany and Japan. Postal operators in these markets are deploying self-service infrastructure that eliminates pre-printed inventory carrying costs. This shift is automating the interface between substrate suppliers and retail distribution networks.
The EU Green Deal's deforestation-free supply chain regulation is compelling cotton-linen pulp traceability from gin to paper mill. European converters must now document fiber origin through mass-balance certification. Security-grade producers in France and Spain are restructuring procurement relationships with Egyptian and Brazilian cotton suppliers to maintain EU market access.
Collector-driven commemorative issuance is displacing transactional volume as the primary margin pool for stamp paper manufacturers. Postal authorities in India and Brazil are expanding limited-edition thematic releases with enhanced security features. This behavioral pivot is most visible in pre-assembled booklet formats that integrate holographic threads and micro-lettering for authentication.
Postage Stamp Paper Market Segmentation
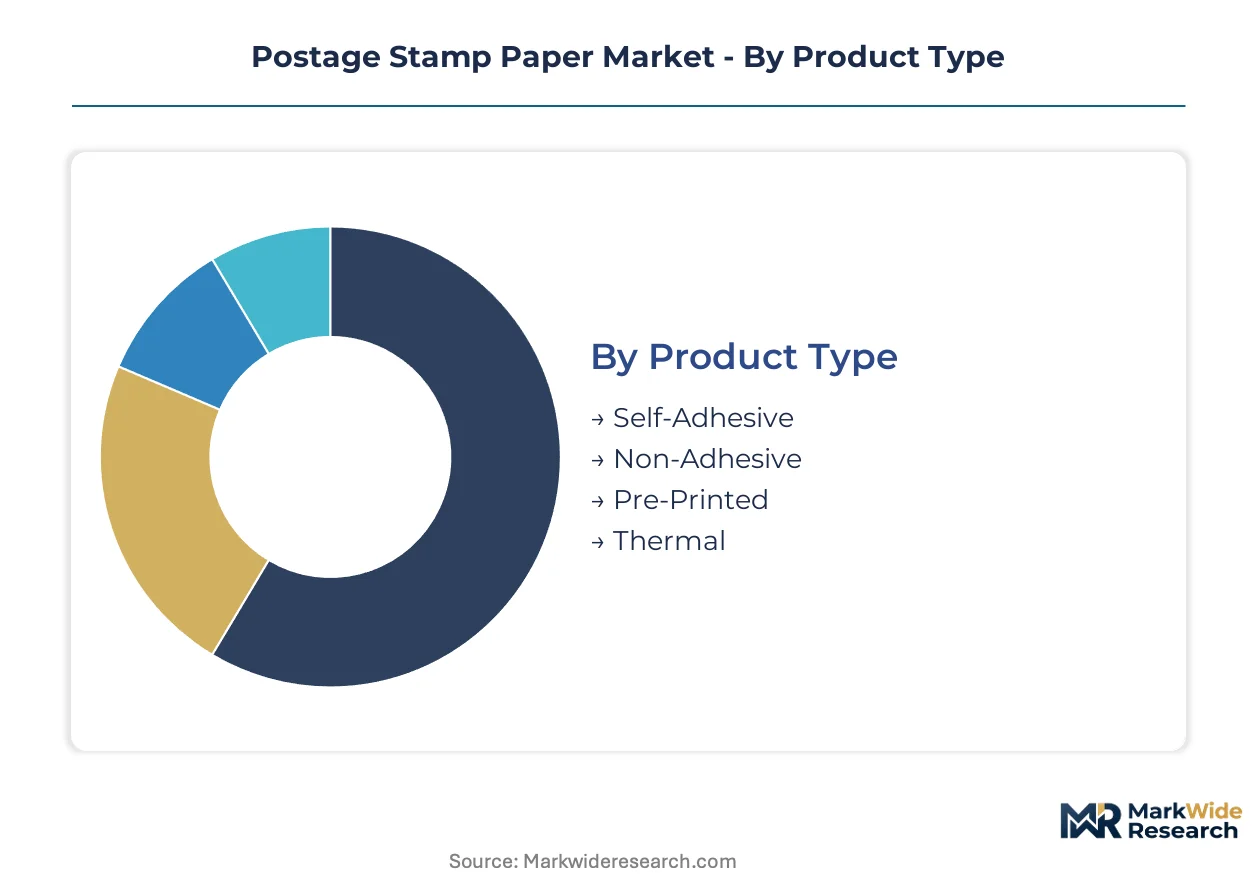
Postage stamp paper procurement patterns diverge sharply across product formats, substrate materials, and distribution channels. Postal authorities prioritize security specifications and retail-ready packaging, while collector segments drive premium material demand. Understanding these fracture lines reveals where margin pools concentrate and which specifications command price premiums.
Product Type:
Format selection hinges on automation compatibility and retail distribution modernization priorities.
- Self-Adhesive:Hot-melt pressure-sensitive coatings eliminate moisture activation and enable automated dispensing at postal kiosks. Correios in Brazil and India Post are consolidating procurement around this format as they phase out legacy gum lines.
- Thermal:Heat-sensitive substrates with embedded leuco-dye chemistry support on-demand denomination printing at unmanned postal infrastructure. Germany and Japan lead deployment of thermal-capable kiosks, pulling substrate demand toward heat-reactive specifications.
- Non-Adhesive:Traditional moisture-activated gum papers persist in commemorative and philatelic segments where archival permanence under ISO 1874 standards takes precedence over convenience.
- Pre-Printed:Fixed-denomination sheets and booklets dominate high-volume transactional mail in markets with limited kiosk penetration.
Volume sits with pre-printed formats; growth tilts toward thermal substrates.
Material:
Raw material tiering separates security-grade archival issues from mass-market disposable stamps.
- Paper:Cotton-linen or alpha-cellulose substrates with controlled porosity measured in Gurley seconds form the baseline for security-grade output. EU Green Deal traceability mandates now require mass-balance certification for European converters sourcing Egyptian or Brazilian cotton.
- Specialty Coating:UV-fluorescent, thermochromic, and holographic security layers command price multiples in limited-edition commemorative releases. India and Brazil are expanding thematic booklet programs with integrated authentication features.
- Polymer:Synthetic substrates resist moisture and tearing in tropical climates, though cotton-paper permanence standards limit adoption in philatelic segments.
- Greaseproof:Barrier-treated papers protect adhesive integrity in high-humidity distribution environments.
Revenue concentrates in specialty-coated grades; expansion is steepest in traceable cotton-linen supply chains.
End User:
Procurement scale and security specification intensity vary dramatically across buyer categories.
- Government:National postal authorities in Germany, India, and Brazil sustain the largest procurement volumes with mandatory BIS, EU Green Deal, or internal security specifications. These buyers drive standardization around self-adhesive booklets and thermal-compatible substrates.
- Collectors:Philatelic purchasers absorb premium-grade cotton substrates with engraved watermarks and archival certification under ISO 1874. Limited-edition thematic releases from India Post and Correios target this segment with enhanced security features.
- Wholesale Distributors:Intermediaries aggregate demand from smaller postal administrations and corporate clients, favoring standardized pre-printed formats over custom specifications.
- Retailers:Convenience and stationery stores stock low-denomination booklets for consumer walk-up demand, prioritizing shelf-ready packaging over substrate sophistication.
Procurement volume flows through government channels; margin capture favors collector-directed issuance.
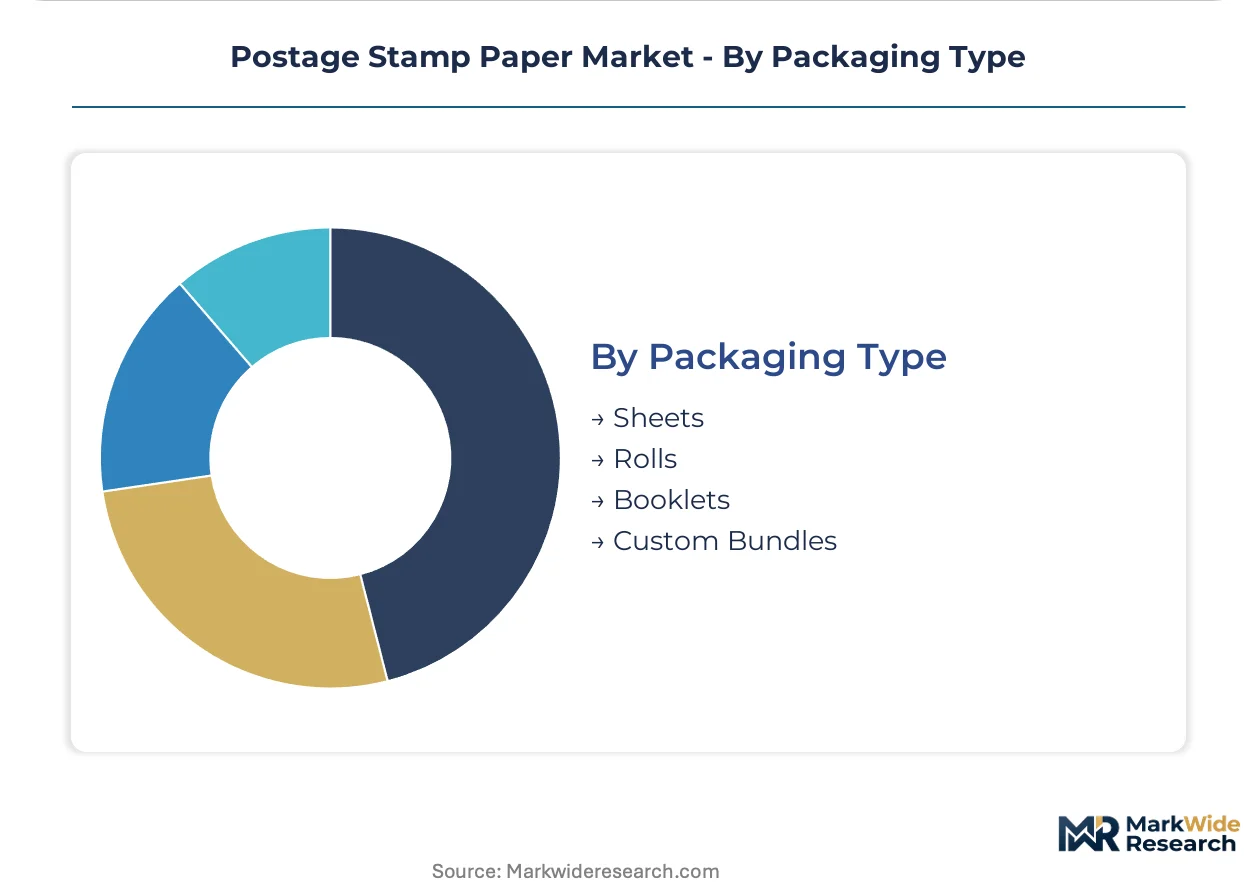
Packaging Type:
Unit configuration determines automation compatibility and retail presentation requirements.
- Booklets:Pre-assembled retail units with integrated security features and barcode-ready backing dominate modernization programs. Modular booklet formats align with automated postal kiosk dispensing systems in Germany and Japan.
- Sheets:Large-format uncut substrates serve high-volume printing operations and philatelic collectors seeking intact panes. Postal authorities in India maintain sheet procurement for commemorative issues with complex engraving requirements.
- Rolls:Continuous substrates feed high-speed printing and perforation lines for transactional stamp production.
- Custom Bundles:Configured assortments target corporate clients and specialty retailers with mixed-denomination offerings.
Production throughput favors roll formats; value accretion shifts toward booklet assembly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in European security paper mills while consumption patterns diverge between digitized postal markets and emerging economies modernizing retail distribution. Germany and France anchor substrate manufacturing through integrated cotton-linen supply chains. Procurement volumes in India and Brazil offset transactional decline in mature markets through commemorative issuance expansion.
Germany
Deutsche Post's kiosk infrastructure modernization sustains thermal substrate demand for on-demand denomination printing. The EU Green Deal's deforestation-free supply chain mandates compel mass-balance certification for cotton-linen pulp sourcing. Bavarian security paper converters restructure procurement relationships with Egyptian cotton suppliers to maintain EU market access.
India
India Post's retail channel expansion through self-adhesive booklet formats sustains procurement volumes despite letter-mail decline. BIS certification requirements for security paper create domestic qualification barriers that favor established converters. Mumbai and Delhi-based printing clusters absorb premium-grade substrates for commemorative thematic releases targeting collector segments.
Brazil
Correios' retail modernization program generates white space for pre-assembled commemorative booklets with integrated security layers. ANVISA-aligned material traceability protocols intersect with postal procurement specifications for substrate authentication. São Paulo's industrial corridor hosts specialized coating operations serving Latin American postal authorities.
Japan
Japan Post's unmanned kiosk deployment accelerates thermal-reactive substrate adoption for variable denomination issuance. METI standards for security printing materials shape supplier qualification criteria for domestic converters. Osaka-Kobe industrial zone maintains engraving and watermarking capabilities for high-denomination philatelic issues.
France
La Poste's commemorative issuance programs sustain premium cotton-paper demand through limited-edition thematic releases. EU Green Deal due diligence rules enforce fiber origin documentation from gin to paper mill. The Troyes-Paris corridor concentrates multi-tonal watermark engraving expertise among specialized cylinder craftsmen.
Postage Stamp Paper Market Competitive Landscape
The competitive structure tilts toward integrated security-grade substrate specialists with captive cotton-linen supply chains. Market concentration reflects capital intensity in cylinder engraving equipment and multi-generational watermark design expertise. Three archetypes dominate: integrated pulp-to-paper manufacturers, specialized coating and security layer applicators, and state-affiliated printers with proprietary engraving capabilities. Capacity expansion and strategic partnerships with postal authorities constitute the dominant competitive moves.
Among integrated manufacturers, Security Papers Limited exemplifies the captive pulp supply chain archetype through its cotton-linen sourcing control. Glatfelter occupies a position anchoring North American demand through wet-laid nonwoven substrate specialization. FNMT-RCM represents the state-affiliated engraving tier with multi-tonal watermark differentiation. These three sit within distinct competitive vectors—raw material security, regional market anchoring, and proprietary authentication technology—rather than direct product overlap.
| Leading Market Players |
|---|
| Security Papers Limited |
| Glatfelter |
| Tullis Russell |
| Stamped Paper Co. |
| FNMT-RCM |
| UPM Raflatac |
| Kaizen Metal Forming |
| August Engraving Ltd |
| Goznak |
| Others |
Value Network & Pricing Analysis
Long-staple cotton fiber indices cascade through postage stamp paper supply chains into three distinct pricing tiers, with Egyptian and Brazilian cotton premiums filtering into security-grade substrate costs that postal authorities absorb through commemorative issuance programs. EU Green Deal mass-balance certification requirements add traceability premiums that European converters pass to government procurement budgets.
Pricing Analysis
Margin tightening in standard-grade substrates reflects letter-mail volume compression across Germany and Japan. Pricing stratifies across premium, standard, and economy tiers based on cotton-linen content percentage and ISO 1874 archival certification status. Cost-down pressure on thermal-reactive grades accelerates because automated kiosk deployment demands heat-sensitive chemistry at scale. Government postal authorities exhibit lowest price sensitivity due to security mandates, while wholesale distributors resist specification premiums.
Supply Chain Analysis
Refurbishment flows for cylinder engraving equipment concentrate maintenance expertise in France and Spain as multi-generational craftsmen retire without apprenticeship pipelines. Raw material sourcing draws from Egyptian cotton gins, Brazilian pulp mills, and alpha-cellulose refineries in Germany. Single-source vulnerability sits with long-staple cotton fiber supply given agricultural commodity cycles. Distribution runs through integrated security paper manufacturers directly to national postal authorities, bypassing traditional wholesale channels for high-denomination issues.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Postage stamp paper markets reward players securing captive cotton-linen pulp supply chains, with backward integration into Egyptian and Brazilian fiber sourcing emerging as the decisive competitive lever.
For Market Incumbents: Acquire cylinder engraving craftsmanship assets through targeted recruitment of retiring Portuguese and Spanish specialists. Invest in hot-melt self-adhesive coating capacity to capture Brazil and India's retail modernization procurement. Defend against thermal substrate commoditization by embedding proprietary leuco-dye chemistry formulations. For New Entrants and Emerging Players: Begin with specialty coating applications for limited-edition commemorative booklets in Brazil and India, where security-feature premiums exceed standard-grade margins. Target Correios' and India Post's thematic release programs with UV-fluorescent and holographic layer integration. Establish technical partnerships with automated kiosk manufacturers to validate thermal substrate compatibility. For Investors and Strategic Acquirers: The window for entry favors integrated pulp-to-paper manufacturers with traceable supply chains and existing BIS or EU Green Deal certifications. Monitor postal digitization rates and letter-mail volume trajectories as inflection indicators for transactional substrate demand erosion against commemorative segment resilience.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cotton-Linen Supply | Captive fiber sourcing from Egyptian and Brazilian suppliers satisfies EU Green Deal traceability mandates. |
| Thermal Substrate R&D Partnership | Collaboration with German and Japanese kiosk manufacturers validates leuco-dye chemistry performance specifications. |
| Cylinder Engraver Apprenticeship Program | Knowledge transfer from retiring French and Spanish craftsmen preserves multi-tonal watermarking capabilities. |
| ISO 1874 Certification Investment | Archival-grade paper standards command price multiples from philatelic collector segments. |
| Brazil-India Distribution Joint Venture | Localized booklet assembly operations align with Correios and India Post retail modernization timelines. |
Research Methodology
Document review covered customs trade data, BIS certification registries, and EU Green Deal compliance filings, complemented by interviews with security paper plant managers, postal procurement officers at Deutsche Post and India Post, cylinder engraving specialists, and downstream printing equipment manufacturers. Secondary validation drew from SEC filings of integrated substrate manufacturers, ISO standards documentation, and national postal authority annual reports. Bottom-up volume estimates triangulated against top-down procurement budget allocations.
Segment-level demand projections incorporate product format evolution, substrate material specifications, and end-user procurement patterns across the analysis window. CAGRs derive from postal digitization trajectory modeling, commemorative issuance program expansion rates, and thermal kiosk deployment schedules. Industry-specific inputs include cotton fiber price volatility indices and security feature adoption curves in limited-edition releases.
Underlying measurement precision varies by segment; thermal substrate and self-adhesive format forecasts carry tighter precision than legacy moisture-activated gum projections. Forecasts reflect assumptions about postal modernization program continuity and collector segment resilience against transactional mail decline. Practitioners should monitor unmanned kiosk deployment rates and long-staple cotton harvest yields for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Coated White Board Paper Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Ultraflute Paper Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Corrugated Fish Box Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Australia Paper Packaging Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Plastic Toilet Paper Dispenser Market
Paper & Paperboard Packaging
Paper Bubble Wrap Market
Paper & Paperboard Packaging
Pre-Impregnated Paper Market
Paper & Paperboard Packaging
Food Contact Paper and Board Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Corrugated Board Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market