
 Europe Mailer Packaging Market | 2026-2036
Europe Mailer Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mailer Packaging Market Intelligence
The direct-to-consumer channel is narrowing as e-commerce platforms consolidate supplier bases and demand standardized mailer specifications. Mondi leverages its integrated paper and recycling infrastructure across Central Europe to supply kraft mailers at scale. Sealed Air competes through proprietary bubble cushioning technologies embedded in padded mailer laminates. DS Smith anchors its position via recycled corrugated board mailers tailored to fashion and electronics subscription services.
Europe mailer packaging comprises lightweight, self-sealing envelopes and pouches engineered from paper, plastic films, bubble laminates, or corrugated board, typically featuring adhesive or zipper closures and designed to protect flat or moderately dimensional goods during single-trip postal and courier distribution. Poly mailers dominate volume due to their gram-for-gram shipping cost advantage over rigid alternatives, while padded mailers capture premium margin pools in electronics and cosmetics where cushioning is non-negotiable. Paper mailers sustain the fastest structural expansion as the EU Green Deal and national extended producer responsibility schemes penalize non-recyclable plastic formats.
REACH and the EU Packaging and Packaging Waste Regulation constrain virgin plastic content and mandate design-for-recycling criteria across mailer formats sold in member states. ECHA substance restrictions further limit certain adhesive chemistries, pushing converters toward water-based and bio-derived sealants. Stakeholders must monitor PPWR implementation timelines and recyclability certification schemes to secure shelf access in France, Germany, and Benelux retail ecosystems.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles as converters must eliminate multi-layer laminates and pivot toward mono-material or fiber-based formats before enforcement timelines activate.
Growth Catalysts
- Last-mile delivery density:Urban consolidation centers in Germany and France are driving poly mailer volume as carriers optimize payload efficiency per delivery stop.
- REACH substance restrictions:Adhesive reformulation mandates are accelerating water-based sealant adoption across Benelux converter networks.
- Fashion subscription services:Weekly replenishment models in apparel and cosmetics are creating dedicated mailer procurement pipelines with standardized sizing.
Market Restraints
- Recycled fiber cost volatility:OCC price swings in Central Europe are compressing margin on kraft mailer production.
- Extrusion-grade PE concentration:Three petrochemical suppliers control the majority of film resin supply to Southern European converters.
- Mechanical recycling limitations:Current sorting infrastructure cannot separate padded mailer laminates at commercial scale.
Strategic Opportunities
- Poland and Czech Republic e-commerce penetration:Underdeveloped fulfillment infrastructure in these markets presents first-mover positioning for regional mailer suppliers.
- Reusable mailer systems:Deposit-return pilots in France are testing durable polypropylene formats for high-frequency urban delivery loops.
- CSRD disclosure requirements:Scope 3 packaging emissions reporting is creating premium positioning for mailers with verified recycled content.
Industry Challenges
- Recyclability certification timelines:Obtaining OPRL or Der Grüne Punkt approval for novel mono-material formats requires 12-18 month validation cycles.
- Legacy heat-sealing equipment:Converters face capex burdens to retool lines for lower-temperature bio-adhesive activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mailer Packaging Market |
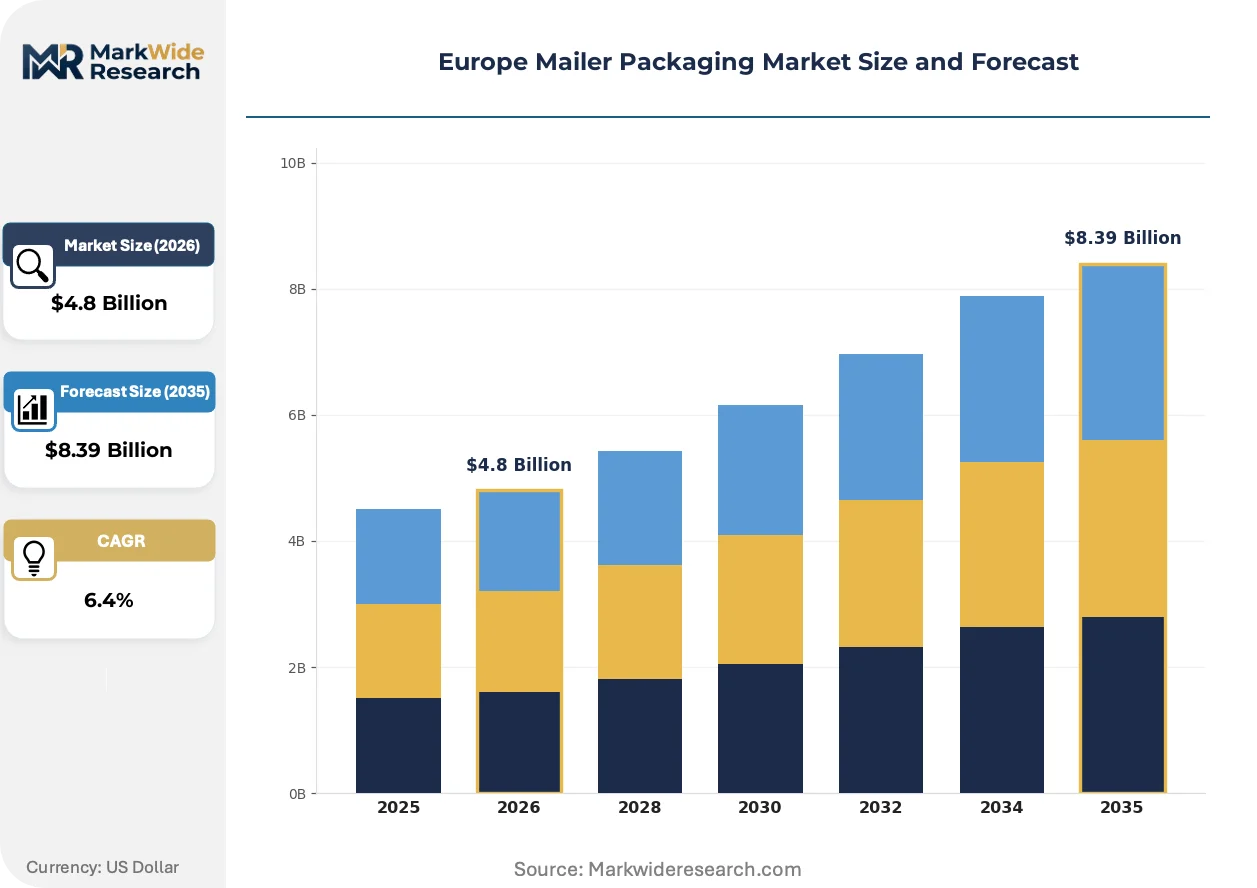
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Mailer Type: Poly Mailers, Rigid Mailers, Padded Mailers, Flat Mailers Material: Plastic, Paper, Bubble Wrap, Corrugated Board Closure Type: Adhesive Seal, Zipper Seal, String Tie, Self-Sealing End User: E-commerce, Retail, Logistics, Healthcare |
| Companies Covered | Mondi, Sealed Air, DS Smith, Henkel Corporation, Intertape Polymer Group, Storopack Hans Reichenecker GmbH, Pregis LLC, Stora Enso, Abriso Jiffy, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mailer Packaging Market Strategic Shifts & Innovations
Digital printing and smart encoding are collapsing minimum order quantities while enabling batch-level traceability. Material science breakthroughs are dissolving the performance gap between fiber and plastic protection.
Digital print integration is digitizing mailer customization workflows. Brand owners in cosmetics and electronics are adopting variable-data printing for regionalized messaging and return-code embedding. This compression of setup economics is digitizing the traditional trade-off between scale efficiency and personalization.
REACH Annex XVII restrictions on persistent organic pollutants are forcing adhesive reformulation across European converter bases. The regulation is disqualifying solvent-based chemistries from shelf access in German retail ecosystems. Fashion and electronics verticals are responding by mandating water-based sealant specifications in supplier scorecards.
Consolidated procurement through platform marketplaces is narrowing supplier bases as Amazon and Zalando enforce dimensional and material standardization. Long-tail merchants are losing negotiating leverage against approved vendor lists. This concentration is most visible in the United Kingdom, where marketplace fulfillment networks control the majority of last-mile packaging specification.
Europe Mailer Packaging Market Segmentation
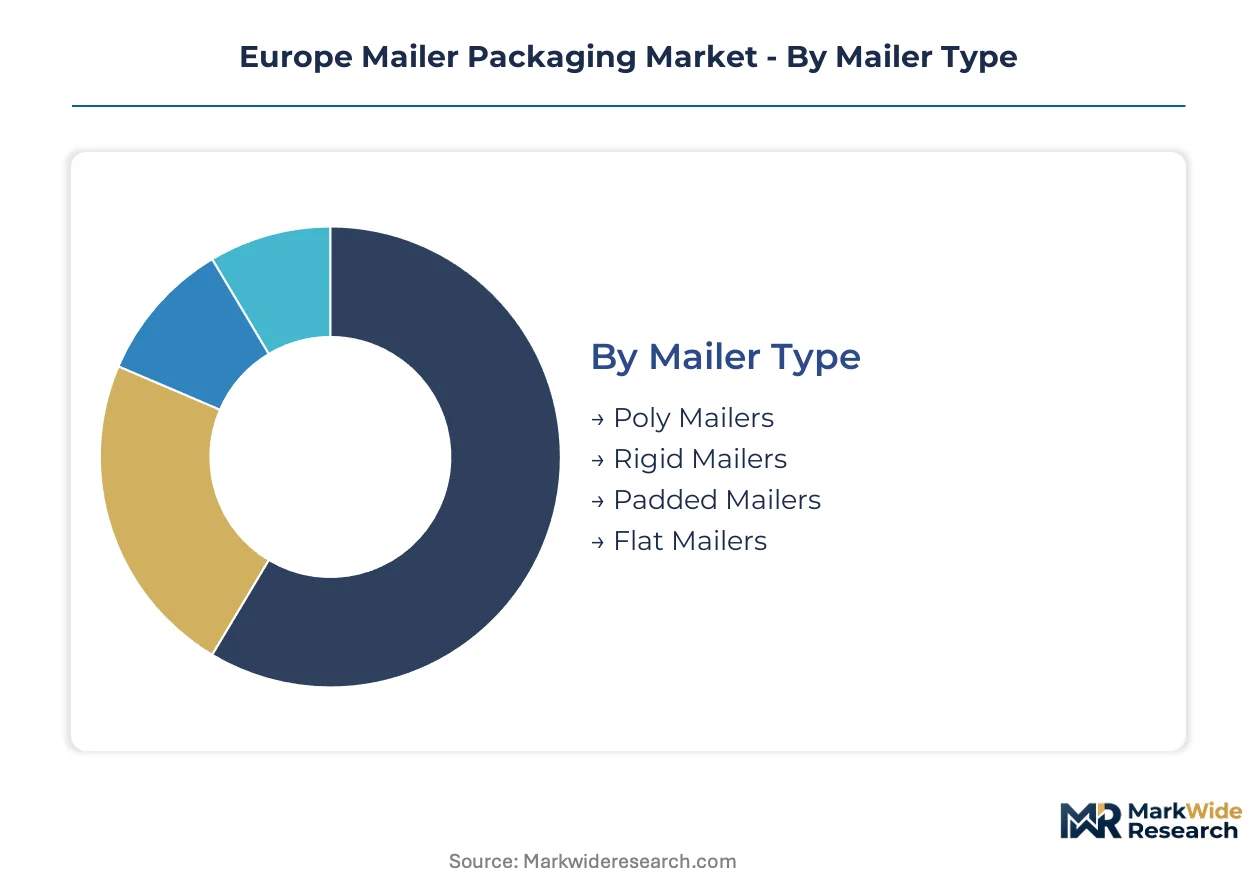
Mailer packaging segments diverge sharply in inventory velocity and specification stability. Poly mailers turn weekly in fulfillment centers while rigid formats sit in longer procurement cycles. Understanding these rhythm differences shapes converter capacity planning and raw material hedging strategies.
Mailer Type:
Cycle times separate these segments dramatically. Poly mailers rotate through distribution centers in days, whereas rigid mailers lock into quarterly replenishment schedules with major retailers.
- Poly Mailers:Lightweight polyethylene or polypropylene pouches with self-adhesive strips dominate last-mile payload optimization. German and French carriers specify these for urban consolidation routes where gram reduction directly fuels delivery economics. REACH compliance pressures are accelerating mono-material redesigns away from multi-layer laminates.
- Padded Mailers:Bubble-lined or foam-cushioned envelopes protect electronics and cosmetics through automated sorting infrastructure. Demand concentrates in Benelux subscription fulfillment hubs where damage rates trigger immediate supplier switches. The segment captures premium positioning through proprietary cushioning geometries.
- Rigid Mailers:Stay-flat cardboard or fiberboard envelopes prevent bending for documents and vinyl media. UK music and publishing verticals sustain niche procurement pipelines with exacting stiffness specifications.
- Flat Mailers:Unpadded paper or plastic sleeves serve low-value apparel and printed materials. Polish e-commerce entrants favor these for cost-minimized cross-border shipments.
Poly mailers anchor the volume base while padded mailers gain share at the steepest rate.
Material:
Cost tiers stratify procurement behavior. Virgin plastic sits at the economy pole while certified recycled paper commands measurable premiums in French and German retail ecosystems.
- Plastic:LDPE and HDPE films deliver the lowest unit cost per shipment. Southern European converters rely on concentrated petrochemical supply chains with limited resin alternatives. PPWR recyclability mandates are forcing mono-material standardization across extrusion lines.
- Paper:Kraft and recycled fiber formats satisfy EU Green Deal procurement scorecards. DS Smith and Mondi operate integrated recycling infrastructure that insulates margin from OCC volatility. Fashion brands in the United Kingdom are mandating paper mailers for customer-facing unboxing experiences.
- Bubble Wrap:Air-retention films laminated to substrate layers provide impact protection. Current mechanical recycling infrastructure cannot separate these composites at commercial scale.
- Corrugated Board:E-flute and micro-flute constructions serve heavy or rigid contents. Electronics subscription services specify these for return-loop durability requirements.
Paper formats are climbing fastest in procurement priority while plastic retains absolute volume leadership.
Closure Type:
Application context dictates seal selection. High-frequency handling favors instant adhesion while reusable loops demand mechanical durability.
- Adhesive Seal:Pressure-sensitive hot-melt or acrylic strips enable single-use security. Water-based formulations are displacing solvent chemistries under ECHA Annex XVII restrictions.
- Zipper Seal:Interlocking plastic tracks support product returns and multi-use scenarios. Cosmetics sampling programs in France specify these for customer retention mechanics.
- String Tie:Twine or ribbon closures serve artisanal and luxury positioning. Niche demand persists in German craft marketplaces.
- Self-Sealing:Integrated adhesive zones without separate liner removal accelerate packing line throughput. Amazon fulfillment centers mandate these specifications across vendor lists.
Adhesive seals dominate shipment counts while zipper formats expand in return-centric business models.
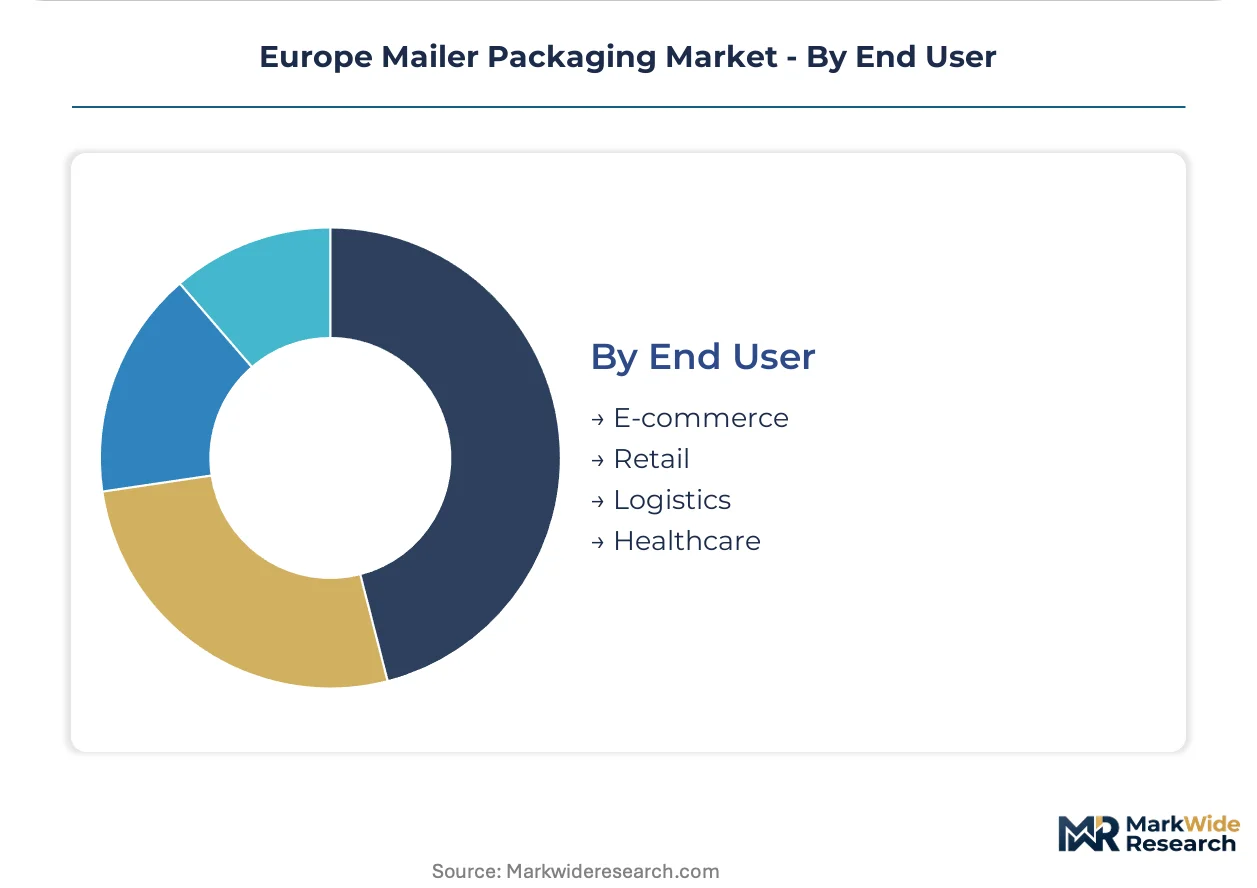
End User:
Customer type determines specification stringency and contract structure. Platform marketplaces enforce standardization while healthcare maintains isolated compliance pathways.
- E-commerce:Pure-play and omnichannel retailers drive aggregate demand through automated fulfillment networks. Zalando and Amazon procurement teams dictate dimensional tolerances and material certifications that cascade through supplier tiers.
- Retail:Brick-and-mortar chains utilize mailers for ship-from-store and direct-to-customer replenishment. UK fashion retailers are consolidating vendor bases to reduce specification variance.
- Logistics:Third-party carriers and postal operators source mailers as operational inputs. Deutsche Post and La Poste negotiate volume contracts with recyclability performance clauses.
- Healthcare:Medical device and pharmaceutical distributors require sterile barrier compatibility and traceability encoding. This segment operates under MDR documentation requirements that extend procurement cycles.
E-commerce commands the volume base while healthcare mailers expand most quickly on compliance-driven specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France commands measurable pricing premiums over Poland as sustainability certification requirements stratify procurement economics across the region. German buyers absorb mid-tier positioning while Southern European markets trade on volume efficiency.
Germany
Deutsche Post's urban consolidation centers and Zalando's fulfillment networks drive poly mailer consumption at scale. The Verpackungsgesetz mandates minimum recycled content thresholds that reshape converter sourcing strategies. The Ruhr industrial corridor hosts extrusion specialists retooling for mono-material PE formats ahead of PPWR enforcement.
France
La Poste's last-mile density and cosmetics subscription services sustain padded mailer demand with exacting cushioning specifications. The AGEC law and forthcoming deposit-return pilots for reusable formats create regulatory complexity for importers. The Lyon logistics cluster anchors regional distribution for paper-based alternatives serving premium fashion brands.
United Kingdom
Amazon and ASOS procurement teams enforce dimensional standardization that compresses supplier margins across vendor lists. Extended producer responsibility schemes under the UK Packaging Waste Regulations accelerate design-for-recycling investments. The Midlands fulfillment belt concentrates automated packing line deployments with adhesive seal specifications.
Poland
E-commerce penetration lags Western benchmarks, creating first-mover positioning for regional mailer suppliers targeting cross-border fulfillment. The country's packaging waste directive implementation timeline trails EU core markets by 18-24 months. The Warsaw-Łódź corridor attracts converter investments serving German retail supply chains with cost-optimized poly formats.
Netherlands
Rotterdam port logistics and Benelux distribution hub status sustain transhipment packaging demand with rapid inventory velocity requirements. KIDV recyclability certification protocols create technical barriers for non-compliant imports. The Eindhoven-Tilburg manufacturing zone hosts adhesive specialists reformulating for water-based sealant specifications under REACH Annex XVII.
Europe Mailer Packaging Market Key Industry Players
Integrated paper conglomerates and specialized protective packaging firms split the market along material-technology lines. Three-tier supplier concentration is visible: multinational converters with captive fiber supply, regional extrusion specialists serving price-sensitive channels, and niche cushioning technology licensors. Strategic moves center on backward integration into recycled fiber sourcing and geographic expansion into underpenetrated Central European fulfillment markets.
Within the integrated paper tier, Mondi and DS Smith occupy positions defined by captive recycling infrastructure and kraft mailer scale. Sealed Air exemplifies the protective technology archetype through proprietary bubble laminate positioning. These three anchors illustrate how material science capabilities and supply chain control separate premium positioning from commodity competition in European procurement ecosystems.
| Leading Market Players |
|---|
| Mondi |
| Sealed Air |
| DS Smith |
| Henkel Corporation |
| Intertape Polymer Group |
| Storopack Hans Reichenecker GmbH |
| Pregis LLC |
| Stora Enso |
| Abriso Jiffy |
| Others |
Cost & Logistics Intelligence
The Ruhr industrial corridor's extrusion capacity expansion directly shapes converter pricing power across German retail procurement networks. PPWR compliance investments in mono-material PE lines are compressing margins on legacy multi-layer formats while elevating certified alternatives.
Pricing Analysis
The customization-premium spread separates configured-to-order kraft mailers from standard poly formats by certification grade and volume scale. Contract-based long-term offtake dominates enterprise procurement through Zalando and Amazon vendor lists, while spot purchasing persists among Polish cross-border entrants. Price differentiation hinges on recyclability certification tier and geographic delivery density. Cost compression in virgin plastic tiers is intensifying because OCC volatility feeds through to recycled fiber alternatives. Fashion subscription services show least price sensitivity; Polish e-commerce entrants absorb maximum pressure.
Supply Chain Analysis
Contract-manufacturing concentration rests with Mondi and DS Smith captive fiber operations across Central Europe, plus regional extrusion specialists in Southern Europe. Geographic supply concentration centers on Germany, France, and Poland. Raw material dependencies draw from LDPE resin, OCC recovered fiber, and water-based adhesive chemistries. Single-source vulnerability in extrusion-grade PE from concentrated petrochemical suppliers threatens format-switching timelines. Distribution runs through platform marketplace fulfillment networks with standardized specification enforcement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as reusable mailer pilots in France threaten single-use volume pools. Deposit-return mechanics for durable polypropylene formats could displace conventional procurement if scaled beyond urban testbeds.
For Market Incumbents: Harden recyclability certification pipelines through accelerated OPRL and Der Grüne Punkt validation cycles. Secure backward integration into OCC sourcing to insulate margin from fiber volatility. The threat of reusable format mandates from AGEC law extensions demands pre-emptive mono-material capacity locks in the Ruhr corridor.
For New Entrants and Emerging Players: Establish a beachhead in Poland's underdeveloped fulfillment infrastructure before PPWR implementation trails close the window. Target Czech Republic e-commerce penetration with cost-optimized poly formats. The most penetrable entry angle runs through cross-border logistics providers serving German retail supply chains.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because adhesive reformulation capabilities and captive fiber supply separate premium positioning from commodity compression. Acquisition targets should display integrated recycling infrastructure and water-based sealant R&D pipelines. Monitor KIDV certification adoption velocity in Benelux as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Format Conversion | PPWR compliance secures shelf access in German retail ecosystems. |
| Backward Integration into OCC Sourcing | Captive fiber supply insulates margin from price volatility. |
| Water-Based Adhesive R&D Investment | REACH Annex XVII alignment eliminates solvent chemistry disqualification. |
| Reusable Mailer Pilot Partnership | La Poste deposit-return trials position for regulatory optionality. |
| Digital Print Customization Scale-Up | Variable-data capability captures cosmetics brand personalization demand. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with converter operations directors, procurement leads at Amazon and Zalando fulfillment networks, adhesive formulation specialists, and sustainability compliance officers; plus secondary validation through EU Packaging and Packaging Waste Regulation implementation documents, ECHA substance restriction databases, KIDV recyclability certification records, and Benelux customs trade flows. Bottom-up capacity assessments triangulated against top-down demand modeling from e-commerce platform fulfillment disclosures.
Forecast inputs considered mailer type, material format, closure mechanism, and end-use vertical across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by procurement contract visibility and regulatory enforcement timelines. Modeled variables included PPWR implementation phasing, REACH adhesive reformulation adoption curves, and urban consolidation center deployment density.
Sensitivities concentrate around PPWR enforcement acceleration, reusable format mandate expansion, and OCC price spike duration. Forecasts reflect assumptions on substitution elasticity and certification timeline adherence. Quarterly review of KIDV approval velocity and deposit-return pilot scale metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
China Paper Packaging Market
Paper & Paperboard Packaging
Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Masking Paper Market
Paper & Paperboard Packaging
Paper and Paperboard Trays Market
Paper & Paperboard Packaging
Paperboard Partition Market
Paper & Paperboard Packaging
Paper Band Market
Paper & Paperboard Packaging
Postal Papers Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Middle East and Africa Paper Packaging Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
Kraft Envelopes Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Paper Carrier Bags Market
Paper & Paperboard Packaging
Countertop Paper Napkin Dispenser Market
Paper & Paperboard Packaging
United Kingdom (UK) Corrugated Board Packaging Market