
 C1S Packaging Paper Market | 2026-2036
C1S Packaging Paper Market Size, Share, and Industry Trends Forecast 2026-2036
C1S Packaging Paper Market Analytics
The EU Packaging and Packaging Waste Regulation is consolidating demand for recyclable, fiber-based packaging across European consumer goods sectors. International Paper leverages its North American mill network to supply high-volume C1S grades to multinational food brands. Mondi anchors its competitive position through integrated pulp-to-paperboard operations in Central Europe. Stora Enso differentiates via biobased barrier coatings that replace plastic films in chilled food applications.
Coated one-side packaging paper consists of bleached or unbleached kraft board with a mineral pigment coating applied to a single surface, typically achieving gloss levels of 60-85 at 75 degrees and basis weights ranging from 200 to 400 gsm for folding carton applications. Its primary purpose is to provide superior print receptivity and visual impact on the exterior of retail packaging while maintaining uncoated, foldable integrity on the interior. Food Grade segments dominate volume due to stringent direct-contact safety requirements that limit supplier qualification pools. Label Paper represents the fastest-expanding category as beverage and cosmetic brands migrate from film to fiber-based pressure-sensitive substrates.
EMA, ECHA, and the EU Green Deal framework collectively shape material compliance pathways, with REACH restrictions on perfluorinated substances forcing coating reformulation across the value chain. CE marking requirements for food-contact materials create certification barriers that favor established producers with dedicated regulatory affairs functions. Stakeholders must monitor evolving extended producer responsibility fee structures, as these will determine regional cost competitiveness for C1S board versus alternative substrates.
Market Dynamics
Coated one-side packaging paper demand is consolidating around fiber-based barrier coatings as REACH restrictions on perfluorinated substances force coating reformulation across European converting operations. This regulatory pressure is compressing supplier qualification pools and accelerating capital deployment toward compliant coating technologies.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightening recyclability mandates across member states are consolidating demand for fiber-based substrates that eliminate multi-material separation costs.
- Food and beverage premiumization:Ready-to-eat brands are migrating toward coated paperboard for exterior print impact and direct-contact safety compliance.
- Germany converting capacity expansion:Significant capacity additions for coated folding cartons are concentrating regional demand and pulling upstream C1S board volumes.
Market Restraints
- Pulp cost volatility:Bleached kraft pulp prices fluctuate with Nordic and Brazilian supply disruptions, compressing margin predictability for integrated and non-integrated producers alike.
- Supplier concentration risk:Central European pulp-to-paperboard operations control critical coating technology, creating bottleneck vulnerability for converters without backward integration.
- Plastic film substitution threat:Thin-gauge barrier films retain cost advantages in high-moisture applications where fiber-based coatings face performance ceilings.
Strategic Opportunities
- Label Paper segment acceleration:Beverage and cosmetic brands are migrating from film to fiber-based pressure-sensitive substrates, expanding addressable volume for C1S grades with adhesive-compatible surfaces.
- Extended producer responsibility tailwinds:Evolving fee structures in EU member states are improving relative cost competitiveness of recyclable C1S board versus alternative substrates.
- Biobased barrier coating convergence:Chilled food applications are opening to mineral-pigment and polysaccharide coatings that replace plastic films without sacrificing shelf-life performance.
Industry Challenges
- CE marking certification timelines:Food-contact material approvals require extensive migration testing that delays new coating chemistry deployment by 18-24 months.
- Coating formulation talent scarcity:Regulatory affairs functions with REACH and EFSA expertise are concentrated among established producers, constraining new entrant qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | C1S Packaging Paper Market |
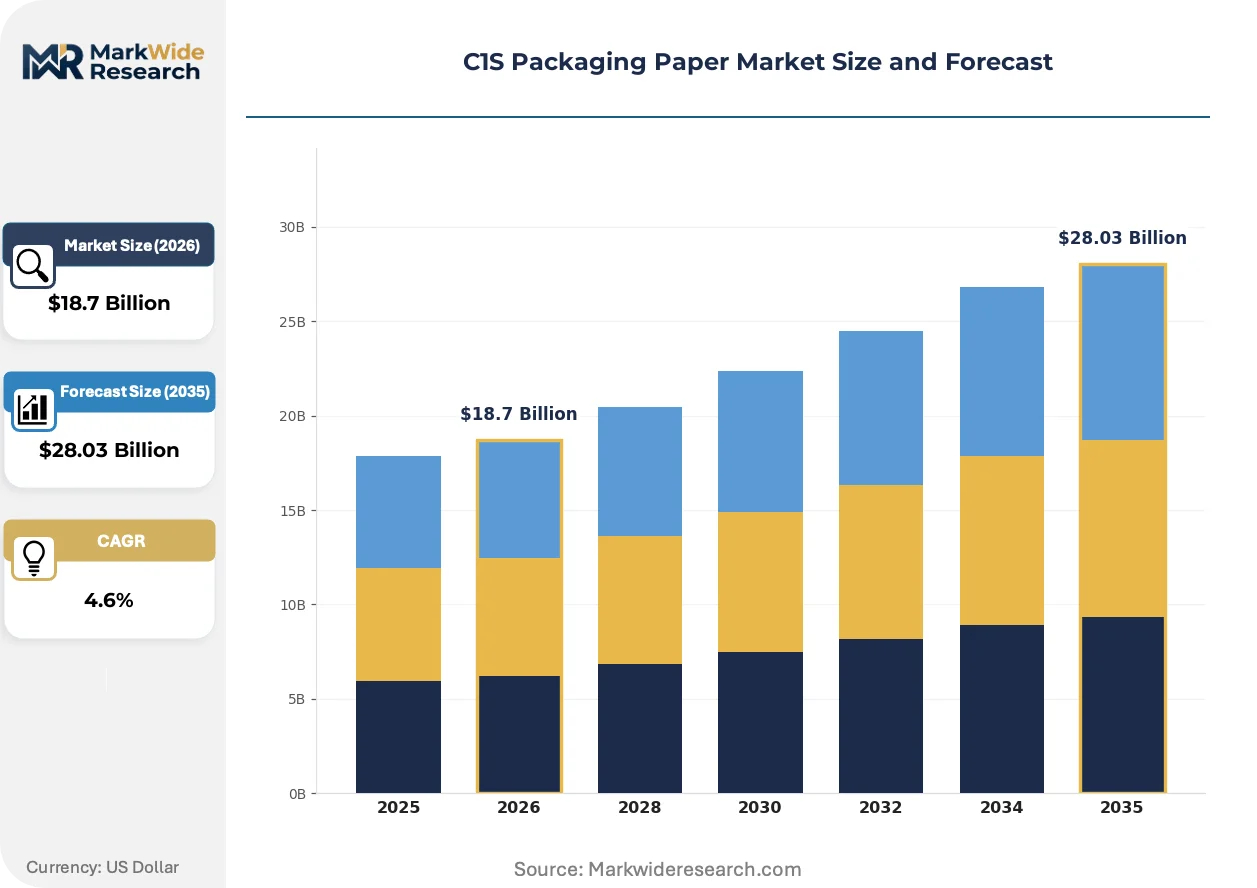
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Custom Coatings, Water Resistant, Label Paper End User: Food & Beverage, Personal Care, Retail, Electronics Application: Box Packaging, Labeling, Wrapping, Promotional Materials Distribution Channel: Online Retail, Direct Sales, Wholesale, Specialty Stores |
| Companies Covered | International Paper, UPM-Kymmene, Westrock, APP, Nippon Paper Group, Mondi, Smurfit Kappa, Stora Enso, Sappi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
C1S Packaging Paper Market Evolving Landscape
Coating chemistry and converting technology are advancing in parallel as regulatory deadlines compress development cycles. The intersection of barrier performance and recyclability is driving material science investment toward single-fiber solutions.
Mineral-pigment coatings with biobased binders are converging with high-speed flexographic printing systems to enable direct food contact without secondary lamination. Premium chocolate and confectionery brands in Belgium and Switzerland are adopting these systems at accelerated pace. This convergence is compressing the traditional multi-step converting chain into integrated coating-printing operations.
REACH restrictions on perfluorinated substances are eliminating legacy grease-resistant chemistries from European food packaging supply chains. Industrial consequence includes forced reformulation of coating recipes across folding carton and label paper grades. Chilled ready-meal segments in Germany and France are responding fastest, with converters qualifying alternative barrier systems ahead of enforcement deadlines.
Brand procurement teams are consolidating supplier relationships around integrated pulp-to-paperboard producers with captive coating development capabilities. Direct mill relationships are displacing merchant distribution in high-volume folding carton accounts. This concentration is most visible in German retail packaging supply chains, where private-label food brands demand single-source accountability for compliance and sustainability claims.
C1S Packaging Paper Market Segmentation
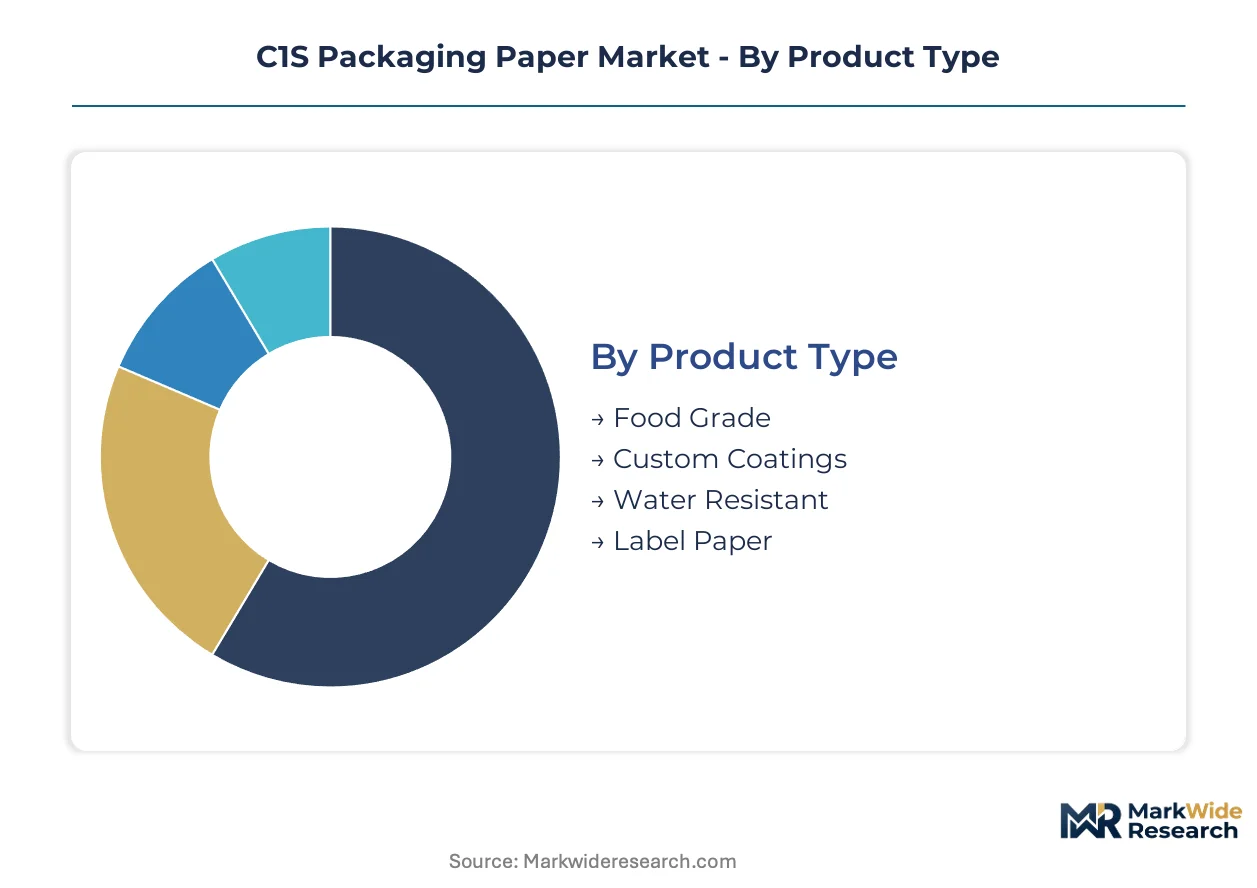
C1S packaging paper segments diverge sharply on coating chemistry and compliance pathways, with food-contact grades demanding migration-tested barrier systems while label papers prioritize adhesive compatibility and print fidelity. Each segment carries distinct qualification timelines and capital requirements that reshape supplier positioning.
Product Type:
Coating upgrades follow replacement cycles tied to REACH enforcement milestones, with converters reformulating barrier systems every 3-5 years to maintain compliance.
- Food Grade:Bleached kraft base stock carries mineral-pigment coatings with biobased binders certified for direct food contact under EFSA migration limits. German chilled ready-meal brands and Belgian chocolate packagers are consolidating procurement around mills with captive coating development labs, compressing qualification pools to integrated producers.
- Label Paper:Single-side coated substrates engineered for pressure-sensitive adhesive lamination, achieving smoothness levels of 200-300 Sheffield units for high-resolution flexographic printing. Beverage brands in France and cosmetic labels in Switzerland are migrating from film to fiber-based substrates, expanding specification volumes for adhesive-compatible C1S grades.
- Custom Coatings:Specialty formulations combining mineral pigments with polysaccharide barriers for niche moisture-resistance requirements.
- Water Resistant:Repulpable barrier coatings replacing polyethylene extrusion in fresh produce and frozen food cartons.
Food Grade sits at the top of the volume ranking, with Label Paper climbing the fastest.
End User:
Cost tier segmentation separates premium brand owners demanding single-source compliance accountability from private-label operators optimizing across merchant distributors.
- Food & Beverage:Ready-to-eat and premium confectionery segments specify coated folding cartons with exterior gloss for shelf impact and uncoated interior for fold integrity. Private-label consolidation in German retail is pulling volume toward direct mill relationships.
- Personal Care:Cosmetic and skincare brands specify label-grade C1S for pressure-sensitive applications, with Swiss and French houses leading fiber-based substrate migration.
- Retail:Point-of-sale and promotional packaging requiring high print fidelity on exterior surfaces.
- Electronics:Anti-static coated boards for small-device secondary packaging.
Food & Beverage commands the largest procurement volumes, while Personal Care is gaining share fastest on premiumization trends.
Application:
Application mix tracks converting technology adoption, with inline coating-printing systems displacing multi-step lamination for shorter-run premium jobs.
- Box Packaging:Folding carton applications dominate, with C1S board forming exterior shells for ready-meal trays and confectionery boxes. German converting capacity expansion is concentrating regional demand for 250-350 gsm grades.
- Labeling:Pressure-sensitive label faces require precise smoothness and adhesive compatibility, with beverage brands driving specification shifts toward fiber-based substrates.
- Wrapping:Gift and promotional wrapping papers utilizing coated exterior for visual impact.
- Promotional Materials:High-gloss direct mail and display applications.
Box Packaging anchors absolute tonnage, with Labeling expanding most quickly on beverage industry substrate migration.
Distribution Channel:
Channel structure reflects customer scale and compliance complexity, with multinational brands bypassing merchants for direct mill accountability.
- Direct Sales:High-volume folding carton accounts in Germany and France negotiate direct mill relationships to secure single-source accountability for REACH compliance and extended producer responsibility documentation. This channel captures the largest accounts but requires dedicated regulatory affairs support.
- Wholesale:Merchant distributors serve mid-tier converters lacking backward integration, though coating technology concentration in Central Europe creates bottleneck vulnerability.
- Online Retail:E-procurement platforms for standardized grades and spot purchases.
- Specialty Stores:Niche distributors for custom coating formulations and small-batch orders.
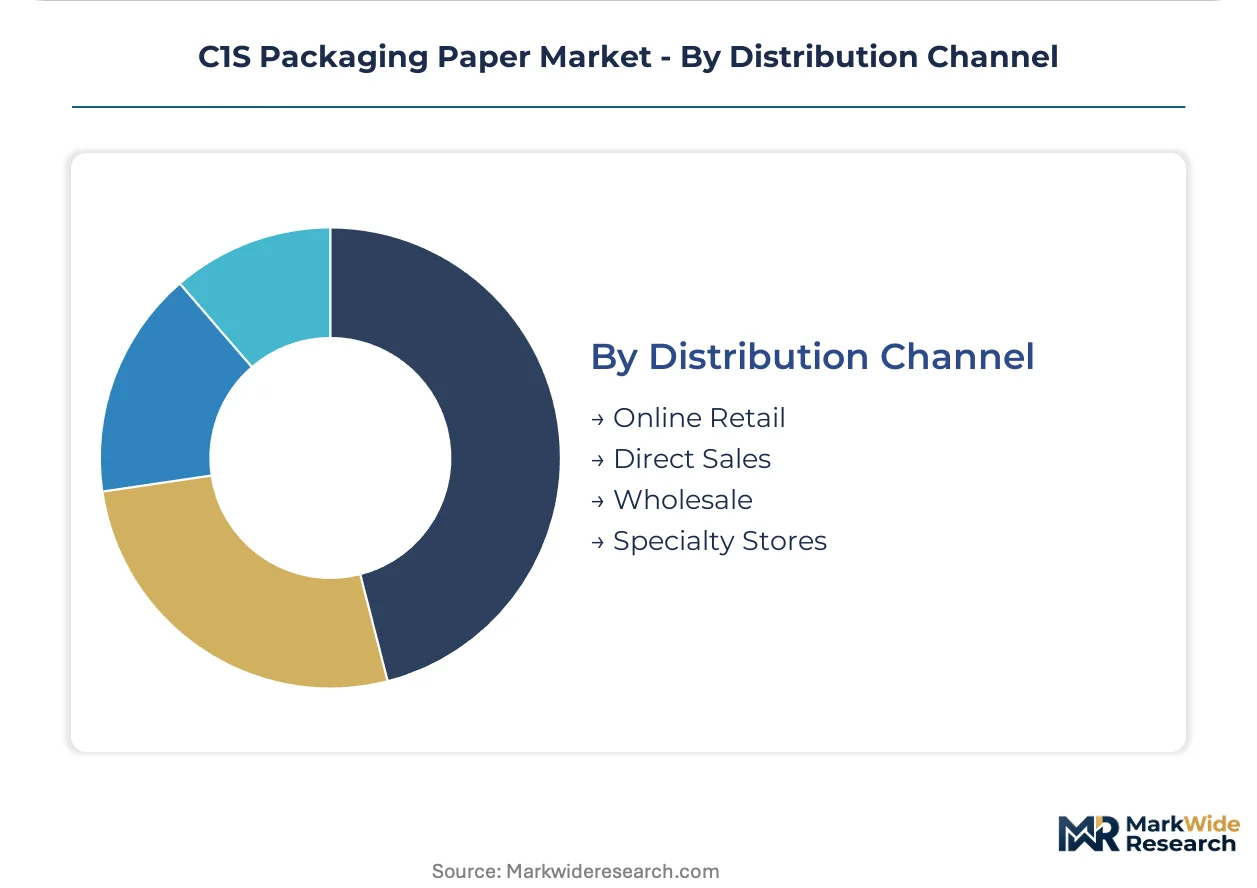
Direct Sales dominates value concentration, with Online Retail climbing fastest on spot-market digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coated one-side packaging paper originated in European industrial centers where folding carton technology first scaled for confectionery and consumer goods. German mills pioneered mineral-pigment coating systems during the mid-twentieth century, establishing technical standards that persist across the value chain.
Germany
Chilled ready-meal brands and private-label retailers drive specification volumes for food-grade C1S board. REACH restrictions on perfluorinated substances force coating reformulation across converting operations. The Rhine-Ruhr corridor concentrates folding carton capacity expansion, pulling upstream board demand toward integrated pulp-to-paperboard mills.
United States
Multinational food brands procure high-volume C1S grades for premium ready-to-eat packaging with exterior print impact. FDA food-contact regulations govern migration limits for direct-contact applications. The Southeast paperboard corridor anchors converting capacity for quick-service restaurant chains and retail private-label programs.
China
Domestic beverage and cosmetic brands accelerate migration from film to fiber-based label substrates. GB standards for food-contact materials create compliance pathways distinct from Western regulatory frameworks. The Yangtze River Delta cluster concentrates coating technology development for export-oriented folding carton producers.
France
Cosmetic houses and luxury confectionery brands specify high-gloss C1S grades for pressure-sensitive label and box applications. EFSA migration testing requirements extend qualification timelines for new coating chemistries. The Lyon-Grenoble axis hosts specialized converters serving premium chocolate and skincare packaging segments.
Belgium
Premium chocolate packagers adopt mineral-pigment coatings with biobased binders for direct food contact without secondary lamination. EU Green Deal packaging waste directives accelerate fiber-based substrate adoption. The Antwerp-Brussels industrial zone concentrates high-speed flexographic printing integration with inline coating systems.
C1S Packaging Paper Market Competitive Landscape
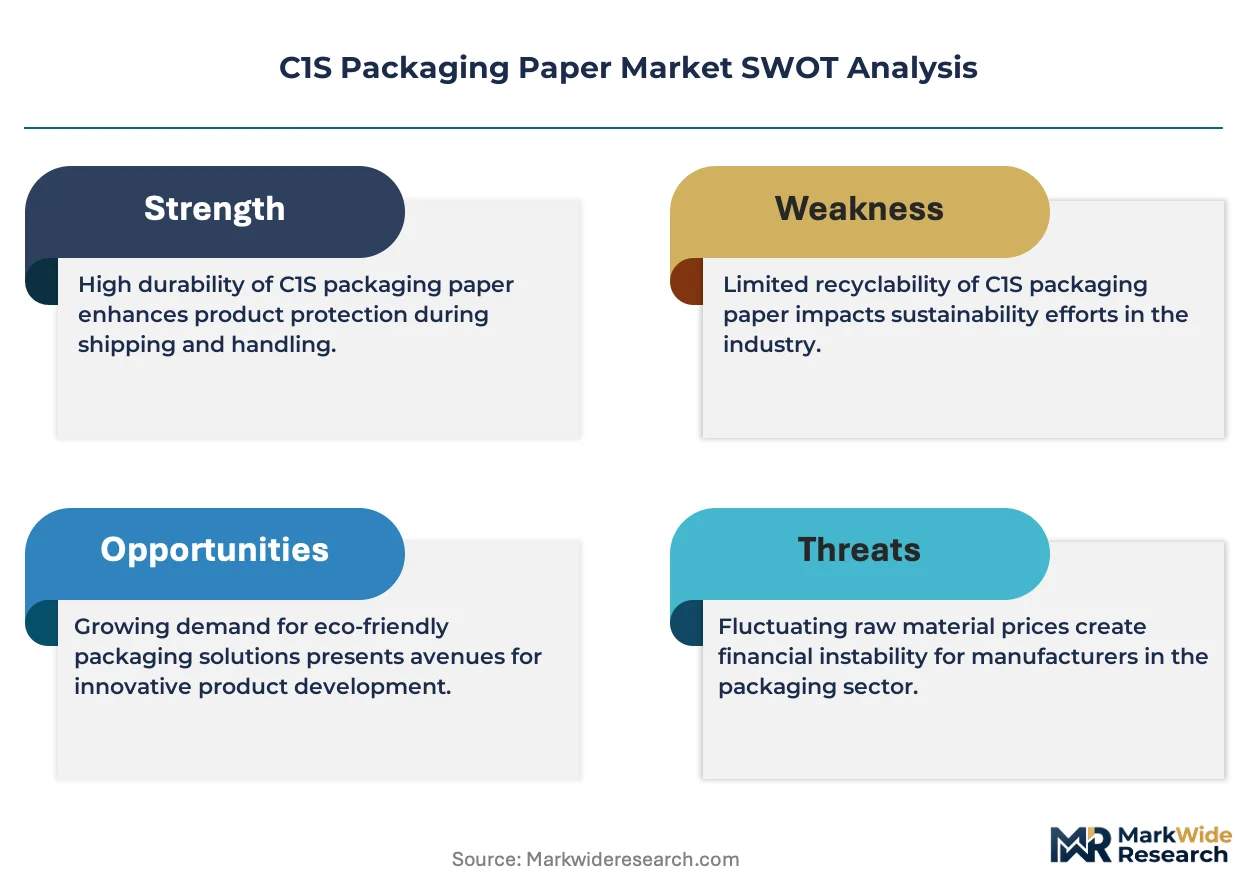
Capital-heavy producers compete with asset-light designers across divergent margin structures. Integrated pulp-to-paperboard operators command coating technology and regulatory certification advantages. Merchant converters without backward integration face bottleneck vulnerability in Central European supply chains. Three archetypes dominate: integrated forest products conglomerates with captive coating labs, regional paperboard specialists serving merchant channels, and diversified packaging converters with in-house specification development. Competitive moves concentrate on strategic partnerships for compliant coating access and geographic expansion into German retail packaging supply chains.
Within the integrated tier, International Paper, Mondi, and Stora Enso exemplify divergent strategic positions. International Paper anchors North American supply to multinational food brands through high-volume mill networks. Mondi occupies a position emphasizing Central European pulp-to-paperboard integration with captive coating development capabilities. Stora Enso represents the biobased barrier coating vector, with mineral-pigment and polysaccharide systems targeting chilled food applications. These three entities illustrate how regulatory affairs scale, geographic mill placement, and coating chemistry investment separate competitive outcomes in REACH-constrained markets.
| Leading Market Players |
|---|
| International Paper |
| UPM-Kymmene |
| Westrock |
| APP |
| Nippon Paper Group |
| Mondi |
| Smurfit Kappa |
| Stora Enso |
| Sappi |
| Others |
Value Network & Pricing Analysis
Bleached kraft pulp price indices cascade through C1S board supply chains, compressing margin structures at integrated mills and forcing tiered pricing stratification across food-grade, label-grade, and economy specifications. REACH-driven coating reformulation costs concentrate pricing power with captive coating developers in Germany and Finland, while merchant converters absorb volatility through quarterly contract renegotiation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs C1S board transactions, with EFSA-certified food-contact grades commanding substantial premiums over label-grade alternatives. Price differentiation hinges on migration-testing documentation and volume scale, with multinational food brands locking annual contracts while mid-tier converters face spot-market exposure. Cost compression in standard grades is intensifying because Nordic pulp supply disruptions feed directly into board pricing formulas. Private-label retailers exhibit highest price sensitivity, whereas premium chocolate and cosmetic houses prioritize compliance assurance over unit cost.
Supply Chain Analysis
Regional distribution centers in the Rhine-Ruhr corridor and Antwerp-Brussels axis coordinate hub-and-spoke delivery patterns for German and Benelux converting clusters. Supply concentrates in Finland, Sweden, and Germany, where integrated pulp-to-paperboard operations control critical coating technology. Raw material dependencies draw from Brazilian eucalyptus pulp, Nordic softwood kraft, and mineral pigment suppliers in France. Single-source vulnerability around biobased barrier coating chemistries creates bottleneck risk for non-integrated converters. Distribution runs through direct mill relationships for high-volume accounts and merchant wholesalers for mid-tier operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
C1S packaging paper represents a late-cycle quality story as food and beverage brands consolidate procurement around REACH-compliant, single-source suppliers capable of EFSA migration documentation. Premium specification demand from Belgian chocolate packagers and French cosmetic houses reinforces pricing power for integrated producers with captive coating labs.
For Market Incumbents: Extend coating formulation capabilities through captive R&D investment in mineral-pigment and polysaccharide barrier systems, defending against plastic film substitution in high-moisture applications. Add converting capacity in the Rhine-Ruhr corridor to anchor German private-label relationships. Backward integration into pulp supply hedges Brazilian and Nordic price volatility. For New Entrants and Emerging Players: Launch via specialty coating partnerships serving Swiss cosmetic labels and French beverage brands migrating from film substrates. White-space targets include adhesive-compatible label grades for pressure-sensitive applications and custom water-resistant formulations for fresh produce cartons. The most penetrable segment sits in mid-tier personal care labels, where specification requirements remain less stringent than direct food-contact grades. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated pulp-to-paperboard operators possessing captive coating development and established EFSA certification pathways. Long-term viability over the next decade favors assets with German mill placement and direct retail brand relationships. Watch REACH enforcement milestones as inflection indicators for coating chemistry replacement cycles and supplier qualification pool compression.| Strategic Initiative | Industry Significance |
|---|---|
| Biobased Barrier Coating Development | REACH restrictions on perfluorinated substances force reformulation investment toward EFSA-compliant mineral-pigment systems. |
| Direct Mill Relationship Expansion | German retail private-label consolidation pulls volume away from merchant channels toward single-source accountability. |
| Label Paper Capacity Addition | Beverage and cosmetic substrate migration from film to fiber expands addressable volume for adhesive-compatible grades. |
| Coating-Printing Integration | Inline flexographic systems in Belgium and Germany compress converting chains for premium chocolate packaging. |
| Extended Producer Responsibility Positioning | Evolving EU fee structures improve relative cost competitiveness of recyclable C1S board versus plastic alternatives. |
Research Methodology
Bottom-up food-grade and label-grade modeling reconciled against top-down pulp-to-paperboard capacity tracking forms the analytical core of this study. Primary interviews with coating R&D directors, folding carton procurement managers at German retailers, EFSA regulatory affairs specialists, and merchant distribution executives combined with secondary validation from customs trade data, Cefic chemical industry reports, SEC filings of listed forest products companies, and EU Packaging and Packaging Waste Regulation implementation documents. Triangulation across these sources anchored volume and value estimates.
Input-output matrices map bleached kraft pulp supply through coating formulation stages to finished C1S board output across the projection horizon. Segmentation dimensions include product type certification tier, end-use industry, application format, and regional converting cluster. CAGRs were derived from trend extrapolation of historical capacity utilization and demand elasticity modeling against REACH compliance cost pass-through. Forecast inputs incorporate pulp price volatility assumptions and coating technology adoption curves for biobased barrier systems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated REACH enforcement timelines or sustained Nordic supply disruptions. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that coating qualification delays and extended producer responsibility fee restructuring could materially revise trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paperboard Partition Market
Paper & Paperboard Packaging
Asia Pacific Paper Packaging Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Display Paper Box Market
Paper & Paperboard Packaging
United States Corrugated Packaging Market
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Global Folding Boxboards Market
Paper & Paperboard Packaging
Flowpack Paper Packaging Market
Paper & Paperboard Packaging
Italy Honeycomb Paper Market
Paper & Paperboard Packaging
Paper Waste Strippers Market
Paper & Paperboard Packaging
Desiccant Paper Market
Paper & Paperboard Packaging
Folding Paperboard Boxes Market
Paper & Paperboard Packaging
Letterpress Card Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market
Paper & Paperboard Packaging
Postage Stamp Paper Market