
 Gable Top Liquid Cartons Market | 2026-2036
Gable Top Liquid Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Gable Top Liquid Cartons Market Analysis
Polyethylene-coated paperboard is repositioning conventional multilayer plastic bottles across European dairy shelves. Tetra Pak International S.A. leverages its aseptic technology heritage to dominate extended-shelf-life dairy applications. Elopak AS anchors its position through renewable polyethylene sourcing from Brazilian sugarcane feedstock. SIG competes aggressively in the food service channel with high-speed filling equipment compatibility.
Gable top liquid cartons are paperboard-based containers with folded, peaked roofs and sealed side seams, typically incorporating polyethylene or aluminum barrier layers to prevent oxygen and moisture ingress for perishable beverages. The format serves primarily as a retail-ready packaging solution for milk, juice, and plant-based drinks requiring chilled distribution. Dairy applications occupy the largest volume share among product type segments, while beverage variants with enhanced oxygen barriers command the strongest margin pools. Retail channels sustain the dominant application position, though food service formats with portion-controlled volumes are expanding fastest in institutional contracts.
EU REACH regulations and the EU Green Deal packaging waste framework mandate recyclability thresholds that reshape substrate selection across European converters. FDA food contact substance notifications govern barrier coating approvals for US dairy and juice packagers, while China's GB standards enforce heavy-metal limits on imported paperboard packaging materials. Stakeholders must monitor evolving extended producer responsibility schemes and substrate certification timelines to secure compliant material pipelines before regulatory deadlines activate.
Market Dynamics
EU Green Deal packaging waste mandates are forcing substrate reselection across European dairy converters, accelerating polyethylene-coated paperboard displacement of multilayer plastic bottles before 2030 recyclability deadlines.
Growth Catalysts
- REACH compliance pressure:ECHA substance restrictions on single-use plastics redirect dairy processors toward fiber-based barrier formats with renewable polyethylene layers.
- Brazilian sugarcane feedstock expansion:Bio-based polyethylene capacity from Braskem and regional suppliers anchors renewable substrate pipelines for Latin American beverage packagers.
- Aseptic filling line upgrades:Extended-shelf-life dairy applications in Indonesia and Nigeria adopt gable top formats previously limited to chilled distribution, opening ambient-stable revenue pools.
Market Restraints
- Aluminum barrier supply concentration:Thin-gauge aluminum foil for oxygen-blocking layers concentrates among Chinese and Russian smelter networks, exposing converters to geopolitical input volatility.
- Polyethylene price tethering to naphtha:Fossil-derived coating resins remain cost-locked to petrochemical feedstock swings despite bio-based alternatives.
- Recycling infrastructure misalignment:Mixed-material cartons face sorting rejection at European paper mills lacking polyethylene separation capacity, creating circularity friction under EU waste directives.
Strategic Opportunities
- Indonesian plant-based beverage acceleration:Oat and coconut milk producers in Jakarta and Surabaya seek barrier-enhanced cartons with tropical humidity resistance for export markets.
- Food service portion-control formats:Institutional contracts for schools and hospitals in France and Germany specify single-serve gable top volumes below 250ml, a white space outside retail-dominant portfolios.
- Digital printing integration:Variable-data decoration enables regional dairy brands to compress SKU launch cycles from months to weeks.
Industry Challenges
- Polymer-to-paper adhesion chemistry:Water-based barrier coatings require reformulation expertise scarce among legacy polyethylene extrusion technicians.
- Extended producer responsibility fee structures:Germany's VerpackG and France's Citeo impose per-unit recycling fees that compress margins on low-volume specialty formats.
- Legacy filling equipment incompatibility:Retrofitting 1980s-era dairy lines for modern carton dimensions demands mechanical engineering talent concentrated at original equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gable Top Liquid Cartons Market |
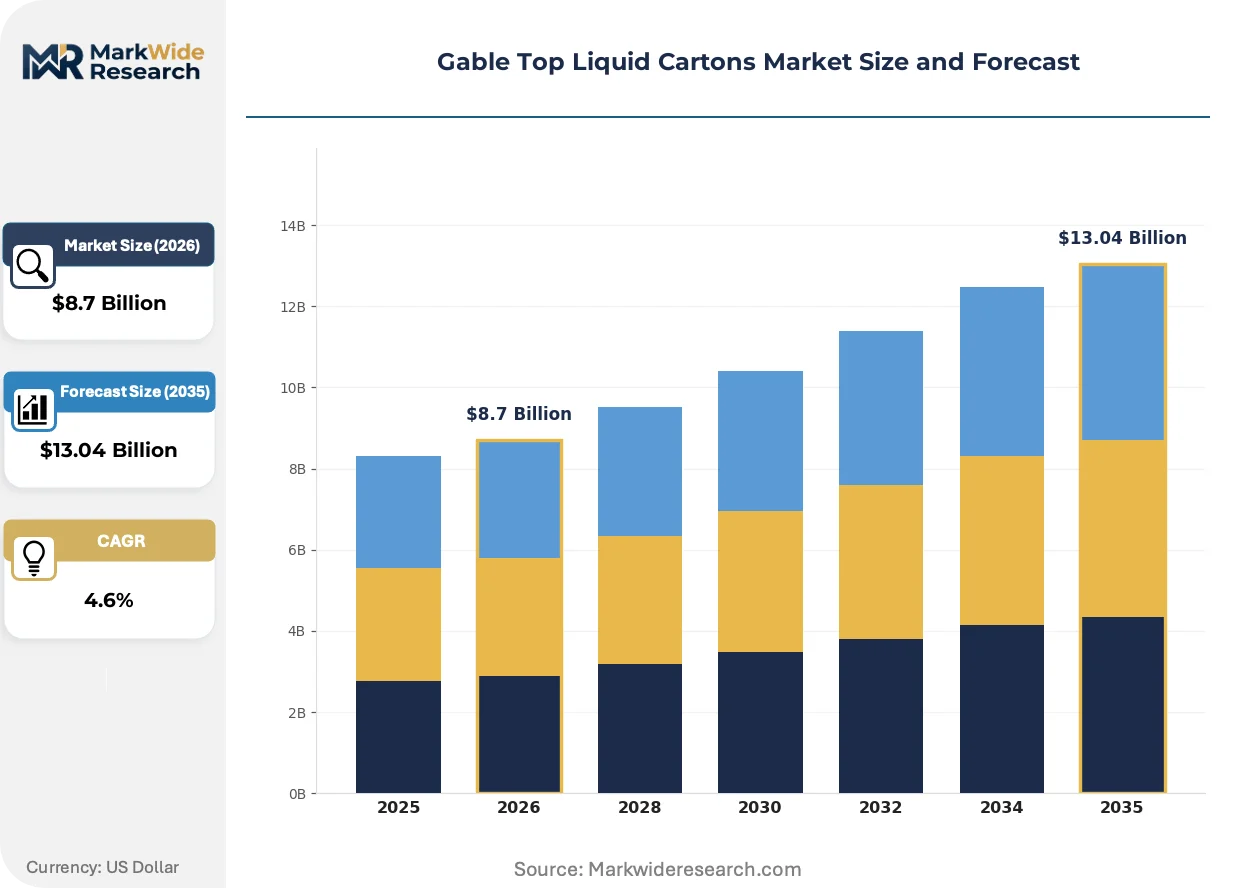
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Juice, Beverage, Dairy Material: Paperboard, Plastic, Aluminum, Composites Application: Food Service, Retail, Institutions, Home Consumption End User: Manufacturers, Distributors, Retailers, Consumers |
| Companies Covered | Tetra Pak International S.A., Elopak AS, SIG, Pactiv Evergreen, Smurfit Kappa, Amcor plc, International Paper, Westrock Company, Nippon Paper Industries Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gable Top Liquid Cartons Market Emerging Trajectories
Barrier coating chemistry and digital production workflows are compressing format development cycles while regulatory deadlines force substrate decisions ahead of recycling infrastructure readiness.
Water-based barrier coatings with nanocellulose reinforcement are modularizing the protective layer stack in gable top cartons. Mid-size juice processors in Spain and Portugal pilot these formulations to eliminate aluminum foil entirely. The technology is modularizing supply chains by decoupling oxygen protection from metal inputs, enabling regional paperboard mills to enter liquid packaging previously blocked by aluminum sourcing constraints.
EU Green Deal packaging waste framework revisions mandate 70% recyclability thresholds for beverage containers by 2030. German dairy cooperatives and French retail chains accelerate polyethylene-coated paperboard adoption to preempt compliance penalties. Chilled dairy segments face the steepest reselection pressure, as pure plastic bottles lose shelf access under retailer sustainability scorecards.
Direct-to-processor procurement contracts are displacing distributor-mediated substrate purchasing among Brazilian and Indonesian beverage manufacturers. Plant-based milk startups in São Paulo and Jakarta negotiate polyethylene supply directly with Braskem and regional biopolymer producers, compressing margin layers and accelerating formulation feedback loops. This pattern concentrates most visibly in oat and coconut milk verticals where brand owners prioritize speed-to-shelf over legacy supply chain risk distribution.
Gable Top Liquid Cartons Market Segmentation
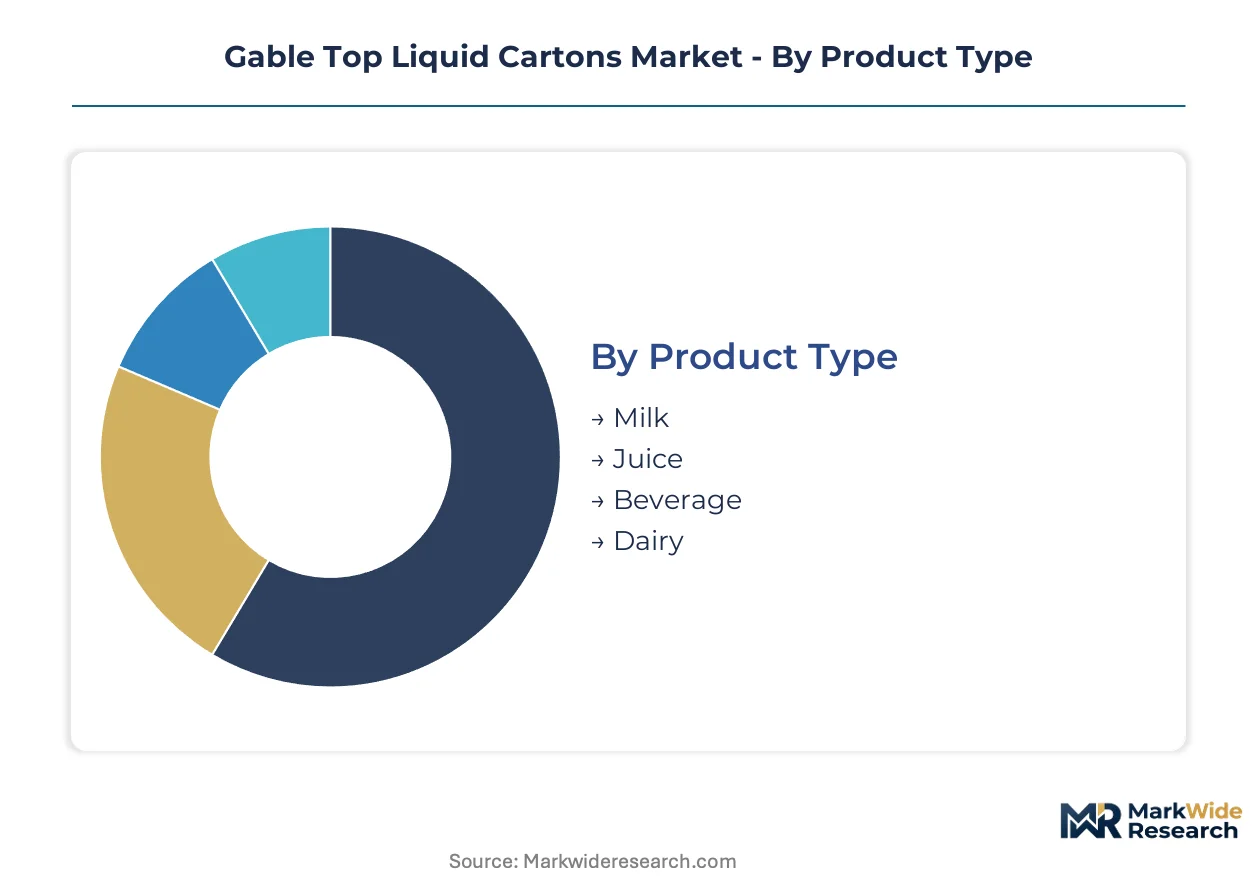
Segmentation in gable top liquid cartons reveals how substrate specifications and distribution channels fragment procurement patterns. Each dimension carries distinct margin profiles and regulatory exposure that reshape converter investment priorities.
Product Type:
Supply concentration for barrier-coated substrates tilts heavily toward chilled dairy applications with established polyethylene extrusion infrastructure.
- Milk:Polyethylene-coated paperboard dominates fresh and extended-shelf-life formats across European and Latin American dairy cooperatives. German and French processors under EU Green Deal mandates are displacing multilayer plastic bottles with fiber-based alternatives before recyclability deadlines.
- Juice:Oxygen-sensitive formulations require aluminum-barrier or nanocellulose-reinforced cartons for ambient distribution. Spanish and Portuguese mid-size processors pilot water-based barrier coatings to eliminate metal inputs entirely.
- Beverage:Plant-based oat and coconut milk variants in Brazil and Indonesia drive demand for tropical humidity-resistant barrier systems with renewable polyethylene layers from sugarcane feedstock.
- Dairy:Fermented products and cream segments utilize higher-barrier constructions with enhanced moisture protection for extended chilled shelf life.
Milk absorbs the bulk of installed capacity; Beverage is expanding most quickly.
Material:
Cost tiers separate legacy fossil-derived coatings from emerging bio-based alternatives with premium positioning.
- Paperboard:Bleached and unbleached kraft grades form the structural substrate, with European mills expanding capacity for liquid packaging board under REACH compliance pressure. Recyclability certification from paper mill networks determines converter qualification status.
- Plastic:Polyethylene extrusion layers—fossil-derived and bio-based—provide heat-seal functionality and moisture barriers. Braskem's Brazilian sugarcane polyethylene anchors renewable supply pipelines for Latin American beverage packagers.
- Aluminum:Thin-gauge foil oxygen barriers concentrate among Chinese and Russian smelter networks, exposing converters to geopolitical input volatility and supply disruption risk.
- Composites:Multi-layer constructions combining paperboard, plastic, and aluminum face sorting rejection at European paper mills lacking separation capacity, creating circularity friction under extended producer responsibility schemes.
Paperboard and Plastic composites absorb the bulk of installed capacity; bio-based Plastic alternatives are climbing the fastest.
Application:
Volume concentration in retail channels contrasts with margin expansion in institutional food service contracts.
- Food Service:Single-serve formats below 250ml for schools and hospitals in France and Germany command premium positioning outside retail-dominant portfolios. Portion-control specifications require dedicated filling line configurations.
- Retail:Multi-serve chilled dairy and juice cartons sustain dominant volume share through supermarket and hypermarket distribution. Retailer sustainability scorecards increasingly block pure plastic bottle shelf access.
- Institutions:Bulk-format supply for cafeterias and catering operations emphasizes cost efficiency over barrier sophistication, with longer contract cycles and lower SKU variety.
- Home Consumption:Direct-to-consumer subscription models for specialty plant-based beverages are emerging in São Paulo and Jakarta with customized digital printing for regional brand differentiation.
Retail absorbs the bulk of installed capacity; Food Service is gaining share fastest.
End User:
Customer type determines procurement complexity, with direct-to-processor contracting displacing distributor intermediation in high-growth verticals.
- Manufacturers:Dairy processors and plant-based beverage startups negotiate substrate supply directly with Braskem and regional biopolymer producers, compressing margin layers and accelerating formulation feedback loops.
- Distributors:Legacy intermediary networks face disintermediation as Brazilian and Indonesian oat and coconut milk producers prioritize speed-to-shelf over supply chain risk distribution.
- Retailers:French and German retail chains impose sustainability scorecards that mandate polyethylene-coated paperboard adoption, preempting regulatory compliance penalties.
- Consumers:End-user recycling behavior and sorting discipline determine actual circularity outcomes, with contamination rates affecting extended producer responsibility fee calculations.
Manufacturers absorb the bulk of procurement volume; Retailers are driving specification change fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port and Indonesia's Batam Free Trade Zone concentrate liquid packaging substrate conversion capacity for Asia-Pacific beverage exports. European dairy processors cluster near Rotterdam and Hamburg port zones to secure renewable polyethylene supply chains.
Germany
Dairy cooperatives in Bavaria and Lower Saxony are retrofitting filling lines for polyethylene-coated paperboard formats ahead of VerpackG extended producer responsibility deadlines. The EU Green Deal packaging waste framework mandates 70% recyclability thresholds by 2030. Hamburg's port infrastructure anchors renewable polyethylene import pipelines from Brazilian sugarcane feedstock suppliers.
United States
Wisconsin and California dairy processors face FDA food contact substance notification requirements for novel barrier coatings in extended-shelf-life applications. The EPA's emerging focus on per- and polyfluoroalkyl substances in food packaging is accelerating water-based barrier pilot programs. Chicago's food service distribution hub demands portion-control formats below 250ml for institutional contracts.
Brazil
São Paulo's oat and coconut milk startups negotiate direct polyethylene procurement with Braskem's bio-based sugarcane operations. ANVISA governs food contact approvals for tropical humidity-resistant barrier systems. The Triângulo Mineiro dairy cluster is converting multilayer plastic bottle lines to gable top formats for export compliance with EU retailer sustainability scorecards.
Indonesia
Jakarta and Surabaya plant-based beverage manufacturers seek barrier-enhanced cartons for coconut milk export to European and Middle Eastern markets. The national standards body enforces heavy-metal limits on imported paperboard packaging materials. Batam's free trade zone concentrates aseptic filling equipment assembly for regional dairy and juice processors.
France
Normandy dairy processors under Citeo extended producer responsibility schemes are displacing pure plastic bottles with fiber-based alternatives. EU REACH regulations restrict single-use plastic substances in food contact applications. The Île-de-France retail corridor imposes sustainability scorecards that block non-recyclable packaging from shelf access.
Gable Top Liquid Cartons Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated packaging groups dominating retail dairy while regional converters capture food service niches. The market exhibits moderate consolidation among substrate suppliers and fragmentation among filling equipment integrators. Three archetypes anchor competitive positioning: multinational aseptic technology licensors, renewable substrate specialists with captive biopolymer supply, and regional paperboard converters serving institutional contracts. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players secure compliant material pipelines before regulatory deadlines activate.
Within the multinational technology tier, Tetra Pak International S.A. and Elopak AS exemplify divergent strategic postures. Tetra Pak's S.A. structure reflects its Swiss-heritage positioning in extended-shelf-life dairy applications, while Elopak's AS form anchors Nordic renewable polyethylene sourcing from Brazilian sugarcane feedstock. SIG occupies a position between these archetypes, competing aggressively in food service channel compatibility with high-speed filling equipment.
| Leading Market Players |
|---|
| Tetra Pak International S.A. |
| Elopak AS |
| SIG |
| Pactiv Evergreen |
| Smurfit Kappa |
| Amcor plc |
| International Paper |
| Westrock Company |
| Nippon Paper Industries Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Barrier coating chemists with polyethylene extrusion expertise cluster in Germany's Ruhr industrial belt and Sweden's packaging technology corridor, where labor-cost differentials of 15-25% against Southern European markets prop open spreads between premium aseptic-grade cartons and standard chilled-dairy formats.
Pricing Analysis
Volume concentrates in standard polyethylene-coated paperboard for chilled milk, while margins pool in aluminum-barrier and nanocellulose-reinforced formats for ambient juice and plant-based beverages. Three-tier pricing structure across premium, standard, and economy levels separates aseptic-compatible substrates with extended shelf-life certification from basic chilled-dairy grades and institutional bulk formats. Pricing pressure stems from Braskem's bio-based polyethylene capacity expansion in Brazil, which compresses premiums on renewable-sourced barriers. Food service buyers in French and German institutional contracts exhibit highest price sensitivity due to per-unit recycling fee exposure under extended producer responsibility schemes, while premium juice processors in Spain and Portugal absorb cost premiums for aluminum-free barrier innovation.
Supply Chain Analysis
Dual-sourcing mandates from Tetra Pak and Elopak force converters to qualify paperboard mills across at least two Nordic or Baltic countries, plus a Latin American backup for bio-based polyethylene layers. Raw material flows draw from Brazilian sugarcane feedstock for renewable polyethylene, Chinese and Russian smelter networks for thin-gauge aluminum foil, and bleached kraft pulp from Scandinavian and Canadian forests. Supply chain risk centers on geopolitical exposure to aluminum concentration, with Russian smelter sanctions triggering spot shortages in European converter networks. Distribution runs through Rotterdam and Hamburg port zones for European dairy processors, with Batam and Hainan free trade zones anchoring Asia-Pacific beverage export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized barrier coating capacity is the binding constraint propping pricing power, as water-based nanocellulose formulation expertise remains concentrated among legacy polyethylene extrusion technicians nearing retirement density in Northern Europe.
For Market Incumbents: Acquire water-based barrier coating R&D facilities in Portugal and Spain to preempt polymer-to-paper adhesion chemistry scarcity. Lock in direct polyethylene procurement contracts with Braskem's Triângulo Mineiro operations before Brazilian bio-based capacity saturates Latin American pricing tiers. Defend against SIG's food service channel aggression by retrofitting filling line compatibility for sub-250ml portion-control formats in French and German institutional markets. For New Entrants and Emerging Players: Indonesian plant-based beverage startups represent the most penetrable buyer archetype, with Jakarta and Surabaya oat milk producers seeking tropical humidity-resistant barriers for European export compliance. Target direct-to-processor procurement relationships that bypass legacy distributor networks compressing margin layers. Establish formulation partnerships with regional paperboard mills lacking aluminum sourcing access to exploit nanocellulose barrier modularization. For Investors and Strategic Acquirers: Re-rating potential sits with renewable substrate specialists with captive biopolymer supply given EU Green Deal recyclability deadline acceleration. Long-term viability favors converters integrating backward into Brazilian sugarcane polyethylene or Nordic pulp supply chains rather than pure equipment licensors. Watch for German VerpackG and French Citeo fee structure revisions as inflection signals for margin compression on low-volume specialty formats.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Polyethylene | Braskem's sugarcane feedstock partnerships secure renewable substrate pipelines ahead of EU recyclability mandates. |
| Water-based Barrier Coating Scale-up | Spanish and Portuguese pilot programs eliminate aluminum foil dependency, opening regional paperboard mill entry. |
| Food Service Format Line Retrofit | Sub-250ml portion-control configurations capture institutional contract premiums in France and Germany. |
| Direct-to-Processor Procurement Systems | São Paulo and Jakarta oat milk startups compress margin layers by negotiating polyethylene supply directly with biopolymer producers. |
| Aseptic Filling Equipment Compatibility Certification | Indonesian and Nigerian dairy processors adopt ambient-stable revenue pools previously limited to chilled distribution. |
Methodological Framework
Document review covered EU REACH substance restriction filings, FDA food contact substance notifications, and ANVISA tropical barrier approval records, complemented by interviews with liquid packaging board procurement directors at German dairy cooperatives, barrier coating R&D leads at Spanish and Portuguese pilot facilities, and food service channel managers at French retail chains. Secondary validation drew from Braskem bio-based polyethylene capacity disclosures, Chinese GB standards on imported paperboard heavy-metal limits, and extended producer responsibility fee schedules under Germany's VerpackG and France's Citeo. Bottom-up volume modeling triangulated against top-down substrate consumption estimates from Nordic and Baltic paperboard mill networks.
Segmentation outputs reflect product type disaggregation across milk, juice, beverage, and dairy formats; material tiering across paperboard, plastic, aluminum, and composite constructions; and application splits between food service, retail, institutional, and home consumption channels across the analysis window. CAGRs were derived from installed filling line capacity expansion tracked through aseptic equipment assembly records in Batam and Hainan free trade zones, cross-referenced with regulatory deadline acceleration under EU Green Deal packaging waste framework revisions. Forecast inputs incorporated Brazilian sugarcane polyethylene feedstock expansion curves and nanocellulose barrier coating pilot-to-commercial transition timelines.
Revisions become necessary when EU recyclability threshold enforcement accelerates ahead of paper mill separation capacity installation, or when aluminum foil supply disruption from geopolitical smelter network exposure exceeds six-month buffer stocks. Deviation in extended producer responsibility fee structure calculations under Germany's VerpackG or France's Citeo would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Cooler Box Market
Packaging Containers
North America Food Cans Market
Packaging Containers
Gable Boxes Market
Packaging Containers
Logistics Packaging Market
Packaging Containers
Custom Boxes Market
Packaging Containers
Pillow Pack Packaging Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Monobloc Aerosol Cans Market
Packaging Containers
Plasma Bottle Market
Packaging Containers
Slide Tray Box Market
Packaging Containers
Self - Locking Trays Market
Packaging Containers
Insulated Storage Vessel Market
Packaging Containers
Insulated Icebox Market
Packaging Containers
Child Resistant Bottles Market
Packaging Containers
Sanitizer Bottles Market
Packaging Containers
Snap Single Dose Dispensers Market