
 Stationery Films Packaging Market | 2026-2036
Stationery Films Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Stationery Films Packaging Market Analytics
Subscription-based packaging design services is shifting how film specifications get locked into long-term supply contracts. Amcor Plc leverages its global manufacturing footprint to anchor multi-year agreements with stationery distributors. Mondi Group competes through specialty kraft-polymer laminates that extend barrier performance for archival document sleeves. Smurfit Westrock dominates corrugated-film hybrid formats that integrate protective backing with transparent display windows.
Stationery films packaging comprises flexible polymer substrates engineered for optical clarity, dimensional stability, and heat-seal compatibility, typically manufactured through cast extrusion or biaxial orientation to achieve thickness tolerances between 12 and 50 microns for protecting writing instruments, paper products, and office supplies from moisture and abrasion. Polypropylene leads product type demand due to its balance of clarity and recyclability, while polyethylene sustains volume in cost-sensitive industrial wrapping where stiffness requirements remain modest. Pharmaceutical packaging application segments command premium margin pools as cleanroom-grade film specifications and child-resistant sealing protocols elevate qualification barriers for suppliers.
EPA guidelines in the United States restrict phthalate plasticizers in PVC film formulations, compelling compounders to validate bio-based alternatives through third-party certification. ECHA maintains REACH substance restrictions that shape raw material procurement across European converter networks. FDA food-contact notification requirements govern adhesive layers in laminated structures destined for stationery items with incidental oral exposure. Stakeholders must monitor evolving extended producer responsibility frameworks that recalibrate cost structures for single-use film formats.
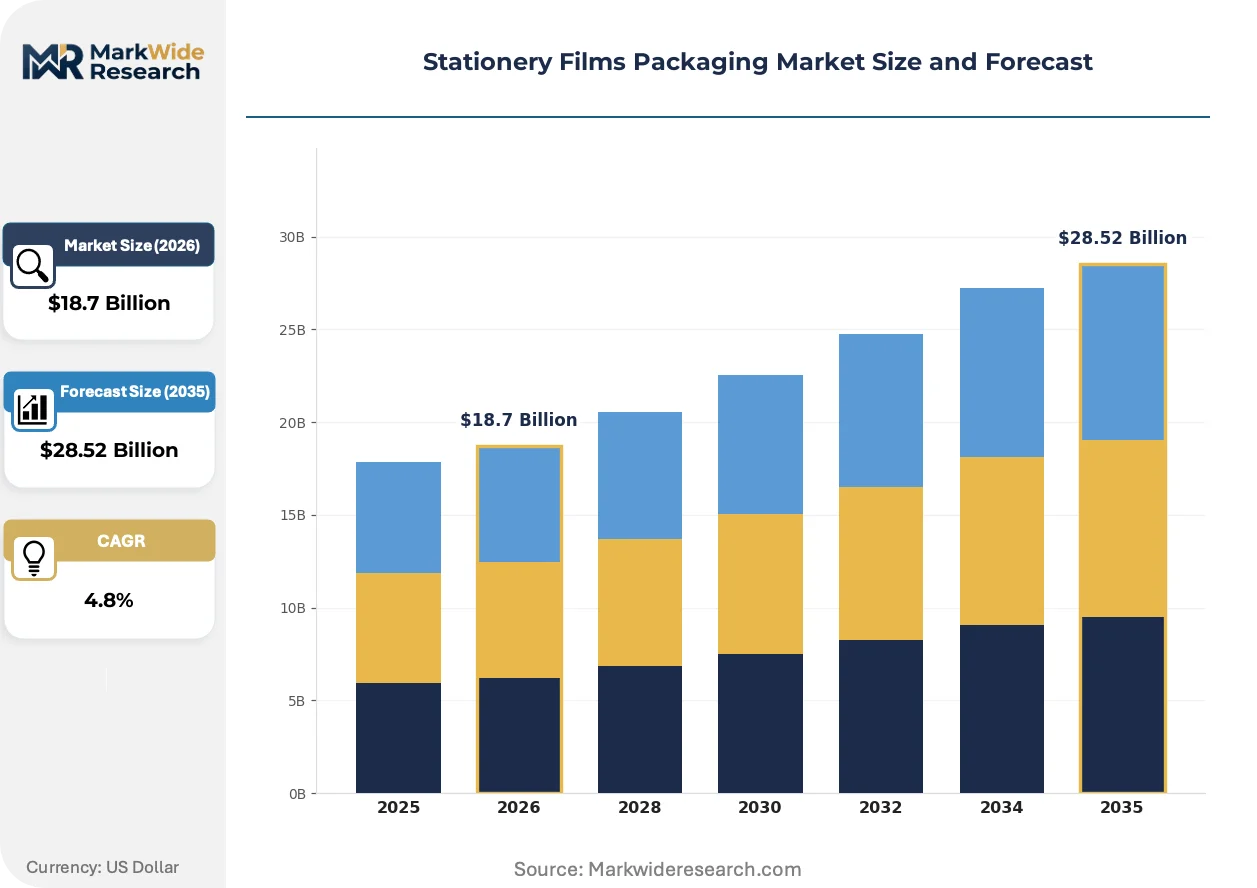
Market Dynamics
Organized retail expansion in India and subscription-based packaging design services are restructuring how film specifications get locked into long-term supply contracts, forcing converters to align capacity with multi-year agreements rather than spot purchasing cycles.
Growth Catalysts
- E-commerce fulfillment infrastructure:Stationery distributors in India are scaling automated packaging lines that require heat-seal compatible films with consistent thickness tolerances, pulling volume from traditional hand-wrapping methods.
- REACH substance restrictions:ECHA's tightening specifications for PVC alternatives in Europe are accelerating validation of bio-based plasticizers, creating qualification pathways for compounders with third-party certification capabilities.
- Pharmaceutical-grade specifications:Cleanroom-grade film requirements and child-resistant sealing protocols for archival document sleeves are elevating margin pools for suppliers with barrier-performance expertise.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyethylene resin costs fluctuate with crude oil indices, compressing converter margins when long-term contract pricing cannot adjust quarterly.
- Supply concentration in cast extrusion:Biaxial orientation capacity clusters among a limited set of equipment owners in East Asia, creating bottlenecks when regional energy costs spike.
- Technical limitation in multi-layer lamination:Adhesive layers meeting FDA food-contact notification requirements add processing complexity and extend qualification timelines for stationery items with incidental oral exposure.
Strategic Opportunities
- Underpenetrated industrial wrapping in Vietnam:Cost-sensitive polyethylene applications in Southeast Asian manufacturing hubs remain underserved by specialty film converters with archival-grade capabilities.
- EU Green Deal procurement mandates:Public sector stationery purchasing in European member states is tilting toward recyclability-certified films, rewarding suppliers with verified polypropylene circularity credentials.
- Smart packaging convergence:Integration of tamper-evident films with track-and-trace serialization is opening specification windows for converters with digital printing and variable data capabilities.
Industry Challenges
- Extended producer responsibility compliance:Evolving EPR frameworks in European member states recalibrate cost structures for single-use film formats, requiring converters to model fee liabilities across multiple jurisdictional schemes.
- Cleanroom certification timelines:Pharmaceutical packaging qualification protocols demand 12-18 month validation cycles that strain working capital before volume commitments materialize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stationery Films Packaging Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, PET Application: Food Packaging, Industrial Packaging, Pharmaceutical Packaging, Consumer Goods Packaging End User: Manufacturers, Retailers, Wholesalers, Exporters Distribution Channel: Direct Sales, Online Retail, Distributors, Retail Outlets |
| Companies Covered | Amcor Plc, Mondi Group, Smurfit Westrock, Sonoco Products Company, Huhtamaki, Stora Enso, DS Smith, TOPPAN Holdings Inc., International Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stationery Films Packaging Market Evolving Landscape
Digital specification platforms and modular production architectures are compressing the traditional film development cycle, enabling converters to prototype barrier-performance variants without dedicated production line changeovers.
Cast extrusion with inline spectrophotometric monitoring is modularizing quality assurance workflows, allowing mid-volume converters to offer thickness-tolerance guarantees previously restricted to biaxial orientation specialists. Stationery distributors with private-label programs are adopting these platforms to reduce qualification sampling from weeks to days. The structural consequence is fragmenting volume among regional players who can now compete on specification precision without capital-intensive equipment portfolios.
EPA guidelines restricting phthalate plasticizers in PVC film formulations are compelling compounders to validate bio-based alternatives through third-party certification bodies. Industrial consequence includes reformulation costs and extended material qualification timelines for converters serving the US market. Archival document sleeve manufacturers are responding by accelerating polypropylene substitution programs to preempt regulatory enforcement actions.
Buyer concentration among subscription-based stationery services is compressing switching cycles and unbundling after-sales technical support from material supply agreements. These platforms now demand real-time inventory visibility and just-in-time delivery windows that displace traditional distributor stocking models. The pattern is most visible in India where organized retail chains and direct-to-consumer brands are consolidating procurement under category managers with specification authority.
Stationery Films Packaging Market Segmentation
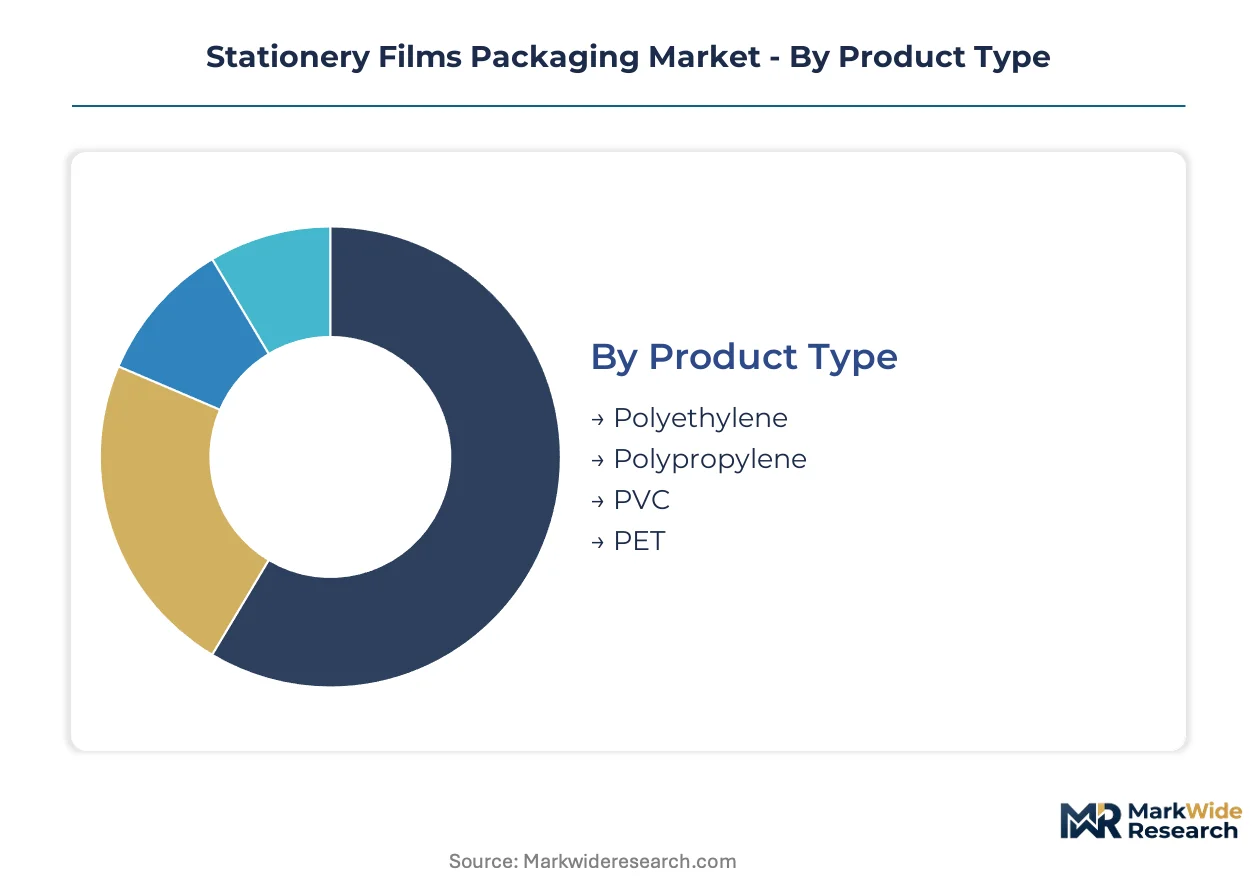
Stationery films packaging segments diverge sharply by technical specification and regulatory burden. Procurement patterns in each category reflect distinct buyer hierarchies: cost-optimized converters prioritize resin economics, while pharmaceutical-grade buyers filter for cleanroom certification and child-resistant sealing protocols.
Product Type:
Material selection hinges on optical clarity requirements, recyclability mandates, and heat-seal compatibility thresholds.
- Polypropylene:Cast extrusion and biaxial orientation deliver thickness tolerances between 12 and 50 microns with superior dimensional stability. Demand concentrates in archival document sleeves and premium writing instrument wrapping where optical clarity and recyclability credentials command specification priority.
- Polyethylene:Cost-sensitive industrial wrapping applications favor blown film extrusion for moisture barrier performance at reduced stiffness. Volume clusters in Southeast Asian manufacturing hubs where modest performance requirements align with resin economics.
- PVC:Phthalate plasticizer restrictions under EPA guidelines and REACH substance limitations are accelerating substitution programs. Compounders with third-party bio-based certification capabilities retain qualification pathways.
- PET:Biaxial orientation yields exceptional barrier performance for extended archival protection. Premium margin pools attach to pharmaceutical-grade specifications requiring cleanroom validation.
Volume sits with Polyethylene; growth tilts toward Polypropylene as EU Green Deal procurement mandates and FDA food-contact compliance reshape material selection criteria.
Application:
End-use differentiation separates commodity wrapping from qualification-intensive barrier formats.
- Consumer Goods Packaging:Shelf appeal and tamper evidence drive specification for transparent display windows in corrugated-film hybrid formats. Organized retail expansion in India pulls volume toward heat-seal compatible films with consistent gauge control.
- Pharmaceutical Packaging:Cleanroom-grade film specifications and child-resistant sealing protocols elevate qualification barriers. Validation cycles extend 12-18 months, straining working capital before volume commitments materialize.
- Industrial Packaging:Cost-sensitive wrapping of bulk stationery supplies emphasizes polyethylene moisture barriers without optical clarity requirements. Automated packaging line integration demands thickness tolerance guarantees.
- Food Packaging:FDA food-contact notification requirements govern adhesive layers in laminated structures. Incidental oral exposure risk in stationery items with gum or candy components triggers compliance protocols.
Revenue concentrates in Pharmaceutical Packaging; expansion accelerates fastest in Consumer Goods Packaging as subscription-based stationery services consolidate procurement under category managers.
End User:
Buyer scale determines contract structure and technical support bundling.
- Retailers:Organized chains and direct-to-consumer brands demand real-time inventory visibility and just-in-time delivery windows. Private-label programs compress qualification sampling cycles through digital specification platforms.
- Manufacturers:Stationery producers with captive packaging operations prioritize multi-year supply agreements locking in resin pricing. Amcor Plc anchors these relationships through global manufacturing footprint coverage.
- Wholesalers:Traditional distributor stocking models face displacement as subscription platforms unbundle after-sales technical support from material supply.
- Exporters:Cross-border shipment requirements elevate barrier performance specifications for humidity and abrasion protection during extended transit.
Contract value aggregates with Retailers; margin expansion favors Manufacturers with backward integration into film converting.
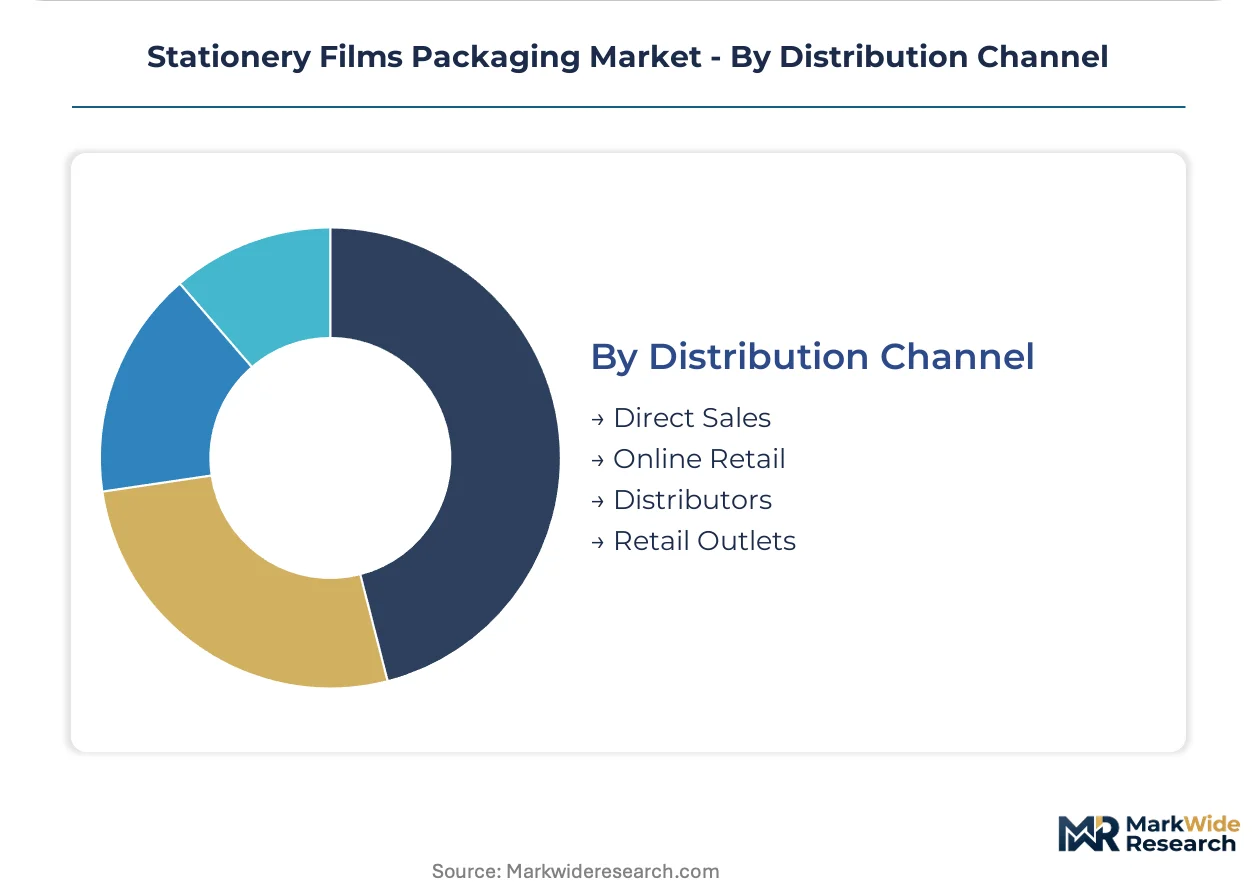
Distribution Channel:
Channel selection reflects order fragmentation and specification complexity tolerance.
- Direct Sales:Large-volume converters engage stationery distributors through multi-year agreements with locked film specifications. Technical collaboration on barrier-performance variants justifies relationship investment.
- Distributors:Regional stocking points serve mid-volume buyers without qualification capabilities for direct mill relationships. Inventory carrying costs compress margins in volatile resin price environments.
- Online Retail:Digital platforms enable specification comparison for standardized film grades. Real-time pricing transparency accelerates spot purchasing cycles.
- Retail Outlets:Small-format stationery shops source pre-converted wrapping materials through packaged goods wholesalers. Limited technical specification authority restricts segment profitability.
Transaction volume flows through Distributors; specification control migrates toward Direct Sales as subscription-based packaging design services consolidate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors the highest concentration of film converting capacity serving stationery distributors, with organized retail chains and direct-to-consumer brands consolidating procurement under category managers with specification authority.
United States
Automated packaging line adoption among e-commerce fulfillment centers drives demand for heat-seal compatible films with consistent thickness tolerances. EPA guidelines restricting phthalate plasticizers in PVC formulations compel compounders to validate bio-based alternatives through third-party certification. Industrial clusters in the Midwest and Southeast concentrate cast extrusion capacity serving private-label stationery programs.
Germany
EU Green Deal procurement mandates tilt public sector stationery purchasing toward recyclability-certified polypropylene films. ECHA maintains REACH substance restrictions that shape raw material procurement across converter networks. The Rhine-Ruhr industrial corridor hosts specialty film laminators supplying archival document sleeves with barrier-performance specifications.
India
Organized retail expansion and subscription-based stationery services restructure supply contracts toward multi-year agreements with locked specifications. BIS standards govern material safety for incidental oral exposure in gum and candy component packaging. The Delhi-NCR and Mumbai-Pune corridors concentrate automated packaging line deployment for e-commerce fulfillment.
China
Biaxial orientation capacity clusters among equipment owners in East Asia create supply bottlenecks when regional energy costs spike. GB standards and dual carbon goals pressure converters toward polypropylene substitution programs. The Yangtze River Delta hosts the densest concentration of cast extrusion lines serving export-oriented stationery manufacturers.
Vietnam
Cost-sensitive polyethylene applications in Southeast Asian manufacturing hubs remain underserved by specialty film converters with archival-grade capabilities. Industrial parks around Ho Chi Minh City attract mid-volume converters seeking to bypass Chinese supply concentration. Local distributors face displacement as regional procurement consolidates under category managers.
Stationery Films Packaging Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the stationery films packaging landscape. Consolidated ownership of biaxial orientation equipment in East Asia contrasts with fragmented regional converters operating cast extrusion lines. Three archetypes dominate: global converters anchoring multi-year supply agreements, specialty laminators targeting pharmaceutical-grade specifications, and mid-volume regional players leveraging digital specification platforms. Competitive moves center on backward integration into resin compounding and geographic expansion into underpenetrated Southeast Asian markets.
Among globally positioned converters, Amcor Plc and Mondi Group occupy positions anchoring long-term relationships with stationery distributors, while Smurfit Westrock exemplifies the corrugated-film hybrid format specialist. These entities represent contrasting strategic postures: the first leverages manufacturing footprint coverage for contract security, the second competes through specialty laminate barrier performance, and the third dominates protective backing with transparent display window integration. Regional mid-cap players in India and Vietnam increasingly fragment volume through modular production architectures that compress qualification timelines.
| Leading Market Players |
|---|
| Amcor Plc |
| Mondi Group |
| Smurfit Westrock |
| Sonoco Products Company |
| Huhtamaki |
| Stora Enso |
| DS Smith |
| TOPPAN Holdings Inc. |
| International Paper |
| Others |
Value Network & Pricing Analysis
Polypropylene resin indices cascading through East Asian biaxial orientation clusters fragment pricing power across three distinct tiers, with pharmaceutical-grade specifications commanding sustained premiums while commodity polyethylene applications face margin compression from volatile petrochemical feedstock costs.
Pricing Analysis
Cost-down pressure on standard-grade polyethylene accelerates because crude oil-linked resin contracts prevent quarterly price adjustments, squeezing converter margins when spot purchasing cycles dominate. Three-tier pricing structure across pharmaceutical-grade, industrial-performance, and economy polyethylene levels separates buyers by certification burden and barrier-performance requirements. Price differentiation hinges on FDA food-contact notification compliance and REACH-certified bio-based plasticizer validation. Subscription-based stationery services exhibit lowest price sensitivity due to specification-locked multi-year agreements, while small-format retail outlets face acute margin pressure from pre-converted material wholesalers.
Supply Chain Analysis
Single-source vulnerability sits with biaxial orientation equipment owners concentrated in China, South Korea, and Japan, where regional energy cost spikes trigger supply bottlenecks for archival-grade film specifications. Raw material procurement draws from polypropylene and polyethylene resin streams, with phthalate-free PVC compounders and adhesive layer suppliers feeding laminated structures. Supply chain risk centers on tariff exposure for converters serving cross-border stationery exporters. Distribution runs through direct mill relationships for large-volume buyers, with regional distributors serving mid-volume converters lacking qualification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
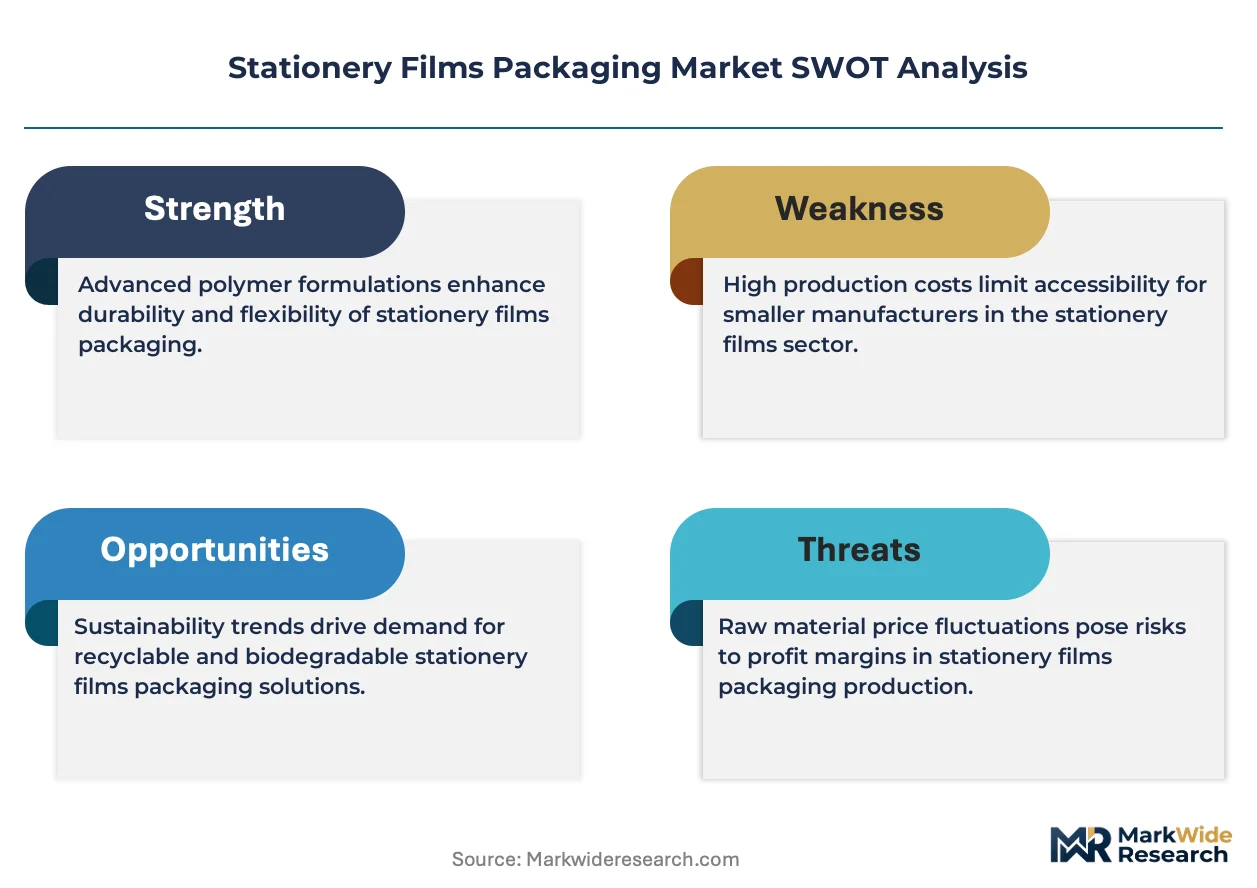
The stationery films packaging market is consolidating around converters with backward integration into resin compounding and third-party certification capabilities, as REACH and EPA regulatory tightening forces smaller compounders without validation infrastructure toward exit.
For Market Incumbents: Hedge against margin erosion in commodity polyethylene by accelerating polypropylene substitution programs and securing multi-year supply agreements with subscription-based stationery services. Anchor contract security through geographic manufacturing footprint expansion into Vietnam's underpenetrated industrial wrapping segment. Invest in cleanroom certification capabilities to capture pharmaceutical-grade margin pools before 12-18 month validation timelines lock out late entrants.
For New Entrants and Emerging Players: Begin with digital specification platforms that compress qualification sampling from weeks to days, targeting mid-volume regional converters in India's Delhi-NCR corridor. Vietnam's cost-sensitive manufacturing hubs offer the most penetrable white-space for polyethylene moisture barrier applications. Pursue modular production architectures that enable barrier-performance prototyping without capital-intensive biaxial orientation equipment.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty laminators with REACH-certified bio-based plasticizer capabilities in Germany's Rhine-Ruhr industrial corridor, where EU Green Deal procurement mandates tilt public sector purchasing toward recyclability-verified films. Long-term viability over the next decade rests on converters with demonstrated circularity credentials and pharmaceutical-grade qualification expertise. Monitor EPR framework fee liability modeling across European member states as the critical inflection signal for single-use film format profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures margin from petrochemical volatility while securing REACH-compliant bio-based plasticizer supply. |
| Cleanroom Certification Investment | Opens pharmaceutical-grade archival document sleeve specifications with 12-18 month validation barriers. |
| Digital Specification Platform Deployment | Compresses qualification timelines for subscription-based stationery services consolidating procurement authority. |
| Geographic Expansion into Vietnam | Addresses underpenetrated cost-sensitive polyethylene applications in Southeast Asian manufacturing hubs. |
| Multi-Year Supply Agreement Structuring | Locks resin pricing for organized retail chains and direct-to-consumer brands in India's e-commerce fulfillment corridor. |
Research Methodology
Document review covered customs and trade data from Indian DGFT and Chinese export registries, complemented by interviews with film converting plant managers, procurement leads at stationery distributors, channel sales heads at regional wholesalers, and technical R&D directors at adhesive layer suppliers. Secondary validation drew from ECHA REACH substance restriction filings, EPA phthalate guideline updates, BIS standards documentation, and SEC 10-K disclosures from publicly traded packaging converters. Bottom-up volume modeling triangulated against top-down resin consumption estimates from petrochemical industry associations.
Historical shipment patterns cross-referenced with panel input from category managers at subscription-based stationery services anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material type, application tier, end-user scale, and regional regulatory cluster. CAGRs derived from weighted-average growth assumptions across polypropylene, polyethylene, PVC, and PET demand trajectories, with specific inputs for e-commerce fulfillment infrastructure deployment rates and REACH substitution program timelines.
Underlying measurement precision varies by segment; pharmaceutical-grade specifications with cleanroom validation requirements carry tighter precision than cost-sensitive industrial wrapping applications. Forecasts reflect assumptions regarding petrochemical feedstock stability, EPR framework evolution, and biaxial orientation capacity expansion that could materially revise outcomes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Cold Seal Paper Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Clear Envelopes and Mailing Supplies Market
Paper & Paperboard Packaging
Fast Food Wrapping Paper Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
Paperboard Packaging Market
Paper & Paperboard Packaging
United Kingdom (UK) Corrugated Board Packaging Market
Paper & Paperboard Packaging
Folding Paperboard Boxes Market
Paper & Paperboard Packaging
Postal Papers Market
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
Testliner Market
Paper & Paperboard Packaging
Fluting Paper Market
Paper & Paperboard Packaging
Paperboard Partition Market
Paper & Paperboard Packaging
Super Calendered Kraft Papers Market