
 Coated Duplex Board Market | 2026-2036
Coated Duplex Board Market Size, Share, and Industry Trends Forecast 2026-2036
Coated Duplex Board Market Outlook
Plastic substitution in pharmaceutical secondary packaging is decoupling volume growth from resin price volatility. Stora Enso leverages its Nordic pulp integration to secure coated duplex board feedstock at stable cost positions. WestRock anchors North American demand through direct partnerships with over-the-counter drug manufacturers requiring FDA-compliant carton substrates. ITC Limited dominates South Asian supply chains with bleached-grade production tailored to export-oriented pharmaceutical packaging.
Coated duplex board consists of a multi-ply recycled or virgin fiber substrate with a mineral pigment coating applied to one or both surfaces, typically achieving grammages between 200 and 450 gsm for structural rigidity and print receptivity. Its primary purpose is to provide premium printable surfaces for folding cartons, blister pack backing, and retail-ready packaging where visual communication and product protection converge. White back grades command margin premiums in cosmetics and pharmaceutical applications where reverse-side printability matters, while gray back variants occupy cost-sensitive segments such as stationery and general consumer goods logistics. Food container applications represent the fastest-growing application dimension as manufacturers migrate from plastic clamshells to fiber-based alternatives under tightening substrate restrictions.
FDA food-contact substance notifications and the EU's Packaging and Packaging Waste Regulation shape material compliance pathways for exporters serving dual-continent supply chains. China's SAMR enforces GB standards for heavy metal migration limits in coated food-contact boards, creating certification barriers for uncertified mills. India's BIS marking requirement for paperboard used in food packaging is tightening domestic quality thresholds. Stakeholders must monitor regulatory divergence between major import jurisdictions to avoid stranded inventory in cross-border pharmaceutical and food packaging supply chains.
Market Dynamics
Plastic substitution mandates across pharmaceutical and food-contact packaging are reconfiguring substrate sourcing priorities for coated duplex board converters, forcing capital reallocation toward fiber-based barrier technologies and compliance certification infrastructure.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content quotas for packaging substrates are pulling converters toward coated duplex board with certified post-consumer fiber streams.
- India's organized retail expansion:Modern trade penetration in tier-2 and tier-3 cities is upgrading folding carton specifications for consumer goods brands seeking shelf-ready presentation.
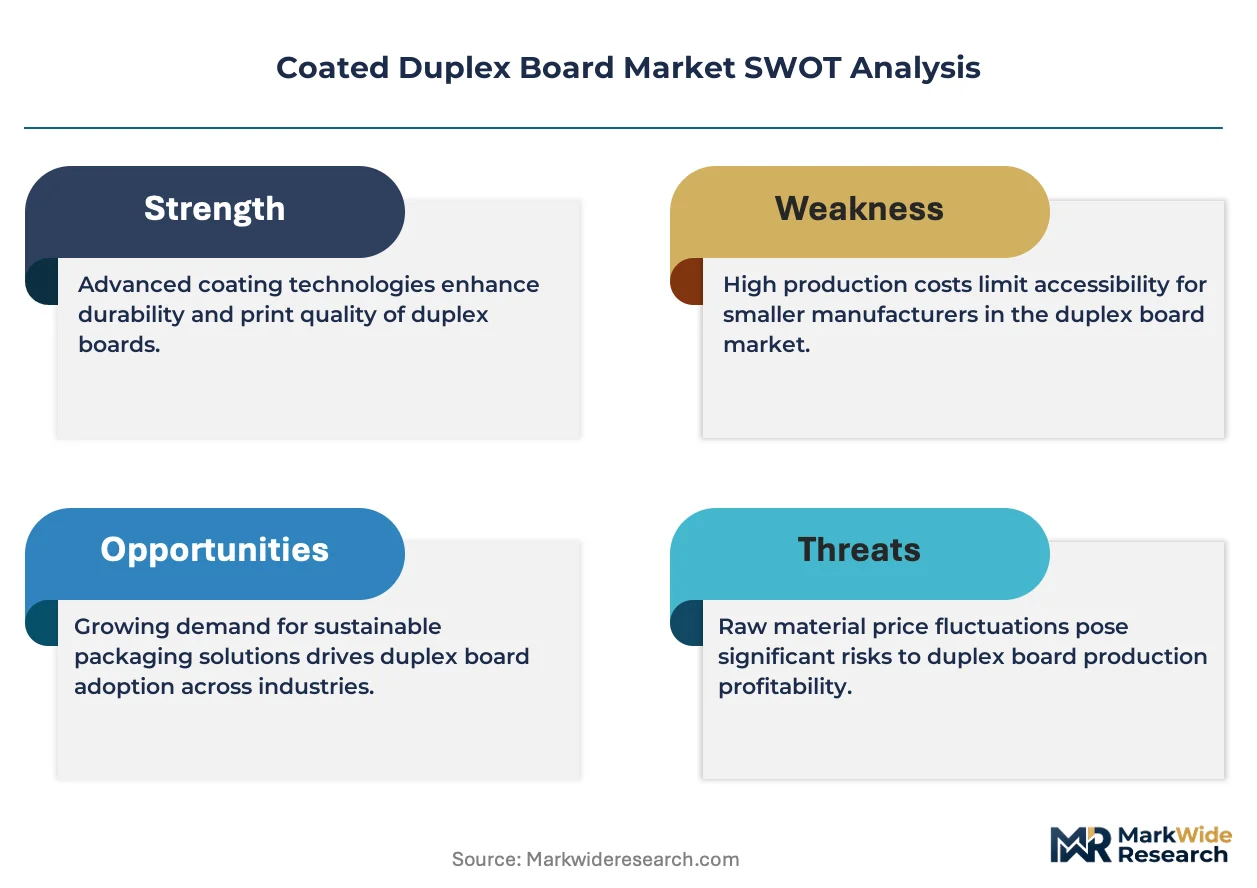
- Oxygen barrier coating chemistry:Advances in water-based polymer barriers are extending coated duplex board into modified atmosphere food containers previously served by multilayer plastics.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container price swings in Asian spot markets compress margin predictability for gray back grade producers dependent on mixed waste streams.
- Bleached pulp supply concentration:Nordic and Brazilian hardwood pulp integration limits independent mill access to premium white back feedstock at scale.
- China GB 4806 heavy metal limits:Migration testing requirements for food-contact boards create certification bottlenecks for exporters lacking in-country laboratory partnerships.
Strategic Opportunities
- Indonesia pharmaceutical packaging:Domestic generic drug manufacturing growth under BPOM oversight is outpacing local coated board converting capacity.
- Digital print compatibility:Short-run folding carton demand from direct-to-consumer cosmetics brands favors coated duplex board with inkjet-optimized surfaces over rotogravure-dependent alternatives.
- India PLI scheme for packaging:Production-linked incentives for paper-based food packaging are attracting greenfield mill investment with integrated coating lines.
Industry Challenges
- Barrier coating technician scarcity:Formulation chemists with food-contact polymer expertise command premium compensation, constraining R&D velocity at mid-tier converters.
- Dual jurisdiction certification timelines:Parallel FDA food-contact substance notifications and EU compliance documentation extend product launch cycles for export-oriented suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coated Duplex Board Market |
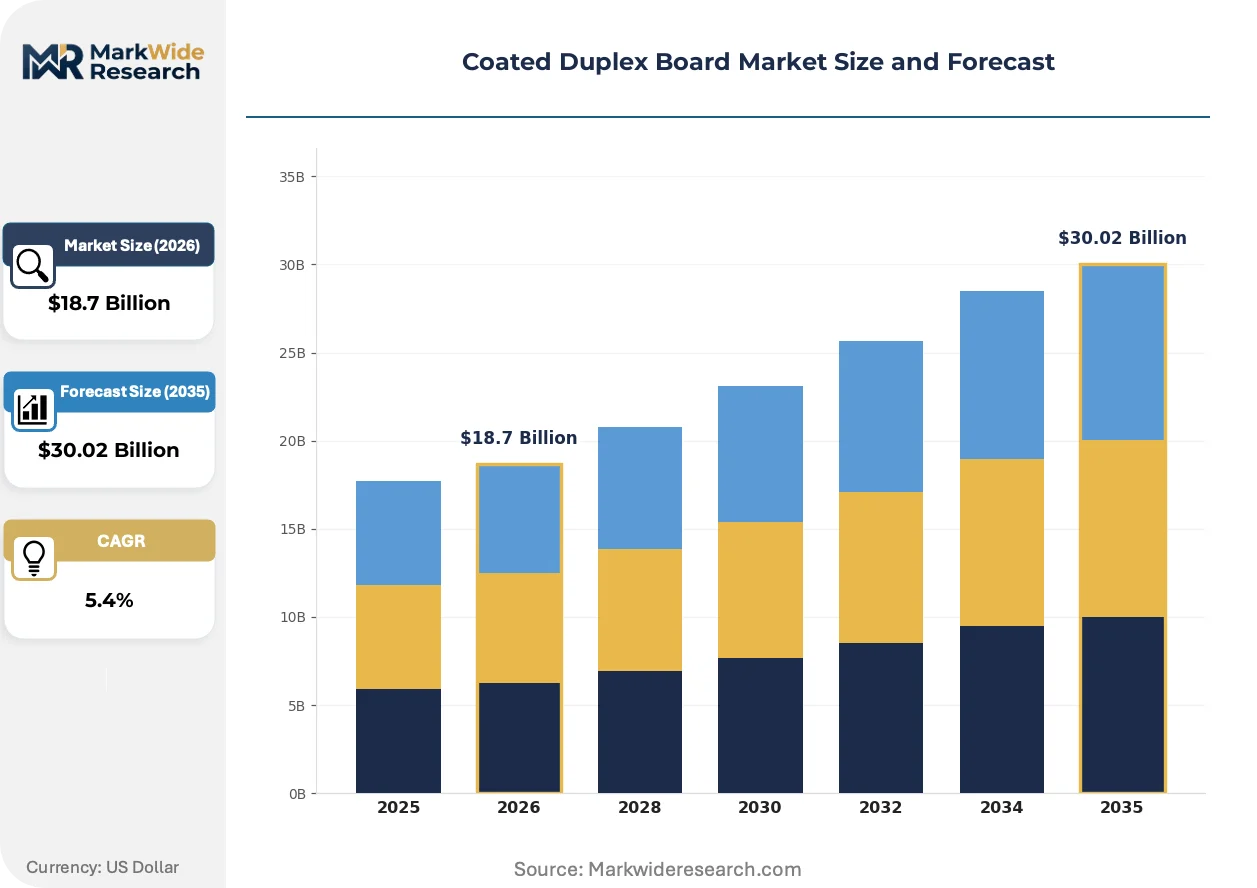
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gray Back, White Back, Kraft, Bleached Application: Packaging, Printing, Stationery, Food Containers End User: Consumer Goods, Pharmaceuticals, Electronics, Logistics Packaging Type: Folding Boxes, Wrapping, Cartons, Sheets |
| Companies Covered | Stora Enso, WestRock, ITC Limited, Asia Pulp & Paper, JK Paper, Nine Dragons Paper, Tamil Nadu Newsprint and Papers Ltd., Edicon Paper Product Pvt. Ltd., Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coated Duplex Board Market Strategic Shifts
Active coating chemistry evolution and regulatory compliance automation are compressing development cycles for next-generation coated duplex board, while procurement digitization is reconfiguring how converters align specification requirements with mill production schedules.
Water-based oxygen barrier coatings is expanding into fresh protein tray applications previously dominated by expanded polystyrene. Poultry and seafood processors in Southeast Asia are trialing these fiber-based alternatives to preempt plastic restrictions. The technology is compressing the cost gap between premium folding carton substrates and commodity plastic clamshells.
REACH substance of very high concern screening is forcing coating formulators to eliminate per- and polyfluoroalkyl substances from grease-resistant formulations. European folding carton converters are accelerating qualification of silicone-based and bio-wax alternatives. Pharmaceutical blister pack backing applications face the tightest reformulation timelines due to FDA-EMA dual registration requirements.
Direct mill-to-brand digital procurement platforms are consolidating specification matching and quality documentation exchange. Consumer goods packaging buyers in India are bypassing traditional distributor networks for volume commitments above five thousand tonnes annually. This channel compression is most visible in Mumbai and Delhi NCR industrial corridors where logistics integration supports just-in-time inventory models.
Coated Duplex Board Market Segmentation
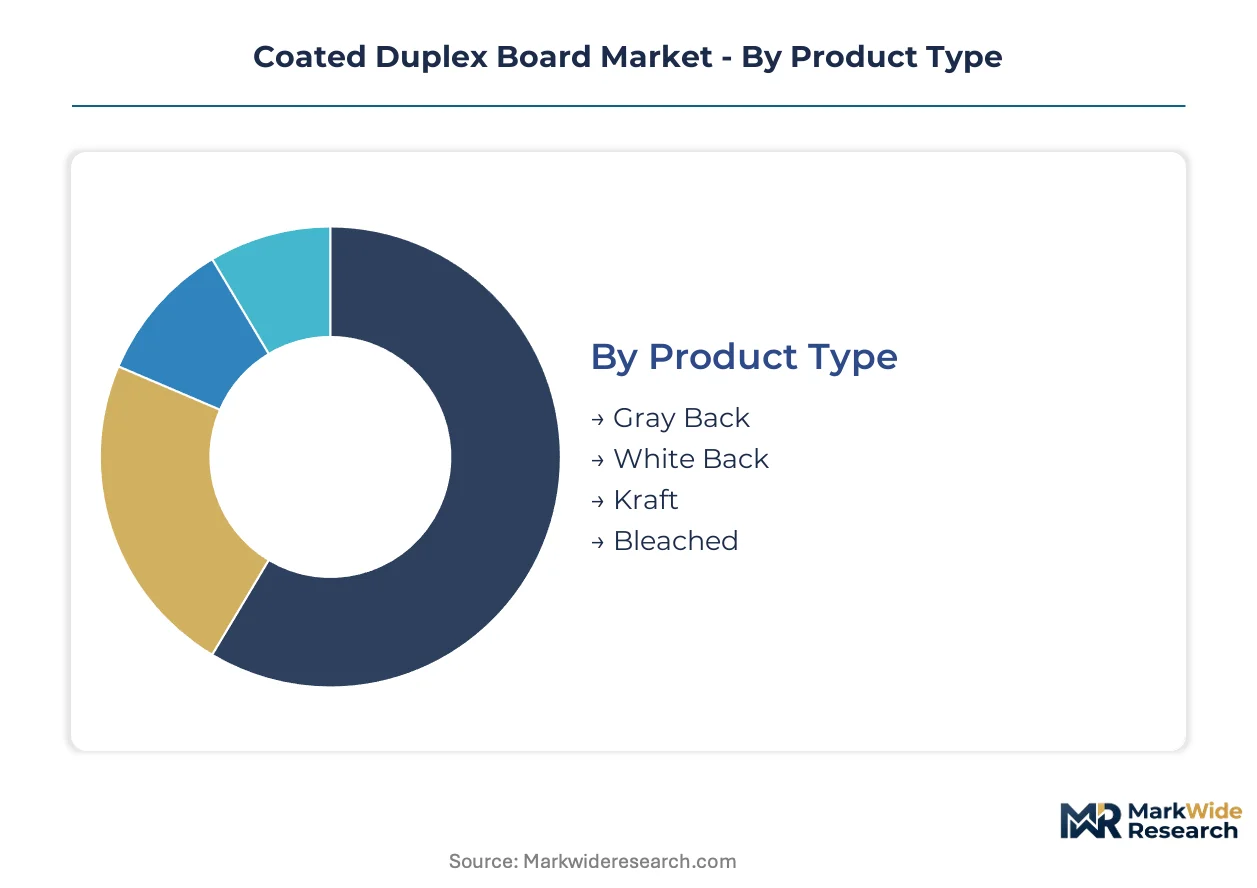
Substrate differentiation in coated duplex board determines compliance pathways, print performance, and barrier functionality across pharmaceutical and food-contact applications. Specification alignment with converter equipment and regulatory jurisdiction shapes procurement decisions more than commodity pricing alone.
Product Type:
Coating chemistry and fiber bleaching intensity define the technical ceiling for each grade, with reverse-side appearance driving cosmetic and pharmaceutical premiumization.
- White Back:Double-coated bleached surface achieves 80+ brightness for high-fidelity pharmaceutical carton printing. Demand clusters in Mumbai and Delhi NCR export corridors where FDA-EMA dual registration requirements favor certified white back substrates for blister pack backing.
- Gray Back:Unbleached recycled fiber core with single-sided coating delivers cost-efficient structural rigidity for logistics applications. Recycled corrugated container price volatility in Asian spot markets compresses margin predictability for gray back specialists dependent on mixed waste streams.
- Kraft:Unbleached virgin fiber substrate retains natural lignin coloration for eco-positioned retail packaging.
- Bleached:Full fiber bleaching enables premium folding carton applications requiring maximum print gamut reproduction.
White Back leads on scale; Kraft gains share fastest in sustainability-positioned segments.
Application:
Functional requirements diverge sharply between protective packaging and visual communication endpoints, with food-contact compliance adding certification complexity.
- Food Containers:Barrier-coated grades with oxygen-blocking polymer layers are displacing expanded polystyrene in fresh protein trays across Southeast Asian processing facilities. China's GB 4806 heavy metal migration limits create certification bottlenecks for exporters lacking SAMR-recognized laboratory partnerships.
- Packaging:Folding carton and rigid box applications dominate tonnage, with pharmaceutical secondary packaging decoupling volume growth from resin price volatility through plastic substitution mandates.
- Printing:Commercial print substrates require calibrated coating porosity for ink adhesion consistency.
- Stationery:Gray back variants occupy file folder and rigid box applications where cost sensitivity exceeds surface aesthetics.
Packaging anchors volume commitment; Food Containers show steepest expansion trajectory.
End User:
Regulatory stringency and brand equity protection create divergent specification thresholds across customer categories.
- Pharmaceuticals:Blister pack backing and folding cartons for over-the-counter drugs require FDA food-contact substance notifications and EMA compliance documentation. Dual jurisdiction certification timelines extend product launch cycles for export-oriented suppliers serving both US and European markets.
- Consumer Goods:Cosmetics and personal care brands in India's organized retail channel drive specification upgrades for shelf-ready presentation in tier-2 and tier-3 city expansions.
- Electronics:Anti-static coating requirements for sensitive component packaging add formulation complexity.
- Logistics:E-commerce corrugated substitution favors gray back structural boards for cost-efficient void fill and protective packaging.
Pharmaceuticals commands premium pricing; Consumer Goods drives volume elasticity.
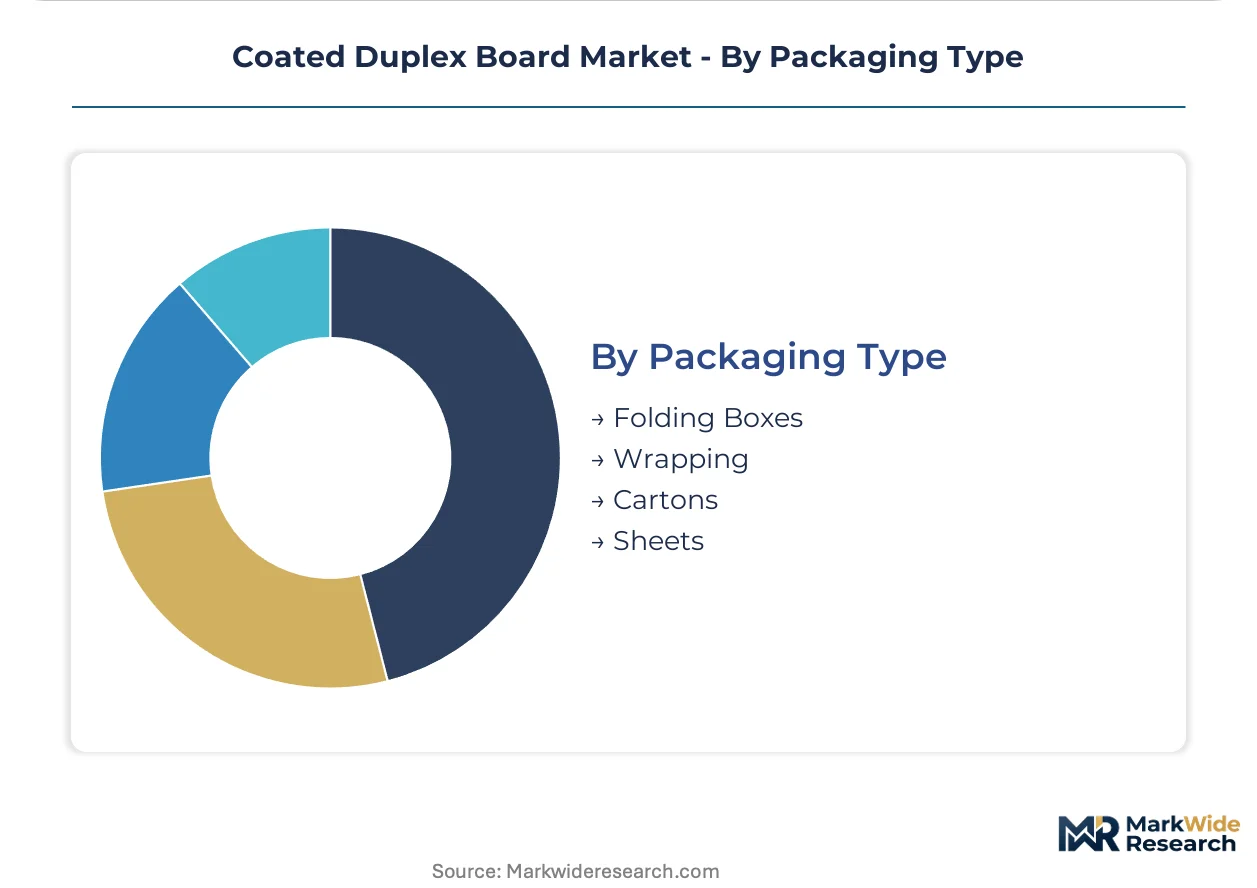
Packaging Type:
Converter equipment compatibility and logistics efficiency determine format selection across the value chain.
- Folding Boxes:Die-cut and creased formats for pharmaceutical and cosmetic applications require precise coating caliper consistency for automated gluing lines. Digital print compatibility favors inkjet-optimized surfaces for short-run direct-to-consumer cosmetics brands bypassing rotogravure-dependent alternatives.
- Cartons:Pre-formed rigid structures for premium spirits and gift packaging command specification premiums.
- Wrapping:Roll-fed formats for industrial protective applications emphasize tear resistance over print quality.
- Sheets:Uncut board for downstream converter flexibility in custom die-cutting operations.
Folding Boxes dominates converter throughput; Cartons maintains premium margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mumbai-Pune pharmaceutical packaging corridor anchors coated duplex board consumption, with FDA-EMA dual registration requirements pulling premium white back grades toward export-oriented converters. Regulatory divergence across major import jurisdictions is fragmenting procurement strategies for multinational pharmaceutical and food packaging supply chains.
China
Fresh protein tray trials in Guangdong processing facilities are accelerating water-based oxygen barrier adoption ahead of plastic restriction deadlines. SAMR enforces GB 4806 heavy metal migration limits that create certification bottlenecks for exporters lacking recognized laboratory partnerships. The Yangtze River Delta concentration of folding carton converters is upgrading specifications for pharmaceutical secondary packaging serving domestic generic drug manufacturers.
India
Organized retail penetration in tier-2 and tier-3 cities is driving specification upgrades for shelf-ready consumer goods presentation. The BIS marking requirement for paperboard used in food packaging is tightening domestic quality thresholds and consolidating supplier relationships. The Delhi-NCR industrial corridor hosts the densest concentration of pharmaceutical carton converters requiring bleached-grade substrates for blister pack backing.
United States
Over-the-counter drug manufacturers are decoupling volume commitments from resin price volatility through plastic substitution mandates in secondary packaging. FDA food-contact substance notification requirements extend product launch cycles for coated duplex board suppliers serving pharmaceutical applications. The Wisconsin-Illinois paperboard belt maintains integrated coating capacity for North American folding carton demand.
Germany
REACH substance of very high concern screening is forcing coating formulators to eliminate PFAS from grease-resistant formulations ahead of pharmaceutical blister pack deadlines. The EU Packaging and Packaging Waste Regulation's recycled content quotas are pulling converters toward certified post-consumer fiber streams. The Baden-Württemberg packaging cluster is accelerating qualification of silicone-based barrier alternatives for food-contact applications.
Indonesia
Domestic generic drug manufacturing growth under BPOM oversight is outpacing local coated board converting capacity and creating import dependency. The Java-based pharmaceutical packaging corridor is attracting regional mill investment to serve unmet folding carton demand. Jakarta-area converters are specifying barrier-coated grades for modified atmosphere food containers targeting modern retail expansion.
Coated Duplex Board Market Competitive Environment
Capacity expansion dominates the current landscape as integrated pulp producers secure coating line investments ahead of regulatory compliance deadlines. The vendor base stratifies between Nordic-Brazilian hardwood pulp integrators with captive bleached feedstock and Asian specialists dependent on volatile old corrugated container spot markets. Three archetypes define competitive positioning: integrated forest products groups with upstream pulp control, regional converters with pharmaceutical certification depth, and scale-driven recycled fiber specialists serving gray back logistics applications. Strategic partnerships with over-the-counter drug manufacturers and backward integration into barrier coating chemistry represent the dominant competitive vectors.
Among Nordic-integrated producers, Stora Enso exemplifies the hardwood pulp control archetype that stabilizes white back feedstock costs for pharmaceutical-grade output. WestRock anchors North American positioning through direct partnerships with FDA-compliant carton substrate requirements. ITC Limited occupies the South Asian specialist tier with bleached-grade production tailored to export-oriented pharmaceutical packaging demand from Mumbai and Delhi-NCR corridors.
| Leading Market Players |
|---|
| Stora Enso |
| WestRock |
| ITC Limited |
| Asia Pulp & Paper |
| JK Paper |
| Nine Dragons Paper |
| Tamil Nadu Newsprint and Papers Ltd. |
| Edicon Paper Product Pvt. Ltd. |
| Smurfit Kappa |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical buyers' FDA-EMA dual registration requirements for blister pack backing substrates are forcing mills to invest in certified bleached fiber streams, compressing margin flexibility for gray back specialists dependent on volatile old corrugated container spot markets.
Pricing Analysis
Old corrugated container price pass-through volatility in Asian spot markets compresses margin predictability for gray back grade producers tethered to mixed waste streams. Three-tier pricing structure across premium white back, standard bleached, and economy gray back levels differentiates by certification grade and fiber bleaching intensity. Pricing pressure stems from Nordic-Brazilian hardwood pulp integration limits that constrain independent mill access to premium feedstock at scale. Logistics applications show highest price sensitivity; pharmaceutical secondary packaging buyers absorb certification premiums for FDA-compliant substrates.
Supply Chain Analysis
Direct mill-to-brand digital procurement platforms in India's Mumbai and Delhi NCR corridors handle hyperscale pharmaceutical converter demand above five thousand tonnes annually. Supply concentrates in China, India, and Nordic countries for bleached fiber integration; Indonesia and Vietnam host emerging converting capacity for Southeast Asian pharmaceutical growth. Raw material dependencies center on old corrugated containers for gray back grades, hardwood pulp for white back production, and water-based oxygen barrier polymers for food-contact applications. Single-source vulnerability runs through Nordic-Brazilian hardwood pulp concentration for premium grades. Distribution runs through integrated forest products groups with captive coating capacity and regional converters with pharmaceutical certification depth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation's recycled content quotas compound demand for certified post-consumer fiber streams, creating procurement urgency across pharmaceutical and food-contact packaging supply chains.
For Market Incumbents: Deepen backward integration into barrier coating chemistry to secure formulation expertise as PFAS elimination deadlines approach under REACH substance of very high concern screening. Expand certified coating line capacity in India's Delhi-NCR corridor to capture organized retail specification upgrades in tier-2 and tier-3 cities. Strengthen direct partnerships with over-the-counter drug manufacturers requiring FDA-compliant carton substrates to defend against integrated pulp competitors. For New Entrants and Emerging Players: Launch via digital procurement platforms targeting direct-to-consumer cosmetics brands in India's Mumbai industrial corridor seeking short-run folding carton capacity with inkjet-optimized surfaces. Penetrate Indonesia's domestic generic drug manufacturing growth under BPOM oversight where local coated board converting capacity lags demand. Qualify water-based oxygen barrier coatings for fresh protein tray applications in Southeast Asian processing facilities ahead of plastic restriction deadlines. For Investors and Strategic Acquirers: Asymmetric upside sits with regional converters possessing pharmaceutical certification depth and established laboratory partnerships for China GB 4806 heavy metal migration testing. Long-term viability favors acquisition targets with integrated coating lines and barrier formulation R&D capabilities rather than commodity gray back specialists exposed to recycled fiber cost volatility. Watch for Indonesia BPOM regulatory harmonization with FDA-EMA standards as inflection indicator for Southeast Asian pharmaceutical packaging demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Chemistry Acquisition | Secures PFAS-free formulation expertise ahead of pharmaceutical blister pack deadlines under REACH screening. |
| Integrated Coating Line Expansion | Captures India PLI scheme incentives for paper-based food packaging with certified post-consumer fiber streams. |
| Digital Procurement Platform Partnership | Aligns mill production schedules with direct-to-consumer cosmetics brands bypassing traditional distributor networks. |
| Dual Jurisdiction Certification Investment | Compresses product launch cycles for exporters serving FDA and EMA pharmaceutical packaging requirements simultaneously. |
| Southeast Asian Converting Capacity Buildout | Addresses Indonesia's domestic generic drug manufacturing growth outpacing local coated board supply. |
Study Parameters
Multiple input streams — primary interviews with mill operations directors, pharmaceutical packaging procurement managers, and barrier coating formulators; secondary validation through FDA food-contact substance notifications, EMA compliance documentation, and China SAMR GB standard filings; customs and trade data from major coated board exporting jurisdictions — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across the projection horizon applied segmentation modeling by substrate grade, end-use application, regulatory jurisdiction cluster, and converter equipment compatibility. CAGRs were derived from volume trajectory analysis incorporating pharmaceutical plastic substitution mandates, organized retail expansion patterns, and barrier coating technology adoption curves. Forecast inputs included old corrugated container price volatility indices and hardwood pulp integration capacity expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt PFAS regulatory acceleration or sudden recycled fiber supply disruptions. Periodic stress-testing of base assumptions is recommended given regulatory divergence between FDA, EMA, and China SAMR compliance pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Waxed Paper Packaging Market
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
Cellular Paper Cardboard Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
Kraftliner Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
South East Asia Corrugated Packaging Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
Envelope Paper Market
Paper & Paperboard Packaging
Sublimation Paper Market
Paper & Paperboard Packaging
Chipboard Box Market
Paper & Paperboard Packaging
Global Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Greyboard Market