
 Post Press Machine Market | 2026-2036
Post Press Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Post Press Machine Market Insights
Modular finishing configurations are repositioning buyer choice across the post press landscape, as converters seek standalone units over monolithic lines for shorter run flexibility. Bobst Group SA leverages its die cutting specialization to anchor premium packaging workflows in Europe and Asia. Heidelberg Druckmaschinen AG sustains technology leadership through integrated folding and binding architectures. Koenig & Bauer competes on high-speed embossing and hot foil stamping platforms for security and luxury print segments.
A post press machine performs cutting, folding, binding, coating, and decorative finishing operations on printed substrates after the primary press run, typically handling paper and board stocks from 60 to 600 gsm at speeds exceeding 15,000 cycles per hour for commercial viability. Folding machines and die cutting equipment dominate installed base value, with laminating devices and gluing systems capturing faster replacement cycles as packaging converters prioritize throughput and adhesive precision. UV coating technology leads margin pools due to its premium positioning in cosmetic and food-grade packaging, while hot foil stamping occupies a defensible niche in anti-counterfeiting and luxury goods applications.
CE marking requirements under the EU Machinery Directive shape equipment design standards for safety interlocks and electromagnetic compatibility across European sales. The EPA enforces volatile organic compound emission limits on coating and gluing operations in US print facilities, directing capital toward solvent-recovery and water-based systems. Japan's METI energy-efficiency benchmarks influence machine specifications for export-oriented manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks for packaging waste, as these regulations will determine which finishing technologies qualify for preferential procurement in circular economy supply chains.
Market Dynamics
E-commerce corrugated packaging demand is compressing run lengths and forcing converters toward reconfigurable finishing lines that swap between folding carton and micro-flute board without mechanical changeover delays.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants in industrial cooling systems is accelerating capital replacement of older die cutting presses with energy-efficient servo-electric alternatives across German and Italian packaging clusters.
- Cosmetic packaging:Premium beauty brands are specifying UV coating and hot foil stamping for shelf differentiation, pulling demand for multi-process finishing centers capable of inline decorative operations.
- Short-run flexibility:Digital print-to-pack workflows in North American commercial print are requiring modular binding and folding units that integrate with variable-data inkjet webs without manual makeready.
Market Restraints
- Steel and aluminum input volatility:Precision die cutting cylinders and heated embossing platens rely on specialized alloy feedstock subject to energy-cost-driven price swings that compress equipment margin pools.
- Control system concentration:Motion controllers and servo drives for high-speed folding machines source predominantly from German and Japanese automation suppliers, creating single-source vulnerability for mid-tier OEMs.
- Water-based adhesive performance limits:Food-grade packaging mandates under FDA and EFSA frameworks restrict solvent-based gluing chemistries that deliver superior bond strength on coated stocks, forcing slower production speeds.
Strategic Opportunities
- India packaging conversion:Domestic e-commerce fulfillment infrastructure expansion is creating first-time demand for automated die cutting and folder-gluer installations in Maharashtra and Gujarat industrial corridors.
- Pharmaceutical serialization:Track-and-trace mandates under the EU MDR and US DSCSA are opening specification windows for finishing equipment with integrated variable-data printing and verification stations.
- Servo-electric and UV-LED convergence:The pairing of precision motion control with instant-cure coating technology is enabling compact finishing lines with 40% smaller footprints than conventional configurations.
Industry Challenges
- Mechatronics skill scarcity:Maintenance of servo-driven folding systems requires technicians fluent in both mechanical timing and PLC programming, a combination rarely found in legacy bindery workforces.
- CE-MDR dual certification timelines:Equipment destined for both EU and medical-device packaging applications must satisfy overlapping machinery safety and quality system audits, extending commercialization cycles.
- Legacy mechanical integration:Hybrid configurations pairing new digital front-ends with existing cutter-creaser infrastructure demand custom engineering that erodes project profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Post Press Machine Market |
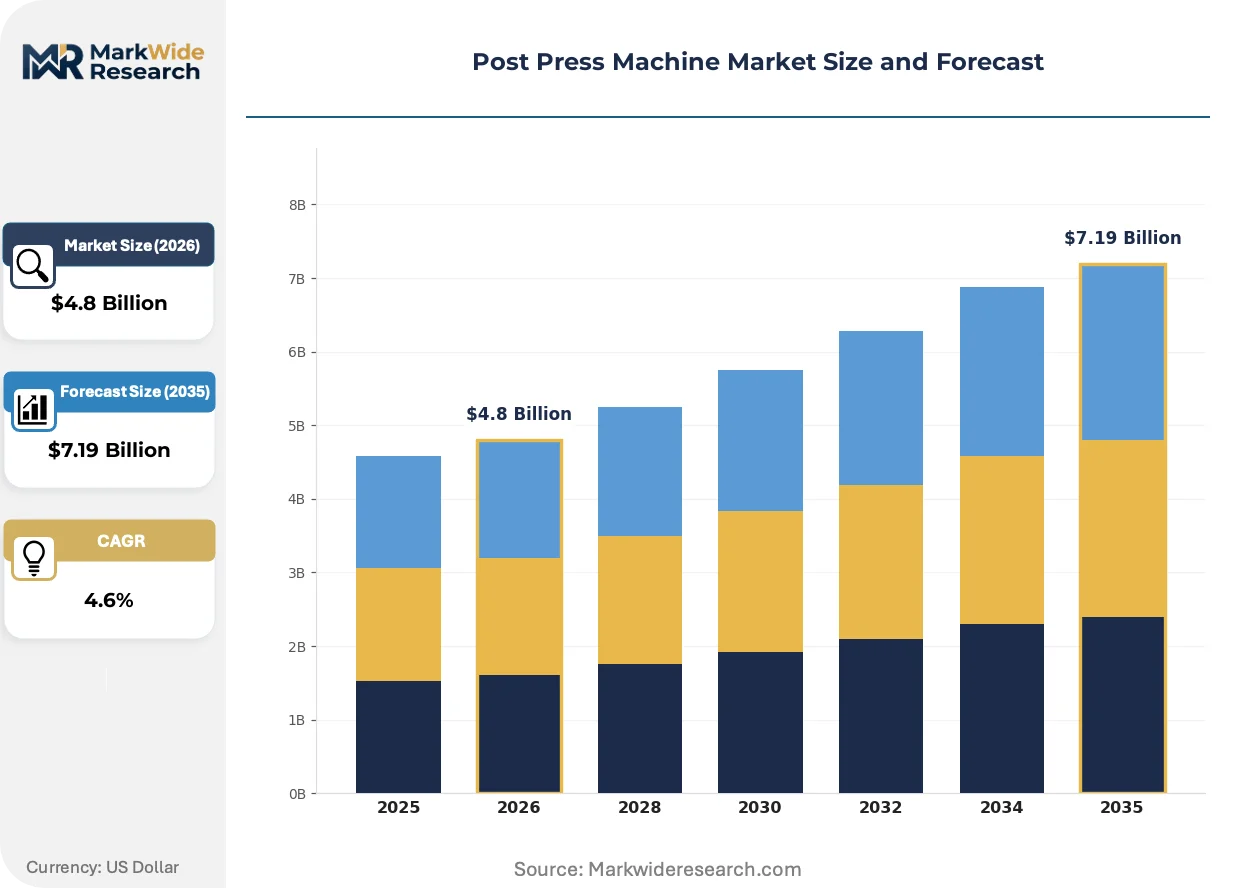
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Machines, Binding Equipment, Laminating Devices, Die Cutting Machines, Gluing Systems Technology: Hot Foil Stamping, UV Coating, Embossing, Die Cutting, Padding Application: Books Production, Packaging Industry, Commercial Printing, Label Manufacturing, Catalog Processing End User: Print Shops, Publishing Companies, Packaging Suppliers, Label Makers, Commercial Printers |
| Companies Covered | Schuler Group, AIDA, Komatsu Ltd., Stamtec, Amada Press System, Bobst Group SA, Heidelberg Druckmaschinen AG, Koenig & Bauer, Nidec Minster, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Post Press Machine Market Trends and Innovations
Finishing equipment architecture is pivoting from fixed mechanical trains toward software-defined process sequences that reconfigure cutting, folding, and coating operations through parameter adjustment rather than physical changeover.
Inline spectrophotometric color measurement is integrating closed-loop quality control directly into coating and embossing stations. High-volume folding carton producers in Germany and the United States are adopting these systems to eliminate offline inspection bottlenecks. The technology is integrating statistical process control with machine learning defect classification, compressing the feedback loop between finishing and prepress departments.
Japan's METI energy-efficiency benchmarking program now extends to industrial printing and converting equipment, mandating disclosure of power consumption per thousand sheets processed. Equipment manufacturers serving export markets are redesigning vacuum generation and drive architectures to qualify for preferential procurement under these standards. The policy is reshaping competitive positioning for Japanese OEMs against European rivals with legacy hydraulic systems.
Brand owners are unbundling after-sales service contracts from initial equipment purchases, treating maintenance spend as a separately negotiated procurement category. Folding carton converters in the Benelux region are piloting performance-based service agreements where OEMs guarantee uptime percentages in exchange for per-unit fees tied to production volume. The shift is visible most acutely in security printing applications where downtime carries contract penalty clauses.
Post Press Machine Market Segmentation
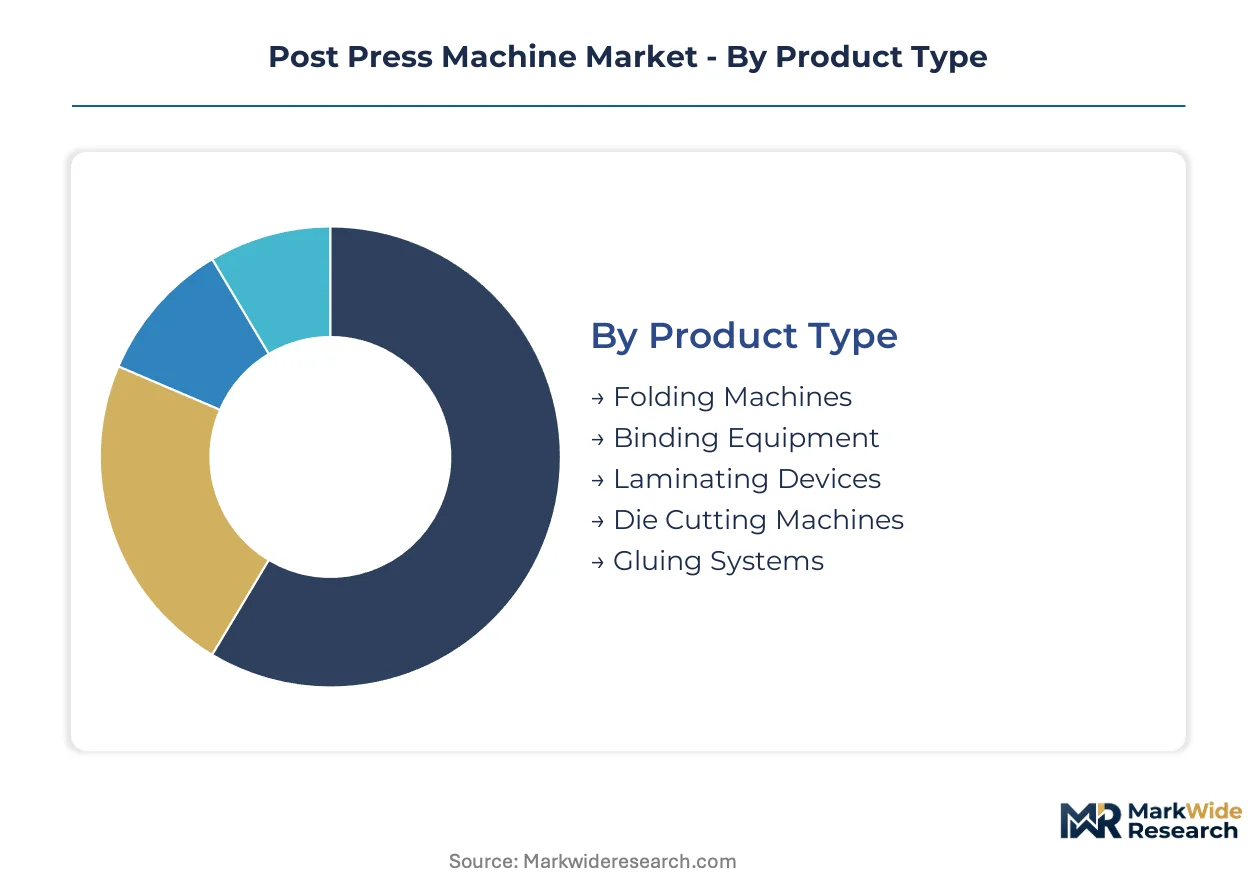
Finishing equipment procurement divides sharply between high-volume packaging workflows and precision book production, with capital allocation patterns diverging across substrate types and speed requirements. Equipment specification cascades through technology choice, application intensity, and end-user scale, creating distinct margin pools for OEMs serving each configuration.
Product Type:
Die cutting machines command the highest upfront capital outlays due to precision-engineered cylinders and servo-electric drive architectures, while gluing systems require lower initial investment but faster replacement cycles.
- Die Cutting Machines:Rotary and flatbed configurations process corrugated board and folding carton stocks at speeds exceeding 15,000 cycles per hour. German packaging clusters around Stuttgart and Munich absorb the majority of high-speed rotary installations driven by cosmetic and pharmaceutical contract manufacturing demand.
- Folding Machines:These systems crease and fold paper and board stocks from 60 to 600 gsm into finished signatures or cartons. Maharashtra and Gujarat industrial corridors in India are expanding folder-gluer capacity to serve domestic e-commerce fulfillment infrastructure buildout.
- Binding Equipment:Saddle stitching and perfect binding lines handle book block assembly and cover attachment for publishing workflows.
- Laminating Devices:Thermal and cold film systems apply protective polymer layers to printed surfaces for durability and gloss enhancement.
- Gluing Systems:Hot-melt and cold-glue applicators secure carton closures and book bindings with precision adhesive deposition.
Die cutting machines absorb the bulk of installed capacity; gluing systems are expanding most quickly due to packaging converter prioritization of adhesive precision and throughput.
Technology:
Margin concentration follows curing energy requirements, with instant-cure UV systems and precision foil registration commanding premium positioning over conventional mechanical processes.
- UV Coating:Instant-cure ultraviolet systems apply scratch-resistant, high-gloss finishes without thermal drying delays. Premium beauty brands in France and Italy specify UV coating for shelf differentiation, pulling demand for multi-process finishing centers with inline decorative capability.
- Hot Foil Stamping:Heated die systems transfer metallic or pigment foils onto substrates for luxury and security applications. Swiss and German security printers deploy these platforms for anti-counterfeiting features on tax stamps and authentication labels.
- Embossing:Raised-image dies create tactile surface textures for premium packaging and stationery.
- Die Cutting:Steel-rule and rotary dies separate printed substrates into finished shapes with precision registration.
- Padding:Edge-gluing systems assemble notepads and forms with repositionable adhesive strips.
UV coating commands the widest margin spread; hot foil stamping maintains defensible niche positioning in security and luxury segments.
Application:
Run length economics separate packaging workflows favoring high-speed automation from book production tolerating longer makeready intervals.
- Packaging Industry:Folding carton and corrugated box finishing dominates equipment utilization rates. North American converters serving Amazon and Walmart fulfillment networks are reconfiguring lines for micro-flute board and variable-data integration.
- Books Production:Hardcover and paperback binding workflows handle shorter runs with greater format flexibility. German educational publishers sustain demand for Smyth sewing and PUR perfect binding systems despite digital displacement in trade publishing.
- Commercial Printing:General job shops process diverse substrates for marketing collateral and corporate communications.
- Label Manufacturing:Narrow-web finishing systems convert printed roll stock into pressure-sensitive and wet-glue labels.
- Catalog Processing:High-volume saddle stitching and inkjet addressing serve retail and B2B mail-order operations.
Packaging industry applications absorb the bulk of installed capacity; books production is contracting fastest as digital formats displace print volumes.
End User:
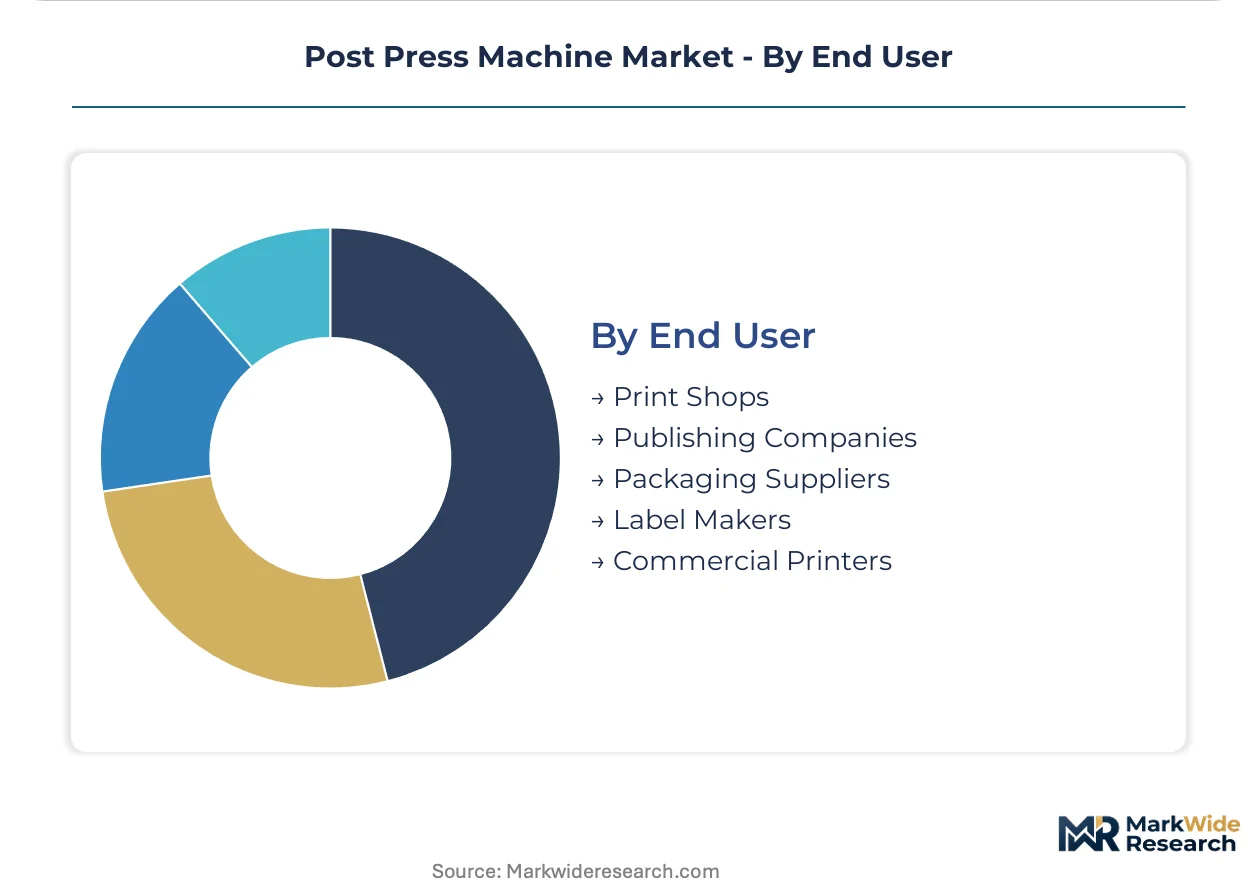
Scale concentration determines automation level, with integrated packaging suppliers deploying full finishing lines while independent print shops acquire standalone units.
- Packaging Suppliers:Integrated converters serving Unilever, Nestlé, and L'Oréal operate captive finishing departments with 24-hour production schedules. Benelux folding carton specialists are piloting performance-based service agreements where OEMs guarantee uptime percentages against per-unit fees.
- Commercial Printers:Generalist shops serving regional advertising and corporate accounts require format flexibility over raw speed. Japanese commercial printers under METI energy-efficiency benchmarking are retiring hydraulic systems for servo-electric alternatives to qualify for preferential procurement.
- Print Shops:Quick-print and copy centers handle short-run digital finishing with tabletop or light-production equipment.
- Publishing Companies:Trade and educational publishers operate captive binderies or contract with specialized finishing houses.
- Label Makers:Narrow-web converters serving beverage and pharmaceutical clients deploy roll-fed finishing systems with inline inspection.
Packaging suppliers command the deepest installed base; commercial printers are upgrading fastest to capture digital print-to-pack workflow integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's Special Investment Region and Delhi-Mumbai Industrial Corridor tax incentives are concentrating post press machine demand in western India, while Germany's High-Tech Strategy 2025 directs capital toward precision finishing clusters.
United States
E-commerce fulfillment networks operated by Amazon and Walmart are compressing run lengths and demanding reconfigurable die cutting lines. The EPA enforces volatile organic compound emission limits on coating operations, pushing converters toward solvent-recovery systems. Folding carton specialists in Wisconsin and Ohio are upgrading folder-gluer capacity for micro-flute board integration.
Germany
Precision-engineered folding and binding equipment serves high-volume print-to-pack workflows for cosmetic and pharmaceutical contract manufacturers. The EU F-Gas Regulation accelerates replacement of hydraulic die cutting presses with servo-electric alternatives. Stuttgart and Munich packaging clusters absorb the majority of high-speed rotary installations.
India
Domestic e-commerce fulfillment infrastructure expansion is creating first-time demand for automated die cutting and folder-gluer installations. The PLI scheme for manufacturing incentivizes local assembly of finishing equipment components. Maharashtra and Gujarat industrial corridors are expanding capacity to serve Flipkart and Reliance retail networks.
Japan
Commercial printers under METI energy-efficiency benchmarking are retiring hydraulic systems for servo-electric alternatives. The country's national industrial standards mandate disclosure of power consumption per thousand sheets processed. Kanto and Kansai regions concentrate demand for compact UV-LED finishing lines.
China
Packaging converters serving export-oriented brand owners are adopting inline spectrophotometric quality control systems. The national dual carbon goals pressure equipment selection toward energy-efficient architectures. Yangtze River Delta finishing houses are integrating machine learning defect classification with coating stations.
Post Press Machine Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Swiss and German engineering groups anchor premium positioning through precision die cutting and security printing platforms. Japanese automation houses leverage servo-drive integration for compact, energy-efficient configurations. Mid-tier European fabricators compete on modular architectures that reduce mechanical changeover intervals. Dominant competitive moves include geographic expansion into Indian industrial corridors and technology licensing partnerships for UV-LED curing convergence.
Within the diversified industrial tier, Komatsu Ltd. and Schuler Group occupy positions spanning metal forming and converting equipment. Bobst Group SA exemplifies the focused specialist archetype through die cutting specialization. Heidelberg Druckmaschinen AG and Koenig & Bauer represent German precision-engineering heritage in folding and decorative finishing platforms. These named entities anchor competitive intensity without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Schuler Group |
| AIDA |
| Komatsu Ltd. |
| Stamtec |
| Amada Press System |
| Bobst Group SA |
| Heidelberg Druckmaschinen AG |
| Koenig & Bauer |
| Nidec Minster |
| Others |
Pricing and Supply Chain Analysis
Servo-electric drive retrofits are compressing total cost of ownership curves while simultaneously redistributing supplier power toward German and Japanese automation houses with captive motion control architectures. This technological inflection concentrates margin capture upstream from mechanical fabricators to precision component specialists.
Pricing Analysis
Short lead-time premiums command 15-25% markups over standard delivery windows as packaging converters facing e-commerce fulfillment deadlines prioritize uptime certainty over capital efficiency. Three-tier pricing structure across premium, standard, and economy levels segments buyers by automation sophistication and after-sales bundling intensity. Pricing pressure stems from steel and aluminum alloy volatility eroding equipment margin pools. Mid-tier OEMs in Italy and Spain exhibit highest price sensitivity due to limited balance sheet capacity for inventory hedging.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Tokyo, and Chicago anchor hub-and-spoke fulfillment patterns for precision die cutting cylinders and servo drive modules. Manufacturing concentrates in Germany, Japan, and Switzerland for high-precision components, with final assembly distributed to India and Mexico for regional market access. Specialized alloy feedstock for heated embossing platens draws from Austrian and Swedish metallurgical suppliers. Single-source vulnerability in motion controller sourcing creates structural risk. Distribution runs through OEM-direct channels for large packaging suppliers and specialized distributors serving independent commercial printers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation and EPA VOC emission limits construct a cost-of-compliance architecture that favors incumbent OEMs with established certification infrastructure and technical service networks, raising effective barriers for capital-constrained entrants.
For Market Incumbents: Hedge against servo-drive supply concentration by cultivating secondary sourcing relationships with Taiwanese motion controller suppliers or pursuing backward integration into drive module assembly. Defend installed base stickiness through performance-based service contracts with uptime guarantees that lock out third-party maintenance providers. Prioritize CE-MDR dual certification investment to capture pharmaceutical serialization demand.
For New Entrants and Emerging Players: Independent commercial printers in North American secondary metros represent the most penetrable buyer segment, as these operators lack capital for full-line OEM relationships and tolerate higher service risk in exchange for 30-40% equipment discounts. Target modular folder-gluer configurations with 24-hour mechanical support response as the go-to-market anchor. Partner with regional distributors in Maharashtra and Gujarat industrial corridors to bypass direct sales infrastructure requirements.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking packaging automation exposure, with strategic value accruing to targets with installed base density above 500 units in high-growth corridors. Long-term viability hinges on software-defined process architecture capabilities that reduce mechanical changeover dependency. Monitor METI energy-efficiency benchmark adoption rates as the inflection signal for servo-electric replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Platform Migration | EU F-Gas compliance and METI benchmarks accelerate hydraulic system obsolescence in German and Japanese packaging clusters. |
| UV-LED Curing Convergence | Instant-cure technology paired with precision motion control enables 40% footprint reduction for compact finishing lines. |
| Performance-Based Service Contracts | Benelux folding carton converters pilot uptime guarantees with per-unit fees tied to production volume. |
| Indian Industrial Corridor Expansion | PLI scheme incentives and Flipkart fulfillment demand drive first-time automated die cutting installations in Gujarat. |
| Pharmaceutical Serialization Integration | EU MDR and US DSCSA track-and-trace mandates open specification windows for inline variable-data finishing stations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with packaging plant engineers, OEM product managers, aftermarket service heads, and procurement leads at integrated converters. Primary fieldwork validated installed base estimates and replacement cycle assumptions. Secondary sources included EU Machinery Directive implementation reports, EPA enforcement actions on VOC emissions, METI energy-efficiency disclosure databases, and SEC filings from publicly traded equipment manufacturers. Bottom-up unit economics triangulated against top-down market sizing from production capacity and utilization rates.
Segment-level modeling operated at technology-application-end user granularity across the projection horizon. Product type splits captured die cutting, folding, binding, laminating, and gluing equipment with distinct replacement cycle and margin profiles. Technology differentiation tracked UV coating, hot foil stamping, and servo-electric architectures. Geographic clustering reflected regulatory framework heterogeneity under EU F-Gas, EPA, and METI regimes. CAGRs derived from regression against macroeconomic indicators and capital expenditure surveys.
Caveats apply where raw material price volatility, trade policy shifts, or accelerated digital displacement of print volumes could materially shift the outlook. Forecasts reflect documented assumptions on e-commerce packaging demand elasticity and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Bottle Filling Machine Market
Packaging Machinery
Face Mask Machines Market
Packaging Machinery
Candy Wrapping Machine Market
Packaging Machinery
Global Blister Packaging Machinery Market
Packaging Machinery
Corrugated Paper Machine Market
Packaging Machinery
Flow Wrap Machines Market
Packaging Machinery
In-Line Thermoforming Machine Market
Packaging Machinery
Tablet Packing Machine Market
Packaging Machinery
Volumetric Filling Machines Market
Packaging Machinery
Orbital Wrapping Machine Market
Packaging Machinery
Confectionery Packaging Machine Market
Packaging Machinery
Global Tissue Paper Converting Machines Market
Packaging Machinery
Aseptic Filling Machines Market
Packaging Machinery
Tube Filling Machine Market
Packaging Machinery
Packaging Conveyors Market
Packaging Machinery
Product Dispensing Machinery Market