
 Polycoated Paper Packaging Market | 2026-2036
Polycoated Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Polycoated Paper Packaging Market Analytics
Asia-Pacific capacity expansion is reconfiguring raw material flows for polycoated paper substrates. Mondi Group leverages integrated pulp-to-paper operations across Central Europe to sustain margin stability amid resin volatility. Huhtamaki anchors its competitive stance through specialized molded fiber and barrier coating expertise in emerging markets. Stora Enso differentiates via biobased polymer research and captive forestry supply chains in the Nordic region.
Polycoated paper packaging consists of cellulose fiber substrates laminated with extruded polyethylene or biopolymer layers to achieve moisture, grease, and oxygen resistance for perishable goods containment. The coating process typically applies 12-30 gsm polymer layers through extrusion or dispersion methods to meet food-contact migration limits. Flexible Packaging leads volume shipment due to its dominance in quick-service restaurant wraps and confectionery sachets, while Rigid Packaging commands premium positioning through structural integrity in chilled dairy and ready-meal trays. The Food Industry end-use segment concentrates procurement scale among multinational processors, whereas Healthcare applications remain nascent but carry elevated certification requirements.
The FDA regulates food-contact substance notifications under 21 CFR, while the EU F-Gas Regulation and REACH restrict certain fluorinated barrier chemistries in favor of alternative coatings. BIS certification requirements in India and China's GB standards for food packaging migration testing are tightening compliance thresholds for exporters. Stakeholders must monitor polymer substitution timelines and regional certification divergence to secure sustained market access across jurisdictions.
Market Dynamics
The EU Single-Use Plastics Directive is forcing foodservice chains to abandon polyethylene-lined containers, redirecting procurement toward fiber-based barrier substrates with extruded biopolymer coatings. This regulatory compression is concentrating demand among converters capable of certifying migration-compliant structures across multiple jurisdictions.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated barrier chemistries are accelerating substitution toward extruded polyethylene and biopolymer coatings in chilled dairy applications.
- Quick-Service Restaurant Chains:Phased elimination of plastic-lined wraps across Germany, France, and the Netherlands is concentrating volume procurement for grease-resistant flexible packaging.
- Biopolymer Dispersion Methods:Advances in aqueous coating application at 12-30 gsm are enabling compliance with food-contact migration limits without fluorinated chemistries.
Market Restraints
- Resin Price Volatility:Polyethylene feedstock fluctuations compress converter margins, particularly for non-integrated producers lacking captive pulp supply.
- Technical Limitation:Current biopolymer barriers exhibit inferior oxygen transmission rates versus conventional fluorinated coatings, limiting shelf-life extension for sensitive perishables.
- Regulatory Friction:Divergent migration testing protocols between FDA 21 CFR notifications and EU REACH compliance create dual-certification burdens for exporters.
Strategic Opportunities
- Healthcare Applications:Sterile barrier packaging for medical devices remains nascent but carries elevated certification requirements and pricing premiums versus food-grade equivalents.
- India BIS Certification:Tightening GB standards alignment for food packaging migration testing creates first-mover advantage for converters establishing compliant supply chains.
- Molded Fiber Convergence:Integration of thermoformed rigid trays with in-mold barrier coatings is opening ready-meal segments previously dominated by plastic clamshells.
Industry Challenges
- Coating Technician Shortage:Specialized expertise in extrusion lamination and dispersion rheology is scarce outside established Nordic and Central European production clusters.
- Legacy Equipment Retrofit:Converting aqueous coating lines from solvent-based systems demands capital intensity that mid-scale converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycoated Paper Packaging Market |
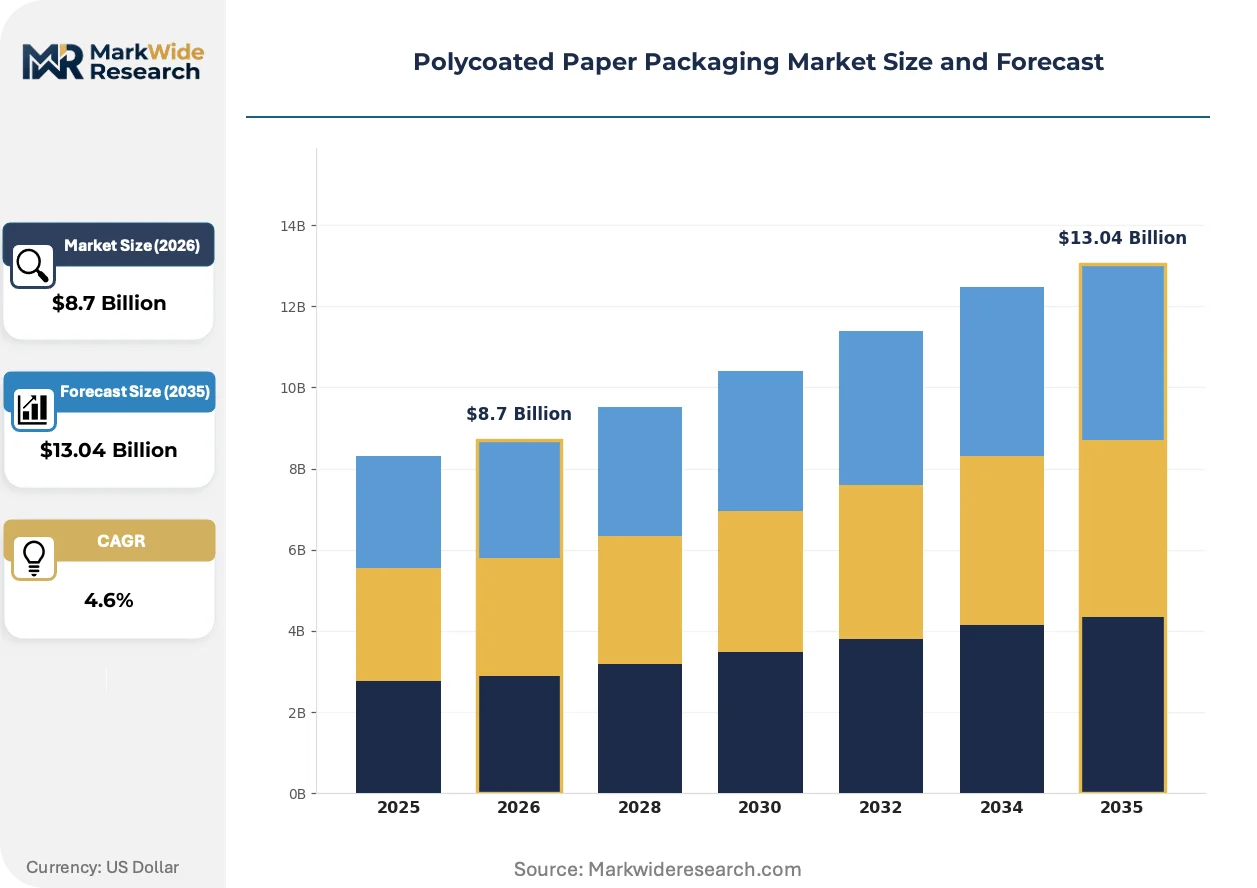
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Pouches, Coated Sheets End User: Food Industry, Beverage Sector, Personal Care, Healthcare Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale Thickness: Single Layer, Double Layer, Multi-Layer, Heavyweight |
| Companies Covered | Amcor Plc, Mondi Group, WestRock, Sealed Air Corporation, UFlex, Huhtamaki, Tetra Pak, Stora Enso, International Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycoated Paper Packaging Market Evolving Landscape
Barrier coating technologies are virtualizing traditional substrate-performance relationships, enabling cellulose fiber to displace multilayer plastic structures in oxygen-sensitive applications. Three convergent developments are compressing the technology adoption cycle across foodservice and retail packaging segments.
Water-based polymer dispersions with nano-cellulose reinforcement are virtualizing conventional extrusion lamination by achieving comparable grease resistance at reduced polymer loading. Bakery brands in Scandinavia are piloting these structures for butter-rich pastries, compressing the certification timeline from 18 months to under 12 months for qualified suppliers.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy fluorinated barrier chemistries from EU food-contact applications by 2026. Chilled dairy processors are responding by qualifying high-density polyethylene extrusion coatings for extended shelf-life yogurt cups, prioritizing converters with established EFSA-compliant testing documentation.
Centralized procurement by multinational quick-service restaurant chains is consolidating specification authority at headquarters level, displacing regional converter relationships. Germany-based procurement teams now mandate pan-European coating compliance certificates, compressing supplier qualification to a pre-approved vendor list of under 15 certified converters.
Polycoated Paper Packaging Market Segmentation
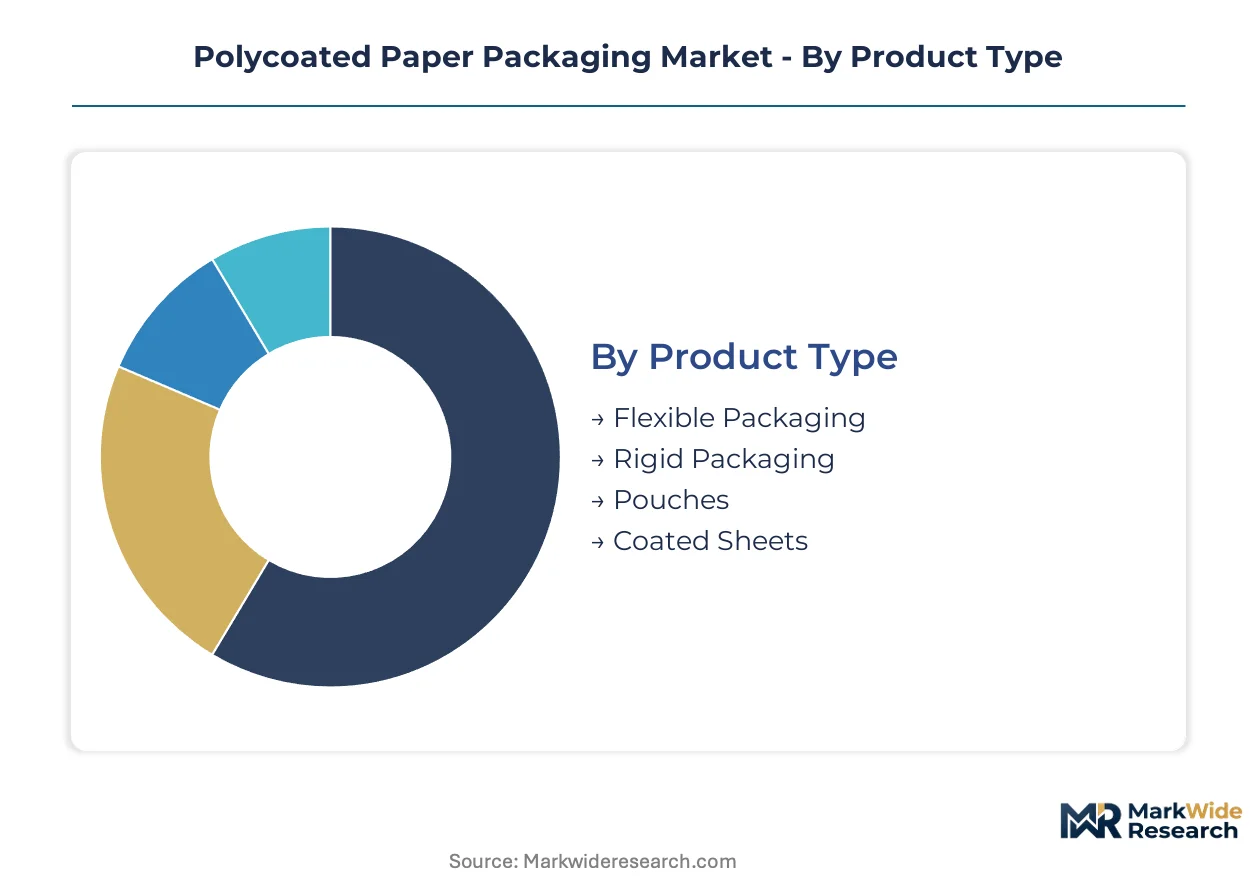
Segmentation in polycoated paper packaging reveals how coating technology, end-use migration limits, and distribution logistics create distinct margin profiles. Procurement specifications vary sharply between quick-service restaurant chains requiring grease-resistant flexible wraps and healthcare sterilization barriers demanding oxygen transmission certification.
Product Type:
After-sales technical support intensity varies dramatically across product categories, with rigid formats requiring mold maintenance programs and flexible formats demanding coating adhesion troubleshooting.
- Flexible Packaging:Polyethylene-laminated cellulose webs at 15-40 gsm coating weights serve quick-service restaurant wraps and confectionery sachets. Germany-based QSR procurement teams now mandate pan-European migration compliance certificates, compressing supplier qualification timelines. By volume, Flexible Packaging leads. By growth pace, Pouches is ahead.
- Rigid Packaging:Thermoformed trays and clamshells with extruded barrier layers achieve structural integrity for chilled dairy and ready-meal segments. EU Single-Use Plastics Directive compliance is redirecting foodservice chains toward these fiber-based alternatives.
- Pouches:Stand-up and flat pouch configurations with resealable zipper integration target premium confectionery and pet food segments requiring moisture vapor transmission resistance.
- Coated Sheets:Flat substrate formats for downstream converter processing into custom shapes, serving bakery box liners and industrial interleaving applications with lower barrier specification thresholds.
Converters with integrated coating lines capture margin advantages in Flexible and Rigid categories where specification complexity demands in-house technical support.
End User:
Application-driven performance requirements stratify procurement behavior, with food-contact migration limits imposing stricter certification burdens than industrial or cosmetic packaging.
- Food Industry:Grease-resistant containers for fried foods, butter-rich pastries, and chilled dairy dominate procurement scale. REACH restrictions on fluorinated chemistries are accelerating substitution toward extruded polyethylene coatings in EU applications.
- Beverage Sector:Liquid-tight cup stock and straw sleeves require heat-seal coating compatibility with hot-fill processes. Paperboard cups with aqueous barrier coatings are gaining share against plastic-lined alternatives.
- Personal Care:Moisture-resistant wraps for soap bars and cosmetic sachets carry lower regulatory burden than food-contact equivalents, enabling faster qualification cycles for coating innovations.
- Healthcare:Sterile barrier packaging for medical devices demands ISO 11607 compliance and elevated oxygen transmission resistance. Certification timelines extend 18-24 months versus 6-12 months for food-grade structures.
Food Industry procurement concentrates volume among multinational processors, while Healthcare commands pricing premiums exceeding 40% per square meter for qualified sterile barriers.
Distribution Channel:
Channel configuration determines order fragmentation and logistics cost absorption, with wholesale and direct procurement favoring integrated converters over trading intermediaries.
- Online Retail:E-commerce direct-to-consumer packaging emphasizes print quality and unboxing experience, driving demand for coated paper with premium surface finish capabilities.
- Supermarkets:Private-label foodservice packaging procurement concentrates specification authority at retail headquarters level, favoring converters with national distribution networks.
- Convenience Stores:Small-format ready-meal and grab-and-go segments require rapid replenishment cycles and localized converter relationships.
- Wholesale:Bulk shipment to downstream converters and foodservice distributors rewards scale economies in coating line utilization and raw material purchasing.
Wholesale channels dominate tonnage movement, while Online Retail exhibits the steepest expansion trajectory as direct-to-consumer food brands proliferate.
Thickness:
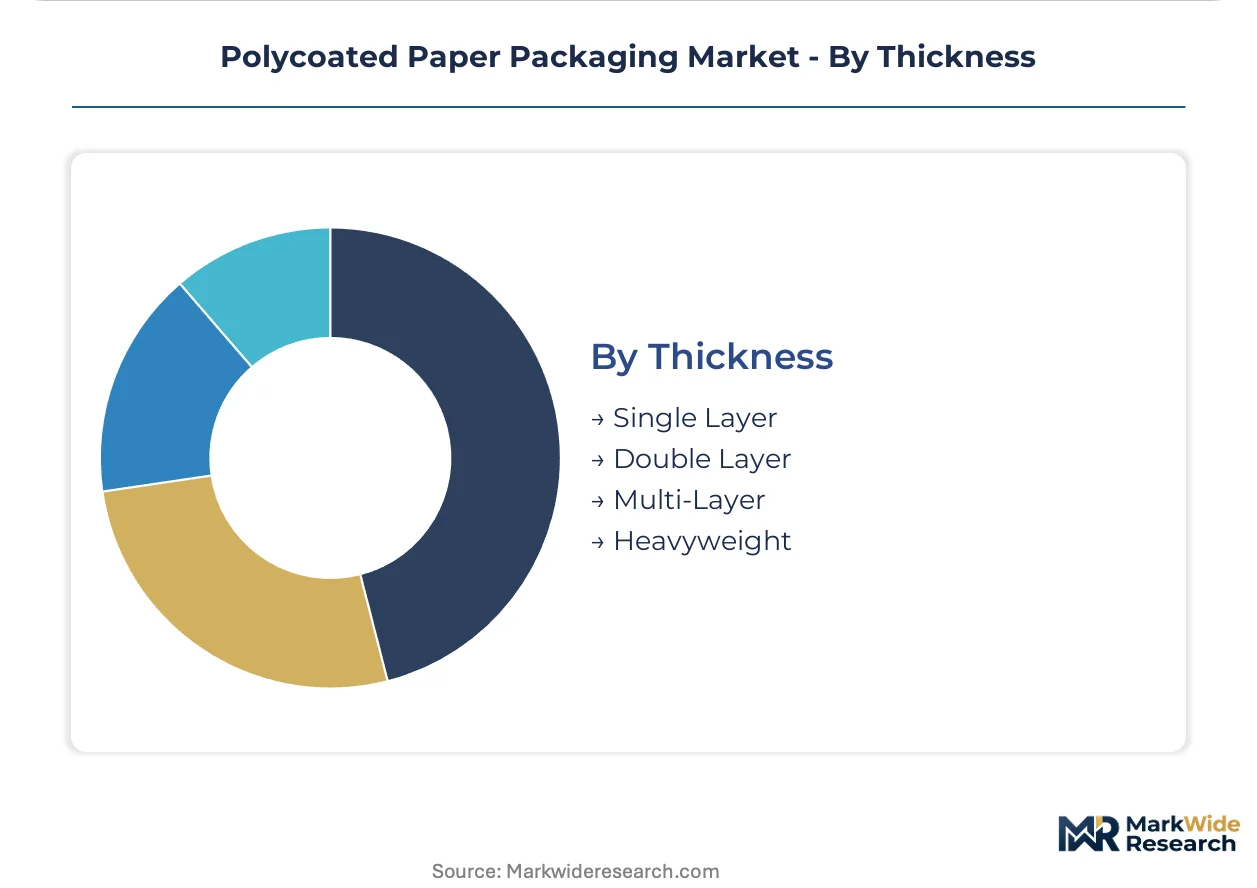
Structural specification tiers align with barrier performance requirements and converting equipment compatibility, with multi-layer constructions commanding technical service intensity for lamination process control.
- Single Layer:Basic grease resistance for dry food interleaving and lightweight wraps, utilizing 12-18 gsm extruded coatings on standard Kraft substrates.
- Double Layer:Enhanced moisture vapor transmission performance through tandem extrusion or dispersion coating sequences, serving bakery and fresh produce applications.
- Multi-Layer:Complex barrier structures combining cellulose fiber with polymer films and adhesive tie layers, targeting oxygen-sensitive applications such as modified atmosphere packaging.
- Heavyweight:Rigid board substrates above 300 gsm with integrated barrier coatings for structural packaging requiring crush resistance and thermal insulation.
Multi-Layer structures lead in technical complexity and margin contribution, while Single Layer dominates unit volume for commodity foodservice applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European supply chain resilience for polycoated paper substrates, while the Yangtze River Delta's integrated pulp-to-paper corridors anchor Asia-Pacific capacity expansion.
Germany
Quick-service restaurant chains in Bavaria and North Rhine-Westphalia are phasing out plastic-lined wraps for grease-resistant fiber alternatives. The EU Single-Use Plastics Directive mandates this transition by specific deadlines. Hamburg's converter cluster concentrates extrusion lamination expertise for pan-European certification compliance.
United States
Chilled dairy processors in Wisconsin and California are qualifying high-density polyethylene coatings for extended shelf-life applications. FDA 21 CFR notifications govern food-contact substance approvals for these structures. The Pacific Northwest's integrated pulp operations supply substrate feedstock to Midwest converting facilities.
China
GB standards for food packaging migration testing are tightening compliance thresholds for exporters serving domestic and international markets. NMPA and SAMR coordinate enforcement across provincial manufacturing zones. The Pearl River Delta's coating technology parks specialize in aqueous dispersion methods for flexible packaging.
India
BIS certification requirements are accelerating supply chain localization for multinational food brands entering the market. FSSAI alignment with international migration protocols creates compliance complexity for importers. Maharashtra's Thane-Belapur industrial belt hosts emerging converter capacity for bakery and ready-meal segments.
France
Bakery chains in Île-de-France are piloting nano-cellulose reinforced water-based coatings for butter-rich pastry containment. ANSM enforces food-contact compliance alongside EU REACH restrictions on fluorinated chemistries. The Auvergne-Rhône-Alpes region clusters specialized barrier coating research with EFSA-aligned testing documentation.
Polycoated Paper Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate and coating supply. The vendor base stratifies across three tiers: multinational integrated producers with captive forestry, regional converters with extrusion lamination expertise, and niche aqueous coating innovators. Two strategic archetypes dominate competitive positioning: backward-integrated pulp-to-paper operators and specialized barrier technology licensors. Capacity expansion and certification documentation investments represent the dominant competitive moves as procurement authority centralizes among multinational foodservice chains.
Among Nordic integrated producers, Stora Enso Oyj and Mondi Group exemplify the captive supply archetype, leveraging in-house pulp operations to stabilize margin exposure to resin volatility. Huhtamaki Oyj occupies a position within the specialized converter tier, anchoring barrier coating expertise for molded fiber applications. These three entities represent distinct strategic postures: forestry-backed integration, continental European scale, and emerging-market technical specialization.
| Leading Market Players |
|---|
| Amcor Plc |
| Mondi Group |
| WestRock |
| Sealed Air Corporation |
| UFlex |
| Huhtamaki |
| Tetra Pak |
| Stora Enso |
| International Paper |
| Others |
Value Network & Pricing Analysis
Integrated pulp-to-paper operations across Finland and Sweden concentrate upstream margin capture for polycoated paper substrates, redirecting value pools toward converters with captive forestry supply chains and extrusion lamination capabilities. Resin price volatility in polyethylene feedstock compresses non-integrated producer margins, forcing procurement consolidation among buyers seeking supply security.
Pricing Analysis
EU REACH compliance dictates the pricing tier structure across food-contact applications, separating EFSA-certified converters from uncertified competitors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from biopolymer barrier inferiority versus fluorinated alternatives, squeezing margins for shelf-life extension applications. Quick-service restaurant chains exhibit highest price sensitivity through centralized procurement, while healthcare sterile barrier buyers accept premiums exceeding standard food-grade equivalents.
Supply Chain Analysis
Extended payment terms from multinational foodservice chains are restructuring working capital requirements for mid-scale converters across Germany, France, and the Netherlands. Raw material supply draws from Nordic pulp operations, Saudi polyethylene resin imports, and Chinese aqueous coating chemical production. Single-source vulnerability concentrates in specialized extrusion lamination equipment sourced from Central European manufacturers. Distribution runs through Rotterdam port logistics for European converter networks, with wholesale channels dominating tonnage movement to downstream foodservice distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as pan-European certification requirements standardize supplier interfaces and compress regional converter relationships into pre-approved vendor lists.
For Market Incumbents: Build certification documentation moats by investing in EFSA-aligned testing infrastructure across multiple jurisdictions. Defend against emerging aqueous coating specialists through backward integration into pulp supply and capacity expansion in Germany's Hamburg converter cluster. Anchor relationships with centralized QSR procurement teams through dedicated technical service programs. For New Entrants and Emerging Players: Establish a beachhead in India's BIS certification-driven localization wave for multinational food brands. Target Maharashtra's Thane-Belapur industrial belt for bakery and ready-meal segment entry. Leverage aqueous dispersion coating expertise as a go-to-market angle against legacy extrusion lamination incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across molded fiber convergence applications requiring thermoforming and in-mold barrier coating integration. Long-term viability favors acquiring specialized barrier technology licensors with healthcare ISO 11607 certification pathways. Watch for biopolymer oxygen transmission rate breakthroughs as the signal indicating shelf-life extension market opening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive forestry operations in Nordic regions stabilize margin exposure to resin volatility. |
| EFSA-Aligned Certification Investment | Pan-European compliance documentation qualifies converters for centralized QSR procurement lists. |
| Aqueous Coating R&D Partnership | Nano-cellulose reinforcement advances compress certification timelines for butter-rich pastry applications. |
| Healthcare Barrier Market Entry | ISO 11607 sterile packaging commands pricing premiums exceeding food-grade equivalents per square meter. |
| India Supply Chain Localization | BIS certification alignment creates first-mover positioning for multinational food brand supplier status. |
Research Methodology
Desk research of trade association filings, customs records, and regulatory databases preceded structured interviews with coating line engineers, foodservice procurement directors, and barrier technology R&D leads. Primary fieldwork with extrusion lamination specialists and aqueous dispersion chemists combined with secondary validation from EU F-Gas Regulation implementation tracking and FDA 21 CFR notification databases. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Fixed regulatory substitution timelines and resin price band assumptions shaped projections across the analysis window. Segmentation dimensions modeled include coating technology type, end-use migration limit tier, distribution channel configuration, and regional certification cluster. CAGRs derived from unit economics modeling of converter line utilization rates and foodservice chain procurement cycle timing. Forecast inputs incorporated EU Single-Use Plastics Directive compliance deadlines and biopolymer barrier performance improvement curves.
Stress conditions across polyethylene feedstock volatility, fluorinated chemistry ban acceleration, and QSR procurement centralization pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about coating technician availability and legacy equipment retrofit financing access. Macroeconomic contraction, regulatory timeline extension, or biopolymer shelf-life breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Release Paper Market
Paper & Paperboard Packaging
Paper Carrier Bags Market
Paper & Paperboard Packaging
Plywood Box Market
Paper & Paperboard Packaging
United Kingdom (UK) Corrugated Board Packaging Market
Paper & Paperboard Packaging
UAE Corrugated Board Packaging Market
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
Asia Pacific Paper Packaging Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Paperboard Packaging Market
Paper & Paperboard Packaging
Foam Cups Market
Paper & Paperboard Packaging
Waxed Paper Packaging Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
SCK Paper Market