
 ESD Protective Signage Labels Market | 2026-2036
ESD Protective Signage Labels Market Size, Share, and Industry Trends Forecast 2026-2036
ESD Protective Signage Labels Market Foresight
Multi-source procurement among electronics OEMs is hardening as supply chain resilience priorities override historical single-vendor relationships. 3M Company leverages its materials science portfolio to sustain premium positioning across permanent adhesive formulations. Brady Corporation anchors North American distribution through direct channel control and specialized industrial标识 portfolios. Desco Industries competes on captive supply of ESD-safe workspace solutions that bundle signage with grounding hardware.
ESD protective signage labels are pressure-sensitive identifiers manufactured from static-dissipative substrates such as metallized polyethylene or carbon-loaded vinyl, designed to maintain surface resistivity between 10^6 and 10^9 ohms while conveying hazard warnings or handling protocols in electrostatic discharge controlled environments. Warning labels dominate procurement volumes due to mandatory posting requirements at EPA boundaries, while polyethylene material grades capture expanding share through superior chemical resistance in solvent-heavy cleanrooms. Permanent adhesive types lead in electronics manufacturing applications where label displacement risks compliance violations, though removable formulations grow fastest in laboratory settings requiring frequent equipment reconfiguration.
FDA facility regulations for medical device manufacturing intersect with OSHA workplace safety standards to mandate visible ESD hazard communication, while IEC 61340-5-1 certification requirements in electronics supply chains directly specify label durability and adhesion performance criteria. The EU RoHS directive constrains substrate chemistries, pushing converters toward halogen-free vinyl alternatives. Stakeholders must monitor evolving IEC standards revisions and regional chemical restriction expansions to anticipate specification shifts before contract renewal cycles.
Market Dynamics
Cleanroom protocol intensification across semiconductor fabrication is compressing replacement cycles for static-dissipative signage as Taiwan and South Korean facilities enforce stricter EPA boundary marking standards.
Growth Catalysts
- IEC 61340-5-1 compliance mandates:Electronics manufacturers must maintain surface resistivity specifications between 10^6 and 10^9 ohms, forcing substrate upgrades across assembly lines.
- Carbon-loaded vinyl substitution:Halogen-free alternatives meeting EU RoHS directive constraints are penetrating solvent-heavy cleanroom environments where chemical resistance determines label longevity.
- Taiwan semiconductor cluster expansion:Captive OEM assembly lines in Hsinchu Science Park drive concentrated procurement volumes for permanent adhesive warning labels.
Market Restraints
- Metallized polyethylene feedstock volatility:Petrochemical input fluctuations compress converter margins on static-dissipative substrate production.
- East Asian supply concentration:Taiwan and South Korea account for disproportionate fabrication demand, creating geographic vulnerability to regional disruption.
- RoHS compliance friction:EU chemical restrictions constrain legacy vinyl formulations, forcing costly formulation redevelopment.
Strategic Opportunities
- Indian electronics manufacturing zones:PLI scheme incentives are attracting semiconductor packaging operations requiring EPA-compliant hazard communication systems.
- Removable adhesive laboratory applications:Research facilities with frequent equipment reconfiguration represent underpenetrated demand for repositionable static-dissipative labels.
- Dual carbon goals alignment:China's MEE regulations are accelerating demand for low-carbon substrate alternatives in domestic cleanroom construction.
Industry Challenges
- IEC certification timeline compression:Standards revision cycles are outpacing converter qualification periods, straining R&D resource allocation.
- Legacy cleanroom integration complexity:Retrofitting existing semiconductor facilities with updated EPA boundary signage requires operational downtime coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ESD Protective Signage Labels Market |
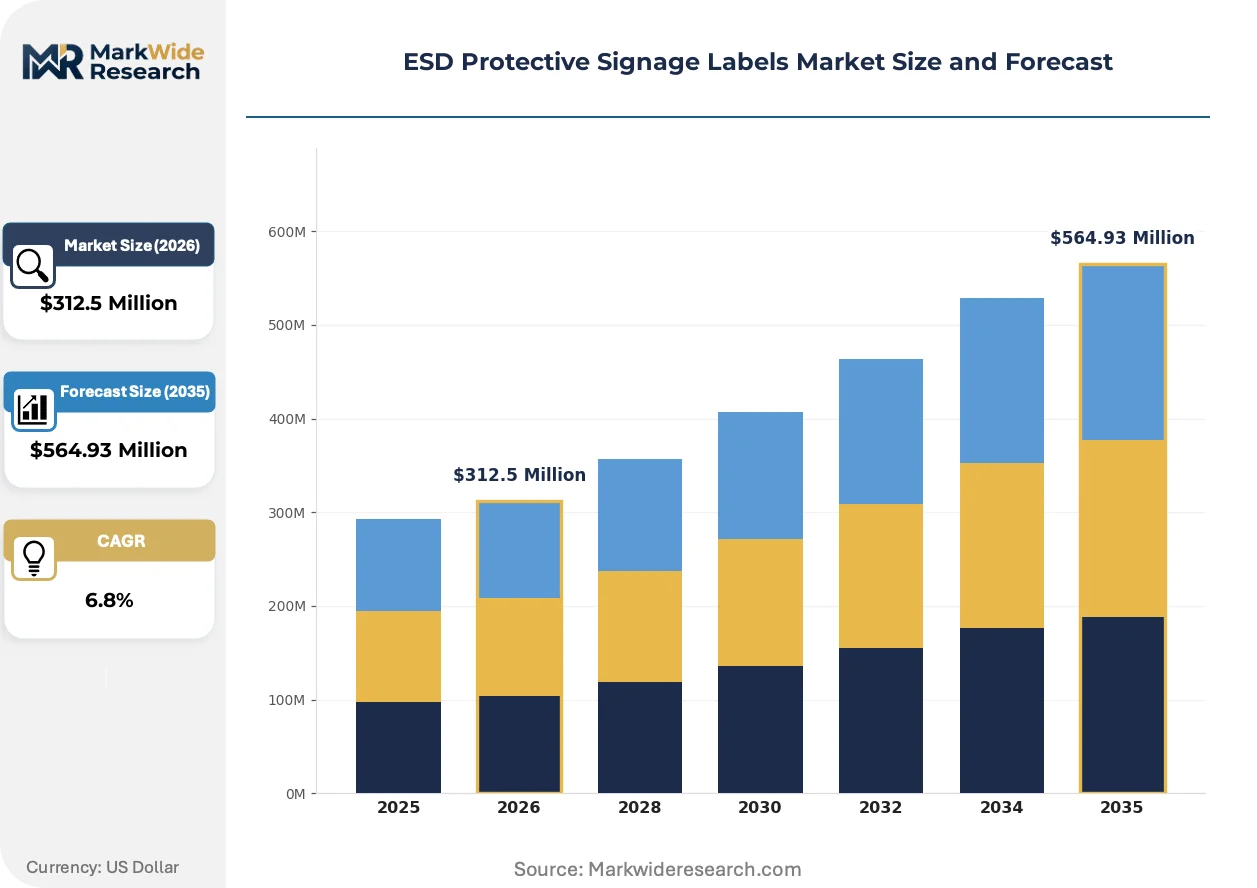
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Warning, Informational, Instructional, Prohibition Material: Vinyl, Polyethylene, Polypropylene, Paper Adhesive Type: Permanent, Removable, Low-Tack, High-Tack Application Area: Manufacturing, Electronics, Laboratories, Warehousing |
| Companies Covered | 3M Company, Brady Corporation, Desco Industries Inc., Nitto Denko Corporation, Panduit Corp., Henkel AG & Co. KGaA, CCL Industries, ULINE, SCS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ESD Protective Signage Labels Market Shifts & Advancements
Material science convergence with regulatory chemistry constraints is redefining substrate specifications as converters balance static-dissipative performance against halogen-free mandates.
Photoluminescent static-dissipative substrates are integrating emergency egress functionality into standard EPA warning labels. Semiconductor fabs in South Korea are adopting these dual-purpose identifiers to consolidate signage density on cleanroom surfaces. The technology is integrating safety system redundancy into single-label footprints, compressing installation labor costs while satisfying multiple compliance frameworks.
REACH substance restriction expansions are forcing substrate reformulation across European electronics supply chains. ECHA candidate list updates targeting specific plasticizers have triggered converter migration to bio-based vinyl alternatives. Medical device manufacturers in Germany face the most acute specification pressure as FDA facility regulations intersect with evolving EU chemical restrictions.
Multi-source qualification protocols are displacing historical single-vendor relationships among electronics OEMs. Direct channel control through specialized industrial distributors is fragmenting procurement concentration that previously favored integrated converters. This pattern is most visible in North American medical device manufacturing where supply chain resilience mandates now require dual-qualified label suppliers.
ESD Protective Signage Labels Market Segmentation
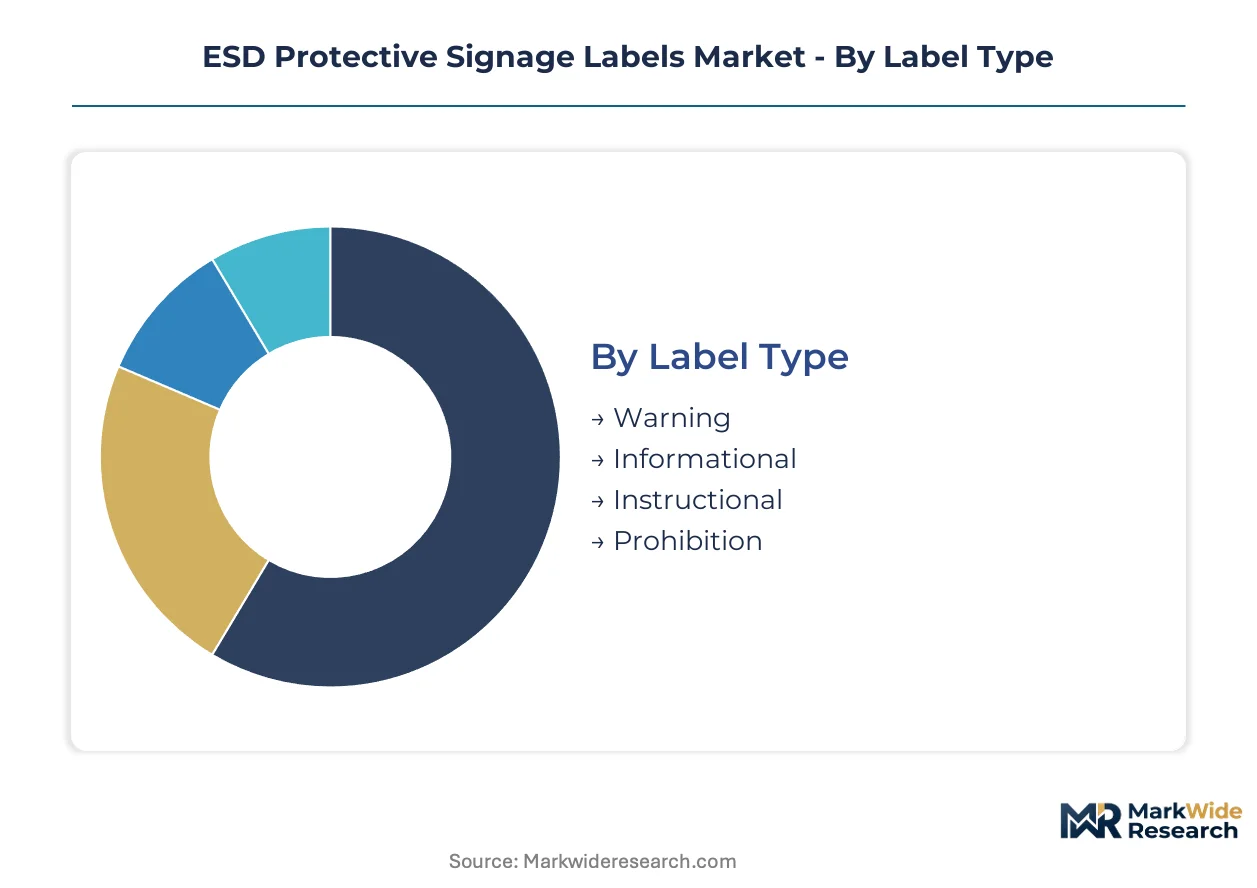
Segmentation in ESD protective signage labels reflects the tension between regulatory compliance mandates and operational flexibility requirements across controlled environments. Procurement patterns diverge sharply between high-volume electronics manufacturing and specialized laboratory applications, with material specifications and adhesive permanence serving as the primary decision axes.
Label Type:
Warning labels command the volume tier through mandatory EPA boundary posting requirements, while premium positioning concentrates in specialized instructional formats for complex handling protocols.
- Warning:These identifiers display hazard symbols and voltage thresholds for electrostatic discharge boundaries. Taiwan semiconductor fabs in Hsinchu Science Park drive concentrated procurement volumes as IEC 61340-5-1 compliance mandates tighten cleanroom protocols.
- Informational:Facility status and zone classification markers communicate EPA boundaries without hazard designation. South Korean memory manufacturers are expanding deployment of these labels to reduce visual clutter while maintaining static-dissipative substrate requirements.
- Instructional:Step-by-step handling protocols for sensitive components.
- Prohibition:Restricted activity markers for non-EPA personnel.
Mature deployment sits with Warning labels across established semiconductor corridors. Newer deployment is concentrated in Informational formats as facilities consolidate signage density.
Material:
Polyethylene grades are gaining share fastest in solvent-heavy cleanrooms where chemical resistance determines replacement cycles, while vinyl maintains legacy penetration through converter qualification inertia.
- Polyethylene:Metallized and carbon-loaded formulations achieve surface resistivity between 10^6 and 10^9 ohms. Medical device manufacturers in Germany are migrating toward these substrates as REACH substance restrictions pressure legacy vinyl formulations.
- Vinyl:Halogen-free alternatives are penetrating EU supply chains under RoHS directive constraints. Japanese electronics OEMs continue specifying traditional vinyl grades where converter relationships and qualification timelines create switching friction.
- Polypropylene:Lightweight substrates for temporary applications with moderate chemical exposure.
- Paper:Cost-sensitive disposable labels for short-duration inventory tracking.
Polyethylene is climbing the fastest as cleanroom chemical exposure intensifies. Paper remains confined to non-critical warehousing applications with minimal static control requirements.
Adhesive Type:
Permanent formulations anchor the premium tier through compliance risk mitigation, while removable adhesives are expanding most quickly in research environments requiring equipment reconfiguration flexibility.
- Permanent:Acrylic and rubber-based chemistries eliminate displacement risks in EPA boundary applications. Electronics manufacturing in Taiwan relies exclusively on permanent adhesives where label detachment triggers audit failures.
- Removable:Repositionable formulations maintain static-dissipative properties through multiple attachment cycles. Indian laboratory facilities under PLI scheme expansion are adopting these adhesives for flexible cleanroom layouts.
- Low-Tack:Temporary holding strength for prototype assembly stations.
- High-Tack:Aggressive bonding for textured or low-energy surfaces in industrial warehousing.
Permanent adhesive procurement dominates captive OEM assembly lines. Removable formulations are gaining share fastest in contract research organizations with dynamic equipment configurations.
Application Area:
Electronics manufacturing concentrates procurement volumes through EPA mandate density, while laboratory applications fragment across institutional and commercial research settings with divergent specification requirements.
- Electronics:Semiconductor fabrication and PCB assembly require continuous EPA boundary marking. South Korean memory fabs are compressing replacement cycles as cleanroom protocols intensify.
- Manufacturing:Medical device production intersects FDA facility regulations with OSHA workplace safety standards. German manufacturers face acute specification pressure from converging EU and US regulatory frameworks.
- Laboratories:Research facilities with frequent equipment reconfiguration.
- Warehousing:Inventory management in controlled storage environments.
Electronics maintains the steepest expansion trajectory through semiconductor capacity additions. Warehousing represents the most price-sensitive segment with minimal static-dissipative performance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metallized polyethylene feedstock concentration in East Asian petrochemical corridors anchors procurement geography for static-dissipative substrate converters. Taiwan and South Korean fabrication clusters drive disproportionate label volumes through captive OEM assembly line procurement.
Taiwan
Hsinchu Science Park semiconductor fabs compress replacement cycles for EPA boundary signage as cleanroom protocols intensify. IEC 61340-5-1 compliance mandates from the country's standards bureau force substrate upgrades across memory and logic chip production lines. Kaohsiung packaging operations are expanding procurement of permanent adhesive warning labels for captive assembly environments.
South Korea
Memory manufacturers in Pyeongtaek and Yongin are adopting photoluminescent static-dissipative substrates to consolidate emergency egress and EPA warning functionality. MFDS facility regulations intersect with semiconductor industry association standards to specify label durability criteria. Busan-area converters are qualifying halogen-free vinyl alternatives under EU RoHS directive alignment pressures.
United States
OSHA workplace safety standards and FDA facility regulations for medical device manufacturing mandate visible ESD hazard communication systems. Greater Boston and Twin Cities medical technology clusters are driving specification pressure for dual-compliant substrates. California-based electronics OEMs are implementing multi-source procurement protocols that fragment historical single-vendor relationships.
Germany
REACH substance restriction expansions and ECHA candidate list updates are forcing substrate reformulation across European electronics supply chains. Bavaria and Baden-Württemberg medical device manufacturers face acute specification pressure from converging FDA and EU regulatory frameworks. Stuttgart-area converters are migrating toward bio-based vinyl alternatives as legacy plasticizers face restriction.
India
PLI scheme incentives for semiconductor packaging and electronics manufacturing are attracting EPA-compliant hazard communication system deployments. Gujarat and Karnataka electronics manufacturing zones are adopting removable adhesive formulations for flexible cleanroom layouts. BIS standards alignment with IEC 61340-5-1 is accelerating domestic converter qualification timelines.
ESD Protective Signage Labels Market Competitive Landscape
Multi-source qualification protocols dominate the current landscape as supply chain resilience priorities displace historical single-vendor relationships. The vendor base stratifies across integrated materials science conglomerates, specialized industrial identification portfolios, and captive workspace solution bundlers. Three archetypes occupy distinct competitive positions: substrate-integrated converters leveraging backward control over adhesive chemistry, distribution-anchored specialists with direct channel control, and bundled solution providers combining signage with grounding hardware. Portfolio diversification and geographic expansion represent the dominant competitive moves as players seek to defend margin position against feedstock volatility.
Among diversified materials science conglomerates, 3M Company and Henkel AG & Co. KGaA exemplify the substrate-integrated archetype through captive adhesive formulation capabilities. Brady Corporation occupies a position within the specialized identification tier, anchoring North American distribution architecture. Desco Industries Inc. and Nitto Denko Corporation represent the bundled solution vector, integrating ESD-safe workspace components beyond standalone label supply. These named entities illustrate competitive positioning without exhausting the participant universe.
| Leading Market Players |
|---|
| 3M Company |
| Brady Corporation |
| Desco Industries Inc. |
| Nitto Denko Corporation |
| Panduit Corp. |
| Henkel AG & Co. KGaA |
| CCL Industries |
| ULINE |
| SCS |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap converters in Taiwan and South Korea anchor pricing discipline through multi-generational supplier relationships with semiconductor fabs, insulating premium tiers from spot-market volatility while compressing margins on standardized warning labels sold through industrial distributors.
Pricing Analysis
Warranty-backed IEC certification and on-site compliance audits are unbundled from base product pricing, with converter qualification services commanding separate fee structures. Three-tier pricing structure across premium, standard, and economy levels separates permanent adhesive formulations with full traceability from removable grades with limited batch documentation. Price differentiation hinges on surface resistivity certification granularity and cleanroom protocol alignment. Cost compression in economy-tier polyethylene labels is intensifying because metallized feedstock volatility transfers directly to converter margins. Contract research organizations exhibit highest price sensitivity due to discretionary procurement volumes, while captive OEM assembly lines absorb premium pricing to mitigate audit failure risks.
Supply Chain Analysis
Regional distribution centers in Kaohsiung, Busan, and Stuttgart maintain hub-and-spoke patterns that consolidate converter output before final-mile delivery to fabrication facilities. Raw material supply draws from South Korean petrochemical corridors for carbon-loaded vinyl, Japanese metallized film specialists, and German adhesive formulators serving REACH-compliant substrates. Single-source vulnerability concentrates in IEC-certified substrate qualification, where converter switching costs extend replacement timelines. Distribution runs through specialized industrial标识 distributors with direct channel control over North American and European medical device clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where feedstock volatility and certification timeline compression are forcing sub-scale converters into distressed sales or strategic exits.
For Market Incumbents: Acquire distressed converter assets in Taiwan and South Korea to consolidate IEC 61340-5-1 qualification portfolios and eliminate redundant certification overhead. Defensive positioning requires backward integration into metallized polyethylene substrate production to capture margin currently leaked to petrochemical suppliers. Carbon-loaded vinyl substitution trends threaten legacy formulation specialists who lack halogen-free R&D pipelines. For New Entrants and Emerging Players: Indian contract research organizations with dynamic equipment reconfiguration needs represent the most penetrable buyer archetype for removable adhesive specialists. Laboratory applications in Gujarat and Karnataka electronics manufacturing zones offer white-space positioning against entrenched permanent adhesive incumbents. Go-to-market execution should leverage PLI scheme procurement windows to establish reference accounts before captive OEM relationships harden. For Investors and Strategic Acquirers: Distressed-cycle entries favor converter assets with captive IEC certification and established relationships with Taiwan semiconductor fabs. Long-term viability rests on substrate formulation flexibility across polyethylene, vinyl, and emerging bio-based alternatives. The signal to watch is BIS standards alignment acceleration in India, which will trigger qualification timeline compression and strand non-compliant inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Captures margin from South Korean petrochemical suppliers while insulating against feedstock volatility. |
| IEC Certification Portfolio Expansion | Accelerates converter qualification timelines for halogen-free vinyl alternatives under REACH pressure. |
| Regional Distribution Center Establishment | Reduces final-mile costs to Hsinchu Science Park fabs through Kaohsiung hub consolidation. |
| Removable Adhesive R&D Investment | Targets Indian laboratory procurement under PLI scheme expansion with repositionable formulations. |
| Photoluminescent Substrate Development | Consolidates emergency egress and EPA warning functionality for South Korean memory manufacturers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among cleanroom operations managers, ESD compliance officers, industrial distributor procurement leads, and substrate converter technical directors. Triangulation combined bottom-up shipment data from Taiwan and South Korean fabrication clusters with top-down electronics manufacturing capex disclosures. Secondary validation drew from IEC standards documentation, ECHA candidate list updates, FDA facility inspection records, and BIS certification registries.
Data-stream reconciliation across volume shipments, material input consumption, and end-use procurement patterns enabled segmentation modeling by label type, material grade, adhesive permanence, and application area. CAGRs were derived from cleanroom construction pipelines and EPA boundary marking replacement cycles observed across the projection horizon. Industry-specific forecast inputs included semiconductor fab capacity additions in Hsinchu Science Park and Pyeongtaek, plus medical device manufacturing expansion in Bavaria and Baden-Württemberg.
Revisions become necessary when IEC standards revision cycles accelerate, REACH substance restrictions expand beyond current plasticizer targets, or geopolitical disruption affects East Asian petrochemical corridors. Forecasts reflect documented assumptions around cleanroom protocol intensification rates and converter qualification timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Integrated Labeling System Market
Labels
Stand Alone Label Applicator Market
Labels
Glue-Applied Labels Market
Labels
Global Print and Apply Labeling and Labeling Equipment Market
Labels
Global Label Adhesive Market
Labels
Sleeve Label Market
Labels
Global Security Labels Market
Labels
Warning Labels and Stickers Market
Labels
Self-Laminating Tags Market
Labels
Wire Marking Labels Market
Labels
Europe Shrink and Stretch Sleeve Label Market
Labels
Linerless Labels Market
Labels
Sustainable Labels Market
Labels
Glue Applied Automotive Labels Market
Labels
Pre-Gummed Labels Market
Labels
Cut and Stack Labels Market