
 Global Sack Kraft Paper Market | 2026-2036
Global Sack Kraft Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sack Kraft Paper Market Intelligence
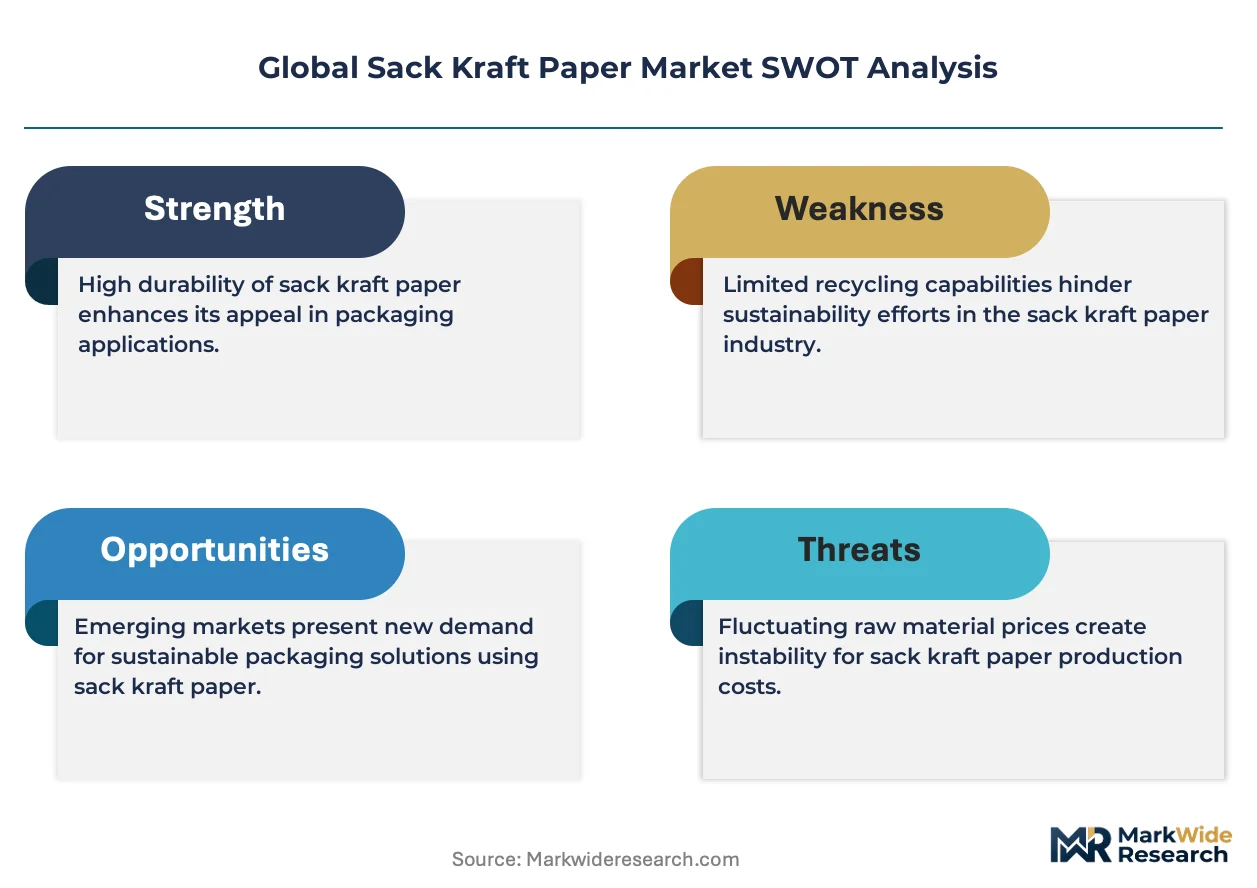
ISO 22000 certification for food-contact packaging is rotating the competitive threshold, disqualifying smaller mills without quality management systems. BillerudKorsnäs AB leverages its integrated Nordic pulp base to supply premium virgin grades for sensitive food applications. Mondi plc anchors Central European demand through dedicated flat-bottom valve bag lines serving cement majors. Stora Enso Oyj differentiates via FSC-certified fiber sourcing that commands preference among sustainability-scrutinizing buyers in Western Europe.
Sack kraft paper denotes a high-strength unbleached paper produced from softwood kraft pulp, typically exhibiting burst strengths above 350 kPa and tear indices suited to pneumatic filling operations in multiwall constructions. Its primary purpose centers on containment and transport of powdered or granular bulk goods across construction, agriculture, and food processing supply chains. Virgin kraft paper retains structural dominance where tensile integrity and moisture resistance prove non-negotiable, particularly in cement and chemical packaging segments. Recycled kraft paper occupies a narrowing but defended position in non-critical agricultural applications where lower basis weights suffice and cost sensitivity runs highest.
REACH compliance in Europe and FDA food-contact regulations in the United States impose divergent substance restrictions and migration limits that fragment formulation standards across export destinations. India's BIS certification for paper sacks used in food grain distribution adds a third compliance layer that regional exporters must navigate for market access. Stakeholders must monitor how tightening extended producer responsibility frameworks in the European Union and diverging state-level packaging laws across the United States reshape the cost structure of cross-border supply.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compelling mills to reformulate toward higher virgin fiber content, creating a structural divergence between compliance-ready suppliers and legacy operators dependent on recycled furnish.
Growth Catalysts
- Infrastructure expansion:Government-backed construction programs in India are multiplying addressable volume for cement packaging applications. Multiwall sack demand tracks directly to public works spending.
- REACH compliance:European substance restrictions are accelerating qualification of virgin kraft grades with certified migration profiles. Food-contact segments now require documented fiber provenance.
- Moisture-resistant coatings:Advanced barrier treatments are extending sack kraft into hygroscopic chemical and fertilizer applications previously served by plastic laminates.
Market Restraints
- Softwood pulp concentration:Nordic and Canadian suppliers control critical kraft pulp supply, exposing converters to input cost volatility when fiber markets tighten.
- Plastic substitution in non-critical uses:Polypropylene woven sacks are capturing cost-sensitive agricultural segments where pneumatic filling requirements are relaxed.
- BIS certification timelines:India's food grain packaging standards impose extended qualification periods that delay market entry for new suppliers.
Strategic Opportunities
- Underpenetrated African markets:Fertilizer distribution networks in Nigeria and Kenya lack qualified domestic sack suppliers, creating import substitution potential for certified producers.
- Extended producer responsibility tailwinds:EU mandates on recyclability are creating preference for mono-material paper constructions over multi-layer plastic alternatives.
- Flat-bottom valve automation:Convergence of form-fill-seal machinery with high-speed kraft lines is opening automated packaging adoption in mid-scale cement plants.
Industry Challenges
- ISO 22000 implementation:Food-contact certification requires documented HACCP systems that smaller mills lack the technical staff to maintain.
- Legacy equipment retrofit costs:Converting lines built for standard open-mouth sacks require substantial capital to handle modern valve-bottom designs with precision gluing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sack Kraft Paper Market |
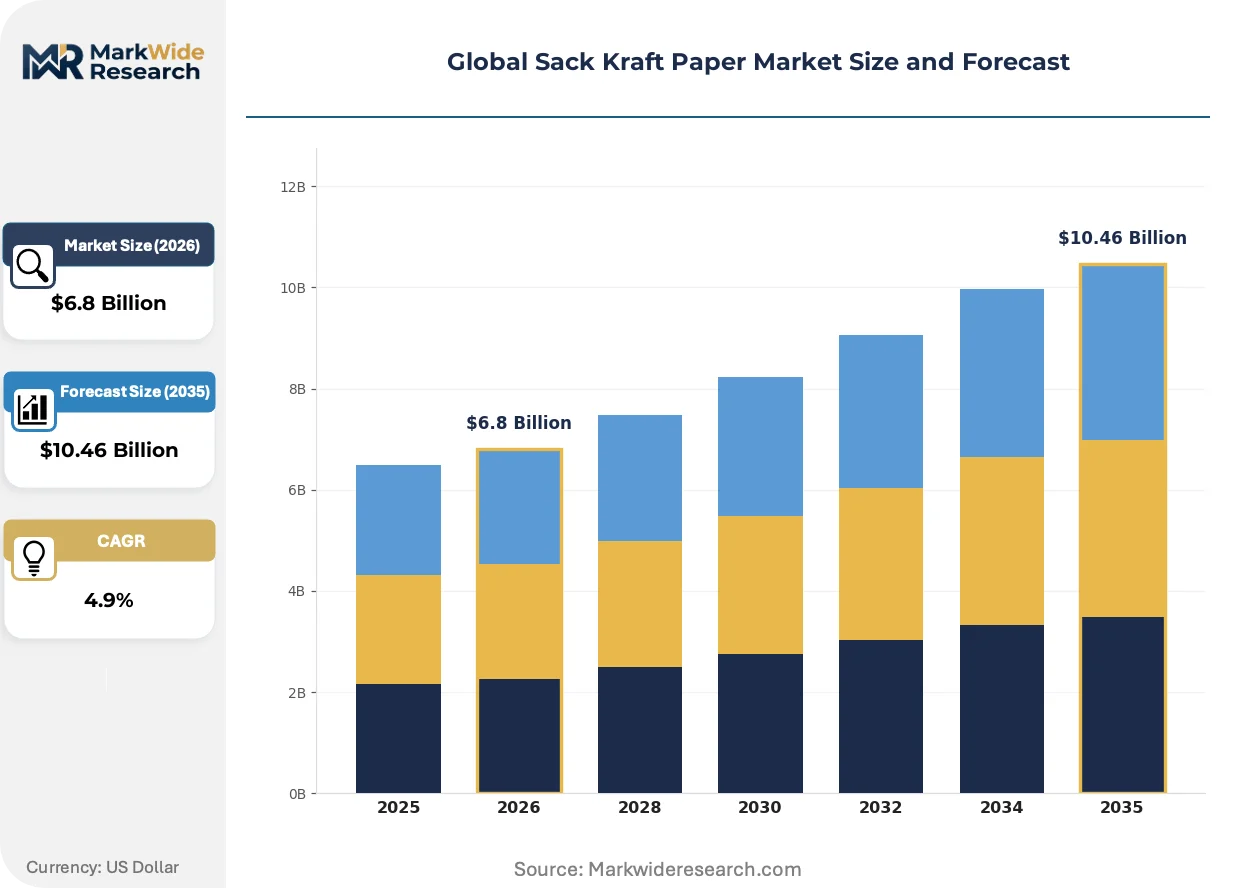
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.46 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virgin Kraft Paper, Recycled Kraft Paper, Semi-Chemical Kraft Paper, White Top Kraft Paper, Colored Kraft Paper Application: Food Packaging, Cement Packaging, Fertilizer Packaging, Chemical Packaging, Animal Feed Packaging End User Industry: Construction Materials, Agriculture Suppliers, Chemical Manufacturers, Food & Beverage Producers, Animal Nutrition Companies Packaging Type: Flat Bottom Valve Bags, Gusseted Bags, Padded Bags, Multiwall Bags, Block Bottom Bags |
| Companies Covered | BillerudKorsnäs AB, Nordic Paper AS, Mondi plc, Stora Enso Oyj, Georgia-Pacific LLC, Smurfit Westrock plc, Segezha Group PJSC, Oji Holdings Corporation, International Paper Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sack Kraft Paper Market Strategic Shifts & Innovations
Active reformulation of fiber mixes and coating chemistries is compressing the performance gap between virgin and recycled grades while regulatory pressure accelerates certification requirements.
High-strength extensible kraft produced through advanced refining and wet-pressing techniques is displacing conventional grades in high-speed cement filling operations. Major European cement producers have adopted these papers for automated lines running above 2,000 bags per hour. The technology is displacing standard kraft in premium packaging tiers where burst strength tolerances have tightened.
REACH substance restrictions on formaldehyde-based wet-strength resins are forcing mills to qualify alternative chemistries for moisture-resistant grades. Industrial consequence includes reformulation costs and extended migration testing timelines. Food-contact sack producers serving EU export markets are most affected, with several operators shifting to glyoxal-based systems.
Consolidated procurement by multinational cement and chemical groups is compressing supplier rosters and extending contract durations. Direct mill relationships are replacing distributor intermediaries in volume accounts above 10,000 annual tonnes. This pattern is most visible in Western Europe where Heidelberg Materials and similar majors have reduced qualified supplier pools by half.
Global Sack Kraft Paper Market Segmentation
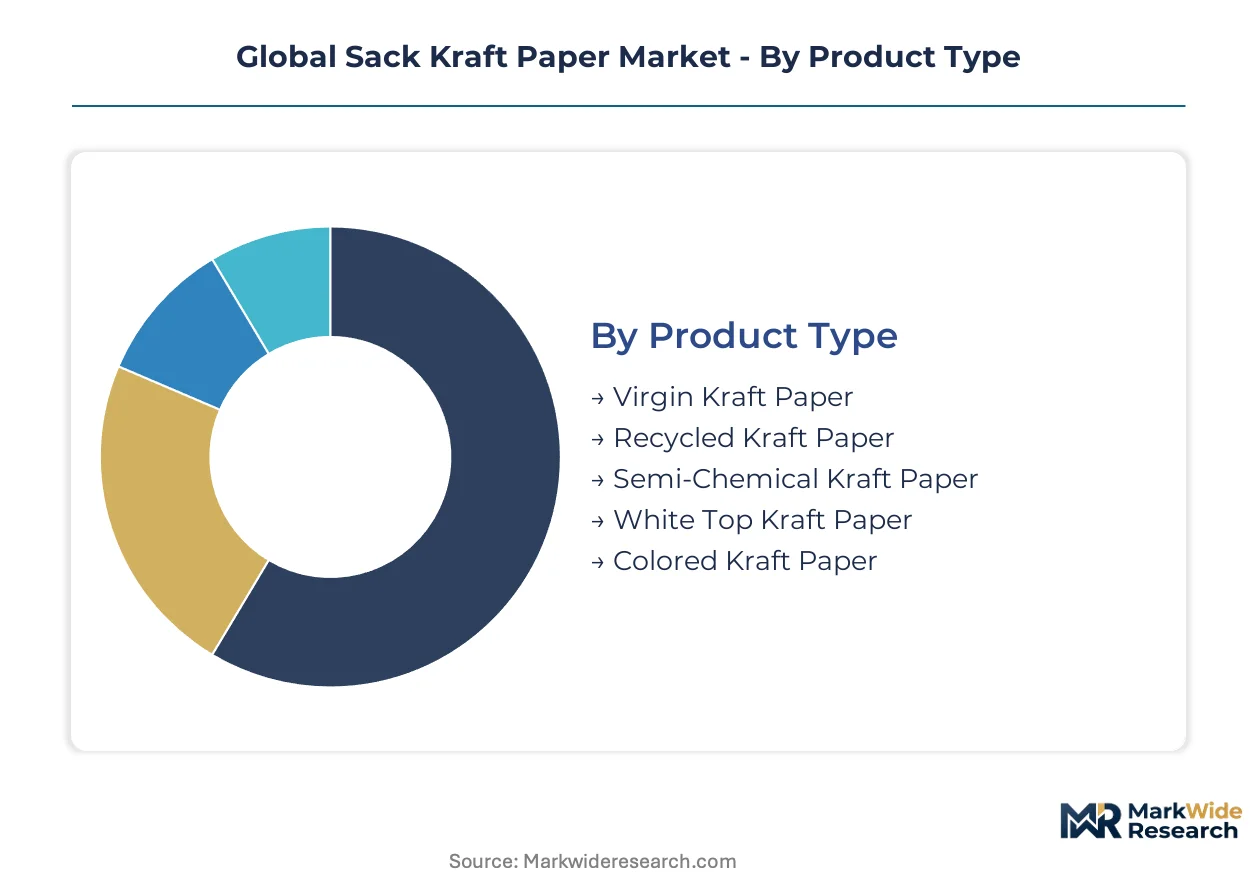
Sack kraft paper markets fragment across fiber source, application criticality, and packaging geometry. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier positioning.
Product Type:
Virgin grades command premium pricing where certification requirements tighten, while recycled furnish competes on cost in less regulated segments.
- Virgin Kraft Paper:Produced from unbleached softwood kraft pulp with burst strengths exceeding 350 kPa. Cement packaging in India and food-contact applications across EU markets concentrate demand as REACH compliance hardens migration requirements.
- Recycled Kraft Paper:Manufactured from post-consumer recovered fiber with reduced tensile properties. Agricultural bagging in cost-sensitive developing markets absorbs volume where BIS certification does not apply.
- Semi-Chemical Kraft Paper:Hybrid furnish combining virgin and recycled streams for mid-tier performance.
- White Top Kraft Paper:Bleached surface layer over unbleached base for printed branding visibility.
- Colored Kraft Paper:Pigmented grades for product differentiation in specialty chemical distribution.
The dominant share belongs to Virgin Kraft Paper, while Recycled Kraft Paper is closing the gap fastest through reformulation advances.
Application:
Volume concentrates in construction-linked segments, though food-contact qualification opens structurally higher-margin positions.
- Cement Packaging:Multiwall constructions withstand pneumatic filling pressures above 2,000 bags per hour. Infrastructure investment across India, Nigeria, and Kenya drives material offtake as government-backed programs expand public works spending.
- Food Packaging:ISO 22000 and FDA food-contact compliance mandatory. EU and US export markets reward documented fiber provenance with contract premiums and extended supply agreements.
- Fertilizer Packaging:Moisture-resistant coatings essential for hygroscopic products; REACH restrictions on formaldehyde-based resins force chemistry transitions.
- Chemical Packaging:Barrier-treated grades penetrate markets previously served by plastic laminates.
- Animal Feed Packaging:Lower basis weight requirements permit recycled furnish adoption where tensile demands relax.
Cement Packaging holds the volume lead, yet Food Packaging expands most quickly on certification premiums.
End User Industry:
Procurement power varies sharply: consolidated cement majors squeeze pricing while fragmented agricultural buyers accept standard terms.
- Construction Materials:Heidelberg Materials and similar multinationals consolidate supplier rosters, extending contract durations above five years for qualified mills.
- Agriculture Suppliers:Distributed procurement across cooperatives and regional distributors preserves price competition.
- Chemical Manufacturers:Migration testing requirements segment supply between REACH-compliant and standard grades.
- Food & Beverage Producers:HACCP documentation demands filter out smaller mills lacking technical staff.
- Animal Nutrition Companies:Cost-driven purchasing favors lighter basis weights with sufficient burst tolerance.
Construction Materials consumes the largest share, though Food & Beverage Producers climb fastest on contact-grade premiums.
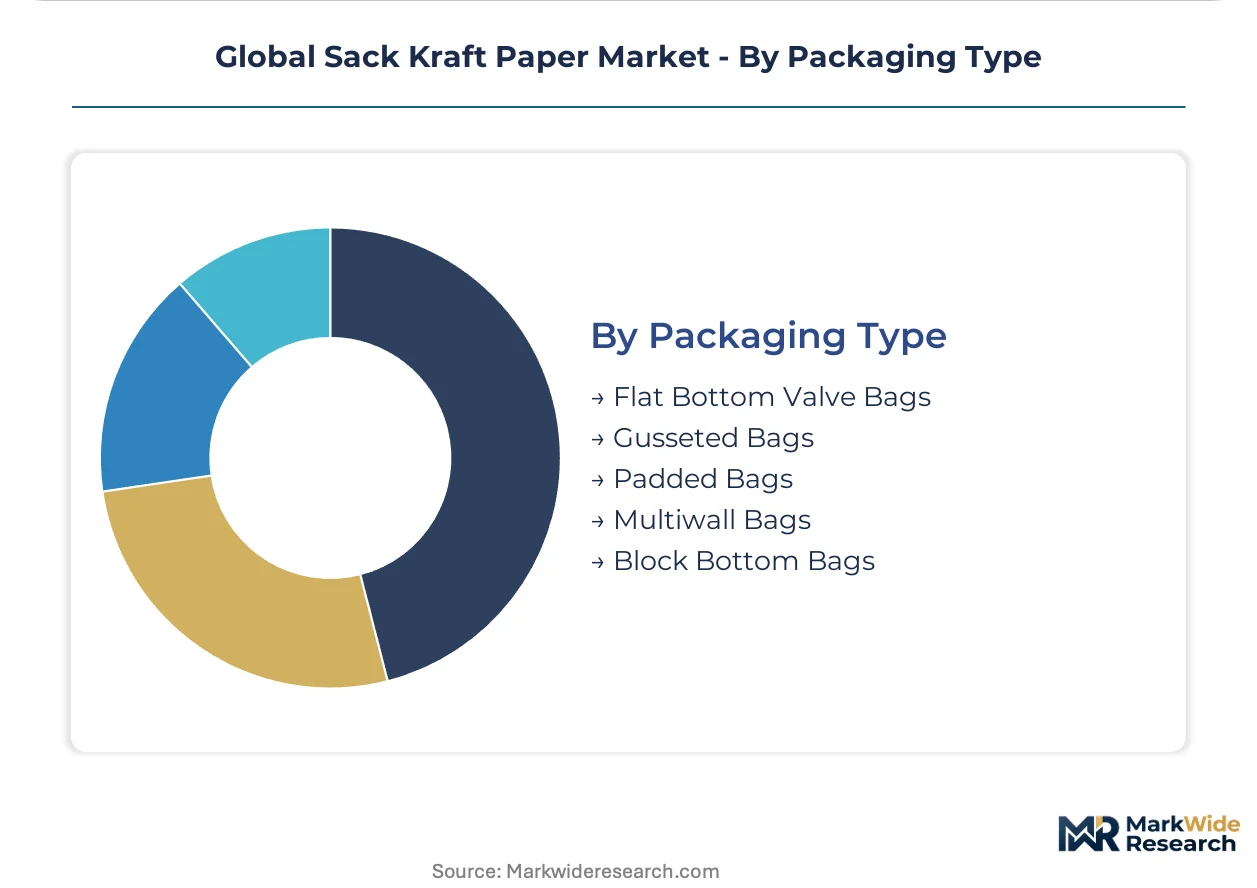
Packaging Type:
Automation readiness now determines format preference as cement plants modernize filling lines.
- Flat Bottom Valve Bags:Precision-glued valve bottoms enable form-fill-seal automation at rates exceeding 2,000 units hourly. Mondi plc anchors Central European supply through dedicated production lines.
- Multiwall Bags:Layered kraft constructions provide burst strength and puncture resistance for pneumatic filling. Virgin fiber dominance persists where structural integrity is non-negotiable.
- Block Bottom Bags:Self-standing geometry improves palletization efficiency in retail-facing distribution.
- Gusseted Bags:Expandable side panels accommodate variable fill volumes in agricultural applications.
- Padded Bags:Cushioned constructions protect fragile contents in specialty chemical handling.
Flat Bottom Valve Bags lead on automation adoption, while Multiwall Bags retain widest application coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration varies sharply by geography. Cement majors in India and construction conglomerates in Germany consolidate procurement through direct mill relationships, while fragmented agricultural cooperatives in Brazil and Nigeria preserve distributor intermediaries.
India
Government-backed infrastructure programs are multiplying cement sack offtake as public works spending accelerates. BIS certification for food grain packaging imposes extended qualification timelines that filter out smaller suppliers. The western industrial belt around Gujarat hosts expanding converting capacity serving domestic cement majors.
Germany
Heidelberg Materials and similar construction groups consolidate supplier rosters, extending contract durations above five years. REACH substance restrictions on formaldehyde-based wet-strength resins force chemistry transitions among domestic mills. The North Rhine-Westphalia cluster anchors Central European supply for automated cement filling lines.
United States
FDA food-contact regulations impose migration testing requirements that segment supply between export-qualified and standard grades. Chemical distributors in the Gulf Coast corridor are adopting moisture-resistant kraft for hygroscopic fertilizer applications. The Southeast pulp and paper corridor maintains integrated virgin fiber supply for sensitive food-contact segments.
Brazil
Cost-sensitive agricultural buyers favor lighter basis weights where tensile demands relax, preserving recycled furnish penetration. ANVISA pharmaceutical packaging standards create adjacent demand for certified fiber provenance in specialty chemical distribution. The São Paulo industrial hinterland concentrates converting capacity for regional fertilizer majors.
Nigeria
Fertilizer distribution networks lack qualified domestic sack suppliers, creating import substitution openings for certified producers. The country's national standards body imposes evolving packaging specifications for food grain distribution. Lagos and Port Harcourt serve as entry points for European and Asian mill supply serving West African construction materials demand.
Global Sack Kraft Paper Market Key Industry Players
Player mix skews toward integrated Nordic pulp producers with captive softwood supply. Market structure concentrates around five major groups controlling critical virgin fiber output. Strategic archetypes separate into pulp-integrated premium suppliers, regional scale operators, and specialty converters. Competitive moves center on backward integration into pulp assets and geographic expansion into underpenetrated African and South Asian markets.
Within the pulp-integrated tier, BillerudKorsnäs AB and Stora Enso Oyj represent the certification-ready archetype serving EU food-contact mandates. Mondi plc occupies a position anchoring Central European cement demand through dedicated production infrastructure. These three exemplify how Nordic fiber access and documented provenance systems create preference among sustainability-scrutinizing buyers.
| Leading Market Players |
|---|
| BillerudKorsnäs AB |
| Nordic Paper AS |
| Mondi plc |
| Stora Enso Oyj |
| Georgia-Pacific LLC |
| Smurfit Westrock plc |
| Segezha Group PJSC |
| Oji Holdings Corporation |
| International Paper Company |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts with Nordic pulp suppliers lock in both fiber access and price visibility for qualified mills serving EU cement and food-contact segments. These arrangements insulate integrated producers from spot pulp volatility while exposing non-integrated converters to margin compression when softwood markets tighten.
Pricing Analysis
Cost-plus contracts indexed to NBSK pulp benchmarks dominate procurement between integrated mills and multinational cement majors. Price differentiation rests on certification grade and volume scale, with ISO 22000-compliant food-contact grades commanding substantial premiums over standard construction tiers. Cost compression in recycled furnish segments is intensifying because polypropylene woven sacks capture cost-sensitive agricultural offtake. Agricultural cooperatives exhibit highest price sensitivity, while consolidated construction materials groups accept premium pricing for assured supply security.
Supply Chain Analysis
Inventory buffers at Nordic port terminals stretch lead times for Asian converters dependent on imported softwood pulp. Supply concentrates in Sweden, Finland, and Canada, with raw material flows drawing from managed boreal forests and plantation eucalyptus in Brazil. Single-source vulnerability runs through the Baltic Sea logistics corridor where ice conditions constrain winter shipments. Distribution runs through direct mill relationships for volume accounts above 10,000 annual tonnes, replacing distributor intermediaries in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified virgin fiber supply and documented certification systems constitute scarce capabilities that filter out smaller competitors, concentrating margin capture among integrated Nordic producers with captive pulp assets and provenance documentation.
For Market Incumbents: Compound certification advantages by extending ISO 22000 and FSC chain-of-custody coverage into underpenetrated African fertilizer markets. Prioritize capacity addition in Gujarat's western industrial belt to anchor Indian cement demand. Defend against polypropylene substitution in agricultural tiers through moisture-resistant coating investments that narrow the performance gap with plastic laminates. For New Entrants and Emerging Players: Lead with BIS certification qualification for India's food grain distribution network, where extended timelines filter out established competitors. Target Nigerian fertilizer packaging as the most penetrable geography, leveraging import substitution demand from underqualified domestic supply. Pursue joint venture structures with European mills seeking REACH-compliant export capacity without greenfield investment. For Investors and Strategic Acquirers: Capital is best deployed toward pulp-integrated mid-cap specialists with latent certification capacity and geographic expansion optionality into Kenya or Vietnam. Long-term viability hinges on backward integration into softwood fiber assets as pulp market concentration intensifies. Watch for EU Packaging and Packaging Waste Regulation enforcement timelines as the inflection signal for premium grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Assets | Captive softwood supply insulates margin from NBSK price volatility. |
| ISO 22000 Certification Investment | Food-contact qualification opens premium tiers in EU export markets. |
| Flat-Bottom Valve Line Automation | Form-fill-seal compatibility anchors supply to Heidelberg Materials. |
| Moisture-Resistant Coating Reformulation | Glyoxal-based systems replace formaldehyde resins under REACH. |
| African Market Entry Partnership | Nigerian fertilizer demand outruns qualified domestic sack supply. |
Research Approach
A spread of perspectives from mill operations directors, cement procurement leads, converting line engineers, and agricultural cooperative buyers converged on the working assumptions. Primary fieldwork combined with secondary validation from customs trade data, BIS certification registries, SEC 10-K pulp disclosures, and EU ECHA substance restriction updates. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates across the analysis window.
Segmentation dimensions modeled include fiber source tier, application criticality, packaging geometry, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections tied to infrastructure spending trajectories and certification adoption curves. Industry-specific forecast inputs encompassed Indian public works budget allocations and EU extended producer responsibility implementation pacing.
The analysis sits within stated boundaries; outcomes outside sustained softwood pulp availability or abrupt REACH chemistry bans would require recalibration. Forecasts reflect documented assumptions on certification timeline elasticity and African import substitution velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Push-Up Paperboard Tube Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Envelope Paper Market
Paper & Paperboard Packaging
Flowpack Paper Packaging Market
Paper & Paperboard Packaging
Global Window Cake Box Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
Vietnam Paper Packaging Market
Paper & Paperboard Packaging
Masking Paper Market
Paper & Paperboard Packaging
Coated Paper Market
Paper & Paperboard Packaging
North America Paper Packaging Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Tea Filter Paper Market
Paper & Paperboard Packaging
Non-Tacky Transfer Paper Market
Paper & Paperboard Packaging
Macerated Paper Padded Mailers Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Global Multi Depth Corrugated Boxes Market