
 US Copper Scrap Market | 2026-2036
US Copper Scrap Market Size, Share, and Industry Trends Forecast 2026-2036
US Copper Scrap Market Intelligence
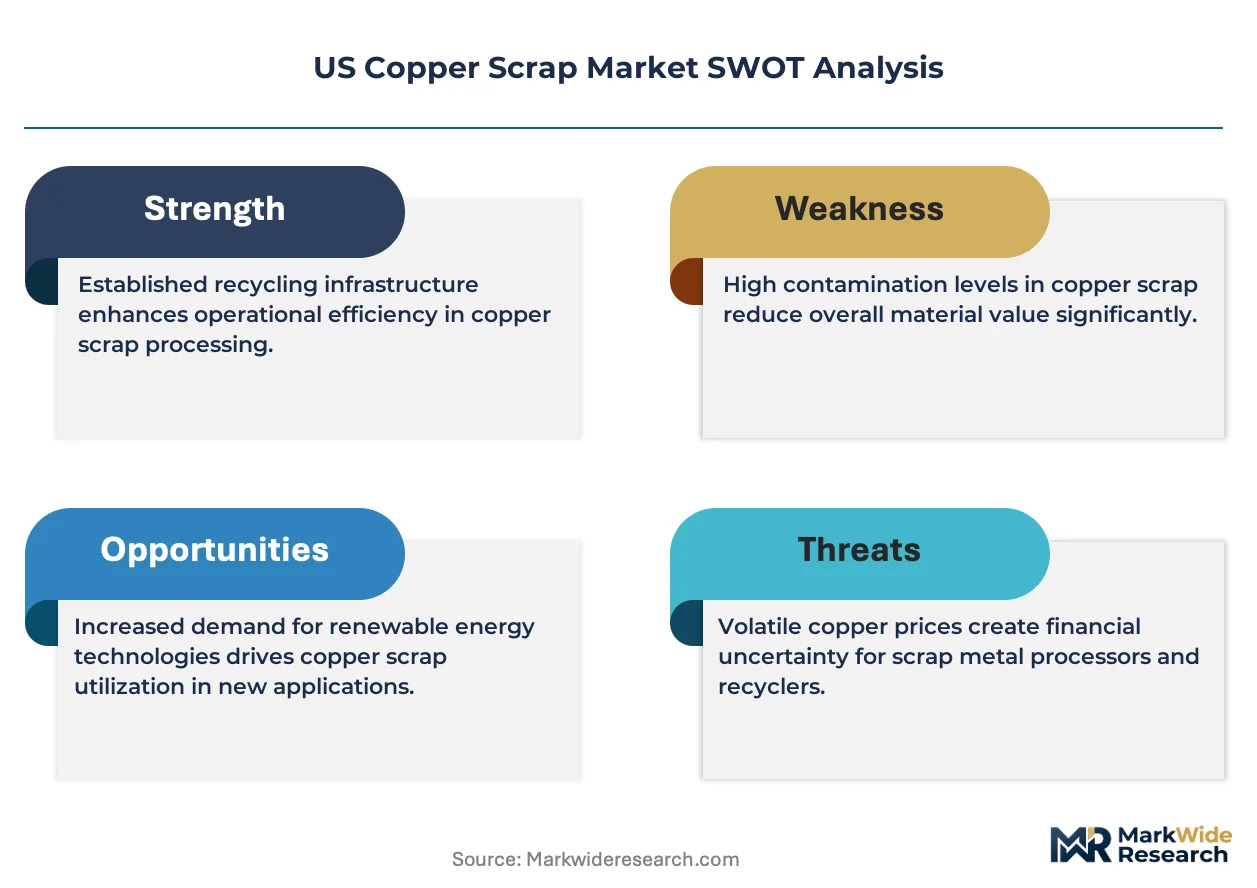
The Inflation Reduction Act's emphasis on domestic sourcing for clean energy technologies is recalibrating collection and processing priorities within the US copper scrap market. Nucor Corporation leverages its extensive recycling network to secure feedstock for its metal products. Sims Metal Management specializes in processing complex scrap streams from industrial and electronic sources, while Radius Recycling sustains a strong presence in construction and demolition scrap collection.
The US copper scrap market encompasses the collection, processing, and trade of non-ferrous metal from end-of-life products and industrial byproducts. This material is categorized by purity, such as 'bare bright' wire with over 99% copper content, which is essential for remelting. Industrial scrap from manufacturing constitutes the largest volume source, providing consistent quality for smelters. While Grade A material commands premium pricing, collection of lower-purity electrical scrap is expanding due to e-waste recycling mandates.
The Environmental Protection Agency (EPA) sets standards for hazardous waste handling and landfill diversion, influencing collection methods. Concurrently, Occupational Safety and Health Administration (OSHA) regulations govern worker safety in scrap processing facilities, impacting operational costs and equipment choices. Future market profitability depends on processors' ability to invest in advanced sorting technologies to meet increasingly stringent purity requirements from manufacturers and fabricators.
Market Dynamics
The primary structural force governing the US copper scrap market is the strategic tension between domestic industrial policy, exemplified by the Inflation Reduction Act, and the inherent volatility of global commodity pricing, which influences collection and trade flows.
Growth Catalysts
- Inflation Reduction Act:This policy incentivizes domestic sourcing for clean energy technologies, directly increasing demand for US-processed copper scrap for use in electric vehicles, grid modernization, and renewable energy infrastructure.
- Construction Sector Offtake:Sustained activity in residential and commercial construction in the US drives consistent demand for copper scrap as a primary feedstock for manufacturing electrical wiring, plumbing pipes, and HVAC components.
- E-Waste Recycling Mandates:State-level electronic waste regulations are expanding the collection stream of lower-purity scrap, creating volume for processors with advanced sorting capabilities to upgrade the material for remelting.
Market Restraints
- Energy Price Volatility:The profitability of scrap processing is sensitive to fluctuations in electricity and natural gas prices, as remelting and refining copper are energy-intensive processes that constitute a significant operational cost.
- Inconsistent Feedstock Quality:Scrap sourced from post-consumer or demolition streams exhibits high variability in purity and composition, complicating processing and requiring additional sorting steps to meet smelter specifications.
- Substitution from Aluminum:In certain applications like electrical wiring for construction and automotive components, high copper prices can trigger material substitution with aluminum, placing a ceiling on demand.
Strategic Opportunities
- Advanced Sorting Investment:Opportunity exists for processors to invest in automated sorting technologies like X-ray fluorescence (XRF) to upgrade mixed and low-grade scrap into high-purity furnace-ready material, capturing significant value.
- EV Infrastructure Feedstock:The national build-out of electric vehicle charging stations and battery manufacturing facilities presents a new, large-scale demand channel for high-conductivity copper products derived from scrap.
- Southeastern US Expansion:As manufacturing investment grows in the US Southeast, an opportunity emerges to develop new collection networks and processing hubs to serve these industrial centers, complementing the established Midwest infrastructure.
Industry Challenges
- Skilled Labor Scarcity:Processors face difficulties in recruiting and retaining technicians skilled in operating and maintaining advanced metallurgical sorting equipment and robotics, impacting plant efficiency and uptime.
- Capital Expenditure Hurdles:The high upfront cost of sophisticated sorting and shredding machinery, coupled with the expense of environmental compliance upgrades, acts as a barrier to entry and expansion for smaller operators.
- Purity Verification Demands:Meeting end-user requirements for certified material with extremely low levels of contaminants necessitates rigorous, costly, and time-consuming quality control and laboratory analysis throughout the process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Copper Scrap Market |
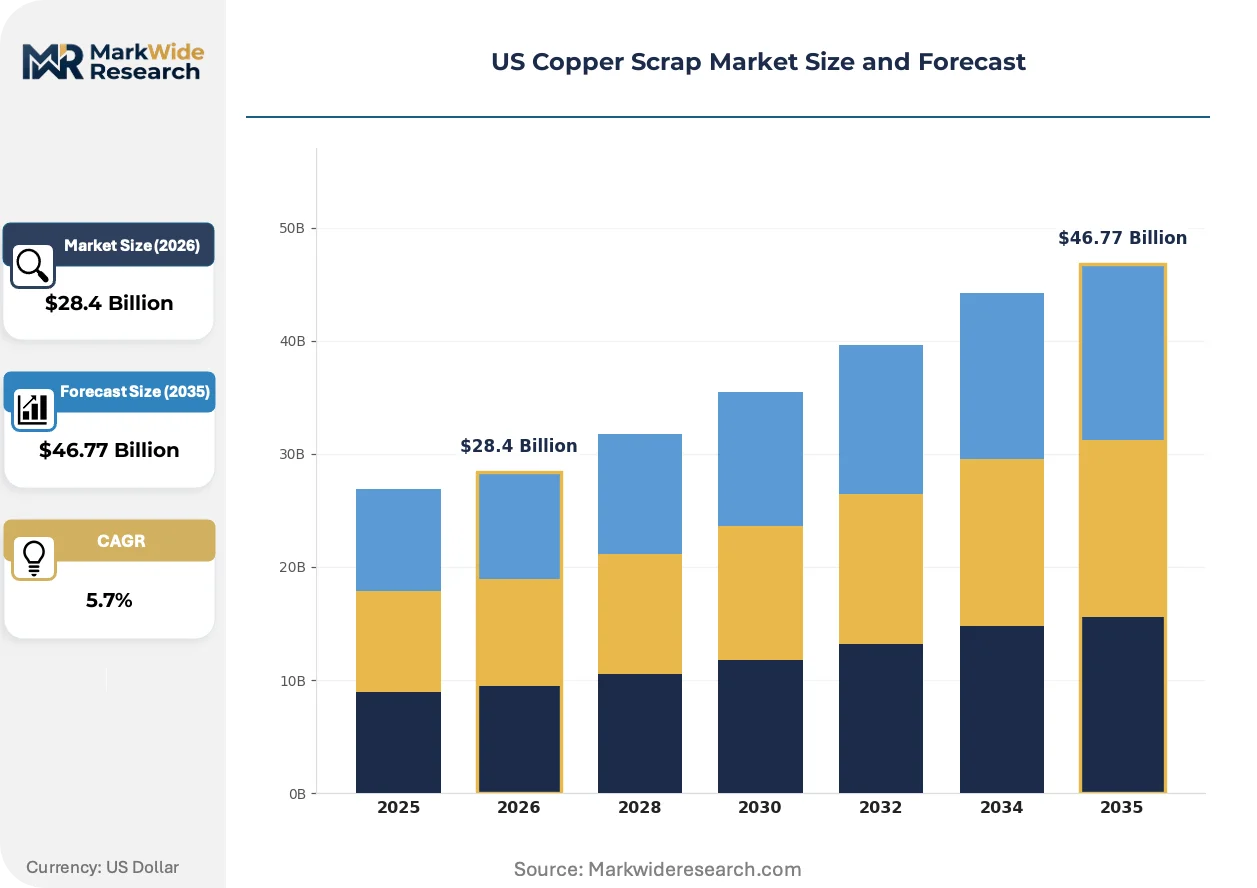
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $46.77 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Source Type: Industrial Scrap, Electrical Scrap, Household Scrap, Construction Scrap Purity Grade: Grade A, Grade B, Dirty Scrap, Low-Quality Scrap Collection Method: Curbside Collection, Drop-off Centers, Buyback Programs, Recycling Facilities End User: Metal Recyclers, Manufacturers, Fabricators, Exporters |
| Companies Covered | Commercial Metals Company, Sims Metal Management, SA Recycling, OmniSource Corporation, Nucor Corporation, AIM Recycling, Radius Recycling, Metalico, Inc., Aurubis AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Copper Scrap Market Strategic Shifts & Innovations
Digitalization and automation are fundamentally altering the operational model of copper scrap processing. The market is shifting from a business based on collection volume to one where value is created through precise material science, driven by manufacturer demand for specific metallurgical properties.
Advanced sorting systems utilizing X-ray fluorescence and optical sensors provide real-time elemental analysis of shredded scrap. Major recycling facilities are adopting this technology to segregate complex scrap streams, such as those from electronics and automobiles, into distinct metal and alloy categories. This automated, high-throughput classification is overtaking traditional manual sorting for achieving the purity levels required by specialty fabricators and foundries.
The Inflation Reduction Act (IRA) is creating powerful incentives for a more localized supply chain. Its domestic content provisions for clean energy projects directly encourage manufacturers to procure copper from US-based recycling facilities. Scrap processors in the industrial Midwest are particularly affected, reconfiguring their operations to provide certified, traceable material to feed the growing US electric vehicle and grid technology sectors.
A shift from transactional spot-market sales to long-term supply agreements is altering procurement patterns. This change favors large, integrated processors who can guarantee consistent volume and quality to industrial consumers, disrupting the business model for smaller dealers. This trend is most prominent within the US automotive and electrical equipment industries, where securing a stable supply of critical raw materials is a top strategic priority.
US Copper Scrap Market Segmentation
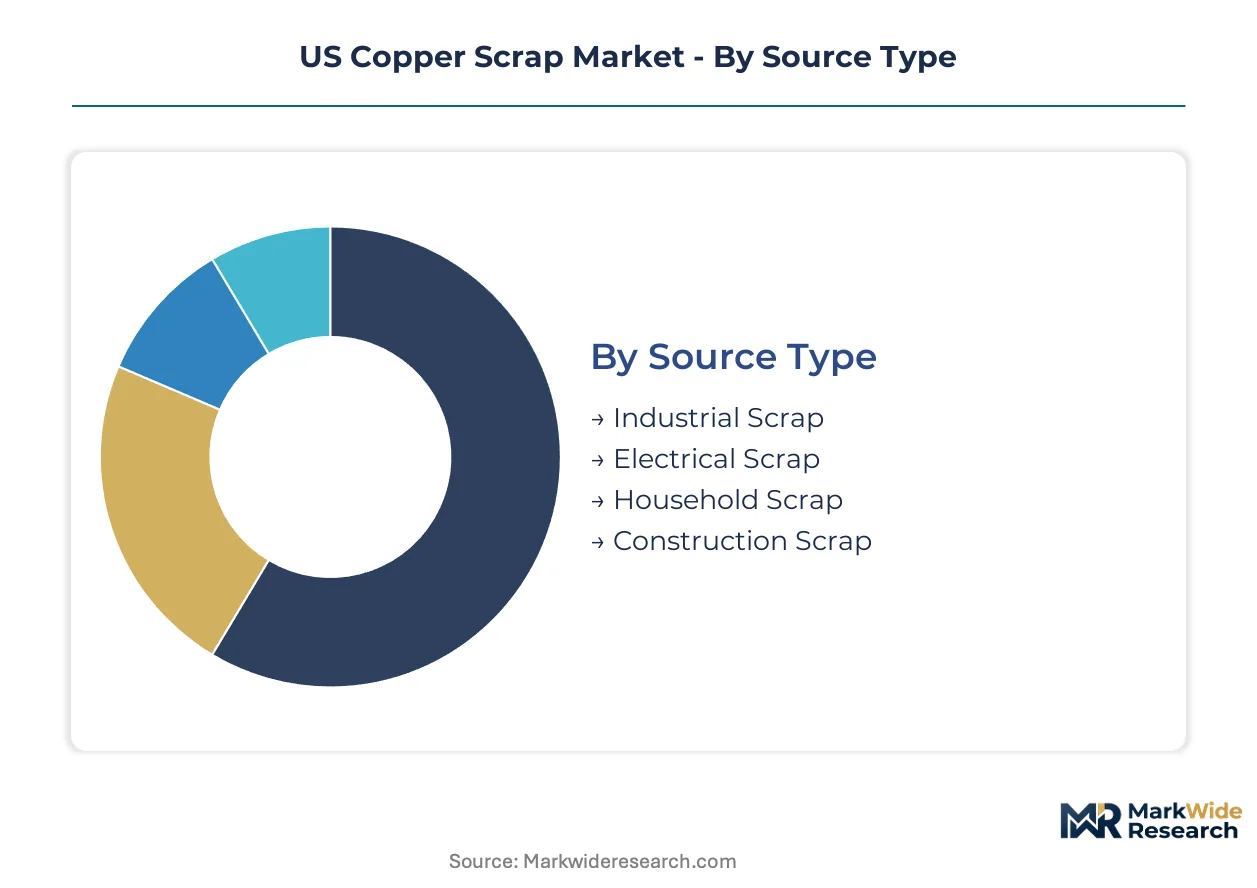
The US copper scrap market's structure is defined by how material is sourced, its quality, collection methods, and final destination. Understanding these segments helps processors and consumers optimize operations and procurement strategies. This segmentation highlights value creation points across the supply chain.
Source Type:
Buyers prioritize source type based on expected purity and processing requirements for their specific applications.
- Industrial Scrap:This material originates from manufacturing processes, often characterized by consistent composition and high purity. Demand concentrates in the industrial Midwest, where smelters require reliable feedstock for continuous production.
- Construction Scrap:Derived from demolition and renovation projects, this scrap includes wiring, pipes, and roofing materials. The US construction sector's sustained activity drives consistent demand for this volume-intensive category.
- Electrical Scrap:Consists of discarded electrical components and wiring, often varying in purity due to insulation and other materials.
- Household Scrap:Collected from residential sources, this category typically includes smaller volumes and mixed metallic content.
Industrial Scrap leads on scale; Construction Scrap leads on momentum.
Purity Grade:
Pricing and processing costs are directly influenced by the purity grade of copper scrap.
- Grade A:This category represents high-purity copper, including 'bare bright' wire with over 99% copper content. Manufacturers of high-conductivity products demand Grade A for direct remelting, minimizing refining steps.
- Dirty Scrap:Characterized by significant contamination from insulation, plastics, or other metals, requiring extensive sorting and processing. E-waste recycling mandates are expanding the collection of this material for upgrading.
- Grade B:Contains slightly lower copper content than Grade A, often with minor impurities or coatings requiring some processing.
- Low-Quality Scrap:Encompasses highly mixed or heavily contaminated materials, necessitating advanced sorting technologies for value recovery.
Grade A material commands premium pricing due to its high quality; Dirty Scrap represents the fastest-growing trajectory in terms of collection volume.
Collection Method:
The volume and efficiency of copper scrap recovery are largely determined by the collection method employed.
- Recycling Facilities:Large-scale operations equipped to process diverse scrap streams from industrial, commercial, and residential sources. The industrial Midwest benefits from these facilities, which consolidate material for regional smelters.
- Buyback Programs:These programs incentivize individuals and businesses to return scrap materials for cash, effectively increasing collection rates for smaller volumes. They play a significant role in diverting material from landfills.
- Curbside Collection:Residential programs where copper scrap is collected alongside other recyclables, typically yielding lower purity and smaller quantities.
- Drop-off Centers:Designated locations where the public can deposit scrap metal, providing a convenient option for intermittent generators.
Recycling Facilities capture the largest share of collected copper scrap; Buyback Programs enhance localized collection efficiency.
End User:
End-users determine their procurement strategy based on the specific application and desired metallurgical properties of the copper.
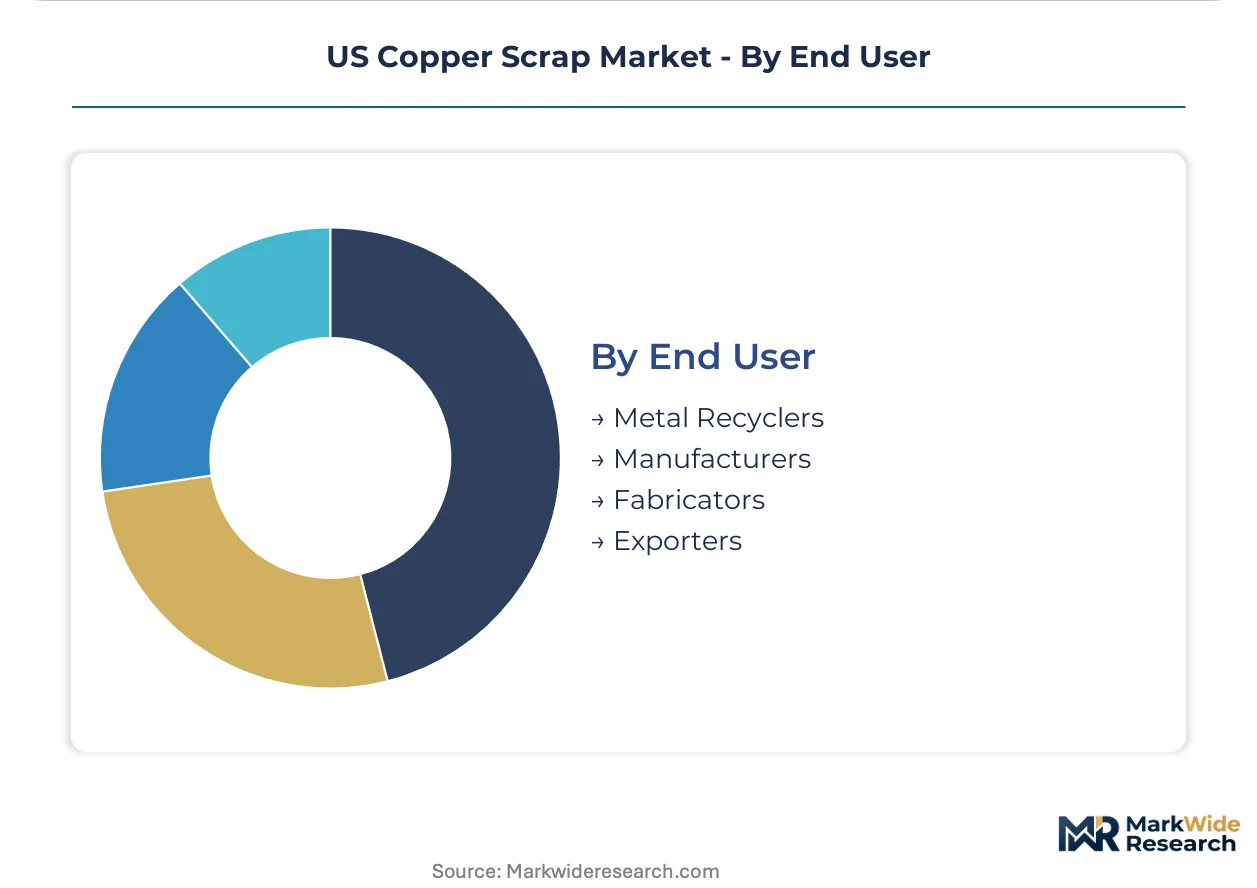
- Manufacturers:These industrial consumers utilize processed copper scrap as a primary feedstock for producing new copper products, such as wire, tubing, and sheets. Domestic sourcing incentives under the Inflation Reduction Act bolster this segment.
- Metal Recyclers:Companies that purchase, sort, process, and sell scrap metal to other end-users, acting as crucial intermediaries in the circular economy. They invest in advanced sorting technologies to meet purity demands.
- Fabricators:Businesses that transform copper ingots or sheets into finished or semi-finished products for various industries.
- Exporters:Entities that ship processed or unprocessed copper scrap to international markets, influenced by global commodity pricing.
Manufacturers hold strategic importance for domestic demand; Metal Recyclers exert significant influence over market supply dynamics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US copper scrap market is anchored by a skilled workforce and established infrastructure across key industrial regions. These areas demonstrate robust demand for recycled copper, driven by manufacturing needs and clean energy initiatives. State and federal policies further shape collection and processing activities within these vital economic hubs.
Industrial Midwest
Manufacturing activity, particularly in automotive and machinery sectors, drives consistent demand for industrial copper scrap in this region. The Inflation Reduction Act incentivizes domestic sourcing for components used in electric vehicles and grid modernization. Major processing and smelting operations in cities like Chicago and Detroit benefit from a concentrated supply base.
US Southeast
Rapid expansion of manufacturing, including new electric vehicle battery plants and associated infrastructure, fuels demand for copper feedstock. Federal incentives under the Inflation Reduction Act support the establishment of new recycling and processing hubs. States like Georgia and Tennessee are seeing significant investment in facilities that require reliable scrap supply.
California
Demand for copper scrap is sustained by construction projects and stringent e-waste recycling mandates across the state. California's strong environmental regulations, such as the Electronic Waste Recycling Act, expand the collection of lower-purity electrical scrap. Technology clusters in Silicon Valley and urban centers like Los Angeles generate substantial volumes of end-of-life electronics.
Northeast Corridor
Infrastructure upgrades and ongoing construction projects in densely populated areas create a steady requirement for copper wiring and plumbing scrap. Environmental Protection Agency (EPA) standards influence waste management practices and promote landfill diversion. Metropolitan areas such as New York and Philadelphia serve as significant collection points for construction and demolition materials.
US Copper Scrap Market Key Industry Players
Capital-intensive processing facilities compete with more agile collection and trading operations within the US copper scrap market. This market exhibits a tiered structure, ranging from large-scale integrated recyclers to specialized processors and regional collection networks. Dominant competitive moves include strategic partnerships to secure feedstock and continuous capacity expansion to meet demand.
Among the large, integrated players, Sims Metal Management exemplifies global processing capabilities for diverse scrap streams. Nucor Corporation represents integrated steel and metals production, leveraging extensive recycling networks to secure raw materials. Radius Recycling maintains a strong presence in construction and demolition scrap collection, supporting downstream manufacturing.
| Leading Market Players |
|---|
| Commercial Metals Company |
| Sims Metal Management |
| SA Recycling |
| OmniSource Corporation |
| Nucor Corporation |
| AIM Recycling |
| Radius Recycling |
| Metalico, Inc. |
| Aurubis AG |
Cost & Logistics Intelligence
Energy price volatility directly impacts processing costs for copper scrap, influencing pricing tiers from collection centers to industrial smelters. This cost component flows through the entire supply chain, affecting profitability at each stage.
Pricing Analysis
The market's pricing structure differentiates between bundled processing services and unbundled material sales. Commodity spot pricing dominates for lower-purity grades, while long-term contract-based offtake agreements secure high-purity 'bare bright' wire. Price differentiation stems from purity grade and certified material traceability. Pricing softness reflects global commodity market fluctuations, with manufacturers of high-conductivity products being least price-sensitive.
Supply Chain Analysis
Skilled labor scarcity in the US Industrial Midwest and Southeast impacts processing facility operational efficiency. The supply chain draws from diverse raw material dependencies, including industrial scrap, construction materials, and electrical waste streams. A structural risk is commodity price volatility for primary copper. Distribution runs through large-scale recycling facilities and metal recyclers to manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US copper scrap market acts as a regulatory compounder, with the Inflation Reduction Act driving significant domestic demand. This policy incentivizes localized supply chains for clean energy technologies, bolstering market growth.
For Market Incumbents: Acquire advanced sorting technologies to maintain purity specifications against increasing feedstock variability. Incumbents must invest in automation to counter skilled labor scarcity and reduce operational costs. This strategy defends against margin pressure from lower-cost processing alternatives and ensures consistent supply for manufacturers. Capacity expansion in the US Southeast can also leverage new manufacturing hubs.
For New Entrants and Emerging Players: Price-point gaps between premium Grade A material and lower-purity dirty scrap offer entry opportunities. New entrants can target the expanding collection of e-waste and construction scrap, which often requires advanced processing. A go-to-market angle involves offering specialized sorting services for complex scrap streams, partnering with existing collection networks. The most penetrable segment is upgrading lower-quality electrical scrap into furnace-ready material.
For Investors and Strategic Acquirers: Consolidation pressure builds where capital expenditure hurdles for advanced sorting equipment limit smaller operators. Long-term viability for the next 5-10 years favors integrated processors with extensive collection networks and processing capabilities. Acquire mid-sized firms with strong regional collection infrastructure or specialized sorting expertise. A key signal to watch is the rate of investment in new US-based clean energy manufacturing facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases processing volume to meet growing domestic demand for recycled copper. |
| Advanced Sorting Technology Investment | Upgrades lower-purity scrap into high-value material, meeting stringent manufacturer specifications. |
| Long-term Supply Agreements | Secures consistent feedstock for industrial consumers, stabilizing procurement patterns. |
| Regional Processing Hub Development | Establishes new collection and processing infrastructure in underserved manufacturing regions. |
| Skilled Workforce Development Programs | Addresses labor scarcity challenges, ensuring efficient operation of advanced metallurgical equipment. |
Research Approach
Coverage spans the US Industrial Midwest, Southeast, California, and Northeast Corridor, with primary inputs from each region. This involved combining in-depth interviews with industry stakeholders and rigorous secondary validation. Primary insights were gathered from recycling facility managers, scrap traders, manufacturing procurement leads, and environmental compliance officers. Secondary data, including EPA regulations and US Department of Commerce trade statistics, informed a triangulated analysis.
Granularity of modeling focused on source type, purity grade, collection method, and end-user segments at a state level. The analytical framework projected market growth across the analysis window, integrating historical data with future demand drivers. Compound annual growth rates were derived from a multi-factor regression model. Key forecast inputs included construction sector activity and clean energy investment trends.
Caveats apply where significant shifts in global commodity prices or US industrial policy could materially alter the outlook. Forecasts reflect assumptions regarding sustained construction activity and IRA implementation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Battery Metals Market
Metals
Lithium Foil Market
Metals
Amorphous Metal Cores Market
Metals
Global Precious Metal Market
Metals
Ore Metals Market
Metals
Welding Materials Market
Metals
316 Stainless Steel Container Market
Metals
Anodized Titanium Market
Metals
Aluminum Hot Rolling Mill Market
Metals
India Metal Fabrication Market
Metals
Steel Ingots Market
Metals
GCC Aluminium Cans Market
Metals
Global Stainless Steel Lashing Wire Market
Metals
Base Metals Market
Metals
Cerium Market
Metals
Steel Drums and Ibcs Market