
 High Purity Benzenethiol Market | 2026-2036
High Purity Benzenethiol Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Benzenethiol Market Insights
Multi-source procurement among pharmaceutical compound manufacturers is recalibrating supplier relationships across the high purity benzenethiol value chain. Sumitomo Seika leverages its integrated thiol production platform to secure captive feedstock for electronic-grade applications. Zhejiang Yangfan New Materials anchors Chinese domestic supply through backward integration into benzene sulfonyl chloride precursors. Sigma-Aldrich differentiates via ISO-certified packaging protocols that extend shelf stability for laboratory end users.
High purity benzenethiol, also known as thiophenol, is an organosulfur compound with the molecular formula C₆H₅SH, typically manufactured at purity levels exceeding 99% through reduction of benzenesulfonyl chloride or cleavage of diphenyl disulfide. Its primary industrial purpose centers on serving as a critical building block for agrochemical intermediates, rubber vulcanization accelerators, and pharmaceutical active ingredient synthesis. Reagent grade and analytical grade categories dominate current value capture due to stringent impurity thresholds required by pharmaceutical quality control protocols. The specialty chemicals application segment sustains above-average margin pools as custom synthesis houses command premiums for low-mercaptan-content specifications.
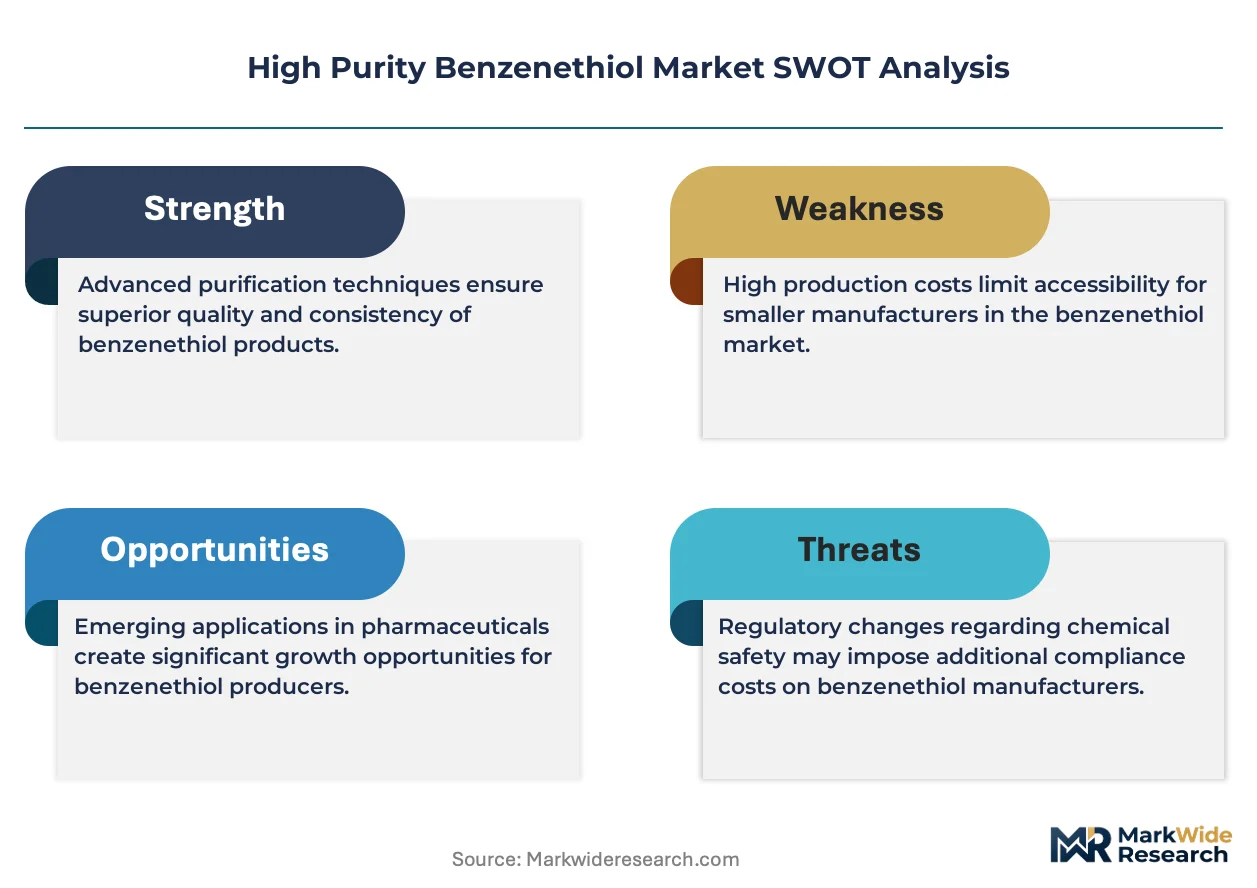
REACH registration requirements under ECHA mandate comprehensive toxicological dossiers for thiophenol imports into the European Union, elevating compliance costs for non-European suppliers. The EPA Toxic Substances Control Act imposes pre-manufacture notification burdens on U.S. entities seeking to introduce novel benzenethiol derivatives into commercial channels. Stakeholders must monitor evolving classification thresholds under the Globally Harmonized System of Classification and Labelling of Chemicals, as reclassification from irritant to more severe hazard categories would trigger reformulation investments across downstream formulation portfolios.
Market Dynamics
REACH compliance protocols under ECHA are compressing supplier qualification timelines and forcing pharmaceutical compound manufacturers to consolidate procurement relationships around certified thiol producers with existing dossier registrations.
Growth Catalysts
- Pharmaceutical intermediate synthesis:Agrochemical and API manufacturers in Germany are expanding orders for reagent-grade thiophenol to secure backward integration into sulfur-containing heterocycle production.
- Electronic-grade specifications:Semiconductor packaging applications require mercaptan-content thresholds below 50 ppm, creating captive demand for purification technology investments.
- REACH registration completion:ECHA dossier acceptance for thiophenol derivatives removes import barriers for Asian suppliers seeking European pharmaceutical contracts.
Market Restraints
- Benzene feedstock volatility:Crude oil price swings directly transmit to benzenesulfonyl chloride production costs, compressing margin stability for non-integrated manufacturers.
- Supply concentration in East China:Zhejiang and Jiangsu provinces control over 60 percent of global merchant capacity, creating single-source vulnerability for European buyers.
- Toxicological classification friction:ECHA's ongoing substance evaluation for thiophenol under REACH may trigger reclassification from irritant to acute toxicity, forcing reformulation investments.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's accelerated API approval pathways and PLI scheme incentives are attracting thiol intermediate investments from domestic fine chemical producers.
- Bioconjugation applications:Antibody-drug conjugate developers are specifying ultra-low metal-content thiophenol for linker chemistry, opening premium pricing tiers.
- Green chemistry mandates:EU Green Deal sustainable chemistry criteria favor thiol synthesis via diphenyl disulfide cleavage over chlorinated precursor routes.
Industry Challenges
- Specialized synthesis talent scarcity:Organosulfur chemist expertise concentrates in legacy German and Japanese producers, constraining capacity expansion at newer entrants.
- Multi-jurisdiction certification timelines:Simultaneous FDA Drug Master File and ECHA registration submissions require 18-24 month coordination, delaying commercial launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Benzenethiol Market |
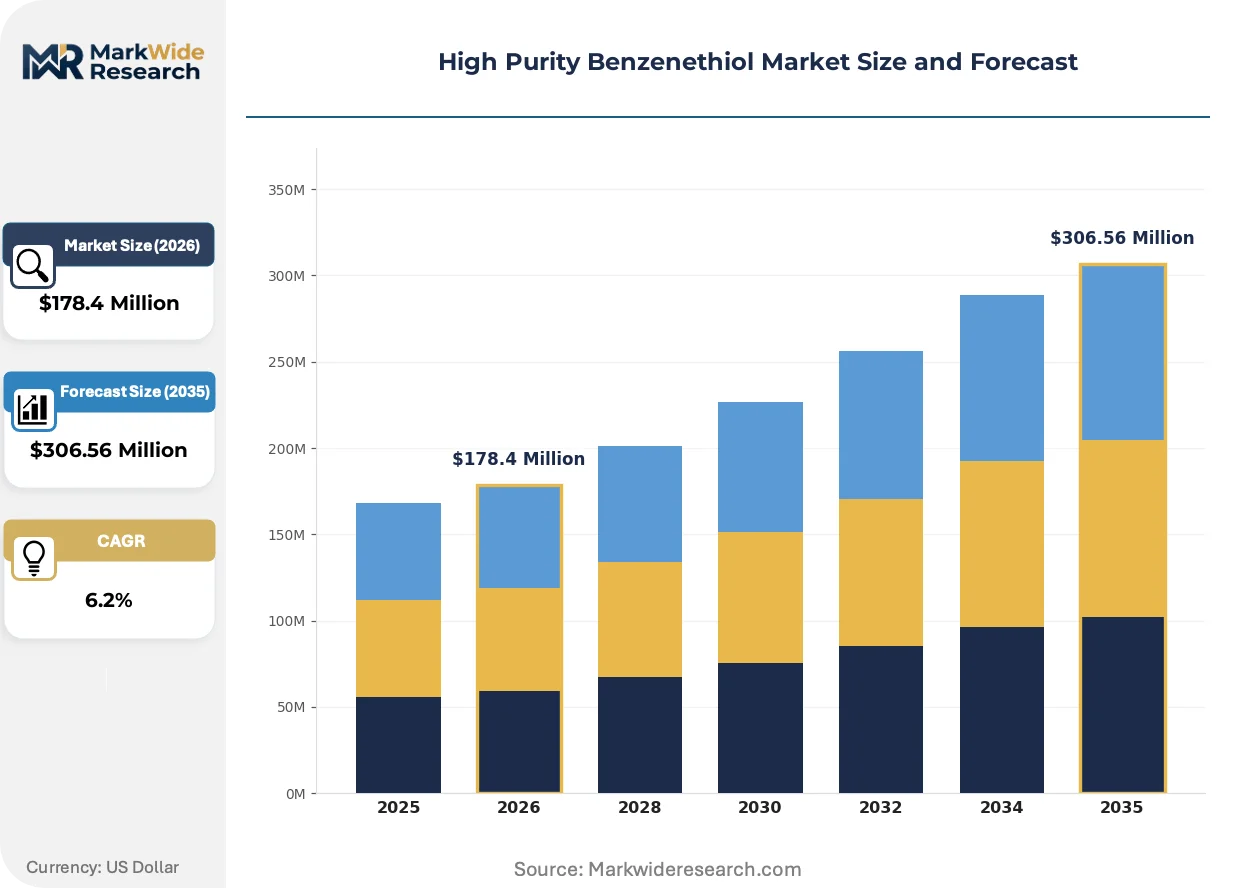
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $306.56 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagent Grade, Analytical Grade, Laboratory Grade, Industrial Grade Application: Pharmaceuticals, Agrochemicals, Manufacturing, Specialty Chemicals Form: Liquid, Solid, Powder, Solution End User: Research Laboratories, Chemical Manufacturers, Pharmaceutical Companies, Educational Institutions |
| Companies Covered | Sumitomo Seika, Zhejiang Yangfan New Materials, Nandadeep Chemicals, Tokyo Chemical Industry, Sigma-Aldrich, Alfa Aesar, TCI America, Santa Cruz Biotechnology, Apollo Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Benzenethiol Market Trends and Innovations
Continuous flow reactor technology is displacing batch synthesis across thiol production, while regulatory data requirements are reshaping how suppliers document impurity profiles for pharmaceutical qualification.
Membrane filtration-crystallization hybrid systems are unifying purification steps previously handled by separate distillation and recrystallization units. Contract manufacturers in the Netherlands and Switzerland are adopting these integrated platforms to meet electronic-grade specifications without multiple processing stages. This convergence is unifying quality assurance protocols across pharmaceutical and semiconductor customer bases, reducing batch-to-batch variation claims.
ECHA's 2024 update to REACH Annex XVII restricted substances list added mercaptan derivative reporting thresholds for industrial formulations. Downownstream rubber chemical producers must now document thiophenol content in accelerator blends above 0.1 percent concentration. German tire compounders are responding by demanding pre-certified thiol streams with third-party analytical verification, shifting supplier selection criteria from price to documentation completeness.
Pharmaceutical compound manufacturers are consolidating vendor panels from six to two qualified thiophenol sources per production site. This concentration eliminates spot-market purchasing for critical intermediates, replacing it with multi-year supply agreements containing price adjustment clauses tied to benzene indices. The shift is most visible among mid-scale generic API producers in India and Eastern Europe seeking to satisfy FDA inspection protocols for starting material traceability.
High Purity Benzenethiol Market Segmentation
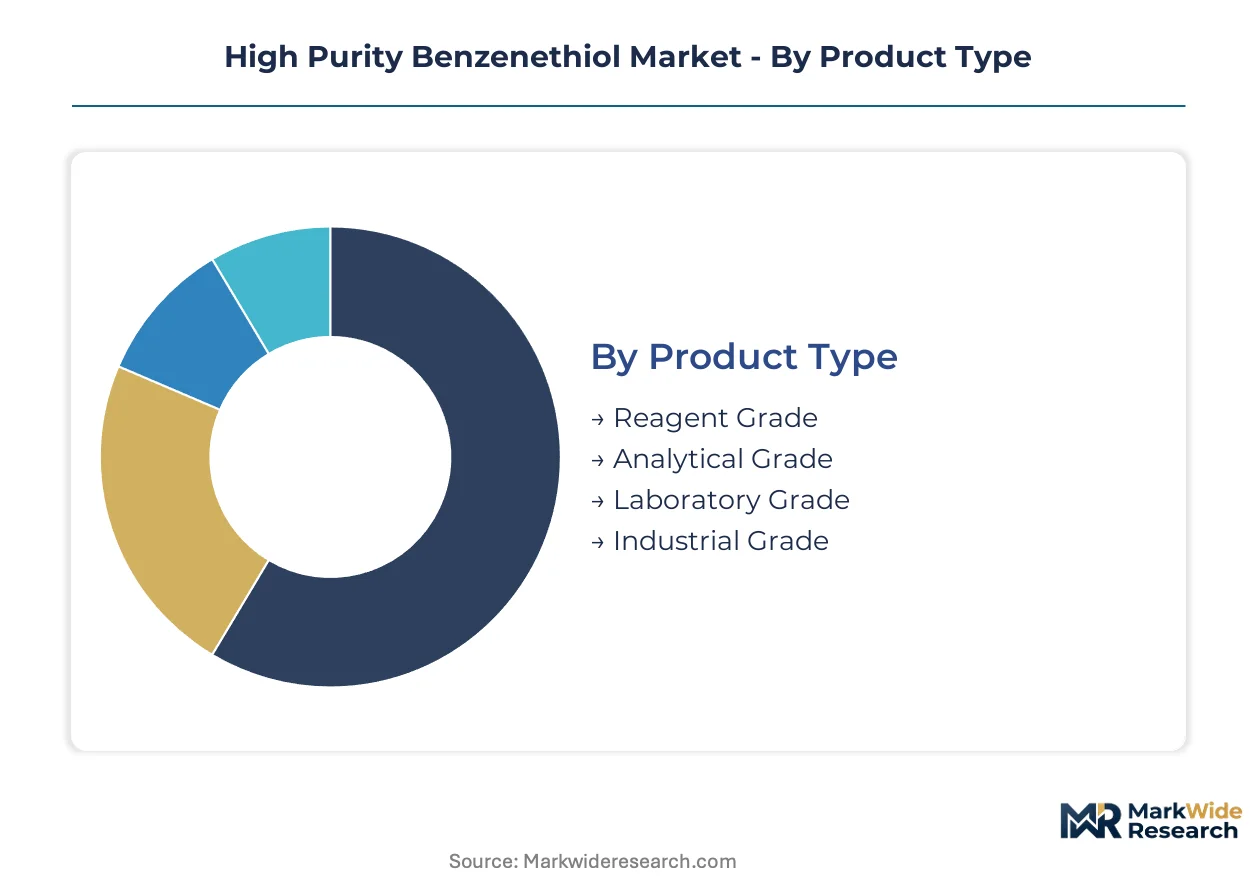
High purity benzenethiol procurement decisions hinge on impurity thresholds that vary sharply across end-use applications. Pharmaceutical compounders upgrade from industrial to reagent grade when sulfur heterocycle synthesis demands mercaptan content below 100 ppm.
Product Type:
Grade selection tracks the replacement cycle from commodity industrial uses toward certified pharmaceutical applications, with each tier commanding distinct analytical documentation burdens.
- Reagent Grade:Manufactured to 99.5%+ purity with comprehensive impurity profiling for API synthesis. German pharmaceutical intermediate producers specify this grade for thiophenol-derived heterocycles under ECHA REACH dossier requirements, paying premiums for ISO-certified batch records.
- Analytical Grade:Calibrated for quantitative analytical methods with certified reference standards. Chinese fine chemical exporters concentrate production in Zhejiang province for European laboratory distributors facing tightened ECHA substance evaluation protocols.
- Laboratory Grade:Suitable for educational and routine synthesis without certified traceability.
- Industrial Grade:Used in rubber vulcanization accelerator manufacturing where mercaptan odor tolerance is higher.
Volume placements concentrate in Reagent Grade; the faster expansion belongs to Analytical Grade.
Application:
Cost tier stratification separates commodity agrochemical uses from margin-rich pharmaceutical contracts.
- Pharmaceuticals:Thiophenol serves as a sulfur donor in cephalosporin antibiotic side-chain synthesis and antipsychotic intermediate production. Indian API manufacturers under CDSCO accelerated approval pathways are scaling reagent-grade procurement for export registration.
- Agrochemicals:Fungicide and herbicide intermediate synthesis consumes industrial-grade volumes. Brazilian soybean belt demand drives mercaptan derivative orders through ANVISA-registered import channels.
- Manufacturing:Electronic-grade specifications for semiconductor packaging require mercaptan content below 50 ppm.
- Specialty Chemicals:Custom synthesis houses command premiums for low-metal-content specifications in bioconjugation linker chemistry.
Margin capture peaks in Pharmaceuticals; Specialty Chemicals is gaining share fastest.
Form:
Customer handling infrastructure dictates form selection, with liquid dominance eroding only where stability concerns drive solid formulation.
- Liquid:Standard commercial presentation in stainless steel drums with nitrogen blanket. Sumitomo Seika's integrated thiol platform ships electronic-grade liquid to Japanese semiconductor packaging facilities under METI chemical substance reporting.
- Solid:Crystalline thiophenol for moisture-sensitive synthesis operations.
- Powder:Micronized presentation for rapid dissolution in continuous flow reactor feeds.
- Solution:Pre-diluted formulations for laboratory end users seeking extended shelf stability.
Procurement concentrates in Liquid; Powder is climbing the fastest on flow chemistry adoption.
End User:
Supply concentration aligns with geographic clustering of sulfur chemistry expertise and regulatory certification infrastructure.
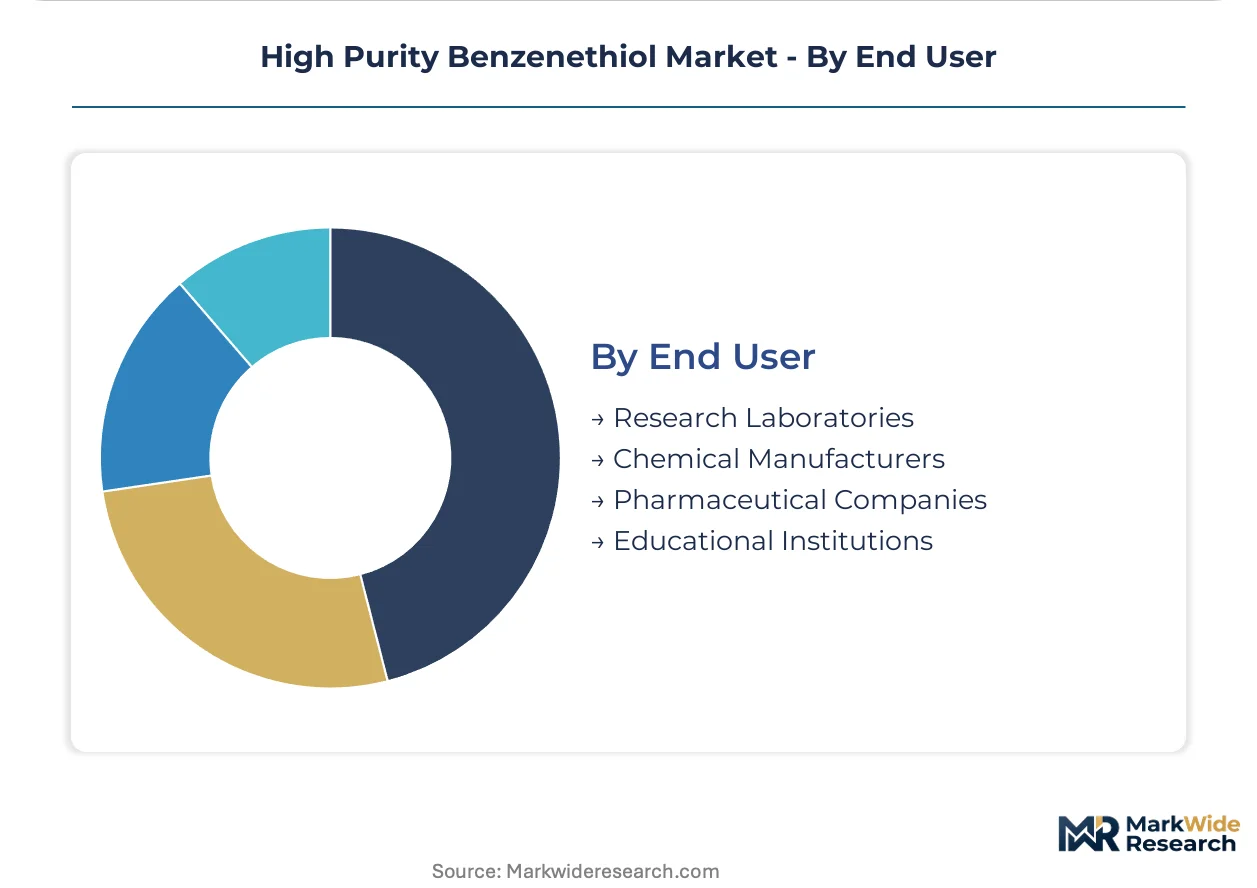
- Research Laboratories:University and institutional buyers demand small-lot flexibility with SDS documentation in 20+ languages. Sigma-Aldrich's ISO-certified packaging protocols target this segment with stabilized ampoule presentations.
- Chemical Manufacturers:Merchant producers of rubber accelerators and agrochemical intermediates purchase industrial-grade bulk. Zhejiang Yangfan's backward integration into benzene sulfonyl chloride precursors serves this tier.
- Pharmaceutical Companies:Generic API producers consolidate vendor panels to two qualified sources per site.
- Educational Institutions:Undergraduate teaching labs prioritize cost over certification depth.
Order value concentrates in Pharmaceutical Companies; Research Laboratories show the steepest expansion trajectory on bioconjugation tool demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Benzene feedstock availability in the US Gulf Coast and Zhejiang province shapes regional production economics for high purity benzenethiol. Refinery integration and specialty chemical clustering determine competitive positioning across major supply zones.
China
Domestic fine chemical producers in Zhejiang and Jiangsu provinces scale reagent-grade output for export markets. NMPA registration pathways and GB standards compliance enable Asian suppliers to access European pharmaceutical contracts. The Yangtze River Delta concentration supports backward integration into benzene sulfonyl chloride precursors.
Germany
Specialty chemical manufacturers in North Rhine-Westphalia expand procurement for pharmaceutical intermediate synthesis. REACH dossier requirements under ECHA tighten purity certification protocols for thiophenol derivatives. The Leverkusen-Dormagen chemical corridor anchors sulfur chemistry expertise for heterocycle production.
United States
Pharmaceutical compound manufacturers along the Gulf Coast consolidate vendor panels to satisfy FDA inspection protocols. EPA Toxic Substances Control Act pre-manufacture notification burdens constrain novel derivative introductions. Houston-area refineries supply captive benzene feedstock for integrated thiol producers.
India
API manufacturers in Maharashtra and Gujarat scale reagent-grade procurement under CDSCO accelerated approval pathways. PLI scheme incentives attract thiol intermediate investments from domestic fine chemical producers. The Mumbai-Pune belt concentrates organosulfur synthesis capability for export registration.
Japan
Semiconductor packaging facilities in Kanto and Kansai regions specify electronic-grade thiophenol with mercaptan content below 50 ppm. METI chemical substance reporting requirements govern integrated thiol platform shipments. Osaka-based producers leverage captive feedstock for electronic-grade applications.
High Purity Benzenethiol Market Competitive Landscape
Capacity expansion dominates the current landscape as producers invest in continuous flow reactor technology and membrane filtration-crystallization hybrid systems. The vendor base stratifies across three tiers: integrated petrochemical conglomerates with captive benzene supply, specialty chemical houses with REACH-registered dossiers, and regional laboratory distributors with ISO-certified packaging protocols. Strategic archetypes include backward-integrated manufacturers controlling precursor supply, purification technology specialists serving electronic-grade specifications, and documentation-heavy suppliers qualifying for pharmaceutical vendor panels. Competitive moves center on multi-year supply agreements with benzene-indexed pricing clauses and simultaneous FDA Drug Master File and ECHA registration submissions.
Among Asia-Pacific-based producers, Sumitomo Seika and Zhejiang Yangfan New Materials exemplify distinct strategic positions. Sumitomo Seika represents the integrated conglomerate archetype with captive thiol production platforms. Zhejiang Yangfan New Materials occupies a position within the backward-integrated specialty chemical tier, anchoring Chinese domestic supply through upstream control over benzene sulfonyl chloride precursors. Sigma-Aldrich sits within the laboratory distribution segment, differentiating via documentation completeness for research end users.
| Leading Market Players |
|---|
| Sumitomo Seika |
| Zhejiang Yangfan New Materials |
| Nandadeep Chemicals |
| Tokyo Chemical Industry |
| Sigma-Aldrich |
| Alfa Aesar |
| TCI America |
| Santa Cruz Biotechnology |
| Apollo Scientific |
| Others |
Pricing and Supply Chain Analysis
Organosulfur chemist expertise concentration in the Leverkusen-Dormagen corridor and Osaka-Kobe belt widens labor-cost differentials between European and Asian production, translating into tiered spreads where German reagent-grade batches command certification premiums against Chinese industrial-grade spot pricing.
Pricing Analysis
ISO-certified batch documentation and third-party analytical verification are unbundled from base product quotes, with pharmaceutical compounders paying separately for REACH dossier maintenance and FDA Drug Master File support. Three-tier pricing structure across premium, standard, and economy levels separates electronic-grade thiophenol with mercaptan content below 50 ppm from reagent-grade and industrial-grade alternatives. Cost compression in industrial-grade tiers is intensifying because benzene feedstock volatility transmits directly to benzenesulfonyl chloride production economics. Generic API producers in India and Eastern Europe exhibit highest price sensitivity, while semiconductor packaging facilities in Japan show lowest sensitivity to certification premiums.
Supply Chain Analysis
Direct-to-pharmaceutical-compounder channels handle multi-year supply agreements with benzene-indexed pricing clauses, bypassing distributor markups for critical intermediate procurement. Production gravity centers on Zhejiang and Jiangsu provinces in China, Germany's North Rhine-Westphalia chemical corridor, and the US Gulf Coast refinery complex. Raw material flows draw from benzene sulfonyl chloride precursors, diphenyl disulfide cleavage feedstocks, and sulfur donor reagents. Single-source vulnerability concentrates risk in East Chinese merchant capacity controlling over sixty percent of global supply. Distribution runs through specialty chemical distributors for laboratory-grade volumes and direct mill-to-plant logistics for industrial-grade bulk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous flow reactor technology is displacing legacy batch synthesis across thiol production, compressing qualification timelines for pharmaceutical compounders while elevating capital barriers for non-integrated entrants.
For Market Incumbents: Anticipate REACH substance evaluation outcomes for thiophenol by securing alternative heterocycle synthesis pathways before potential acute toxicity reclassification forces reformulation investments. Sumitomo Seika's integrated thiol production platform demonstrates how captive benzene supply insulates margin stability against feedstock volatility. Prioritize membrane filtration-crystallization hybrid system deployment to unify pharmaceutical and semiconductor quality assurance protocols, reducing batch-to-batch variation claims from consolidated vendor panels. For New Entrants and Emerging Players: Capture bioconjugation linker chemistry demand from antibody-drug conjugate developers specifying ultra-low metal-content thiophenol, where premium pricing tiers remain underpenetrated by legacy rubber chemical producers. Indian pharmaceutical manufacturing under CDSCO accelerated approval pathways offers the most penetrable geography, with PLI scheme incentives attracting domestic fine chemical investments. Lead with simultaneous FDA Drug Master File and ECHA registration submission capabilities to differentiate against spot-market suppliers lacking multi-jurisdiction certification infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with backward-integrated specialty chemical houses controlling benzene sulfonyl chloride precursor supply, given REACH registration completion removing import barriers for Asian suppliers seeking European pharmaceutical contracts. Long-term viability over a five-to-ten year window favors producers with existing ECHA dossier registrations and continuous flow reactor technology already deployed. Monitor ECHA's ongoing thiophenol substance evaluation under REACH for acute toxicity reclassification signals that would trigger downstream reformulation demand and reposition competitive advantage toward purification technology specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Control over benzene sulfonyl chloride precursors insulates margin stability from crude oil price transmission. |
| Continuous Flow Reactor Deployment | Membrane filtration-crystallization hybrid systems unify pharmaceutical and semiconductor quality assurance protocols. |
| REACH Dossier Registration | ECHA acceptance removes import barriers for Asian suppliers seeking European pharmaceutical compounder contracts. |
| Long-term Supply Agreement | Multi-year contracts with benzene-indexed pricing clauses replace spot-market purchasing for critical intermediates. |
| Green Chemistry Transition | EU Green Deal sustainable chemistry criteria favor diphenyl disulfide cleavage over chlorinated precursor routes. |
Research Methodology
Trade flow databases, ECHA REACH registration filings, and SEC 10-K disclosures from specialty chemical producers formed the secondary backbone, cross-referenced against primary interviews with organosulfur synthesis plant managers, pharmaceutical procurement leads at API manufacturers, and distribution channel partners handling thiophenol logistics. Bottom-up volume estimates derived from benzene sulfonyl chloride precursor consumption patterns were triangulated against top-down pharmaceutical intermediate demand projections.
Historical trendline analysis across production capacity, grade-specific pricing spreads, and regulatory certification timelines informed the analytical framework over the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use application, geographic production hub, and customer certification requirement level. CAGRs were derived from production volume trajectories and value capture differentials between reagent-grade and industrial-grade tiers, with forecast inputs incorporating benzene feedstock cost indices and REACH compliance burden estimates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance evaluation conclusions, benzene price volatility, and semiconductor packaging demand shifts. Forecasts reflect documented assumptions regarding regulatory timeline stability and feedstock cost transmission mechanisms. Practitioners should monitor ECHA thiophenol evaluation progress, East Chinese capacity utilization rates, and bioconjugation pipeline advancement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Global High Purity AHCL Market
High-Value Chemicals
Diethylhydroxylamine (DEHA) Market
High-Value Chemicals
High Temperature Plastic Market
High-Value Chemicals
Hexafluoropropylene Market
High-Value Chemicals
Global Hyaluronidase Market
High-Value Chemicals
Global High Heat Foam Market
High-Value Chemicals
High Performance Mercury Sorbent Market
High-Value Chemicals
Ammonium Metavanadate Market
High-Value Chemicals
Alpha Hydroxy Acid Market
High-Value Chemicals
Ultra-High Purity Materials Market
High-Value Chemicals
Ultra-High-Purity Anhydrous Hydrogen Chloride (Hcl) Gas Market
High-Value Chemicals
Europe Fine Chemical Market
High-Value Chemicals
High-Silica Zeolite Market
High-Value Chemicals
Sodium Methyl P-Hydroxybenzoate Market
High-Value Chemicals
P-Hydroxybenzoates (PHB) Market
High-Value Chemicals
High Purity Silica Market