
 Global Stainless Steel Lashing Wire Market | 2026-2036
Global Stainless Steel Lashing Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stainless Steel Lashing Wire Market Outlook
China's Yangtze River Delta is rewriting capacity dynamics for stainless steel wire production, with new cold-drawing facilities coming online to serve Asian marine and telecom markets. Loos & Co. leverages decades of aerospace wire expertise to anchor premium lashing wire segments in North American infrastructure. Nevatia Steel competes on cost-optimized 300-series formulations for construction bundling applications across South Asian project sites. Acerinox S.A. controls integrated melt-to-wire output from its European mills, sustaining margin capture through captive stainless supply.
Stainless steel lashing wire denotes cold-drawn austenitic or ferritic wire, typically 0.5 mm to 4.0 mm in diameter, engineered with minimum 10.5% chromium content to resist oxidation and mechanical fatigue under tension loadings. Its primary function secures cable bundles, piping runs, and structural elements across marine decks, telecom towers, and concrete reinforcement frames where corrosion exposure would degrade carbon steel alternatives. Single strand configurations dominate volume in telecommunications guy-wire anchoring due to straightforward tensioning and lower per-meter cost, while braided constructions command margin premiums in offshore oil platform lashing where multi-axis flexibility prevents stress fractures. Marine applications are outpacing construction in growth velocity as classification societies tighten lifeline and rigging replacement cycles.
ISO 1788 sets dimensional tolerances for stainless wire rope and lashing products, while China's GB/T 9944 governs domestic corrosion testing protocols that exporters must satisfy for market access. The EU's REACH framework restricts hexavalent chromium surface treatments, forcing reformulation of passivation layers across Asian supply chains shipping into European ports. Japan's METI maintains JIS G 4309 standards that differentiate precision-drawn wire from general construction grades, creating a technical barrier for uncertified producers. Stakeholders must monitor evolving nickel alloy surcharges and regional carbon border adjustments that will reshape sourcing economics between integrated mills and distributed wire drawers.
Market Dynamics
Offshore wind developers in the North Sea are compressing replacement cycles for corrosion-resistant rigging, forcing wire producers to recertify products under accelerated salt-spray protocols that exceed baseline ISO 1788 requirements.
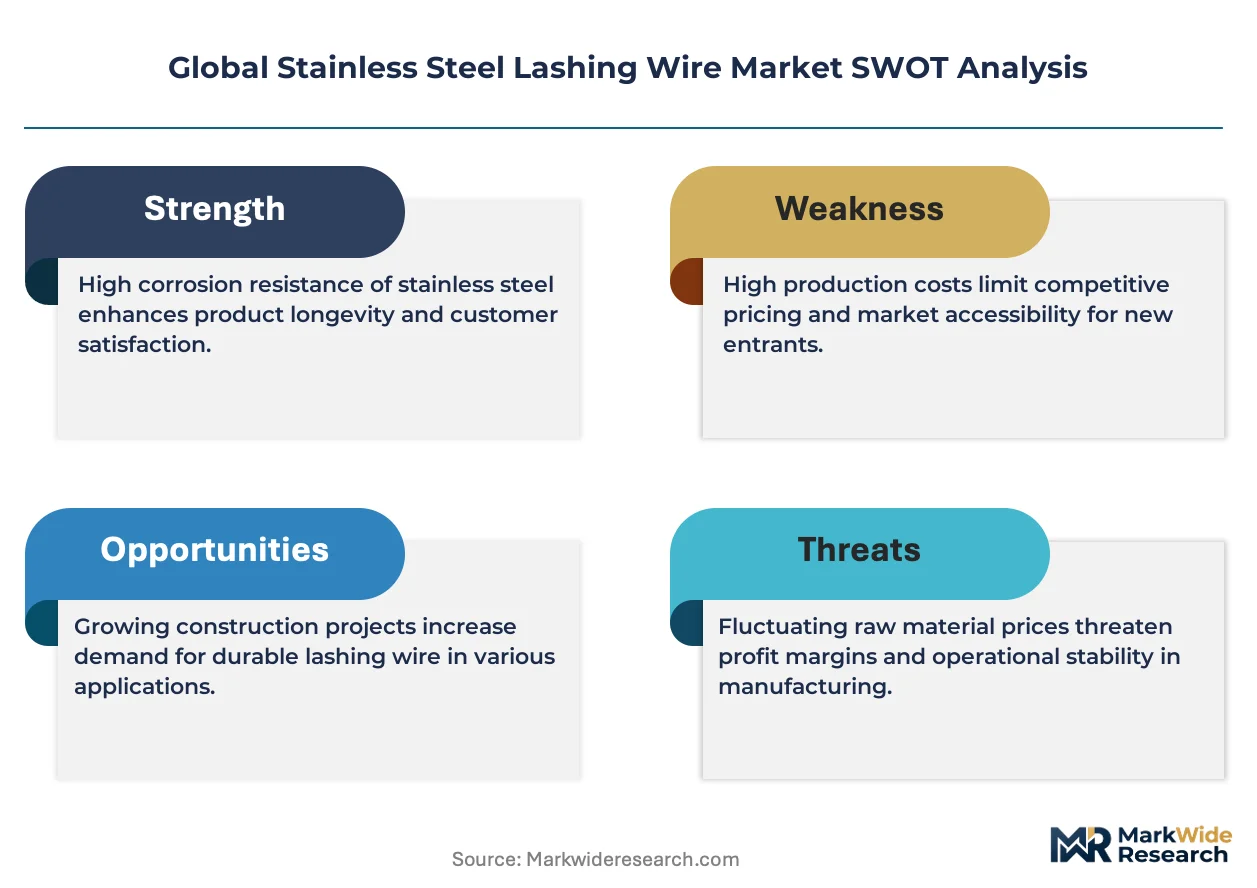
Growth Catalysts
- Marine-grade specification tightening:Classification societies now mandate 316L stainless for subsea cable lashing, eliminating 304-series alternatives from North Sea tender qualifications.
- China's dual carbon goals:MIIT subsidies for low-carbon cold-drawing facilities are expanding melt-shop capacity in Jiangsu province to serve Asian shipbuilding clusters.
- REACH Article 33 disclosure:ECHA enforcement of substance-of-very-high-concern reporting is filtering non-compliant Asian exporters from European marine procurement lists.
Market Restraints
- Nickel alloy surcharge volatility:LME nickel price swings above USD 25,000/tonne directly compress cold-drawn wire margins, forcing spot-indexed pricing that deters long-term supply agreements.
- European melt-shop concentration:Acerinox and Aperdominate EU 300-series slab supply, creating captive feedstock bottlenecks for independent wire drawers without backward integration.
- High-performance polymer substitution:aramid fiber lashing in telecom guy-wire applications displaces stainless below 2.0 mm diameter where tensile requirements permit.
Strategic Opportunities
- Vietnam coastal manufacturing:Underdeveloped stainless wire capacity near Haiphong port offers first-mover positioning for marine lashing serving ASEAN ship repair yards.
- EU Carbon Border Adjustment Mechanism:CBAM phase-in from 2026 creates tariff advantages for European melt-to-wire producers against Chinese imports with embedded coal-power emissions.
- Digital twin integration:Convergence of RFID-tagged wire batches with predictive maintenance platforms enables outcome-based tension-monitoring contracts for offshore platform operators.
Industry Challenges
- Precision-drawn technician scarcity:Cold-drawing expertise for sub-1.0 mm aerospace-grade tolerance is concentrating among retiring European and Japanese workforces without pipeline replacement.
- Multi-standard certification lag:Simultaneous compliance with JIS G 4309, GB/T 9944, and EN 10264-4 extends product qualification timelines to 18-24 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stainless Steel Lashing Wire Market |
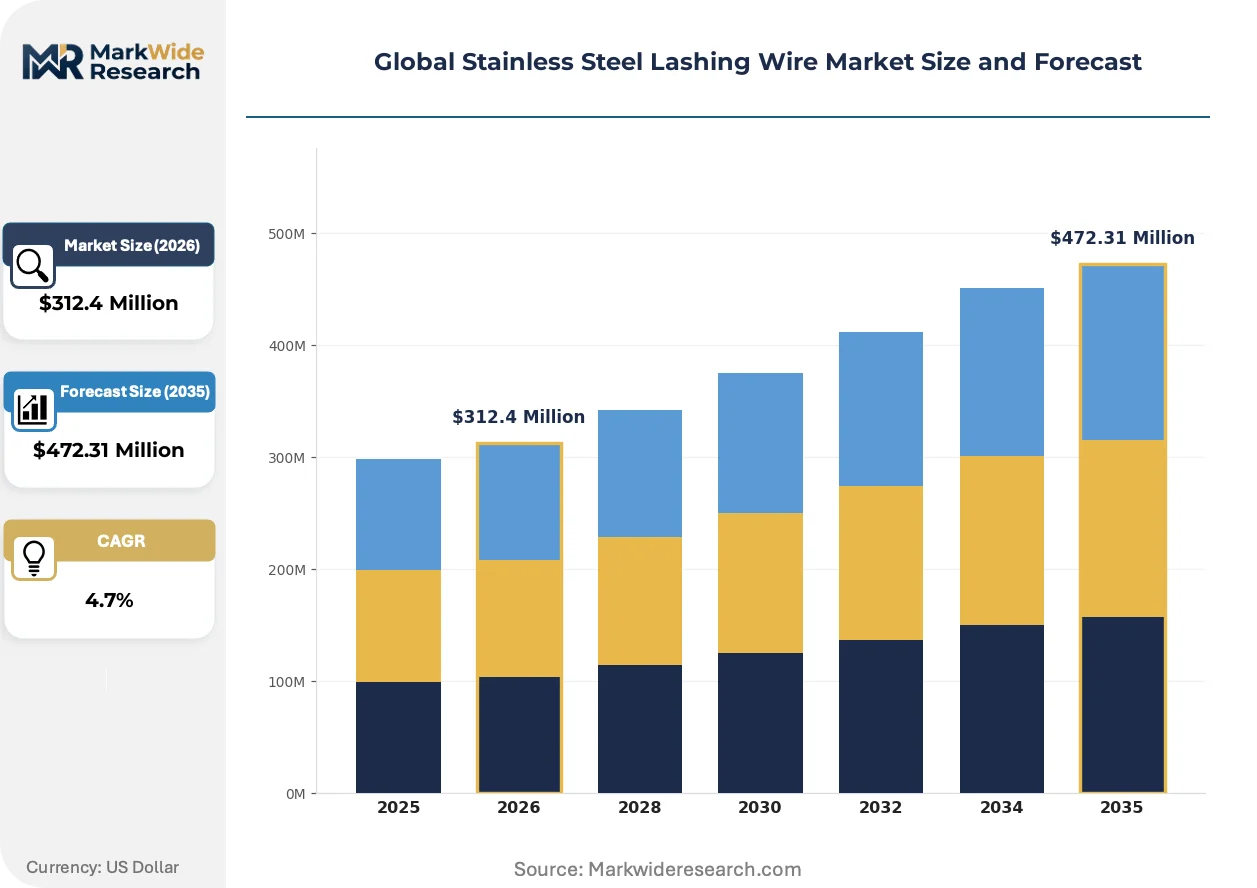
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Strand, Double Strand, Multi-Strand, Braided Application: Construction, Marine, Telecommunications, Automotive Diameter: 1 mm, 2 mm, 3 mm, 4 mm End User: Contractors, Manufacturers, Wholesalers, Retailers |
| Companies Covered | Loos & Co., Power Manufacturing, Phoenix Utility Products Corporation, CWI-America, Nevatia Steel, Wire World, Multicom Inc., Anand Arc Ltd., Acerinox S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stainless Steel Lashing Wire Market Strategic Shifts
Material science advances and regulatory disclosure mandates are restructuring how stainless lashing wire is specified, traced, and procured across marine and infrastructure verticals.
Plasma-enhanced chemical vapor deposition of chromium nitride surface coatings is extending salt-spray resistance beyond 3,000 hours for 316L substrates. Offshore wind EPC contractors in the North Sea are specifying these treatments for monopile cable management systems. This performance tier is virtualizing the traditional tradeoff between austenitic corrosion resistance and ferritic cost economics.
REACH Annex XIV authorization requirements for hexavalent chromium passivation are forcing reformulation of surface treatments across Asian export supply chains. Wire producers in Zhejiang and Guangdong provinces are shifting to trivalent chromium and cerium-based alternatives. European marine distributors are demanding third-party ECHA compliance documentation before contract execution.
Telecom tower operators are unbundling wire supply from turnkey installation contracts, creating direct procurement relationships with certified wire drawers. This disintermediation bypasses traditional rigging-house markups in North American and Australian markets. Towercos now specify lot-traceable 302HQ wire with mill-test certificates for guy-anchor systems above 50-meter hub heights.
Global Stainless Steel Lashing Wire Market Segmentation
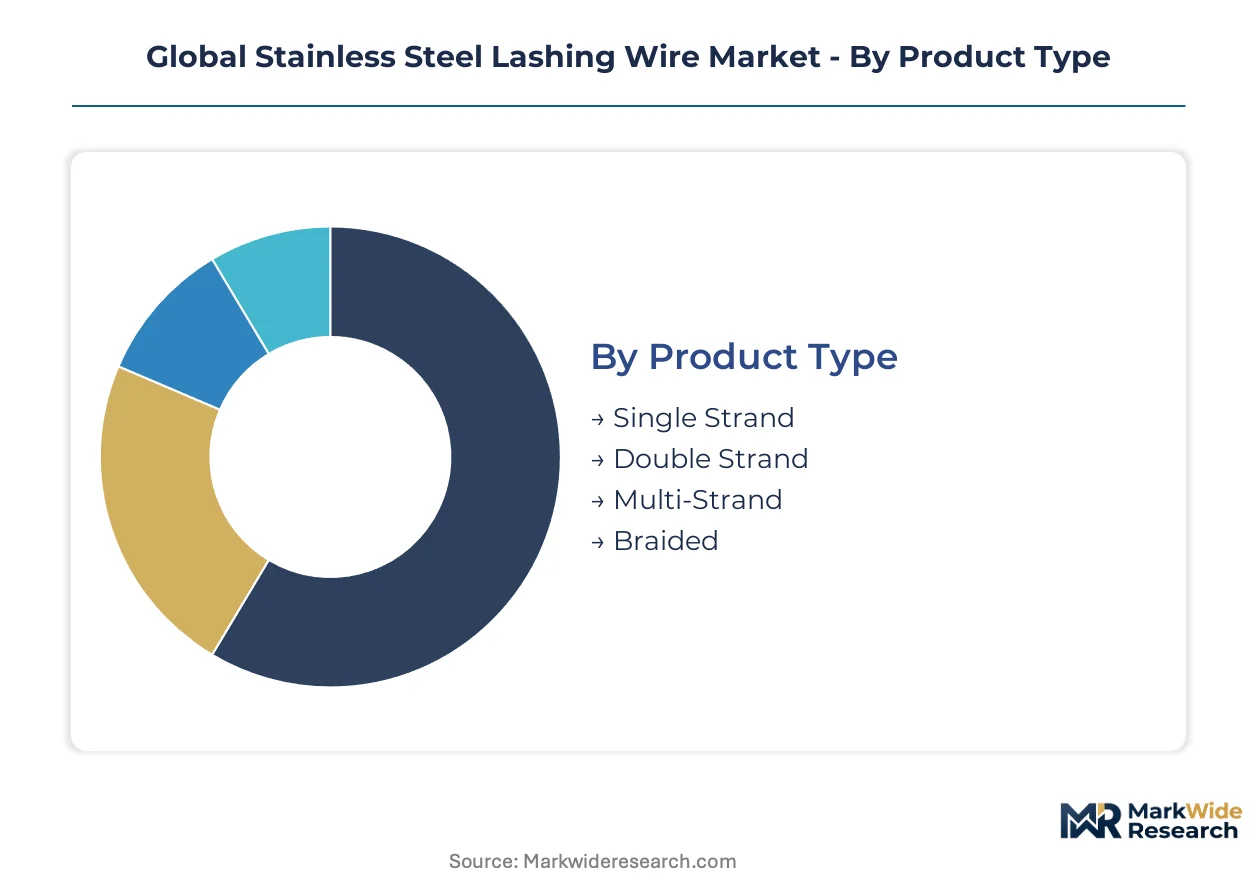
Stainless steel lashing wire specifications diverge sharply across marine, telecom, and construction verticals, with diameter tolerances and strand architecture directly determining corrosion resistance and tensile performance. Procurement patterns fragment by end-user sophistication, from bulk contractors specifying mill certificates to retailers stocking commodity grades for maintenance markets.
Product Type:
Mature configurations dominate volume in established marine and telecom applications, while emerging braided architectures capture premium positioning in dynamic-load environments.
- Single Strand:Cold-drawn austenitic wire in continuous lengths simplifies tensioning operations on telecom guy-wire systems. North American tower operators specify lot-traceable 302HQ grades for installations above 50-meter hub heights, with direct procurement bypassing traditional rigging-house intermediaries.
- Double Strand:Paired wire construction balances cost efficiency against redundancy for mid-rise construction bundling. Chinese coastal manufacturing zones favor this format for shipbuilding piping runs where 304-series corrosion resistance satisfies classification society minimums without 316L surcharge premiums.
- Multi-Strand:Three to seven wire configurations distribute mechanical stress across offshore platform cable management systems.
- Braided:Interwoven architectures deliver multi-axis flexibility for subsea cable lashing where monopile movement induces cyclic loading.
Single strand retains volume leadership; braided holds the steepest expansion curve.
Application:
Cost tier stratification separates specification-intensive marine procurement from price-sensitive construction bundling.
- Marine:Classification societies now mandate 316L stainless for subsea cable lashing, eliminating 304-series alternatives from North Sea tender qualifications. Offshore wind developers compress replacement cycles, forcing producers to recertify under accelerated salt-spray protocols exceeding baseline ISO 1788 requirements.
- Construction:Concrete reinforcement frames and scaffolding lashing consume ferritic grades where oxidation exposure remains intermittent. Nevatia Steel competes on cost-optimized 300-series formulations across South Asian project sites with less stringent chloride exposure.
- Telecommunications:Aramid fiber substitution displaces stainless below 2.0 mm diameter where tensile requirements permit, constraining addressable market.
- Automotive:Exhaust system hangers and underbody cable management specify heat-resistant grades for thermal cycling environments.
Marine commands margin premiums; telecommunications faces material substitution pressure.
Diameter:
Volume concentration sits at mid-range specifications serving construction and marine bulk applications, with precision-drawn thin gauges requiring scarce technical expertise.
- 2 mm:The workhorse specification balances tensile capacity against handling convenience for shipbuilding piping runs and telecom guy-wire anchoring. Chinese cold-drawing facilities in Jiangsu province optimize output at this diameter to serve Asian shipbuilding clusters.
- 3 mm:Heavy-duty marine lashing and offshore platform rigging demand this gauge for lifeline and safety cable applications. North Sea operators specify plasma-enhanced chromium nitride coatings to extend salt-spray resistance beyond 3,000 hours.
- 1 mm:Precision-drawn sub-1.0 mm tolerance concentrates among retiring European and Japanese workforces without pipeline replacement.
- 4 mm:Structural anchoring and heavy construction bundling utilize this maximum standard gauge.
2 mm dominates unit volume; 1 mm precision grades face technician scarcity constraints.
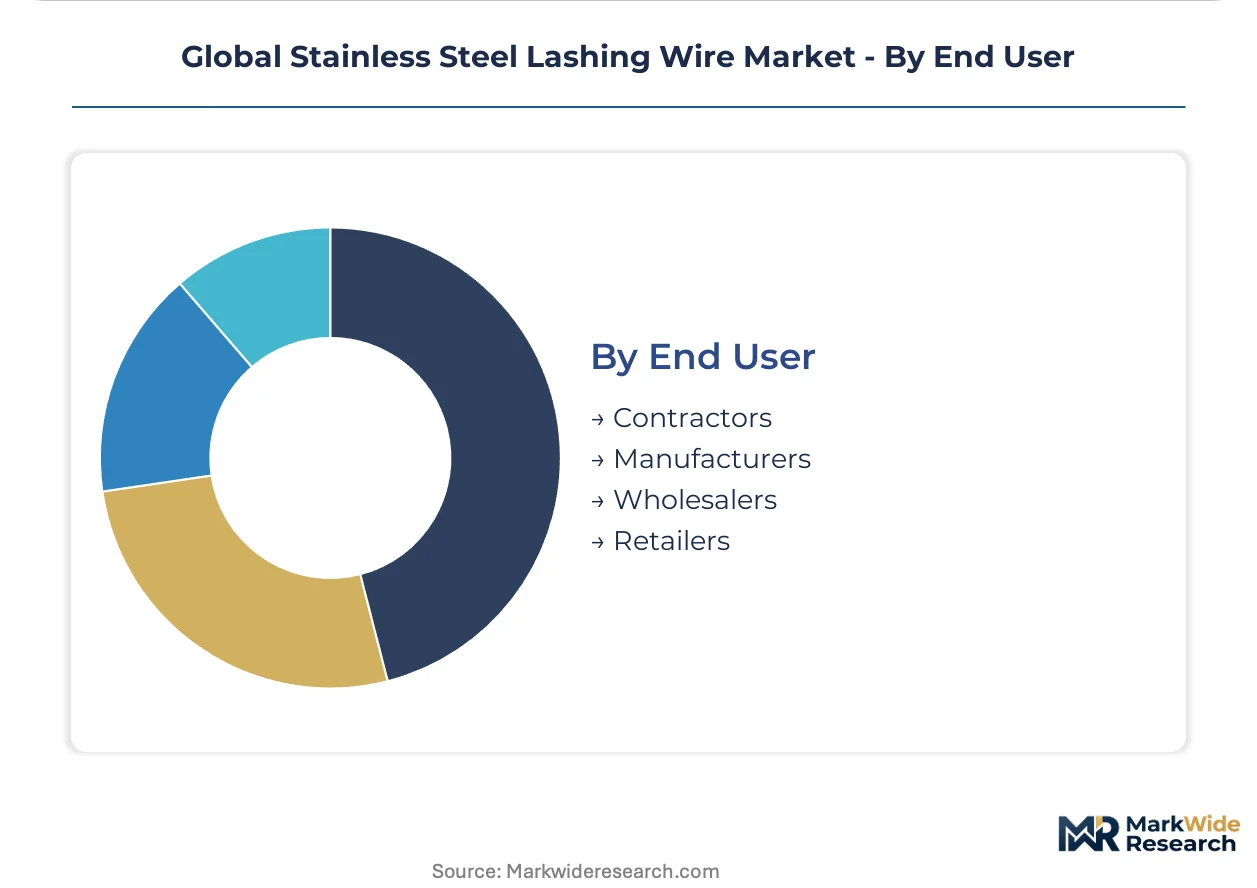
End User:
Customer type determines certification requirements and pricing structure, from mill-direct bulk contracts to distributed retail channels.
- Contractors:Large-scale marine and infrastructure projects demand mill-test certificates and lot traceability. North Sea EPC contractors now specify RFID-tagged wire batches integrated with predictive maintenance platforms for outcome-based tension-monitoring contracts.
- Manufacturers:OEM integration into cable assemblies and pre-fabricated rigging systems requires dimensional tolerances per JIS G 4309 precision-drawn standards.
- Wholesalers:Regional distributors stock standard grades for maintenance and repair markets with shorter lead time requirements.
- Retailers:Hardware and marine supply outlets serve small-scale maintenance with limited technical specification.
Contractors drive specification intensity; manufacturers face multi-standard certification lag of 18-24 months.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea offshore wind interconnect underwrites Northern Europe's centrality to corrosion-resistant rigging demand. China's Yangtze River Delta port clusters anchor Asian supply expansion. The US Gulf Coast petrochemical corridor sustains marine maintenance procurement.
China
MIIT subsidies for low-carbon cold-drawing facilities expand melt-shop capacity in Jiangsu province to serve Asian shipbuilding clusters. GB/T 9944 corrosion testing protocols govern domestic standards that exporters must satisfy for market access. Yangtze River Delta manufacturing zones see new facilities coming online to serve regional marine and telecom markets.
Germany
North Sea offshore wind developers compress replacement cycles for corrosion-resistant rigging, forcing producers to recertify under accelerated salt-spray protocols. ECHA enforcement of REACH Article 33 substance-of-very-high-concern reporting filters non-compliant imports from European procurement lists. Hamburg and Bremerhaven port industrial zones concentrate marine lashing distribution for North European offshore construction.
United States
Telecom tower operators unbundle wire supply from turnkey installation contracts, creating direct procurement relationships with certified wire drawers. FCC infrastructure permitting timelines shape deployment velocity for guy-wire anchoring systems above 50-meter hub heights. Gulf Coast petrochemical and offshore platform maintenance clusters sustain demand for 316L-grade marine lashing.
Japan
METI maintains JIS G 4309 standards that differentiate precision-drawn wire from general construction grades, creating technical barriers for uncertified producers. Kanto and Kansai industrial corridors retain concentrated expertise in sub-1.0 mm aerospace-grade tolerance cold-drawing. Demographic pressures on technical workforce availability constrain expansion of precision-drawn capacity.
Vietnam
Underdeveloped stainless wire capacity near Haiphong port offers first-mover positioning for marine lashing serving ASEAN ship repair yards. National industrial development frameworks prioritize coastal manufacturing zone expansion without yet specifying stainless wire segment incentives. Emerging ship repair clusters along the northern coastline generate incremental demand for 304-series construction-grade lashing.
Global Stainless Steel Lashing Wire Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in cold-drawn wire fabrication. The vendor base distributes across integrated melt-to-wire producers, independent wire drawers, and regional distributors. Three archetypes dominate: backward-integrated stainless mills capturing margin through captive slab supply; precision-drawn specialists leveraging decades of aerospace tolerance expertise; and cost-optimized regional formulators serving price-sensitive construction bundling. Competitive moves concentrate on capacity expansion in coastal manufacturing zones and multi-standard certification investments to reduce 18-24 month qualification timelines.
Among North American fabricators, Loos & Co. and CWI-America occupy positions in precision-drawn segments serving infrastructure and aerospace-adjent applications. European integrated producers exemplified by Acerinox S.A. anchor the captive supply archetype through melt-to-wire control. Nevatia Steel represents cost-optimized 300-series formulation strategies targeting South Asian construction markets.
| Leading Market Players |
|---|
| Loos & Co. |
| Power Manufacturing |
| Phoenix Utility Products Corporation |
| CWI-America |
| Nevatia Steel |
| Wire World |
| Multicom Inc. |
| Anand Arc Ltd. |
| Acerinox S.A. |
| Others |
Value Chain & Pricing Dynamics
Jiangsu province's expanding cold-drawing capacity is reshaping downstream pricing power across Asian marine procurement, as new melt-shop investments compress regional feedstock costs while European integrated mills defend premium positioning through REACH-compliant surface treatments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates 316L marine-grade with plasma-enhanced coatings from 304-series construction bundles and ferritic maintenance grades. Price differentiation hinges on certification tier—ISO 1788 and JIS G 4309 precision standards command substantial premia over GB/T 9944 baseline compliance—and captive slab supply from integrated mills. Cost compression in standard-grade construction segments is intensifying because Chinese coastal overcapacity floods spot markets. Small-scale maintenance buyers through retail channels exhibit highest price sensitivity; North Sea offshore wind EPC contractors demonstrate lowest sensitivity given replacement cycle liabilities.
Supply Chain Analysis
Tariff exposure between China and the European Union under CBAM phase-in dominates strategic sourcing decisions for marine-grade wire procurement. Geographic supply concentration centers on China, Germany, and Japan, with Jiangsu and Zhejiang provinces anchoring Asian melt-to-wire output. Raw material dependencies rest on nickel alloy surcharges, chromium ore feedstock, and trivalent chromium passivation chemistry substitutes. Single-source vulnerability concentrates in European 300-series slab supply controlled by integrated producers. Distribution runs through mill-direct bulk contracts for large contractors, rigging-house intermediaries for mid-tier projects, and regional wholesalers for maintenance markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as telecom tower operators disintermediate traditional rigging-house channels, creating direct procurement niches for certified precision drawers capable of lot-traceable 302HQ supply.
For Market Incumbents: Insulate premium positioning by deepening captive nickel alloy supply through backward integration into Jiangsu melt-shop partnerships, while accelerating multi-standard certification investments to compress 18-24 month JIS G 4309 and EN 10264-4 qualification timelines. Aramid fiber substitution below 2.0 mm diameter and REACH Article 33 enforcement against hexavalent chromium passivation represent immediate threats requiring trivalent chromium reformulation R&D. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's underdeveloped stainless wire capacity near Haiphong port, serving ASEAN ship repair yards with 304-series construction-grade lashing before escalating to 316L marine specifications. The most penetrable segment lies in mid-rise construction bundling across South Asian project sites where Nevatia Steel's cost-optimized 300-series formulations demonstrate viable price positioning. A go-to-market angle emphasizing direct contractor relationships—bypassing traditional distributor markups—mirrors successful North American telecom tower disintermediation patterns. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-drawn specialists with aerospace-grade tolerance expertise concentrated among retiring European and Japanese workforces. Long-term viability across a 5-10 year window hinges on acquiring capabilities in sub-1.0 mm cold-drawing and plasma-enhanced surface treatment deposition before demographic attrition eliminates technical workforce pipelines. The signal to watch is accelerated salt-spray protocol adoption by North Sea offshore wind developers exceeding baseline ISO 1788 requirements, indicating premium-tier demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Slab Supply | Acerinox S.A. sustains margin capture through integrated melt-to-wire control across European mills. |
| Multi-Standard Certification Investment | Simultaneous JIS G 4309 and EN 10264-4 compliance reduces 18-24 month qualification barriers for new entrants. |
| Coastal Manufacturing Zone Expansion | Haiphong port positioning captures ASEAN ship repair demand before regional capacity saturation. |
| Surface Treatment Reformulation | Trivalent chromium and cerium-based alternatives satisfy REACH Annex XIV authorization requirements. |
| Digital Twin Integration | RFID-tagged wire batches with predictive maintenance platforms enable outcome-based tension-monitoring contracts. |
Study Parameters
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings. Conversations with cold-drawing facility managers, marine classification society surveyors, telecom tower procurement officers, and offshore wind EPC contractors informed demand-side dynamics. Secondary sources include ECHA substance-of-very-high-concern databases, MIIT low-carbon facility subsidy registries, and ISO 1788 technical committee documentation. Bottom-up capacity assessments across Jiangsu and Zhejiang provinces triangulate against top-down trade flow analysis.
Calibration against historical nickel alloy surcharge volatility and regional carbon border adjustment timelines shapes the analytical framework. Segmentation dimensions span product architecture, application vertical, diameter specification, and end-user procurement sophistication. CAGRs derive from elasticity modeling against shipbuilding output and offshore wind installation forecasts. Industry-specific inputs include LME nickel price band scenarios and REACH compliance cost pass-through assumptions.
Sensitivities concentrate around nickel price spikes above USD 25,000/tonne, accelerated CBAM phase-in schedules, and demographic attrition in precision-drawn technician pools. Forecasts reflect documented assumptions about classification society specification tightening and dual carbon policy enforcement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Europe Metal Casting Market
Metals
North America Aluminum Casting Market
Metals
India Metal Fabrication Market
Metals
Zirconium Market
Metals
Global Copper Sputtering Target Market
Metals
Global Aluminum Extruded Products Market
Metals
Global Vanadium Market
Metals
Galvanized Steel Market
Metals
Global High Purity Titanium Powder Market
Metals
Heat-Treated Steel Plates Market
Metals
Copper Powder Market
Metals
Monel Alloy Market
Metals
Global Metal and Metal Manufactured Products Market
Metals
Russia Metal Fabrication Market
Metals
Metal Powder Market
Metals
Metallurgical Silicon Market