
 Global 3D Printing Construction Material Market | 2026-2036
Global 3D Printing Construction Material Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Printing Construction Material Market Analysis
Project finance tied to milestone-based construction completion is fragmenting capital requirements across the 3D printing construction material value chain. COBOD International leverages its equipment-leasing partnerships to lower entry barriers for regional contractors. Sika AG anchors European supply through its pre-mixed printable mortar formulations. ICON Technology dominates North American project pipelines with its vertically integrated build-operate models.
3D printing construction material encompasses cementitious, polymer-based, composite, and metal feedstocks formulated for layer-by-layer deposition under robotic gantry or arm-based systems, typically achieving compressive strengths of 20-60 MPa depending on binder chemistry and curing protocol. Its primary purpose is to reduce formwork labor, cut material waste by 30-60% versus cast-in-place methods, and enable geometrically complex structural elements without custom molds. Cementitious material type leads current volume owing to compatibility with existing concrete supply chains and lower per-kilogram raw material costs. Infrastructure application represents the fastest-growing segment as bridge culverts, flood barriers, and utility housings demonstrate printable durability under variable load conditions. Binder jetting technology occupies the premium margin tier where metal powder deposition serves architectural cladding and structural connectors requiring tight tolerance control.
The EU Green Deal and REACH frameworks impose embodied carbon disclosure and chemical safety thresholds on construction inputs sold across member states, compelling reformulation of printable cement blends away from high-Portland compositions. The US EPA and OSHA jointly govern silica exposure limits at material mixing sites, shaping on-site printer enclosure standards and automated batching adoption. China's GB standards and dual carbon goals mandate recycled aggregate incorporation rates that printable concrete mixes can satisfy more readily than conventional pours due to controlled layer-by-layer placement. Stakeholders must monitor whether national building codes will recognize printed wall assemblies as load-bearing elements without redundant steel framing, a determination that will unlock or constrain multi-story deployment.
Market Dynamics
The 3D printing construction material sector is bifurcating between equipment-leasing platforms that lower contractor entry barriers and proprietary material suppliers capturing recurring revenue through formulation lock-in.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:These mandates redirect R&D budgets toward low-clinker cementitious mixes, accelerating printable mortar adoption across Dutch and German infrastructure projects.
- Robotic gantry deposition speed:Layer-by-layer construction compresses project timelines by 40-70% versus conventional formwork, attracting residential developers in the United Arab Emirates seeking rapid low-rise housing delivery.
- China's GB standards on recycled aggregate:Controlled placement protocols in printable concrete satisfy mandated incorporation rates more readily than conventional pours, opening municipal procurement channels.
Market Restraints
- Silica exposure compliance costs:US EPA and OSHA joint enforcement at mixing sites necessitates automated batching enclosures, elevating capital requirements for regional contractors.
- High-Portland cement reformulation lag:REACH chemical safety thresholds create friction as European suppliers revalidate printable blend performance against legacy compressive strength benchmarks.
- Steel framing redundancy:National building codes in most jurisdictions still require redundant structural reinforcement, negating material savings from printed wall assemblies.
Strategic Opportunities
- Bridge culvert and flood barrier applications:Infrastructure segments demonstrate printable durability under variable load conditions, creating specification pathways for civil engineering firms.
- Port-logistics cluster proximity:Netherlands-based supply chains around Rotterdam and Delft University spinouts enable just-in-time mortar delivery with reduced transport emissions.
- Metal powder binder jetting:Architectural cladding and structural connector applications command premium margins where tight tolerance control differentiates from cementitious alternatives.
Industry Challenges
- Load-bearing certification timelines:Multi-story deployment awaits code recognition of printed assemblies as primary structural elements, freezing vertical construction applications.
- Robotic gantry operator training gaps:Layer deposition calibration and real-time mix adjustment require specialized technicians scarce in conventional construction labor pools.
- Curing protocol standardization:Variable environmental conditions complicate quality assurance across distributed project sites, demanding portable testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Printing Construction Material Market |
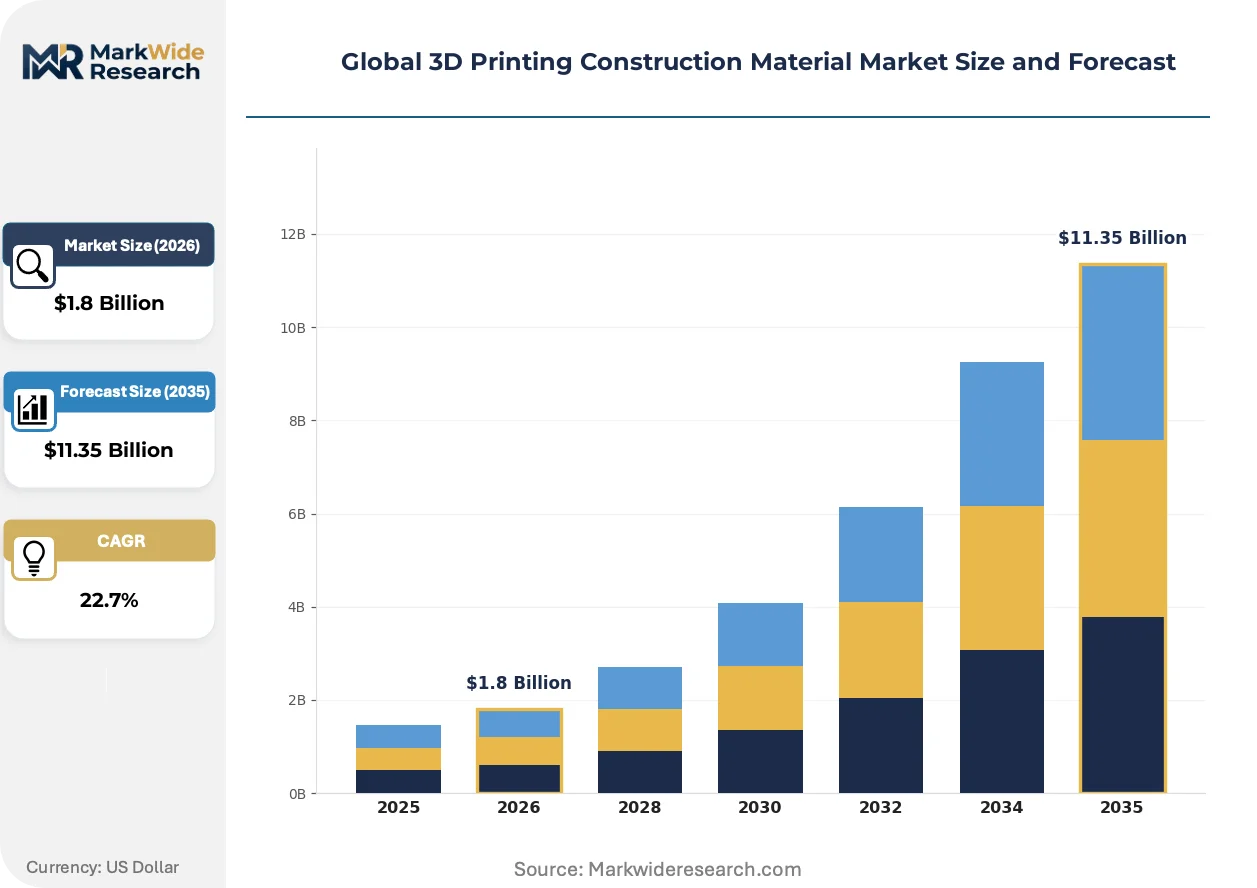
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cementitious, Polymer-Based, Composite, Metal Application: Residential Structures, Commercial Buildings, Infrastructure Projects, Art Installations Technology: FDM, SLA, SLS, Binder Jetting End Use: Construction Companies, Architects, Developers, Contractors |
| Companies Covered | CyBe Construction, Sika AG, COBOD International, Mighty Buildings, Holcim Group, Apis Cor, ICON Technology, Saint-Gobain, XtreeE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Printing Construction Material Market Emerging Trajectories
Formulation chemistry and deposition hardware are converging to enable geometrically complex elements without custom mold fabrication, compressing design-to-assembly cycles.
Printable mortar technology is migrating from experimental demonstration projects to production-scale housing developments. Residential contractors in the United Arab Emirates now specify printed concrete walls for low-rise units, abandoning traditional block-laying crews. The shift compresses labor costs and formwork waste simultaneously.
REACH chemical safety disclosure requirements are compelling European suppliers to document binder jetting feedstock compositions. Pre-mixed printable formulations now carry embodied carbon certificates traceable to clinker content. German and Dutch regulators are piloting accelerated approval pathways for low-carbon printable blends in public infrastructure tenders.
Specification decisions increasingly hinge on project finance structures tied to milestone-based completion. Build-operate models favor vertically integrated material suppliers who warranty structural performance across the asset lifecycle. North American infrastructure funds now require printable material traceability from batching through curing as a condition of debt financing.
Global 3D Printing Construction Material Market Segmentation
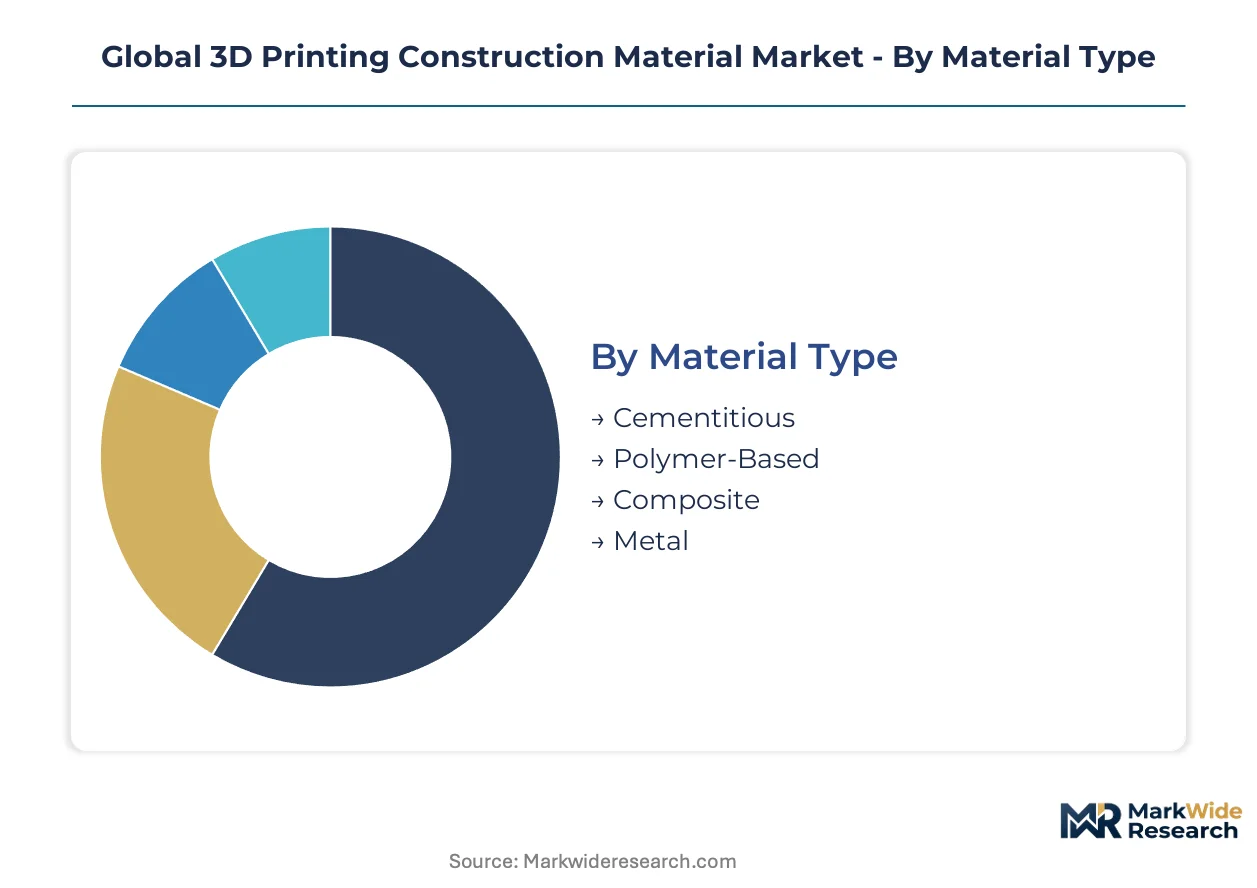
Segmentation in construction materials determines procurement cadence and formulation lock-in. Material type dictates raw material sourcing cycles. Application segments separate capital-heavy infrastructure from fast-turn residential projects. Technology and end-use dimensions reveal where equipment leasing versus outright purchase prevails.
Material Type:
Cementitious formulations turn over fastest due to continuous batching requirements and per-project customization, while metal powders rotate slowest given powder metallurgy lead times and aerospace-grade qualification protocols.
- Cementitious:Portland-based and geopolymer binders formulated for 20-60 MPa compressive strength under gantry deposition. Demand concentrates in the Netherlands where Delft University spinouts and Rotterdam port-logistics firms cluster around printable mortar supply chains. The EU Green Deal's embodied carbon thresholds redirect R&D budgets toward low-clinker compositions.
- Polymer-Based:Thermoplastic and thermoset resins including fiber-reinforced epoxies for non-structural architectural elements. Specifiers in the United Arab Emirates leverage rapid-cure properties for low-rise housing timelines compressed by 40-70% versus conventional formwork.
- Composite:Hybrid matrices combining mineral binders with polymer modifiers or recycled fiber reinforcement. Japanese infrastructure contractors specify these for seismic-resistant utility housings.
- Metal:Titanium, aluminum, and steel powders deposited via binder jetting for architectural cladding and structural connectors. German and Swiss fabricators dominate premium-margin applications requiring tight tolerance control.
Cementitious dominates installed base. Metal is where expansion concentrates.
Application:
Cost tier separation distinguishes high-volume standardized housing from bespoke commercial commissions where geometric complexity commands formulation premiums.
- Residential Structures:Single-family and low-rise multi-family units employing printed concrete walls. Developers in the United Arab Emirates scale adoption for rapid delivery of affordable housing stock. Chinese municipal procurement channels favor printable concrete for meeting GB standards on recycled aggregate incorporation.
- Commercial Buildings:Office facades, retail shells, and hospitality structures requiring aesthetic surface finishes. Dutch and German projects increasingly specify pre-mixed printable mortars with embodied carbon certificates traceable to clinker content.
- Infrastructure Projects:Bridge culverts, flood barriers, and utility housings demonstrating printable durability under variable load conditions. Civil engineering firms in Japan and the Netherlands lead specification pathways.
- Art Installations:Sculptural and non-load-bearing architectural elements emphasizing geometric freedom. Museums and cultural institutions commission these for temporary or permanent exhibition pieces.
Infrastructure Projects are climbing the fastest as civil engineering firms validate printable durability under variable load conditions. Residential Structures anchor current volume.
Technology:
Volume concentration separates mass-market extrusion methods from premium powder-bed systems where equipment utilization rates determine contract economics.
- FDM:Fused deposition modeling using thermoplastic filament or concrete paste extrusion through robotic gantry systems. Contractors favor this for lowest capital entry via equipment-leasing partnerships.
- SLA:Stereolithography curing liquid resin with ultraviolet lasers for high-detail architectural models and small-scale facade elements.
- SLS:Selective laser sintering fusing polymer or composite powders for functional prototyping and limited production runs.
- Binder Jetting:Liquid binder deposition onto metal or sand powder beds enabling complex geometries without thermal stress. REACH chemical safety disclosure requirements compel European suppliers to document feedstock compositions for architectural cladding applications.
FDM dominates installed base. Binder Jetting is gaining share fastest in premium-margin architectural metalwork.
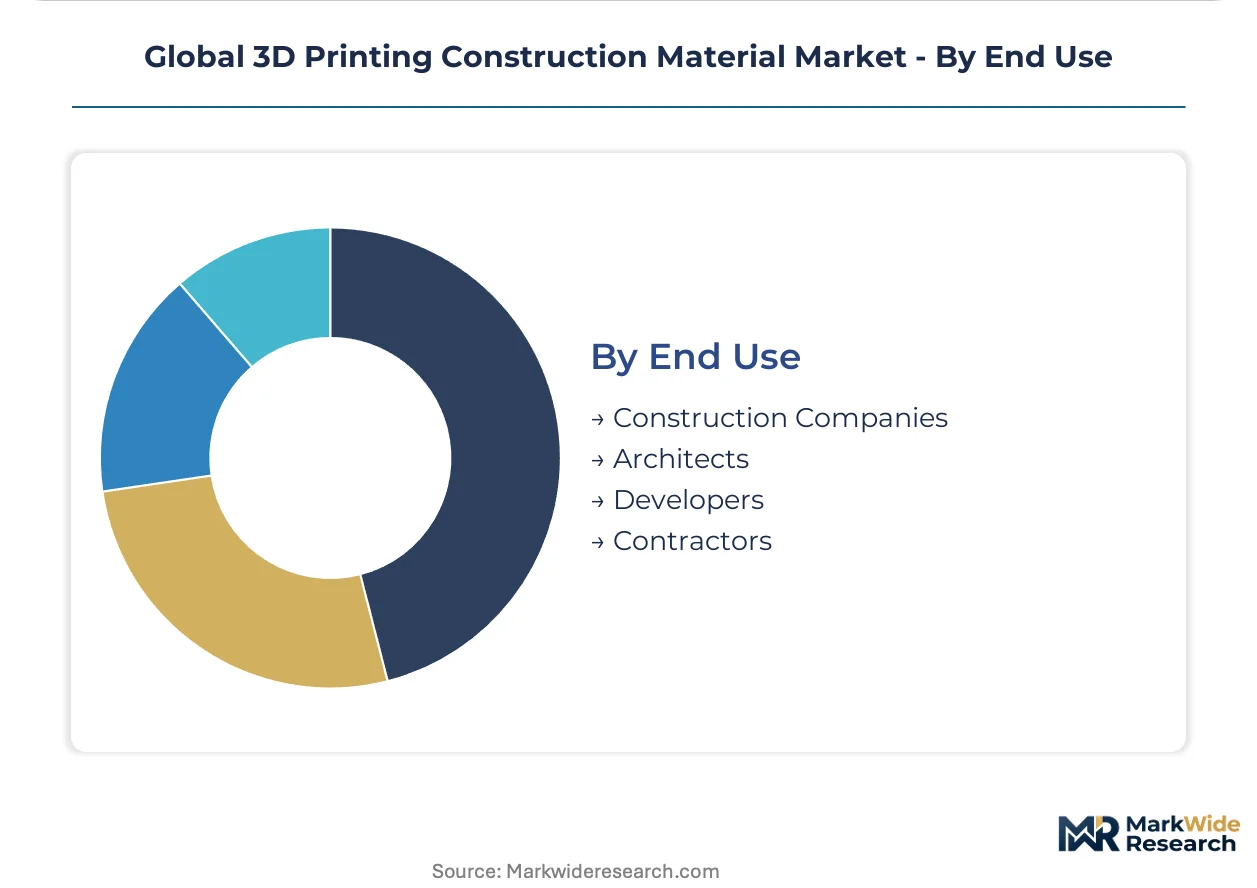
End Use:
Customer type determines whether procurement flows through project finance structures or recurring operational budgets.
- Construction Companies:General contractors integrating printed elements into traditional project delivery. US EPA and OSHA silica exposure compliance costs elevate capital requirements for automated batching enclosures.
- Architects:Design firms specifying printable materials for geometrically complex elements without custom mold fabrication. Dutch and German regulators pilot accelerated approval pathways for low-carbon printable blends.
- Developers:Asset owners employing build-operate models favoring vertically integrated material suppliers who warranty structural performance across lifecycle. North American infrastructure funds require printable material traceability from batching through curing.
- Contractors:Specialized trades executing deposition under milestone-based completion contracts. Robotic gantry operator training gaps constrain labor pool availability.
Construction Companies dominate installed base. Developers are where expansion concentrates as build-operate models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal embodied carbon thresholds redirect R&D budgets toward low-clinker cementitious mixes across member states. The UAE accelerates printed concrete adoption for low-rise housing delivery. China's GB standards on recycled aggregate create municipal procurement advantages for printable concrete placement protocols.
United States
North American infrastructure funds now require printable material traceability from batching through curing as a condition of debt financing. US EPA and OSHA jointly enforce silica exposure limits at material mixing sites, elevating capital requirements for automated batching enclosures. ICON Technology anchors project pipelines through vertically integrated build-operate models concentrated in Texas and California developments.
Netherlands
Delft University spinouts and Rotterdam port-logistics firms cluster around printable mortar supply chains serving Dutch and German infrastructure tenders. REACH chemical safety disclosure requirements compel suppliers to document binder jetting feedstock compositions with embodied carbon certificates traceable to clinker content. Regulators pilot accelerated approval pathways for low-carbon printable blends in public works specifications.
United Arab Emirates
Residential developers scale adoption of printed concrete walls for rapid low-rise housing delivery timelines compressed by 40-70% versus conventional formwork. MOHAP and municipal building authorities coordinate on construction material safety standards for robotic gantry deployment. Dubai-based contractors leverage equipment-leasing partnerships to lower entry barriers for regional construction firms.
China
GB standards and dual carbon goals mandate recycled aggregate incorporation rates that printable concrete mixes satisfy more readily than conventional pours due to controlled layer-by-layer placement. MEE oversight shapes municipal procurement channels favoring construction methods demonstrating embodied carbon reduction. Yangtze River Delta infrastructure contractors lead specification of printable durability for bridge culverts and utility housings.
Germany
German and Swiss fabricators dominate premium-margin architectural metalwork applications requiring tight tolerance control through binder jetting deposition. ECHA REACH frameworks impose chemical safety thresholds compelling reformulation of printable cement blends away from high-Portland compositions. Bavarian and North Rhine-Westphalian engineering firms validate printable structural connectors for civil infrastructure under variable load conditions.
Global 3D Printing Construction Material Market Vendor Landscape
On the supply side, the industry is bifurcating between equipment-leasing platforms that lower contractor entry barriers and proprietary material suppliers capturing recurring revenue through formulation lock-in. Three strategic archetypes dominate: vertically integrated build-operate specialists, pre-mixed printable mortar formulators, and gantry system equipment lessors. Competitive moves concentrate on strategic partnerships binding material supply to hardware deployment, and geographic expansion through regional licensing arrangements.
Within the equipment-leasing archetype, COBOD International exemplifies the platform model lowering capital barriers for contractors. Among European material formulators, Sika AG anchors supply through pre-mixed printable mortar formulations. At the vertically integrated end, ICON Technology occupies a position representing build-operate models that warranty structural performance across asset lifecycles.
| Leading Market Players |
|---|
| CyBe Construction |
| Sika AG |
| COBOD International |
| Mighty Buildings |
| Holcim Group |
| Apis Cor |
| ICON Technology |
| Saint-Gobain |
| XtreeE |
| Others |
Supply Flow & Price Mechanics
Rotterdam port-logistics clusters concentrate printable mortar formulation capacity, anchoring margin pools with pre-mixed suppliers who capture recurring revenue through specification lock-in. Equipment-leasing platforms compete on capital accessibility, compressing hardware margins while material premiums persist.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels dominates: premium formulations carry REACH-compliant embodied carbon certificates, standard blends serve Dutch infrastructure tenders, and economy tiers target UAE residential developers. Price differentiation hinges on clinker content and automated batching integration. Cost compression in economy tiers intensifies as Chinese municipal procurement channels favor recycled aggregate incorporation. Regional contractors exhibit highest price sensitivity; build-operate developers warrant structural performance premiums.
Supply Chain Analysis
Tariff exposure between China and European Union member states dominates supply chain risk planning for printable cementitious feedstocks. Manufacturing concentrates in China, Germany, and the Netherlands. Raw material sourcing draws from low-clinker cement suppliers, recycled aggregate processors, and polymer modifier producers. Single-source vulnerability persists in gantry system robotics sourced from German fabricators. Distribution runs through port-logistics clusters enabling just-in-time mortar delivery to infrastructure project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against conventional cast-in-place concrete methods that retain code recognition and contractor familiarity. Incumbents must demonstrate structural performance equivalence while compressing project timelines.
For Market Incumbents: Build formulation lock-in moats through pre-mixed printable mortar certifications traceable to EU Green Deal embodied carbon thresholds. Anchor supply relationships with Rotterdam and Delft University clusters to secure just-in-time delivery capacity. Defend against equipment-leasing platforms by bundling material warranties with gantry system deployments.
For New Entrants and Emerging Players: North American infrastructure funds represent underpenetrated capital channels where printable material traceability requirements create specification barriers. Target bridge culvert and flood barrier applications where civil engineering firms validate durability under variable load conditions. Enter through build-operate partnerships that warranty structural performance across asset lifecycles.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed equipment-leasing platforms seeking material supply integration. Five-to-ten year viability hinges on national building code recognition of printed wall assemblies as load-bearing elements without redundant steel framing. Monitor accelerated approval pathway pilots in Dutch and German public infrastructure tenders as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Clinker Cement Supply | Secures embodied carbon-compliant feedstock for EU Green Deal threshold compliance. |
| Equipment-Leasing Partnership Expansion | Lowers capital barriers for UAE contractors adopting printed concrete wall systems. |
| REACH Chemical Safety Certification Investment | Enables premium pricing for architectural metalwork through binder jetting deposition. |
| Port-Logistics Cluster Proximity Agreements | Reduces transport emissions for just-in-time mortar delivery to Dutch infrastructure sites. |
| Build-Operate Model Vertical Integration | Captures lifecycle revenue through structural performance warranties across North American developments. |
Methodological Framework
The analysis maps cementitious, polymer-based, composite, and metal feedstock sub-sectors, each validated through deposition hardware engineers, printable mortar formulators, civil engineering specification leads, and municipal procurement officers. Primary interviews combined with secondary validation from customs trade data, SEC filings of construction material suppliers, EU tender databases, and Chinese GB standard documentation. Bottom-up project pipeline enumeration triangulates against top-down construction spending allocation models.
Assumptions held fixed include current EU Green Deal embodied carbon thresholds, US EPA silica exposure enforcement levels, and Chinese recycled aggregate incorporation mandates. Segmentation dimensions span material type, application, technology, and end-use across the projection horizon. CAGRs derive from layer deposition speed improvements, code recognition timelines for load-bearing assemblies, and equipment-leasing penetration rates. Industry-specific inputs include gantry system utilization curves and printable mortar batch-to-batch consistency metrics.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed construction material conglomerates would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Metal Jet 3D Printing Technology Market
3D Printing Materials
Advanced Materials for 3D Printing Market
3D Printing Materials
Polypropylene in 3D Printing Market
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
Polyamide 12 Powder for High-Performance 3D Printing Market
3D Printing Materials
Global Biocompatible 3D Printing Materials Market
3D Printing Materials
3D Printing Plastics Market
3D Printing Materials
Aerospace 3D Printing Materials Market
3D Printing Materials
3D Printing High Performance Plastic Market
3D Printing Materials
Stainless Steel 3D Printing Market
3D Printing Materials
Additive Manufacturing and Materials Market
3D Printing Materials
3D Printing Iron Powder Market
3D Printing Materials
Global 3D Printing Ceramics Market
3D Printing Materials
Graphene in 3D Printing Market
3D Printing Materials
3D Printed Nanocellulose Market
3D Printing Materials
3D Printing Polymers Market