
 Steel Drums and Ibcs Market | 2026-2036
Steel Drums and Ibcs Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Drums and Ibcs Market Analytics
Composite IBC totes is repositioning cost structures in bulk liquid packaging. Greif Inc. leverages vertical integration across steel and fiber drum lines to sustain margin control. Mauser Packaging Solutions anchors its position through closed-loop IBC reconditioning networks. Schütz GmbH & Co. KGaA differentiates via specialized multilayer blow-molding for chemical-grade IBC inner bottles.
Steel drums and IBCs are cylindrical and rectangular bulk containers fabricated from cold-rolled carbon steel or stainless steel, typically ranging from 15 to 350 gallons in nominal capacity, designed for the transport and storage of liquids, powders, and hazardous materials under UN/DOT certification. IBCs incorporate palletized bases, integrated valves, and stackable geometries to optimize warehouse cube utilization and forklift handling efficiency. Steel drums retain dominance in petroleum and lubricant logistics where drum integrity under stacking load remains non-negotiable, while IBCs capture expanding share in specialty chemical distribution due to reduced residual product loss and simplified decanting operations. Food-grade stainless steel drums command premium positioning in pharmaceutical and flavoring compound applications where extractable limits and surface finish specifications drive specification discipline.
EPA hazardous waste manifest requirements, DOT 49 CFR packaging standards, and UN Model Regulations on the Transport of Dangerous Goods collectively dictate drum wall thickness, closure design, and periodic retest intervals for continued service. India's BIS certification for steel packaging and the EU F-Gas Regulation's indirect pressure on refrigerant logistics formats shape compliance investment priorities for drum and IBC manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks for industrial packaging to determine whether reconditioning infrastructure or lightweight material substitution delivers superior lifecycle economics.
Market Dynamics
UN-certified steel alternatives are redirecting capital flows from single-use plastics as chemical manufacturers in Germany, India, and Brazil expand stainless steel IBC procurement for corrosive material handling.
Growth Catalysts
- EU F-Gas Regulation:Indirect pressure on refrigerant logistics formats accelerates steel IBC adoption for temperature-sensitive chemical transport across European distribution networks.
- India's western industrial corridor:Concentrated demand from Gujarat through Maharashtra drives stainless steel drum orders for specialty chemical and agrochemical formulation plants.
- Reusable IBC designs:Closed-loop reconditioning infrastructure reduces per-trip packaging costs for bulk liquid shippers serving multi-site manufacturing networks.
Market Restraints
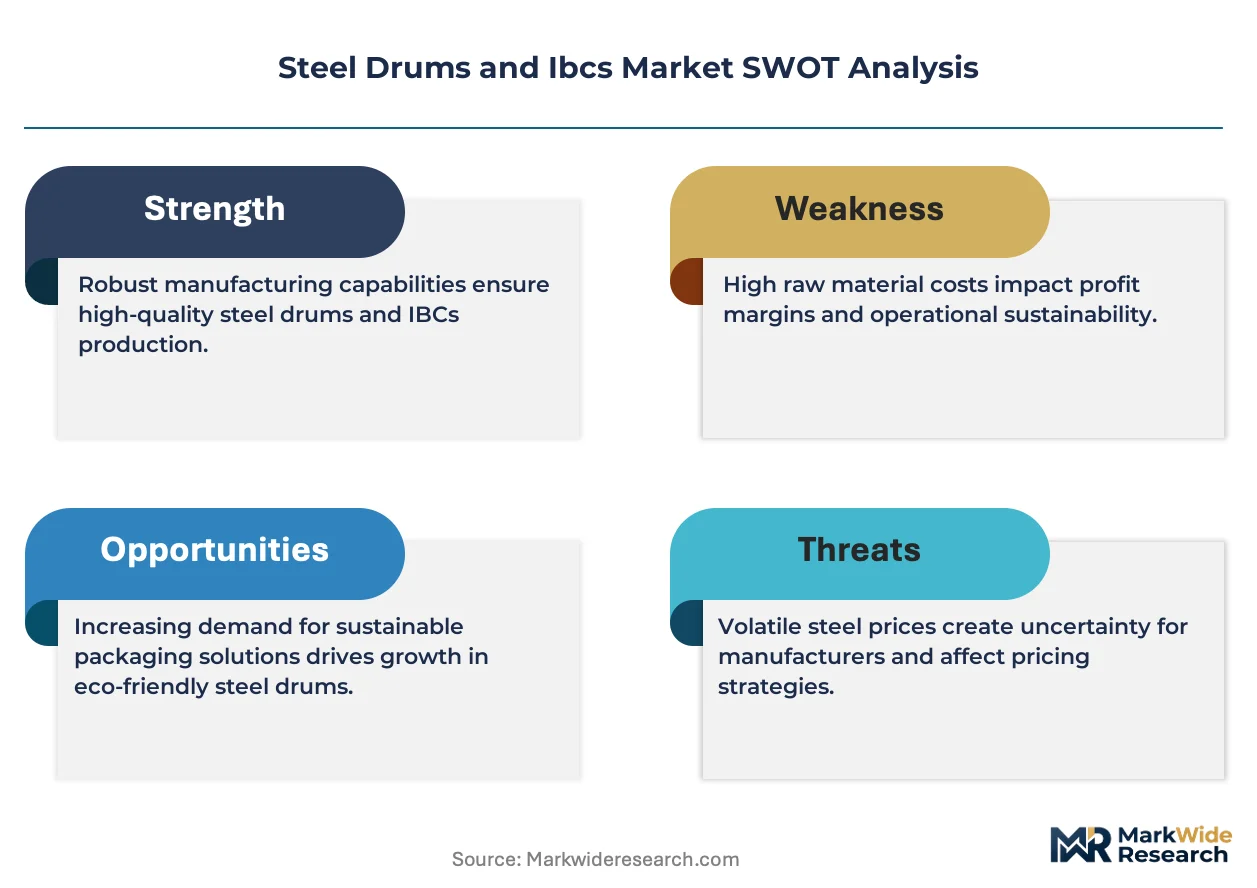
- Cold-rolled carbon steel price volatility:Input cost swings compress fabricator margins and destabilize long-term supply contracts with chemical distributors.
- Composite IBC substitution:Multilayer blow-molded inner bottles with galvanized steel cages capture share in non-corrosive liquid applications where UN certification permits polymer construction.
- DOT 49 CFR retest intervals:Mandatory periodic pressure testing of steel drums creates compliance overhead that extends asset turnover cycles for smaller logistics operators.
Strategic Opportunities
- Brazilian agrochemical expansion:Underpenetrated demand for stainless steel IBCs in São Paulo state fertilizer blending operations offers first-mover positioning for certified fabricators.
- Food-grade stainless steel drums:Premium positioning in pharmaceutical extractables compliance and flavoring compound applications commands specification-driven pricing discipline.
- Extended producer responsibility frameworks:Emerging industrial packaging take-back mandates in the EU and India favor reconditioning infrastructure investments over lightweight material substitution.
Industry Challenges
- UN/DOT certification timelines:Design qualification and periodic retest protocols delay new product introductions and constrain rapid format pivots.
- Welding automation skill gaps:Shortage of certified operators for food-grade seam welding limits capacity expansion at drum fabricators serving pharmaceutical clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Drums and Ibcs Market |
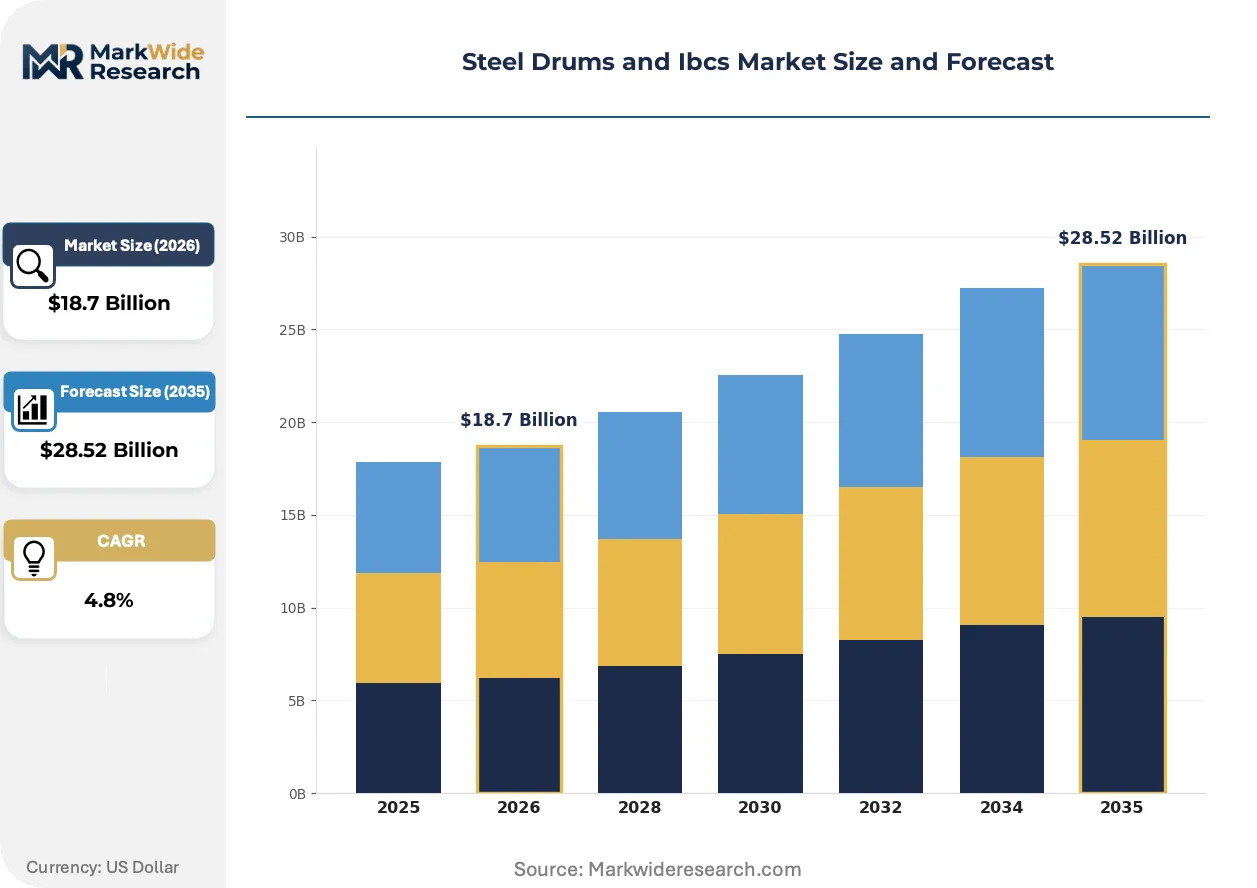
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Drums, IBCs, Open-Head Drums, Closed-Head Drums End User: Chemicals, Pharmaceuticals, Food & Beverage, Oil & Gas Size: 55 Gallons, 30 Gallons, 20 Gallons, Custom Sizes Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Greif Inc., Mauser Packaging Solutions, Schütz GmbH & Co. KGaA, Balmer Lawrie & Co. Ltd., Time Technoplast Ltd., Hoover Ferguson Group Inc., Sicagen India Limited, Snyder Industries Inc., Thielmann US LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Drums and Ibcs Market Evolving Landscape
Material science advances and regulatory stringency are compressing format lifecycles while reconditioning networks reshape asset economics across bulk liquid supply chains.
Stainless steel IBCs with electropolished internal surfaces deliver sub-ppm extractable limits for active pharmaceutical ingredient handling. Specialty chemical distributors in Germany and Switzerland are specifying these units for high-purity solvent logistics. Electropolished construction is overtaking standard 316L finishes in applications where USP Class VI compliance is mandatory.
REACH substance restrictions on certain polymer stabilizers are narrowing the formulation space for composite IBC inner bottles. European chemical distributors are reverting to all-steel constructions for substances under authorization consideration. Drum and IBC manufacturers serving the EU market are expanding stainless steel capacity to hedge against further polymer regulatory tightening.
Leasing-based procurement models are displacing outright purchase for multi-trip IBC fleets. Third-party pooling operators in India and Brazil are consolidating asset ownership and maintenance responsibility. Chemical manufacturers in Maharashtra and São Paulo state are adopting per-trip pricing to eliminate capital tie-up and residual liability for container integrity.
Steel Drums and Ibcs Market Segmentation
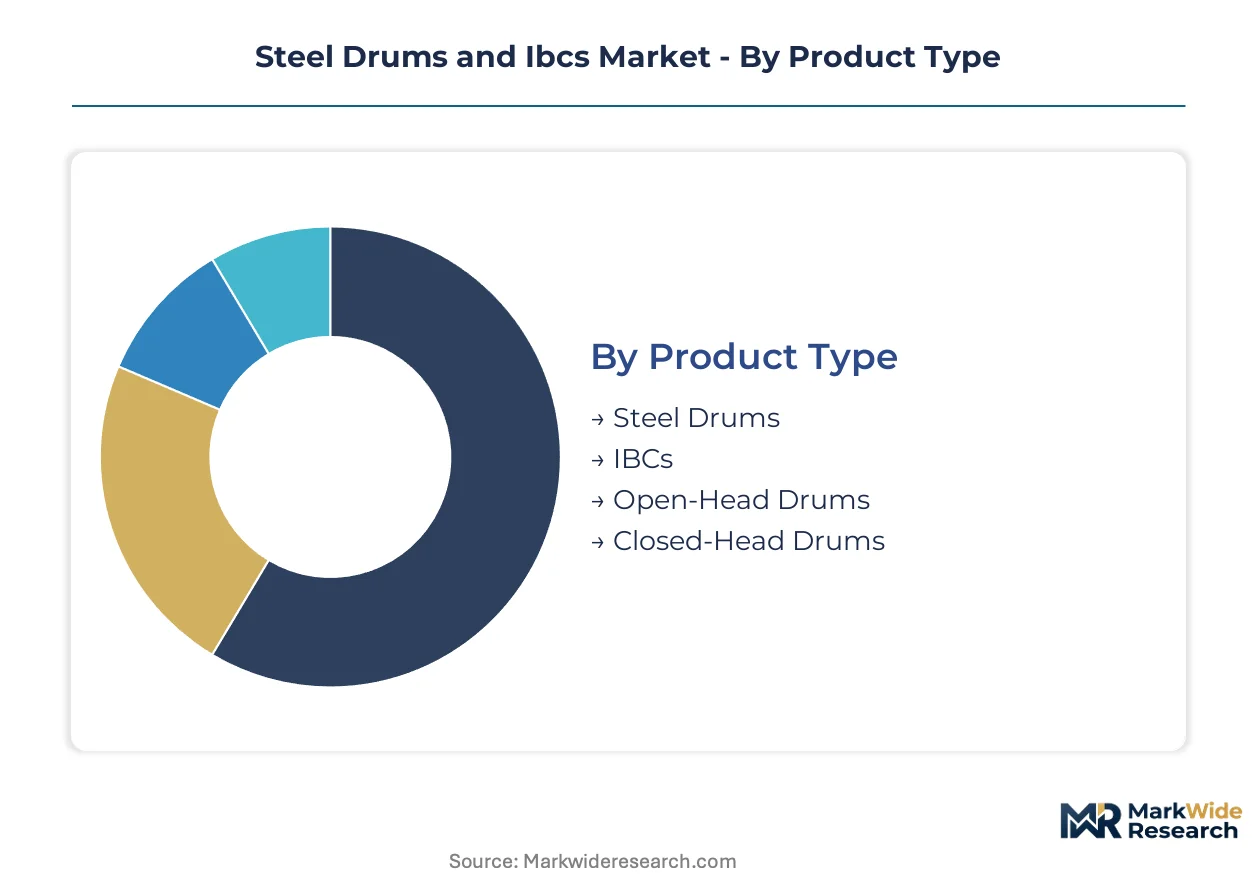
Segmentation in steel drums and IBCs reveals how container specifications align with hazardous material classifications, regulatory compliance tiers, and supply chain handling requirements. Buyers select formats based on UN certification needs, residual product sensitivity, and fleet reconditioning economics rather than unit cost alone.
Product Type:
Buyers in this category differentiate by corrosive content tolerance, reusability cycles, and access requirements for filling and decanting operations.
- Steel Drums:Cold-rolled carbon steel or stainless steel cylinders rated for 15-55 gallon capacities under DOT 49 CFR and UN Model Regulations. Chemical manufacturers in Germany specify these for petroleum and lubricant logistics where stacking load integrity remains non-negotiable under warehouse racking systems.
- IBCs:Palletized rectangular or cylindrical containers with integrated valves and forklift pockets, typically 220-330 gallon nominal capacity. Stainless steel variants are capturing procurement share in India and Brazil for corrosive material handling where residual loss minimization justifies premium positioning.
- Open-Head Drums:Removable lid designs with bolt ring or lever lock closures enabling top access for solids and viscous materials. Food-grade stainless specifications serve pharmaceutical extractables compliance in flavoring compound applications.
- Closed-Head Drums:Fixed top construction with 2-inch and 3/4-inch bung fittings for liquid tightness under pressure testing protocols. These units dominate hazardous waste manifest compliance for EPA-regulated material transport.
Volume sits with steel drums; growth tilts toward IBCs.
End User:
End-use concentration determines material grade requirements, certification stringency, and reconditioning infrastructure investment.
- Chemicals:Specialty chemical distributors in Germany and Switzerland drive stainless steel IBC demand for high-purity solvent logistics. REACH substance restrictions on polymer stabilizers are redirecting procurement toward all-steel constructions for substances under authorization consideration.
- Pharmaceuticals:Active pharmaceutical ingredient handlers specify electropolished stainless steel IBCs with sub-ppm extractable limits. USP Class VI compliance mandates are overtaking standard 316L finishes in Maharashtra formulation plants.
- Food & Beverage:Surface finish specifications and BIS certification requirements govern drum selection for edible oil and concentrate transport. India's western industrial corridor from Gujarat through Maharashtra concentrates demand for food-grade stainless units.
- Oil & Gas:Lubricant blenders and petroleum distributors rely on closed-head steel drums for drum integrity under extended stacking loads in outdoor storage yards.
Chemicals command the largest installed base; pharmaceuticals show the steepest expansion trajectory.
Size:
Capacity selection reflects forklift handling constraints, warehouse cube utilization targets, and residual product loss tolerance.
- 55 Gallons:Standard drum capacity dominating petroleum logistics and hazardous waste transport. DOT 49 CFR retest intervals apply to these units for continued service certification.
- 30 Gallons:Mid-size format gaining traction in specialty chemical distribution where batch sizes do not justify full 55-gallon procurement. São Paulo state fertilizer blending operations are specifying these for underpenetrated demand segments.
- 20 Gallons:Compact drums serving pharmaceutical pilot batches and flavoring compound sampling. Limited reconditioning infrastructure constrains fleet economics for smaller logistics operators.
- Custom Sizes:Non-standard capacities specified for unique material density or handling equipment compatibility. Extended producer responsibility frameworks in the EU are complicating take-back logistics for non-standard formats.
Procurement concentrates at 55 gallons; customization is climbing fastest among pharmaceutical contract manufacturers.
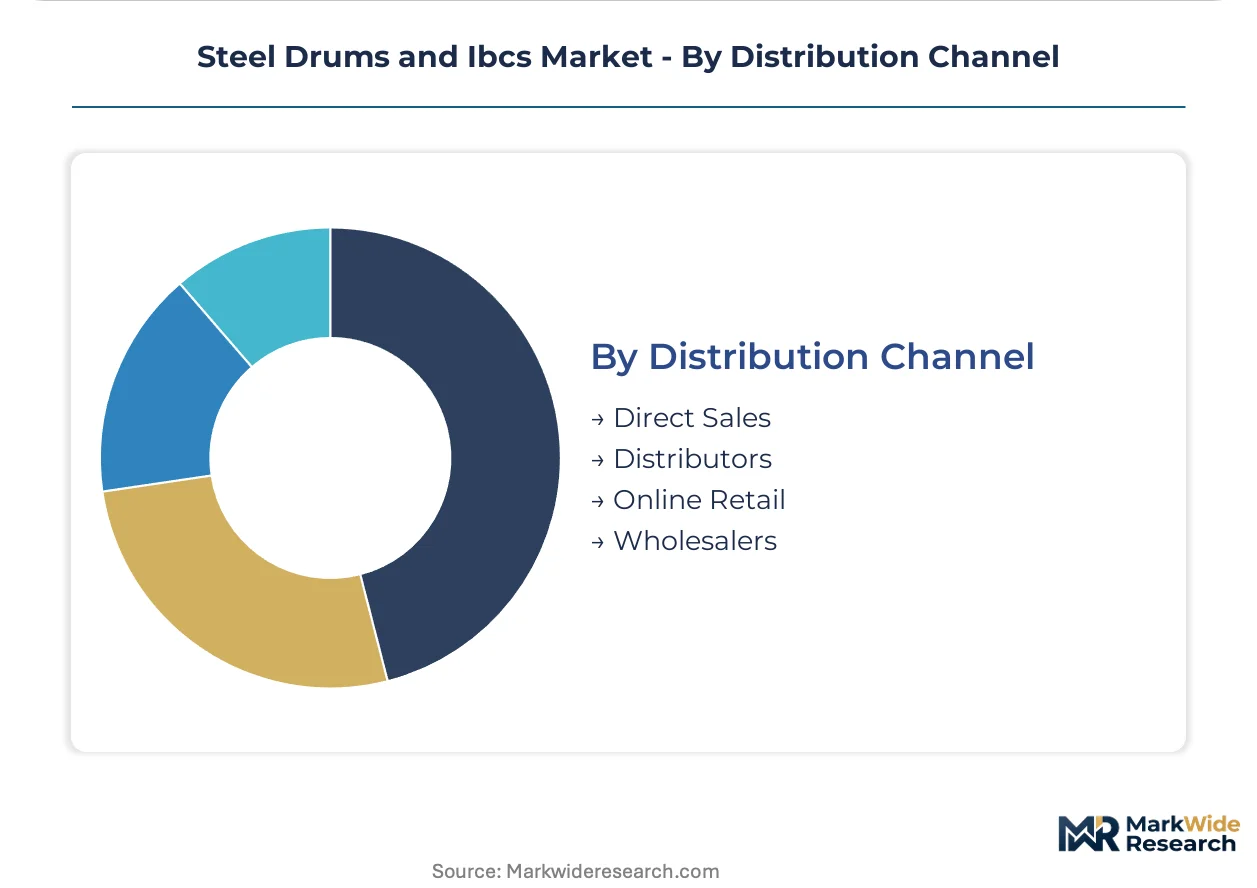
Distribution Channel:
Channel selection determines pricing transparency, technical specification support, and reconditioning service bundling.
- Direct Sales:Large chemical manufacturers negotiate multi-year fleet leasing with fabricators owning closed-loop reconditioning networks. Per-trip pricing eliminates capital tie-up for Maharashtra and São Paulo state operations.
- Distributors:Regional stockists provide specification compliance documentation and rapid replacement for UN-certified drum emergencies. These intermediaries dominate mid-size chemical distributor procurement in Brazil.
- Online Retail:Digital platforms serve small-volume buyers with standard drum specifications and transparent unit pricing. Limited technical consultation constrains adoption for hazardous material applications requiring certification guidance.
- Wholesalers:Bulk aggregators supply standardized drum formats to downstream repackagers and logistics operators. Price volatility in cold-rolled carbon steel compresses margins and destabilizes long-term supply contracts through this channel.
Direct sales anchor volume; leasing-based procurement through distributors is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate stainless steel drum procurement for chemical and agrochemical formulation plants. India's western industrial corridor generates sustained demand for UN-certified packaging across specialty chemical distribution networks.
Germany
Specialty chemical distributors in the Rhine-Ruhr and Ludwigshafen clusters drive stainless steel IBC demand for high-purity solvent logistics. REACH substance restrictions on polymer stabilizers redirect procurement toward all-steel constructions for substances under authorization consideration. Bavarian pharmaceutical formulators specify electropolished 316L finishes for active ingredient handling.
India
Chemical manufacturers across Maharashtra and Gujarat expand stainless steel IBC procurement for corrosive material handling in agrochemical blending operations. BIS certification requirements govern drum selection for food-grade edible oil transport. The western industrial corridor from Ahmedabad through Mumbai concentrates drum orders for specialty chemical plants.
Brazil
Fertilizer blending operations in São Paulo state generate underpenetrated demand for stainless steel IBCs in agrochemical distribution. ANVISA pharmaceutical regulations shape container specifications for active ingredient import logistics. The Campinas-Santos chemical belt anchors drum procurement for petroleum and lubricant supply chains.
United States
EPA hazardous waste manifest requirements dictate drum wall thickness and closure design for chemical distributors serving multi-site manufacturing networks. DOT 49 CFR retest intervals create compliance overhead that extends asset turnover cycles in Texas and Louisiana petrochemical corridors. Gulf Coast lubricant blenders rely on closed-head steel drums for extended outdoor storage integrity.
Switzerland
Swissmedic pharmaceutical regulations mandate sub-ppm extractable limits for active pharmaceutical ingredient containers in Basel and Zurich formulation hubs. Electropolished stainless steel IBCs overtake standard 316L finishes where USP Class VI compliance is mandatory. The Rhine corridor chemical distributors specify these units for temperature-sensitive solvent transport.
Steel Drums and Ibcs Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated packaging groups controlling fleet leasing networks and regional fabricators capturing spot procurement. The vendor base organizes around three archetypes: vertically integrated steel-and-fiber drum operators, closed-loop IBC reconditioning specialists, and electropolished stainless steel premium fabricators. Capacity expansion and backward integration into steel coil sourcing represent the dominant competitive vectors as input cost volatility compresses margins.
Among Germany-based fabricators, Schütz GmbH & Co. KGaA exemplifies the multilayer blow-molding specialist archetype, while Thielmann US LLC occupies a position within the premium stainless steel tier. Greif Inc. represents the vertically integrated packaging group model with cross-material portfolio breadth. These three anchors illustrate how geographic specialization and certification depth stratify competitive positioning across chemical-grade and food-grade segments.
| Leading Market Players |
|---|
| Greif Inc. |
| Mauser Packaging Solutions |
| Schütz GmbH & Co. KGaA |
| Balmer Lawrie & Co. Ltd. |
| Time Technoplast Ltd. |
| Hoover Ferguson Group Inc. |
| Sicagen India Limited |
| Snyder Industries Inc. |
| Thielmann US LLC |
| Others |
Value Network & Pricing Analysis
Cold-rolled carbon steel coil costs cascade through three pricing tiers for drum fabricators, with spot-market volatility compressing margins at economy-grade producers while electropolished stainless specialists in Germany and Switzerland sustain premium positioning through captive sourcing agreements.
Pricing Analysis
Short lead-time premiums command pricing separation from contract-scheduled deliveries, with emergency UN-certified drum orders from Maharashtra chemical plants attracting 15-20% markups over standard fleet procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and reconditioning service bundling. Pricing pressure stems from composite IBC substitution in non-corrosive applications where polymer inner bottles meet DOT specifications. Small logistics operators in Brazil show highest price sensitivity due to capital constraints on reconditioning infrastructure.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cold-rolled carbon steel coil suppliers, where input concentration exposes fabricators to tariff exposure and maritime logistics chokepoints through the Strait of Malacca. Raw material sourcing draws from Chinese steel mills, Indian stainless producers, and European specialty alloy foundries. Component dependencies include electropolishing chemicals from German suppliers and valve assemblies from Italian precision manufacturers. Distribution runs through closed-loop reconditioning networks owned by integrated packaging groups, with spot procurement flowing via regional distributors in São Paulo and Mumbai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Welding automation skill gaps for food-grade seam certification constrain capacity expansion, propping pricing for electropolished stainless drum specialists serving pharmaceutical extractables compliance.
For Market Incumbents: Extend reconditioning network coverage into underpenetrated Brazilian agrochemical corridors before composite IBC substitution hardens in fertilizer blending applications. Backward integration into stainless steel coil sourcing hedges against Chinese supply volatility. Certification depth for USP Class VI and BIS food-grade specifications defends margin position against mid-tier carbon steel commoditization. For New Entrants and Emerging Players: Electropolished surface treatment technology offers a first-mover wedge in Indian pharmaceutical formulation hubs where USP Class VI compliance is displacing standard 316L finishes. São Paulo state fertilizer blending operations present the most penetrable geography, with ANVISA pharmaceutical regulations creating specification barriers that favor certified fabricators over commodity importers. Leasing-based per-trip pricing models eliminate capital barriers for chemical manufacturers seeking fleet flexibility without residual liability. For Investors and Strategic Acquirers: REACH substance restrictions tightening on polymer stabilizers are the leading indicator that all-steel construction demand will accelerate across European chemical distribution networks. Acquisition targets should prioritize fabricators with captive electropolishing capacity and closed-loop reconditioning infrastructure in Germany or India. Watch for BIS certification backlog announcements as a signal of demand inflection in India's western industrial corridor.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Coil Sourcing | Captive supply from Indian or European mills insulates margin from Chinese price volatility. |
| Electropolishing Capacity Expansion | USP Class VI compliance capability commands specification-driven pricing in Basel and Zurich pharmaceutical hubs. |
| Closed-Loop Reconditioning Network Buildout | Per-trip leasing models displace outright purchase in Maharashtra and São Paulo state chemical operations. |
| UN/DOT Certification Fast-Track Investment | Compressed design qualification timelines accelerate new product introduction in refrigerant logistics formats. |
| Food-Grade Surface Finish Specialization | BIS certification for edible oil transport captures premium positioning in Gujarat through Mumbai corridor demand. |
Research Methodology
Independent corroboration across drum fabricator procurement leads, chemical distributor fleet managers, and reconditioning network operators underwrites the qualitative findings. Primary interviews with plant engineers at specialty chemical manufacturers in Germany, India, and Brazil combined with secondary validation from customs trade data, BIS certification registries, and SEC filings from integrated packaging groups. Bottom-up demand modeling triangulates against top-down steel coil consumption estimates.
Comparable-period anchoring to historical stainless steel IBC procurement cycles in European chemical distribution established the forecast baseline across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, end-use industry concentration, and regional regulatory cluster. CAGRs were derived from capacity utilization trends and reconditioning fleet expansion rates, with input from REACH regulatory trajectory and DOT retest interval compliance costs.
Several conditions sit outside the modeled scope, including abrupt steel tariff reconfigurations, unforeseen polymer material science breakthroughs, and force majeure disruptions to maritime coil supply routes. Forecasts reflect documented assumptions about certification timeline stability and reconditioning infrastructure investment continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Europe Aluminium Powder Market
Metals
Aluminum Tubes Market
Metals
Ruthenium Market
Metals
High Purity Pig Iron Market
Metals
Copper Chromium Black Market
Metals
Monel Alloy Market
Metals
Metal Recycling Market
Metals
Anodized Titanium Market
Metals
India Metal Fabrication Market
Metals
Refined Nickel Market
Metals
North America Metal Finishing Market
Metals
Global Copper Market
Metals
North America Metal Casting Market
Metals
Cerium Market
Metals
Aluminium Powder Market
Metals
Potassium Platinochloride Market