
 India Metal Fabrication Market | 2026-2036
India Metal Fabrication Market Size, Share, and Industry Trends Forecast 2026-2036
India Metal Fabrication Market Foresight
Maintenance and refurbishment service contracts are broadening revenue streams beyond one-time equipment sales for Indian fabricators. Larsen & Toubro anchors its position through captive engineering capabilities spanning hydrocarbon and infrastructure verticals. Bharat Forge Ltd specializes in closed-die forging and precision machining for defense and heavy-truck applications. Zetwerk competes via its digital manufacturing platform that aggregates capacity across tier-2 and tier-3 suppliers nationwide.
India metal fabrication encompasses cutting, bending, welding, and assembling of raw metal materials into finished components or structures, typically employing carbon steel grades IS 2062 and IS 1079 with thickness tolerances governed by BIS specifications for load-bearing applications. The process serves as an intermediate industrial function, converting mill-produced sections into deployable assets for construction frames, automotive bodies, and process machinery. Structural steel commands the largest volume share among product types, reflecting sustained government infrastructure outlays on bridges, metro rail, and industrial corridors. Welding technology retains dominant application share, though laser cutting is gaining traction among automotive tier-1 suppliers seeking tighter tolerances for EV battery enclosures and lightweight body-in-white assemblies.
BIS standards for structural steel, CDSCO requirements for medical device fabrication, and CEA electrical safety norms collectively shape product specifications and certification pathways for metal fabricators operating across Indian states. Compliance with these frameworks determines market access for contractors bidding on public infrastructure projects and OEM supply contracts. Stakeholders must monitor evolving PLI scheme eligibility for specialty steel and advanced manufacturing equipment, as incentive structures will redirect capital toward higher-value fabrication capabilities.
Market Dynamics
India's metal fabrication sector faces a structural pivot as BIS certification mandates for structural steel tighten quality thresholds while electric vehicle platforms pull lighter chassis assemblies into production pipelines. This dual pressure compresses margins for legacy operators while rewarding precision-capable fabricators with automotive OEM contracts.
Growth Catalysts
- PLI Scheme Eligibility:Government incentives for specialty steel production redirect capital toward higher-value fabrication capabilities, particularly for automotive and defense applications requiring advanced metallurgy.
- EV Platform Demand:Electric vehicle manufacturers require aluminum-intensive and high-strength steel chassis structures that conventional stamping cannot deliver, creating pull for precision metalworking clusters.
- Gujarat Industrial Corridor:Port-linked special economic zones in Mundra and Dahej attract integrated fabrication investments serving export-oriented machinery and process equipment sectors.
Market Restraints
- Scrap Steel Price Volatility:Input cost swings for ferrous scrap undermine contract profitability for electric-arc-furnace-dependent fabricators serving construction and infrastructure verticals.
- Import Concentration in Cutting Equipment:Laser and plasma cutting systems rely predominantly on German, Japanese, and Chinese OEM supply chains, exposing tier-2 fabricators to extended lead times and currency risk.
- Technical Limitation in Thick-Section Welding:Qualified welders for pressure vessel and bridge fabrication remain scarce, capping capacity expansion for structural steel contractors bidding on public infrastructure.
Strategic Opportunities
- Tamil Nadu Aerospace Cluster:Defense offset obligations and Boeing-Airbus supplier development programs create white space for AS9100-certified precision fabricators near Chennai and Coimbatore.
- Battery Enclosure Fabrication:Laser-welded aluminum cell housings and thermal management plates represent an emerging application vector as cell manufacturing localizes under ACC PLI schemes.
- Digital Manufacturing Platforms:Capacity aggregation models that connect OEM demand with tier-2 and tier-3 supplier networks reduce asset intensity while capturing value from fragmented supply bases.
Industry Challenges
- Welder Certification Backlogs:BIS and AWS qualification timelines stretch 8-14 weeks, delaying project mobilization for infrastructure contractors facing liquidated damages clauses.
- Capex Intensity in Automation:Robot welding cells and CNC press brakes require capital outlays that strain balance sheets of family-owned fabricators with limited banking relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Metal Fabrication Market |
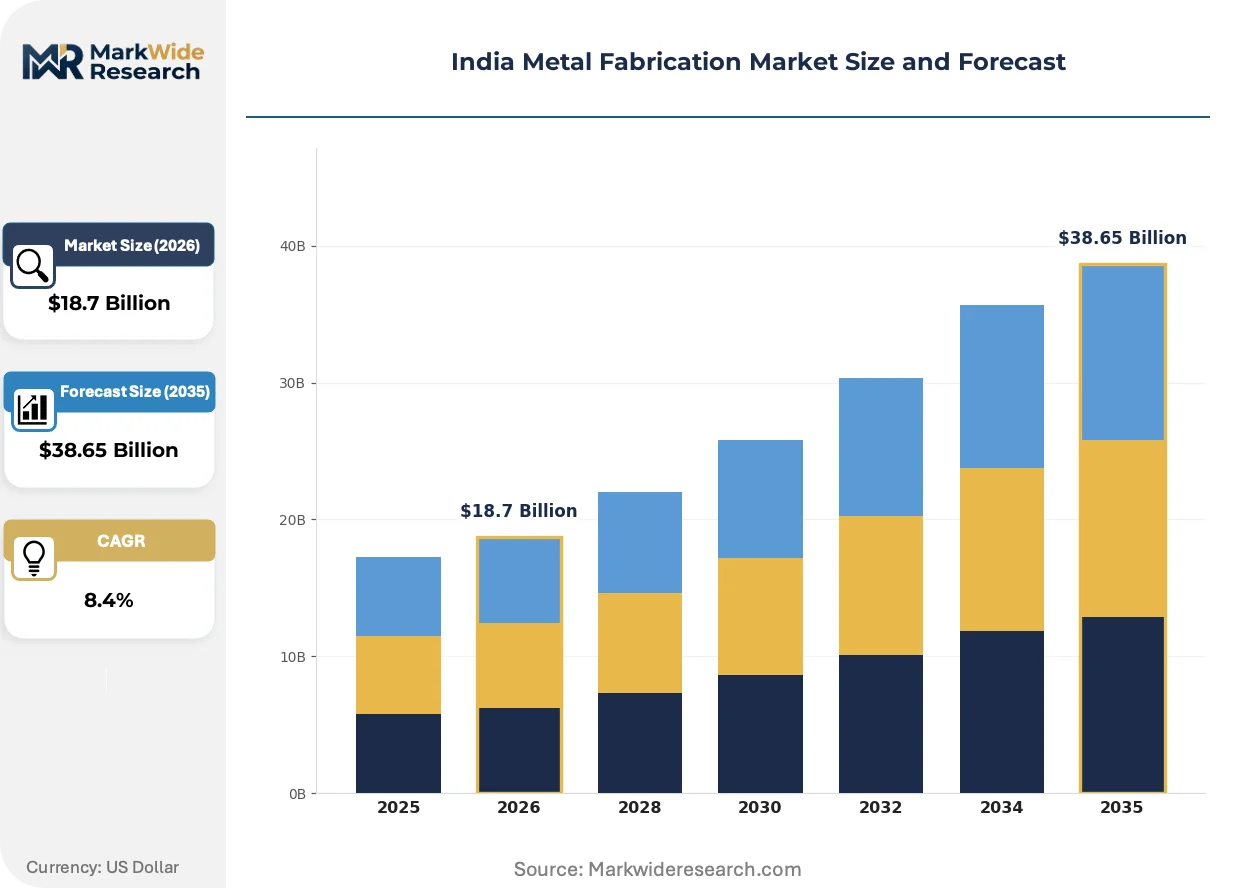
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Steel, Stainless Steel, Aluminum, Copper Application: Aerospace, Construction, Automotive, Machinery Technology: Welding, Laser Cutting, Plasma Cutting, Punching End User: OEMs, Tier-1 Suppliers, Fabricators, Contractors |
| Companies Covered | Pennar Industries Ltd, Mukand Ltd, Larsen & Toubro, Zetwerk, Walchandnagar Industries Ltd, ISGEC Heavy Engineering Ltd, Bharat Forge Ltd, Kirby Building Systems India, Bharat Heavy Electricals Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Metal Fabrication Market Shifts & Advancements
Digital thread technologies and regulatory compression are reshaping how Indian fabricators engineer, certify, and deliver metal structures across automotive, defense, and infrastructure verticals. These shifts favor integrated players with captive design capabilities over pure-play job shops.
Hybrid laser-arc welding is unifying thick-section joining and precision finishing in a single pass, eliminating secondary grinding operations for pressure vessel manufacturers. Boiler and heat exchanger fabricators in Gujarat and Maharashtra are adopting this technology to compress delivery cycles on export contracts. The process is unifying quality assurance with production speed, allowing mid-cap fabricators to compete for European pressure equipment directives without dedicated post-weld treatment lines.
BIS has tightened IS 2062 and IS 1079 certification protocols for structural steel used in government bridge and metro rail projects, mandating third-party inspection at mill and fabrication stages. This regulatory compression disqualifies uncertified job shops from public sector bidding while consolidating contract flow toward integrated EPC contractors with captive quality systems. Infrastructure fabricators in Haryana and Uttar Pradesh are responding by embedding BIS liaison officers within project management offices.
Automotive OEMs now require tier-1 suppliers to assume full-stack fabrication responsibility for EV battery enclosures, displacing the traditional stamping-welding-assembly disaggregation. This consolidation compresses the supplier pyramid and rewards fabricators with in-house laser cutting, CNC bending, and friction-stir welding capabilities. The shift is most visible in Pune and Chennai automotive corridors, where Mahindra, Tata Motors, and Hyundai suppliers are reconfiguring capacity for aluminum-intensive platforms.
India Metal Fabrication Market Segmentation
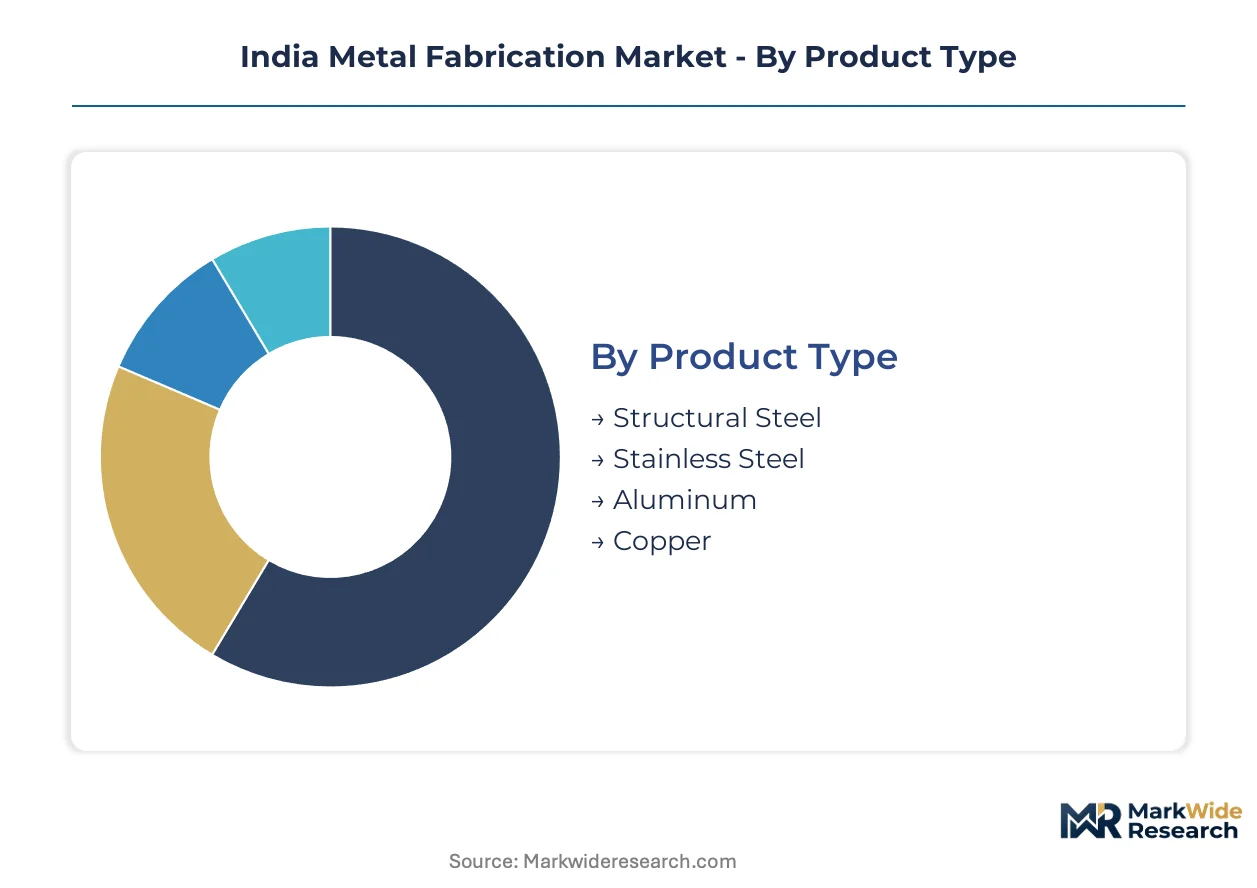
Segmentation in the India metal fabrication market reveals how BIS certification tiers, automotive OEM specifications, and infrastructure procurement protocols fragment demand across material grades, process technologies, and customer types. Understanding these divisions exposes where margin pools concentrate and which capability investments unlock contract access.
Product Type:
Standardization intensity varies sharply across this category, from commodity-grade structural sections to aerospace-certified aluminum alloys requiring mill-test certificates and traceability documentation.
- Structural Steel:Carbon steel grades IS 2062 and IS 1079 dominate government bridge, metro rail, and industrial corridor projects. Demand concentrates in Haryana and Uttar Pradesh fabrication clusters serving Delhi-Mumbai Industrial Corridor contracts, with BIS third-party inspection mandates now disqualifying uncertified suppliers from public sector bidding.
- Stainless Steel:Austenitic and duplex grades serve food processing equipment, pharmaceutical vessels, and coastal infrastructure requiring corrosion resistance. Maharashtra and Gujarat fabricators report expanding order books from dairy equipment OEMs and desalination plant contractors facing CDSCO and coastal regulation compliance.
- Aluminum:High-strength alloys for EV battery enclosures and aerospace structural components.
- Copper:Bus bars, heat exchangers, and electrical switchgear applications governed by CEA safety norms.
Leading the category by volume: structural steel. Expanding most quickly: aluminum alloys for electric vehicle platforms.
Application:
Cost tier stratification separates price-sensitive infrastructure contracts from premium aerospace and defense programs requiring AS9100 certification and offset compliance.
- Construction:Building frames, pre-engineered structures, and infrastructure metalwork constitute the volume base. Contractors in Gujarat's Mundra and Dahej SEZs leverage port-linked logistics to serve export-oriented machinery housing and process equipment markets.
- Automotive:Body-in-white assemblies, chassis structures, and EV battery enclosures demand precision tolerances unavailable from conventional job shops. Tier-1 suppliers in Pune and Chennai corridors are reconfiguring capacity for aluminum-intensive platforms as Mahindra, Tata Motors, and Hyundai consolidate fabrication responsibility.
- Aerospace:Defense offset obligations and Boeing-Airbus supplier development programs near Chennai and Coimbatore.
- Machinery:Industrial equipment frames, agricultural implements, and material handling systems.
Construction commands the largest revenue share. Aerospace applications are climbing the fastest as defense localization accelerates.
Technology:
Customer type determines technology adoption pace, with OEMs and tier-1 suppliers automating faster than project-based contractors.
- Welding:Arc, MIG, TIG, and hybrid laser-arc processes retain dominant application share across pressure vessels, bridges, and automotive structures. Gujarat and Maharashtra boiler fabricators adopt hybrid laser-arc welding to compress delivery cycles on European export contracts without dedicated post-weld treatment lines.
- Laser Cutting:Fiber and CO2 systems deliver tight tolerances for EV battery enclosures and precision components. Automotive tier-1 suppliers in Tamil Nadu and Karnataka are replacing mechanical punching with laser systems to meet OEM tolerance requirements for aluminum cell housings.
- Plasma Cutting:Thick-section carbon steel processing for shipbuilding and heavy equipment.
- Punching:High-volume blanking for standard structural components and electrical enclosures.
Welding leads by installed base. Laser cutting is gaining share fastest among automotive suppliers.
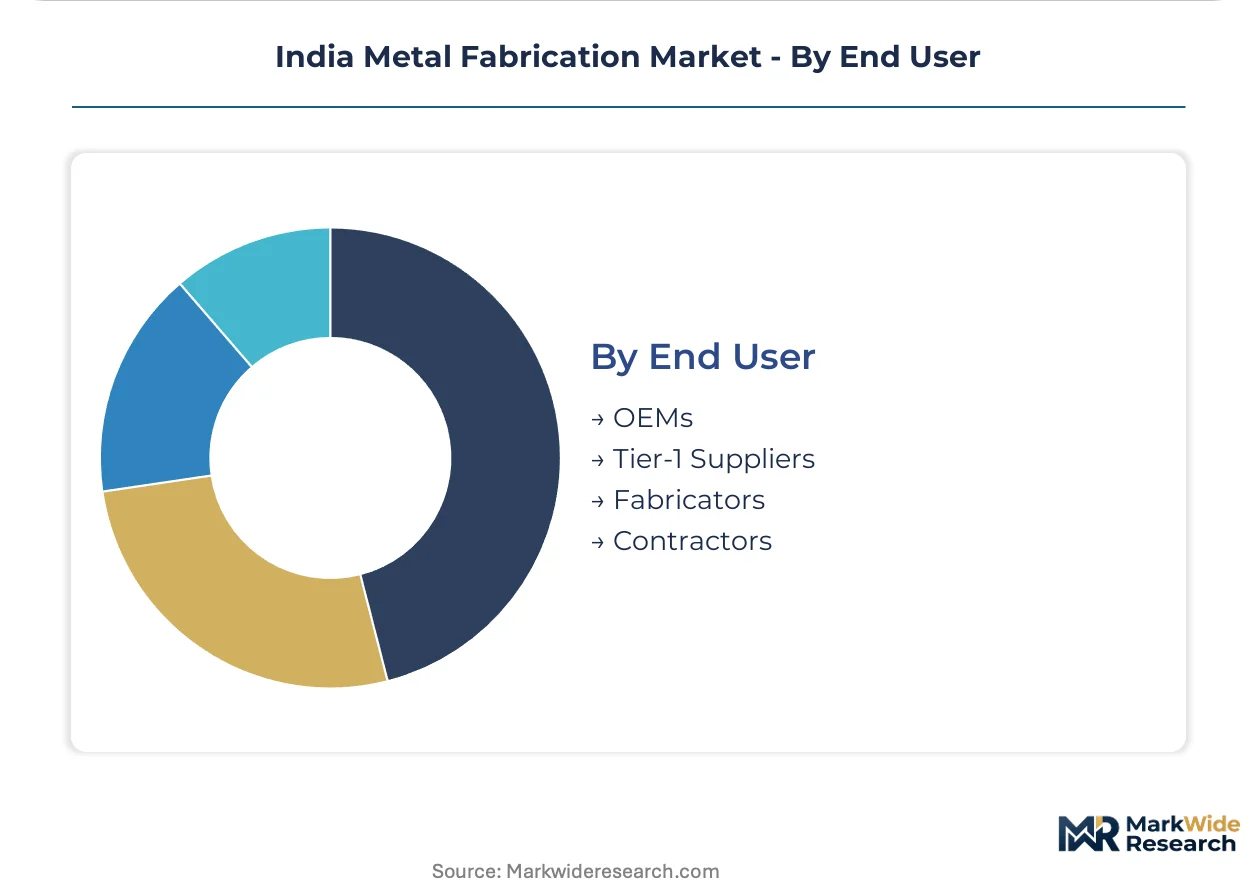
End User:
Supply concentration varies by procurement sophistication, from OEMs with captive quality systems to fragmented contractor networks.
- OEMs:Automotive, aerospace, and machinery manufacturers demand full-stack fabrication responsibility including design validation and BIS certification. EV battery enclosure contracts now require in-house laser cutting, CNC bending, and friction-stir welding capabilities that compress the traditional supplier pyramid.
- Tier-1 Suppliers:Intermediate fabricators serving OEMs with certified sub-assemblies and just-in-sequence delivery.
- Fabricators:Independent job shops competing on capacity availability and regional logistics.
- Contractors:Project-based operators bidding on public infrastructure with thin margins and liquidated damages exposure.
OEMs dominate value capture. Tier-1 suppliers are restructuring fastest to assume consolidated fabrication responsibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in western and southern industrial corridors, while consumption spreads across infrastructure corridors and automotive manufacturing belts. State-level policy variations and port access create divergent cost structures for fabricators.
Gujarat
Port-linked special economic zones in Mundra and Dahej attract integrated fabrication investments serving export-oriented machinery sectors. PLI scheme incentives for specialty steel redirect capital toward higher-value capabilities in this coastal corridor. Dahej SEZ fabricators report expanding order books from process equipment OEMs seeking duty-advantaged export platforms.
Maharashtra
Pune and Mumbai-Nashik industrial belts concentrate automotive tier-1 suppliers reconfiguring for aluminum-intensive EV platforms. BIS certification mandates for structural steel tighten quality thresholds for bridge and metro contractors in the Mumbai Metropolitan Region. Boiler and heat exchanger fabricators adopt hybrid laser-arc welding to compress delivery cycles on European export contracts.
Tamil Nadu
Chennai and Coimbatore aerospace clusters emerge under defense offset obligations and Boeing-Airbus supplier development programs. CDSCO requirements for medical device fabrication shape stainless steel demand from pharmaceutical equipment OEMs. AS9100-certified precision fabricators near Sriperumbudur capture value from defense localization mandates.
Haryana
Delhi-Mumbai Industrial Corridor contracts concentrate structural steel demand in Faridabad and Gurgaon fabrication clusters. BIS third-party inspection protocols now disqualify uncertified suppliers from public sector bidding. Welders for pressure vessel and bridge fabrication remain scarce, capping capacity expansion for infrastructure contractors facing liquidated damages clauses.
Karnataka
Bengaluru and Hosur corridors host precision metalworking for machinery and aerospace sub-assemblies. CEA electrical safety norms govern copper bus bar and switchgear fabrication for power distribution OEMs. Tier-2 fabricators face extended lead times on German and Japanese laser cutting equipment, constraining automation adoption.
India Metal Fabrication Market Competitive Landscape
Top-tier vendors anchor integrated EPC and defense supply chains, while mid-cap specialists occupy automotive and aerospace niches. The vendor base stratifies across captive engineering capabilities, digital manufacturing platforms, and commodity job shops. Three archetypes dominate: diversified conglomerates with hydrocarbon and infrastructure verticals, precision forging specialists serving heavy-truck and defense applications, and capacity aggregators connecting OEM demand with fragmented tier-2 networks. Competitive moves center on automation capex and BIS certification investments that disqualify uncertified rivals from public infrastructure bidding.
Among diversified engineering conglomerates, Larsen & Toubro occupies a position exemplifying captive capabilities across multiple verticals. Bharat Forge Ltd represents the precision-forging archetype for defense and heavy-truck applications. Zetwerk anchors the digital manufacturing platform tier, aggregating capacity across tier-2 and tier-3 suppliers nationwide. These three illustrate how scale, specialization, and network effects create distinct competitive positions in a market tightening around certification and precision requirements.
| Leading Market Players |
|---|
| Pennar Industries Ltd |
| Mukand Ltd |
| Larsen & Toubro |
| Zetwerk |
| Walchandnagar Industries Ltd |
| ISGEC Heavy Engineering Ltd |
| Bharat Forge Ltd |
| Kirby Building Systems India |
| Bharat Heavy Electricals Ltd |
| Others |
Supply & Pricing Matrix
BIS third-party inspection mandates for structural steel are disqualifying uncertified fabricators from public infrastructure bidding, forcing supply consolidation toward integrated EPC contractors with captive quality systems and compressing margins for legacy job shops.
Pricing Analysis
Margin tightening in tier-2 structural steel fabrication reflects BIS certification backlogs stretching 8-14 weeks, while premium pricing accrues to AS9100-certified precision fabricators serving aerospace and defense offset programs. Three-tier pricing structure across certified-premium, standard-compliant, and uncertified-economy levels separates contract access tiers. Cost-down pressure on commodity job shops accelerates as OEMs consolidate supplier pyramids for EV battery enclosures. Public infrastructure contractors exhibit highest price sensitivity due to thin margins and liquidated damages exposure, whereas automotive tier-1 suppliers prioritize precision capability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German, Japanese, and Chinese OEMs supplying laser and plasma cutting systems to Indian fabricators, exposing tier-2 operators to extended lead times and currency risk. Raw material flows draw from domestic steel mills producing IS 2062 and IS 1079 grades, with specialty aluminum alloys and high-strength steels importing from South Korea and Japan. Ferrous scrap price volatility feeds from global commodity markets, undermining contract profitability for electric-arc-furnace-dependent fabricators. Distribution runs through project-based contractor networks for infrastructure and direct OEM-supplier relationships for automotive and aerospace verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified welder scarcity for pressure vessel and bridge fabrication caps capacity expansion, propping pricing for certified contractors while compressing availability for public infrastructure timelines.
For Market Incumbents: To counter BIS certification mandates disqualifying uncertified rivals, embed liaison officers within project management offices to accelerate third-party inspection timelines, and deepen backward integration into specialty steel processing under PLI scheme incentives to capture higher-value fabrication margins. For New Entrants and Emerging Players: Begin with battery enclosure fabrication for EV platforms localizing under ACC PLI schemes, where laser-welded aluminum cell housings and thermal management plates represent penetrable white space with consolidated OEM demand and limited incumbent precision capability. For Investors and Strategic Acquirers: The window for entry favors AS9100-certified precision fabricators near Tamil Nadu aerospace clusters, where defense offset obligations and Boeing-Airbus supplier development programs create acquisition targets with durable contract pipelines; watch for ACC PLI scheme capacity commissioning as inflection signal for battery enclosure demand localization.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Certification Investment | Unlocks defense offset contracts and Boeing-Airbus supplier programs near Chennai. |
| Hybrid Laser-Arc Welding Adoption | Compresses European pressure equipment delivery cycles without post-weld treatment lines. |
| Backward Integration into Specialty Steel | Captures PLI scheme incentives while securing advanced metallurgy for automotive and defense. |
| Digital Manufacturing Platform Launch | Aggregates tier-2 and tier-3 capacity to serve fragmented OEM demand with reduced asset intensity. |
| BIS Liaison Office Embedding | Accelerates third-party inspection timelines to meet public infrastructure liquidated damages clauses. |
Research Methodology
Multi-period observation of BIS certification timelines, PLI scheme disbursement patterns, and EV platform localization announcements anchored the trend analysis, supplemented by interviews with fabrication plant managers, OEM procurement leads at automotive and aerospace manufacturers, EPC contractor project directors, and BIS certification officers. Secondary validation drew from Ministry of Steel production statistics, DGFT trade data, CDSCO medical device filings, and CEA electrical safety notifications. Bottom-up capacity estimates across Gujarat, Maharashtra, Tamil Nadu, Haryana, and Karnataka clusters triangulated against top-down demand projections from infrastructure outlay announcements and automotive production schedules.
The input-output matrix mapped raw material flows from domestic mills and import channels through fabrication processes to end-use applications across construction, automotive, aerospace, and machinery verticals. Segmentation dimensions modeled included material grade tier, certification level, process technology, and regional production cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating PLI scheme incentive effects and BIS regulatory compression. Industry-specific forecast inputs included EV platform aluminum intensity assumptions and defense localization mandate timelines.
Underlying measurement precision varies by segment; certified-premium fabrication clusters carry tighter precision than fragmented tier-3 job shops due to disclosure requirements and contract transparency. Forecasts reflect assumptions on PLI scheme continuity, BIS enforcement intensity, and EV adoption trajectories that could revise outcomes if policy shifts or demand disappoints. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Bronze Market
Metals
Metal Powder Market
Metals
India Steel Market
Metals
Anodized Titanium Market
Metals
China Copper Market
Metals
Aluminum Tubes Market
Metals
Aluminum Wire Market
Metals
Global Brass Rods Market
Metals
Flat-Rolled Stainless Steel Market
Metals
Copper and Copper Alloy Powder Market
Metals
Silico Manganese Market
Metals
Beryllium Market
Metals
Stainless Steel Panels Market
Metals
Huntite Market
Metals
India Special Steel Market
Metals
Galvanized Steel Coil Market